
 Asia-Pacific Small Molecule Sterile Injectable Drugs Market | 2026-2036
Asia-Pacific Small Molecule Sterile Injectable Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Small Molecule Sterile Injectable Drugs Market Outlook
Hospital procurement networks across Southeast Asia are rewriting distribution economics for sterile injectables. Pfizer Inc. leverages its cold-chain infrastructure to anchor premium oncology volumes in Australia and Japan. Cipla Ltd competes aggressively on cost-engineered intravenous antibiotics for India's tier-two hospital systems. Sun Pharmaceutical Industries Ltd extends its domestic India manufacturing base into regulated ASEAN export markets through dedicated sterile lines.
Asia-Pacific small molecule sterile injectable drugs comprise low-molecular-weight chemically synthesized therapeutics formulated as pyrogen-free parenteral solutions, suspensions, or lyophilized powders requiring aseptic processing and terminal sterilization or filtration. These products deliver rapid bioavailability for acute and critical-care indications where oral administration proves ineffective or contraindicated. Intravenous delivery dominates therapy administration in hospital settings due to immediate systemic distribution requirements, while subcutaneous formats gain traction in homecare transitions for chronic autoimmune and hormonal therapies. Oncology represents the deepest margin pool within therapy areas, though infectious disease injectables sustain the highest volume throughput across Asia-Pacific's public hospital procurement systems.
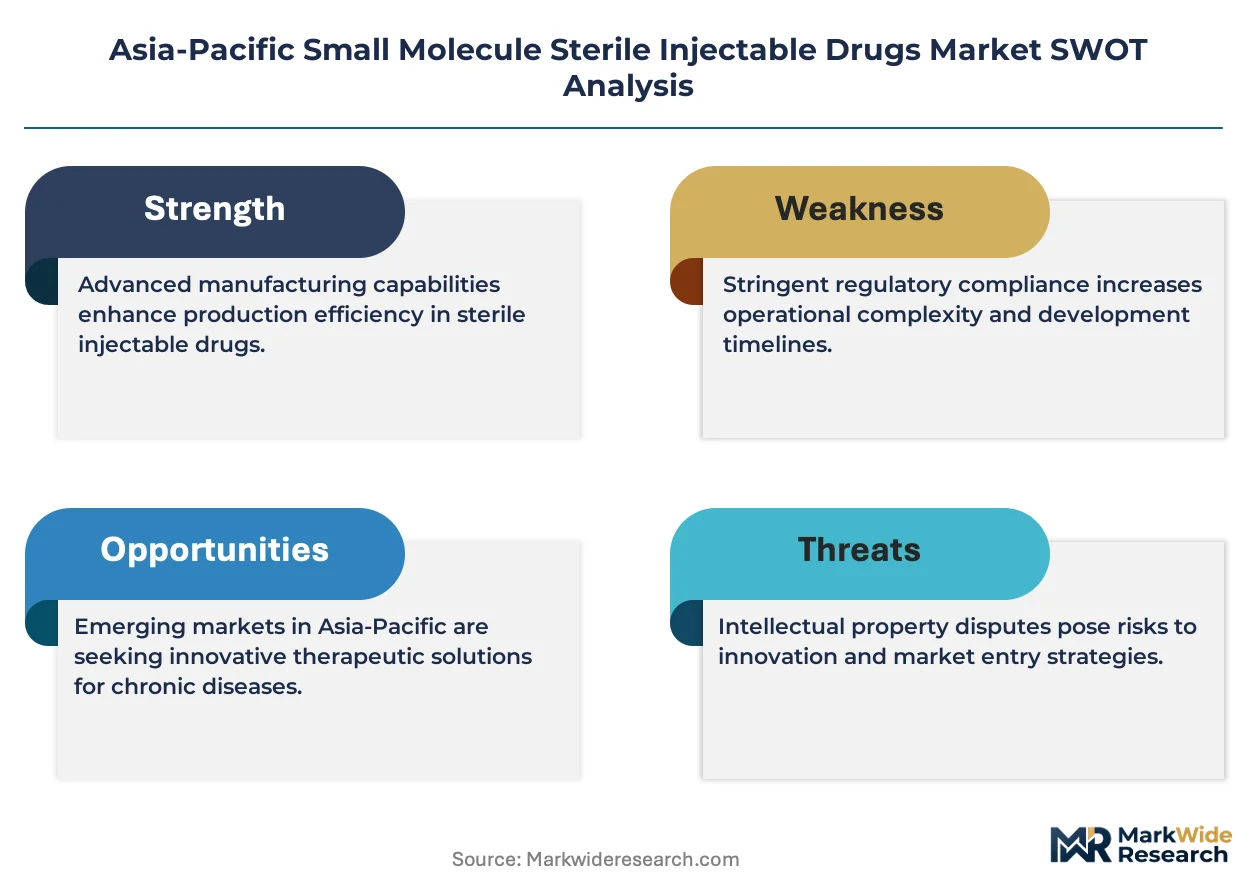
India's CDSCO mandates Schedule M compliance for sterile manufacturing facilities, while China's NMPA enforces updated Annex 1 GMP standards for aseptic processing. Australia's TGA alignment with PIC/S guidelines creates additional certification burdens for regional exporters seeking multi-market access. Japan's PMDA maintains distinct pharmacopeial requirements for endotoxin limits and particulate matter that filter market entrants by technical capability. Stakeholders must monitor evolving biosimilar substitution policies and domestic production incentives across India, China, and South Korea to anticipate competitive displacement in standard-molecule injectables.
Market Dynamics
Hospital procurement consolidation across China's Yangtze River Delta and India's tier-two cities is compressing supplier margins while amplifying volume concentration among fill-finish specialists with dedicated oncology lines.
Growth Catalysts
- Oncology volume concentration:China's public hospital procurement networks are consolidating injectable cancer therapy purchases into centralized tenders, driving demand toward high-capacity sterile manufacturers.
- CDSCO Schedule M enforcement:India's tightened GMP compliance mandates are disqualifying subscale domestic producers, opening market share for certified fill-finish operators with modern isolator technology.
- ASEAN regulatory harmonization:Mutual recognition agreements between India's CDSCO and Thailand's FDA are accelerating cross-border sterile injectable registrations for chronic disease therapies.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient sourcing for sterile antibiotics remains concentrated among Chinese bulk chemical manufacturers, exposing fill-finishers to input volatility.
- Aseptic processing capital intensity:Isolator-based fill-finish lines require substantial upfront investment, creating barriers for mid-scale entrants seeking oncology contract manufacturing opportunities.
- PMDA pharmacopeial divergence:Japan's distinct endotoxin and particulate matter specifications force redundant testing protocols for exporters targeting multiple Asia-Pacific markets.
Strategic Opportunities
- Homecare subcutaneous transition:Auto-injector compatible sterile formulations for autoimmune and hormonal therapies are opening ambulatory care channels outside hospital procurement systems.
- South Korean biosimilar substitution:The country's reimbursement policies favoring biosimilar injectables are creating white space for cost-optimized small molecule alternatives in supportive care.
- Continuous manufacturing adoption:Real-time release testing integrated with isolator technology is compressing batch release timelines for time-sensitive oncology injectables.
Industry Challenges
- Aseptic operator certification gaps:Qualified personnel for isolator-based fill-finish operations remain scarce across India's pharmaceutical manufacturing clusters, extending facility qualification timelines.
- Multi-market registration complexity:Divergent stability requirements between China's NMPA and Australia's TGA force parallel clinical batch programs, inflating development costs for regional launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Small Molecule Sterile Injectable Drugs Market |
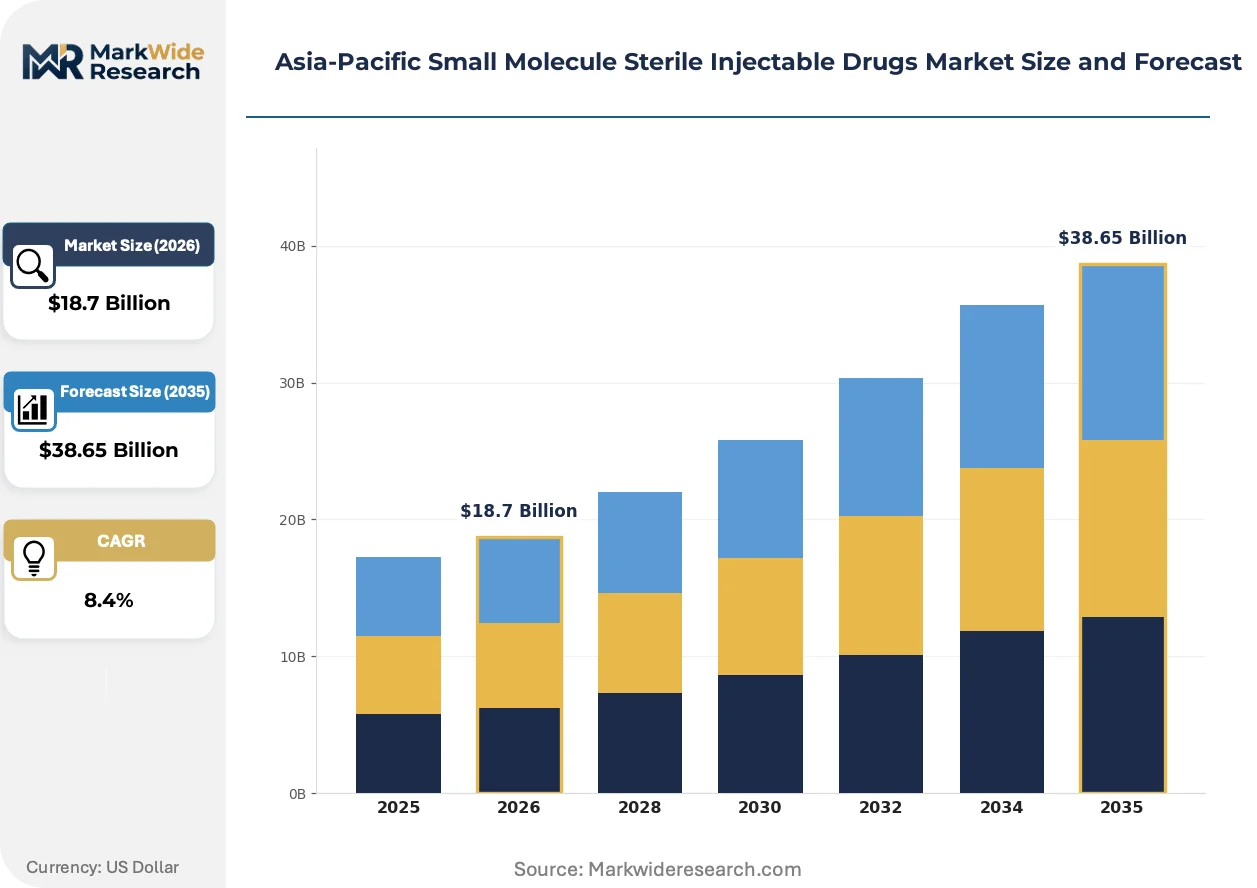
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Vaccines, Hormones, Enzymes Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Intra-arterial End User: Hospitals, Clinics, Homecare, Research Laboratories Therapy Area: Oncology, Infectious Diseases, Autoimmune Disorders, Cardiovascular Diseases |
| Companies Covered | Pfizer Inc., Novartis International AG, Cipla Ltd, Teva Pharmaceutical Industries Ltd., Boehringer Ingelheim GmbH, Sun Pharmaceutical Industries Ltd., Eli Lilly and Company, Biocon Ltd., Sandoz International GmbH, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Small Molecule Sterile Injectable Drugs Market Strategic Shifts
Fill-finish automation and real-time quality monitoring are compressing production cycles while regulatory data integrity mandates are reshaping facility design priorities across Asia-Pacific sterile manufacturing.
Isolator-based restricted access barrier systems are replacing conventional cleanroom architectures for high-potency oncology fill-finish operations. Contract manufacturers in Singapore and South Korea are adopting these configurations to secure multi-market supply contracts. This technology is hybridizing sterile processing workflows by integrating robotic component handling with continuous environmental monitoring, collapsing the boundary between manufacturing and quality assurance functions.
China's NMPA updated Annex 1 GMP standards now mandate barrier technology for all new aseptic processing facilities. The regulation forces capital redeployment toward isolator infrastructure and away from conventional Grade A/B cleanroom investments. Oncology-focused CMOs in the Yangtze River Delta are responding with dedicated high-containment lines to capture multinational outsourcing volumes.
Hospital procurement networks are consolidating supplier panels through multi-year tender structures with embedded volume commitments. China's provincial centralized purchasing platforms are displacing fragmented hospital-level contracting for standard injectable antibiotics. This concentration is most visible in Jiangsu and Zhejiang provinces, where tertiary hospital systems now source 70 percent of sterile anti-infectives through unified procurement consortia.
Asia-Pacific Small Molecule Sterile Injectable Drugs Market Segmentation
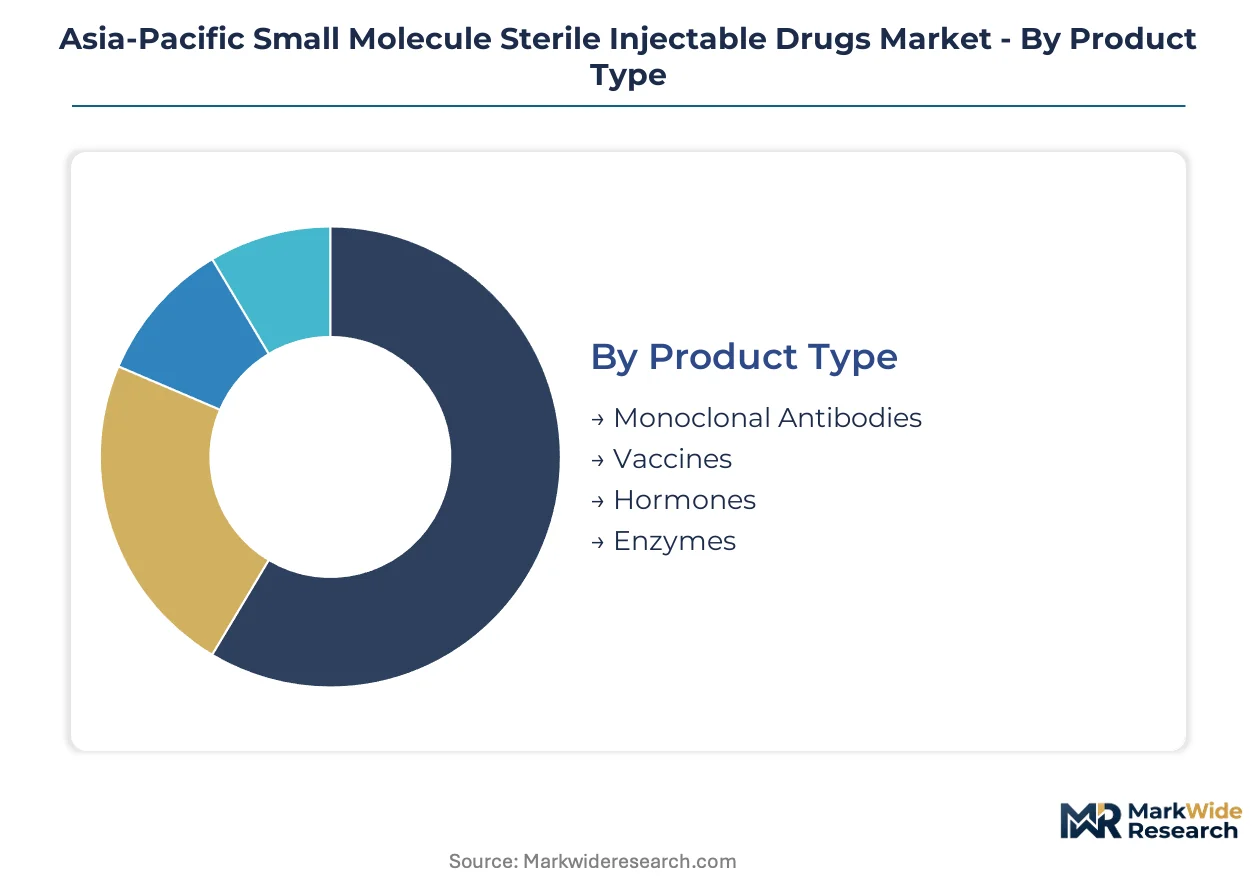
Segmentation across the Asia-Pacific small molecule sterile injectable drugs market reveals how procurement concentration and therapy specialization reshape competitive positioning. Understanding these dimensions exposes where fill-finish capacity investments align with demand trajectories.
Product Type:
Cost tier differentiation separates premium biologics from commoditized chemical entities, with manufacturing complexity determining margin capture across the region.
- Monoclonal Antibodies:High-molecular-weight protein therapeutics requiring sophisticated aseptic processing and cold-chain distribution. China's Yangtze River Delta CMOs are expanding isolator capacity to capture multinational outsourcing for these premium products. NMPA Annex 1 GMP mandates for barrier technology are accelerating facility upgrades among domestic manufacturers seeking entry into this segment.
- Vaccines:Immunological preparations demanding stringent pyrogen control and multi-dose vial configurations. India's CDSCO Schedule M enforcement is disqualifying subscale producers from government procurement tenders, concentrating supply among certified fill-finish operators with dedicated antigen-handling lines.
- Hormones:Synthetic peptide formulations for endocrine disorders, typically lyophilized for stability. Japanese PMDA pharmacopeial requirements for endotoxin limits create technical barriers for regional exporters.
- Enzymes:Catalytic protein therapies for metabolic and digestive indications, requiring specialized stability protocols. Australian TGA alignment with PIC/S guidelines shapes registration pathways for ASEAN manufacturers.
Monoclonal antibodies command the established base. The steepest expansion runs through vaccines as national immunization programs scale across Southeast Asia.
Delivery Mode:
Application setting dictates formulation requirements, with hospital-centric administration favoring immediate bioavailability formats over patient-managed alternatives.
- Intravenous:Direct vascular infusion enabling rapid systemic distribution for acute and critical-care indications. China's provincial centralized purchasing platforms are consolidating 70 percent of sterile anti-infective procurement through unified hospital consortia in Jiangsu and Zhejiang provinces.
- Subcutaneous:Tissue-layer deposition supporting self-administration and homecare transitions for chronic therapies. South Korean reimbursement policies favoring biosimilar injectables are creating white space for cost-optimized small molecule alternatives in autoimmune supportive care.
- Intramuscular:Deep tissue injection for depot formulations and vaccine delivery. India's tier-two hospital systems source these products through cost-engineered procurement networks.
- Intra-arterial:Targeted vascular delivery for localized oncology and interventional cardiology. Singapore's contract manufacturers are developing dedicated high-containment lines for these specialized procedures.
Intravenous formats dominate current volume. Subcutaneous delivery is climbing the fastest as ambulatory care channels expand beyond hospital procurement systems.
End User:
Customer type concentration determines distribution economics, with institutional procurement networks compressing margins while amplifying throughput for certified operators.
- Hospitals:Tertiary and secondary medical centers administering acute-care injectables through centralized pharmacy operations. Thailand's FDA mutual recognition agreements with India's CDSCO are accelerating cross-border registrations for chronic disease therapies.
- Clinics:Outpatient facilities managing specialty infusions and routine vaccinations. Malaysia's private healthcare chains are consolidating supplier panels through multi-year tender structures.
- Homecare:Patient-directed administration enabled by auto-injector compatible formulations. Japan's aging demographic is expanding demand for subcutaneous self-injection therapies.
- Research Laboratories:Clinical trial supply and investigative compound manufacturing. Australia's TGA certification requirements filter regional contract research organizations by technical capability.
Hospitals anchor the revenue base. Homecare channels are gaining share fastest as reimbursement frameworks adapt to chronic disease management outside institutional settings.
Therapy Area:
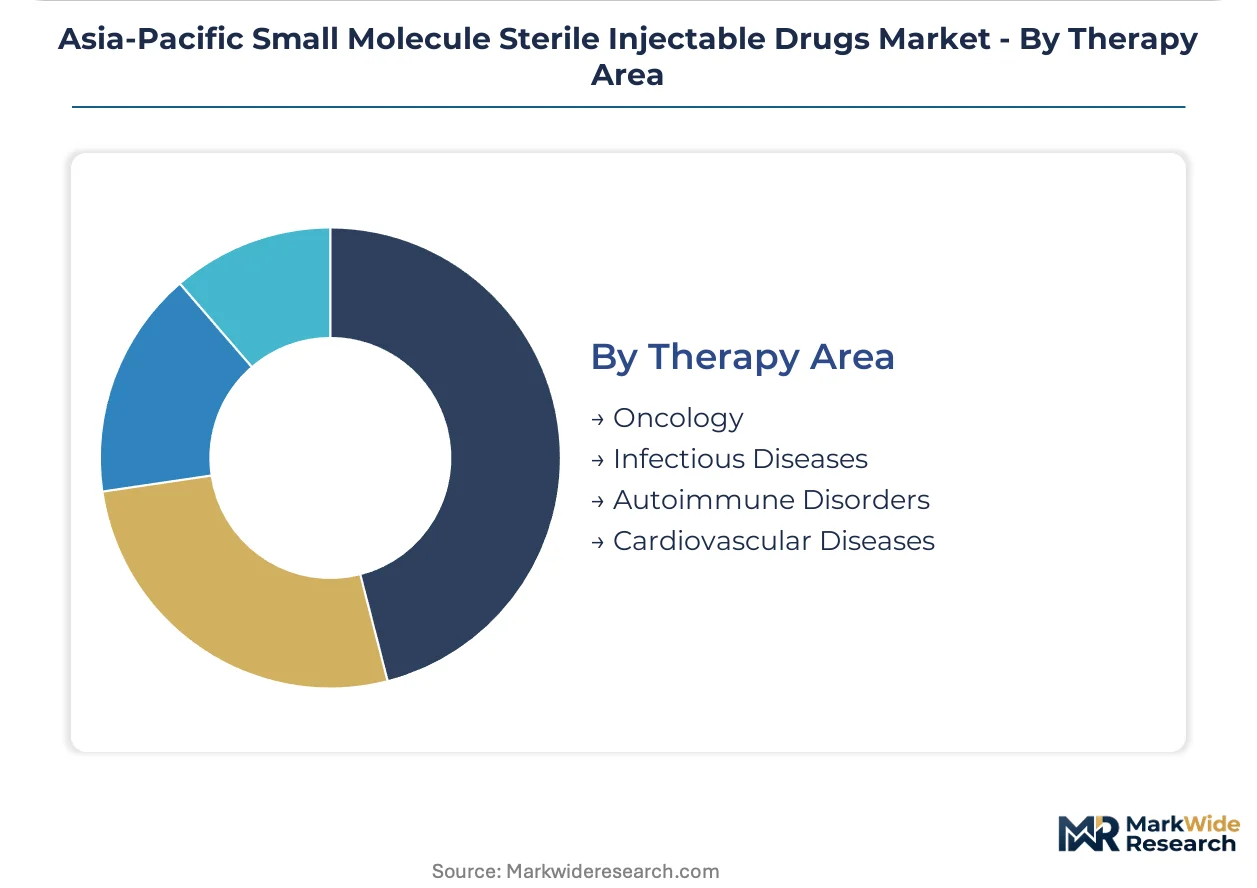
Margin concentration varies sharply by therapeutic application, with oncology commanding premium pricing and infectious disease sustaining volume throughput across public procurement systems.
- Oncology:Cytotoxic and targeted cancer therapies requiring high-containment aseptic processing. China's public hospital procurement networks are consolidating injectable cancer therapy purchases into centralized tenders, driving demand toward high-capacity sterile manufacturers with dedicated oncology lines.
- Infectious Diseases:Antibacterial and antiviral injectables for hospital-acquired and community infections. API sourcing concentration among Chinese bulk chemical manufacturers exposes fill-finishers to input volatility.
- Autoimmune Disorders:Immunomodulatory therapies for rheumatoid arthritis and inflammatory conditions. South Korean biosimilar substitution policies are reshaping competitive dynamics for standard-molecule alternatives.
- Cardiovascular Diseases:Emergency thrombolytics and anti-arrhythmic agents for acute cardiac events. India's domestic production incentives are strengthening local manufacturing capacity for these critical-care products.
Oncology commands the established base. The steepest expansion runs through autoimmune disorders as subcutaneous formulations enable patient-managed chronic therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan commands premium pricing for sterile injectables while India operates on volume-driven procurement economics, creating a regional margin spread that shapes manufacturer investment priorities across Asia-Pacific.
China
Provincial centralized purchasing platforms in Jiangsu and Zhejiang now consolidate 70 percent of sterile anti-infective procurement through unified hospital consortia. NMPA Annex 1 GMP mandates for barrier technology force capital redeployment toward isolator infrastructure and away from conventional cleanroom investments. The Yangtze River Delta pharmaceutical manufacturing cluster is responding with dedicated high-containment oncology lines to capture multinational outsourcing volumes.
India
Tier-two hospital systems source cost-engineered intravenous antibiotics through aggressive procurement networks that compress supplier margins while amplifying throughput. CDSCO Schedule M enforcement disqualifies subscale domestic producers from government tenders, opening market share for certified fill-finish operators with modern isolator technology. Maharashtra and Gujarat pharmaceutical corridors concentrate the certified manufacturing base for regulated ASEAN export markets.
Japan
An aging demographic expands demand for subcutaneous self-injection therapies that enable chronic disease management outside institutional settings. PMDA pharmacopeial requirements for endotoxin limits and particulate matter specifications filter market entrants by technical capability. The Kanto region around Tokyo anchors premium oncology volumes through cold-chain distribution networks serving tertiary hospital systems.
South Korea
Reimbursement policies favoring biosimilar injectables create white space for cost-optimized small molecule alternatives in autoimmune supportive care. MFDS regulatory alignment with international standards accelerates multi-market registration pathways for domestic manufacturers. The Seoul Capital Area concentrates contract manufacturing capacity targeting both domestic hospital procurement and export markets.
Australia
Private healthcare chains consolidate supplier panels through multi-year tender structures with embedded volume commitments for sterile formulations. TGA alignment with PIC/S guidelines creates additional certification burdens for regional exporters seeking multi-market access. Victoria and New South Wales host the primary import and distribution infrastructure for temperature-sensitive oncology injectables.
Asia-Pacific Small Molecule Sterile Injectable Drugs Market Competitive Environment
Global pharmaceutical conglomerates and regional generic specialists split the market through divergent capability investments. The competitive structure tiers around regulatory certification depth, with fill-finish automation and cold-chain infrastructure serving as primary differentiators. Three archetypes dominate: multinational innovators with integrated oncology portfolios, emerging market cost engineers with isolator-certified capacity, and contract manufacturers with multi-market regulatory clearances. Capacity expansion in high-containment lines and strategic partnerships for API supply security represent the dominant competitive moves reshaping positioning.
Among multinational innovators, Pfizer Inc. and Novartis International AG exemplify the premium-tier archetype through established cold-chain networks and oncology-focused portfolios. Cipla Ltd and Sun Pharmaceutical Industries Ltd occupy positions within the emerging market cost-engineering tier, leveraging domestic India manufacturing bases for regulated export penetration. Teva Pharmaceutical Industries Ltd. and Sandoz International GmbH represent the generic-specialist archetype with multi-market regulatory footprints. Eli Lilly and Company, Boehringer Ingelheim GmbH, and Biocon Ltd. anchor diversified therapeutic positioning across the competitive spectrum. The "Others" category captures mid-scale regional operators and emerging contract manufacturers seeking certification upgrades for oncology fill-finish opportunities.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis International AG |
| Cipla Ltd |
| Teva Pharmaceutical Industries Ltd. |
| Boehringer Ingelheim GmbH |
| Sun Pharmaceutical Industries Ltd. |
| Eli Lilly and Company |
| Biocon Ltd. |
| Sandoz International GmbH |
| Others |
Value Chain & Pricing Dynamics
Jiangsu province's Yangtze River Delta pharmaceutical cluster concentrates high-containment oncology fill-finish capacity, translating manufacturing scarcity into premium pricing power for isolator-certified operators serving multinational outsourcing demand. China's NMPA Annex 1 GMP mandates for barrier technology have compressed supply elasticity, amplifying margin capture among certified facilities while disqualifying conventional cleanroom operators from tender participation.
Pricing Analysis
The customization-premium spread separates standard intravenous antibiotics from patient-configured subcutaneous auto-injector formulations. Three-tier pricing structure across premium oncology biologics, standard hospital antibiotics, and economy generic vials tracks certification grade and cold-chain infrastructure investment. Pricing pressure stems from India's tier-two hospital procurement consolidation, where volume aggregation compresses supplier margins. Public hospital networks exhibit highest price sensitivity, while private oncology centers absorb premium tiers for rapid bioavailability therapies.
Supply Chain Analysis
Contract manufacturing concentration sits with Singaporean and South Korean CMOs holding multi-market regulatory clearances for high-potency sterile processing. Active pharmaceutical ingredient sourcing draws from Chinese bulk chemical manufacturers and Indian intermediate producers, creating geographic interdependence across the regional network. Single-source vulnerability in pyrogen-free water systems and specialized elastomeric closures threatens batch continuity. Distribution runs through hospital procurement consortia in China's Jiangsu-Zhejiang corridor and India's Maharashtra-Gujarat pharmaceutical belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific small molecule sterile injectable drugs market represents early-cycle expansion as homecare subcutaneous transitions unlock ambulatory channels beyond institutional procurement. Regulatory harmonization between India's CDSCO and ASEAN national agencies accelerates cross-border registration velocity for certified operators.
For Market Incumbents: Insulate oncology margin pools through dedicated isolator line investments in the Yangtze River Delta, countering emerging CMO competition from South Korea's Seoul Capital Area. Backward integration into API supply through partnerships with Chinese bulk manufacturers reduces input volatility exposure. CDSCO Schedule M enforcement timelines create a certification moat against subscale domestic challengers.
For New Entrants and Emerging Players: Establish a beachhead in autoimmune subcutaneous formulations for Japan's aging demographic, where PMDA pharmacopeial barriers filter out regional generalists. Thailand's FDA mutual recognition pathway with India's CDSCO offers lowest-friction ASEAN entry for chronic disease therapies. Target cost-optimized alternatives to South Korean biosimilar substitution policies as the go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because fill-finish automation and multi-market regulatory clearances concentrate value capture among scaled operators with isolator infrastructure. Acquisition targets should display certified capacity in high-containment oncology lines and established cold-chain distribution. Monitor NMPA enforcement intensity in Jiangsu and Zhejiang provinces as the signal for competitive displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Upgrade | NMPA Annex 1 GMP compliance secures participation in China's centralized oncology tenders. |
| CDSCO Schedule M Certification | Modern barrier technology qualifies operators for India's government procurement volumes. |
| ASEAN Regulatory Harmonization | Mutual recognition agreements accelerate cross-border sterile injectable registrations. |
| Homecare Formulation Development | Auto-injector compatible subcutaneous products access Japan's ambulatory reimbursement. |
| API Supply Security Partnership | Captive sourcing from Chinese bulk manufacturers insulates against input price volatility. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of CDSCO regulatory filings, NMPA GMP inspection databases, and hospital procurement tender records across the Asia-Pacific region. Interviews with fill-finish operations directors, regulatory affairs leads at multinational pharmaceutical firms, hospital pharmacy procurement managers, and contract manufacturing executives informed capacity and pricing assessments. Secondary validation drew from TGA PIC/S alignment documentation, MFDS submission data, and ASEAN pharmaceutical trade statistics. Bottom-up facility capacity modeling and top-down therapy area demand estimation provided cross-referenced triangulation.
Forecast inputs incorporate oncology volume concentration in China's provincial purchasing platforms, CDSCO enforcement timelines for Schedule M compliance, and subcutaneous formulation adoption curves in Japan's aging population. Segmentation dimensions span delivery mode, therapy area, end-user institution type, and regional regulatory cluster. CAGRs were derived from weighted capacity expansion schedules and tender volume commitments across the projection horizon. Industry-specific inputs include isolator technology deployment rates and mutual recognition agreement implementation progress.
Sensitivities concentrate around NMPA enforcement intensity, API supply disruptions from Chinese bulk manufacturers, and biosimilar substitution policy shifts in South Korea. Forecasts reflect documented assumptions regarding regulatory harmonization velocity and hospital procurement consolidation trajectories. Quarterly review of provincial tender award data, CDSCO facility inspection outcomes, and MFDS approval timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Pharma PLM Market
Pharmaceuticals
Etoricoxib Market
Pharmaceuticals
Gastrointestinal Diseases Drug Development Market
Pharmaceuticals
Estrogen Replacement Therapy (ERT) Market
Pharmaceuticals
Sweden Pharmaceutical Market
Pharmaceuticals
Pharmacy Market
Pharmaceuticals
Europe Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Middle-East and Africa Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Hyperphosphatemia Drugs Market
Pharmaceuticals
HIV Antivirals Market
Pharmaceuticals
Tuberculosis Therapeutics Market
Pharmaceuticals
Hypertensive Emergency Medications Market
Pharmaceuticals
Drug-Induced Dyskinesia Market
Pharmaceuticals
Global Chickenpox Vaccine Market
Pharmaceuticals
Osteoarthritis Drugs Market
Pharmaceuticals
Guanethidine Market