
 Sitagliptin Market | 2026-2036
Sitagliptin Market Size, Share, and Industry Trends Forecast 2026-2036
Sitagliptin Market Insights
Multi-source API procurement is rebalancing toward qualified Indian and Chinese suppliers as Western manufacturers diversify beyond single-source dependence. Merck & Co., Inc. anchors the innovator segment with its original DPP-4 inhibitor franchise and sustained manufacturing scale. AstraZeneca competes through combination therapy portfolios that pair SGLT-2 inhibitors with complementary mechanisms. Pfizer Inc. leverages its generic infrastructure to supply cost-competitive sitagliptin tablets across regulated and emerging markets.
Sitagliptin is a selective dipeptidyl peptidase-4 inhibitor administered orally at doses of 25 mg, 50 mg, or 100 mg once daily to enhance incretin hormone activity and improve glycemic control in type 2 diabetes patients. The molecule functions by prolonging active GLP-1 and GIP levels, stimulating glucose-dependent insulin secretion while suppressing inappropriate glucagon release. Combination therapies dominate current revenue pools as clinicians prioritize dual-mechanism regimens for patients with inadequate monotherapy response, whereas the generics segment accelerates fastest as patent expirations across major markets unlock volume substitution. Oral tablets retain the largest share of delivery modes due to patient adherence advantages, though extended release formulations attract reformulation investment aimed at differentiated pharmacokinetic profiles.
The FDA enforces bioequivalence standards under 21 CFR 320 that generic sitagliptin manufacturers must satisfy for abbreviated new drug application approval, directly shaping development timelines and clinical trial investment. India's CDSCO aligns with ICH Q7 guidelines for API manufacturing while the PLI scheme incentivizes domestic DPP-4 inhibitor intermediate production, altering regional supply economics. Stakeholders must monitor evolving pharmacovigilance requirements for DPP-4 inhibitor cardiovascular outcomes as regulators tighten post-market surveillance expectations across multiple jurisdictions.
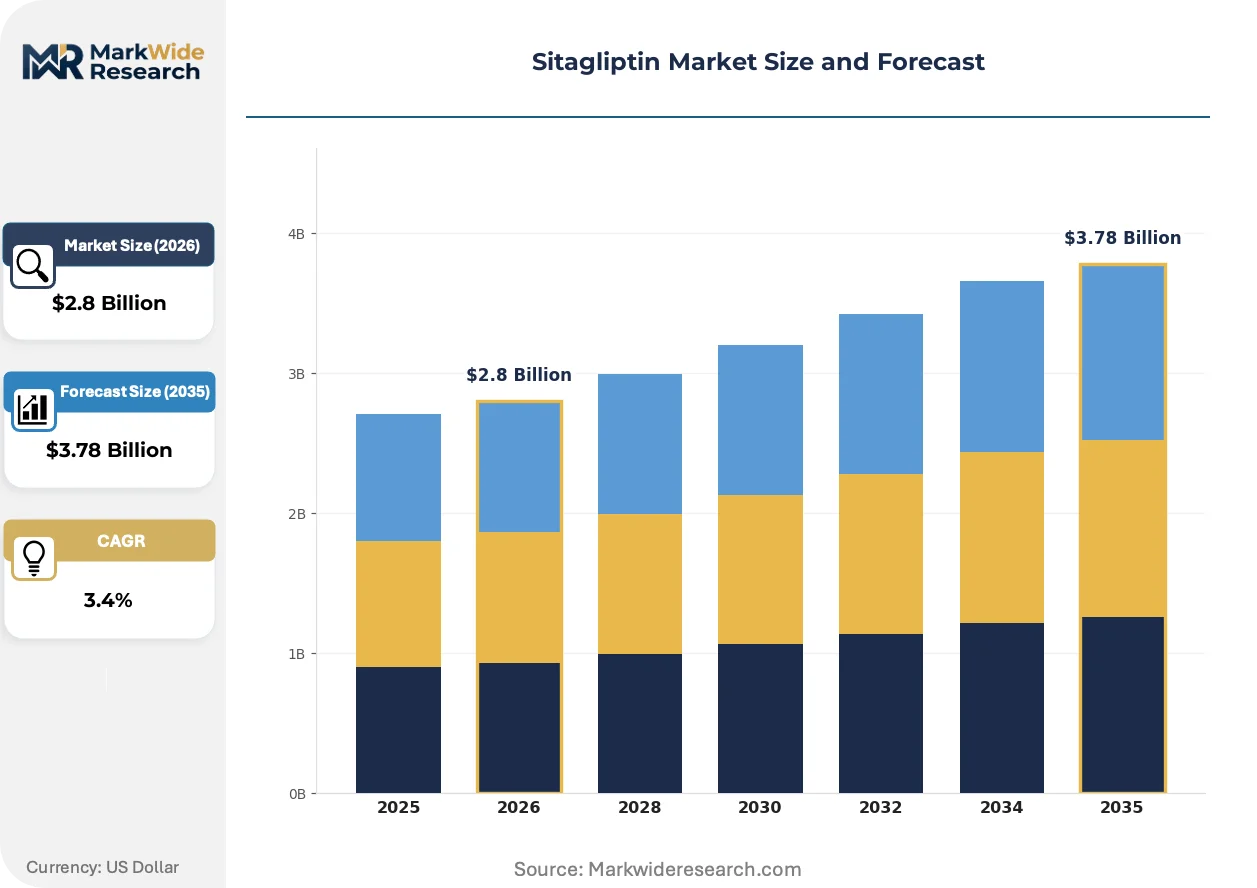
Market Dynamics
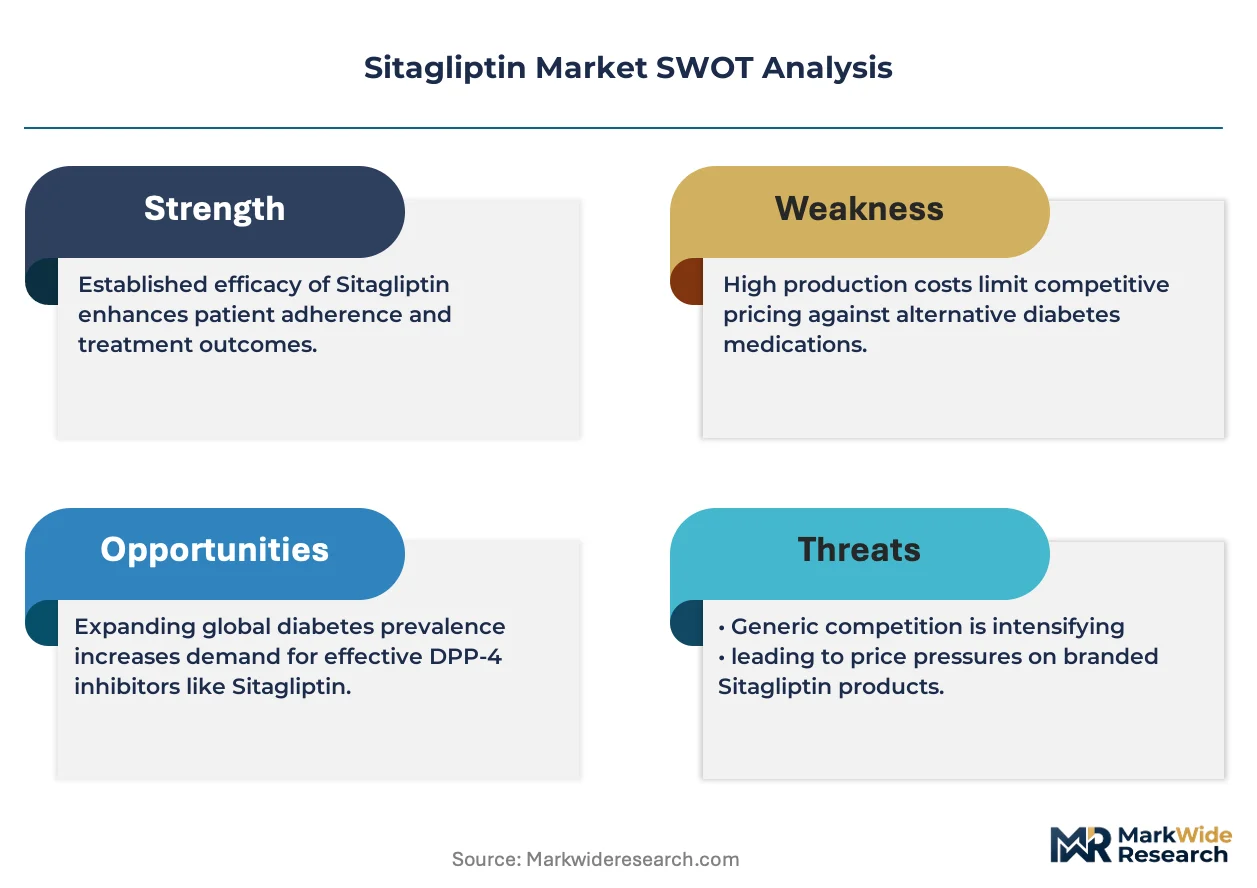
Patent cliff dynamics across major regulated markets are accelerating volume substitution toward generic DPP-4 inhibitors, compressing innovator pricing power while expanding accessible patient populations through cost reduction.
Growth Catalysts
- Hospital formulary expansion:Payer contracts increasingly prioritize glycemic control metrics, driving procurement of oral antidiabetic therapies into acute care settings.
- India's PLI scheme for APIs:Domestic pharmaceutical production incentives under CDSCO-aligned ICH Q7 guidelines are scaling DPP-4 inhibitor intermediate manufacturing capacity.
- Combination therapy protocols:Dual-mechanism regimens pairing SGLT-2 inhibitors with DPP-4 inhibitors are displacing monotherapy as first-line intensification strategies.
Market Restraints
- API supply concentration:Qualified suppliers cluster in India and China, creating single-source vulnerability for Western formulation manufacturers diversifying procurement.
- FDA bioequivalence requirements:21 CFR 320 standards for abbreviated new drug applications extend generic development timelines and inflate clinical trial investment thresholds.
- Cardiovascular outcome liabilities:Post-market pharmacovigilance obligations for DPP-4 inhibitor cardiac safety profiles elevate regulatory compliance costs across multiple jurisdictions.
Strategic Opportunities
- Extended-release formulations:Reformulation investment targeting differentiated pharmacokinetic profiles offers patent-protected lifecycle extension beyond immediate-release commoditization.
- Generic infrastructure leverage:Existing tablet manufacturing networks can capture volume substitution in emerging markets where originator patents have already expired.
- CDSCO registration pathways:India's streamlined approval frameworks for domestic API producers create first-mover positioning in price-sensitive South Asian markets.
Industry Challenges
- Bioanalytical capability scarcity:GLP-1 and GIP assay validation for bioequivalence studies requires specialized CRO capacity that concentrates in limited geographic clusters.
- Supply chain reconfiguration friction:Western manufacturers face qualification delays when shifting API procurement from legacy European suppliers to Indian CDSCO-certified facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sitagliptin Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sitagliptin, Combination Therapies, Generics, Brand Name Drugs End User: Hospitals, Clinics, Home Care Settings, Pharmacies Therapy Area: Type 2 Diabetes, Metabolic Disorders, Prediabetes, Cardiovascular Disorders Delivery Mode: Oral Tablets, Injectable Solutions, Extended Release Formulations, Others |
| Companies Covered | Merck & Co., Inc., AstraZeneca, Boehringer Ingelheim, Pfizer Inc., Eli Lilly and Company, Novartis AG, Sanofi, Takeda Pharmaceutical Company Limited, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sitagliptin Market Trends and Innovations
Formulation science and regulatory science are advancing in parallel, with delivery technology evolution and pharmacovigilance requirements together reshaping competitive differentiation in oral antidiabetic therapy.
Fixed-dose combination tablets integrating DPP-4 inhibitors with SGLT-2 inhibitors or metformin are converging with clinician preference for simplified dosing regimens. Hospital systems and large payer networks are adopting these combinations at accelerating rates to reduce pill burden and improve adherence metrics. This convergence is compressing standalone monotherapy volumes while expanding the addressable market for dual-mechanism products.
The FDA's sustained enforcement of 21 CFR 320 bioequivalence standards is elevating generic development complexity for DPP-4 inhibitors with narrow therapeutic indices. Manufacturers must demonstrate pharmacokinetic equivalence through rigorous fasting and fed studies, extending approval timelines by 12-18 months relative to conventional oral solids. Generic sponsors are responding by pre-submission meetings and adaptive trial designs to mitigate regulatory risk.
Hospital procurement committees are consolidating supplier relationships through sole-source or dual-source contracts for oral antidiabetic formularies, displacing fragmented multi-vendor purchasing. Group purchasing organizations are capturing increasing volume share from direct manufacturer contracts in the United States. This concentration is most visible in integrated delivery networks where pharmacy benefit managers and hospital systems share cost accountability.
Sitagliptin Market Segmentation
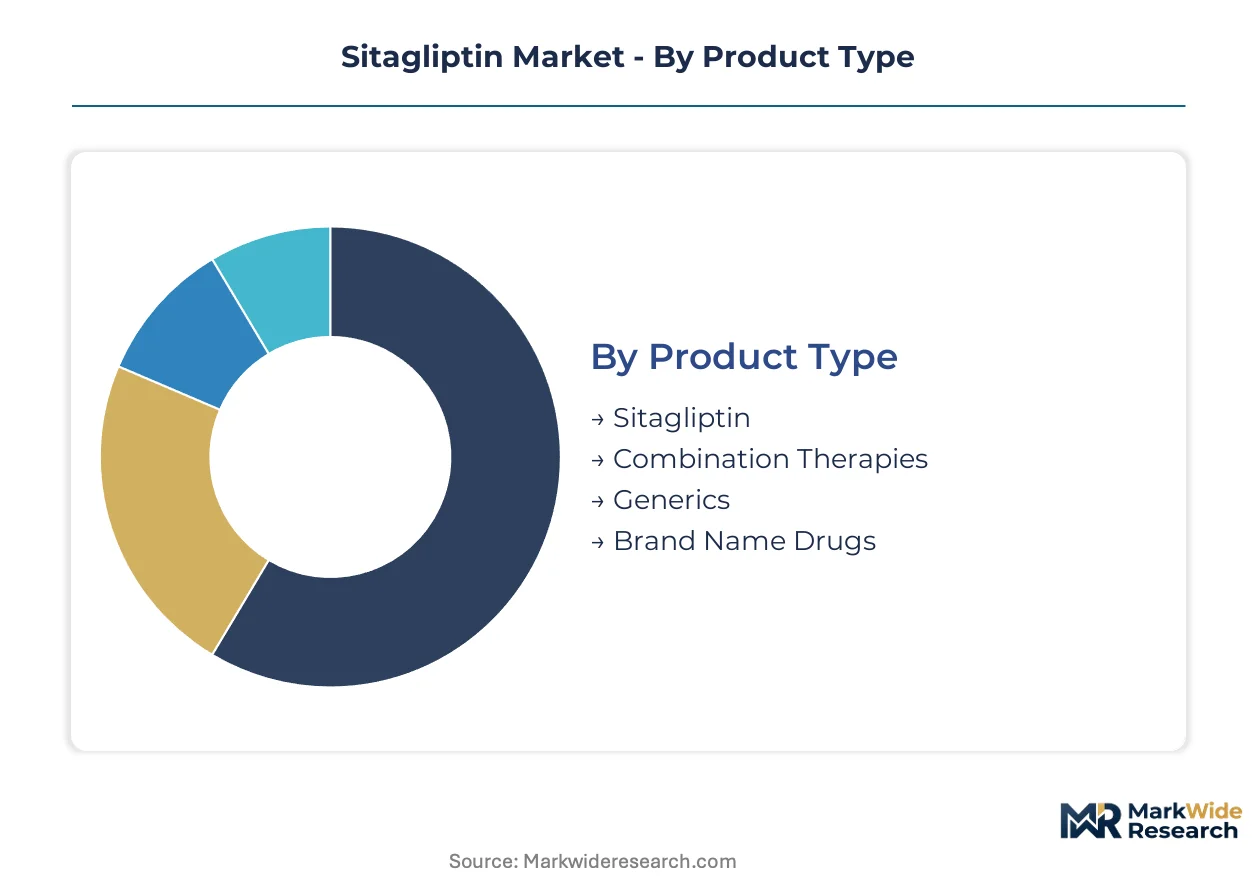
Segmentation in the Sitagliptin Market reveals distinct procurement patterns across therapy configurations and care settings. Each axis exposes different margin structures, regulatory pathways, and competitive intensity that shape strategic positioning.
Product Type:
Dosage form specifications and intellectual property status create four distinct competitive arenas with diverging investment requirements and pricing power.
- Sitagliptin:The original DPP-4 inhibitor molecule administered as monotherapy in 25 mg, 50 mg, or 100 mg tablets. Patent expiration across major regulated markets has compressed originator pricing while expanding prescription volume through improved formulary access.
- Combination Therapies:Fixed-dose formulations pairing sitagliptin with SGLT-2 inhibitors or metformin dominate hospital procurement as clinicians prioritize simplified regimens for intensification protocols. These products command premium positioning through differentiated clinical outcomes data.
- Generics:Bioequivalent tablets manufactured under FDA 21 CFR 320 or CDSCO guidelines capture accelerating volume as procurement committees consolidate around cost-effective suppliers. Indian and Chinese API producers anchor supply for Western formulation partners.
- Brand Name Drugs:Patent-protected originator products retain formulary presence in markets with delayed generic entry or where clinical differentiation supports continued reimbursement. Merck's original franchise maintains residual share through prescriber loyalty and established safety profiles.
Mature deployment sits with Brand Name Drugs. Newer deployment is concentrated in Generics.
End User:
Care setting economics and reimbursement mechanics fragment demand across institutional and retail channels with distinct procurement behaviors.
- Hospitals:Integrated delivery networks and group purchasing organizations consolidate antidiabetic procurement through sole-source contracts tied to glycemic control outcome metrics. Acute care settings drive volume for combination therapies administered during inpatient stays.
- Clinics:Outpatient facilities balance formulary compliance with patient-specific therapeutic adjustments, generating demand for flexible dosing options across monotherapy and combination portfolios.
- Home Care Settings:Long-term diabetes management in residential environments favors oral tablet convenience and adherence packaging. Care coordinators influence product selection through remote monitoring protocols.
- Pharmacies:Retail dispensing channels face direct patient cost sensitivity and pharmacy benefit manager tiering decisions that accelerate generic substitution rates.
Volume concentrates in Hospitals. Steepest expansion trajectory belongs to Home Care Settings.
Therapy Area:
Indication breadth extends beyond core diabetes into adjacent metabolic and cardiovascular applications with varying evidentiary requirements.
- Type 2 Diabetes:The primary approved indication driving prescription volume through glycemic control endpoints. Clinical guidelines position DPP-4 inhibitors as second-line or add-on therapy when metformin monotherapy proves inadequate.
- Metabolic Disorders:Off-label and investigational applications in polycystic ovary syndrome and non-alcoholic fatty liver disease attract specialized prescribing in academic medical centers with research protocols.
- Prediabetes:Preventive intervention applications remain limited by reimbursement constraints and risk-benefit calculations for pre-symptomatic populations, though emerging outcome data may expand addressable use.
- Cardiovascular Disorders:Post-market pharmacovigilance obligations and cardiovascular outcome trial data influence prescribing patterns in patients with established cardiac comorbidities, with regulatory scrutiny elevating documentation requirements.
Established utilization centers on Type 2 Diabetes. Emerging utilization is expanding in Metabolic Disorders.
Delivery Mode:
Pharmaceutical technology investments differentiate immediate-release commoditized tablets from reformulation opportunities with patent-protected profiles.
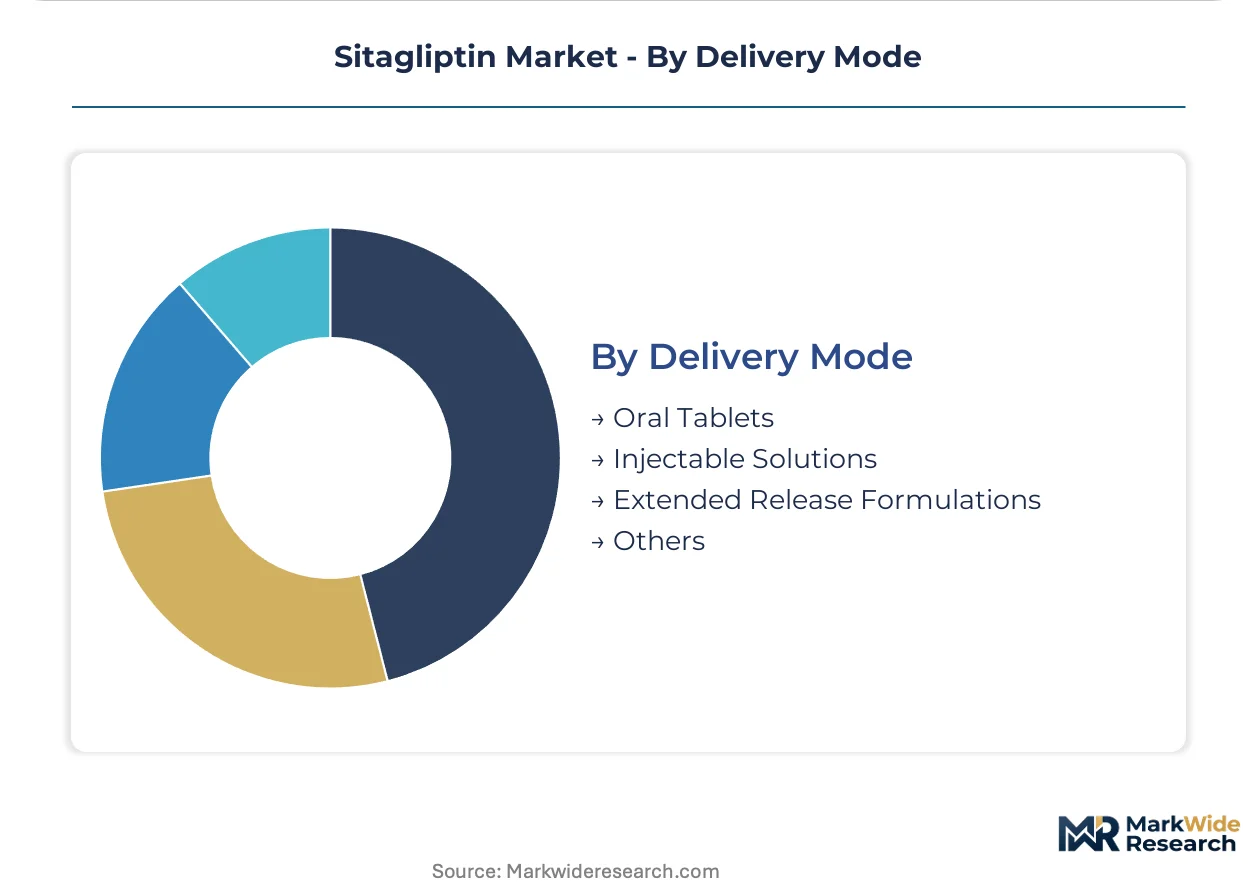
- Oral Tablets:Immediate-release formulations in standard dosages dominate prescription volume through manufacturing scale and patient acceptance. Bioequivalence requirements under FDA and CDSCO frameworks govern generic substitution.
- Injectable Solutions:Parenteral delivery remains minimal for DPP-4 inhibitors given the established efficacy of oral administration, though investigational depot formulations attract development interest for adherence improvement.
- Extended Release Formulations:Reformulation investment targets differentiated pharmacokinetic profiles with reduced dosing frequency. Patent-protected lifecycle extension strategies focus on these technologies as immediate-release products commoditize.
- Others:Novel delivery mechanisms including orally disintegrating tablets and fixed-dose combination packaging address specific patient population needs in geriatric or polypharmacy contexts.
Current production scale favors Oral Tablets. Reformulation investment is concentrating in Extended Release Formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API manufacturing for sitagliptin concentrates in Asian chemical hubs while formulation demand distributes across North American hospital networks and European reimbursement systems.
United States
Hospital procurement committees at integrated delivery networks consolidate oral antidiabetic purchasing through sole-source contracts tied to glycemic control metrics. FDA bioequivalence requirements under 21 CFR 320 govern generic sitagliptin approval timelines. New Jersey and Massachusetts host major pharmaceutical formulation facilities serving national distribution networks.
India
Domestic pharmaceutical production scales under CDSCO-aligned ICH Q7 guidelines with PLI scheme incentives for DPP-4 inhibitor intermediate manufacturing. CDSCO registration pathways streamline approval for domestic API producers targeting price-sensitive South Asian markets. Hyderabad and Ahmedabad anchor contract manufacturing clusters supplying Western formulation partners.
Germany
EMA pharmacovigilance requirements for cardiovascular outcomes shape prescribing patterns in patients with cardiac comorbidities. Statutory health insurance reimbursement frameworks prioritize cost-effective generic substitution once patent protection expires. Frankfurt and Munich concentration includes major distribution hubs for Central European hospital networks.
China
NMPA regulatory frameworks govern domestic manufacturing of DPP-4 inhibitor APIs with increasing alignment to international quality standards. Provincial pharmaceutical industrial parks in Jiangsu and Zhejiang attract investment for antidiabetic active ingredient production. Shanghai formulation facilities serve both domestic hospital procurement and export markets.
Japan
PMDA post-market surveillance obligations for cardiac safety profiles elevate documentation requirements for DPP-4 inhibitor prescribing. Universal health coverage reimbursement mechanisms emphasize bioequivalent generic substitution to contain pharmaceutical expenditure. Osaka and Tokyo pharmaceutical clusters concentrate formulation manufacturing for domestic distribution.
Sitagliptin Market Competitive Landscape
Global majors compete with regional champions across formulation scale and API supply integration. The market structure separates into patent-protected originators, multi-source generic manufacturers, and combination therapy specialists. Three archetypes dominate: innovator franchise holders defending lifecycle value, contract manufacturers capturing volume substitution, and portfolio diversifiers integrating SGLT-2 inhibitor pairings. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers reposition for post-patent dynamics.
Among innovator-origin companies, Merck & Co., Inc. and AstraZeneca occupy positions reflecting divergent strategic postures. Merck exemplifies the original DPP-4 inhibitor franchise holder managing lifecycle extension through manufacturing scale and established safety profiles. AstraZeneca represents the combination therapy specialist archetype, with portfolio construction emphasizing dual-mechanism regimens that pair complementary drug classes. Pfizer Inc. sits within the generic infrastructure tier, leveraging tablet manufacturing networks to supply cost-competitive products across regulated and emerging markets where patent cliffs have already occurred.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| AstraZeneca |
| Boehringer Ingelheim |
| Pfizer Inc. |
| Eli Lilly and Company |
| Novartis AG |
| Sanofi |
| Takeda Pharmaceutical Company Limited |
| GlaxoSmithKline plc |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap API producers in Gujarat and Hyderabad anchor upstream supply, connecting procurement discipline to downstream pricing power through captive intermediate manufacturing and CDSCO-aligned quality certifications.
Pricing Analysis
Warranty and service bundling separates originator brands from unbundled generic offerings, with Merck's original franchise commanding premium positioning through established safety documentation and prescriber support programs. Three-tier pricing structure across premium, standard, and economy levels reflects FDA bioequivalence tiering, volume scale, and geographic delivery cost differentials. Price erosion runs through immediate-release commoditized tablets as Indian and Chinese API producers expand qualified supply. Hospital procurement committees exhibit lowest price sensitivity due to glycemic control outcome guarantees, while retail pharmacy channels face direct patient cost pressure accelerating generic substitution.
Supply Chain Analysis
Dual-sourcing requirements mandated by Western formulation manufacturers are rebalancing procurement toward qualified Indian CDSCO-certified facilities and Chinese NMPA-registered producers, reducing legacy European supplier dependence. Active pharmaceutical ingredient production concentrates in India, China, and the United States, drawing from DPP-4 inhibitor intermediates, specialized solvents, and analytical reference standards. Single-source vulnerability persists for bioanalytical assay validation capacity concentrated in limited geographic clusters. Distribution runs through integrated delivery networks and group purchasing organizations consolidating sole-source contracts for hospital formularies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into API manufacturing represents the decisive competitive race, with backward control over DPP-4 inhibitor intermediates under India's PLI scheme offering margin defense against commoditization pressure.
For Market Incumbents: Anticipate accelerated volume substitution by securing captive supply of CDSCO-certified APIs through partnership or acquisition in Hyderabad-Ahmedabad manufacturing clusters. Defend formulary position through extended-release formulation investment creating patent-protected lifecycle extension beyond immediate-release generic erosion. Reinforce hospital procurement relationships through glycemic control outcome guarantees and sole-source contract structures. For New Entrants and Emerging Players: Direct-to-hospital digital procurement platforms offer the lowest-friction entry vector for qualified generic tablet suppliers seeking bypass of traditional distribution markups. Target price-sensitive South Asian markets through CDSCO registration pathways with streamlined domestic approval frameworks. Capture volume in emerging markets where originator patents have already expired, leveraging existing tablet manufacturing infrastructure without bioequivalence study investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor contract manufacturing organizations with validated FDA 21 CFR 320 bioequivalence dossiers and established Western formulation partnerships in the United States and Germany. Long-term viability hinges on API supply integration and extended-release pipeline assets within a five-to-ten year therapeutic window. Monitor FDA abbreviated new drug application approval velocity as inflection indicator for generic substitution pace.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Manufacturing | Captive supply of DPP-4 inhibitor intermediates under India's PLI scheme reduces procurement cost volatility. |
| Extended-Release Formulation Development | Patent-protected pharmacokinetic profiles defend margin against immediate-release commoditization pressure. |
| Hospital System Partnership | Sole-source contracts with integrated delivery networks lock in volume through glycemic control guarantees. |
| CDSCO Registration Pathway Investment | Streamlined domestic approval frameworks accelerate first-mover positioning in South Asian price-sensitive markets. |
| Bioequivalence Study Capability Expansion | In-house GLP-1 and GIP assay validation reduces dependence on scarce specialized CRO capacity clusters. |
Research Methodology
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, combined with primary interviews involving regulatory affairs leads, formulary directors, hospital procurement managers, and payer access specialists. Bottom-up prescription volume modeling and top-down pharmaceutical expenditure analysis enabled triangulation across data sources. Trade data from Indian DGFT and Chinese customs records supplemented API production estimates.
Historical trendline analysis of DPP-4 inhibitor prescription patterns, patent expiration timelines, and generic substitution rates established baseline trajectories across the projection horizon. Segmentation modeling incorporated treatment line positioning, dosage form specifications, administration route preferences, and regional regulatory cluster dynamics. CAGRs were derived from volume-demand elasticity functions calibrated to bioequivalence approval velocities and hospital formulary expansion rates.
Inputs from CDSCO manufacturing facility registrations and FDA abbreviated new drug application databases were available through the study window; gaps in real-time hospital procurement contract terms introduce uncertainty bands around volume concentration estimates. Deviation in FDA bioequivalence enforcement stringency or cardiovascular outcome trial findings would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Latin America FMD Vaccine Market
Pharmaceuticals
Global Anesthesia Drugs Market
Pharmaceuticals
Depression Drugs Market
Pharmaceuticals
Synthetic Drugs Market
Pharmaceuticals
Pantoprazole Market
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
Iodine Deficiency Drug Market
Pharmaceuticals
Global Cold and Flu Drugs Market
Pharmaceuticals
Global Immune Checkpoint Inhibitors Market
Pharmaceuticals
Alectinib Drugs Market
Pharmaceuticals
Germany Pharmaceutical Cold Chain Logistics Market
Pharmaceuticals
Latin America Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
Immunoglobulin Market
Pharmaceuticals
Unit Dose Manufacturing Market
Pharmaceuticals
Advanced Therapy Medicinal Products (Atmps) Market
Pharmaceuticals
Inotropic Agent Market