
 Saline Laxative Market | 2026-2036
Saline Laxative Market Size, Share, and Industry Trends Forecast 2026-2036
Saline Laxative Market Analytics
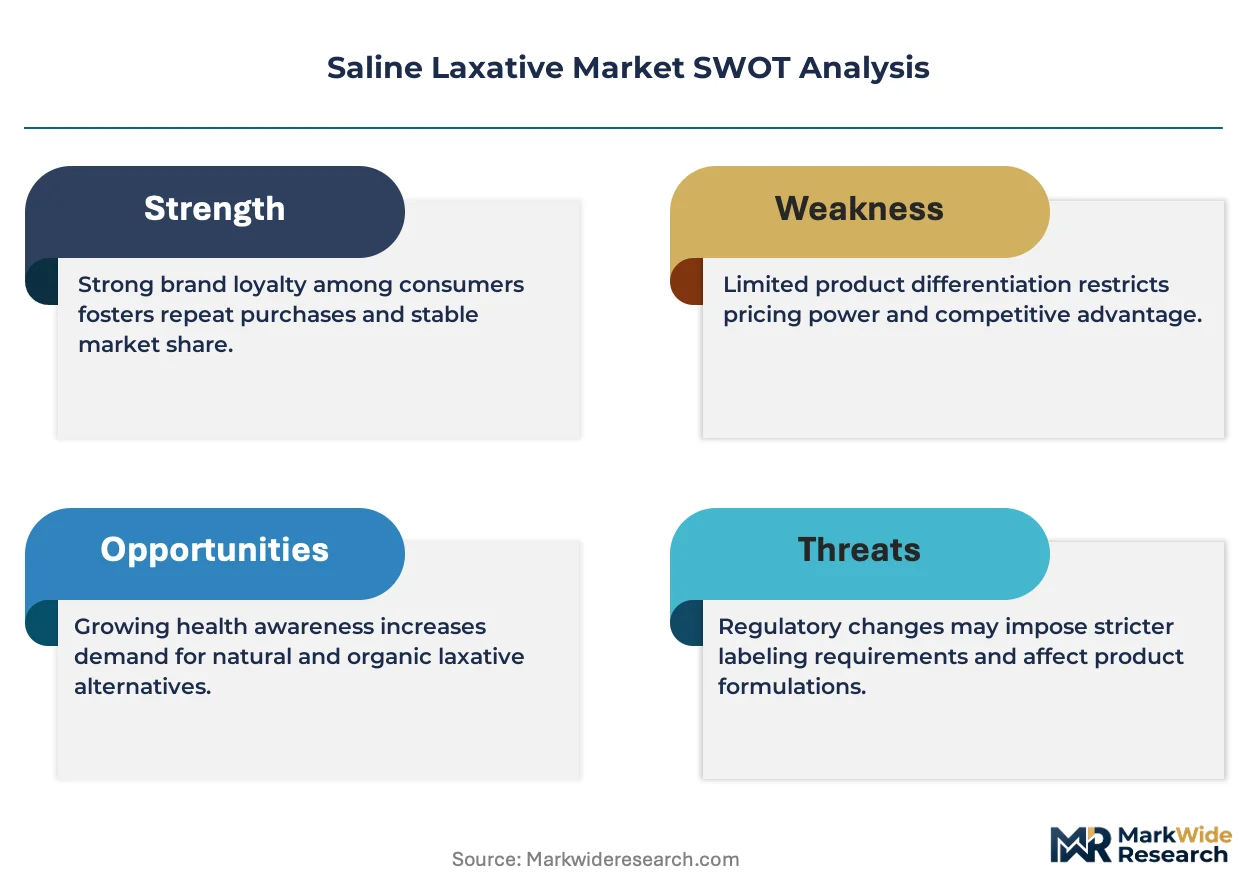
The FDA's updated safety communications on sodium phosphate renal risks is shifting demand toward magnesium-based alternatives across institutional buyers. Bayer AG leverages its consumer health infrastructure to sustain shelf presence in retail pharmacy channels. C.B. Fleet Company anchors the bowel preparation segment with specialized liquid formulations for procedural cleansing. Beutlich Pharmaceuticals LLC competes through hospital-focused distribution networks.
Saline laxatives are osmotic agents containing magnesium or sodium salts that draw water into the intestinal lumen through passive diffusion, typically producing evacuation within 30 minutes to 6 hours depending on compound and dose. Their primary commercial purpose spans both over-the-counter constipation relief and prescription bowel cleansing before endoscopic or surgical procedures. Magnesium citrate formulations occupy the fastest-expanding position within the product type dimension as clinicians seek alternatives with lower nephrotoxicity profiles. Liquid formulations dominate hospital and clinic procurement due to rapid onset reliability, while tablet and powder formats extend reach into home care settings where patient convenience drives selection.
FDA labeling requirements, USP monograph standards for saline cathartics, and Joint Commission medication management protocols collectively elevate product quality thresholds and restrict market access for non-compliant manufacturers. The EPA's pharmaceutical discharge guidelines additionally shape manufacturing facility compliance investments. Stakeholders must monitor evolving renal safety data and corresponding regulatory responses to determine formulation portfolio priorities.
Market Dynamics
FDA renal safety warnings on sodium phosphate formulations are forcing institutional buyers toward magnesium-based alternatives, restructuring procurement patterns across hospital systems and ambulatory surgical centers.
Growth Catalysts
- Aging Demographics:The United States population over 65 years drives diagnostic colonoscopy volumes, expanding institutional demand for procedural bowel preparation solutions.
- Outpatient Surgical Migration:Ambulatory surgery center expansion accelerates consumption of single-dose liquid formulations optimized for same-day discharge protocols.
- REACH Chemical Registration:European magnesium salt manufacturers gain competitive access as compliance barriers filter non-registered sodium phosphate competitors from EU hospital tenders.
Market Restraints
- Magnesium Sulfate Feedstock Volatility:Mining concentration in China's Liaoning province creates input cost exposure for formulation manufacturers dependent on bulk mineral supply.
- Nephrotoxicity Liability Thresholds:FDA boxed warning requirements elevate product liability insurance costs and deter new market entrants lacking clinical safety databases.
- Polyethylene Glycol Substitution:PEG-electrolyte solutions capture share in prescription bowel prep as gastroenterologists prioritize renal safety over osmotic speed.
Strategic Opportunities
- Home-Based Diagnostic Preparation:Direct-to-patient distribution models bypass hospital pharmacy formularies, capturing value from telehealth-integrated colonoscopy scheduling.
- Japan's Elderly Care Infrastructure:METI long-term care insurance expansions create reimbursement pathways for OTC magnesium citrate in institutional eldercare settings.
- Combination Formulation Development:Simethicone-integrated magnesium products address bloating complaints, differentiating against commodity saline laxatives in retail pharmacy.
Industry Challenges
- Formulation Stability Expertise:Shortage of pharmaceutical chemists specializing in high-osmolarity liquid stability creates bottlenecks in product line extensions.
- USP Monograph Conformance Timelines:Updated saline cathartic purity standards demand 18-24 month validation cycles, delaying new product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saline Laxative Market |
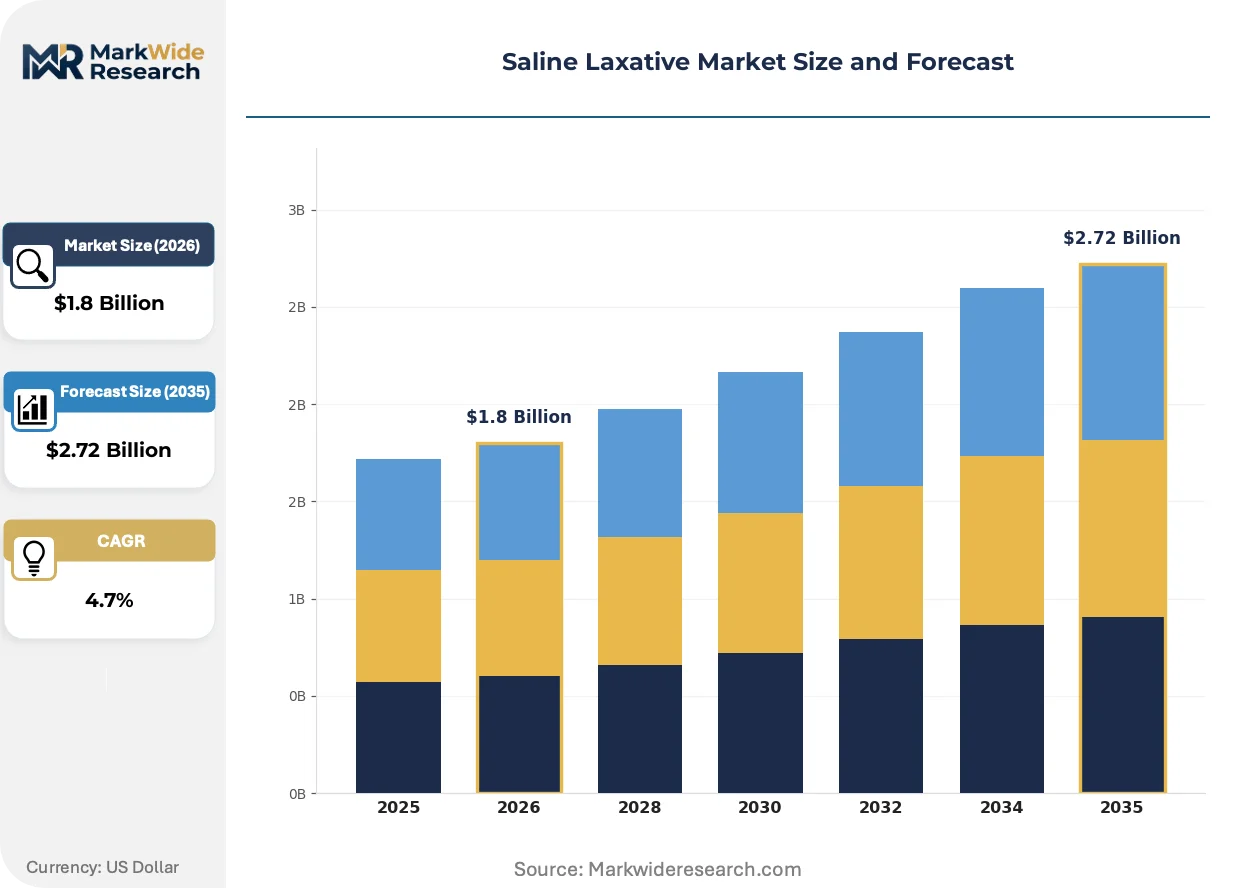
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnesium Citrate, Sodium Phosphate, Epsom Salt, Sodium Sulfate Formulation: Liquid, Powder, Tablet, Granule End User: Hospitals, Clinics, Pharmacies, Home Care Distribution Channel: Online, Retail, Wholesale, Healthcare Facilities |
| Companies Covered | Bayer AG, Beutlich Pharmaceuticals LLC, C.B. Fleet Company, Salix Pharmaceuticals, Cardinal Health, McKesson Corporation, Walgreen Co, The Kroger Company, Prestige Consumer Healthcare Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saline Laxative Market Evolving Landscape
Electrolyte-balanced magnesium formulations are displacing legacy sodium phosphate compositions as clinicians prioritize renal safety alongside cathartic efficacy.
Microencapsulated magnesium citrate technology is electrifying the tablet segment, enabling delayed-release kinetics that match liquid onset speeds while preserving patient convenience. Hospital outpatient departments are piloting these formats for take-home colonoscopy prep kits. The technology is compressing differentiation advantages historically held by liquid-only manufacturers.
EPA pharmaceutical discharge guidelines are tightening manufacturing facility wastewater standards, forcing capital investment in closed-loop solvent recovery systems. Bulk chemical producers serving the saline laxative supply chain face compliance deadlines that favor integrated manufacturers with captive purification infrastructure. Contract formulation facilities in the US Southeast are consolidating as smaller operators exit rather than retrofit.
Hospital procurement committees are unbundling bowel preparation from endoscopy service contracts, creating standalone tender categories that reward unit-dose packaging innovations. Gastroenterology practice groups in Texas and Florida are driving this specification shift. The change exposes pure-play manufacturers to price transparency while favoring suppliers with flexible packaging configurations.
Saline Laxative Market Segmentation
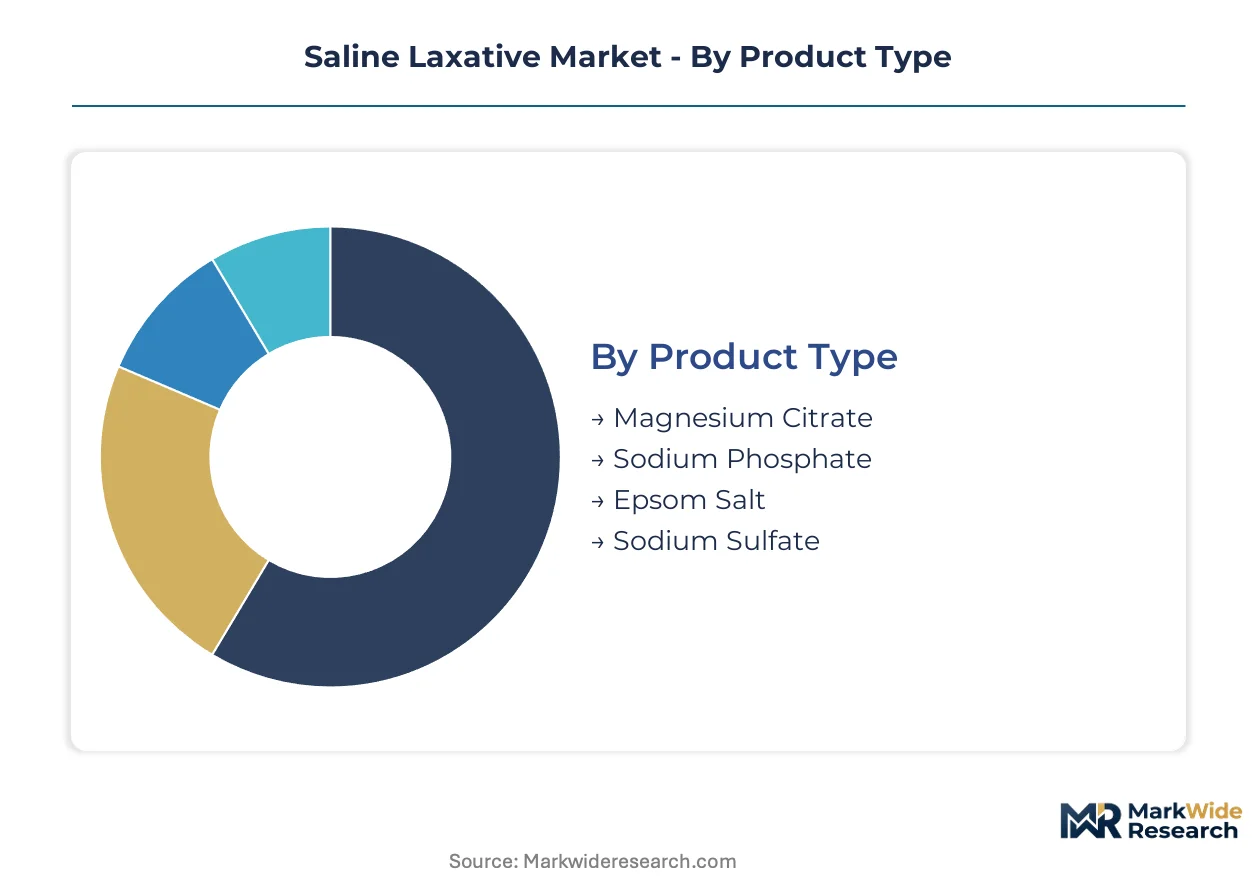
Segmentation in saline laxatives determines regulatory pathway complexity, procurement channel access, and reimbursement eligibility. Manufacturers optimize portfolio mix across these dimensions to match institutional tender specifications and retail pharmacy formulary requirements.
Product Type:
FDA renal safety labeling requirements fall heaviest on sodium phosphate formulations, while magnesium-based alternatives navigate lighter regulatory scrutiny. EMA and Health Canada maintain parallel vigilance databases that influence formulation decisions across North American and European manufacturing.
- Magnesium Citrate:Organic magnesium salt with superior bioavailability and lower nephrotoxicity profile compared to sodium-based alternatives. Demand concentrates in United States ambulatory surgical centers as clinicians abandon sodium phosphate for pre-procedural bowel preparation. FDA's ongoing safety communications accelerate this substitution pattern.
- Sodium Phosphate:Inorganic salt compound with rapid osmotic action but elevated renal risk requiring boxed warnings. Procurement contracts in Texas and Florida hospital systems now exclude this formulation from colonoscopy prep protocols. Product liability insurance costs deter new market entrants.
- Epsom Salt:Magnesium sulfate heptahydrate with established USP monograph standards for OTC constipation relief.
- Sodium Sulfate:Anhydrous inorganic salt primarily employed in combination bowel preparation regimens.
Magnesium citrate sits at the top of the volume ranking, with sodium phosphate contracting fastest amid safety-driven procurement exclusions.
Formulation:
Cost tiers separate hospital procurement from retail self-selection, with liquid formats commanding premium unit pricing against commodity powder and tablet alternatives. Packaging complexity and stability validation requirements scale with osmolarity concentration.
- Liquid:High-osmolarity aqueous solutions with immediate bioavailability and predictable evacuation timing. United States hospital outpatient departments specify unit-dose liquid vials for take-home colonoscopy kits. Rapid onset reliability justifies premium pricing in procedural settings.
- Tablet:Solid oral dosage with microencapsulated delayed-release technology matching liquid onset speeds. Microencapsulated magnesium citrate tablets are electrifying home care demand as patients prioritize convenience over hospital pharmacy dispensing.
- Powder:Bulk reconstitution format with extended shelf stability and lower shipping costs.
- Granule:Free-flowing particulate intermediate between powder and tablet dissolution profiles.
Liquid formulations retain institutional dominance, though tablet formats are climbing fastest on microencapsulation advances.
End User:
Customer type dictates specification rigor, with hospitals enforcing Joint Commission medication management protocols that home care settings bypass entirely. Reimbursement pathways diverge sharply across these channels.
- Hospitals:Institutional buyers with formulary committees screening for FDA boxed warnings and USP monograph conformance. United States health systems in California and New York now mandate magnesium-based alternatives for all elective colonoscopy procedures.
- Clinics:Ambulatory facilities with lighter inventory requirements favoring single-dose liquid procurement.
- Pharmacies:Retail dispensaries stocking OTC magnesium citrate alongside prescription bowel prep alternatives.
- Home Care:Direct-to-patient distribution bypassing institutional pharmacy intermediaries.
Hospitals anchor procurement volume, while home care gains share fastest on telehealth-integrated diagnostic scheduling.
Distribution Channel:
Channel selection determines price transparency exposure and packaging specification requirements. Healthcare facilities impose unit-dose and bar-coding standards that retail and wholesale channels ignore.
- Online:Direct-to-consumer platforms with subscription replenishment models for chronic constipation management. Amazon and specialized pharmacy platforms capture growing magnesium citrate volume as patients research renal safety profiles independently.
- Retail:Brick-and-mortar pharmacies with shelf-space competition driving brand concentration.
- Wholesale:Distributor intermediaries serving independent pharmacies and small clinic networks.
- Healthcare Facilities:Direct manufacturer contracting with group purchasing organizations.
Healthcare facilities dominate contract value, with online channels expanding most quickly on patient-directed research behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists cluster around pharmaceutical manufacturing hubs in the United States, Germany, and Japan, anchoring regional production capacity for high-osmolarity saline laxatives.
United States
Ambulatory surgery centers in Texas and Florida drive institutional procurement of magnesium citrate formulations as colonoscopy volumes rise among patients over 65. FDA boxed warning requirements on sodium phosphate products reshape hospital formulary decisions nationwide. New Jersey and Pennsylvania host contract manufacturing organizations specializing in liquid bowel preparation solutions.
Germany
EMA vigilance databases influence magnesium salt formulation standards across European hospital systems. REACH chemical registration compliance filters non-registered sodium phosphate competitors from EU procurement tenders. Bavaria's pharmaceutical manufacturing corridor concentrates formulation facilities serving central European distribution networks.
Japan
METI long-term care insurance expansions create reimbursement pathways for OTC magnesium citrate in institutional eldercare settings. PMDA pharmacovigilance protocols maintain stringent renal safety documentation requirements for osmotic laxatives. The Kansai region around Osaka anchors domestic production of electrolyte-balanced bowel preparation solutions.
India
CDSCO regulatory pathways for saline cathartics attract contract manufacturing investment from multinational pharmaceutical firms. Bulk magnesium sulfate feedstock availability from domestic mining operations supports cost-competitive formulation production. Gujarat's pharmaceutical manufacturing belt specializes in USP-grade mineral salt processing for export markets.
China
NMPA oversight of pharmaceutical-grade mineral salts shapes export competitiveness for magnesium-based laxative ingredients. Liaoning province's mining concentration creates input cost exposure for global formulation manufacturers dependent on bulk magnesium sulfate supply. The Yangtze River Delta hosts purification facilities serving international contract formulation demand.
Saline Laxative Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the saline laxative market, with integrated chemical manufacturers holding cost advantages in bulk mineral salt supply while specialized pharmaceutical firms dominate finished formulation innovation. The vendor base separates into three tiers: multinational consumer health conglomerates with retail pharmacy infrastructure, hospital-focused specialty pharmaceutical companies with procedural cleansing expertise, and regional generic manufacturers competing on price. Consolidation pressures concentrate among contract formulation facilities as EPA discharge compliance costs force smaller operators to exit. Dominant competitive moves include backward integration into captive magnesium salt purification and portfolio diversification toward electrolyte-balanced alternatives.
Within the multinational consumer health tier, Bayer AG exemplifies asset-light brand leverage through retail pharmacy channel presence. C.B. Fleet Company anchors the hospital-focused specialty segment with concentrated expertise in procedural bowel preparation. Beutlich Pharmaceuticals LLC occupies a position emphasizing institutional distribution networks over direct consumer marketing. These three entities represent distinct strategic archetypes rather than direct peer competitors, with each optimizing for different procurement channel specifications and patient access points.
| Leading Market Players |
|---|
| Bayer AG |
| Beutlich Pharmaceuticals LLC |
| C.B. Fleet Company |
| Salix Pharmaceuticals |
| Cardinal Health |
| McKesson Corporation |
| Walgreen Co |
| The Kroger Company |
| Prestige Consumer Healthcare Inc |
| Others |
Value Network & Pricing Analysis
Specialized pharmaceutical chemists in New Jersey and Pennsylvania command wage premiums that compress margin spreads between premium liquid formulations and commodity powder alternatives. Labor-cost differentials between these formulation hubs and lower-cost manufacturing regions in India and China directly shape three-tier pricing structures across the saline laxative market.
Pricing Analysis
Contract-based long-term offtake agreements dominate hospital procurement, with unit-dose liquid vials commanding substantial premiums over bulk powder formats. Price differentiation hinges on USP monograph certification tier and volume scale, with ambulatory surgery centers showing highest sensitivity due to bundled reimbursement constraints. Cost compression in sodium phosphate segments is intensifying because FDA boxed warnings trigger procurement exclusions, forcing distressed pricing to clear residual inventory.
Supply Chain Analysis
Reverse-logistics flows for expired bowel preparation kits are minimal given single-use clinical protocols, though hospital consolidation programs increasingly mandate supplier take-back of damaged or recalled inventory. Bulk magnesium sulfate feedstock concentrates in China's Liaoning province, India's Gujarat belt, and Germany's Bavarian chemical corridor. Formulation manufacturers draw from these mining regions while facing single-source vulnerability in high-purity mineral salt purification. Distribution runs through healthcare group purchasing organizations and specialized pharmaceutical wholesalers serving ambulatory surgical networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The saline laxative market functions as a regulatory compounder where FDA renal safety milestones continuously restructure demand toward magnesium-based alternatives, rewarding manufacturers with preemptive formulation pivots.
For Market Incumbents: Acquire captive magnesium salt purification assets to secure feedstock cost advantages as Liaoning mining concentration elevates input price volatility. C.B. Fleet Company and Bayer AG should expand electrolyte-balanced formulation capacity in Pennsylvania and New Jersey to preempt polyethylene glycol substitution in hospital formularies. Backward integration into USP-grade mineral processing insulates margin structures from Chinese export quota fluctuations. For New Entrants and Emerging Players: Direct-to-patient subscription platforms offer the most penetrable entry vector, bypassing entrenched hospital pharmacy formularies through telehealth-integrated colonoscopy scheduling. Target home care segments in Texas and Florida where microencapsulated tablet adoption outpaces liquid dispensing. White-label manufacturing partnerships with Gujarat-based CDSCO-registered facilities enable rapid cost-competitive scale without capital-intensive US facility construction. For Investors and Strategic Acquirers: Consumer health conglomerates are the most active acquirer in this space, seeking bolt-on magnesium citrate portfolios to complement existing gastrointestinal franchises. Long-term viability favors manufacturers with dual regulatory track records across FDA and EMA jurisdictions, insulating against single-market pricing pressure. Monitor PMDA pharmacovigilance bulletins for early signals of renal safety scrutiny spreading to Japanese magnesium salt approvals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnesium Salt Purification | Captive USP-grade feedstock production insulates margin structures from Liaoning mining concentration risks. |
| Microencapsulated Tablet Line Extension | Delayed-release kinetics match liquid onset speeds while capturing home care convenience premiums. |
| Direct-to-Patient Distribution Launch | Telehealth-integrated colonoscopy scheduling bypasses hospital pharmacy formulary gatekeepers. |
| Electrolyte-Balanced Formulation Development | Renal safety profiles differentiate against legacy sodium phosphate compositions facing procurement exclusions. |
| EMA Parallel Registration Pathway | Dual-jurisdiction approval expands addressable market beyond FDA-dependent hospital systems. |
Research Methodology
Coverage spans the United States, Germany, Japan, India, and China, with primary inputs from each market anchoring regional demand calibration. The analysis combines interviews with hospital procurement managers, formulary directors at ambulatory surgery centers, pharmaceutical chemists specializing in high-osmolarity liquids, and regulatory affairs leads at magnesium salt manufacturers. Secondary validation draws from FDA safety communications, EMA vigilance databases, USP monograph updates, and hospital GPO contract disclosures. Bottom-up volume estimates triangulate against top-down expenditure flows from Medicare outpatient claims data.
Granularity extends to product type, formulation format, end-user channel, and distribution pathway, with additional modeling of state-level colonoscopy volume differentials across the analysis window. CAGRs derive from logistic adoption curves fitted to historical procurement patterns and projected outpatient surgical migration trends. Forecast inputs incorporate Joint Commission medication management protocol adoption timelines and EPA pharmaceutical discharge compliance investment cycles.
The model assumes a particular technology adoption path; alternative pathways for microencapsulated delayed-release kinetics would alter the outlook if bioequivalence studies fail to match liquid onset reliability. Practitioners should monitor FDA boxed warning expansion scope, REACH chemical registration enforcement intensity, and PMDA renal safety documentation requirements for early signals of regulatory trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
United Kingdom OTC Drugs Market
Pharmaceuticals
Organ Transplant Rejection Medications Market
Pharmaceuticals
Hyoscine-N-Butyl Bromide Market
Pharmaceuticals
Attenuated Vaccines Market
Pharmaceuticals
Herpes Labialis Treatment Market
Pharmaceuticals
Blood Clotting Accelerant Market
Pharmaceuticals
Authorized Generics Market
Pharmaceuticals
Ophthalmic Drug Delivery Systems Market
Pharmaceuticals
Global Online Pharmacy Market
Pharmaceuticals
North America Hormone Replacement Therapy Market
Pharmaceuticals
Global Endometriosis Drugs Market
Pharmaceuticals
Europe Contraceptives Market
Pharmaceuticals
Global Janus Kinase Inhibitor (JAK) Market
Pharmaceuticals
Organ Transplant Immunosuppressant Drugs Market
Pharmaceuticals
Wilson Disease Drugs Market
Pharmaceuticals
Europe Heparin Market