
 Global Antiemetic Drugs Market | 2026-2036
Global Antiemetic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antiemetic Drugs Market Foresight
FDA Good Manufacturing Practice certification for sterile injectable antiemetics is redrawing competitive boundaries in the intravenous segment. Pfizer Inc. leverages its oncology portfolio depth to anchor hospital formulary contracts across North American cancer centers. Sanofi sustains brand loyalty in the postoperative nausea segment through established anesthesiology relationships. Merck KGaA differentiates via neurokinin-1 receptor antagonist specialization, a higher-margin niche with limited generic penetration.
Antiemetic drugs comprise pharmacological agents that antagonize neurotransmitter receptors—principally 5-HT3, D2, NK-1, and CB1 subtypes—to suppress vomiting center activation in the medulla oblongata. These compounds function as critical supportive-care therapeutics enabling patients to complete curative chemotherapy regimens without dose reduction or discontinuation. Serotonin receptor antagonists occupy the largest revenue pool due to entrenched oncology protocols, while neurokinin-1 antagonists generate superior per-unit margins despite smaller prescription volumes. The intravenous route dominates hospital and oncology center administration, though transdermal delivery for motion sickness and home healthcare applications commands expanding interest from payers seeking administration cost reduction.
FDA oncology supportive-care guidelines, EMA's MDR compliance requirements for combination-device presentations, and WHO essential medicines list inclusion collectively determine market access tiers and reimbursement eligibility across developed markets. REACH chemical registration in Europe constrains active pharmaceutical ingredient sourcing flexibility, elevating compliance costs for manufacturers dependent on Asian supply intermediates. Stakeholders must monitor FDA label expansion decisions for NK-1 antagonists into delayed-phase chemotherapy-induced nausea, as this indication boundary will determine whether premium-priced assets retain differentiation against commoditized 5-HT3 generics.
Market Dynamics
FDA accelerated approval pathways for supportive-care oncology drugs compress development timelines, forcing manufacturers to front-load clinical investment while oncology centers consolidate purchasing power around formulary-preferred suppliers.
Growth Catalysts
- Oncology center expansion:Chemotherapy protocol proliferation drives demand for intravenous antiemetics in hospital outpatient settings across the United States.
- EMA MDR compliance:Combination-device presentation requirements for transdermal delivery systems create regulatory moats protecting compliant manufacturers.
- 5-HT3 receptor antagonist protocol entrenchment:Standard-of-care status in oncology supportive-care guidelines locks in recurring prescription volumes.
Market Restraints
- REACH chemical registration:Active pharmaceutical ingredient sourcing flexibility constraints elevate compliance costs for European manufacturers dependent on Asian supply intermediates.
- Generic 5-HT3 commoditization:Patent expiration waves compress pricing power for serotonin receptor antagonists in mature markets.
- Delayed-phase NK-1 indication boundary:Limited label expansion for neurokinin-1 antagonists restricts premium pricing differentiation against commoditized alternatives.
Strategic Opportunities
- Home healthcare channel development:Payer pressure for administration cost reduction expands transdermal and oral antiemetic demand outside hospital settings.
- India CDSCO pathway utilization:Emerging market regulatory harmonization enables earlier market entry for biosimilar supportive-care agents.
- Neurokinin-1 and 5-HT3 combination protocols:Dual-mechanism regimens in high-emetic-risk chemotherapy create adherence-based revenue capture.
Industry Challenges
- Sterile injectable GMP certification timelines:FDA facility inspection backlogs delay product launches and contract manufacturing transfers.
- Formulary consolidation complexity:Hospital purchasing committee standardization limits physician prescribing autonomy and brand access.
- Supply chain reconfiguration friction:API geographic concentration risk requires dual-sourcing qualification without disrupting batch consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antiemetic Drugs Market |
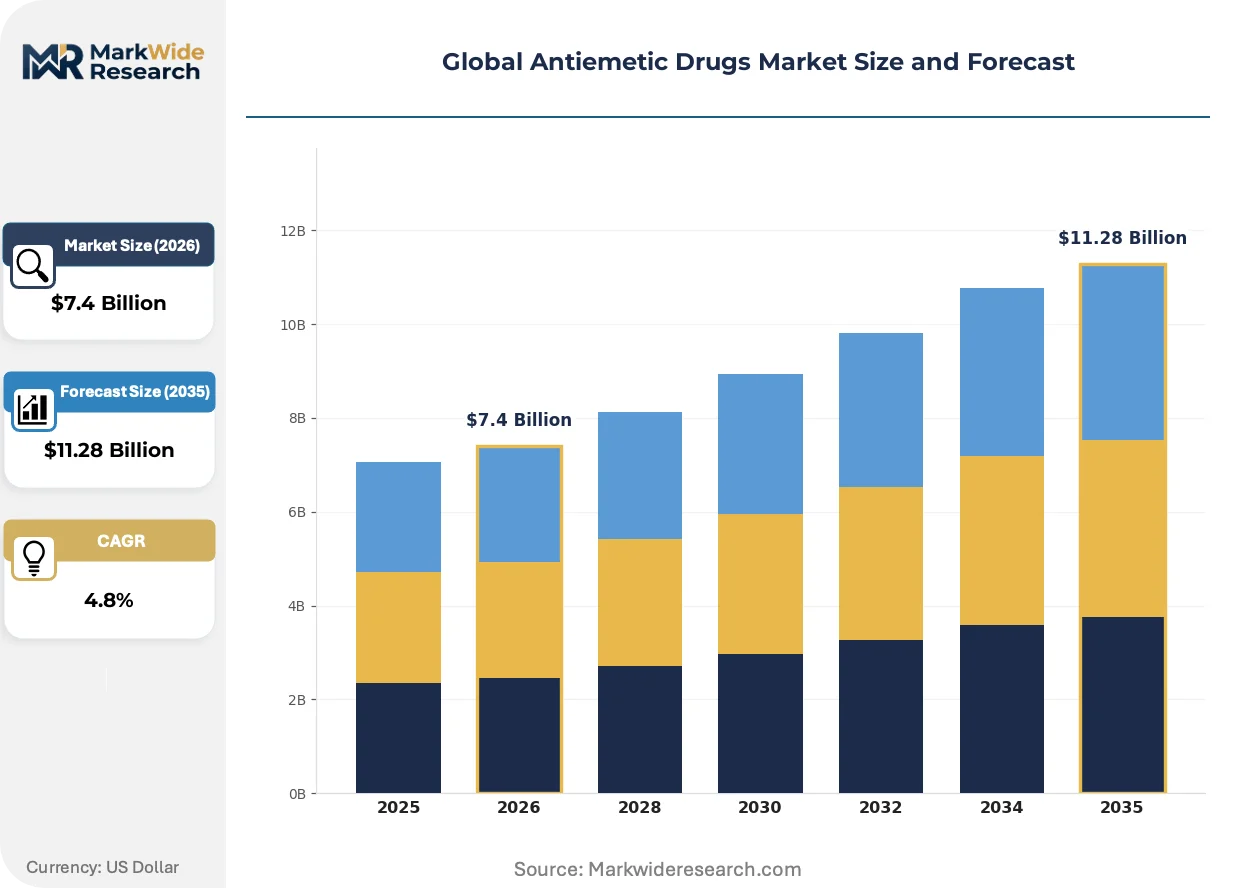
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $11.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serotonin Receptor Antagonists, Dopamine Antagonists, Anticholinergics, Neurokinin-1 Antagonists, Cannabinoids Therapy Area: Chemotherapy-Induced Nausea, Postoperative Nausea, Motion Sickness, Pregnancy-Induced Nausea, Gastrointestinal Disorders End User: Hospitals, Oncology Centers, Ambulatory Surgical Centers, Outpatient Clinics, Home Healthcare Providers Route of Administration: Oral, Intravenous, Intramuscular, Transdermal, Sublingual |
| Companies Covered | Cipla Inc., Sanofi, Pfizer Inc., Eagle Pharmaceuticals, Inc., Astellas Pharma Inc., Johnson & Johnson Services, Inc., Merck KGaA, Viatris Inc., GSK plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antiemetic Drugs Market Shifts & Advancements
Transdermal delivery systems and combination receptor-targeting protocols are fragmenting the traditional intravenous-dominant administration model while regulatory data requirements intensify.
Long-acting 5-HT3 receptor antagonist formulations are decomposing the conventional multi-dose intravenous administration cycle in outpatient oncology. Cancer centers in the United States adopt monthly depot injections to reduce chair time and nursing labor. This shift compresses per-patient revenue frequency while expanding total addressable volume through compliance improvement.
EMA MDR technical documentation requirements for combination-device presentations are elevating development costs for transdermal patch manufacturers. European notified body capacity constraints extend approval timelines by twelve to eighteen months. Smaller sponsors retreat from combination product development, ceding white space to established device-drug integrators with dedicated regulatory infrastructure.
Hospital formulary consolidation is compressing supplier rosters to three preferred vendors per therapeutic class. Oncology group purchasing organizations in the United States negotiate multi-year contracts bundling antiemetics with chemotherapy agents. This concentration forces secondary manufacturers toward specialty clinic channels and cash-pay motion sickness segments where purchasing autonomy persists.
Global Antiemetic Drugs Market Segmentation
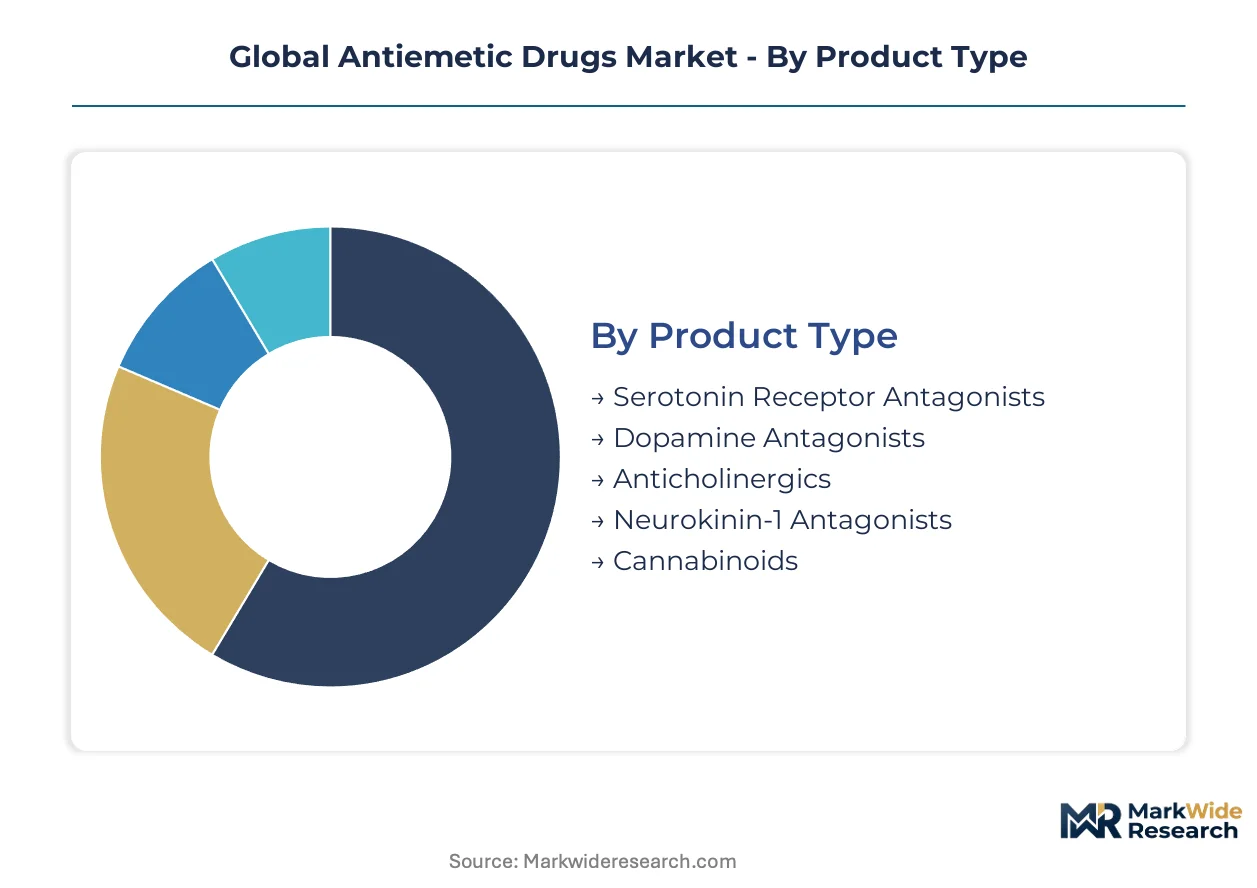
Antiemetic drug segmentation reveals distinct substitution dynamics across receptor-targeting technologies, with generic incursion reshaping competitive boundaries in mature pharmacological classes. Understanding segment-level vulnerability to therapeutic alternatives and administration-mode switching enables precise portfolio positioning against evolving clinical protocols and payer cost-containment mandates.
Product Type:
Serotonin receptor antagonists face the most acute substitution pressure from commoditized generics, while neurokinin-1 antagonists maintain structural pricing power through indication-specific label protections.
- Serotonin Receptor Antagonists:These 5-HT3-targeting agents, including ondansetron and palonosetron formulations, constitute the largest prescription volume pool in oncology supportive care. Demand concentrates in United States hospital outpatient departments where ASCO guideline entrenchment locks in protocol-standard status, though FDA-approved generic equivalents now capture over half of new prescriptions in mature markets.
- Neurokinin-1 Antagonists:Aprepitant and fosaprepitant compositions deliver superior efficacy in delayed-phase chemotherapy-induced nausea through substance P pathway blockade. Oncology centers in Germany and Japan adopt these agents for high-emetic-risk regimens despite premium pricing, driven by complete response rate advantages in CINV combination protocols.
- Dopamine Antagonists:Prochlorperazine and metoclopramide formulations serve cost-sensitive postoperative and emergency department applications.
- Anticholinergics:Scopolamine derivatives dominate motion sickness prophylaxis with established transdermal delivery infrastructure.
- Cannabinoids:Dronabinol and nabilone occupy restricted-access oncology and AIDS wasting syndrome niches under controlled-substance scheduling.
Serotonin receptor antagonists anchor the volume base while neurokinin-1 antagonists gain share at the steepest rate.
Therapy Area:
Cost tier stratification separates curative oncology applications from symptomatic management segments, with reimbursement intensity determining manufacturer investment priority.
- Chemotherapy-Induced Nausea:CINV prophylaxis commands the highest per-patient revenue intensity due to mandatory multi-drug regimens in emetogenic chemotherapy. United States oncology centers drive demand concentration, with Medicare reimbursement codes supporting combination 5-HT3 and NK-1 antagonist protocols in hospital outpatient settings.
- Postoperative Nausea:PONV prophylaxis in ambulatory surgical settings favors rapid-onset intravenous formulations with short recovery room stays. German and French hospital systems standardize on 5-HT3 antagonists for laparoscopic procedures, though generic substitution compresses unit economics.
- Motion Sickness:Transdermal scopolamine and oral antihistamine demand concentrates in travel medicine and military procurement channels.
- Pregnancy-Induced Nausea:Doxylamine-pyridoxine combinations and ginger-derived supplements dominate over-the-counter and prescription first-line therapy.
- Gastrointestinal Disorders:Prokinetic and antiemetic overlap in functional dyspepsia and gastroparesis management limits pure-play positioning.
Chemotherapy-induced nausea anchors the volume base while postoperative nausea applications expand most quickly through ambulatory surgical center proliferation.
End User:
Customer-type concentration around institutional purchasing power creates divergent access economics, with formulary control intensity varying by care delivery setting.
- Oncology Centers:Dedicated cancer treatment facilities in the United States and Japan exercise consolidated purchasing through group purchasing organization contracts bundling antiemetics with chemotherapy agents. These centers generate the highest per-site revenue concentration due to protocol-mandated multi-cycle prophylaxis.
- Hospitals:General acute care institutions in the United Kingdom and Australia manage antiemetic procurement through pharmacy and therapeutics committees with standardized preference lists for surgical and emergency applications.
- Ambulatory Surgical Centers:Freestanding facilities in the United States favor rapid-turnover intravenous formulations with minimal nursing supervision requirements.
- Outpatient Clinics:Community-based practices in India and Brazil rely on oral generic alternatives due to reimbursement constraints.
- Home Healthcare Providers:United States home infusion services and European domiciliary care networks drive transdermal and oral demand outside institutional settings.
Hospitals anchor the volume base while oncology centers gain share at the steepest rate.
Route of Administration:
Supply concentration in sterile injectable manufacturing creates asymmetric competitive moats across administration modes, with GMP certification barriers protecting incumbent positions.
- Intravenous:IV delivery dominates hospital and oncology center administration for acute CINV and PONV prophylaxis, requiring FDA-validated aseptic processing capabilities. United States contract manufacturing capacity constraints limit new entrant access to this high-barrier segment.
- Oral:Tablet and capsule formulations serve maintenance therapy and cost-sensitive markets with lowest manufacturing complexity. Indian and Chinese API suppliers enable aggressive generic pricing in oral 5-HT3 antagonists.
- Transdermal:Scopolamine patches and emerging cannabinoid delivery systems target motion sickness and home healthcare applications with extended-release pharmacokinetics.
- Intramuscular:Depot formulations and emergency antiemetic injections occupy niche acute care and psychiatric applications.
- Sublingual:Rapid-dissolve tablets address swallowing difficulties in pediatric and geriatric populations with limited commercial scale.
Intravenous administration anchors the volume base while transdermal delivery climbs the fastest on home healthcare channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oncology supportive-care guidelines and Medicare reimbursement codes concentrate antiemetic demand in the United States, while EMA MDR compliance requirements and Japan's PMDA accelerated review pathways shape access dynamics across developed markets.
United States
Oncology center proliferation and ASCO protocol entrenchment drive intravenous antiemetic consumption. Medicare Part B reimbursement supports combination 5-HT3 and NK-1 antagonist regimens in hospital outpatient settings. The Greater Boston and Houston medical corridors host concentrated cancer research infrastructure.
Germany
High-emetic-risk chemotherapy adoption and statutory health insurance coverage for supportive-care agents sustain neurokinin-1 antagonist demand. EMA MDR technical documentation requirements extend approval timelines for transdermal combination devices. The Rhine-Ruhr and Bavarian hospital networks standardize on dual-mechanism CINV prophylaxis.
Japan
PMDA oncology supportive-care guidelines and aging demographics expand outpatient chemotherapy volumes. National health insurance price listing cycles compress launch-to-reimbursement intervals for novel antiemetics. The Kanto and Kansai regions concentrate cancer center capacity and pharmaceutical procurement authority.
India
CDSCO regulatory harmonization and domestic generic manufacturing scale enable cost-sensitive oral antiemetic access. Government health mission procurement programs standardize 5-HT3 antagonist formularies in public hospitals. Maharashtra and Gujarat host API synthesis clusters supplying domestic and export markets.
United Kingdom
NICE technology appraisal pathways and NHS England cancer program budgets determine antiemetic formulary inclusion. Postoperative nausea prophylaxis in ambulatory surgery centers favors rapid-turnover intravenous formulations. The London-Southeast and Midlands hospital networks exercise consolidated pharmacy and therapeutics committee authority.
Global Antiemetic Drugs Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with oncology portfolio depth, creating tiered competition between established hospital formulary incumbents and emerging generic manufacturers. Concentration intensifies around group purchasing organization contracts bundling antiemetics with chemotherapy agents. Strategic archetypes include patent-protected NK-1 specialists, commoditized 5-HT3 generic suppliers, and combination-device integrators. Dominant competitive moves encompass formulary contract consolidation and sterile injectable GMP certification acquisition.
Among diversified pharmaceutical conglomerates, Pfizer Inc., Sanofi, and Merck KGaA occupy positions reflecting distinct competitive vectors. Pfizer exemplifies oncology portfolio breadth anchoring hospital formulary contracts. Sanofi represents established anesthesiology channel relationships in postoperative applications. Merck KGaA sits within the neurokinin-1 specialization archetype, a higher-margin niche with limited generic penetration. These entities illustrate how receptor-targeting focus and therapeutic area concentration determine margin architecture against commoditizing alternatives.
| Leading Market Players |
|---|
| Cipla Inc. |
| Sanofi |
| Pfizer Inc. |
| Eagle Pharmaceuticals, Inc. |
| Astellas Pharma Inc. |
| Johnson & Johnson Services, Inc. |
| Merck KGaA |
| Viatris Inc. |
| GSK plc |
| Others |
Supply & Pricing Matrix
Ninety-day API inventory buffers at European formulation sites now separate premium-priced sterile injectables from commoditized oral alternatives, concentrating pricing power with manufacturers holding dual-sourced GMP-certified supply chains across India and China.
Pricing Analysis
Certification level creates the primary spread between sterile injectable and oral generic tiers. Contract-based long-term offtake agreements dominate oncology center procurement, with FDA-grade GMP certification and volume scale as the two key differentiation drivers. Cost compression in the 5-HT3 oral segment is intensifying because Indian API suppliers have expanded generic manufacturing capacity. Hospital formulary committees exhibit the lowest price sensitivity, while outpatient clinics in emerging markets demonstrate acute cost responsiveness.
Supply Chain Analysis
Shanghai port customs clearance delays now represent the dominant chokepoint for Asian API transit into European formulation facilities. Active pharmaceutical ingredient synthesis concentrates in India, China, and Switzerland, with key dependencies on 5-HT3 receptor antagonist precursors, NK-1 antagonist intermediates, and sterile packaging components. Single-source vulnerability in scopolamine alkaloid extraction from Indian medicinal plant suppliers elevates discontinuity risk for transdermal motion sickness products. Distribution runs through hospital group purchasing organizations in the United States and regional pharmaceutical wholesalers in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home healthcare antiemetic delivery services are expanding faster than intravenous hardware sales, creating recurring revenue layers through patient compliance monitoring and remote nursing support that pharmaceutical manufacturers can attach to core drug formulations.
For Market Incumbents: Consolidate formulary contract positions through multi-year bundling of antiemetics with chemotherapy agents, while securing backward integration into sterile injectable manufacturing to offset FDA inspection backlog risks from contract manufacturers. Generic 5-HT3 commoditization and oncology center purchasing consolidation represent the primary threats; captive GMP-certified production capacity in the United States and India provides the essential defensive lever. For New Entrants and Emerging Players: CDSCO fast-track approval pathways for biosimilar supportive-care agents unlock earlier market entry in India than FDA or EMA routes permit. Target oral generic 5-HT3 antagonists in Brazilian and Mexican outpatient clinics where formulary autonomy persists, and pursue white-space positioning in transdermal cannabinoid delivery for home healthcare applications. A direct-to-clinic distribution model bypassing hospital purchasing committees offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because FDA sterile injectable GMP certification scarcity protects incumbent pricing power against generic incursion across the analysis window. Acquisition targets should display neurokinin-1 antagonist specialization or combination-device integration capabilities with established European notified body relationships. The signal to watch is FDA label expansion decisions for NK-1 antagonists into delayed-phase CINV, which would determine whether premium assets retain differentiation or face commoditization pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval for supportive-care oncology drugs compresses development timelines for NK-1 antagonists. |
| Manufacturing Scale-Up | Sterile injectable GMP certification acquisition protects margin position in hospital formulary negotiations. |
| Licensing Agreement | Combination-device partnerships with established European notified bodies overcome MDR technical documentation barriers. |
| Pipeline Diversification | Dual-mechanism 5-HT3 and NK-1 protocols capture adherence-based revenue in high-emetic-risk chemotherapy. |
| Geographic Expansion | CDSCO pathway utilization enables earlier biosimilar entry in Indian government health mission procurement programs. |
Research Methodology
Operator-level perspectives from oncology pharmacy directors, hospital formulary managers, regulatory affairs leads at sterile injectable manufacturers, and group purchasing organization contract specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA Orange Book listings, EMA EPAR assessments, ClinicalTrials.gov protocol registries, and CMS Medicare Part B reimbursement data. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulated demand estimates across the analysis window.
Sensitivity analysis tested forecast robustness against regulatory approval delays, API supply disruptions, and formulary exclusion scenarios. Segmentation dimensions modeled encompass receptor-targeting technology, therapy area, end-user setting, route of administration, and regional regulatory cluster. CAGRs derived from patient volume projections, protocol penetration assumptions, and pricing trajectory modeling across the projection horizon. Forecast inputs incorporated chemotherapy protocol expansion rates, ambulatory surgical center proliferation, and transdermal delivery adoption curves.
Underlying assumptions cover sustained FDA oncology supportive-care guideline entrenchment, with deviation risk concentrated in REACH chemical registration enforcement intensity and generic 5-HT3 patent litigation outcomes. Practitioners should keep alternative scenarios live as EMA MDR notified body capacity constraints and hospital formulary consolidation trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Gout Therapeutics Market
Pharmaceuticals
Global Bacterial Vaccines Market
Pharmaceuticals
India Nicotine Replacement Therapy Market
Pharmaceuticals
Global Prophylactic HIV Drugs Market
Pharmaceuticals
Global Cyclosporine Market
Pharmaceuticals
Marine Derived Pharmaceuticals Market
Pharmaceuticals
BRAF-MEK Inhibitors Market
Pharmaceuticals
Critical Care Drugs Market
Pharmaceuticals
Italy OTC Drugs Market
Pharmaceuticals
Compound Potassium Hydrogen Phosphate Injection Market
Pharmaceuticals
Oral Solid Dosage Pharmaceutical Formulation Market
Pharmaceuticals
Efinaconazole Market
Pharmaceuticals
Global Recombinant Vaccines Market
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Theophylline and Aminophylline Market
Pharmaceuticals
Soft Capsules Drugs Market