
 Carbapenem Market | 2026-2036
Carbapenem Market Size, Share, and Industry Trends Forecast 2026-2036
Carbapenem Market Intelligence
Hospital procurement of broad-spectrum antibiotics is realigning toward carbapenems as resistant gram-negative infections rise in intensive care units. Pfizer Inc leverages its institutional distribution network to sustain formulary access across tertiary care centers. Merck & Co Inc anchors its position through deep R&D investment in beta-lactamase inhibitor combinations. Aurobindo Pharma Ltd competes on cost-efficient injectable manufacturing for emerging markets.
Carbapenems constitute a class of ultra-broad-spectrum beta-lactam antibiotics characterized by a bicyclic nucleus with a carbon-substituted penem ring, conferring stability against most serine beta-lactamases and carbapenemases. These agents serve as last-reserve therapy for infections caused by extended-spectrum beta-lactamase-producing Enterobacterales and Pseudomonas aeruginosa. Meropenem dominates hospital formularies due to superior central nervous system penetration and established dosing protocols. Intravenous administration leads volume consumption, though continuous infusion protocols are gaining traction in critical care settings. Powder formulations for reconstitution occupy the largest manufacturing footprint, while premixed bags command premium positioning in high-throughput infusion centers.
FDA antimicrobial susceptibility testing standards, EMA pharmacovigilance requirements, and WHO essential medicines list classifications collectively shape carbapenem prescribing patterns and market access pathways. These frameworks restrict empirical use, mandate resistance surveillance reporting, and influence reimbursement thresholds for novel combinations. Stakeholders must monitor evolving carbapenemase surveillance data and regulatory incentives for anti-infective development to anticipate shifts in clinical utility and commercial priority.
Market Dynamics
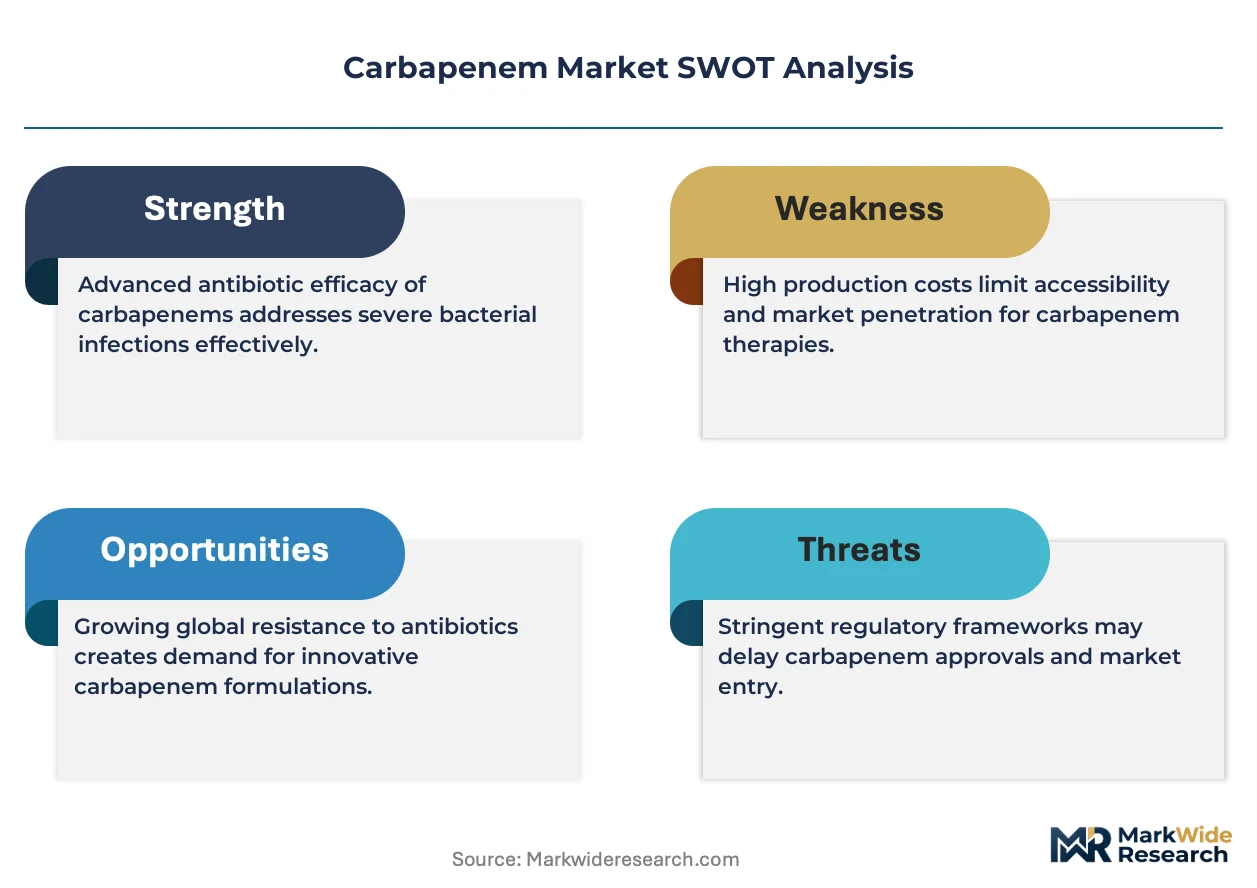
Hospital formulary committees are tightening carbapenem access protocols as antimicrobial stewardship programs gain institutional authority, creating a bifurcation between empiric restriction and targeted therapy pathways.
Growth Catalysts
- ESBL Surveillance Mandates:CDC and ECDC resistance reporting requirements are expanding carbapenem testing volumes in clinical microbiology laboratories.
- Continuous Infusion Protocols:Pharmacokinetic optimization in critical care units is extending meropenem dosing intervals and per-patient consumption.
- China:National Health Commission guidelines on multidrug-resistant organism management are accelerating carbapenem adoption in tier-3 hospitals.
Market Restraints
- API Concentration Risk:Active pharmaceutical ingredient manufacturing for carbapenem cores concentrates among Indian and Chinese contract manufacturers.
- FDA Q1/Q2 Qualification:Stringent chemistry manufacturing controls for beta-lactam facilities extend facility approval timelines.
- Polymyxin Revival:Renewed clinical interest in colistin for carbapenem-resistant Acinetobacter is creating therapeutic substitution pressure.
Strategic Opportunities
- India:Underpenetrated secondary hospital networks present volume expansion potential for cost-optimized injectable formulations.
- Outpatient Parenteral Antimicrobial Therapy:Home infusion services are opening ambulatory channels traditionally reserved for inpatient administration.
- Beta-Lactamase Inhibitor Convergence:Pairing carbapenem backbones with novel avibactam-class inhibitors is extending spectrum against KPC producers.
Industry Challenges
- Sterile Manufacturing Talent Scarcity:Aseptic processing expertise gaps in injectable antibiotic facilities constrain capacity expansion.
- Carbapenemase Surveillance Integration:Real-time resistance data connectivity between hospital laboratories and pharmacy information systems demands substantial IT infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbapenem Market |
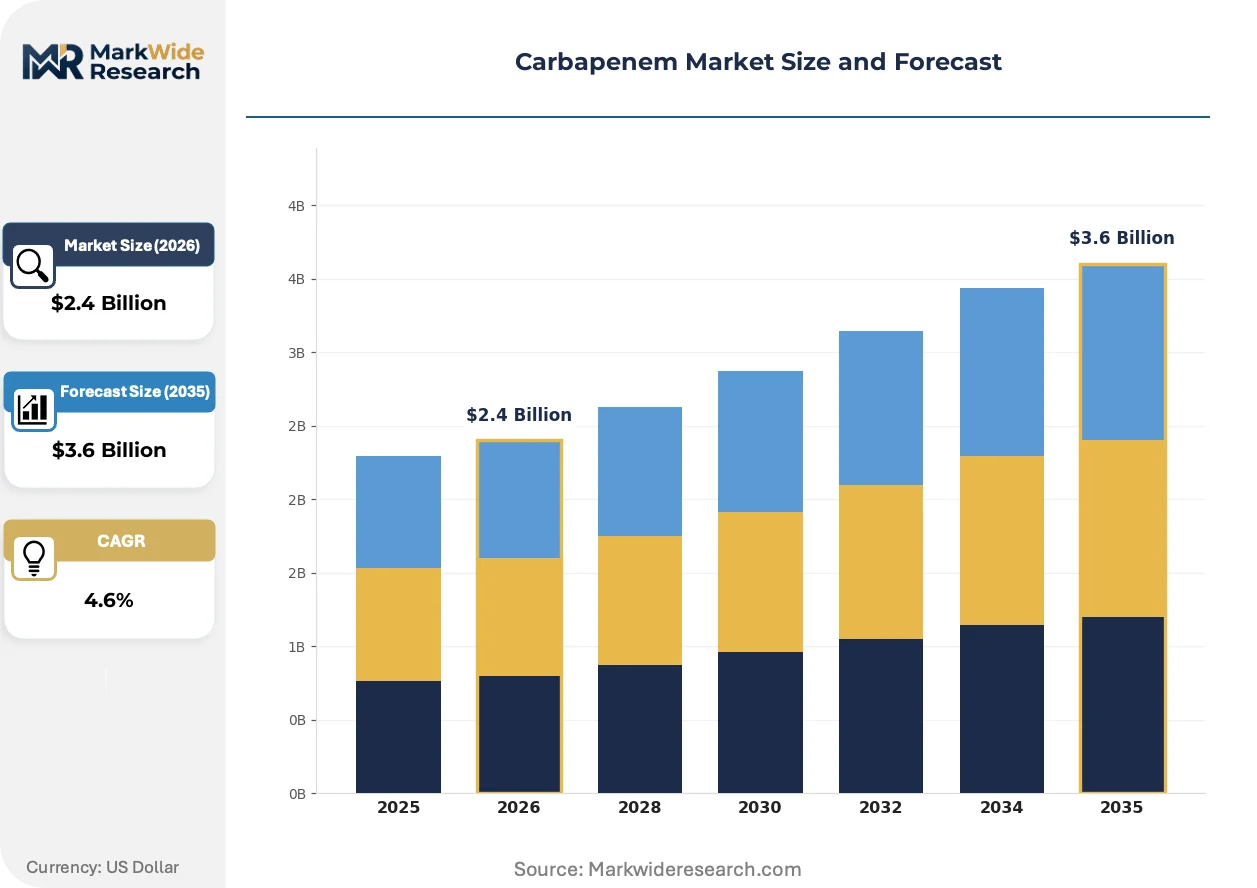
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.6 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imipenem, Meropenem, Ertapenem, Doripenem End User: Hospitals, Clinics, Laboratories, outpatient settings Administration Route: Intravenous, Intramuscular, Oral, Continuous Infusion Formulation: Injection, Powder, Solution, Premixed |
| Companies Covered | Pfizer Inc, Merck & Co Inc, AstraZeneca plc, Aurobindo Pharma Ltd, Daewoong Pharmaceutical Co Ltd, Sandoz International GmbH, Fresenius Kabi LLC, GlaxoSmithKline plc, Shionogi & Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbapenem Market Strategic Shifts & Innovations
Carbapenem development trajectories are pivoting toward resistance-evasion chemistry and administration efficiency rather than spectrum expansion alone.
Dual-carbapenem combination therapy is unifying meropenem and ertapenem protocols for synergistic activity against metallo-beta-lactamase producers. Intensive care units in Germany and the Netherlands are piloting these regimens for Pseudomonas bacteremia. This approach is unifying previously separate therapeutic algorithms into consolidated critical care pathways.
EMA's revised guideline on antibacterial agents now mandates robust resistance surveillance data as a condition of marketing authorization renewal. Pharmaceutical developers must embed epidemiological monitoring into post-approval commitments. Novel beta-lactamase inhibitor combinations face heightened evidentiary thresholds in European markets.
Hospital purchasing consortia are consolidating antibiotic procurement under centralized tender mechanisms. Group purchasing organizations in the United States are displacing individual hospital negotiations with multi-year supply agreements. This concentration is compressing supplier margins while securing volume commitments for high-throughput infusion centers.
Carbapenem Market Segmentation
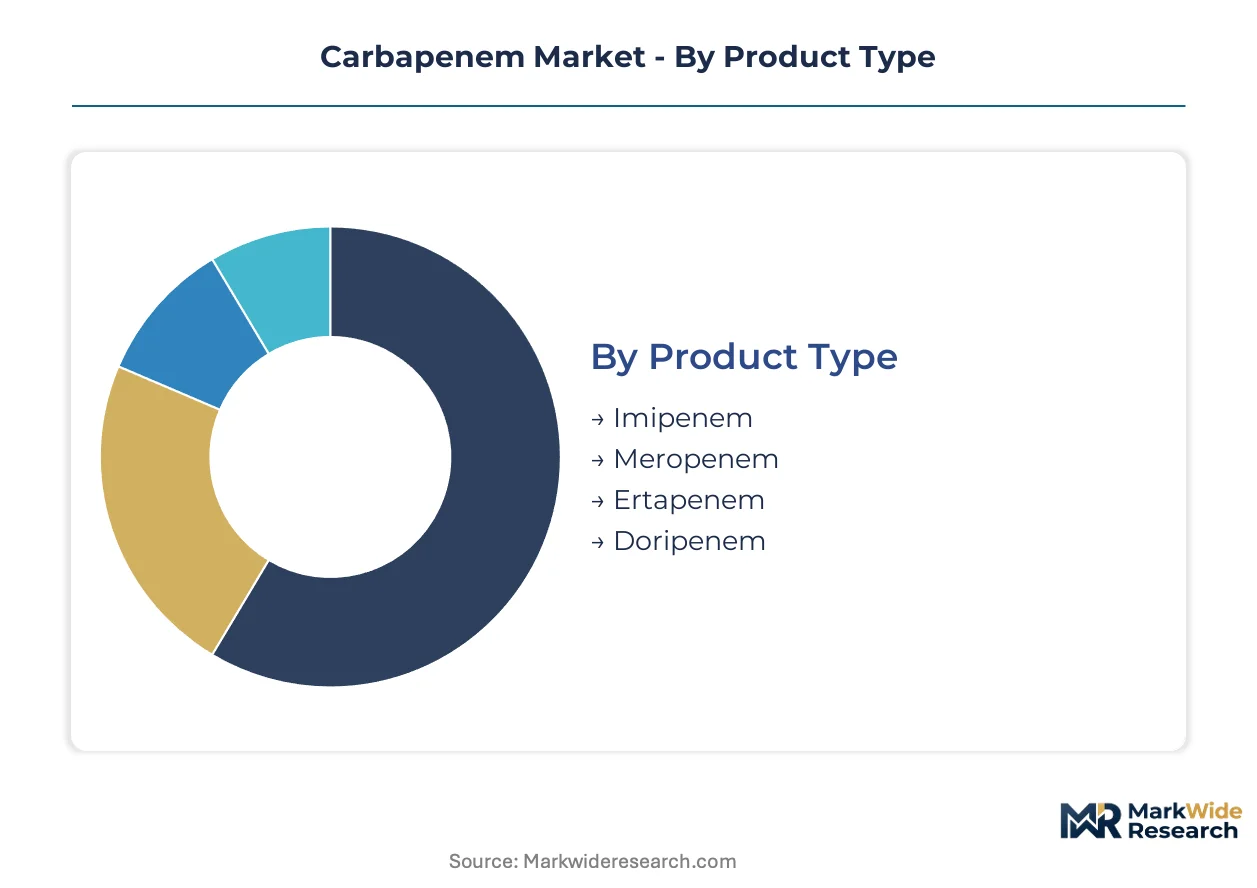
Carbapenem prescribing patterns fragment across molecular variants, care settings, and delivery technologies. Hospital formulary committees weight pharmacokinetic profiles against resistance surveillance data when segmenting procurement budgets.
Product Type:
Institutional formularies upgrade meropenem protocols as ESBL prevalence rises, while imipenem-cilastatin retains cost-tier positioning in budget-constrained networks.
- Imipenem:The original carbapenem requires co-administration with cilastatin to prevent renal dehydropeptidase degradation. Demand concentrates in emerging market tertiary hospitals where cost sensitivity outweighs CNS penetration requirements; renal dosing complexity constrains adoption in elderly populations.
- Meropenem:Superior blood-brain barrier penetration and simplified dosing protocols dominate ICU formularies. United States academic medical centers anchor volume consumption; continuous infusion pharmacokinetics extend per-patient utilization in sepsis protocols.
- Ertapenem:Once-daily dosing and outpatient parenteral compatibility suit transition-of-care programs. Pseudomonas coverage gaps limit use in cystic fibrosis and burn units.
- Doripenem:Narrower approved indications restrict formulary placement to Pseudomonas bacteremia protocols. Japanese and South Korean regulators maintain broader labeling than FDA equivalents.
Volume placements concentrate in Meropenem; the faster expansion belongs to Ertapenem as OPAT networks mature.
End User:
Antimicrobial stewardship programs are tightening access hierarchies across the patient journey, concentrating carbapenem authority in infectious disease consult services.
- Hospitals:Tertiary and quaternary centers command absolute volume share through ICU stewardship protocols. China tier-3 hospitals and German university clinics anchor regional consumption clusters.
- Clinics:Infusion center expansion for OPAT is displacing traditional inpatient days. United States Medicare reimbursement shifts favor ambulatory parenteral administration.
- Laboratories:Reference microbiology services drive susceptibility testing volumes that shape empiric prescribing algorithms. ECDC and CDC resistance reporting mandates expand testing menu inclusion.
- Outpatient settings:Home health nursing and specialty pharmacy networks are capturing step-down therapy from acute care. Regulatory frameworks for outpatient carbapenem administration remain fragmented across state and national jurisdictions.
Procurement budgets cluster in Hospitals; the steepest expansion trajectory runs through Outpatient settings.
Administration Route:
Pharmacokinetic optimization in critical care is displacing intermittent bolus protocols with precision dosing technologies.
- Intravenous:Intermittent bolus remains the default for ward-level administration. Manufacturing scale and generic competition compress unit economics.
- Intramuscular:Ertapenem's stability in intramuscular formulation enables community-based administration. Resource-limited settings lacking IV infrastructure leverage this route for serious infection management.
- Oral:No approved oral carbapenem exists; this segment captures pipeline assets and investigator-initiated trials. Bioavailability challenges and beta-lactamase susceptibility constrain development viability.
- Continuous Infusion:Target attainment optimization in sepsis and meningitis protocols is extending meropenem half-life utilization. Australian and Dutch ICU networks lead protocol adoption.
Utilization concentrates in Intravenous delivery; Continuous Infusion claims the fastest share gain.
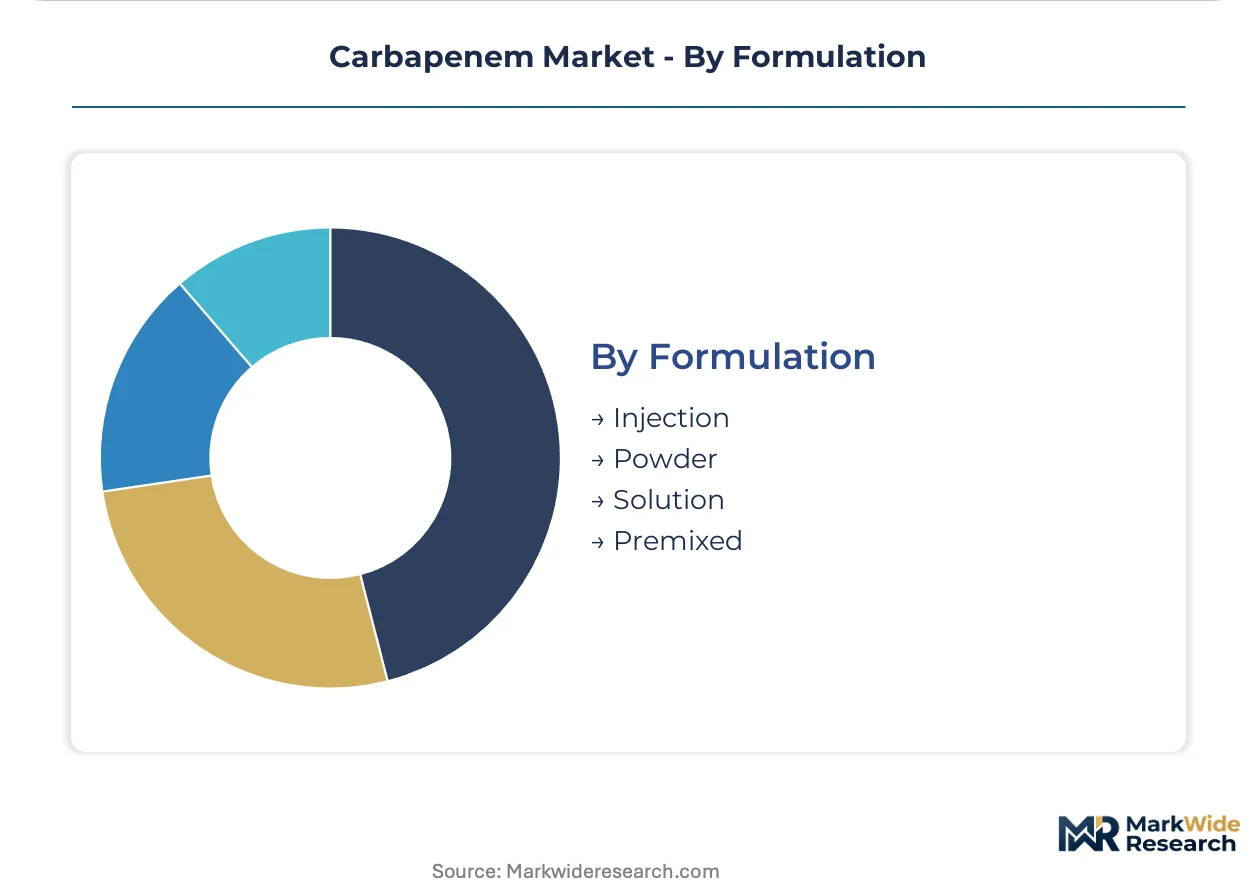
Formulation:
Supply chain resilience priorities are shifting procurement preferences from powder reconstitution toward ready-to-use formats.
- Injection:Ready-to-use vials command premium positioning in emergency department rapid-sepsis protocols. Cold chain requirements constrain distribution reach.
- Powder:Lyophilized vials for reconstitution dominate manufacturing volumes and generic substitution. Indian and Chinese API-to-finished-dose integration anchors cost structures.
- Solution:Premixed bag alternatives in non-premium positioning serve mid-tier hospital networks. Stability limitations restrict shelf-life and geographic distribution radius.
- Premixed:Outsourced compounding and pharmacy-automation compatibility drive adoption in high-throughput United States infusion centers. FDA 503B outsourcing facility regulations shape competitive access.
Manufacturing output concentrates in Powder; Premixed formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Hyderabad and Zhengzhou concentrate carbapenem API manufacturing through tax-advantaged export processing frameworks. These zones anchor global supply chains for sterile injectable antibiotics.
United States
Academic medical centers in Boston and Houston drive meropenem consumption through sepsis protocols and continuous infusion adoption. FDA antimicrobial susceptibility testing mandates expand reference laboratory capacity. The Research Triangle Park microbiology cluster in North Carolina anchors resistance surveillance infrastructure development.
Germany
University clinics in Berlin and Munich pilot dual-carbapenem combination therapy for metallo-beta-lactamase producers. EMA pharmacovigilance requirements tighten post-approval resistance monitoring obligations. The Frankfurt-Rhine-Main pharmaceutical manufacturing corridor sustains sterile injectable export capacity.
China
Tier-3 hospitals in Shanghai and Guangzhou accelerate carbapenem adoption under National Health Commission multidrug-resistant organism guidelines. NMPA chemistry manufacturing controls extend facility qualification timelines for beta-lactam sites. The Zhengzhou pharmaceutical export zone concentrates API-to-finished-dose integration for cost-optimized injectables.
India
Secondary hospital networks in Maharashtra and Gujarat present volume expansion potential for generic carbapenem formulations. CDSCO sterile manufacturing standards constrain aseptic processing capacity expansion. The Hyderabad-Visakhapatnam corridor anchors injectable antibiotic export manufacturing through special economic zone incentives.
Japan
ICU networks in Tokyo and Osaka optimize meropenem pharmacokinetics through therapeutic drug monitoring programs. PMDA antibacterial agent guidelines mandate robust resistance surveillance for marketing authorization renewal. The Kansai pharmaceutical cluster maintains formulation expertise for lyophilized injectable production.
Carbapenem Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with originator firms commanding formulary access in tertiary care while generic fabricators capture volume in cost-sensitive networks. The structure concentrates around three strategic tiers: research-intensive innovators with beta-lactamase inhibitor pipelines, mid-scale sterile injectable specialists, and API-integrated cost leaders. Dominant competitive moves include capacity expansion in aseptic processing facilities and strategic partnerships for novel combination therapy development.
Among research-intensive innovators, Pfizer Inc and Merck & Co Inc exemplify the institutional distribution archetype, leveraging hospital formulary relationships to sustain access across academic medical centers. Aurobindo Pharma Ltd represents the cost-optimized manufacturing tier, occupying a position within API-integrated generic supply chains for emerging market penetration.
| Leading Market Players |
|---|
| Pfizer Inc |
| Merck & Co Inc |
| AstraZeneca plc |
| Aurobindo Pharma Ltd |
| Daewoong Pharmaceutical Co Ltd |
| Sandoz International GmbH |
| Fresenius Kabi LLC |
| GlaxoSmithKline plc |
| Shionogi & Co Ltd |
| Others |
Cost & Logistics Intelligence
Continuous infusion protocol adoption in critical care units is compressing per-dose economics while extending treatment duration, simultaneously reshaping hospital procurement volume commitments and manufacturing batch planning across sterile injectable facilities.
Pricing Analysis
Short lead-time premiums for ready-to-use premixed bags command 15-25% markups over powder reconstitution formats in emergency department rapid-sepsis protocols. Pricing stratifies across premixed premium, standard lyophilized vial, and economy generic powder tiers based on FDA 503B outsourcing facility certification status and cold chain compliance. Cost compression in the economy tier intensifies because Indian and Chinese API-integrated manufacturers expand batch volumes for emerging market tenders. Government hospital procurement committees in China and India exhibit highest price sensitivity; United States academic medical centers prioritize therapeutic drug monitoring compatibility over unit cost.
Supply Chain Analysis
Aseptic processing technician shortages in Hyderabad and Zhengzhou special economic zones constrain sterile injectable capacity expansion despite tax-advantaged export processing frameworks. Active pharmaceutical ingredient manufacturing for carbapenem cores concentrates in India and China, with beta-lactamase inhibitor chemistry drawing from specialized fermentation capabilities in Japan and South Korea. Single-source vulnerability pervades the KPC-targeting inhibitor segment where novel avibactam-class supply rests on limited qualified facilities. Distribution runs through hospital purchasing consortia and group purchasing organizations in the United States, direct tender negotiations in Germany, and centralized procurement in China's tier-3 hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA Q1/Q2 chemistry manufacturing controls and EMA pharmacovigilance mandates erect steep compliance barriers that protect incumbent positions while raising capital requirements for new facility qualification, creating durable moats for certified manufacturers.
For Market Incumbents: To counter polymyxin revival and therapeutic substitution pressure, deepen backward integration into beta-lactamase inhibitor API supply and expand aseptic processing capacity in Frankfurt-Rhine-Main or Research Triangle Park corridors. Anchor formulary access through embedded resistance surveillance data services that lock hospital microbiology laboratories into proprietary platforms. For New Entrants and Emerging Players: Launch via outpatient parenteral antimicrobial therapy networks in United States Medicare reimbursement corridors and secondary hospital networks in Maharashtra and Gujarat. Capture step-down therapy volume from acute care through home health nursing partnerships, bypassing entrenched tertiary center procurement committees. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale sterile injectable specialists with FDA-approved beta-lactam facilities and existing EMA rapporteur relationships. Long-term viability hinges on resistance-evasion chemistry pipelines rather than commodity meropenem volume. Watch carbapenemase surveillance integration mandates as the inflection signal—regulatory pressure for real-time laboratory-pharmacy data connectivity will consolidate vendor bases around IT-capable incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Infusion Protocol Expansion | Extends meropenem per-patient consumption in Australian and Dutch ICU networks. |
| Beta-Lactamase Inhibitor Convergence | Pairs carbapenem backbones with avibactam-class chemistry against KPC producers. |
| Premixed Bag Manufacturing Scale-Up | Captures premium positioning in high-throughput United States infusion centers. |
| Resistance Surveillance Data Integration | Locks hospital formulary access through embedded IT infrastructure partnerships. |
| Secondary Hospital Network Penetration | Opens volume expansion in India's underpenetrated Maharashtra and Gujarat corridors. |
Research Approach
FDA filings, EMA pharmacovigilance databases, and ClinicalTrials.gov formed the secondary backbone, supplemented by customs records from Indian DGFT and Chinese export processing zone authorities. Primary interviews with hospital formulary directors, infectious disease pharmacists, sterile manufacturing plant managers, and antimicrobial stewardship program leads validated demand assumptions. Bottom-up and top-down triangulation cross-checked patient volume projections against API production capacity disclosures.
Bottom-up modeling anchored volume forecasts to hospital admission trends, ICU sepsis protocol adoption rates, and resistance surveillance reporting mandates across the analysis window. Top-down verification assessed pharmaceutical industry capital expenditure patterns and sterile injectable facility approval timelines. Segmentation dimensions included molecular variant, administration route, formulation type, end-user setting, and regional regulatory cluster. CAGR derivation incorporated pharmacokinetic optimization trends, continuous infusion adoption curves, and outpatient parenteral therapy reimbursement shifts.
Carbapenemase emergence patterns, FDA facility inspection backlogs, and EMA marketing authorization renewal requirements are the dominant revision risks. Forecasts reflect documented assumptions regarding stewardship program enforcement intensity and generic substitution elasticity. A small set of named triggers—KPC prevalence thresholds, 503B outsourcing facility regulation changes, and dual-carbapenem protocol outcomes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Oral Antiviral Market
Pharmaceuticals
Russia Diabetes Drugs Market
Pharmaceuticals
Amlodipine Besylate Market
Pharmaceuticals
Global Esketamine Market
Pharmaceuticals
Italy Healthcare Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
Antiretroviral (ARV) Agents Market
Pharmaceuticals
Global Aromatase Inhibitors Drug Market
Pharmaceuticals
Placental Protein Market
Pharmaceuticals
Penicillin Market
Pharmaceuticals
Minocycline Hydrochloride Market
Pharmaceuticals
PD-1/PD-L1 Inhibitor Market
Pharmaceuticals
Antihelminthics Market
Pharmaceuticals
Sympathoimemetic Agents Market
Pharmaceuticals
Global Pharmaceutical Traceability Market
Pharmaceuticals
Testosterone Nasal Gels Market