
 Performance Enhancing Drugs Market | 2026-2036
Performance Enhancing Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Performance Enhancing Drugs Market Outlook
Peptide-based formulations are recalibrating cost structures across the performance enhancing drugs landscape as synthetic alternatives displace conventional hormone therapies. Pfizer Inc. leverages its biologics manufacturing infrastructure to sustain supply chain reliability for regulated peptide products. Novo Nordisk A/S anchors its position through endocrine science expertise that extends into growth hormone modulation. Eli Lilly and Company differentiates via metabolic research capabilities that position its portfolio for evolving anti-doping compliance frameworks.
Performance enhancing drugs comprise pharmacological agents engineered to augment muscular development, oxygen delivery, or recovery velocity through hormonal modulation, tissue synthesis acceleration, or metabolic pathway alteration. These substances typically operate via androgen receptor agonism, erythropoietin stimulation, or selective tissue anabolism, serving therapeutic rehabilitation, athletic performance optimization, and physique enhancement objectives. Anabolic steroids retain the largest revenue footprint among product categories, though peptides demonstrate the steepest trajectory as precision-engineered analogs reduce off-target effects. Among end users, athletes and bodybuilders command the dominant share, while fitness enthusiasts represent the fastest-growing segment as wellness culture normalizes pharmacological biohacking.
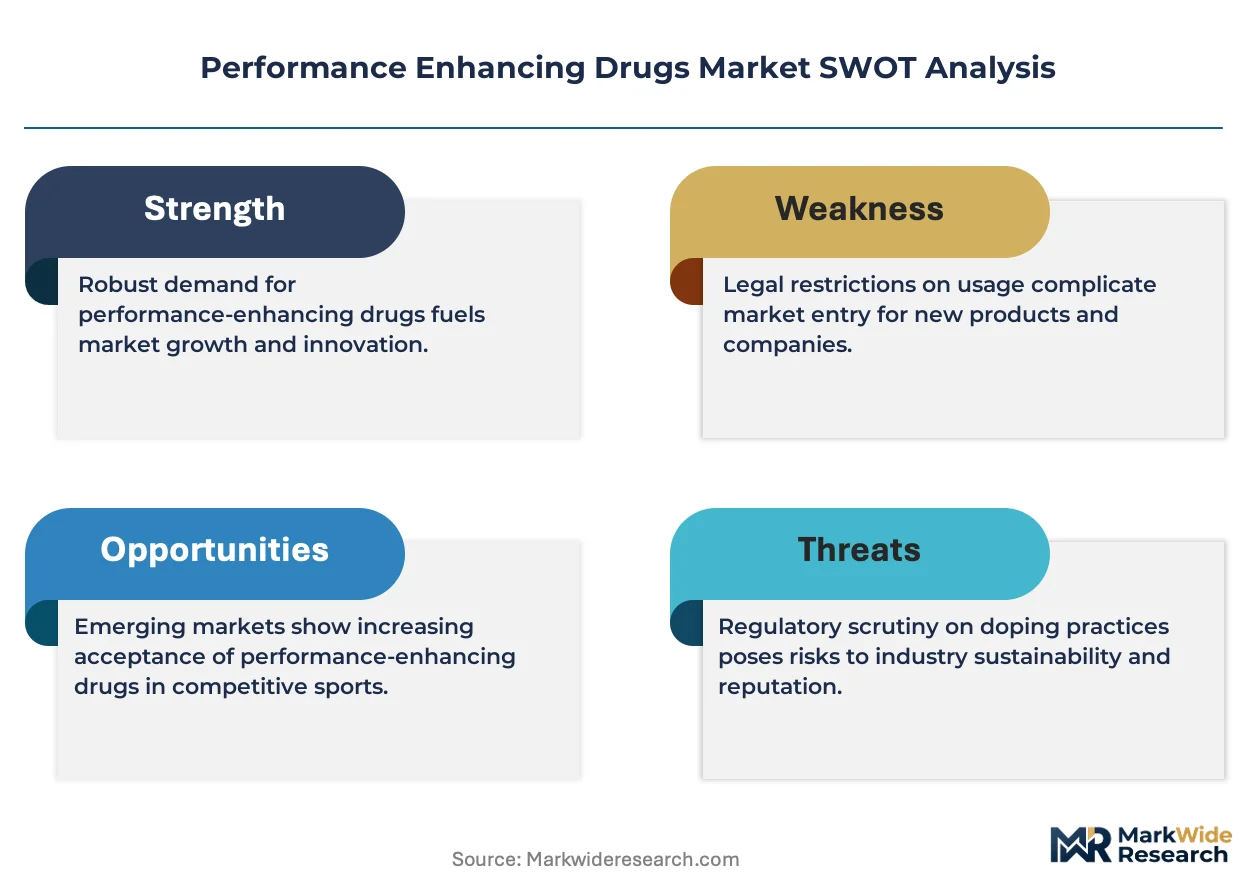
The World Anti-Doping Agency coordinates prohibited substance lists that determine product legality across Olympic and professional sports jurisdictions, directly constraining addressable demand for manufacturers. FDA scheduling under the Anabolic Steroid Control Act and DEA controlled-substance classifications further segment the market between prescription-regulated, criminalized, and unregulated product tiers. Stakeholders must monitor evolving peptide classification debates and state-level testosterone therapy regulations to anticipate compliance cost shifts and channel access restrictions.
Market Dynamics
Peptide therapeutics are compressing development cycles while fragmenting regulatory oversight across national anti-doping frameworks, forcing manufacturers to maintain parallel compliance architectures for the same molecular compound.
Growth Catalysts
- Anti-Doping Protocol Revisions:The World Anti-Doping Agency's annual prohibited list updates create recurring demand for reformulated compounds that bypass detection thresholds while retaining pharmacological efficacy.
- Aging Demographics:Hormone optimization protocols among men over 45 in the United States drive off-label prescribing for testosterone derivatives and growth hormone secretagogues.
- Biologics Manufacturing Scale-Up:Contract development organizations in Switzerland and Singapore now offer GMP peptide synthesis at kilogram scale, reducing unit costs for precision-engineered analogs.
Market Restraints
- Raw Material Concentration:Ninety percent of synthetic peptide precursors originate from Chinese chemical manufacturers, exposing formulators to export license volatility and geopolitical friction.
- Regulatory Friction:The FDA's Anabolic Steroid Control Act creates scheduling uncertainty for novel peptide structures, delaying commercialization timelines by 18-36 months for investigational compounds.
- Detection Technology Arms Race:Mass spectrometry advances at WADA-accredited laboratories now identify metabolite signatures for previously undetectable compounds, compressing product lifecycles.
Strategic Opportunities
- Micro-Dosing Protocols:Sub-therapeutic dosing regimens among amateur endurance athletes in Germany and Australia evade current testing thresholds while sustaining demand for pharmaceutical-grade supply.
- Regenerative Medicine Convergence:Combination therapies pairing peptide growth factors with platelet-rich plasma injections open reimbursement pathways through sports medicine clinics in the United States.
- Telehealth Distribution:Online hormone optimization platforms in Texas and Florida bypass traditional clinic gatekeepers, capturing patient acquisition costs below brick-and-mortar models.
Industry Challenges
- Compound Stability Expertise:Lyophilization and cold-chain logistics for peptide formulations require specialized formulation chemists, with talent concentrated among former biologics specialists from Cambridge and Basel clusters.
- Dual-Use Documentation:Manufacturers must maintain separate batch records for research-grade and clinical-grade material, with customs authorities in the Netherlands and Belgium increasingly scrutinizing import declarations for precursor chemicals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Performance Enhancing Drugs Market |
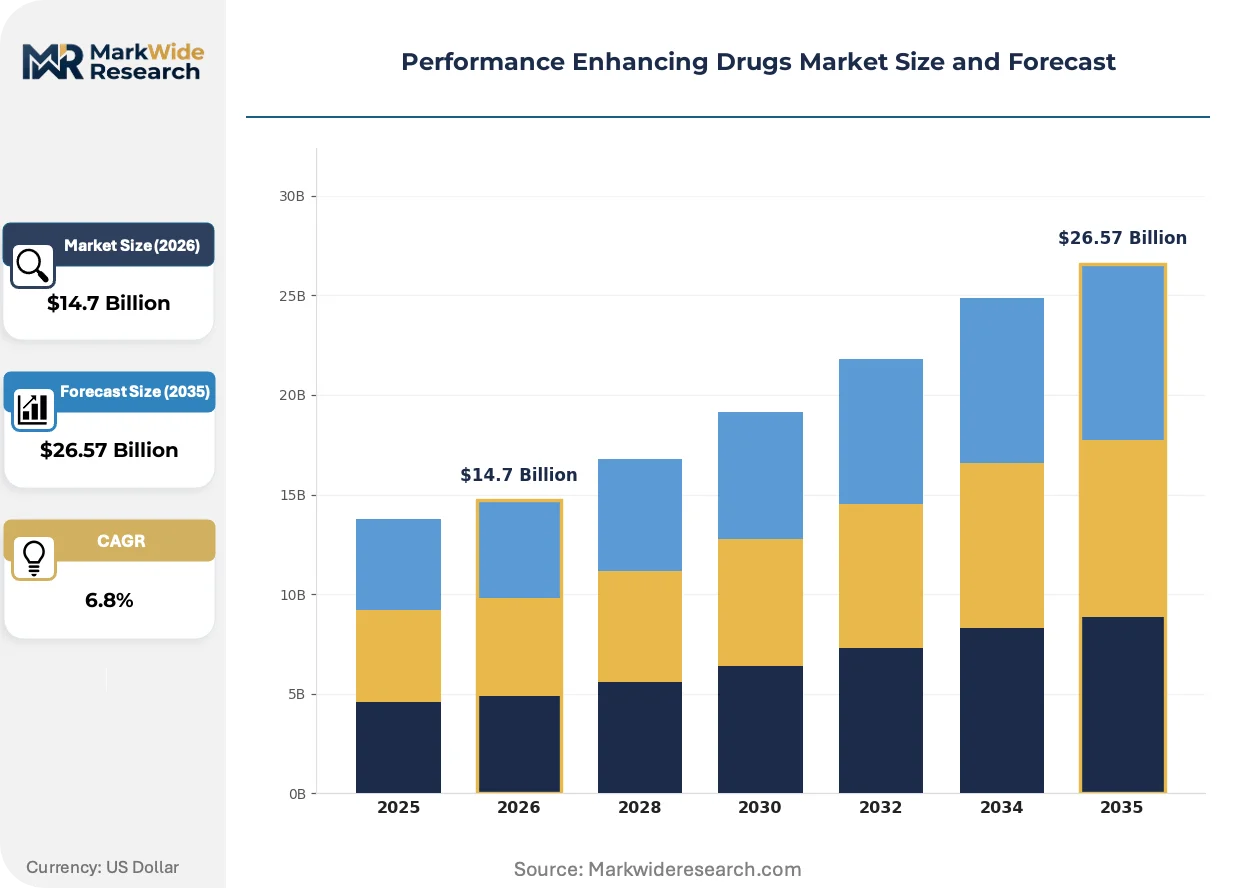
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anabolic Steroids, Peptides, Hormones, Stimulants End User: Athletes, Bodybuilders, Fitness Enthusiasts, Recreational Users Delivery Mode: Oral, Injectable, Transdermal, Subcutaneous Regulatory Status: Controlled Substances, Prescription Only, Over the Counter, Unregulated |
| Companies Covered | Taj Pharmaceuticals Limited, Balkan Pharmaceuticals, Bayer AG, AstraZeneca, Novo Nordisk A/S, Eli Lilly and Company, Pfizer Inc., Onnit Labs, LLC, Douglas Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Performance Enhancing Drugs Market Strategic Shifts
Precision molecular engineering is fragmenting the traditional anabolic steroid market while regulatory arbitrage between national jurisdictions creates parallel supply channels for identical compounds.
Oral bioavailable peptides are electrifying administration convenience for end users previously limited to injectable formats. Subcutaneous delivery devices from diabetes care applications now adapt to growth hormone secretagogues, with compounding pharmacies in Arizona and Nevada integrating these platforms into anti-aging protocols. This convergence is electrifying patient adherence rates while compressing the addressable market for conventional intramuscular testosterone esters.
The European Medicines Agency's revised guidance on peptide-containing medicinal products now mandates stability data across five temperature excursion scenarios, forcing reformulators to invest in forced degradation studies. Manufacturers targeting EU distribution must demonstrate 24-month shelf life under variable shipping conditions, with Swissmedic adopting identical standards for parallel import recognition. German and Austrian sports medicine clinics now prioritize EMA-registered suppliers over compounded alternatives to mitigate liability exposure.
Direct-to-consumer laboratory testing is disrupting traditional physician gatekeeping for hormone optimization. Consumers in California and Colorado now sequence baseline biomarkers through mail-order panels before consulting telehealth prescribers, compressing the diagnostic-to-treatment interval from weeks to days. This self-directed health management pattern concentrates among high-income fitness enthusiasts aged 35-50, with subscription-based monitoring services replacing annual physical examinations as the primary touchpoint for dose adjustment.
Performance Enhancing Drugs Market Segmentation
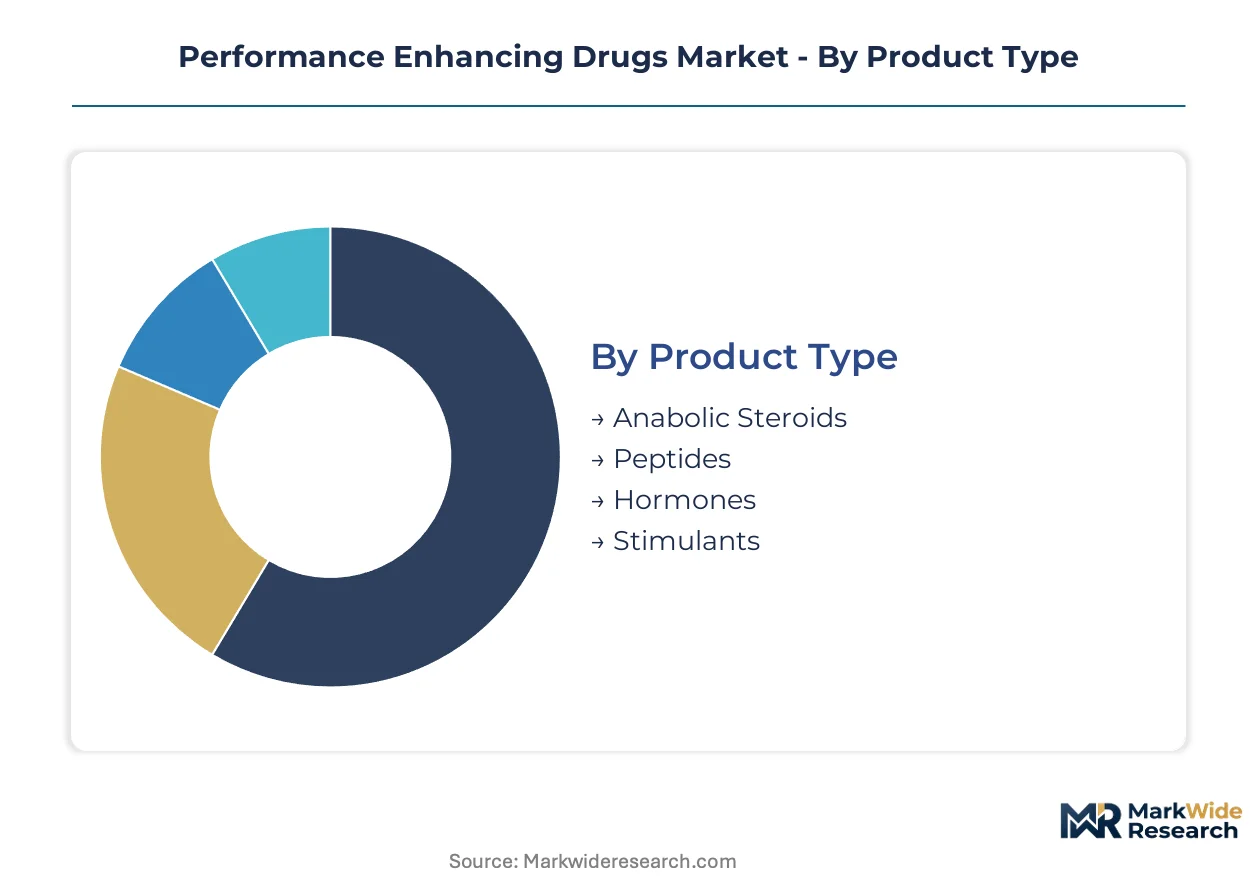
Performance enhancing drugs demand fragments across molecular classes, user sophistication levels, and compliance tiers. Manufacturers configure parallel production lines to serve divergent regulatory pathways for identical compounds.
Product Type:
Purchasing decisions pivot on detection windows versus pharmacological potency tradeoffs.
- Anabolic Steroids:Synthetic testosterone derivatives activate androgen receptors to accelerate protein synthesis and erythropoiesis. Demand concentrates among competitive bodybuilders in the United States and Eastern Europe where underground laboratory networks sustain supply despite DEA Schedule III classification.
- Peptides:Short-chain amino acid analogs stimulate selective growth hormone release with reduced systemic exposure. Precision-engineered variants from Swiss and Singaporean GMP facilities now capture share fastest among anti-aging clinics in Florida and Texas seeking WADA-compliant therapeutic alternatives.
- Hormones:Recombinant erythropoietin and insulin-like growth factors modulate metabolic and oxygen-carrying capacity. Prescription testosterone replacement therapy dominates legitimate channel volume.
- Stimulants:Sympathomimetic compounds enhance alertness and reduce perceived exertion during endurance events. Pre-workout formulations drive over-the-counter sales through nutritional supplement retailers.
Volume sits with Anabolic Steroids; growth tilts toward Peptides.
End User:
Risk tolerance and procurement sophistication stratify the addressable population.
- Athletes:Olympic and professional competitors face mandatory WADA testing protocols. Micro-dosing regimens among amateur endurance athletes in Germany and Australia sustain demand for pharmaceutical-grade supply that evades current detection thresholds.
- Bodybuilders:Physique competitors prioritize hypertrophic outcomes over longevity considerations. This cohort tolerates higher side-effect profiles and sources through gym-floor distribution networks.
- Fitness Enthusiasts:High-income professionals aged 35-50 normalize pharmacological biohacking within wellness culture. Telehealth hormone optimization platforms in Texas and Florida capture this expanding segment below traditional clinic acquisition costs.
- Recreational Users:Casual consumers seek aesthetic enhancement without competitive aspirations. Price sensitivity drives demand toward unregulated research chemical markets.
Bodybuilders command current volume; Fitness Enthusiasts expand most quickly.
Delivery Mode:
Administration convenience directly determines adherence rates and clinical uptake.
- Oral:Hepatic first-pass metabolism limits bioavailability for many compounds. New peptide formulations with enhanced gastric stability are electrifying patient preference among convenience-focused users.
- Injectable:Intramuscular depot formulations sustain therapeutic levels over extended intervals. This route retains dominance for testosterone esters and long-acting anabolic agents.
- Transdermal:Creams and patches eliminate needle burden while achieving steady-state absorption. Compounding pharmacies in Arizona integrate these into anti-aging protocols.
- Subcutaneous:Diabetes care delivery devices now adapt to growth hormone secretagogues. Swissmedic-registered suppliers prioritize this format for EU distribution compliance.
Injectable formats retain volume leadership; subcutaneous delivery gains share fastest.
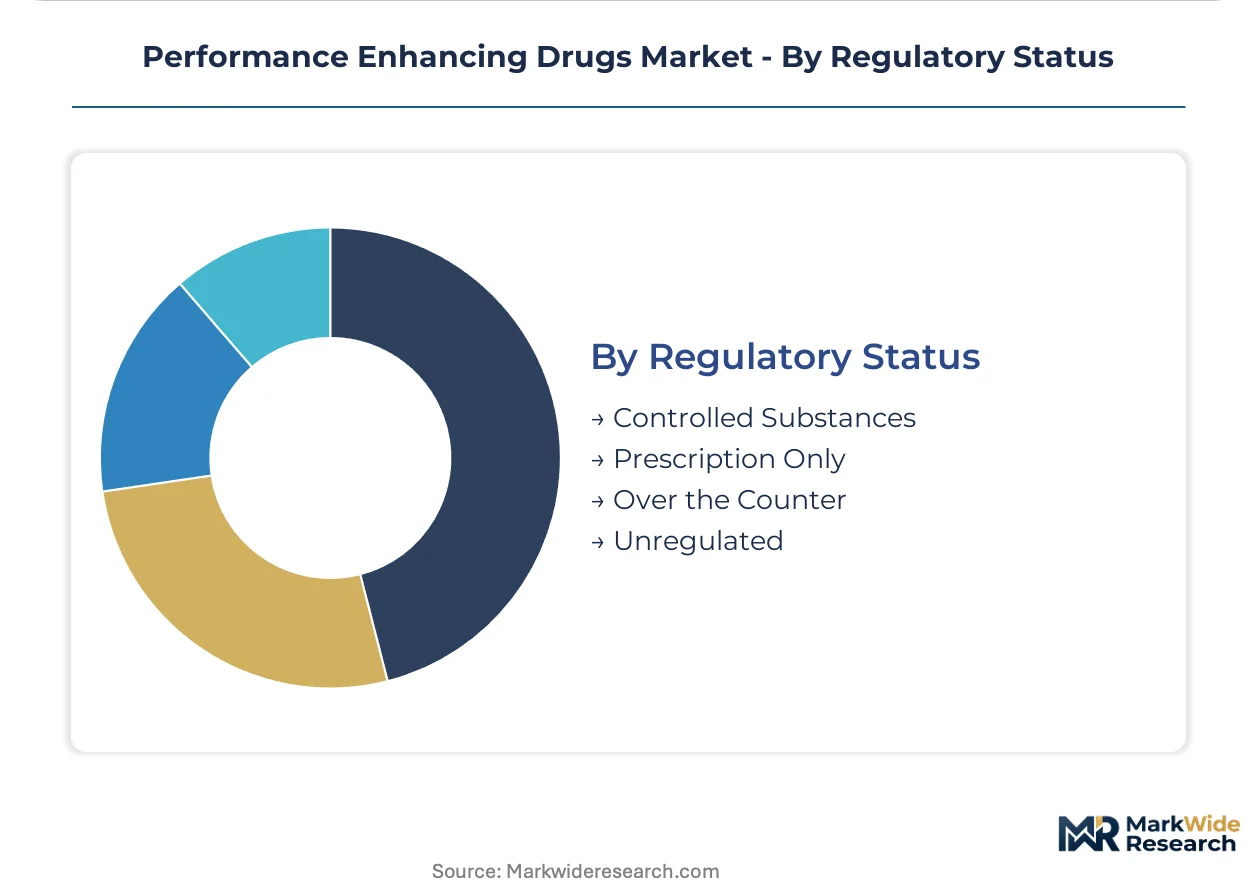
Regulatory Status:
Compliance tier determines margin structure and channel access.
- Controlled Substances:DEA Schedule III classification under the Anabolic Steroid Control Act mandates prescription requirements and distribution tracking. Manufacturers face 18-36 month commercialization delays for novel compounds.
- Prescription Only:FDA-approved indications restrict promotion while permitting legitimate medical use. Endocrinology and sports medicine specialists serve as gatekeepers.
- Over the Counter:Nutritional supplement frameworks accommodate precursor compounds and herbal alternatives. Retail shelf presence drives volume through convenience stores and online marketplaces.
- Unregulated:Research chemical designation exploits jurisdictional gaps in precursor scheduling. Customs authorities in the Netherlands and Belgium increasingly scrutinize import declarations for these materials.
Controlled Substances capture premium pricing; unregulated tiers expand volume fastest through channel arbitrage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jebel Ali Free Zone in Dubai concentrates peptide precursor transshipment for Middle Eastern markets, while Swiss cantons offer preferential tax treatment for biologics manufacturing. These incentive structures redirect manufacturing investment away from higher-tax jurisdictions.
United States
Texas and Florida telehealth platforms drive hormone optimization demand among aging professionals. The FDA's Anabolic Steroid Control Act creates scheduling bottlenecks for novel peptide structures. Arizona compounding pharmacies integrate subcutaneous delivery devices into anti-aging protocols.
Germany
Amateur endurance athletes in Bavaria sustain demand for micro-dosing regimens that evade detection thresholds. The country's national anti-doping agency coordinates with WADA-accredited laboratories in Cologne. Frankfurt sports medicine clinics prioritize EMA-registered suppliers over compounded alternatives.
Switzerland
Swissmedic-registered GMP facilities in Basel produce precision-engineered peptide analogs for EU distribution. The cantonal tax framework attracts biologics specialists from Cambridge clusters. Geneva-based contract manufacturers now offer kilogram-scale peptide synthesis.
Australia
Recreational fitness enthusiasts in New South Wales normalize pharmacological biohacking through direct-to-consumer laboratory testing. The Therapeutic Goods Administration scrutinizes import declarations for research chemical precursors. Melbourne sports medicine clinics combine peptide growth factors with platelet-rich plasma injections.
Singapore
Contract development organizations in the Biopolis cluster reduce unit costs for GMP peptide synthesis. The Economic Development Board incentivizes biologics manufacturing scale-up through tax holidays. Local facilities now supply pharmaceutical-grade material to anti-aging clinics across Southeast Asia.
Performance Enhancing Drugs Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consolidated biologics giants controlling prescription-regulated channels while fragmented compounding pharmacies capture wellness-oriented demand. The vendor base organizes around three archetypes: vertically integrated pharmaceutical conglomerates, precision peptide engineering specialists, and telehealth-integrated distribution platforms. Competitive moves concentrate on biologics manufacturing scale-up in Swiss and Singaporean free zones, alongside strategic partnerships between compounding pharmacies and diabetes care device manufacturers.
Among pharmaceutical conglomerates, Pfizer Inc., Novo Nordisk A/S, and Eli Lilly and Company occupy positions that exemplify divergent strategic emphases. Pfizer leverages biologics manufacturing infrastructure to sustain supply chain reliability for regulated peptide products. Novo Nordisk anchors its market presence through endocrine science expertise extending into growth hormone modulation. Eli Lilly differentiates via metabolic research capabilities that position its portfolio for evolving anti-doping compliance frameworks.
| Leading Market Players |
|---|
| Taj Pharmaceuticals Limited |
| Balkan Pharmaceuticals |
| Bayer AG |
| AstraZeneca |
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Pfizer Inc. |
| Onnit Labs, LLC |
| Douglas Laboratories |
| Others |
Value Chain & Pricing Dynamics
Peptide precursor spot prices on the Shanghai chemical exchange cascade through three distinct pricing tiers, with GMP-certified Swiss and Singaporean manufacturers commanding premiums over research-grade Chinese suppliers while telehealth platforms in Texas and Florida compress margins through direct-to-consumer distribution models.
Pricing Analysis
Lead-time premiums for pharmaceutical-grade peptide formulations reach maximum spread against spot inventory discounts in the unregulated research chemical tier. Three-tier pricing structure across GMP-certified, pharmacy-compounded, and unregulated economy levels reflects certification grade and cold-chain logistics investment. Pricing pressure stems from mass spectrometry detection advances at WADA-accredited laboratories that compress product lifecycles and force accelerated reformulation costs. Fitness enthusiasts aged 35-50 through telehealth platforms exhibit lowest price sensitivity, while recreational users sourcing through gym-floor networks drive volume at economy tiers.
Supply Chain Analysis
Freight cost volatility for temperature-controlled peptide shipments between Basel and Dubai transshipment hubs amplifies landed cost differentials across distribution channels. Manufacturing concentrates in China for synthetic precursors, Switzerland for GMP finishing, and Singapore for contract scale-up. Raw material dependencies include amino acid building blocks, lyophilization excipients, and specialized vial components. Single-source vulnerability concentrates in Chinese precursor manufacturers controlling ninety percent of synthetic peptide inputs. Distribution runs through compounding pharmacies in Arizona and Nevada, Swissmedic-registered EU suppliers, and direct-to-consumer telehealth platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum across this market accelerates as manufacturers pursue captive control over peptide precursor supply to mitigate export license volatility from Chinese chemical producers.
For Market Incumbents: To counter detection technology advances at WADA-accredited laboratories, Pfizer and Novo Nordisk should deepen backward integration into amino acid precursor production and secure exclusive distribution partnerships with telehealth platforms in Texas and Florida. Certification investment in Swissmedic and EMA registrations creates defensive moats against unregulated competitors. For New Entrants and Emerging Players: The premium-to-economy price gap in peptide therapeutics offers entry points through pharmacy-compounded intermediates positioned between GMP-certified and research-grade tiers. Target fitness enthusiasts aged 35-50 in California and Colorado through direct-to-consumer laboratory testing partnerships. Go-to-market leverage concentrates on subscription-based hormone optimization protocols that bypass traditional clinic gatekeepers. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision peptide engineering specialists with Swiss or Singaporean manufacturing footprints during periods of FDA scheduling uncertainty. Long-term viability across the next decade hinges on regulatory arbitrage capabilities between national anti-doping frameworks. Monitor WADA prohibited list revision timing as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Scale-Up | Kilogram-scale peptide synthesis in Singapore reduces unit costs for precision-engineered analogs. |
| Telehealth Platform Integration | Direct-to-consumer hormone optimization in Texas and Florida compresses patient acquisition costs below brick-and-mortar models. |
| Regulatory Certification Pathway | Swissmedic and EMA registrations open EU distribution channels while mitigating liability exposure for sports medicine clinics. |
| Backward Integration into Precursors | Captive amino acid supply from Chinese manufacturers insulates against export license volatility and geopolitical friction. |
| Detection-Evasive Reformulation | Annual WADA prohibited list updates force recurring R&D investment to sustain pharmacological efficacy within compliance frameworks. |
Study Parameters
FDA Anabolic Steroid Control Act scheduling records, WADA prohibited substance databases, and Swissmedic registration filings formed the secondary backbone, cross-referenced with primary interviews involving peptide formulation chemists, anti-doping laboratory directors, telehealth platform operators, and compounding pharmacy procurement managers. Bottom-up demand modeling across molecular classes and end-user segments triangulated against top-down regulatory constraint analysis.
Historical trendline analysis of peptide therapeutic commercialization timelines informed projection frameworks across the analysis window, with segmentation dimensions covering product type, delivery mode, regulatory status, and regional compliance cluster. CAGRs derived from patent expiration patterns, detection technology advancement curves, and demographic shift projections in hormone optimization demand. Forecast inputs incorporated WADA protocol revision frequency and FDA scheduling precedent for novel peptide structures.
Underlying measurement precision varies by segment; GMP-certified pharmaceutical channels carry tighter precision than unregulated research chemical tiers due to customs declaration scrutiny variability. Forecasts reflect assumptions regarding regulatory enforcement continuity and detection technology diffusion rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Glioblastoma Treatment Drugs Market
Pharmaceuticals
Endocarditis Drugs Market
Pharmaceuticals
Mild Laxatives Market
Pharmaceuticals
Specialty Active Pharmaceutical Ingredients Market
Pharmaceuticals
Listeria Monocytogenes Treatment Market
Pharmaceuticals
Fucosidosis Therapeutics Market
Pharmaceuticals
Non-Sterile Liquids/Suspensions Market
Pharmaceuticals
Antiviral Drugs Market
Pharmaceuticals
Contraceptive Drugs Market
Pharmaceuticals
Global Chick Embryo Cell Rabies Vaccine Market
Pharmaceuticals
North America Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Asia-Pacific Human Papillomavirus Vaccine Market
Pharmaceuticals
Global Lipid Disorder Treatment Market
Pharmaceuticals
Marburg Virus Disease Therapeutics Market
Pharmaceuticals
Global Paracetamol Market
Pharmaceuticals
Bladder Cancer Treatment Drugs Market