
 Vasopressin Antagonists Market | 2026-2036
Vasopressin Antagonists Market Size, Share, and Industry Trends Forecast 2026-2036
Vasopressin Antagonists Market Analytics
Hospital end-user demand is consolidating as the primary revenue channel for vasopressin antagonist manufacturers, while homecare adoption remains constrained by monitoring requirements. Otsuka Pharmaceutical Co. Ltd. leverages its tolvaptan franchise across hyponatremia and autosomal dominant polycystic kidney disease indications. Merck & Co. Inc. competes through R&D intensity in novel vaptan analogs. Astellas Pharma Inc. anchors its position in the Japanese market with established nephrology relationships.
Vasopressin antagonists constitute a class of pharmaceutical compounds that selectively block arginine vasopressin receptors, primarily V1A and V2 subtypes, to modulate water reabsorption in renal collecting ducts and vascular tone. These agents function by competitively inhibiting vasopressin binding, thereby increasing free water clearance and correcting dilutional hyponatremia without altering sodium excretion. Tolvaptan dominates the product type landscape as the only oral agent with broad approved indications, while conivaptan maintains niche utilization in acute inpatient settings requiring intravenous delivery. The application segment shows heart failure and hyponatremia capturing the largest patient pools, with liver disease representing an emerging but less penetrated indication due to hepatotoxicity monitoring requirements.
The FDA's Risk Evaluation and Mitigation Strategy for tolvaptan and EMA's pharmacovigilance requirements for hepatotoxicity signal shape prescriber behavior and product labeling across developed markets. Japan's PMDA maintains distinct efficacy thresholds for hyponatremia correction that influence regional formulation strategies. Stakeholders must monitor evolving biomarker-guided patient selection criteria and competitive entry of generic tolvaptan formulations to anticipate shifts in pricing power and therapeutic positioning.
Market Dynamics
The FDA's Risk Evaluation and Mitigation Strategy for tolvaptan hepatotoxicity monitoring is compressing prescribing flexibility while simultaneously creating compliance barriers that reshape competitive positioning among hospital formularies and specialty nephrology practices.
Growth Catalysts
- Orphan drug incentives:The FDA's orphan drug designation framework accelerates development timelines for rare disease indications such as autosomal dominant polycystic kidney disease, expanding reimbursable patient pools.
- Hospital formulary consolidation:Integrated delivery networks in the United States are standardizing hyponatremia protocols around single-agent preferred drug lists, concentrating volume with established vaptan suppliers.
- Biomarker-guided selection:Urinary aquaporin-2 assays and arginine vasopressin level stratification are enabling precision dosing that improves correction rates and reduces rebound hyponatremia.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthetic peptide manufacturing for vaptan scaffolds concentrates among contract manufacturers in India and China, exposing supply continuity to geopolitical friction and import inspection backlogs.
- Intravenous administration limitations:Conivaptan's hospital-only infusion requirement restricts utilization to acute care settings, excluding chronic outpatient management where oral tolvaptan dominates.
- Generic entry timelines:Patent cliff dynamics for tolvaptan formulations in the United States and European Union are compressing originator pricing power ahead of anticipated multi-source competition.
Strategic Opportunities
- Pediatric hyponatremia protocols:Underpenetrated neonatal and pediatric ICU segments in Germany and France present expansion vectors as EMA pediatric investigation plan obligations mature into approved indications.
- Home infusion services:Specialty pharmacy distribution channels are enabling monitored outpatient vaptan administration that bridges acute correction and chronic maintenance without hospital admission.
- Combination therapy positioning:Convergent use with SGLT2 inhibitors in heart failure populations is creating protocol-level integration opportunities that differentiate vaptan prescribing from diuretic monotherapy.
Industry Challenges
- Hepatotoxicity surveillance infrastructure:Monthly liver function test requirements impose patient compliance burdens and laboratory coordination costs that fragment care continuity.
- Pharmacovigilance reporting complexity:EMA's enhanced adverse event documentation for suspected drug-induced liver injury strains smaller market authorization holders with limited regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vasopressin Antagonists Market |
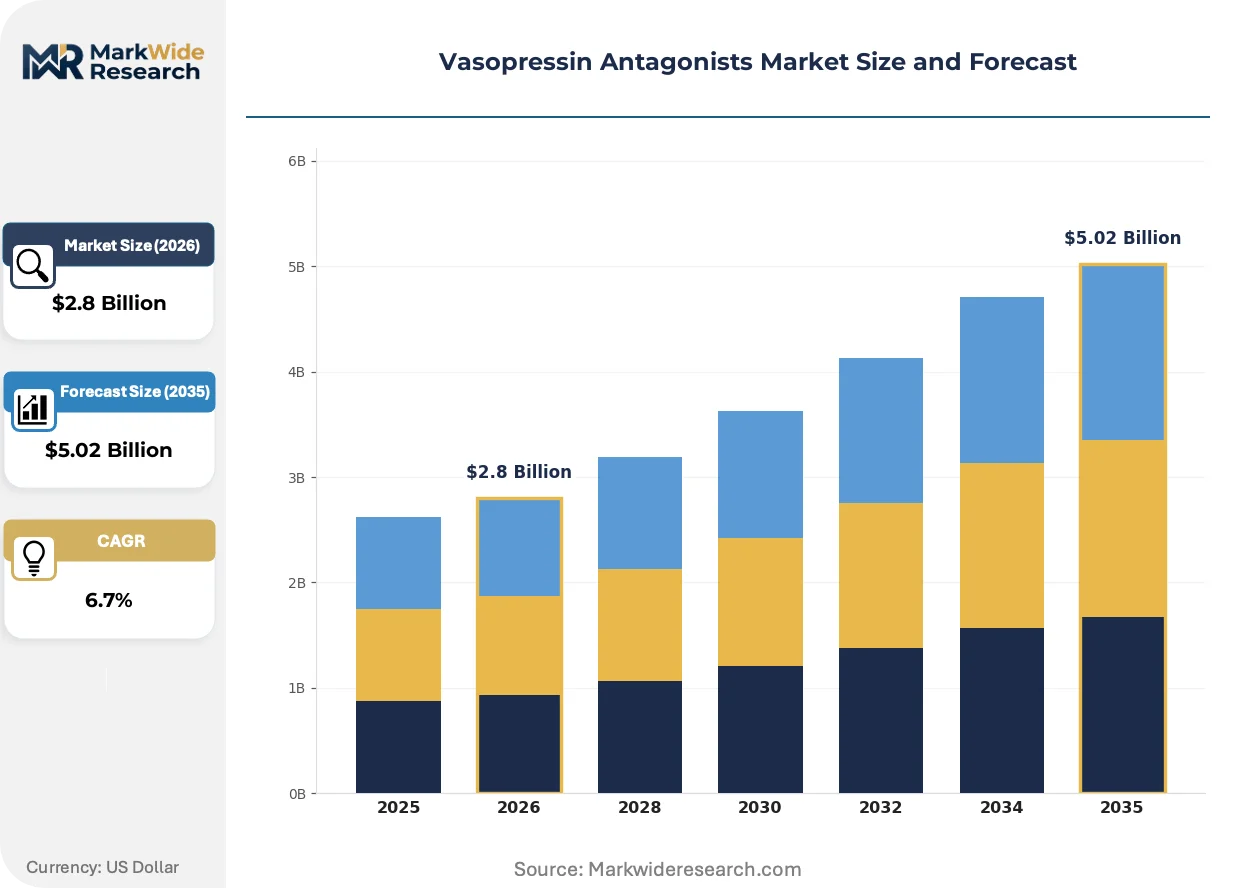
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conivaptan, Tolvaptan, Lixivaptan, Others Application: Heart Failure, Hyponatremia, Liver Disease, Kidney Disorders Delivery Mode: Injection, Oral, Infusion, Others End User: Hospitals, Clinics, Homecare, Long-term Care Facilities |
| Companies Covered | Otsuka Pharmaceutical Co. Ltd., Cumberland Pharmaceuticals Inc., Merck & Co. Inc., Boehringer Ingelheim GmbH, Merck KGaA, Astellas Pharma Inc., Azevan Pharmaceuticals Inc., Athenex Inc., Dr. Reddys Laboratories Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vasopressin Antagonists Market Evolving Landscape
Biomarker integration and digital therapeutic adjuncts are reconfiguring how vasopressin antagonist therapy is initiated, monitored, and reimbursed across acute and chronic care continuums.
Next-generation vaptan analogs with modified pharmacokinetic profiles are unifying rapid onset with extended duration, enabling single-dose correction protocols. Hospital pharmacy and therapeutics committees are adopting these agents for emergency department hyponatremia pathways. This convergence is compressing average length of stay for hyponatremia admissions and shifting economic value toward the index hospital encounter.
The EMA's pharmacovigilance risk assessment committee has mandated enhanced liver safety monitoring across all vasopressin antagonist-containing products, requiring quarterly benefit-risk reassessments. Marketing authorization holders must submit periodic safety update reports with cumulative hepatotoxicity signal detection. Specialist prescribers in France and Italy are responding by restricting initiation to hepatology-cleared patients and implementing shared-care protocols with hepatology services.
Integrated health systems are unbundling drug acquisition from clinical monitoring services, creating separate reimbursement streams for vaptan therapy and laboratory surveillance. Hospital outpatient departments are displacing traditional infusion centers as the locus of chronic vaptan administration. This reconfiguration is most visible in United States Medicare Advantage populations where capitated payment models incentivize site-of-care optimization.
Vasopressin Antagonists Market Segmentation
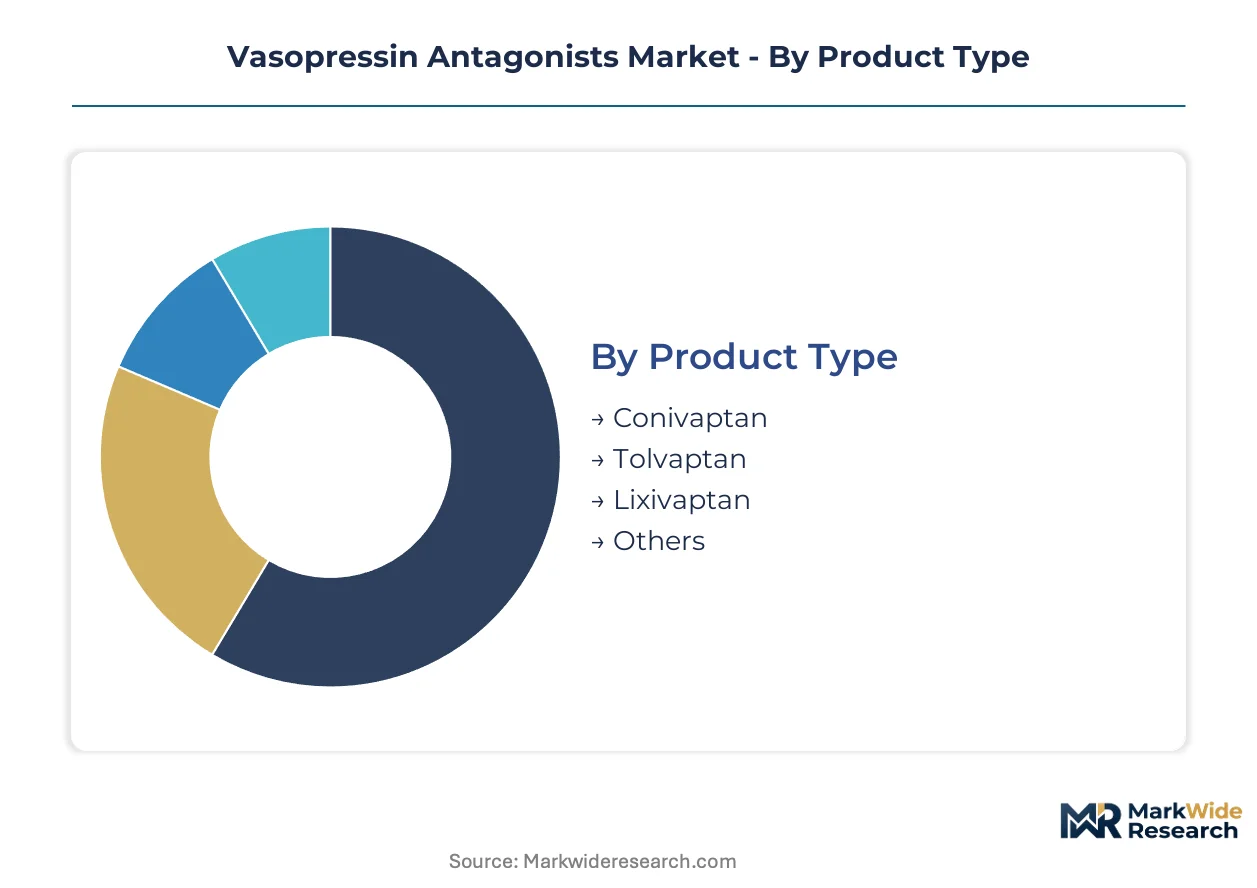
Vasopressin antagonist prescribing patterns fragment sharply across acute versus chronic care settings, with product form and delivery mode determining reimbursement pathways and prescriber access. Segmentation clarity enables manufacturers to align formulation investments with site-of-care economics and regulatory surveillance requirements.
Product Type:
Standalone oral agents dominate outpatient chronic management, while intravenous formulations embed within hospital protocols for acute correction.
- Tolvaptan:Oral V2-selective antagonist with FDA-approved indications spanning hyponatremia and autosomal dominant polycystic kidney disease. Hospital formularies in the United States anchor volume through integrated hyponatremia protocols, though hepatotoxicity REMS requirements constrain prescribing flexibility.
- Conivaptan:Dual V1A/V2 antagonist delivered via intravenous infusion, restricted to inpatient settings by its infusion requirement and shorter half-life. Emergency departments and ICUs in Germany and France concentrate utilization for rapid sodium correction in symptomatic patients.
- Lixivaptan:Oral V2-selective agent with modified pharmacokinetic profile designed for once-daily dosing; clinical development programs target heart failure populations with preserved ejection fraction.
- Others:Investigational vaptan analogs including mozavaptan and satavaptan, plus next-generation compounds in Phase II trials with extended-duration profiles.
Volume placements concentrate in Tolvaptan; the faster expansion belongs to Lixivaptan as heart failure protocols evolve.
Application:
Cost tier stratification separates high-acuity inpatient indications from chronic outpatient maintenance, with reimbursement intensity varying by correction urgency and monitoring burden.
- Hyponatremia:Dilutional sodium deficiency arising from syndrome of inappropriate antidiuretic hormone secretion, heart failure, or cirrhosis. Specialist nephrology and hospitalist services in the United States drive demand through protocolized correction pathways.
- Heart Failure:Volume overload management in acute decompensated and chronic heart failure populations. Cardiology departments in Japan leverage PMDA-approved labeling for congestion relief alongside loop diuretics.
- Liver Disease:Ascites and dilutional hyponatremia in cirrhotic patients; hepatotoxicity surveillance requirements limit penetration despite unmet need in hepatology services.
- Kidney Disorders:Autosomal dominant polycystic kidney disease progression modification and dialysis-related water retention; nephrology practices coordinate with genetic counseling services for patient selection.
Revenue concentration sits with Hyponatremia; Kidney Disorders is climbing the fastest as orphan drug pathways mature.
Delivery Mode:
Customer type alignment determines route selection, with hospital purchasing departments favoring infusion controls and outpatient pharmacies prioritizing oral adherence.
- Oral:Tablet and liquid formulations enabling chronic outpatient administration with monthly laboratory monitoring. Medicare Advantage plans in the United States favor this route for site-of-care cost containment.
- Injection:Bolus intravenous delivery for rapid onset in emergency settings; anesthesiology and critical care units control utilization through restricted drug protocols.
- Infusion:Continuous intravenous delivery requiring pump infrastructure and nursing supervision; limited to tertiary hospital settings with pharmacy compounding capabilities.
- Others:Subcutaneous depot formulations and transdermal patches in preclinical development, targeting adherence improvement in chronic populations.
Procurement volume clusters around Oral delivery; Infusion commands the steepest expansion trajectory as hospital-at-home programs proliferate.
End User:
Supply concentration in integrated delivery networks concentrates purchasing power among large hospital systems, fragmenting access for smaller clinical settings.
- Hospitals:Acute care facilities with emergency departments, ICUs, and specialty nephrology services. IDN formulary committees in the United States standardize vaptan selection through value-based contracting.
- Clinics:Outpatient nephrology and cardiology practices managing chronic hyponatremia and heart failure; laboratory coordination capabilities determine prescribing eligibility.
- Homecare:Specialty pharmacy and home infusion services delivering oral and select intravenous vaptans with remote monitoring; growth constrained by hepatotoxicity surveillance infrastructure requirements.
- Long-term Care Facilities:Skilled nursing facilities managing stable chronic hyponatremia; regulatory complexity and laboratory access limitations restrict penetration.
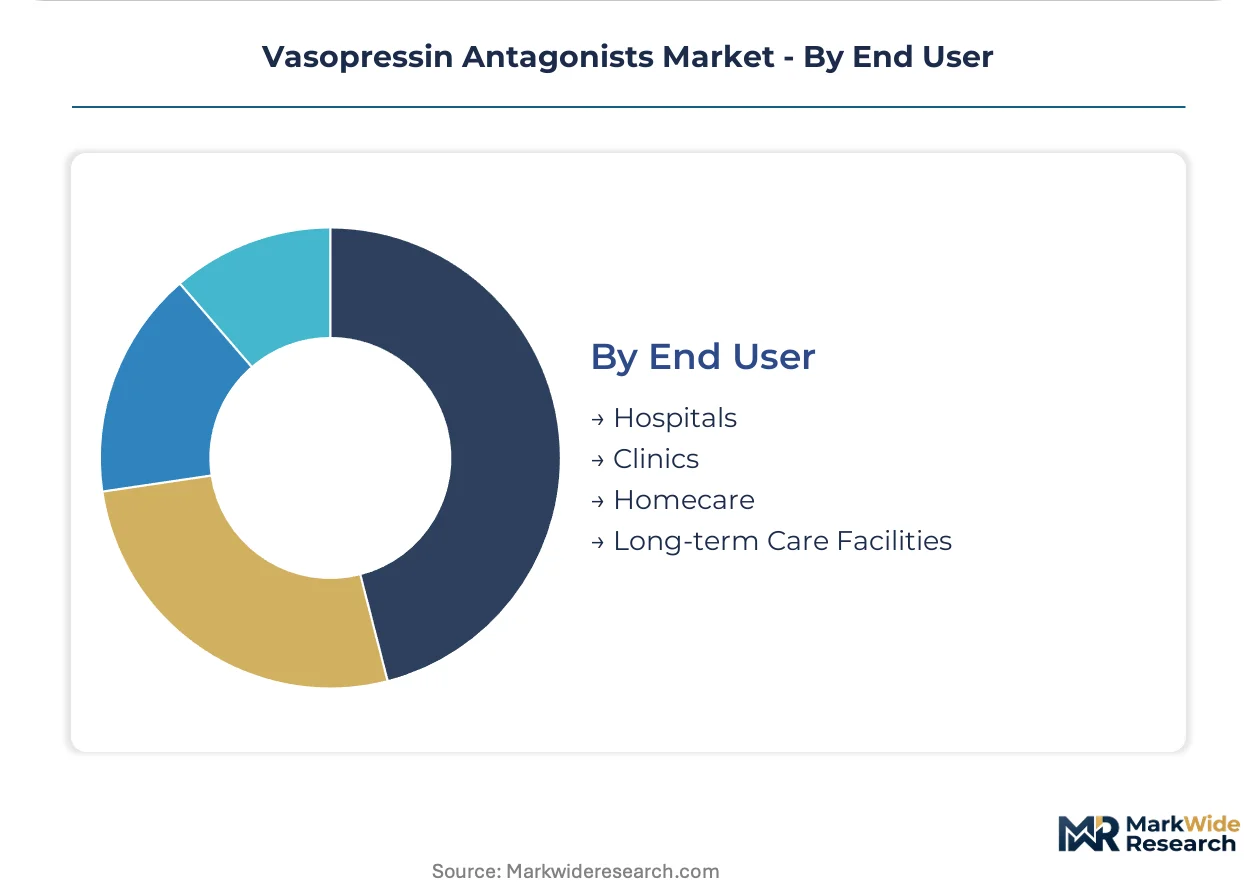
Patient encounters concentrate in Hospitals; Homecare is gaining share fastest as remote monitoring technologies advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of vasopressin antagonist active pharmaceutical ingredients concentrates in Indian and Chinese contract facilities, while consumption tilts toward hospital systems in the United States, Germany, and Japan where chronic heart failure and hyponatremia protocols drive specialist prescribing.
United States
Hospital formulary consolidation within integrated delivery networks concentrates purchasing power for tolvaptan and conivaptan among large academic medical centers in Boston and Houston. The FDA's Risk Evaluation and Mitigation Strategy for hepatotoxicity monitoring shapes prescriber behavior and limits homecare expansion. Specialist nephrology practices in the Midwest coordinate with pharmacy benefit managers to navigate prior authorization requirements.
Germany
Emergency departments in Berlin and Munich utilize intravenous conivaptan for rapid sodium correction in symptomatic hyponatremia patients. The country's national pharmaceutical regulator enforces EMA pharmacovigilance requirements for liver safety monitoring that influence hospital protocol design. Outpatient nephrology clinics in Bavaria are piloting biomarker-guided dosing protocols using urinary aquaporin-2 assays.
Japan
Cardiology departments in Tokyo and Osaka leverage PMDA-approved labeling for vasopressin antagonist use in heart failure congestion management alongside loop diuretics. The Ministry of Economy, Trade and Industry supports domestic pharmaceutical manufacturing through targeted industrial policy. Astellas Pharma anchors its position through established relationships with regional nephrology societies in Kansai and Chubu regions.
India
Contract manufacturers in Hyderabad and Ahmedabad produce synthetic peptide scaffolds for vaptan compounds serving global supply chains. The Central Drugs Standard Control Organization regulates active pharmaceutical ingredient export certifications that enable participation in US and EU markets. Domestic hospital adoption remains limited by cost containment priorities in public sector healthcare facilities.
Switzerland
Specialty pharmaceutical research clusters in Basel host development programs for next-generation vaptan analogs with modified pharmacokinetic profiles. Swissmedic maintains distinct efficacy thresholds for hyponatremia correction that influence regional clinical trial design. University hospital networks in Geneva and Zurich coordinate multinational investigator-initiated studies for rare disease indications.
Vasopressin Antagonists Market Competitive Landscape
Top-tier vendors anchor originator drug development, while mid-tier specialists and generic manufacturers occupy downstream formulation and supply chain positions. The competitive structure reflects patent cliff dynamics for oral tolvaptan formulations alongside REMS-limited prescribing flexibility that protects incumbent positions. Strategic archetypes include integrated pharmaceutical conglomerates with nephrology franchises, hospital-focused specialty pharmaceutical firms, and contract manufacturing organizations with peptide synthesis capabilities. Competitive moves center on geographic licensing arrangements for rare disease indications and vertical integration into active pharmaceutical ingredient production.
Among Japan-based pharmaceutical conglomerates, Otsuka Pharmaceutical Co. Ltd. and Astellas Pharma Inc. occupy positions defined by regional nephrology relationships and established hospital formulary presence. Merck & Co. Inc. represents the integrated multinational archetype with research intensity in novel vaptan analogs. These three companies exemplify distinct strategic postures: regional franchise depth, multinational R&D scale, and integrated commercial infrastructure respectively.
| Leading Market Players |
|---|
| Otsuka Pharmaceutical Co. Ltd. |
| Cumberland Pharmaceuticals Inc. |
| Merck & Co. Inc. |
| Boehringer Ingelheim GmbH |
| Merck KGaA |
| Astellas Pharma Inc. |
| Azevan Pharmaceuticals Inc. |
| Athenex Inc. |
| Dr. Reddys Laboratories Ltd. |
| Others |
Value Network & Pricing Analysis
Modified pharmacokinetic profiles in next-generation vaptan analogs are simultaneously compressing manufacturing cycle times and concentrating synthetic peptide production among specialized contract manufacturers in India and China. This convergence reshapes cost economics for hospital purchasers while embedding geopolitical exposure into pricing negotiations.
Pricing Analysis
Short lead-time premiums for REMS-compliant tolvaptan supply contrast with discounted spot inventory of intravenous conivaptan nearing patent expiration. Three-tier pricing structure across originator formulations, authorized generics, and multi-source competition reflects hepatotoxicity monitoring bundling and formulary tier placement. Cost compression in oral generic segments is intensifying because of anticipated FDA approvals, while hospital IDNs with captive pharmacy services exhibit lowest price sensitivity.
Supply Chain Analysis
Freight cost volatility for temperature-controlled active pharmaceutical ingredient shipments from Hyderabad and Ahmedabad to US and EU formulation facilities is compressing margin structures for mid-tier distributors. Synthetic peptide scaffolds draw from contract manufacturers in India, China, and Switzerland, with final fill-finish resting on facilities in Germany and Japan. Single-source vulnerability concentrates in arginine vasopressin receptor antagonist precursor supply. Distribution runs through hospital purchasing cooperatives and specialty pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into active pharmaceutical ingredient production represents the decisive competitive lever as patent cliffs approach and REMS infrastructure becomes the primary moat.
For Market Incumbents: To counter generic tolvaptan entry and hepatotoxicity surveillance commoditization, deepen captive supply of synthetic peptide scaffolds through acquisition of Indian contract manufacturers. Secure exclusive formulation partnerships with integrated delivery networks in the United States to lock in hospital formulary placement ahead of multi-source competition.
For New Entrants and Emerging Players: Begin with pediatric hyponatremia protocols in Germany and France where EMA pediatric investigation plan obligations have matured into addressable regulatory pathways. Target home infusion services bridging acute correction and chronic maintenance, leveraging remote liver function monitoring technologies to circumvent incumbent REMS infrastructure advantages.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to hospital-focused specialty pharmaceutical firms seeking nephrology franchise depth. Five-to-ten-year viability hinges on hepatotoxicity risk mitigation capabilities and REMS program operational scale. Monitor FDA generic approval timelines as the critical inflection signal for originator pricing power erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| REMS Program Expansion | Operational scale in hepatotoxicity surveillance creates formulary stickiness against generic substitution. |
| Pediatric Investigation Plan Execution | EMA-mandated studies in neonatal ICU segments unlock reimbursable patient pools in France and Germany. |
| Biomarker-Guided Dosing Development | Urinary aquaporin-2 assay integration differentiates precision positioning from diuretic monotherapy. |
| Specialty Pharmacy Network Partnership | Home infusion capabilities bypass hospital site-of-care limitations for chronic maintenance populations. |
| Active Pharmaceutical Integration | Captive supply of synthetic peptide scaffolds insulates margin from Indian and Chinese contract manufacturer concentration. |
Research Methodology
Independent corroboration across regulatory filings, hospital procurement databases, and clinical trial registries underwrites the qualitative findings in this study. Primary interviews with drug development executives, formulary directors, regulatory affairs leads, and payer access specialists combined with secondary validation from FDA REMS documentation, EMA pharmacovigilance reports, ClinicalTrials.gov entries, and hospital GPO contract disclosures. Bottom-up patient-flow modeling and top-down pharmaceutical expenditure triangulation anchored segmentation outputs.
Rate-of-change decomposition across patient population growth, treatment penetration shifts, and pricing trajectory segments informed the analytical framework over the projection horizon. Segmentation dimensions encompassed product type, application indication, delivery mode, end-user setting, and regional regulatory cluster. CAGRs derived from log-linear trend fitting applied to historical volume and value series, with biomarker adoption curves and generic entry scenarios as industry-specific forecast inputs.
Underlying measurement precision varies by segment; hospital end-user and oral delivery categories carry tighter precision than emerging homecare applications. Forecasts reflect documented assumptions regarding REMS program persistence, hepatotoxicity signal evolution, and integrated delivery network consolidation trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Next-Generation Immunology Drugs Market
Pharmaceuticals
Medicinal Fungi Market
Pharmaceuticals
Global HPMC Capsules Market
Pharmaceuticals
Global Ceftiofur Market
Pharmaceuticals
Acetaminophen Market
Pharmaceuticals
Calcitriol Capsules Market
Pharmaceuticals
Topical Drugs CDMO Market
Pharmaceuticals
Belgium Pharmaceutical Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market
Pharmaceuticals
Human Papillomavirus (HPV) Vaccine Market
Pharmaceuticals
Metformin Hydrochloride Market
Pharmaceuticals
Hard Empty HPMC Capsule Market
Pharmaceuticals
OTC Dry Eye Drops Market
Pharmaceuticals
Global Lipid Disorder Treatment Market
Pharmaceuticals
Global Nausea Medicine Market
Pharmaceuticals
Bispecific Antibody Therapeutics Contract Manufacturing Market