
 Croatia Pharmaceutical Market | 2026-2036
Croatia Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Croatia Pharmaceutical Market Insights
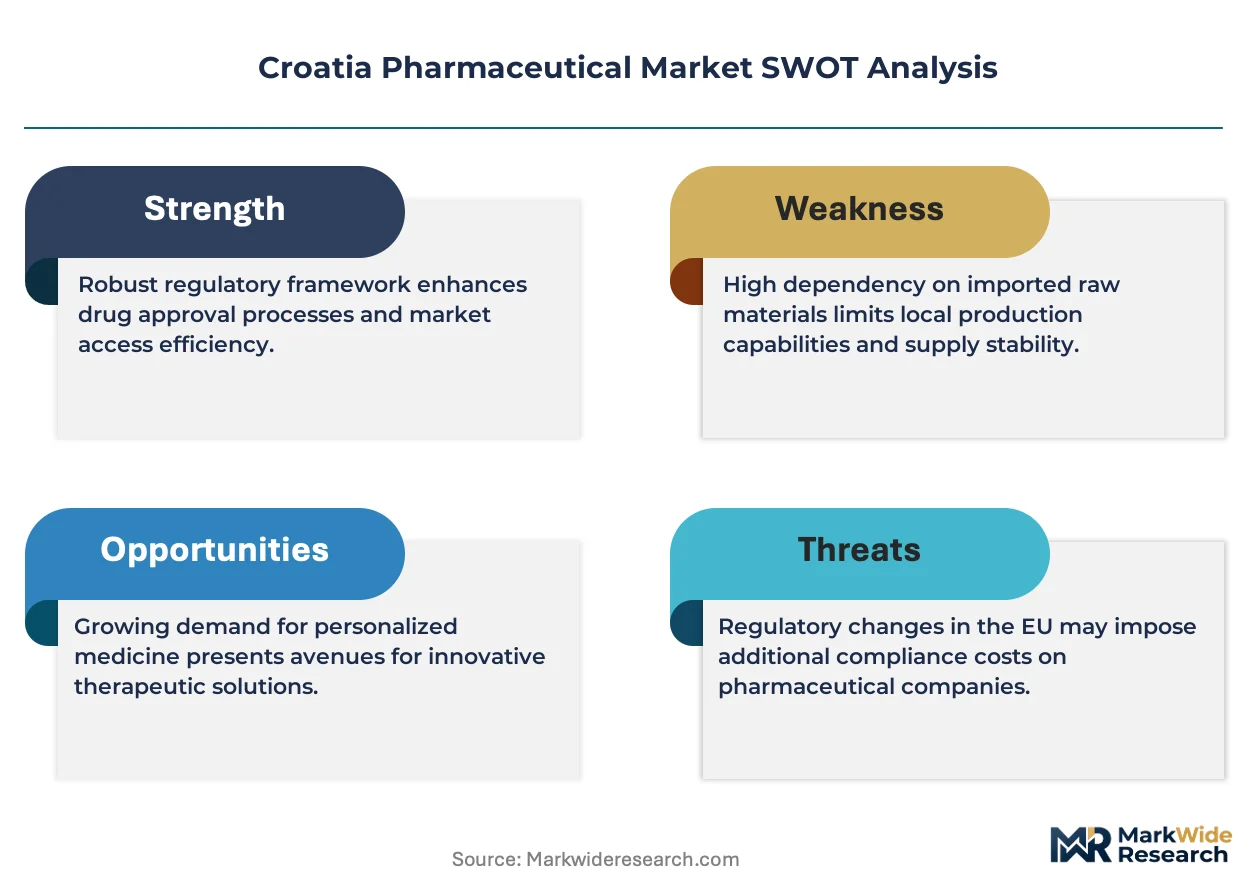
The EU Green Deal pharmaceutical sustainability framework is rebalancing procurement criteria across Croatian hospital networks. Pliva Croatia leverages its Zagreb manufacturing base to sustain domestic supply chain reliability for critical generics. Belupo anchors its position through specialized prescription medicines targeting cardiovascular and neurology segments. JGL competes in the over-the-counter and dermocosmetic space, differentiating through pharmacy channel control rather than hospital tenders.
Pharmaceuticals comprise chemically synthesized or biologically derived active substances formulated for disease prevention, diagnosis, or treatment, with specifications including purity thresholds, bioavailability parameters, and stability profiles under ICH guidelines. Prescription medicines dominate value generation as Croatia's HZZO reimbursement list concentrates spending on chronic disease management, while biologics capture expanding margin pools in oncology and autoimmune therapy areas. Generics face margin compression from parallel trade flows, yet oral delivery modes maintain volume leadership across retail pharmacy and home care channels where patient adherence programs drive repeat dispensing.
The Agency for Medicinal Products and Medical Devices of Croatia (HALMED) enforces EU MDR-aligned pharmacovigilance standards, while the Ministry of Health shapes market access through national reimbursement list revisions that directly determine product commercial viability. BIS and CDSCO equivalency assessments for imported active pharmaceutical ingredients add compliance layers for manufacturers sourcing from India. Stakeholders must monitor how Croatia's EU presidency rotations and evolving HTA methodologies redistribute bargaining power between domestic producers and multinational patent holders.
Market Dynamics
The EU Falsified Medicines Directive serialization mandate is compressing packaging timelines for Croatian manufacturers while hospital procurement centralization around oncology biologics concentrates purchasing power in Zagreb and Split university networks.
Growth Catalysts
- EU Green Deal pharmaceutical sustainability framework:Croatian hospital networks are rebalancing procurement criteria toward carbon footprint metrics and circular packaging standards, favoring domestic manufacturers with localized supply chains.
- Biologics demand concentration:Croatia's HZZO reimbursement list expansion for oncology and autoimmune therapies is pulling investment toward cold-chain infrastructure and specialized distribution capabilities in university hospital clusters.
- Serialization compliance investment:Domestic manufacturers upgrading track-and-trace systems are capturing contract manufacturing opportunities from regional neighbors still adapting to EU Falsified Medicines Directive requirements.
Market Restraints
- Active pharmaceutical ingredient import dependency:BIS and CDSCO equivalency assessments for Indian-sourced APIs add 6-12 month approval delays and testing cost burdens for Croatian formulators.
- Parallel trade arbitrage pressure:Price differentials with neighboring EU member states enable re-importation of identical generics, eroding domestic pharmacy margins and manufacturer volume commitments.
- Reimbursement list rigidity:HZZO's biannual revision cycle and HTA methodology constraints limit rapid commercialization pathways for novel therapies even after EMA approval.
Strategic Opportunities
- Dalmatia and Slavonia regional expansion:Secondary city hospital networks outside Zagreb-Split axis remain underserved for specialty pharmacy services and chronic disease management programs.
- Home care channel development:Post-pandemic patient preference for outpatient biologic administration is creating demand for certified home infusion networks and pharmacy-delivered adherence packaging.
- EU presidency regulatory influence windows:Croatia's rotating council leadership positions create temporary leverage to shape pharmaceutical procurement harmonization directives favoring domestic manufacturing scale.
Industry Challenges
- Qualified pharmacovigilance specialist scarcity:HALMED's EU MDR-aligned reporting requirements exceed domestic training pipeline output, forcing reliance on contracted EU regulatory affairs consultancies.
- Legacy ERP serialization integration:Mid-sized manufacturers face 18-24 month system overhauls to achieve EU Falsified Medicines Directive compliance without disrupting batch release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Croatia Pharmaceutical Market |
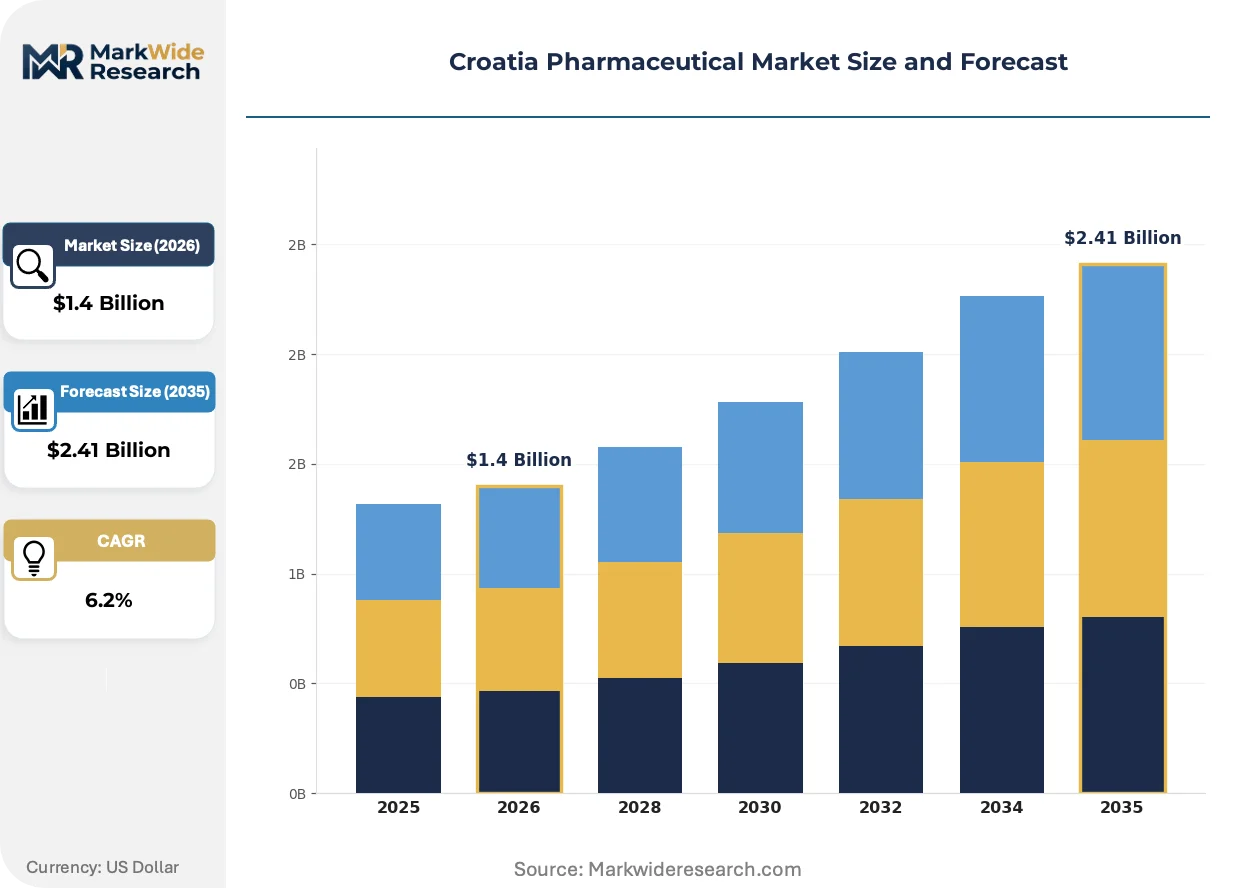
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Medicines, Over-the-Counter Drugs, Biologics, Generics End User: Hospitals, Retail Pharmacies, Clinics, Home Care Therapy Area: Oncology, Cardiovascular, Neurology, Infectious Diseases Delivery Mode: Oral, Injectable, Transdermal, Inhalation |
| Companies Covered | Pliva Croatia, Belupo, TAPI, JGL, PharmaS, Fidifarm, Pfizer Inc., Novartis AG, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Croatia Pharmaceutical Market Trends and Innovations
Digital traceability infrastructure and sustainable packaging mandates are converging to reshape Croatian pharmaceutical manufacturing economics, while procurement centralization is compressing supplier negotiation cycles.
Track-and-trace serialization platforms are automating batch verification workflows from manufacturing through pharmacy dispensing. Domestic manufacturers and hospital procurement networks are adopting these systems ahead of EU Falsified Medicines Directive enforcement deadlines. The technology is automating compliance documentation and reducing manual inspection labor at distribution checkpoints.
HALMED's alignment with EU MDR pharmacovigilance standards is tightening adverse event reporting timelines and post-market surveillance obligations for all marketed products. Domestic manufacturers must now maintain EU-equivalent quality management systems to retain manufacturing authorizations. Oncology biologics and high-risk implantable devices face the steepest compliance cost escalation.
Hospital procurement consolidation into centralized tendering bodies is fragmenting traditional pharmacy-wholesaler relationships. Zagreb and Split university hospital networks now negotiate directly with manufacturers for high-value biologic categories, bypassing regional distributors. This concentration is most visible in oncology and immunology therapy procurement where annual contract values justify dedicated account management resources.
Croatia Pharmaceutical Market Segmentation
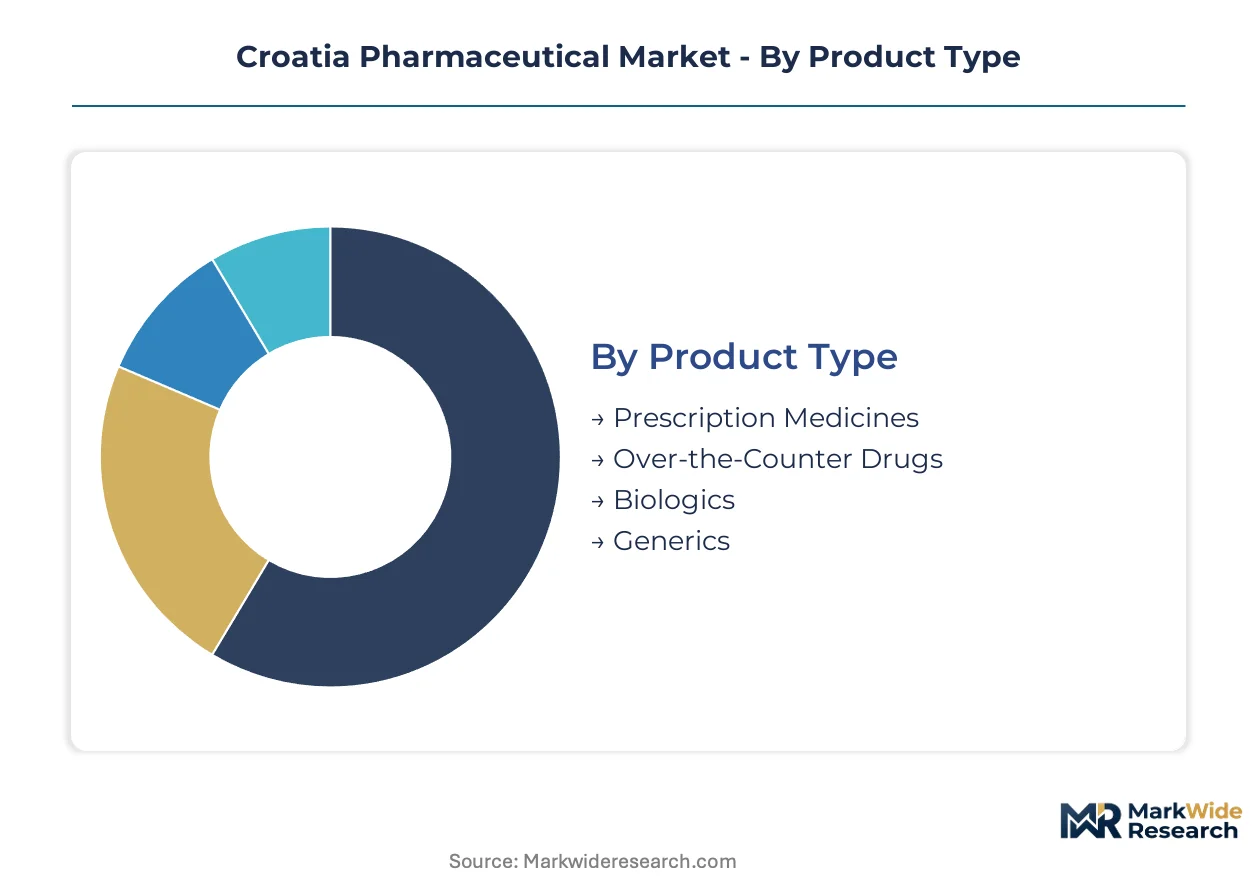
Croatia's pharmaceutical segmentation reveals how HZZO reimbursement priorities and hospital procurement centralization reshape commercial pathways across product categories. Therapy area concentration in Zagreb-Split corridors and delivery mode preferences for outpatient care define competitive positioning for domestic and multinational suppliers.
Product Type:
Active ingredient complexity and regulatory pathway differentiation separate high-margin biologics from volume-driven generic categories in Croatian procurement frameworks.
- Prescription Medicines:Chronic disease formulations dominate HZZO reimbursement spending, with cardiovascular and diabetes therapies anchoring pharmacy dispensing volumes through Zagreb's hospital outpatient networks. Zagreb Clinical Hospital Center and Split University Hospital concentrate demand for specialist-prescribed chronic therapies where adherence programs drive repeat dispensing cycles.
- Biologics:Monoclonal antibodies and recombinant proteins require cold-chain infrastructure investment, with oncology and autoimmune applications capturing procurement attention through centralized university hospital tenders. HZZO's expanding reimbursement list for biologic therapies pulls distribution capabilities toward Zagreb and Split clusters where infusion centers anchor administration.
- Over-the-Counter Drugs:Pharmacy channel control determines competitive outcomes for analgesics and digestive remedies across Croatia's retail network.
- Generics:Price compression from parallel trade arbitrage with neighboring EU states erodes margin pools for oral solid dosage forms.
Prescription medicines lead on scale; biologics lead on momentum.
End User:
Procurement centralization intensity varies sharply across Croatian healthcare delivery settings, fragmenting supplier engagement models.
- Hospitals:Centralized tendering bodies at Zagreb and Split university networks negotiate directly with manufacturers for high-value biologics, bypassing traditional wholesale relationships. Oncology and immunology procurement concentrates annual contract values that justify dedicated account management and cold-chain logistics investment.
- Retail Pharmacies:Community pharmacy networks dispense reimbursed chronic therapies and over-the-counter categories, with patient adherence packaging programs differentiating service levels. Split and Rijeka pharmacy chains compete on home delivery capabilities for elderly patient populations.
- Clinics:Specialist outpatient settings in Osijek and Zadar administer injectable therapies outside hospital admission pathways.
- Home Care:Post-pandemic patient preference shifts demand certified infusion networks for biologic administration in domestic settings.
Hospitals command procurement leverage; home care channels are expanding most quickly.
Therapy Area:
Disease burden demographics and HZZO prioritization frameworks concentrate commercial investment in specific therapeutic domains.
- Oncology:Targeted therapies and immunotherapies drive biologics procurement through HALMED's accelerated assessment pathways for high-unmet-need indications. Zagreb's KBC Zagreb and Split's KBC Split anchor clinical trial participation and early access programs for novel oncology agents.
- Cardiovascular:Hypertension and dyslipidemia prescriptions sustain pharmacy volume leadership across Croatia's aging population, with generic statins and ACE inhibitors dominating reimbursed dispensing. Dalmatia regional networks emphasize stroke prevention programs linking hospital discharge to community pharmacy follow-up.
- Neurology:Multiple sclerosis and epilepsy therapies require specialist prescribing networks concentrated in university hospital neurology departments.
- Infectious Diseases:Antimicrobial stewardship programs constrain broad-spectrum antibiotic utilization in Croatian hospital formularies.
Cardiovascular therapies lead on scale; oncology leads on momentum.
Delivery Mode:
Patient adherence requirements and administration setting constraints shape formulation development priorities for Croatian market entry.
- Oral:Tablet and capsule formulations maintain volume leadership across retail pharmacy and home care channels where self-administration drives patient preference. Zagreb-based manufacturers prioritize immediate-release and modified-release oral solids for HZZO reimbursement list positioning.
- Injectable:Subcutaneous and intravenous delivery modes concentrate in hospital and home infusion settings for biologics and parenteral generics. Cold-chain infrastructure investment in Split and Osijek distribution hubs enables temperature-controlled injectable reach to regional hospital networks.
- Transdermal:Patch formulations for pain management and hormone replacement occupy niche pharmacy segments.
- Inhalation:Respiratory therapies for asthma and COPD require patient training programs linked to pulmonology clinic networks.
Oral delivery leads on scale; injectable modes gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Croatia's pharmaceutical industry traces its modern foundations to Pliva's 1921 establishment in Zagreb, which established domestic manufacturing capabilities that expanded through Yugoslav-era production networks and reoriented toward EU regulatory alignment following 2013 accession.
Zagreb
Zagreb concentrates Croatia's pharmaceutical manufacturing infrastructure and regulatory headquarters, with Pliva Croatia and Belupo anchoring production of generics and specialized prescription medicines. HALMED's central offices coordinate EU MDR-aligned pharmacovigilance enforcement across the national territory. The city's university hospital network, led by KBC Zagreb, dominates procurement of oncology biologics and immunotherapy agents.
Split
Split anchors Dalmatia's pharmaceutical distribution corridor, with KBC Split serving as the southern hub for biologics infusion and clinical trial participation. The city's port infrastructure supports temperature-controlled import logistics for cold-chain therapies. Regional pharmacy chains compete on home delivery capabilities for elderly populations across coastal counties.
Osijek
Osijek represents Slavonia's pharmaceutical access point, with specialist outpatient clinics administering injectable therapies outside hospital admission pathways. The city's location near Hungarian and Serbian borders exposes retail pharmacies to parallel trade arbitrage pressure. Regional hospital networks remain underserved for specialty pharmacy services compared to Zagreb-Split corridors.
Rijeka
Rijeka's Adriatic port facilities handle API import volumes for domestic formulators facing BIS and CDSCO equivalency assessment requirements for Indian-sourced materials. The city's pharmacy chains differentiate through chronic disease management programs targeting aging coastal populations. Proximity to Slovenian and Italian markets creates price comparison dynamics for reimbursed generics.
Croatia Pharmaceutical Market Competitive Landscape
Premium-margin players sit above commodity-margin players across therapy complexity and cold-chain infrastructure requirements. Domestic manufacturers with localized supply chains capture procurement preference under EU Green Deal sustainability frameworks, while multinational patent holders concentrate on biologics categories with concentrated hospital tender access. Three archetypes define competitive positioning: integrated domestic manufacturers with manufacturing authorization depth, multinational biologics specialists with university hospital account management, and regional generic formulators exposed to parallel trade compression. Consolidation pressure operates through hospital procurement centralization and serialization compliance cost escalation.
Among Croatia-based producers, Pliva Croatia exemplifies the integrated domestic manufacturer archetype through its Zagreb production base and critical generics portfolio. Belupo occupies a parallel position anchored in specialized prescription medicines for cardiovascular and neurology segments. JGL represents the differentiated domestic player competing through pharmacy channel control in over-the-counter and dermocosmetic categories rather than hospital tender participation. These three entities collectively illustrate how domestic manufacturing scale, therapy area specialization, and channel strategy diversification create distinct competitive positions under HZZO reimbursement constraints.
| Leading Market Players |
|---|
| Pliva Croatia |
| Belupo |
| TAPI |
| JGL |
| PharmaS |
| Fidifarm |
| Pfizer Inc. |
| Novartis AG |
| Johnson & Johnson |
| Others |
Pricing and Supply Chain Analysis
Captive API sourcing from Zagreb-based manufacturing clusters anchors both supply reliability and pricing power for domestic Croatian formulators confronting HZZO reimbursement constraints. Horizontal consolidation among university hospital procurement bodies concentrates purchasing leverage, compressing margin pools for non-integrated suppliers while rewarding manufacturers with localized production footprints under EU Green Deal sustainability criteria.
Pricing Analysis
Three-tier pricing structure across originator biologics, branded generics, and commodity generics separates margin pools in Croatian pharmaceutical procurement. Price differentiation rests on cold-chain certification tiers and HZZO reimbursement list positioning, with oncology biologics commanding premium positioning through accelerated HALMED assessment pathways. Cost compression in oral solid generics is intensifying because parallel trade arbitrage with neighboring EU member states erodes pharmacy margins. Retail pharmacy chains demonstrate highest price sensitivity for reimbursed chronic therapies, while university hospital procurement bodies negotiate least sensitively for biologics with limited therapeutic substitutes.
Supply Chain Analysis
Temperature-controlled freight costs for biologics distribution absorb disproportionate margin share in Croatian pharmaceutical logistics, particularly for Split-based cold-chain reach to Dalmatia regional networks. Active pharmaceutical ingredient supply concentrates in India and China, with domestic formulators drawing from these sources subject to BIS and CDSCO equivalency assessment delays. Single-source vulnerability for oncology biologics API supply creates structural risk exposure for Croatian manufacturers dependent on Indian import channels. Distribution runs through centralized hospital procurement bodies in Zagreb and Split for high-value categories, while retail pharmacy networks handle reimbursed chronic therapies and over-the-counter products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Croatia's pharmaceutical market functions as a stable compounder anchored by HZZO's expanding reimbursement commitment to chronic disease management and oncology biologics. Demographic aging and EU regulatory alignment sustain predictable demand trajectories across the analysis window.
For Market Incumbents: Extend serialization compliance investments into contract manufacturing services for regional neighbors still adapting to EU Falsified Medicines Directive requirements. Deepen backward integration into API sourcing through strategic partnerships with Indian manufacturers holding established BIS and CDSCO certification pathways. HALMED's tightening pharmacovigilance timelines threaten non-compliant competitors, creating consolidation leverage for integrated domestic players with EU-equivalent quality management systems. For New Entrants and Emerging Players: EU Green Deal pharmaceutical sustainability framework in Croatia opens a window for carbon-footprint-certified packaging suppliers and circular economy logistics providers. Target Dalmatia and Slavonia regional hospital networks outside the Zagreb-Split corridor, where specialty pharmacy services remain underserved for chronic disease management programs. Home care infusion networks for outpatient biologic administration represent the most penetrable channel, with patient preference shifts creating demand for certified domestic administration services. For Investors and Strategic Acquirers: Roll-up economics work for mid-sized domestic formulators with HALMED manufacturing authorizations because hospital procurement centralization favors scaled suppliers with dedicated account management capabilities. Five-to-ten year viability hinges on positioning for biologics cold-chain infrastructure rather than generic oral solid exposure. Watch HZZO HTA methodology evolution as the inflection signal determining whether novel therapy commercialization accelerates or remains constrained by biannual reimbursement list rigidity.| Strategic Initiative | Industry Significance |
|---|---|
| EU Falsified Medicines Directive Serialization Compliance | HALMED-aligned track-and-trace systems enable contract manufacturing capture from regional neighbors. |
| Biologics Cold-Chain Infrastructure Expansion | Split and Osijek distribution hubs secure temperature-controlled reach to underserved regional networks. |
| Green Manufacturing Certification Investment | EU Green Deal procurement criteria favor domestic producers with localized, low-carbon supply chains. |
| Home Care Infusion Network Development | Post-pandemic patient preference shifts create certified administration capacity outside hospital settings. |
| API Sourcing Partnership Structuring | BIS and CDSCO equivalency pathways with Indian suppliers reduce approval delays for critical inputs. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers grounded this analysis in operational reality across Croatian pharmaceutical networks. Secondary validation drew from EMA submissions, HALMED pharmacovigilance reports, ClinicalTrials.gov entries, and HZZO reimbursement list documentation. Bottom-up patient population modeling and top-down healthcare expenditure triangulation converged on segment-level demand estimates.
Bottom-up volume builds by therapy area, dosage form, and administration route were cross-checked against top-down healthcare budget allocation patterns across the projection horizon. Segmentation dimensions included treatment line positioning, patient population severity tiers, regional regulatory clusters, and cold-chain infrastructure requirements. CAGRs were derived from demographic trend extrapolation, reimbursement list expansion trajectories, and biologics penetration curve analysis in comparable EU markets.
Revisions become necessary when HALMED regulatory enforcement intensity shifts, HZZO HTA methodology undergoes structural reform, or API import equivalency pathways with Indian authorities experience procedural disruption. Stakeholders should weight assumptions against their own operating context and monitor procurement centralization velocity in university hospital networks as a demand concentration signal.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Inhaled Antibiotics Market
Pharmaceuticals
Tuberculosis Vaccine Treatment Market
Pharmaceuticals
Diphtheria Tetanus Pertussis Vaccine Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Global Monoclonal Antibody Therapeutics Market
Pharmaceuticals
Focal Segmental Glomerulosclerosis (FSGS) Therapeutics Market
Pharmaceuticals
Tramadol Drug Market
Pharmaceuticals
Global Ovulation Inducing Drugs Market
Pharmaceuticals
Short-Acting Insulin Market
Pharmaceuticals
Sweden Pharmaceutical Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Herbal Drugs Market
Pharmaceuticals
Cholinesterase Inhibitors Market
Pharmaceuticals
North America Sodium-Dependent Glucose Co-Transporter 2 (Sglt2) Market
Pharmaceuticals
Selective Serotonin Reuptake Inhibitors Market