
 Agricultural Seeder Market | 2026-2036
Agricultural Seeder Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Seeder Market Outlook
Commercial growers is unwinding the traditional farmer-dominant procurement pattern in agricultural seeders. Deere and Company leverages its precision agriculture ecosystem to control high-margin technology bundles. AGCO Corporation anchors its position through Fendt and Challenger brand specialization in large-scale air seeder systems. CNH Industrial competes via Case IH and New Holland channel density across North American dealer networks.
An agricultural seeder is a mechanized planting device engineered to meter seeds at controlled depths and spacing, typically operating with disc openers, press wheels, and seed tubes calibrated to soil conditions and crop specifications. Its primary commercial purpose is to optimize germination rates, reduce seed waste, and enable uniform crop establishment across extensive acreage. Air seeders dominate North American prairie operations where pneumatic delivery handles high-volume wheat and canola programs, while precision seeders capture margin pools in specialty vegetable and high-value row-crop segments where singulation accuracy commands price premiums. Mechanical seeders retain volume leadership in developing agricultural economies where capital constraints favor simpler, repairable platforms over electronically controlled alternatives.
The EPA enforces Clean Water Act provisions that incentivize no-till seeding practices to reduce soil erosion and nutrient runoff into watersheds. The EU Green Deal's Farm to Fork strategy imposes pesticide reduction targets that drive demand for precision seeders enabling targeted input application. ISO 7256 standards govern seeding uniformity testing, creating compliance barriers for equipment entering regulated markets. Stakeholders must monitor how carbon credit frameworks and soil carbon measurement protocols reshape equipment specifications and financing structures.
Market Dynamics
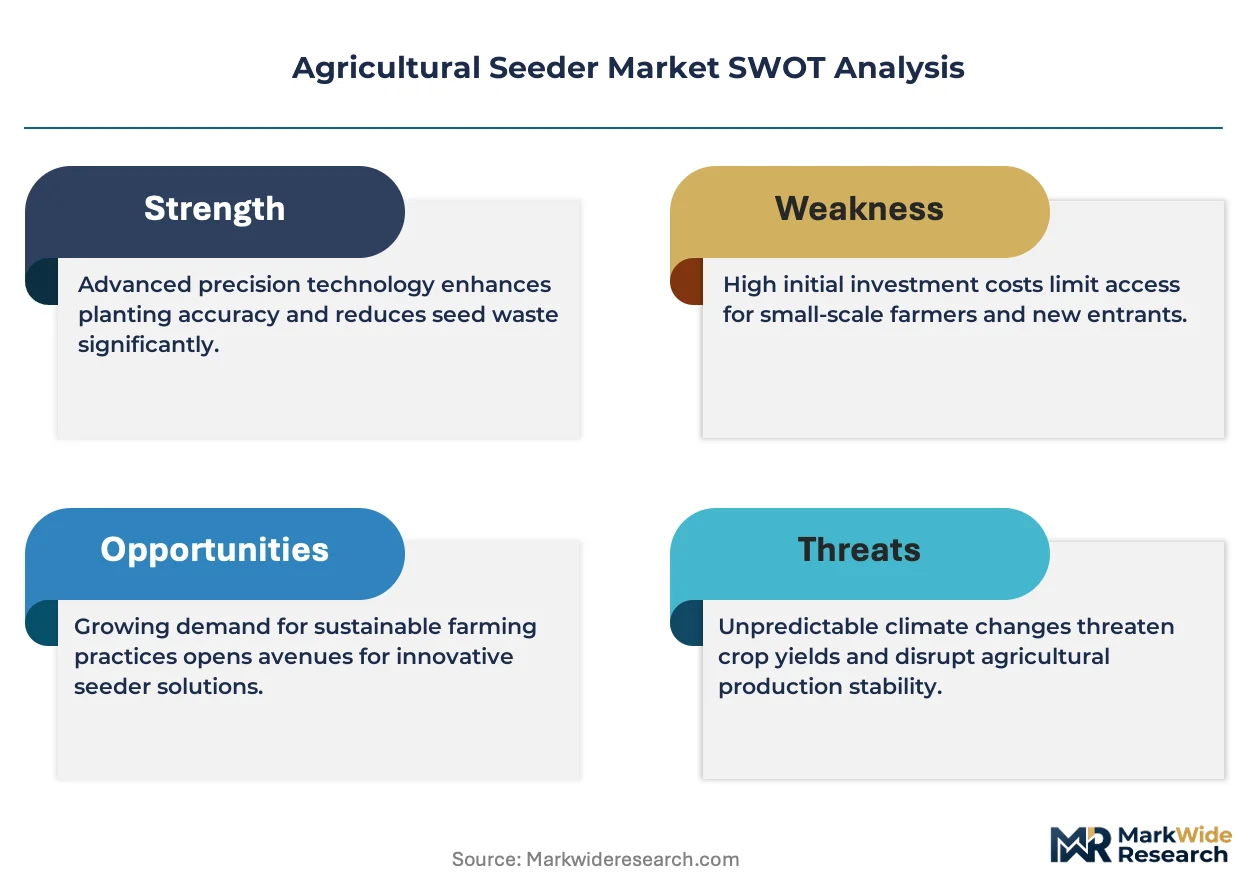
Precision agriculture mandates from the EU Green Deal and EPA water-quality frameworks are compressing adoption cycles for variable-rate seeding and no-till equipment, forcing capital reallocation across farm operations and dealer networks.
Growth Catalysts
- EU Green Deal Farm to Fork mandates:Pesticide reduction targets in the European Union accelerate demand for precision seeders that enable targeted input placement and minimize chemical overlap.
- Carbon credit frameworks:Soil carbon measurement protocols in North America and Australia create financing structures that reward no-till seeding practices with verified carbon sequestration.
- Black Sea wheat zone expansion:Large-scale mechanization programs across Ukraine and Russia displace manual broadcasting with air seeder systems calibrated for high-volume cereal establishment.
Market Restraints
- Steel and aluminum input volatility:Disc opener assemblies and frame structures face margin compression from commodity metal price swings that manufacturers cannot fully pass to price-sensitive buyers.
- Electronic component supply concentration:GPS modules, hydraulic sensors, and ISOBUS controllers concentrate sourcing from East Asian semiconductor fabricators, exposing delivery timelines to geopolitical friction.
- ISO 7256 compliance barriers:Seeding uniformity testing standards create certification friction for mechanical seeder platforms entering regulated European and North American markets.
Strategic Opportunities
- Sub-Saharan Africa mechanization gap:Capital-constrained smallholders in Nigeria and Ethiopia present volume potential for simplified, repairable mechanical seeders with local parts fabrication networks.
- Autonomous tractor convergence:Integration of RTK-guided seeders with unmanned power units enables overnight planting windows and labor cost reduction for US Corn Belt operators.
- EPA water-quality incentives:Clean Water Act provisions that reward no-till adoption create equipment financing subsidies through USDA conservation programs.
Industry Challenges
- Precision agriculture technician scarcity:Dealer service departments struggle to recruit personnel capable of calibrating variable-rate hydraulic systems and troubleshooting ISOBUS communication faults.
- Legacy fleet integration complexity:Retrofitting ten-year-old mechanical seeders with GPS guidance and section control requires adapter kits that compromise seeding accuracy and void remaining warranty coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Seeder Market |
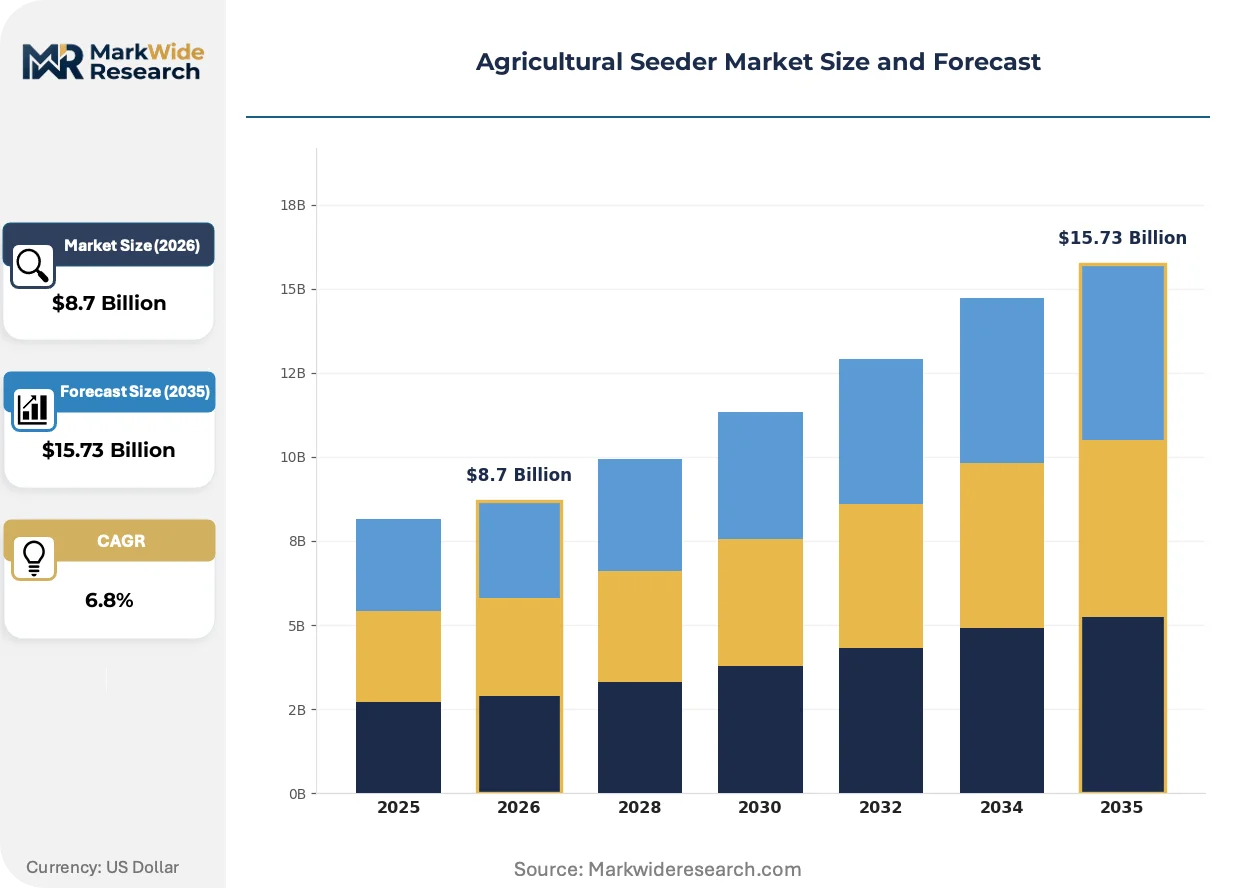
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Seeders, Air Seeders, Precision Seeders, Broadcast Seeders Application: Crops, Vegetables, Fruits, Legumes End User: Farmers, Agricultural Cooperatives, Commercial Growers, Research Institutions Distribution Channel: Online Retail, Direct Sales, Distributors, Resellers |
| Companies Covered | Deere and Company, AGCO Corporation, CNH Industrial, Great Plains Manufacturing, Salford Group, Bourgault Industries, John Deere, Kinze Manufacturing, Case IH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Seeder Market Strategic Shifts
Active reshaping in agricultural seeders centers on three vectors: electronic control architectures fragmenting equipment categories, regulatory frameworks compressing practice windows, and buyer consolidation rewiring distribution economics.
Variable-rate seeding technology is fragmenting the traditional mechanical-electronic divide in equipment procurement. Large-scale growers in Brazil's Mato Grosso and the US Corn Belt now specify hydraulic metering with real-time prescription adjustment, compressing demand for fixed-rate mechanical alternatives. This capability split is enabling tiered pricing structures that separate precision-enabled platforms from basic air seeders.
EPA Clean Water Act enforcement is tightening nutrient runoff thresholds across Chesapeake Bay and Mississippi River watersheds. Industrial consequence falls on corn-soy operations where conventional tillage faces practice restrictions. The most affected segment—Illinois and Iowa row-crop farmers—responds by specifying no-till drill configurations with residue management attachments that satisfy conservation compliance.
Consolidation among commercial growing operations is compressing dealer relationship models. Multi-thousand-acre enterprises in Saskatchewan and Kansas now negotiate direct manufacturer contracts that bypass traditional distributor markups. This channel displacement is most visible in air seeder procurement for wheat-canola rotations, where volume concentration enables specification of custom toolbar widths and pneumatic delivery configurations unavailable through standard dealer inventory.
Agricultural Seeder Market Segmentation
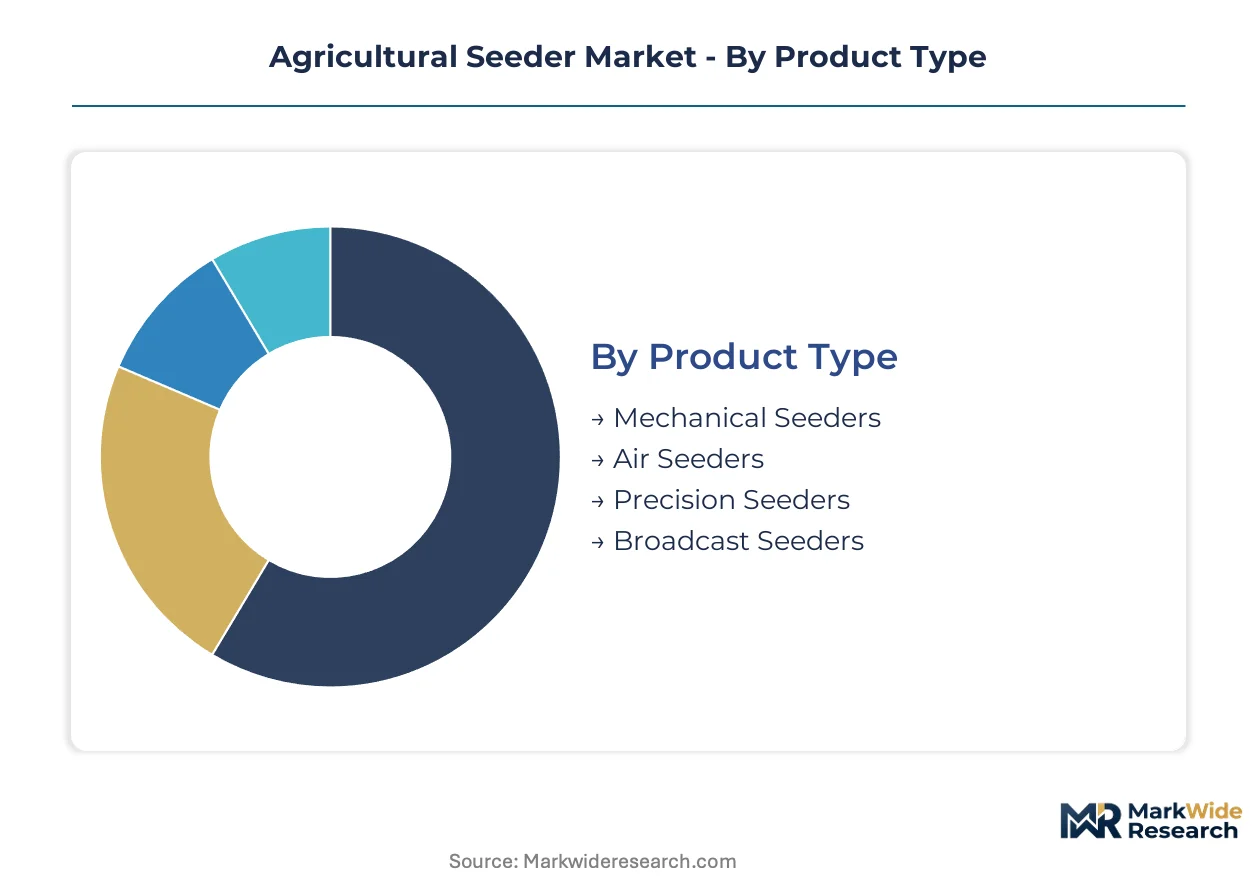
Equipment segmentation in agricultural seeders determines capital allocation patterns across farm operations. Technology tiers separate precision-capable platforms from mechanical alternatives, while end-user consolidation is rewiring procurement channels toward direct manufacturer relationships.
Product Type:
Margin pools concentrate in pneumatic and electronically controlled platforms where prescription agriculture commands price premiums over fixed-rate mechanical systems.
- Air Seeders:Pneumatic delivery systems meter seed through centralized tanks into individual row units via pressurized air streams. Demand clusters in Saskatchewan wheat-canola rotations and Kansas dryland grain operations where high-volume throughput justifies capital intensity. Carbon credit frameworks rewarding no-till establishment accelerate specification of residue-handling configurations.
- Precision Seeders:Electronic singulation systems achieve sub-inch spacing accuracy through vacuum or finger-pickup metering mechanisms. Vegetable operations in California's Salinas Valley and Florida's winter vegetable belt specify these platforms where seed cost density and germination uniformity determine profitability. EU Green Deal pesticide reduction mandates drive section-control and variable-rate hydraulic specifications.
- Mechanical Seeders:Gravity-fed fluted-wheel or plate-type metering dominates smallholder procurement in Ethiopia and Nigeria where repairability outweighs precision requirements.
- Broadcast Seeders:Centrifugal spinner or pneumatic boom systems distribute seed without individual row placement, retaining volume in pasture renovation and cover-crop programs across Australian mixed-farming operations.
Air seeders hold installed capacity across North American prairie grain systems. Precision seeders are rotating up the share rankings as specialty crop acreage expands and regulatory compliance tightens input application windows.
Application:
Volume distribution tracks crop value density, with high-input row crops justifying precision equipment premiums over extensive cereal programs.
- Crops:Corn, soybean, and wheat establishment commands the majority of seeder deployment by acreage. Illinois and Iowa operators specify no-till drills with residue managers to satisfy EPA Clean Water Act compliance in Mississippi River watersheds. Variable-rate prescription compatibility separates premium platform specifications from base mechanical configurations.
- Vegetables:Lettuce, tomato, and brassica transplanting requires precision singulation where seed cost and plant spacing uniformity directly impact harvestable yield. California's Central Valley and Spain's Almería greenhouse complexes drive demand for multi-row precision planters with automated depth control.
- Fruits:Orchard and vineyard establishment utilizes specialized deep-placement drills for rootstock and cover-crop interseeding, concentrated in Washington apple regions and Italian table-grape zones.
- Legumes:Soybean and pulse crop planting overlaps with grain crop equipment specifications, though inoculant application attachments create specialized demand in Brazil's Cerrado expansion zones.
Crop applications retain volume leadership across global grain belts. Vegetable planting is gaining share fastest as protected agriculture expansion and labor cost pressures accelerate mechanization in high-value fresh produce.
End User:
Procurement concentration is shifting from fragmented farmer networks toward consolidated commercial operations with direct manufacturer negotiation leverage.
- Commercial Growers:Multi-thousand-acre enterprises in Mato Grosso and Saskatchewan bypass dealer networks for factory-direct air seeder procurement with custom toolbar specifications. Volume concentration enables specification of pneumatic configurations unavailable through standard inventory.
- Farmers:Individual owner-operators in the US Corn Belt and Black Sea wheat zone remain the volume base for mid-tier mechanical and entry-level electronic seeders, though cooperative purchasing aggregates negotiation position.
- Agricultural Cooperatives:Shared-equipment programs in France's cereal regions and Ukraine's oblast-level associations pool capital for high-specification precision platforms with ISOBUS compatibility.
- Research Institutions:University and government trial stations in Brazil's Embrapa network and USDA research locations specify plot-scale precision seeders with data-logging capabilities for variety testing protocols.
Farmers retain installed base majority across developing agricultural economies. Commercial growers are climbing the fastest in new equipment procurement share as consolidation concentrates acreage under professional management.
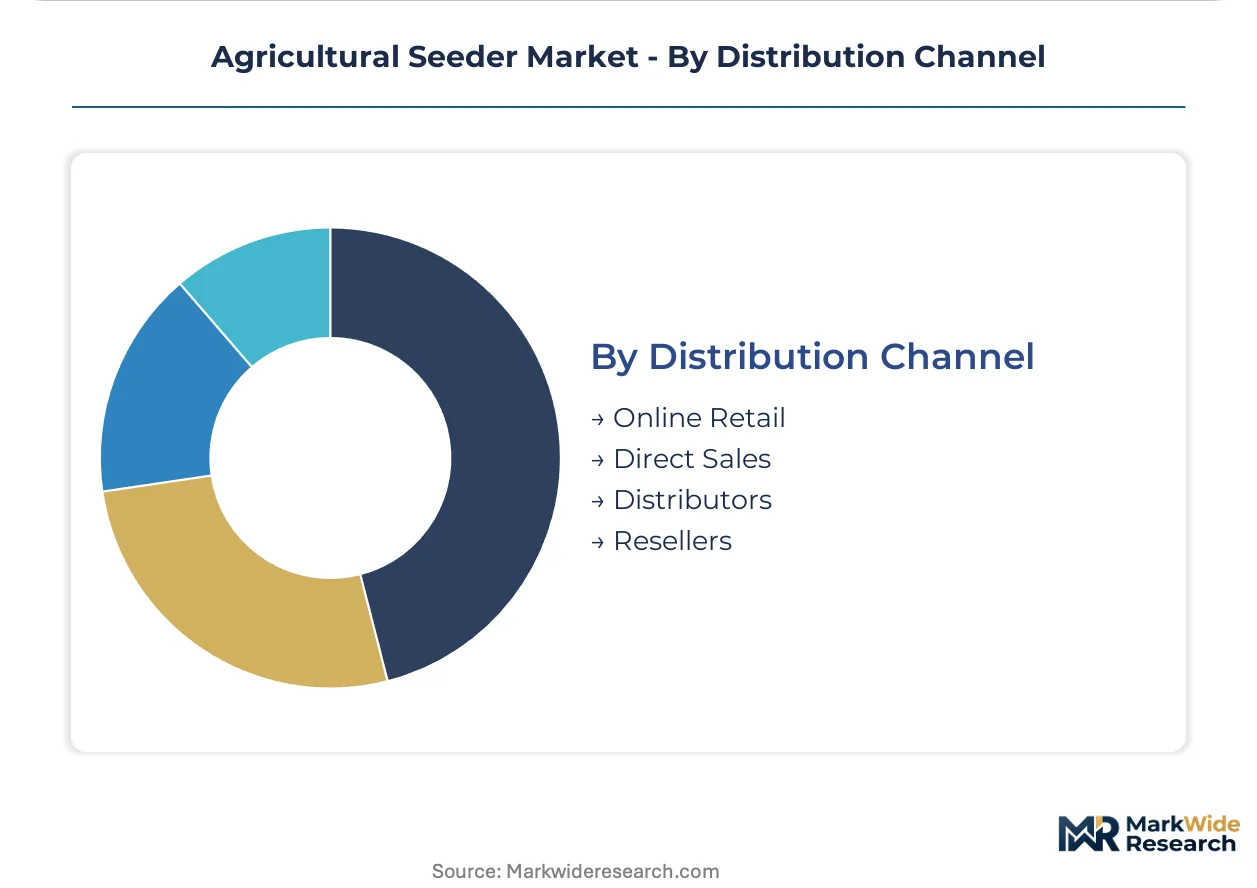
Distribution Channel:
Channel economics fragment between high-touch dealer service requirements for precision electronics and direct procurement efficiency for standardized mechanical platforms.
- Direct Sales:Manufacturer-to-grower contracts eliminate distributor markups for large-volume air seeder procurement. Deere and AGCO field organizations negotiate specification packages with Saskatchewan wheat cooperatives and Brazilian soybean operators above defined acreage thresholds.
- Distributors:Authorized dealer networks remain essential for precision seeder calibration, warranty service, and ISOBUS troubleshooting. EPA and EU Green Deal compliance documentation flows through these channels for regulated market entry.
- Resellers:Independent equipment traders handle used mechanical seeder turnover in Eastern European and Central Asian markets where capital constraints favor depreciated platforms.
- Online Retail:E-commerce penetration concentrates in small-scale broadcast seeder and attachment components, with limited traction for capital-intensive primary planting equipment requiring demonstration and service support.
Distributors hold relationship infrastructure for precision agriculture service dependencies. Direct sales are rotating up the share rankings as commercial grower consolidation compresses traditional dealer economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River navigation system underwrites the United States' dominance in agricultural seeder deployment, moving soybeans and corn from Illinois and Iowa to export terminals at New Orleans.
United States
Illinois and Iowa operators specify no-till drills with residue managers to satisfy EPA Clean Water Act compliance in Mississippi River watersheds. The USDA conservation programs subsidize equipment financing for verified carbon sequestration practices. Deere and Company leverages its precision agriculture ecosystem across the Corn Belt, bundling RTK guidance with variable-rate hydraulic systems.
Brazil
Mato Grosso soybean frontiers drive demand for high-volume air seeders calibrated for Cerrado expansion zones. ANVISA pesticide regulations align with EU Green Deal standards, accelerating precision seeder adoption for targeted input placement. Embrapa research stations in Brasília validate plot-scale precision platforms for variety testing protocols.
Germany
Fendt and Challenger brand specialization anchors AGCO Corporation's position in large-scale air seeder systems across Lower Saxony and Bavaria cereal regions. The EU Green Deal Farm to Fork strategy imposes pesticide reduction targets that drive section-control specifications. Cooperative purchasing in Schleswig-Holstein aggregates negotiation position for ISOBUS-compatible platforms.
Ukraine
Black Sea wheat zones in Kharkiv and Odesa oblasts displace manual broadcasting with air seeder systems for high-volume cereal establishment. Oblast-level agricultural associations pool capital for precision platforms despite import logistics friction. The Danube River grain corridor infrastructure supports equipment delivery timelines to southern port zones.
India
Punjab and Haryana smallholders present volume potential for simplified mechanical seeders with local parts fabrication networks. The BIS certification framework creates compliance barriers for electronically controlled alternatives. Kinze Manufacturing and regional fabricators compete across the Indo-Gangetic Plain where capital constraints favor repairable platforms.
Agricultural Seeder Market Competitive Environment
Listed leaders compete with private specialists across technology tiering and channel density. The vendor base concentrates around three structural positions: precision ecosystem integrators, air seeder volume manufacturers, and mechanical platform fabricators serving capital-constrained geographies. Two dominant competitive moves reshape positioning—direct sales contracts that bypass distributor markups for large-scale growers, and strategic partnerships that embed ISOBUS compatibility across tractor-seeder combinations.
Within the precision ecosystem tier, Deere and Company and AGCO Corporation exemplify integrated technology bundling. CNH Industrial occupies a position in channel density across North American dealer networks. Among private specialists, Bourgault Industries and Salford Group represent Canadian fabrication expertise in pneumatic delivery configurations. Kinze Manufacturing anchors mid-tier mechanical and entry-level electronic positioning for price-sensitive procurement.
| Leading Market Players |
|---|
| Deere and Company |
| AGCO Corporation |
| CNH Industrial |
| Great Plains Manufacturing |
| Salford Group |
| Bourgault Industries |
| John Deere |
| Kinze Manufacturing |
| Case IH |
| Others |
Value Chain & Pricing Dynamics
Pneumatic delivery systems displacing gravity-fed mechanical alternatives across North American prairie operations simultaneously concentrate component sourcing in East Asian semiconductor hubs and compress margin pools for repairable platforms in capital-constrained markets. Steel-to-aluminum frame substitution in disc opener assemblies redirects procurement toward Chinese and Russian primary metal suppliers while amplifying exposure to commodity price volatility that manufacturers cannot fully pass to price-sensitive smallholders.
Pricing Analysis
Volume-discount tiering structures separate precision-enabled platforms with ISOBUS compatibility and variable-rate hydraulics from base mechanical configurations. Price differentiation rests on certification grade for EPA Clean Water Act compliance and after-sales service bundling for calibration support. Pricing pressure stems from steel and aluminum input volatility in disc opener manufacturing. Commercial growers in Saskatchewan and Mato Grosso exhibit lowest price sensitivity due to carbon credit financing structures, while Ethiopian and Nigerian smallholders face acute capital constraints favoring depreciated mechanical alternatives.
Supply Chain Analysis
Inventory-strategy preferences favor just-in-time component flows for GPS modules and hydraulic sensors from Taiwan and South Korea, while finished equipment manufacturers maintain strategic stockpiles of steel frame structures sourced from China and India. Raw material dependencies center on high-grade steel for disc openers, aluminum for toolbar assemblies, and semiconductor components for ISOBUS controllers. Supply chain risk concentrates in single-source vulnerability for RTK guidance systems. Distribution runs through authorized dealer networks for precision platform service dependencies, with direct manufacturer contracts bypassing traditional markups for large-scale air seeder procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection in agricultural seeders hinges on ISOBUS interoperability standardization that collapses proprietary technology bundling and forces ecosystem openness across tractor-seeder combinations.
For Market Incumbents: Fortify precision agriculture service infrastructure by embedding proprietary telemetry systems that lock in recurring calibration revenue streams. Deepen backward integration into hydraulic sensor manufacturing to offset East Asian semiconductor supply concentration. Counter direct sales channel displacement by commercial growers through exclusive residue-management attachment specifications unavailable through factory-direct procurement. For New Entrants and Emerging Players: Certification fast-track through EPA conservation program eligibility creates immediate access to USDA equipment financing subsidies for no-till drill configurations. White-space concentration sits in simplified mechanical seeders with local parts fabrication networks for Nigerian and Ethiopian smallholders. Penetrate via cooperative purchasing aggregation models that pool capital for mid-tier electronic platforms across Ukraine's oblast-level agricultural associations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Canadian pneumatic specialists possessing established Black Sea wheat zone distribution infrastructure. Long-term viability over a multi-year horizon hinges on carbon credit framework durability and soil carbon measurement protocol standardization. Acquisition target archetypes include ISOBUS-compatible precision platform fabricators with embedded software capabilities. Monitor EPA Clean Water Act enforcement intensity across Mississippi River watersheds as inflection indicator for no-till equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISOBUS Compatibility Certification | Ensures seamless tractor-seeder integration across Deere, AGCO, and CNH Industrial equipment ecosystems. |
| Carbon Credit Financing Partnership | Links no-till seeder procurement to USDA conservation program subsidies for verified soil carbon sequestration. |
| Regional Parts Fabrication Network | Enables mechanical seeder repairability for Ethiopian and Nigerian smallholders facing capital constraints. |
| Direct Manufacturer Contracting | Bypasses distributor markups for Saskatchewan wheat cooperatives and Brazilian soybean operators above acreage thresholds. |
| Precision Agriculture Technician Training | Addresses dealer service department scarcity in variable-rate hydraulic calibration and ISOBUS troubleshooting. |
Study Parameters
Initial hypotheses were tested against primary input from precision agriculture service technicians, OEM procurement managers at Deere and AGCO, dealer network operations directors, and conservation program administrators at USDA NRCS, then refined through secondary validation. Secondary data sources encompassed EPA Clean Water Act enforcement records, EU Green Deal Farm to Fork strategy documents, ISO 7256 seeding uniformity testing standards, and customs trade data for agricultural machinery imports. Bottom-up equipment deployment estimates across Illinois, Iowa, Mato Grosso, and Kharkiv oblast were triangulated against top-down market sizing from manufacturer production disclosures.
Variance-decomposition across the projection horizon isolates contribution from precision technology adoption rates, regulatory compliance cost pass-through, and commercial grower consolidation velocity. Segmentation dimensions modeled include equipment technology tier, crop application intensity, end-user scale category, and regional regulatory framework cluster. CAGRs were derived from equipment replacement cycle analysis and acreage expansion projections. Industry-specific forecast inputs incorporate EPA water-quality incentive program enrollment trajectories and Black Sea wheat zone mechanization program funding allocations.
Underlying assumptions cover carbon credit framework durability and East Asian semiconductor supply continuity, with deviation risk concentrated in geopolitical friction affecting GPS module delivery timelines. Forecasts reflect these assumptions with sensitivity bands for commodity metal price volatility. Revision becomes warranted when EPA Clean Water Act enforcement intensity or EU Green Deal pesticide reduction mandates cross implementation thresholds that accelerate equipment replacement cycles beyond baseline projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Global Sunflower Market
Seeds
Tallow Tree Seed Market
Seeds
Global Sorghum Seed Market
Seeds
Global Maize Seed Market
Seeds
Flower Seed Market
Seeds
Tomato Seed Market
Seeds
Asia-Pacific Forage Seed Market
Seeds
Faba Beans Market
Seeds
Chia Seeds Market
Seeds
Global Alfalfa Seed Market
Seeds
Native Grass Seeds Market
Seeds
North America Alfalfa Seed Market
Seeds
Organic Seed Market
Seeds
Genetically Modified Seeds Market
Seeds
Global Fruit and Vegetable Seeds Market
Seeds
Americas Seeds Market