
 Global Acephate Market | 2026-2036
Global Acephate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acephate Market Analysis
Consolidation among large-scale agricultural producers in Brazil and India is expanding the addressable base for acephate suppliers serving contract farming operations. FMC Corporation leverages its Latin American distribution infrastructure to sustain volume commitments with soybean cooperatives. Bayer Crop Science AG anchors its position through backward integration into active ingredient synthesis. UPL Limited competes on cost structure in South Asian markets with generic acephate formulations.
Acephate is an organophosphate insecticide formulated as a soluble powder or emulsifiable concentrate containing 75-97% active ingredient, manufactured through phosphorylation of methamidophos to inhibit acetylcholinesterase in target pests. It functions primarily as a systemic and contact treatment against aphids, leaf miners, and thrips in row crop and horticultural systems. Agricultural insecticides occupy the dominant value share as growers prioritize broad-spectrum pest control in high-acreage soybean and cotton programs. The ornamental plants application segment generates premium pricing due to lower volume tolerance for phytotoxicity and stricter residue protocols in greenhouse environments.
The US EPA re-registration review of organophosphates shapes product label restrictions and buffer zone requirements that determine field application economics for acephate users. Brazil's ANVISA and India's CEA enforce maximum residue limits that dictate export market access for treated commodities. China's MEE oversight of phosphorus chemical production affects upstream raw material availability and environmental compliance costs. Stakeholders must monitor regulatory divergence between jurisdictions with maintained registrations and those pursuing accelerated phase-outs.
Market Dynamics
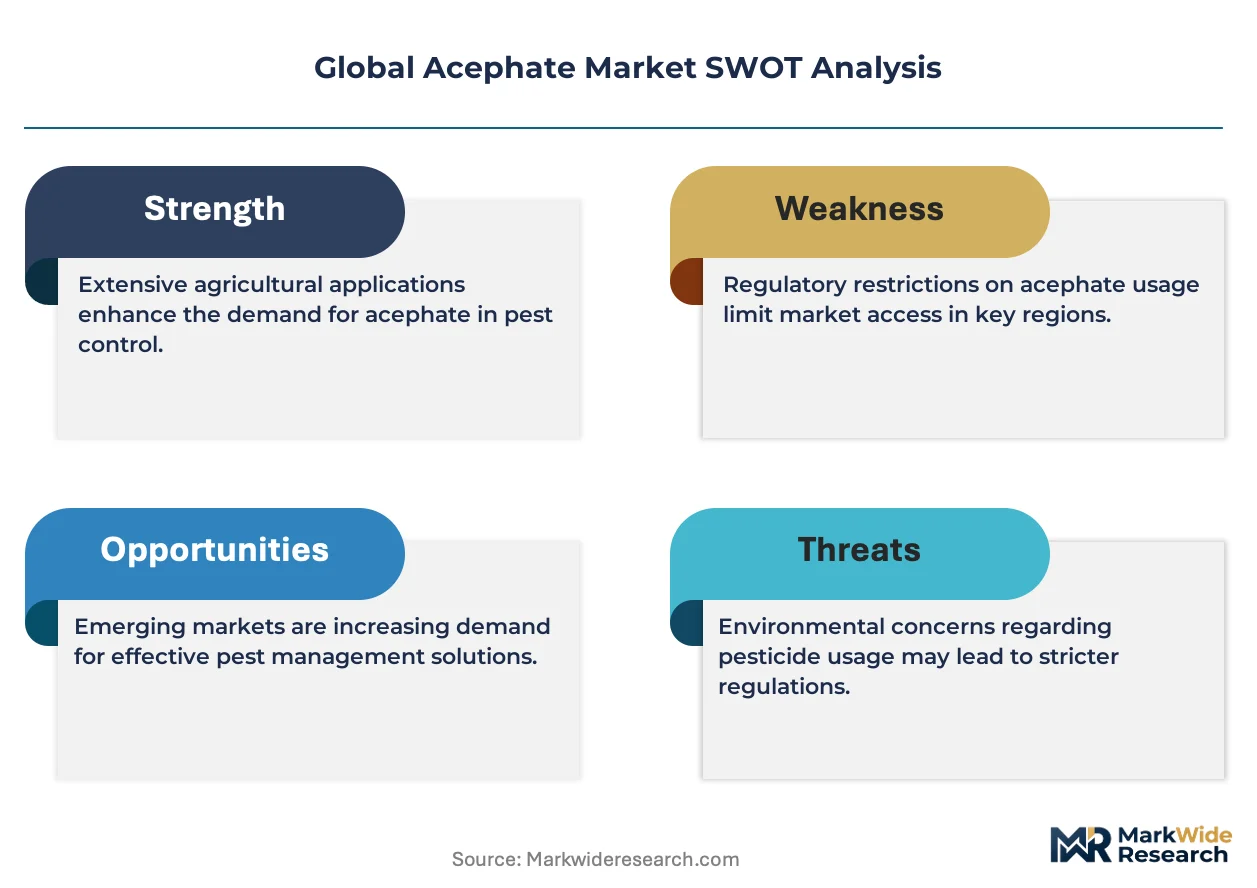
Regulatory divergence between jurisdictions maintaining organophosphate registrations and those accelerating phase-outs is fragmenting supply chains and forcing suppliers to maintain parallel product portfolios. This structural tension compresses margins while expanding compliance overhead across export-oriented production zones.
Growth Catalysts
- Neonicotinoid withdrawal under EFSA guidance:The European Union's phased elimination of seed treatments redirects row crop producers toward acephate as a resistance management alternative in soybean and cotton systems.
- Piercing-sucking pest pressure:Aphid and thrips infestations in Brazil's Mato Grosso state and India's Maharashtra region sustain demand for systemic organophosphate chemistries with contact and translaminar activity.
- Contract farming consolidation:Large-scale agricultural producers in Brazil and India are standardizing input procurement, creating volume commitments that stabilize supplier offtake.
Market Restraints
- Phosphorus chemical feedstock concentration:Upstream methamidophos and phosphorylation reagents concentrate in China's Yangtze River Delta, exposing formulations to environmental compliance cost volatility under MEE oversight.
- Acetylcholinesterase toxicity classification:Worker exposure restrictions and buffer zone mandates from the US EPA re-registration review limit application windows and field economics.
- Biological insecticide substitution:Bacillus thuringiensis and pheromone-based alternatives gain share in greenhouse ornamental segments with stricter residue protocols.
Strategic Opportunities
- Export-oriented production zones:Brazil's Cerrado expansion and India's Gujarat cotton belt remain underpenetrated for high-concentration soluble powder formulations.
- Integrated pest management bundling:Pairing acephate with selective biologicals creates compliance-aligned portfolios for EU-destined commodity shipments.
- Drone application infrastructure:Aerial spraying platforms in Australian broadacre operations and Ukrainian sunflower regions enable precision dosing that reduces buffer zone conflicts.
Industry Challenges
- Toxicological registration dossier compilation:Chronic exposure studies and environmental fate data requirements strain regulatory affairs capacity across multiple jurisdictions simultaneously.
- Residue monitoring system interoperability:Divergent maximum residue limit protocols between ANVISA, CEA, and EPA create certification complexity for multi-destination exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acephate Market |
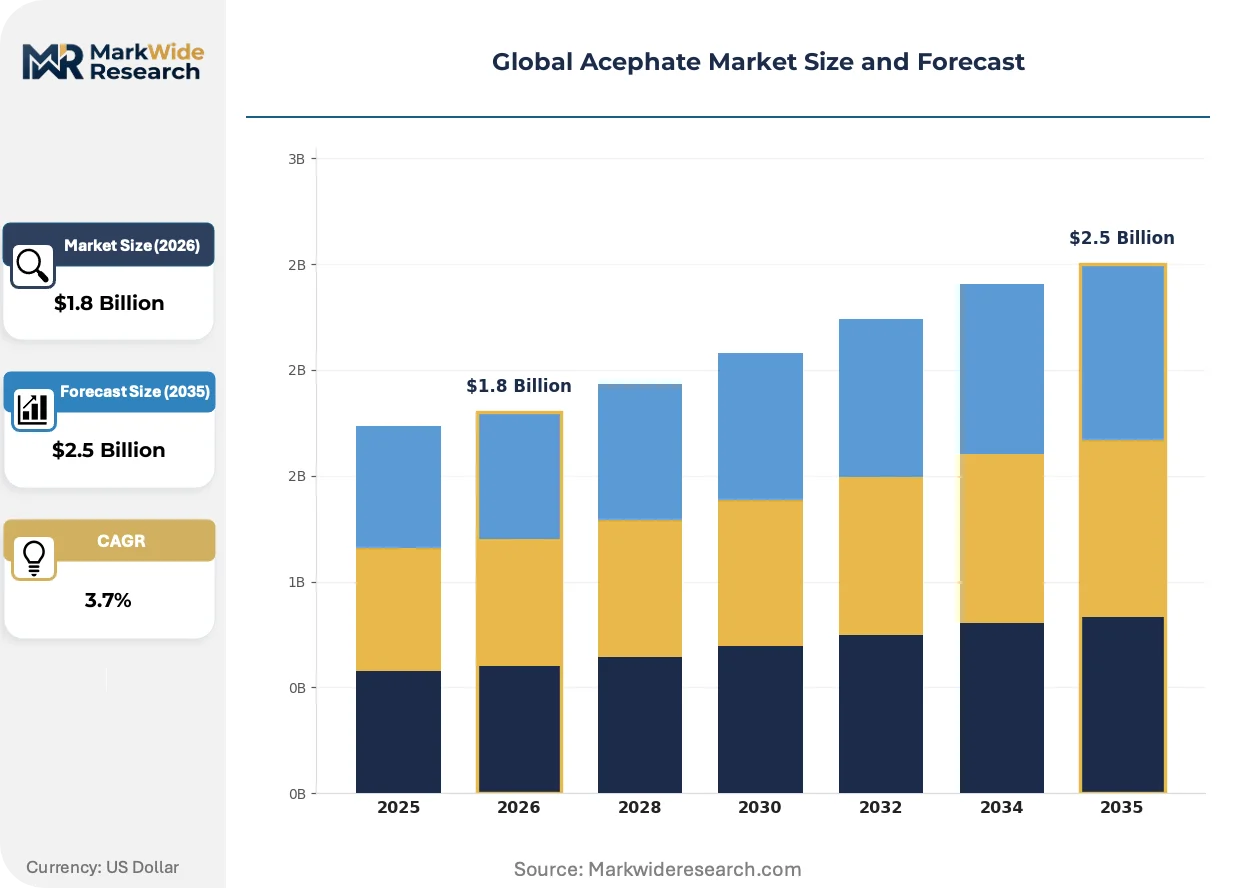
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agricultural Insecticides, Pesticides, Insect Growth Regulators, Miticides Application: Crops, Vegetables, Fruits, Ornamental Plants End User: Agricultural Producers, Farm Managers, Pest Control Services, Distributors Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Dealers |
| Companies Covered | Drexel Chemical Company, FMC Corporation, Syngenta, Corteva Inc., Nufarm Limited, ADAMA Limited, UPL Limited, Bayer Crop Science AG, Sinon Chemical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acephate Market Emerging Trajectories
Formulation chemistry and application technology are converging to extend acephate's utility window amid tightening exposure standards. These developments prioritize operator safety, residue mitigation, and compatibility with precision agriculture infrastructure.
Microencapsulation technology is integrating organophosphate actives into polymer matrices that control release rates and reduce dermal exposure during handling. Large-scale cotton cooperatives in Australia's Murray-Darling basin are piloting these formulations for aerial application. The technology is integrating worker safety protocols with operational throughput requirements in mechanized row crop systems.
REACH authorization procedures for organophosphate intermediates are tightening supply chain documentation requirements for EU-destined commodities. Formulators must now maintain substance volume tracking and exposure scenario modeling across downstream uses. Specialty crop exporters in Morocco and Kenya are restructuring supplier qualification protocols to maintain supermarket compliance.
Cooperative procurement consortia in Brazil's Matopiba region are consolidating insecticide purchasing through shared warehousing and volume tendering. These aggregators displace distributor margins while demanding extended payment terms and technical support bundling. The consolidation is most visible in soybean seed treatment and foliar spray programs across the agricultural frontier states.
Global Acephate Market Segmentation
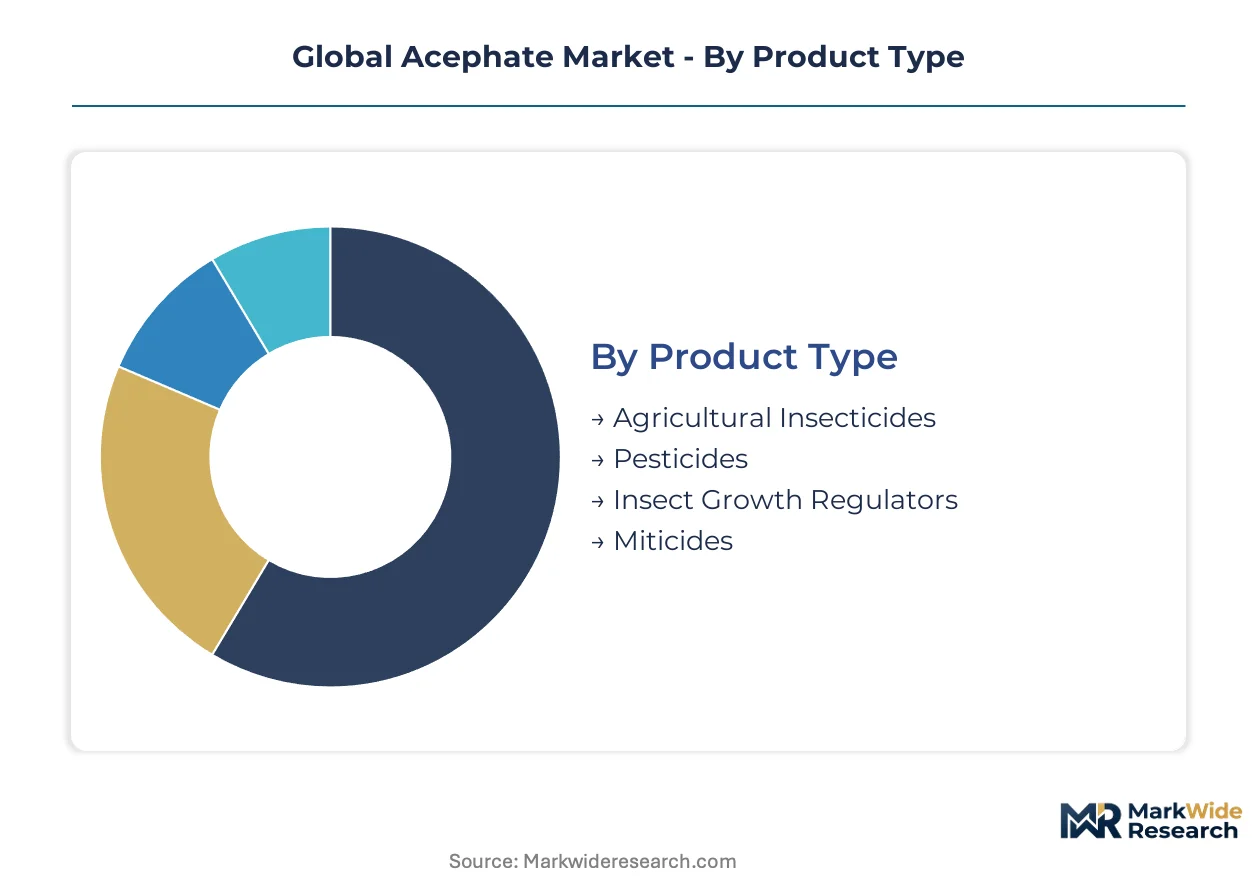
Acephate suppliers calibrate formulation concentration, application protocols, and channel economics to distinct buyer workflows across agricultural and ornamental systems. Segmentation discipline separates volume-driven row crop operators from residue-sensitive greenhouse producers with divergent procurement patterns.
Product Type:
Agricultural buyers prioritize efficacy-to-cost ratios and tank-mix compatibility, while ornamental and specialty crop operators emphasize worker safety profiles and pre-harvest interval flexibility.
- Agricultural Insecticides:Formulated as 75-97% soluble powder or emulsifiable concentrate for broad-spectrum control of aphids, leaf miners, and thrips in high-acreage soybean and cotton programs. Brazil's Mato Grosso state and India's Maharashtra region concentrate procurement through cooperative procurement consortia seeking volume pricing on foliar spray programs.
- Pesticides:Multi-active blends combining acephate with pyrethroids or neonicotinoids for resistance management in intensive monoculture systems. Demand clusters in Brazil's Cerrado expansion zones where piercing-sucking pest pressure necessitates rotational chemistry protocols.
- Insect Growth Regulators:Juvenile hormone analogs and chitin synthesis inhibitors paired with acephate for integrated pest management bundling in EU-destined export commodities.
- Miticides:Spider mite-specific formulations targeting two-spotted mite infestations in greenhouse tomato and strawberry operations under ANVISA and CEA residue protocols.
Agricultural Insecticides leads volumes today; Miticides is gaining share fastest.
Application:
Application segmentation tracks residue tolerance thresholds and pre-harvest interval requirements that determine label economics across commodity export destinations.
- Crops:Soybean, cotton, and maize systems in Brazil's Mato Grosso and Goiás states represent the dominant volume anchor. Row crop producers leverage acephate's systemic and contact activity against aphid vectors of viral diseases, with application timing synchronized to growth stages that minimize buffer zone conflicts under EPA re-registration constraints.
- Vegetables:Brassica and solanaceous crops in India's Gujarat and Karnataka regions require frequent reapplications due to compressed pre-harvest intervals, sustaining demand for high-concentration soluble powder formulations that reduce per-hectare handling costs.
- Fruits:Citrus and grape programs in São Paulo state and Maharashtra face stringent EU EFSA maximum residue limits that favor reduced-rate applications with extended pre-harvest intervals.
- Ornamental Plants:Greenhouse rose and chrysanthemum producers in Kenya's Naivasha cluster and Colombia's Bogotá plateau command premium pricing for microencapsulated formulations with lower dermal exposure risk and phytotoxicity margins.
Crops dominates current offtake; Ornamental Plants expands most quickly.
End User:
End user segmentation reflects scale-driven procurement centralization versus decentralized decision-making in fragmented landholding structures.
- Agricultural Producers:Large-scale contract farming operations in Brazil's Matopiba region and India's Punjab standardize acephate procurement through cooperative warehousing and volume tendering, displacing traditional distributor margins while demanding technical support bundling.
- Farm Managers:Professional agronomists overseeing multi-site operations in Australia's Murray-Darling basin pilot drone application infrastructure to reduce buffer zone labor costs and improve dosing precision.
- Pest Control Services:Licensed applicators serving peri-urban greenhouse clusters in Morocco's Souss-Massa region navigate REACH authorization documentation for EU supermarket compliance.
- Distributors:Regional agrochemical wholesalers in Ukraine's sunflower belt and Argentina's Pampas maintain parallel product portfolios to serve export markets with divergent organophosphate registration statuses.
Agricultural Producers anchor volume commitments; Pest Control Services climbs the fastest.
Distribution Channel:
Channel selection correlates with buyer scale, technical support requirements, and payment term flexibility across emerging and mature agricultural economies.
- Online Retail:E-commerce platforms penetrate smallholder segments in India's Andhra Pradesh and Telangana with credit-enabled purchasing and agronomic advisory content, though logistics constraints limit bulk formulation shipments.
- Supermarkets:Hypermarket agrochemical sections in Brazil's urban periphery serve hobby farmers and peri-urban vegetable producers with pre-packaged consumer quantities.
- Specialty Stores:Dedicated agrochemical retailers in South Africa's Free State and Australia's Queensland provide formulation guidance and tank-mix compatibility testing for complex resistance management programs.
- Wholesale Dealers:Volume distributors with Latin American infrastructure sustain FMC Corporation's commitments to soybean cooperatives through extended payment terms and inventory financing.
Wholesale Dealers retains volume leadership; Online Retail posts steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized agronomists and pesticide formulators concentrate in agricultural export corridors where regulatory divergence creates compliance arbitrage opportunities. Workforce density in Brazil's Cerrado and India's Gujarat cotton belt anchors formulation demand. Technical talent clusters around ANVISA, CEA, and EPA registration consultancies in São Paulo, Mumbai, and Washington DC metro areas.
Brazil
Soybean cooperatives in Mato Grosso and Goiás states drive soluble powder procurement for aphid vector management. ANVISA enforces maximum residue limits that dictate EU export market access for treated commodities. The Matopiba agricultural frontier concentrates contract farming consolidation and cooperative warehousing infrastructure.
India
Maharashtra and Gujarat cotton belt producers expand acephate purchases for thrips resistance protocols. CEA regulations govern pre-harvest intervals and buffer zones for export-oriented vegetable programs. Karnataka greenhouse clusters near Bengaluru pilot microencapsulated formulations for ornamental rose exports.
United States
EPA re-registration reviews of organophosphate chemistries shape label restrictions and buffer zone economics for row crop operators. The Mississippi Delta cotton corridor and Midwest soybean belt concentrate aerial application infrastructure. California Central Valley specialty crop producers navigate stricter state-level worker exposure standards.
China
MEE oversight of phosphorus chemical production in the Yangtze River Delta affects upstream methamidophos availability and environmental compliance costs. Formulation plants in Jiangsu and Zhejiang provinces supply active ingredient to Latin American and South Asian markets. Shandong Peninsula agrochemical clusters face dual carbon goal pressure on energy-intensive phosphorylation processes.
Australia
Murray-Darling basin cotton cooperatives pilot drone application platforms to reduce buffer zone labor conflicts. TGA and APVMA residue protocols align with EU EFSA standards for export wheat and canola shipments. Queensland broadacre operators integrate acephate into resistance management rotations for Helicoverpa armigera control.
Global Acephate Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation and active ingredient supply tiers. Market structure tilts toward consolidation among multinational agrochemical platforms with captive distribution networks. Three archetypes dominate: backward-integrated innovators with in-house synthesis capability, generic formulators competing on cost structure, and regional distributors with technical advisory bundling. Competitive moves center on portfolio diversification into biological insecticide pairings and geographic expansion through cooperative procurement consortia.
Within the multinational integrated tier, Bayer Crop Science AG and FMC Corporation exemplify archetypes with Latin American infrastructure and soybean cooperative relationships. ADAMA Limited and UPL Limited represent cost-focused formulators with South Asian manufacturing concentration. Sinon Chemical Group anchors Chinese phosphorus chemical supply positioning. These players occupy distinct competitive spaces without overlapping strategic postures.
| Leading Market Players |
|---|
| Drexel Chemical Company |
| FMC Corporation |
| Syngenta |
| Corteva Inc. |
| Nufarm Limited |
| ADAMA Limited |
| UPL Limited |
| Bayer Crop Science AG |
| Sinon Chemical Group |
| Others |
Supply Flow & Price Mechanics
Phosphorus chemical specialists concentrated in China's Yangtze River Delta drive labor-cost differentials that widen spreads between premium formulated products and generic soluble powders. ANVISA and CEA residue certification tiers separate pricing bands for export-oriented Brazilian soybean cooperatives and Indian cotton belt aggregators.
Pricing Analysis
The bundled-vs-unbundled service split separates cooperative procurement consortia demanding technical advisory and inventory financing from transactional spot buyers. Three-tier pricing structure across premium, standard, and economy levels tracks formulation concentration, with microencapsulated products commanding spreads over soluble powders due to worker safety profiles. Cost compression in generic soluble powders intensifies as UPL Limited and ADAMA Limited expand South Asian manufacturing. Agricultural producers in Brazil's Matopiba region exhibit highest price sensitivity; ornamental greenhouse operators in Kenya's Naivasha cluster show least sensitivity due to phytotoxicity risk premiums.
Supply Chain Analysis
Warehouse-distribution layer concentration in São Paulo, Mumbai, and Buenos Aires anchors hub-and-spoke patterns serving soybean cooperatives and cotton belt aggregators. Active ingredient supply centers on China, India, and Brazil, with methamidophos and phosphorylation reagents drawing from Yangtze River Delta chemical clusters. Single-source vulnerability concentrates in Chinese phosphorus chemical feedstocks under MEE environmental compliance oversight. Distribution runs through wholesale dealers with Latin American infrastructure sustaining volume commitments to cooperative procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in acephate hinges on formulation premiumization toward microencapsulated products and cooperative procurement consolidation reducing distributor margin capture.
For Market Incumbents: Deploy backward integration into active ingredient synthesis to secure methamidophos supply under MEE environmental tightening. Bayer Crop Science AG anchors positioning through captive phosphorylation capacity, while FMC Corporation leverages Latin American distribution infrastructure against generic formulator price erosion. Channel control through cooperative warehousing partnerships defends offtake stability against UPL Limited cost competition. For New Entrants and Emerging Players: Launch via drone application service bundling in Australian broadacre and Ukrainian sunflower regions where precision dosing reduces buffer zone conflicts. Underpenetrated Cerrado expansion zones and Gujarat cotton belt cooperative consortia offer white-space entry with high-concentration soluble powder formulations. Technical advisory partnerships with farm managers piloting aerial platforms provide differentiated go-to-market positioning against established wholesale dealer networks. For Investors and Strategic Acquirers: Valuations sit cheapest among generic formulators with South Asian manufacturing concentration and limited backward integration. Long-term viability over a five-to-ten year window rests on regulatory divergence between jurisdictions maintaining organophosphate registrations and those accelerating phase-outs. Acquisition targets with ANVISA and CEA dual-certification capabilities signal defensible export market access; the inflection indicator to watch is EPA re-registration review timelines affecting label restrictions and buffer zone economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Synthesis | Bayer Crop Science AG secures methamidophos supply under MEE environmental compliance tightening. |
| Cooperative Procurement Consortium Partnerships | FMC Corporation locks volume commitments with Matopiba soybean aggregators displacing traditional distributors. |
| Microencapsulation Formulation Development | Specialty exporters in Kenya and Colombia command premium pricing for reduced dermal exposure risk. |
| Drone Application Infrastructure Deployment | Australian cotton cooperatives in the Murray-Darling basin reduce buffer zone labor conflicts through precision dosing. |
| Dual-Certification Regulatory Investment | Formulators maintaining ANVISA and CEA dossiers preserve EU-destined commodity market access. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with formulation plant managers, procurement leads at Brazilian soybean cooperatives, distribution channel partners in Latin American wholesale networks, and regulatory affairs directors navigating EPA re-registration reviews. Secondary validation drew from customs and trade data, ANVISA and CEA residue limit publications, SEC 10-K filings of listed agrochemical firms, and EFSA guidance documents on organophosphate evaluations. Bottom-up volume estimates from cooperative procurement consortia triangulated against top-down market sizing from active ingredient trade flows.
Segment-weighting across the analysis window applied product type, application, end user, and distribution channel dimensions with regional production hub overlays. Agricultural insecticide volumes modeled separately from ornamental plant premiums due to divergent residue tolerance thresholds. CAGRs derived from historical offtake patterns at cooperative procurement consortia and projected acreage expansion in Brazil's Cerrado and India's Gujarat cotton belt. Forecast inputs incorporated ANVISA maximum residue limit revisions and EPA buffer zone constraint scenarios.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU organophosphate phase-out scenarios or MEE environmental shutdowns in the Yangtze River Delta. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Indonesia Fungicide Market
Crop Protection
Phytogenic Poultry Feed Additives Market
Crop Protection
India Insecticide Market
Crop Protection
Europe Soil Treatment Market
Crop Protection
India Herbicide Market
Crop Protection
Pre-Emergent Herbicide Market
Crop Protection
Tebuconazole Market
Crop Protection
Glufosinate Ammonium Market
Crop Protection
Global Dicamba Herbicide Market
Crop Protection
South America Crop Protection Chemicals Market
Crop Protection
Global Turf Protection Market
Crop Protection
United Kingdom Crop Protection Chemicals Market
Crop Protection
Trapping and Mating Disruption Systems Market
Crop Protection
Global Crop Growth Regulators Market
Crop Protection
North America Crop Protection Chemicals Market
Crop Protection
Asia Pacific Herbicide Market