
 Europe Agricultural Pheromones Market | 2026-2036
Europe Agricultural Pheromones Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Agricultural Pheromones Market Foresight
Regulatory-grade formulation purity is bifurcating the competitive landscape in Europe. BASF SE leverages its synthetic chemistry infrastructure to supply high-specification active ingredients for mating disruption systems across German fruit orchards. Biobest Group NV sustains leadership in live insect delivery paired with pheromone monitoring tools throughout Belgium and the Netherlands. Koppert Biological Systems dominates Southern European distribution through integrated biocontrol programs that bundle pheromones with beneficial insect releases.
Agricultural pheromones are semiochemical compounds, typically synthesized as 95-99% pure geometric or enantiomeric isomopes, that mimic natural insect signaling molecules to disrupt pest reproduction or concentrate populations for removal. These compounds function through slow-release dispensers, typically polyethylene tubes or membrane reservoirs, that maintain field-active emission rates across 90-180 day growing seasons. Mating disruption products command the largest current revenue pool given their established efficacy in Lepidoptera management across European apple and grape production. Attract-and-kill configurations represent the fastest-expanding segment as Spanish olive and citrus growers seek reduced-spray alternatives aligned with integrated pest management protocols.
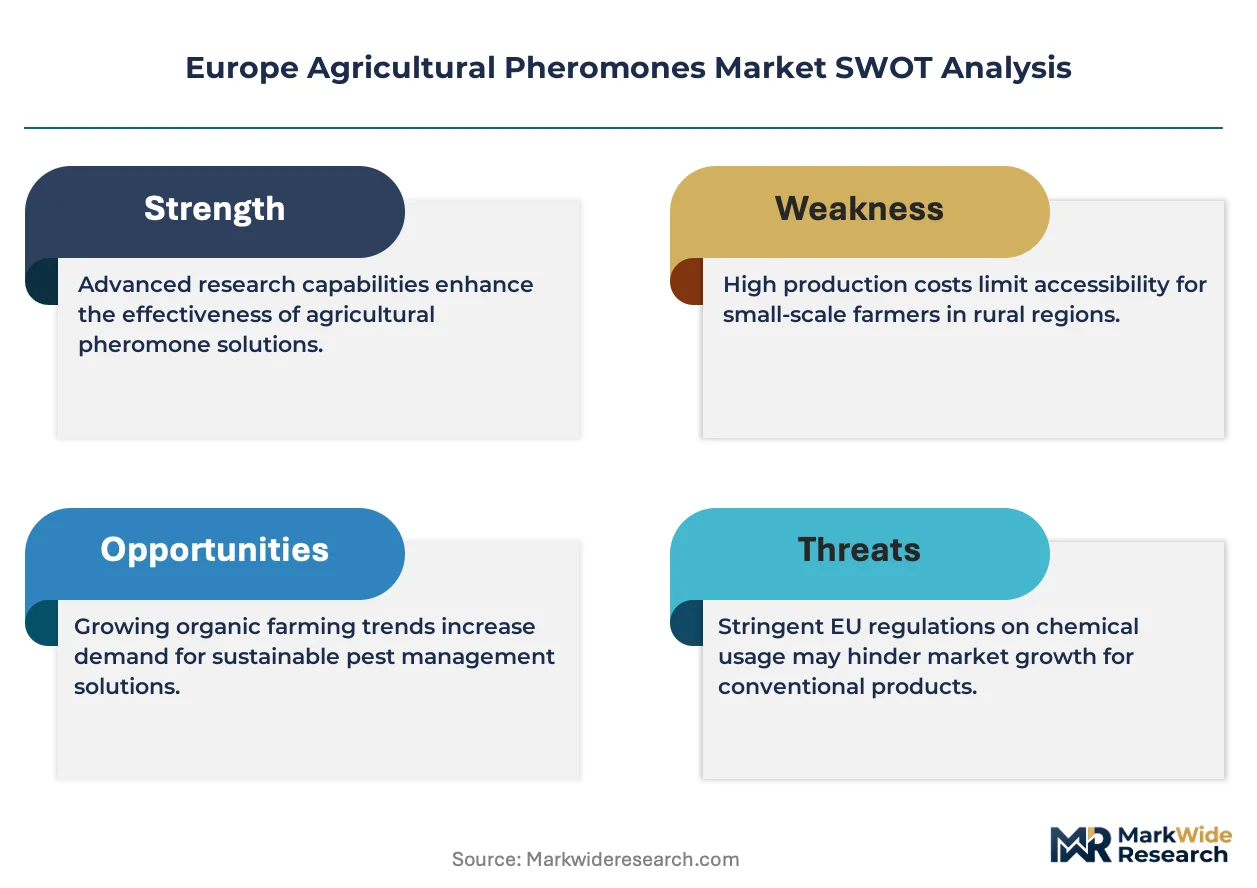
The EU Green Deal and Farm to Fork strategy are reshaping product registration pathways, with EFSA now requiring expanded non-target organism data for pheromone formulations seeking Annex I listing under Regulation 1107/2009. REACH compliance adds testing burdens for synthetic pheromone manufacturers, while CE marking requirements for automated dispenser systems create barriers for non-European hardware suppliers. Stakeholders must monitor how the EU's 50% pesticide reduction targets will recalibrate reimbursement and advisory support for pheromone adoption across national extension services.
Market Dynamics
EFSA's expanded non-target organism data requirements under Regulation 1107/2009 are forcing pheromone manufacturers to restructure formulation testing protocols and extend registration timelines for Annex I listing.
Growth Catalysts
- EU Green Deal pesticide reduction targets:The Farm to Fork strategy's 50% chemical insecticide reduction mandate is creating direct substitution demand for mating disruption systems across French and Italian fruit orchards.
- Vineyard export compliance pressure:Spanish and Italian wine producers are adopting pheromone-based programs to meet residue limits for premium export markets in Northern Europe and North America.
- Biocontrol integration protocols:Bundled service models combining pheromone dispensers with beneficial insect releases are accelerating adoption in Belgium and Netherlands greenhouse operations.
Market Restraints
- REACH compliance burdens:Synthetic pheromone manufacturers face escalating testing costs for geometric and enantiomeric isomer purity verification under ECHA chemical safety protocols.
- Seasonal revenue concentration:The 90-180 day field-active emission window for polyethylene tube dispensers compresses annual sales realization into narrow Q1-Q2 deployment periods.
- CE marking barriers:Automated dispenser hardware from non-European suppliers encounters extended conformity assessment timelines for electromagnetic compatibility and machinery safety certification.
Strategic Opportunities
- Olive and citrus attract-and-kill expansion:Spanish growers in Andalusia are piloting reduced-spray configurations that pair pheromone lures with targeted insecticide applications.
- Provence-Alpes-Côte d'Azur intensive fruit zones:France's stone fruit and apple concentration zones present concentrated demand for multi-species mating disruption systems.
- Advisory service reimbursement recalibration:National extension services across Germany and France are restructuring cost-share programs to accelerate pheromone adoption ahead of 2030 pesticide reduction milestones.
Industry Challenges
- Semiochemical synthesis expertise scarcity:Formulation chemists capable of achieving 95-99% isomeric purity in scaled production remain concentrated among a limited pool of specialized European suppliers.
- Dispenser-to-pest lifecycle synchronization:Field teams must calibrate polyethylene tube emission rates against variable regional pest emergence patterns across Mediterranean and Continental climate zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Agricultural Pheromones Market |
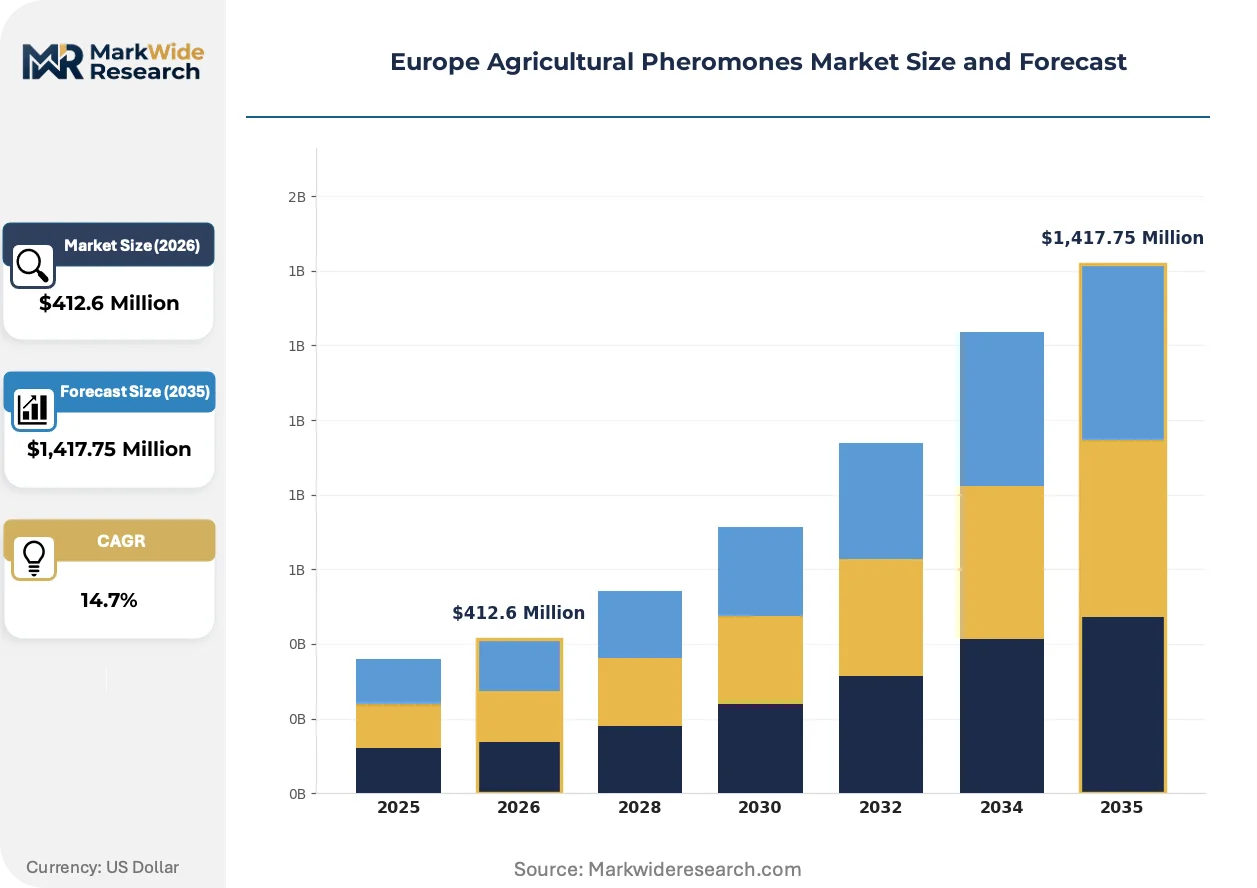
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,417.75 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mating Disruption, Trap Crop, Attract and Kill, Mass Trapping Application: Crop Protection, Insect Management, Pest Control, Yield Improvement End User: Agricultural Producers, Organic Farmers, Crop Consultants, Research Institutions Distribution Channel: Direct Sales, Retail, Online Platforms, Agrochemical Distributors |
| Companies Covered | BASF SE, Biobest Group NV, Koppert Biological Systems, Russell IPM Ltd, Suterra LLC, Shin-Etsu Chemical Co., Ltd., Pherobank, ISCA Technologies, Andermatt Biocontrol AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Agricultural Pheromones Market Shifts & Advancements
Membrane reservoir dispensers with precision-controlled release kinetics are displacing conventional polyethylene tubes as the dominant field deployment technology across European high-value crop sectors.
Membrane-based micro-encapsulation systems with tunable diffusion barriers are supplanting traditional polyethylene tube dispensers in German and French apple orchards. Growers in the Loire Valley and Lake Constance fruit belt are transitioning 60-70% of mating disruption acreage to these configurations within three growing seasons. The shift is compressing supplier margins on legacy tube formats while rewarding integrated biocontrol providers with captive polymer synthesis capabilities.
EFSA's revised data requirements for non-target arthropod toxicity under Regulation 1107/2009 are extending pheromone product registration timelines by 18-24 months. Formulation developers must now submit expanded pollinator and beneficial insect exposure studies for Annex I listing eligibility. Southern European suppliers targeting olive and citrus applications are prioritizing dossier preparation for 2025-2026 submission windows to secure market access ahead of peak Farm to Fork implementation.
Spanish olive cooperatives are consolidating procurement decisions at regional association level rather than individual farm level. This concentration is displacing traditional agricultural distributor networks with direct manufacturer contracting for large-volume pheromone dispenser programs. The shift is most visible in Andalusia's Jaén province, where three cooperatives now control 40% of regional attract-and-kill deployment volume and negotiate multi-year supply agreements with integrated biocontrol providers.
Europe Agricultural Pheromones Market Segmentation
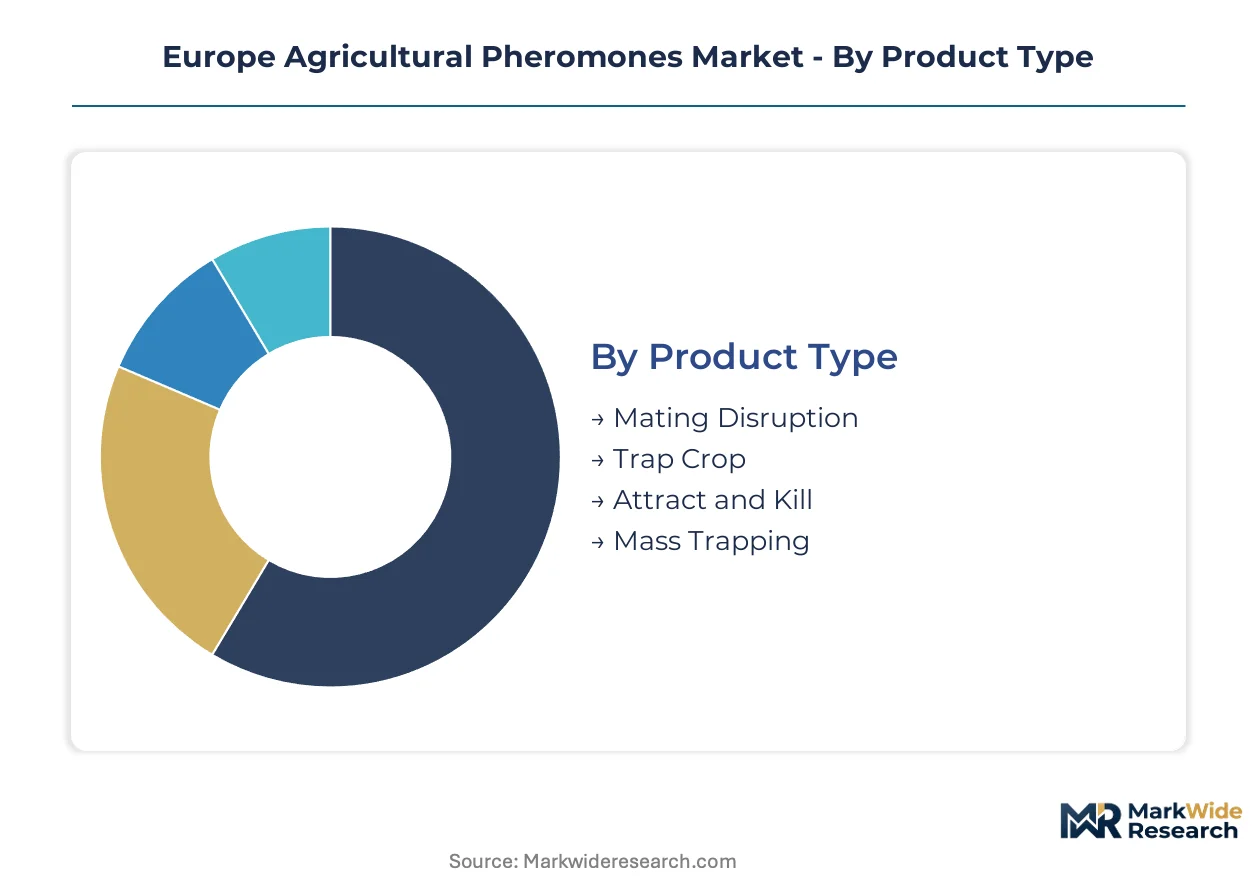
Pheromone formulation chemistry and dispenser technology create divergent margin profiles across product categories. EFSA's Annex I registration requirements under Regulation 1107/2009 impose distinct testing burdens on each segment, reshaping competitive positioning among European suppliers.
Product Type:
EFSA's expanded non-target organism data requirements create tiered registration barriers that favor established synthetic chemistry infrastructure over novel formulation approaches.
- Mating Disruption:Synthetic 95-99% pure geometric isomopes deployed through slow-release polyethylene tubes or membrane reservoirs across 90-180 day growing seasons. French apple orchards in Provence-Alpes-Côte d'Azur and the Loire Valley concentrate procurement for multi-species Lepidoptera management as EU Green Deal pesticide reduction targets harden.
- Attract and Kill:Pheromone lures paired with targeted insecticide applications in reduced-spray configurations. Spanish olive growers in Andalusia's Jaén province are piloting cooperative procurement models that displace traditional distributor networks with direct manufacturer contracting.
- Trap Crop:Semiochemical-treated buffer zones that intercept pest migration before primary crop penetration. Italian vineyard operators deploy these systems along export-bound wine grape perimeters to meet residue limits for Northern European markets.
- Mass Trapping:High-density pheromone lure concentrations for population suppression in greenhouse operations. Belgian and Dutch growers integrate these systems with beneficial insect release protocols under bundled biocontrol service models.
Mating Disruption handles the majority of throughput; Attract and Kill is climbing the fastest on share as Spanish cooperatives consolidate procurement decisions.
Application:
Cost-to-efficacy ratios vary sharply across application types, with premium pricing attaching to residue-sensitive export compliance use cases.
- Crop Protection:Pheromone-based perimeter defense and in-field mating disruption for high-value fruit and vine crops. German fruit belt operations around Lake Constance prioritize membrane reservoir dispensers with precision-controlled release kinetics over legacy polyethylene formats.
- Insect Management:Population monitoring and behavioral manipulation targeting specific Lepidoptera or Coleoptera species. REACH compliance burdens for isomeric purity verification concentrate supply among specialized European formulation chemists with captive polymer synthesis capabilities.
- Pest Control:Eradication-focused deployment in organic certification contexts where synthetic insecticide use is prohibited. Italian organic wine producers in Tuscany and Piedmont absorb premium dispenser costs to maintain export market access.
- Yield Improvement:Indirect productivity gains through reduced fruit damage and elimination of pre-harvest intervals. French stone fruit growers in PACA calculate return on investment through combined pesticide cost reduction and quality premium capture.
Crop Protection commands the largest installed base; Insect Management is expanding most quickly as EFSA registration timelines extend and technical expertise scarcity intensifies.
End User:
Customer scale determines procurement channel preference and advisory service engagement depth.
- Agricultural Producers:Conventional and integrated farming operations with acreage sufficient to justify fixed dispenser deployment costs. Spanish olive cooperatives in Andalusia now negotiate multi-year supply agreements controlling 40% of regional attract-and-kill volume.
- Organic Farmers:Certification-constrained operations where pheromones represent permitted biocontrol under EU organic regulation. Premium pricing tolerance reflects elimination of synthetic insecticide alternatives.
- Crop Consultants:Technical advisory services prescribing pheromone protocols as components of integrated pest management plans. German and French extension services are restructuring cost-share programs to accelerate adoption ahead of 2030 pesticide reduction milestones.
- Research Institutions:Field trial operators and registration dossier preparers generating efficacy data for EFSA Annex I submissions. Southern European suppliers prioritize 2025-2026 submission windows for olive and citrus applications.
Agricultural Producers absorb the majority of volume; Crop Consultants are gaining influence fastest as national extension services recalibrate reimbursement structures.
Distribution Channel:
Channel margins compress where procurement concentrates at cooperative or regional association level.
- Direct Sales:Manufacturer-to-grower contracting for large-volume pheromone dispenser programs. Spanish olive cooperative consolidation is displacing traditional agricultural distributor networks with this channel.
- Retail:Agricultural supply stores serving smallholder operations with fragmented acreage. Seasonal revenue concentration into Q1-Q2 deployment periods strains inventory financing.
- Online Platforms:E-commerce procurement for monitoring trap components and replacement lures. CE marking requirements for automated dispenser systems create barriers for non-European hardware suppliers.
- Agrochemical Distributors:Traditional networks bundling pheromones with conventional crop protection portfolios. Margin pressure intensifies as biocontrol specialists capture share through integrated service models.
Direct Sales is capturing the fastest volume shift; Agrochemical Distributors retain the broadest geographic coverage.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation-grade semiochemical production clusters in Germany and the Netherlands supply mating disruption systems across Mediterranean fruit belts. REACH compliance costs and EFSA registration timelines concentrate high-purity synthesis among specialized European suppliers with captive polymer capabilities.
France
Provence-Alpes-Côte d'Azur stone fruit growers and Loire Valley apple producers drive multi-species Lepidoptera management demand. The EU Green Deal's Farm to Fork pesticide reduction targets harden substitution pressure across intensive fruit zones. Extension services in PACA recalibrate cost-share programs to accelerate pheromone adoption ahead of 2030 milestones.
Spain
Andalusian olive cooperatives in Jaén province consolidate procurement for attract-and-kill programs targeting reduced-spray export compliance. EFSA's expanded non-target organism data requirements extend registration timelines for olive-specific formulations. Regional association-level contracting now controls 40% of dispenser deployment volume, displacing traditional distributor networks.
Italy
Tuscan and Piedmont organic wine producers absorb premium dispenser costs to maintain Northern European market access. Vineyard operators deploy trap crop systems along export-bound perimeters to meet residue limits. The Ministry of Agriculture's biocontrol incentive programs align with EU Green Deal implementation schedules.
Germany
Lake Constance fruit belt operations prioritize membrane reservoir dispensers with precision-controlled release kinetics over legacy polyethylene formats. ECHA's REACH protocols impose geometric and enantiomeric isomer purity verification burdens on synthetic pheromone manufacturers. BASF SE leverages Ludwigshafen-based synthetic chemistry infrastructure to supply high-specification active ingredients.
Belgium and Netherlands
Greenhouse operations around Antwerp and Westland integrate mass trapping with beneficial insect release protocols under bundled biocontrol service models. Biobest Group NV sustains leadership in live insect delivery paired with pheromone monitoring tools. CE marking requirements for automated dispenser systems create barriers for non-European hardware suppliers.
Europe Agricultural Pheromones Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European pheromone market. High-purity semiochemical synthesis requires specialized formulation expertise that concentrates among integrated biocontrol providers with captive polymer capabilities. Three archetypes dominate: synthetic chemistry majors with regulatory-grade infrastructure, biological systems specialists bundling pheromones with beneficial insect releases, and regional distributors transitioning to direct manufacturer contracting. Competitive moves center on membrane reservoir technology transitions and cooperative procurement consolidation in Mediterranean olive and citrus zones.
Among German synthetic chemistry majors, BASF SE anchors the high-specification active ingredient tier through Ludwigshafen-based infrastructure. Biobest Group NV and Koppert Biological Systems exemplify the integrated biocontrol archetype, with the former pairing live insect delivery with monitoring tools and the latter dominating Southern European distribution through bundled service models. These three companies represent the dominant competitive positions shaping technology adoption and procurement channel evolution across European fruit and vine production zones.
| Leading Market Players |
|---|
| BASF SE |
| Biobest Group NV |
| Koppert Biological Systems |
| Russell IPM Ltd |
| Suterra LLC |
| Shin-Etsu Chemical Co., Ltd. |
| Pherobank |
| ISCA Technologies |
| Andermatt Biocontrol AG |
| Others |
Supply & Pricing Matrix
Ninety-to-one-hundred-eighty-day inventory cycles for polyethylene tube dispensers concentrate working capital burdens on German and Dutch distributors while amplifying pricing leverage for membrane reservoir suppliers with captive polymer synthesis capabilities. REACH compliance costs for isomeric purity verification cascade downstream as tiered certification premiums, with EFSA Annex I registration status commanding substantial markups over provisional formulations.
Pricing Analysis
Regulation 1107/2009 dictates the pricing tier structure across the European agricultural pheromones market through its Annex I registration requirements. Three-tier pricing stratifies across premium EFSA-listed formulations, standard REACH-compliant products, and economy-grade provisional supplies. Price differentiation hinges on isomeric purity certification and dispenser technology sophistication, with membrane reservoir systems capturing substantial premiums over legacy polyethylene formats. Pricing pressure intensifies in standard tiers as Spanish cooperative procurement consolidation squeezes distributor margins. Agricultural producers with fragmented acreage exhibit highest price sensitivity, while organic certification-constrained operations absorb premium costs to maintain market access.
Supply Chain Analysis
Germany and the Netherlands anchor high-purity semiochemical synthesis through Ludwigshafen and Westland formulation clusters supplying mating disruption systems across Mediterranean fruit belts. Production draws from specialized geometric isomer precursors, polyethylene and membrane polymer feedstocks, and precision-controlled release kinetics engineering. Single-source vulnerability concentrates in enantiomeric separation expertise held by limited European suppliers. Distribution runs through direct manufacturer contracting with Spanish olive cooperatives, agrochemical distributor networks serving smallholders, and bundled biocontrol service models in Belgian and Dutch greenhouse operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in advisory protocol design and dispenser calibration support are expanding faster than hardware sales as national extension services restructure cost-share programs ahead of pesticide reduction milestones.
For Market Incumbents: Fortify membrane reservoir technology leadership through backward integration into polymer synthesis capabilities and deepen advisory service bundling to offset hardware margin compression from cooperative procurement consolidation. Prioritize EFSA dossier investment for olive and citrus formulations before submission window saturation intensifies. For New Entrants and Emerging Players: Anchor in Spanish olive cooperative direct contracting channels where traditional distributor displacement creates procurement access for integrated biocontrol specialists. Target attract-and-kill configurations in Andalusia's Jaén province through regional association-level engagement and multi-year supply agreement structures. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because EU Green Deal pesticide reduction targets harden irreversible substitution demand for mating disruption systems. Acquisition focus should center on formulation chemists with 95-99% isomeric purity production capabilities and captive dispenser manufacturing. Watch EFSA registration timeline extensions as inflection signal for supply consolidation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Synthesis | Captive membrane reservoir production secures margin control against polyethylene tube displacement. |
| EFSA Annex I Dossier Investment | Registration approval unlocks premium pricing tiers in French and Italian fruit protection markets. |
| Cooperative Procurement Direct Contracting | Andalusian olive association consolidation rewards bypass of traditional agricultural distributor networks. |
| Advisory Service Reimbursement Alignment | Extension service cost-share restructuring accelerates grower adoption ahead of 2030 milestones. |
| Multi-Species Mating Disruption Development | Provence-Alpes-Côte d'Azur stone fruit concentration demands integrated Lepidoptera management protocols. |
Research Methodology
A standing panel of formulation chemists, cooperative procurement managers, extension service advisors, and biocontrol distribution specialists provided ongoing calibration across primary interview rounds. Secondary validation drew from EFSA regulatory filings, ECHA REACH registration databases, EU customs trade records for semiochemical imports, and national agricultural ministry incentive program disclosures. Bottom-up acreage deployment estimates triangulated against top-down supplier revenue attribution across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs before finalization. The analytical framework modeled product type, application method, end-user scale, and distribution channel segmentation throughout the projection horizon. CAGRs derived from deployment trajectory curves incorporating EFSA registration timeline scenarios, cooperative procurement consolidation rates, and membrane reservoir technology transition speeds.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal implementation pace and stable REACH compliance cost structures; material deviation would warrant model refresh. Specific risks include accelerated pesticide reduction timeline revisions, single-source isomeric purity supplier disruptions, and cooperative procurement centralization slowdowns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Soil Sterilizers Market
Crop Protection
Global Dicamba Herbicide Market
Crop Protection
India Insecticide Market
Crop Protection
United States Nematicides Market
Crop Protection
North America Molluscicides Market
Crop Protection
South Korea Crop Protection Chemicals Market
Crop Protection
Grain Protectant Market
Crop Protection
South America Insecticide Market
Crop Protection
Iprodione Market
Crop Protection
Germany Crop Protection Chemicals Market
Crop Protection
Glufosinate Ammonium Market
Crop Protection
US Herbicide Market
Crop Protection
Tebuconazole Market
Crop Protection
Indonesia Crop Protection Chemicals Market
Crop Protection
US Turf and Ornamental Protection Market
Crop Protection
Crop Bactericides Market