
 Dicamba Market | 2026-2036
Dicamba Market Size, Share, and Industry Trends Forecast 2026-2036
Dicamba Market Analysis
United States production capacity for dicamba active ingredient is tilting toward integrated manufacturing corridors. Bayer AG anchors its position through captive supply chains for dicamba-tolerant seed-herbicide systems. BASF SE differentiates via specialized salt formulations engineered for reduced volatility profiles. Corteva Agriscience competes through broad portfolio breadth spanning amine and ester chemistries.
Dicamba denotes a synthetic auxin herbicide belonging to the benzoic acid chemical family, typically formulated as dimethylamine salts or diglycolamine salts for agricultural spraying, functioning through disruption of plant cell elongation and protein synthesis to control broadleaf weeds in grass crops. The herbicide product category dominates commercial volume due to established row-crop dependency, while liquid formulation concentrates margin pools through precision application compatibility with modern sprayer fleets. Salts and ester formulation types segment the technical supply base, with amine salts leading in regulatory acceptance and ester variants facing tighter volatility restrictions across jurisdictions.
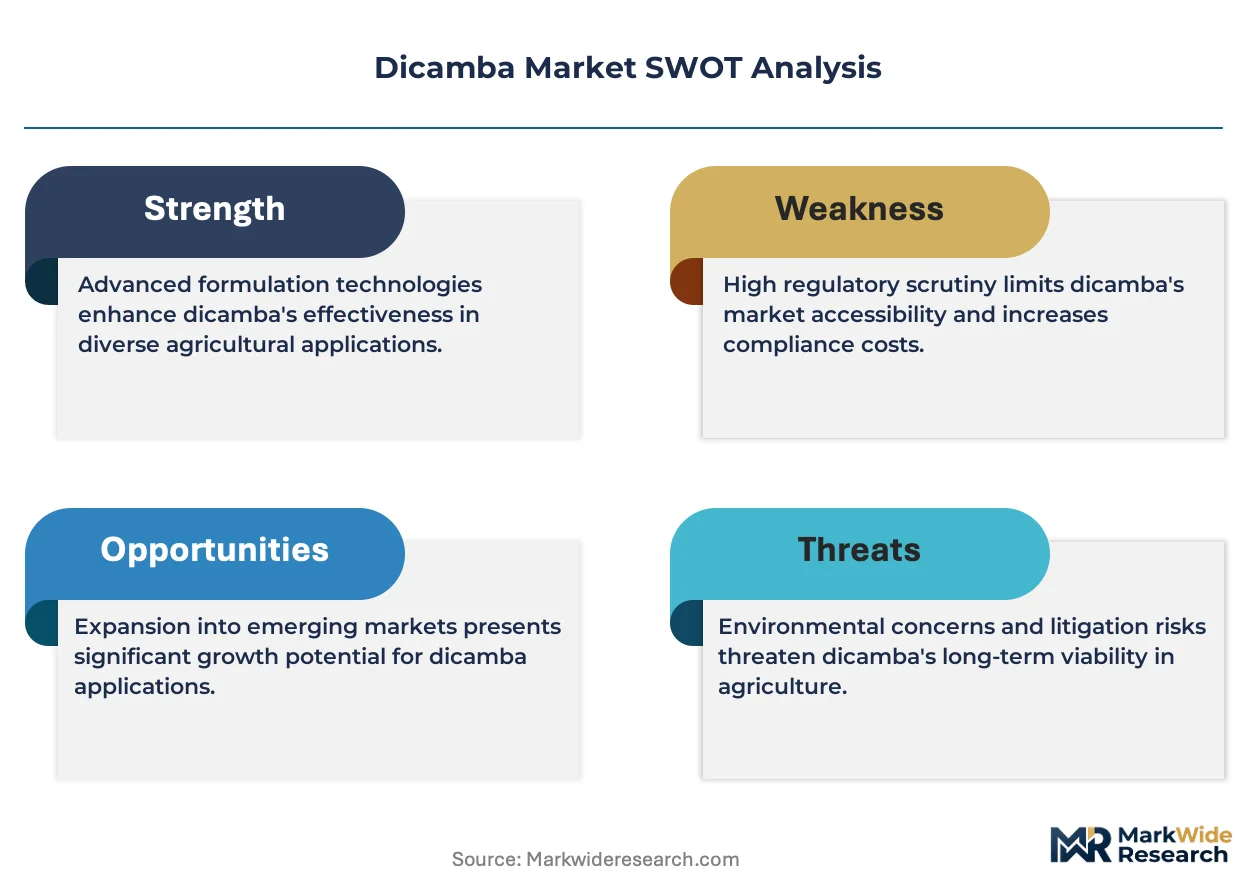
EPA registration requirements under the Federal Insecticide, Fungicide, and Rodenticide Act mandate downwind buffer zones and application cutoff dates, directly constraining seasonal demand windows and product label specifications. State-level Department of Agriculture rules in Illinois, Indiana, and Arkansas impose additional training certifications and record-keeping burdens that elevate compliance costs for applicators and distributors. Stakeholders must monitor pending state 24(c) special local need registrations and federal re-registration timelines to anticipate supply disruptions and label restriction expansions.
Market Dynamics
EPA volatility mitigation mandates under the Federal Insecticide, Fungicide, and Rodenticide Act are compressing formulation windows and forcing salt chemistry pivots across the supply base. Low-vapor-pressure diglycolamine salts now dominate new product registrations while older dimethylamine formulations face label restrictions.
Growth Catalysts
- Dicamba-tolerant soybean seed systems:Stacked trait platforms in the United States Corn Belt expand addressable acreage for post-emergent broadleaf weed control. Farmers adopting these systems lock in herbicide demand across multiple growing seasons.
- EPA 24(c) special local need registrations:State-level flexibility for targeted pest pressures extends commercial utility beyond federal label limits. Arkansas and Illinois leverage this pathway for resistant weed management protocols.
- Precision application hardware:Drift-reduction nozzles and pulse-width modulation sprayers enable compliance with buffer zone requirements. Equipment manufacturers integrate these technologies into new machine sales.
Market Restraints
- Active ingredient supply concentration:Captive production at integrated agrochemical majors limits merchant market availability. Third-party formulators face raw material access constraints during peak seasonal demand.
- Volatile organic compound exposure liability:Off-target movement claims generate litigation risk and insurance cost escalation. Applicators in high-density soybean regions bear elevated legal exposure.
- Glufosinate and 2,4-D choline alternative systems:Competing herbicide-tolerant seed platforms capture acreage from dicamba-dependent rotations. Bayer and Corteva promote these alternatives in resistance management programs.
Strategic Opportunities
- Brazilian cerrado expansion:Dicamba-tolerant cotton and soybean adoption lags North American penetration by approximately five years. Local registration pathways through ANVISA offer first-mover positioning.
- Co-formulation with residual herbicides:Tank-mix compatibility with acetochlor and metolachlor extends control spectrum into mid-season weed flushes. Formulation houses develop pre-mix products for this application window.
- Carbon intensity scoring alignment:Reduced tillage systems enabled by effective chemical weed control qualify for climate-smart agriculture incentives. USDA conservation programs reward adoption of integrated weed management protocols.
Industry Challenges
- Applicator certification complexity:State-mandated training modules for auxinic herbicide use vary across Illinois, Indiana, and Arkansas jurisdictions. Compliance administrators track expiration dates and reciprocity agreements.
- Seed-herbicide system integration timelines:Trait introgression into elite germplasm requires multi-year breeding cycles. Product launch synchronization between seed and chemistry divisions strains coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dicamba Market |
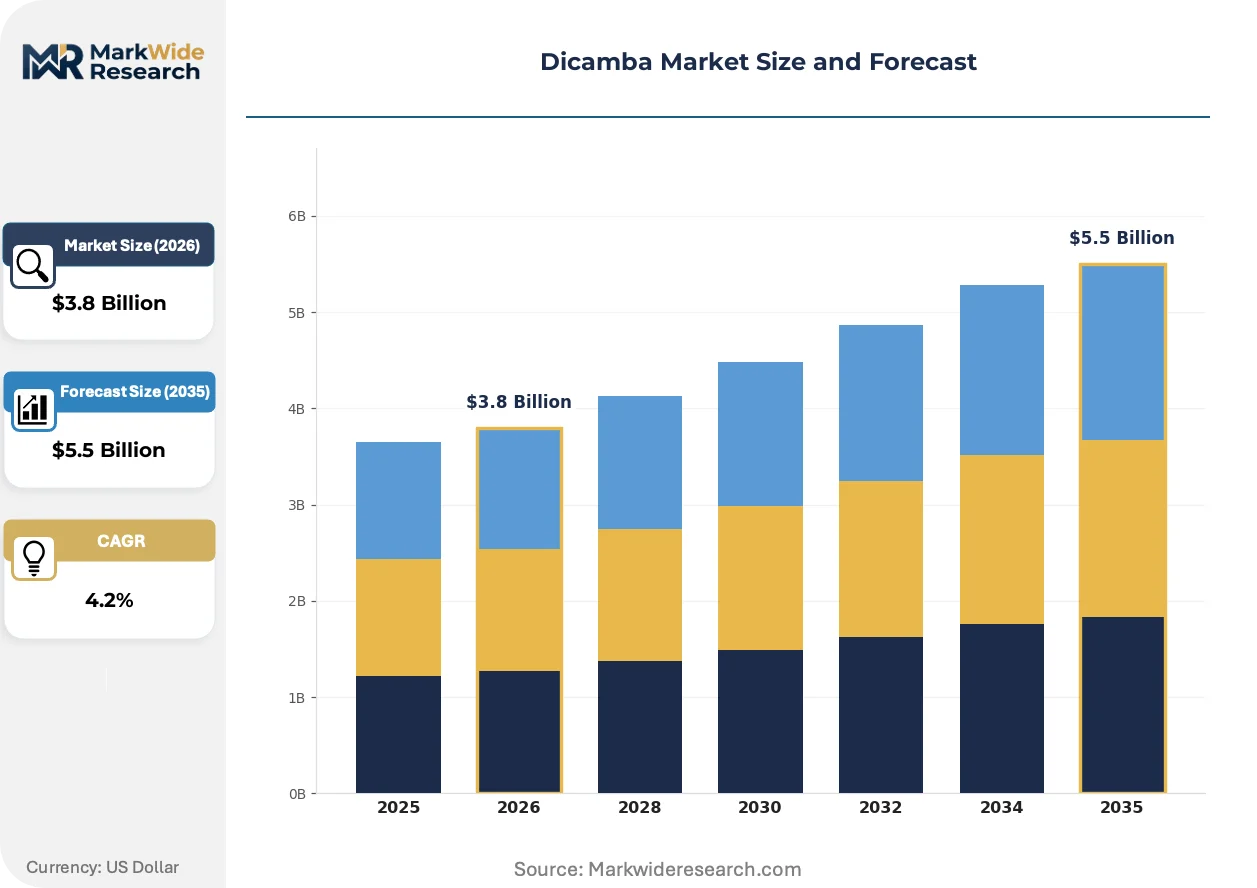
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicide, Liquid Formulation, Granular, Pre-emergent End Use Sector: Agriculture, Forestry, Horticulture, Turf Management Application Method: Spraying, Soil Drench, Granular Application, Foliar Treatment Formulation Type: Salts, Ester, Amine, Others |
| Companies Covered | BASF SE, Bayer AG, Corteva Agriscience, Syngenta Group, Nufarm Limited, ADAMA Ltd., FMC Corporation, UPL Limited, Albaugh LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dicamba Market Emerging Trajectories
Formulation chemistry and application technology are converging to address volatility constraints while maintaining efficacy against resistant weed populations. Three developments define the current innovation cycle.
Low-vapor-pressure diglycolamine salt formulations are rendering obsolete traditional dimethylamine salt products in regulatory-sensitive jurisdictions. Major row-crop operations in Iowa and Minnesota have completed fleet transitions to these chemistries ahead of mandatory cutoff dates. The shift compresses margins on legacy inventory while rewarding early reformulation investments.
EPA buffer zone calculations now incorporate sensitive crop registries and real-time meteorological data through the Bulletins Live! Two system. This digital infrastructure forces applicators to verify field-specific restrictions within 24 hours of spraying. The compliance burden falls heaviest on custom application businesses serving fragmented landholdings.
Farmer purchasing patterns now prioritize bundled seed-herbicide insurance products over standalone chemistry procurement. Retail agronomists in the Corn Belt report contract consolidation with fewer suppliers offering comprehensive resistance management guarantees. This concentration shifts margin capture toward integrated system providers and reduces price transparency for generic alternatives.
Dicamba Market Segmentation
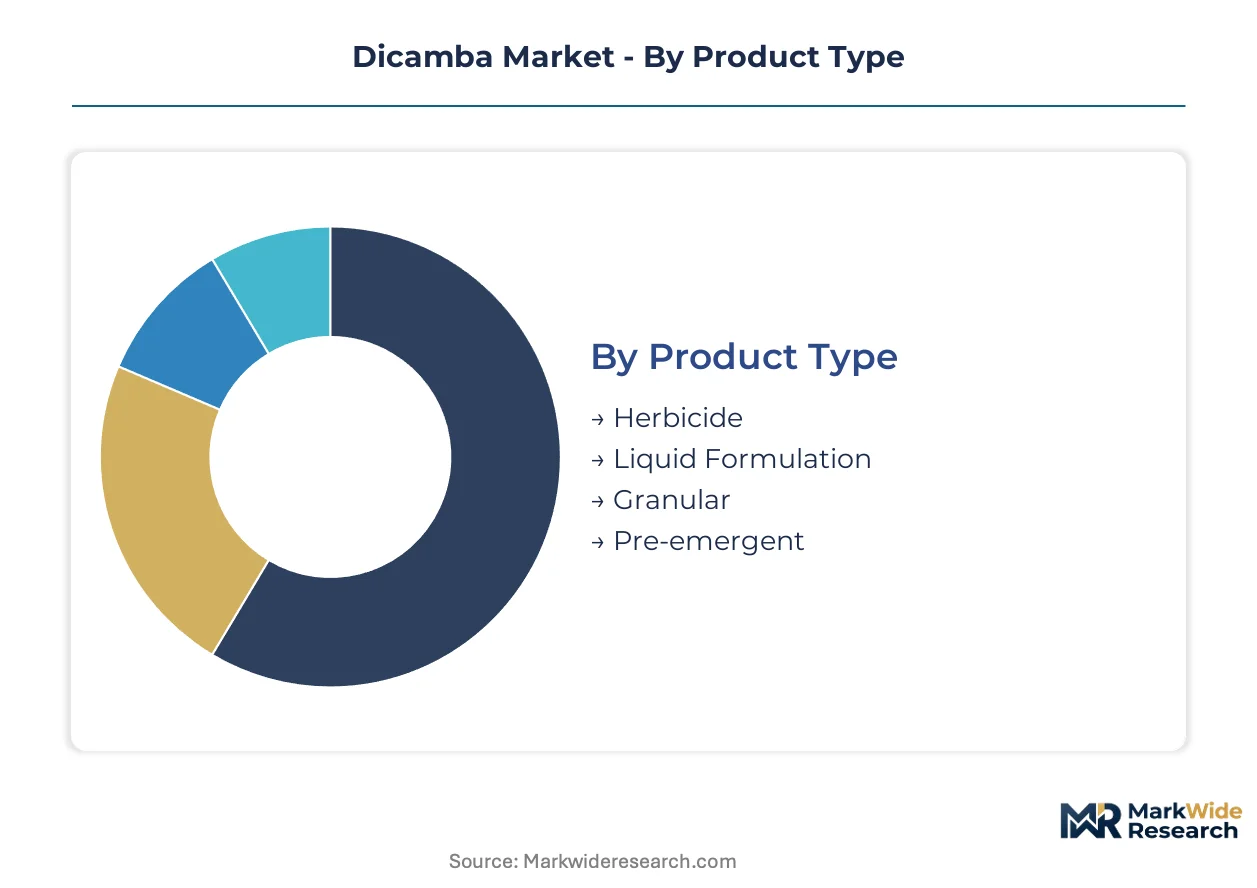
Dicamba market segmentation reveals how formulation chemistry, application technology, and end-use specialization create distinct commercial zones. Each category carries unique regulatory burdens and margin structures that reshape supplier positioning across row-crop and specialty agriculture.
Product Type:
Product categories span the full use-case spectrum from broad-acre row crops to precision turf applications, with formulation complexity determining price tier and seasonal demand concentration.
- Herbicide:Synthetic auxin chemistry formulated as dimethylamine or diglycolamine salts for post-emergent broadleaf control in dicamba-tolerant soybean and cotton systems. Demand clusters in the United States Corn Belt where stacked-trait seed platforms lock in multi-season chemistry procurement.
- Liquid Formulation:Concentrate products engineered for compatibility with pulse-width modulation sprayers and drift-reduction nozzles. Iowa and Illinois retailers report fleet transitions to these chemistries ahead of EPA volatility mandate deadlines.
- Granular:Solid carrier formulations for pre-plant incorporation in conservation tillage systems.
- Pre-emergent:Soil-applied products targeting early-season weed flushes before crop canopy closure.
The dominant share belongs to Herbicide, while Liquid Formulation is closing the gap fastest.
End Use Sector:
Customer type determines volume scale and technical service intensity, with agriculture commanding bulk procurement and specialty sectors demanding customized stewardship protocols.
- Agriculture:Row-crop production of soybean, cotton, and corn in dicamba-tolerant systems across the United States Midwest and Delta regions. EPA buffer zone requirements and state training mandates elevate compliance costs for commercial applicators serving fragmented landholdings.
- Forestry:Site preparation and release treatments in commercial timber stands.
- Horticulture:Specialty crop applications with heightened sensitivity to off-target movement.
- Turf Management:Golf course and athletic field maintenance requiring precision application windows.
Agriculture captures the volume base, with Horticulture expanding most quickly on premium pricing.
Application Method:
Equipment compatibility and drift potential segment the technical supply base, with precision methods gaining regulatory preference over broadcast alternatives.
- Spraying:Aerial and ground-based application using drift-reduction nozzles and real-time meteorological verification through EPA Bulletins Live! Two system. Custom applicators in Indiana and Arkansas bear the heaviest compliance burden from 24-hour pre-spray field checks.
- Soil Drench:Root-zone delivery for pre-emergent weed control in reduced-tillage systems.
- Granular Application:Mechanical spreader distribution for pre-plant incorporation.
- Foliar Treatment:Targeted post-emergent spraying on weed foliage with adjuvant systems.
Spraying maintains the dominant position, while Foliar Treatment gains share on resistance management protocols.
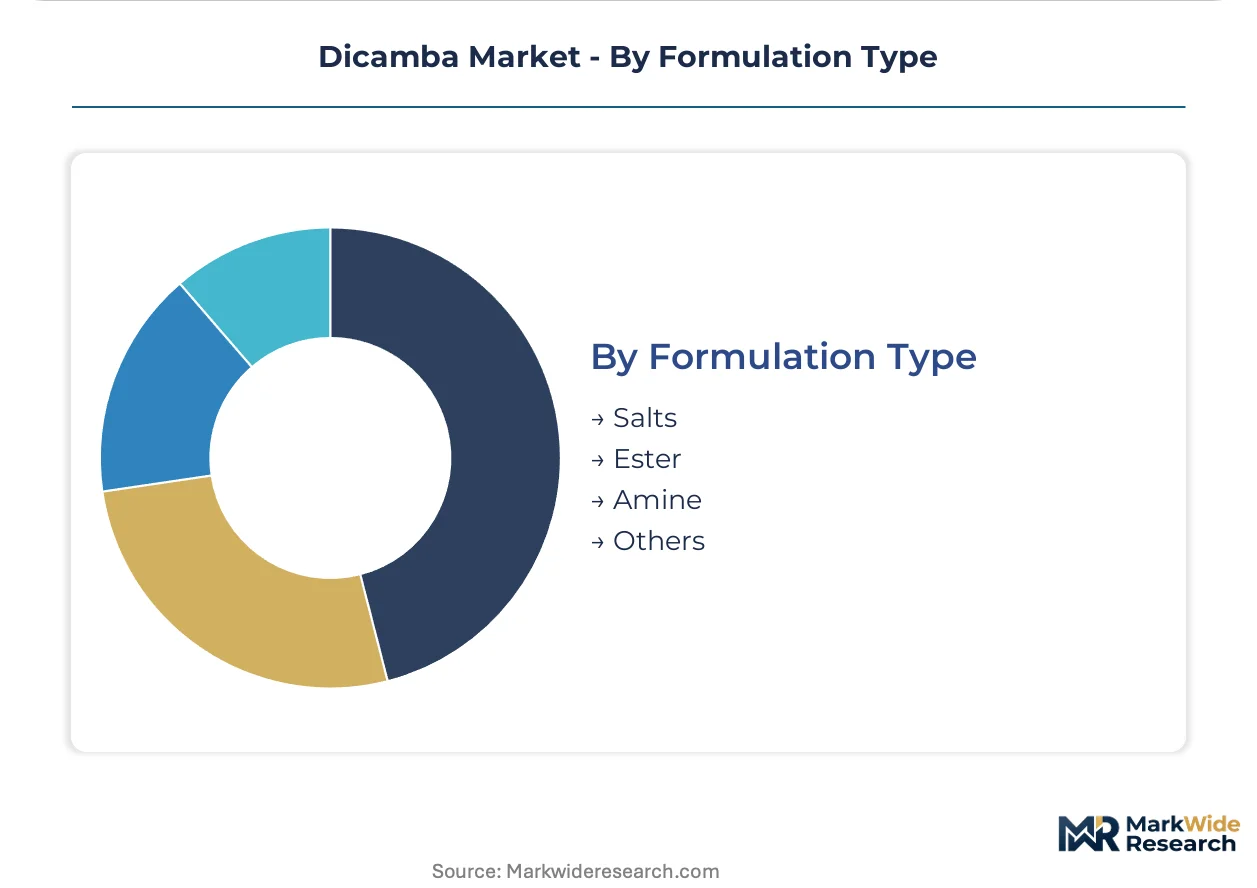
Formulation Type:
Margin structure concentrates in low-vapor-pressure chemistries as regulatory pressure renders legacy salt products obsolete.
- Salts:Diglycolamine and dimethylamine salt formulations dominating commercial registrations. Minnesota and Iowa operations have completed transitions to low-vapor-pressure diglycolamine variants ahead of mandatory dimethylamine phaseouts.
- Ester:Volatile organic compound formulations facing tightened restrictions across multiple jurisdictions.
- Amine:Water-soluble salt chemistry with established regulatory acceptance.
- Others:Experimental and niche formulation chemistries in development pipelines.
Salts command the dominant formulation share, with Amine climbing the fastest on regulatory stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River barge network and Gulf Coast export terminals underwrite North American dicamba distribution, connecting Midwest formulation plants to Brazilian and Argentine import markets.
United States
Dicamba-tolerant soybean acreage in Iowa, Illinois, and Indiana drives formulation demand. EPA volatility mitigation mandates under FIFRA compress application windows and elevate diglycolamine salt adoption. The St. Louis corridor anchors captive production for integrated seed-herbicide systems.
Brazil
Cerrado soybean and cotton expansion lags North American trait penetration by approximately five years. ANVISA registration pathways for low-vapor-pressure formulations offer first-mover positioning. Mato Grosso grain terminals concentrate import logistics for agrochemical distributors.
Canada
Prairie canola and soybean operations adopt dicamba-tolerant varieties for Group 2-resistant kochia management. Health Canada's PMRA imposes buffer zones mirroring EPA standards but with extended spring application windows. Winnipeg serves as the regulatory submission hub for North American label harmonization.
Argentina
Pampas grain belt soybean producers confront Palmer amaranth and waterhemp pressure in no-till systems. The national agricultural regulator SENASA evaluates diglycolamine salt registrations following Brazilian ANVISA precedents. Rosario export terminals link formulation imports to interior distribution networks.
Australia
Cotton and grain sorghum sectors in Queensland and New South Wales deploy dicamba for fleabane and sowthistle control. The Australian Pesticides and Veterinary Medicines Authority maintains stringent drift mitigation labeling. Brisbane formulation facilities serve Pacific island export markets.
Dicamba Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in salt chemistry and adjuvant supply. The vendor base concentrates around three integrated agrochemical majors with captive dicamba active ingredient capacity. Strategic archetypes include seed-herbicide bundlers, standalone formulation houses, and generic salt suppliers. Competitive moves center on multi-year grower contracting and co-formulation partnerships with residual herbicide developers.
Within the integrated platform tier, BASF SE, Bayer AG, and Corteva Agriscience exemplify divergent strategic positioning. BASF SE anchors its presence through specialized diglycolamine salt formulations engineered for reduced volatility profiles. Bayer AG occupies the system-integration position via captive supply chains linking dicamba-tolerant seed genetics to chemistry procurement. Corteva Agriscience represents portfolio breadth spanning amine and ester chemistries across multiple row-crop segments.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Corteva Agriscience |
| Syngenta Group |
| Nufarm Limited |
| ADAMA Ltd. |
| FMC Corporation |
| UPL Limited |
| Albaugh LLC |
| Others |
Supply Flow & Price Mechanics
Captive production of dicamba active ingredient at integrated agrochemical majors in the United States and Germany concentrates upstream supply, locking margin capture into seed-herbicide bundled systems and compressing pricing power for standalone generic formulators.
Pricing Analysis
EPA volatility mitigation mandates under FIFRA dictate the pricing tier structure across the dicamba market. Three-tier pricing structure across premium, standard, and economy levels separates diglycolamine salt formulations with full regulatory compliance from legacy dimethylamine products facing label restrictions and unbranded generic alternatives. Price differentiation hinges on formulation vapor pressure certification and bundled insurance coverage against off-target movement claims. Pricing pressure stems from glufosinate-tolerant seed systems capturing acreage in resistance management rotations. Commercial applicators serving fragmented Corn Belt landholdings exhibit highest price sensitivity due to insurance cost escalation, while integrated seed-chemistry platform adopters show lowest sensitivity through multi-season contracting.
Supply Chain Analysis
Extended payment terms from agrochemical distributors to custom applicators anchor working capital flows through the supply chain. Active ingredient manufacturing concentrates in the United States, Germany, and China. Formulation draws from specialized salt chemistry inputs, drift-reduction adjuvant systems, and precision application hardware. Single-source vulnerability sits with captive production at Bayer, BASF, and Corteva limiting merchant market availability during peak seasonal demand. Distribution runs through Midwest retail agronomists and cooperatives serving dicamba-tolerant soybean acreage in Iowa, Illinois, and Indiana.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against glufosinate and 2,4-D choline herbicide-tolerant seed platforms that threaten to displace dicamba-dependent acreage in resistance management rotations.
For Market Incumbents: Harden formulation chemistry moats through accelerated diglycolamine salt capacity expansion ahead of mandatory dimethylamine phaseouts. Deepen backward integration into specialized salt precursor supply to secure raw material access during peak seasonal demand windows. Lock in multi-season grower contracts bundling seed genetics, herbicide procurement, and off-target movement insurance to raise switching costs against glufosinate platform competitors. For New Entrants and Emerging Players: Establish a beachhead in Brazilian cerrado dicamba-tolerant cotton and soybean systems where trait penetration lags North American adoption by approximately five years. Target ANVISA registration pathways for low-vapor-pressure formulations ahead of integrated majors completing local label submissions. Pursue co-formulation partnerships with residual herbicide developers to extend control spectrum into mid-season weed flushes without requiring captive active ingredient capacity. For Investors and Strategic Acquirers: Capital is best deployed toward formulation houses with established diglycolamine salt expertise and ANVISA regulatory submission capabilities in Brazil. Long-term viability hinges on substitution risk mitigation through portfolio diversification beyond auxinic herbicides into glufosinate or 2,4-D systems. Watch state-level 24(c) special local need registration expansions in Arkansas and Illinois as inflection indicators for sustained dicamba utility in resistant weed management protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Salt Chemistry | Captive diglycolamine precursor supply secures formulation margins against raw material volatility. |
| ANVISA Registration Pathway Completion | Brazilian regulatory approval unlocks first-mover positioning in Cerrado soybean expansion zones. |
| Seed-Herbicide Insurance Bundling | Comprehensive resistance management guarantees shift margin capture from generics to integrated platforms. |
| Co-formulation with Residual Herbicides | Tank-mix compatibility with acetochlor extends commercial utility into mid-season application windows. |
| Precision Application Hardware Integration | Drift-reduction nozzle bundling with chemistry sales ensures EPA buffer zone compliance. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA registration databases, FIFRA label submissions, and state Department of Agriculture regulatory filings. Interviews with formulation chemists at agrochemical majors, retail agronomists in Iowa and Illinois, custom applicators in Indiana and Arkansas, and procurement leads at Midwest agricultural cooperatives provided demand-side validation. Secondary sources include SEC 10-K filings from listed agrochemical companies, ANVISA and PMRA regulatory submission records, and USDA planted acreage surveys. Bottom-up volume estimates from county-level seed adoption data triangulate against top-down active ingredient production capacity assessments.
Forecast inputs span formulation type adoption curves, seed trait penetration rates by state, regulatory phaseout timelines for high-vapor-pressure chemistries, and competing herbicide-tolerant platform acreage capture across the projection horizon. Segmentation dimensions modeled include product type, formulation chemistry, application method, and end-use sector with geographic granularity to state level in the United States and province level in Canada. CAGRs derive from logistic curve fitting of technology adoption patterns adjusted for regulatory constraint impacts. Specific inputs incorporate EPA volatility mandate compliance deadlines and Brazilian ANVISA registration pathway progression.
Sensitivities concentrate around EPA label restriction expansions, state 24(c) registration revocations, and accelerated glufosinate platform adoption in resistant weed management protocols. Forecasts reflect documented assumptions regarding seed trait introgression timelines and formulation chemistry transition rates. Macroeconomic commodity price collapse, unanticipated federal re-registration denials, or breakthrough non-chemical weed control technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Europe Seed Treatment Market
Crop Protection
Europe Fungicide Market
Crop Protection
Miticides Market
Crop Protection
Iprodione Market
Crop Protection
Nematicides Market
Crop Protection
Global Home and Garden Pesticides Market
Crop Protection
Fumigation Service Market
Crop Protection
Tebuconazole Epoxide Market
Crop Protection
Global Dicamba Herbicide Market
Crop Protection
Grain Fumigants Market
Crop Protection
Azoxystrobin Market
Crop Protection
US Insecticide Market
Crop Protection
Global Insecticides Market
Crop Protection
Vietnam Fungicide Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
Global Turf Protection Market