
 Argentina Crop Protection Chemicals Market | 2026-2036
Argentina Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Crop Protection Chemicals Market Outlook
Biological formulation technology is tilting R&D priorities toward microencapsulation and nano-delivery systems that improve active ingredient stability in variable climates. Syngenta Group leverages its global germplasm pipeline to bundle seed traits with proprietary chemistries. Bayer AG anchors its position through backward integration into glufosinate-ammonium production. FMC Corporation differentiates via selective herbicide portfolios tailored to no-till soybean rotations.
Crop protection chemicals comprise formulated biocidal products containing one or more active ingredients—typically synthesized organic molecules such as glyphosate, chlorpyrifos, or azoxystrobin—blended with surfactants, solvents, and stabilizers to control weeds, insects, or fungal pathogens in agricultural systems. These formulations function by disrupting cellular respiration, nervous system signaling, or cell wall biosynthesis in target organisms, thereby preserving yield potential across broadacre and specialty crop production. Herbicides command the largest value share within the product type dimension, reflecting Argentina's dominance in transgenic soybean and corn hectares where glyphosate-tolerant traits dominate. Foliar application modes are gaining share against soil-applied alternatives as farmers prioritize input timing flexibility and reduced pre-plant labor. Bio-pesticides remain nascent but attract capital as SENASA accelerates registration pathways for microbial and biochemical alternatives.
SENASA, Argentina's national agricultural health and quality service, enforces maximum residue limits aligned with Mercosur trade protocols and EU import standards, forcing exporters to maintain dual-compliance dossiers. The country's central bank and agricultural secretariat coordinate foreign exchange access for input imports, directly influencing product availability and pricing at the distributor level. Stakeholders must monitor evolving EU Green Deal pesticide reduction targets, as these extraterritorial standards cascade into Argentine export supply chains through buyer specifications and sanitary certifications.
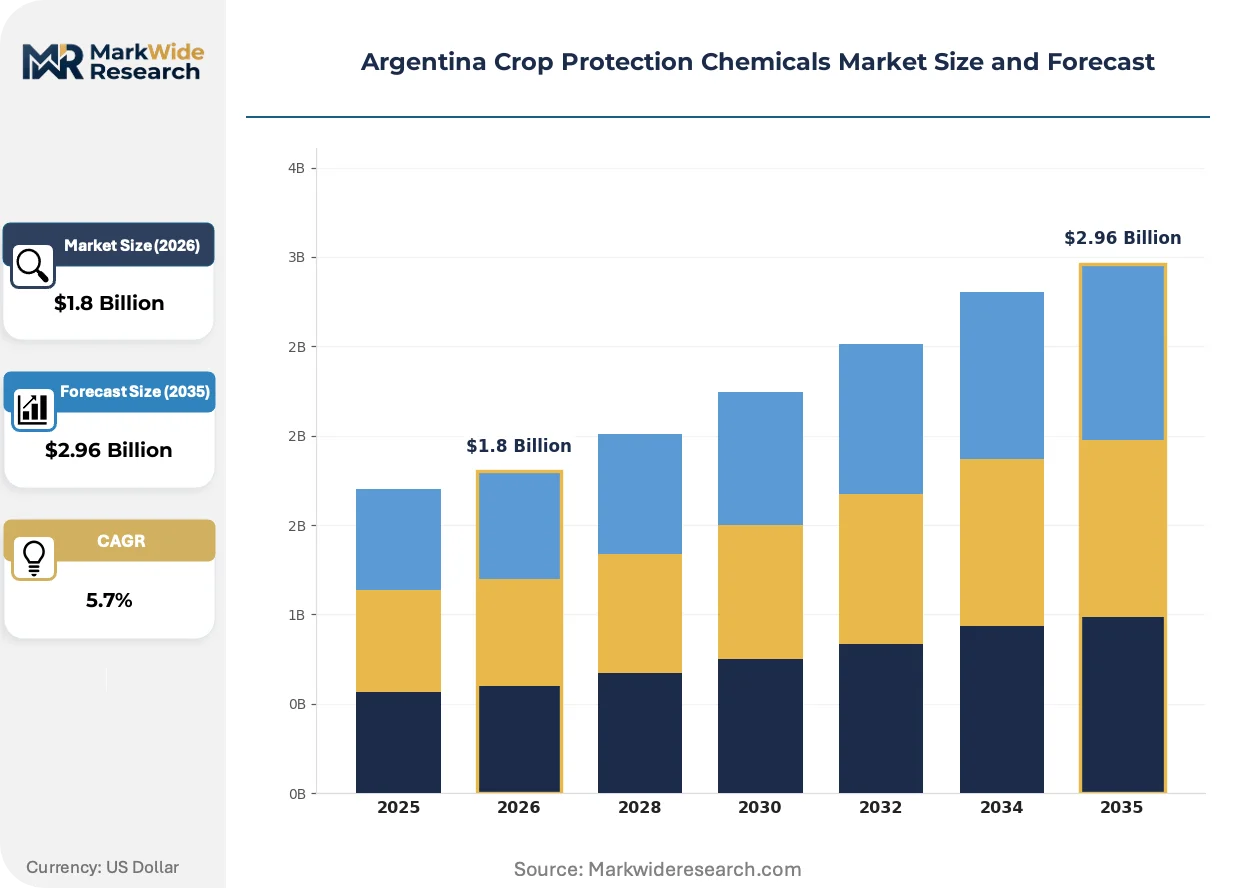
Market Dynamics
SENASA's accelerated maximum residue limit revisions are compressing product lifecycles across Argentina's Pampas grain belt, forcing manufacturers to reformulate active ingredient portfolios ahead of EU Green Deal compliance deadlines.
Growth Catalysts
- Integrated Pest Management Mandates:SENASA's technical guidelines for soybean and corn operations are institutionalizing biocontrol rotation protocols that expand addressable demand for selective chemistries.
- Export-Oriented Compliance Investment:Mercosur-EU trade alignment requirements are driving processing facilities to upgrade residue monitoring infrastructure, creating downstream pull for certified formulations.
- No-Till Expansion:Soil conservation practices across Buenos Aires and Córdoba provinces are elevating demand for pre-emergent herbicide systems compatible with reduced disturbance regimes.
Market Restraints
- Active Ingredient Import Dependency:Central bank foreign exchange rationing constrains access to Chinese-manufactured technical-grade glyphosate and 2,4-D precursors.
- Registration Timeline Compression:SENASA's shortened re-evaluation windows for existing registrations are elevating regulatory affairs overhead without proportional revenue protection.
- Biological Substitution Pressure:Bacillus thuringiensis and Trichoderma-based alternatives are capturing share in specialty crop segments with lower residue tolerance thresholds.
Strategic Opportunities
- Northern Extension Zones:Salta and Tucumán provinces present underdeveloped addressable markets for horticultural fungicide applications in expanding blueberry and avocado operations.
- Microencapsulation Convergence:Nano-delivery systems combined with climate-adaptive stabilizers are opening premium positioning for temperature-sensitive biological actives.
- Digital Distribution Infrastructure:Direct-to-farm platform models are bypassing traditional cooperatives in Santa Fe and Entre Ríos, capturing margin through disintermediation.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Argentina's universities produce insufficient surfactant and adjuvant specialists to staff expanding R&D facilities in Rosario and Pilar.
- Dual-Compliance Documentation Burden:Maintaining parallel residue dossiers for Mercosur and EU specifications is stretching quality assurance bandwidth at mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Crop Protection Chemicals Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Bio-Pesticides Application: Agricultural, Horticultural, Turf Management, Specialty Crops Mode of Action: Systemic, Contact, Soil-Applied, Foliar Active Ingredient: Glyphosate, Chlorpyrifos, Imidacloprid, Azoxystrobin |
| Companies Covered | Corteva Agriscience, FMC Corporation, Syngenta Group, Rainbow Agro, UPL Limited, Bayer AG, ADAMA Agricultural Solutions Ltd, Albaugh LLC, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Crop Protection Chemicals Market Strategic Shifts
Formulation science and regulatory architecture are converging to reshape competitive positioning, with stability engineering and compliance automation emerging as primary differentiation vectors.
Microencapsulation technology is hybridizing conventional synthetic actives with biological carriers to extend field persistence under Pampas humidity fluctuations. Large-scale soybean operations in Buenos Aires province are piloting these hybrid systems at scale. The approach is compressing the performance gap between synthetic reliability and biological compatibility, forcing incumbents to restructure product development pipelines.
SENASA's 2024 residue limit harmonization protocols with EU Regulation 396/2005 are mandating expanded analytical testing for export-bound grain. Processing cooperatives must now maintain third-party-certified laboratory capacity. The herbicide segment faces the steepest compliance cost escalation, with glyphosate-tolerant soybean supply chains absorbing the bulk of verification overhead.
Farmer purchasing behavior is fragmenting across channel types, with digital input platforms capturing share from legacy cooperative procurement systems. Younger operators in Córdoba and Santa Fe provinces are prioritizing price transparency and credit flexibility over established loyalty relationships. This behavioral shift is most pronounced in the 500-2,000 hectare mechanized segment, where operational autonomy preferences override collective bargaining incentives.
Argentina Crop Protection Chemicals Market Segmentation
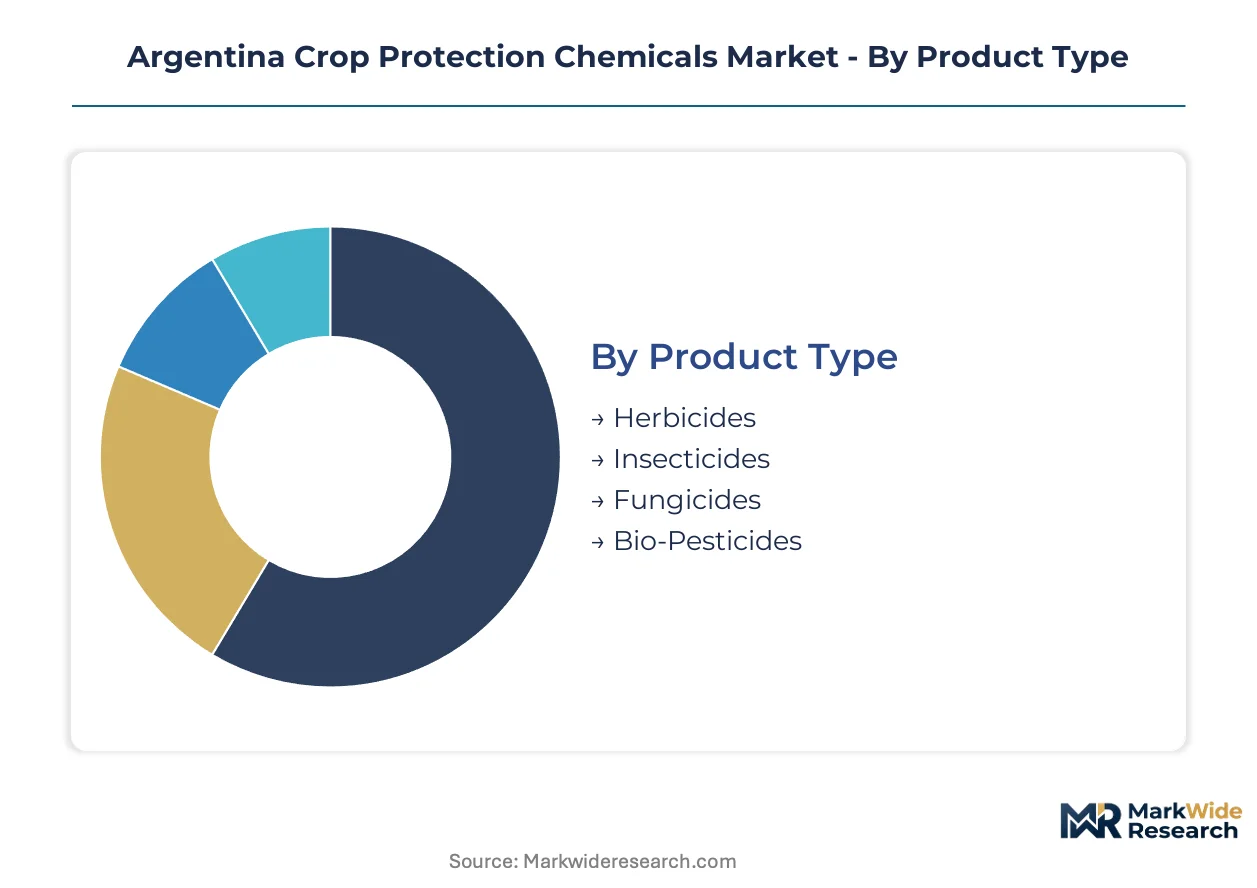
Segmentation in Argentina's crop protection market reveals how regulatory pressure and farming system evolution create divergent investment cycles across product categories. Understanding these velocity differences enables manufacturers to calibrate R&D spend against registration timelines and residue compliance windows.
Product Type:
Reformulation cycles vary dramatically across product types, with herbicide portfolios turning over fastest as SENASA accelerates maximum residue limit revisions while bio-pesticide registrations lag due to extended efficacy validation requirements.
- Herbicides:Formulated products containing glyphosate, glufosinate-ammonium, or selective active ingredients targeting weed competition in broadacre systems. Demand concentrates in Buenos Aires province's soybean-corn rotations where no-till adoption elevates pre-emergent system requirements. SENASA's tightened residue protocols are forcing 18-24 month reformulation cycles on export-bound formulations.
- Insecticides:Neurotoxic and growth-regulating chemistries including neonicotinoids and pyrethroids for lepidopteran and hemipteran control. Córdoba province's expanding corn hectares drive organophosphate and diamide demand, though EU import restrictions on chlorpyrifos residues are compressing usable product lifespans.
- Fungicides:Azole, strobilurin, and SDHI-based formulations protecting against soybean Asian rust and corn foliar diseases. Applications spike in humid Pampas seasons with variable efficacy windows.
- Bio-Pesticides:Microbial and biochemical alternatives derived from Bacillus thuringiensis, Trichoderma, and plant extracts. SENASA's streamlined registration pathway for low-risk substances is shortening time-to-market versus conventional chemistry.
Herbicides anchor the volume base while bio-pesticides gain share at the steepest rate.
Application:
Cost tier differentiation separates commodity broadacre systems from precision-intensive specialty operations, with input pricing power inversely correlated to farm scale and direct export exposure.
- Agricultural:Broadacre soybean, corn, and wheat production across the Pampas grain belt. Santa Fe and Entre Ríos provinces generate the highest absolute consumption volumes through mechanized cooperatives with centralized procurement.
- Horticultural:Intensive fruit and vegetable operations in Mendoza and San Juan valleys requiring residue-compliant formulations for EU and US export markets. Blueberry and cherry growers in northern Buenos Aires absorb premium-priced fungicide and insecticide systems.
- Turf Management:Golf course and sports field maintenance in Greater Buenos Aires and Córdoba metropolitan zones. Niche volume with elevated margin structures tied to aesthetic performance specifications.
- Specialty Crops:Avocado, olive, and nut production in emerging northern zones. Salta and Tucumán provinces present underdeveloped addressable markets with limited distribution infrastructure.
Agricultural applications dominate absolute spend while horticultural demand climbs fastest on export compliance investment.
Mode of Action:
Application method selection reflects labor cost trajectories and climate adaptation priorities, with foliar systems displacing soil-applied alternatives as timing flexibility gains value.
- Systemic:Translocated chemistries absorbed through roots or foliage and distributed throughout plant vascular systems. Glyphosate-tolerant soybean systems in Buenos Aires and La Pampa provinces depend on systemic herbicide reliability for volunteer corn and weed control.
- Contact:Surface-acting formulations requiring complete coverage for efficacy. Desiccation applications in pre-harvest soybean and sunflower operations favor paraquat and diquat contact modes despite restricted use protocols.
- Soil-Applied:Pre-plant or pre-emergent treatments incorporated into seedbeds for residual weed control. No-till expansion is compressing soil-applied share as post-emergent flexibility preferences strengthen.
- Foliar:Direct leaf and stem applications via ground or aerial equipment. Fungicide and insecticide demand is concentrating in foliar modes as farmers prioritize responsive timing against pest pressure fluctuations.
Systemic modes retain the largest installed base while foliar applications expand most quickly on operational flexibility premiums.
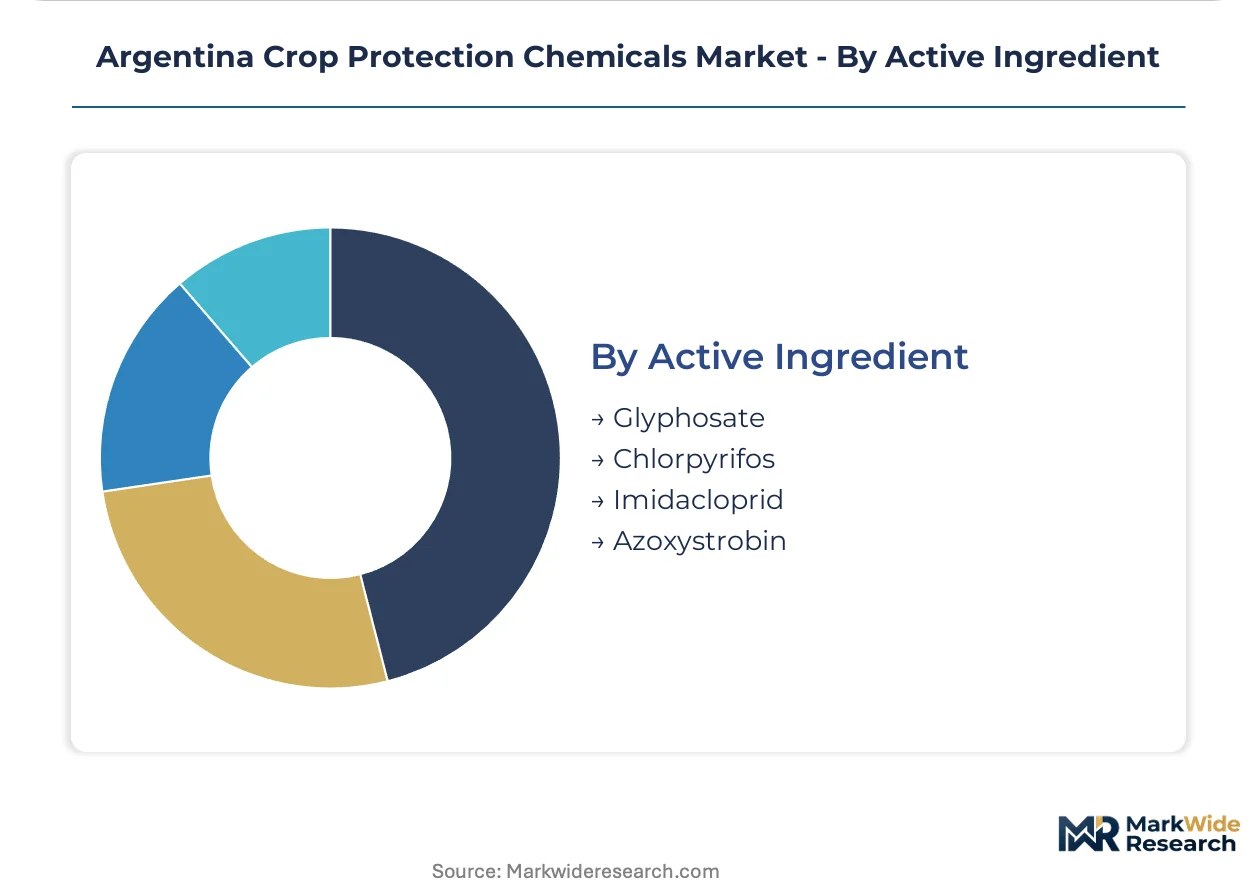
Active Ingredient:
Supply concentration and import dependency create divergent availability risks across active ingredient categories, with Chinese-manufactured technicals dominating high-volume herbicide inputs.
- Glyphosate:Broad-spectrum phosphonate herbicide inhibiting EPSP synthase in transgenic-tolerant cropping systems. Argentina's dependence on imported Chinese technical-grade material exposes formulation capacity to central bank foreign exchange rationing volatility.
- Chlorpyrifos:Organophosphate insecticide targeting acetylcholinesterase in soil-dwelling and foliar pests. EU and domestic residue restrictions are accelerating phase-out timelines despite continued corn rootworm demand in Córdoba.
- Imidacloprid:Neonicotinoid seed treatment and foliar insecticide with systemic distribution properties. Soybean aphid and white grub control in southern Pampas provinces sustains volume despite pollinator risk assessments.
- Azoxystrobin:Strobilurin fungicide disrupting mitochondrial respiration in Asian rust and Cercospora pathogens. Premium pricing in high-value export soybean segments supports margin despite resistance management rotation requirements.
Glyphosate anchors the volume base while azoxystrobin captures value expansion on fungicide resistance management protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's crop protection chemicals trade flows reflect a structural deficit in technical-grade active ingredient manufacturing, with formulation capacity concentrated in the Pampas grain belt while import dependency shapes regional supply security.
Buenos Aires Province
Soybean-corn rotations across the Humid Pampas generate the highest absolute herbicide consumption volumes in South America. SENASA's maximum residue limit protocols align with EU Regulation 396/2005, forcing exporters in the Bahía Blanca corridor to maintain certified laboratory infrastructure for glyphosate and 2,4-D verification.
Córdoba Province
Expanding corn hectares in the central sierras drive organophosphate and diamide insecticide demand for lepidopteran control. The provincial agricultural secretariat coordinates with SENASA on integrated pest management technical guidelines, accelerating biocontrol rotation adoption among cooperative members in the Marcos Juárez cluster.
Santa Fe Province
Mechanized cooperatives with centralized procurement dominate fungicide and foliar nutrient applications in the Rosario hinterland. The central bank's foreign exchange rationing directly constrains access to Chinese-manufactured technical-grade inputs, creating intermittent availability gaps at distributor warehouses in the port logistics zone.
Entre Ríos Province
Wheat-soybean double-cropping systems in the Paraná delta elevate demand for pre-emergent herbicide systems compatible with reduced tillage regimes. Digital input platforms are capturing procurement share from legacy cooperative channels among mid-scale operators in the Concordia production belt.
Salta and Tucumán Provinces
Emerging blueberry and avocado operations in northern valleys require residue-compliant fungicide and insecticide formulations for EU and US export markets. Limited distribution infrastructure and sparse technical support networks create underdeveloped addressable markets for horticultural chemical suppliers.
Argentina Crop Protection Chemicals Market Competitive Environment
On the supply side, the industry is consolidating around integrated multinational platforms with captive germplasm pipelines and backward-integrated active ingredient sourcing. Three strategic archetypes dominate: trait-chemistry bundlers leveraging proprietary seed platforms, selective herbicide specialists targeting no-till rotation systems, and generic technical-grade suppliers exposed to foreign exchange volatility. Competitive moves center on reformulation acceleration to meet compressed SENASA re-evaluation windows and microencapsulation technology licensing for climate-adaptive delivery systems.
Within the multinational tier, Bayer AG and Syngenta Group exemplify trait-chemistry integration models, while FMC Corporation occupies a position among selective herbicide specialists. BASF SE anchors the fungicide resistance management segment. Corteva Agriscience represents the germplasm-forward archetype with bundled input positioning. UPL Limited and ADAMA Agricultural Solutions Ltd sit within the generic technical-grade supplier category exposed to import dependency risks.
| Leading Market Players |
|---|
| Corteva Agriscience |
| FMC Corporation |
| Syngenta Group |
| Rainbow Agro |
| UPL Limited |
| Bayer AG |
| ADAMA Agricultural Solutions Ltd |
| Albaugh LLC |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
The Bahía Blanca-Rosario freight corridor's volatile trucking and rail costs compress margin structures for glyphosate distributors serving Buenos Aires province's soybean belt, concentrating pricing power among backward-integrated multinationals while fragmenting procurement options for cooperative buyers dependent on Chinese technical-grade imports.
Pricing Analysis
Next-generation microencapsulation formulations command 40-60% premiums over conventional emulsifiable concentrates, while legacy organophosphate chemistries face accelerating price erosion. The market operates on a contract-based long-term offtake model anchored to grain futures, with price differentiation driven by SENASA certification tier and volume scale. Pricing pressure stems from central bank foreign exchange rationing constraining import access. Smallholder operators in northern provinces exhibit highest price sensitivity, while export-oriented horticultural growers in Mendoza absorb premium fungicide systems with minimal elasticity.
Supply Chain Analysis
Extended payment terms from Chinese technical-grade manufacturers—now stretching 90-120 days—are straining working capital for Argentine formulation plants in Pilar and Rosario. Supply concentrates in China for glyphosate and 2,4-D precursors, with India and Germany contributing specialty surfactant intermediates. Raw material dependencies include phosphonate herbicide technicals, petroleum-derived solvents, and climate-stabilizer adjuvants. Single-source vulnerability from Shanghai port congestion creates intermittent stockouts. Distribution runs through cooperative procurement hubs in Santa Fe and Entre Ríos, with digital platforms capturing share among mid-scale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's crop protection sector sits in early-cycle expansion as SENASA's streamlined bio-pesticide registration pathway accelerates penetration of microbial alternatives in export-oriented horticultural segments.
For Market Incumbents: Build regulatory data moats by pre-positioning residue dossiers ahead of EU Green Deal compliance deadlines. Bayer AG and Syngenta Group should deepen backward integration into glufosinate-ammonium production to offset foreign exchange rationing exposure. Channel control through exclusive distribution agreements with Santa Fe cooperatives defends against digital platform disintermediation threatening legacy procurement relationships. For New Entrants and Emerging Players: Salta province's underdeveloped blueberry fungicide market offers white-space penetration with limited incumbent technical support infrastructure. Tucumán's expanding avocado hectares present parallel opportunity for residue-compliant insecticide systems. A direct-to-farm digital platform model—bypassing cooperative markups—captures margin among 500-2,000 hectare operators in Córdoba prioritizing price transparency over loyalty relationships. For Investors and Strategic Acquirers: Formulation specialists with captive microencapsulation IP represent priority acquisition targets as climate-adaptive delivery systems displace conventional chemistries. Long-term viability hinges on SENASA registration velocity and EU trade alignment durability. Monitor SENASA's re-evaluation window compression as inflection signal for regulatory affairs overhead escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredients | Bayer AG's captive glufosinate-ammonium production insulates margin from central bank foreign exchange volatility. |
| Microencapsulation Technology Licensing | Climate-adaptive delivery systems extend field persistence under Pampas humidity fluctuations for biological actives. |
| Dual-Compliance Certification Investment | Parallel Mercosur-EU residue dossiers unlock premium positioning in export-bound grain supply chains. |
| Digital Distribution Platform Buildout | Direct-to-farm models capture procurement share from legacy cooperatives in Santa Fe and Entre Ríos. |
| Northern Extension Zone Market Development | Salta and Tucumán horticultural operations present underdeveloped addressable markets for fungicide suppliers. |
Study Parameters
A standing panel of SENASA regulatory affairs directors, cooperative procurement managers in Santa Fe, formulation plant managers in Rosario, and horticultural export operators in Mendoza provided ongoing calibration against secondary validation from customs trade data, SENASA registration filings, SEC 10-K agricultural chemical disclosures, and ACC/Cefic regional reports. Primary interviews with distribution channel partners and technical R&D directors at Pilar facilities combined with bottom-up volume triangulation against top-down trade flow analysis.
Scenario-bracketing around EU Green Deal implementation velocity and central bank foreign exchange policy generated bounded projections across the analysis window. Segmentation dimensions modeled include product type, application mode, geographic production cluster, and SENASA compliance tier. CAGRs derived from historical volume trajectories adjusted for registration timeline compression and no-till adoption curves. Industry-specific inputs incorporated glyphosate-tolerant trait penetration rates and Asian rust pressure indices.
Practitioners should monitor SENASA re-evaluation window announcements and EU Regulation 396/2005 amendment schedules for early signals of regulatory burden shifts. Forecasts reflect documented assumptions on trade alignment durability and biological substitution velocity. Macroeconomic deviation in foreign exchange policy, regulatory acceleration beyond modeled timelines, or technological breakthrough in RNA-interference crop protection would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Soybean Fungicide Seed Treatment Market
Crop Protection
North America Crop Protection Chemicals Market
Crop Protection
Europe Fungicide Market
Crop Protection
Asia-Pacific Acaricides Market
Crop Protection
Global Phosphine Fumigation Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
Vietnam Herbicide Market
Crop Protection
Generic Crop Protection Chemicals Market
Crop Protection
Canada Nematicides Market
Crop Protection
Pest Control Market
Crop Protection
Tembotrione Market
Crop Protection
Phytogenic Poultry Feed Additives Market
Crop Protection
Rodent Control Pesticides Market
Crop Protection
Global Algaecides Market
Crop Protection
Europe Molluscicides Market
Crop Protection
Germany Crop Protection Chemicals Market