
 Irrigation Liner Market | 2026-2036
Irrigation Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Irrigation Liner Market Insights
North American geomembrane producers is expanding manufacturing footprints to serve irrigation infrastructure renewal across the western United States. BTL Liners leverages vertical integration in custom fabrication to anchor premium project contracts. Raven Industries competes through advanced polymer R&D for UV-resistant agricultural membranes. Layfield Group dominates distribution networks across the Canadian prairie provinces.
An irrigation liner is a synthetic membrane barrier, typically manufactured from polyethylene, PVC, EPDM, or HDPE in thicknesses ranging from 20 mil to 80 mil, engineered to prevent water seepage from canals, reservoirs, and on-farm conveyance systems. The primary commercial purpose is to reduce water loss in agricultural distribution networks where unlined earthen channels can lose 30-50% of conveyed volume to infiltration. HDPE formulations command the largest volume share due to chemical resistance and weldability for large-scale canal projects. Agricultural applications generate the dominant revenue pool, though golf course installations are expanding fastest as turf managers face municipal water restrictions. Heavy duty thickness grades capture the majority of margin dollars because installation labor costs make material failure prohibitively expensive.
The EPA enforces Clean Water Act provisions that limit agricultural runoff and seepage into groundwater tables, directly shaping liner specifications for federally funded water projects. ASTM D7176 governs HDPE geomembrane manufacturing standards, while ISO 10318 provides international classification for geosynthetics used in fluid containment. State water boards in California, Texas, and Colorado administer additional permitting requirements that dictate minimum liner thickness and seam testing protocols for new irrigation district infrastructure. Stakeholders must monitor how drought contingency planning at the state level reshapes capital allocation priorities for conveyance efficiency investments.
Market Dynamics
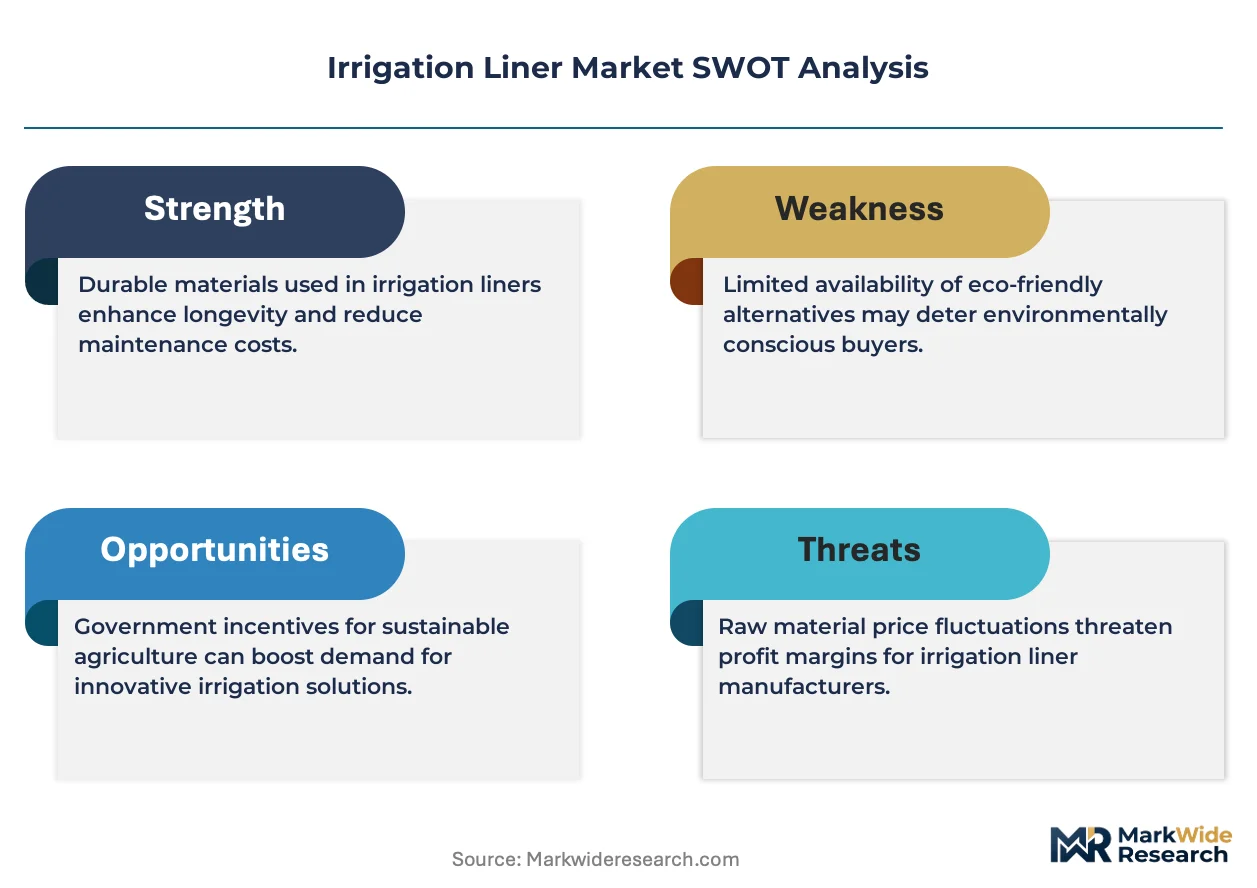
Water scarcity enforcement is compressing installation timelines for conveyance infrastructure across agricultural districts, forcing irrigation authorities to accelerate liner deployment before seasonal planting windows close.
Growth Catalysts
- Clean Water Act tightening:EPA enforcement of permissible leakage rates for federally funded water projects is mandating lined canal specifications in California's Central Valley and Texas High Plains irrigation districts.
- Drought resilience mandates:Australia's Murray-Darling Basin water recovery programs are channeling capital toward seepage reduction infrastructure for permanent horticulture plantings.
- HDPE weldability advances:Automated hot-wedge seaming equipment is enabling faster field installation of large-scale canal geometries, reducing project labor hours.
Market Restraints
- Petrochemical feedstock volatility:Ethylene and propylene price swings directly compress HDPE and PVC liner margins, forcing producers to carry inventory risk or pass costs to municipal buyers with fixed budgets.
- Installation labor scarcity:Certified geomembrane welders concentrate in the US Mountain West and Alberta, creating bottlenecks for simultaneous multi-site district projects.
- Earthen channel persistence:Unlined dirt canals remain cost-competitive for low-value field crops in regions without volumetric water pricing, delaying liner adoption.
Strategic Opportunities
- Sub-Saharan Africa irrigation expansion:Ethiopia's Awash Valley and Kenya's Tana River Basin are developing lined distribution networks for commercial farming zones with development finance backing.
- Golf course water restrictions:Municipal conservation ordinances in Arizona, Nevada, and Colorado are mandating impermeable reservoir and canal systems for turf irrigation.
- Smart liner integration:Embedding fiber-optic leak detection sensors during HDPE installation is creating premium service contracts for canal monitoring.
Industry Challenges
- ASTM D7176 seam certification backlog:Third-party testing laboratories face month-long queues for destructive weld sample analysis, delaying project commissioning.
- Legacy earthen channel integration:Retrofitting liners into existing canal geometries requires custom fabrication and field cutting that extends installation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Irrigation Liner Market |
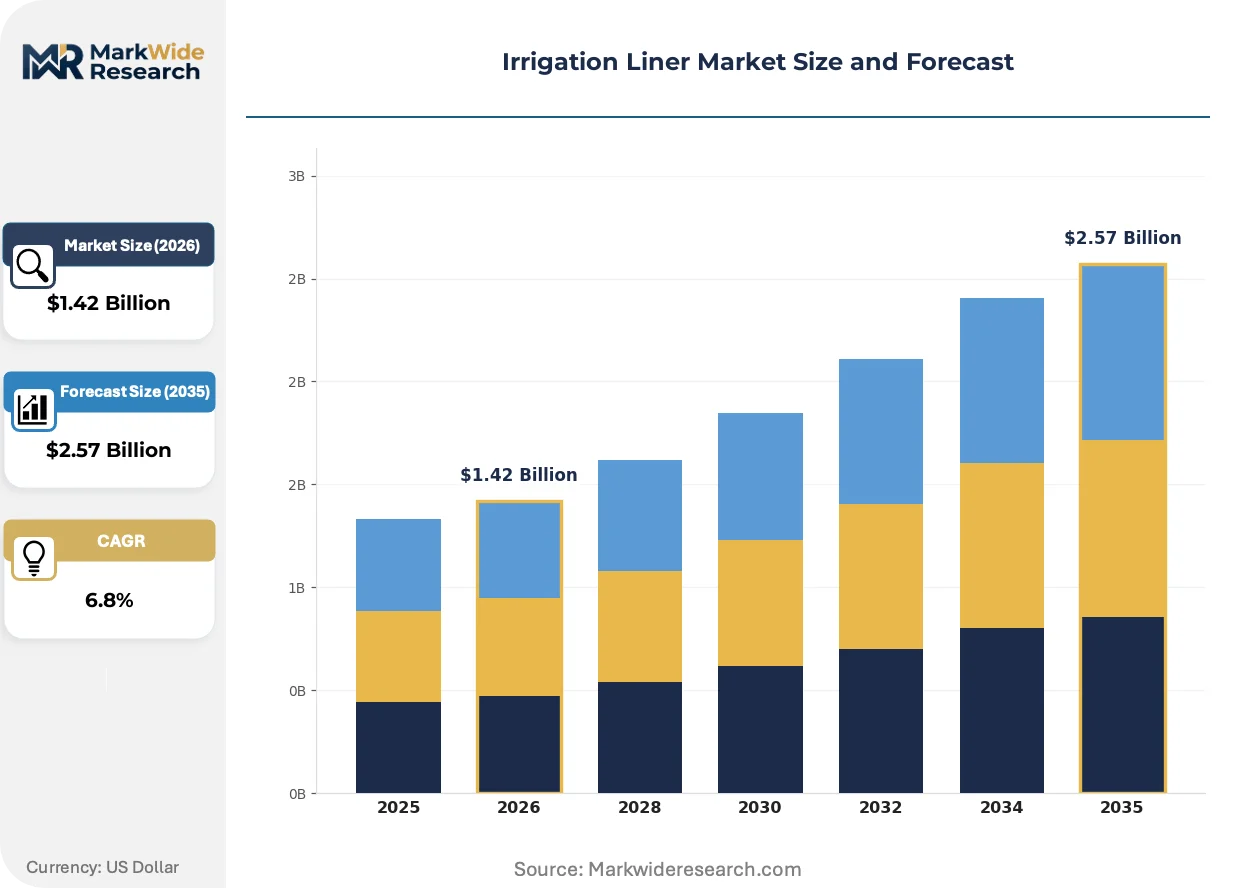
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, PVC, EPDM, HDPE Application: Agricultural, Horticultural, Landscape, Golf Courses Thickness: Heavy Duty, Medium Duty, Light Duty, Ultra Heavy Size: Standard Roll, Custom Roll, Sheet, Panel |
| Companies Covered | BTL Liners, Western Ag Enterprises, Raven Industries, Layfield Group, Fast Ditch, Linerfit Irrigation, Netafim Ltd, Rivulis Pte. Ltd., Valmont Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Irrigation Liner Market Trends and Innovations
Material science advances and digital monitoring integration are redefining performance expectations for agricultural fluid containment, shifting buyer criteria from basic impermeability toward predictive durability metrics.
Co-extruded HDPE geomembranes with carbon black dispersion layers and conductive inner skins are modularizing quality assurance workflows for large canal projects. Agricultural water districts in California and Colorado are specifying these formulations for automated spark testing of seam integrity. The technology is modularizing field verification protocols, compressing commissioning timelines from weeks to days while reducing reliance on destructive sample testing.
REACH restrictions on phthalate plasticizers are forcing PVC liner reformulation across European irrigation infrastructure programs. Manufacturers serving Spain's Ebro Basin and Italy's Po Valley are accelerating migration to bio-based plasticizer alternatives ahead of 2025 compliance deadlines. The regulatory pressure is elevating HDPE market share in Mediterranean agricultural districts previously dominated by flexible PVC.
Performance-based liner procurement is displacing lowest-bid specifications in Australian and US western state tenders. Water authorities now contract for guaranteed seepage rates over 20-year operational lifespans, transferring material degradation risk to manufacturers. This model concentrates contract awards among producers with vertical fabrication control and in-house polymer testing laboratories.
Irrigation Liner Market Segmentation
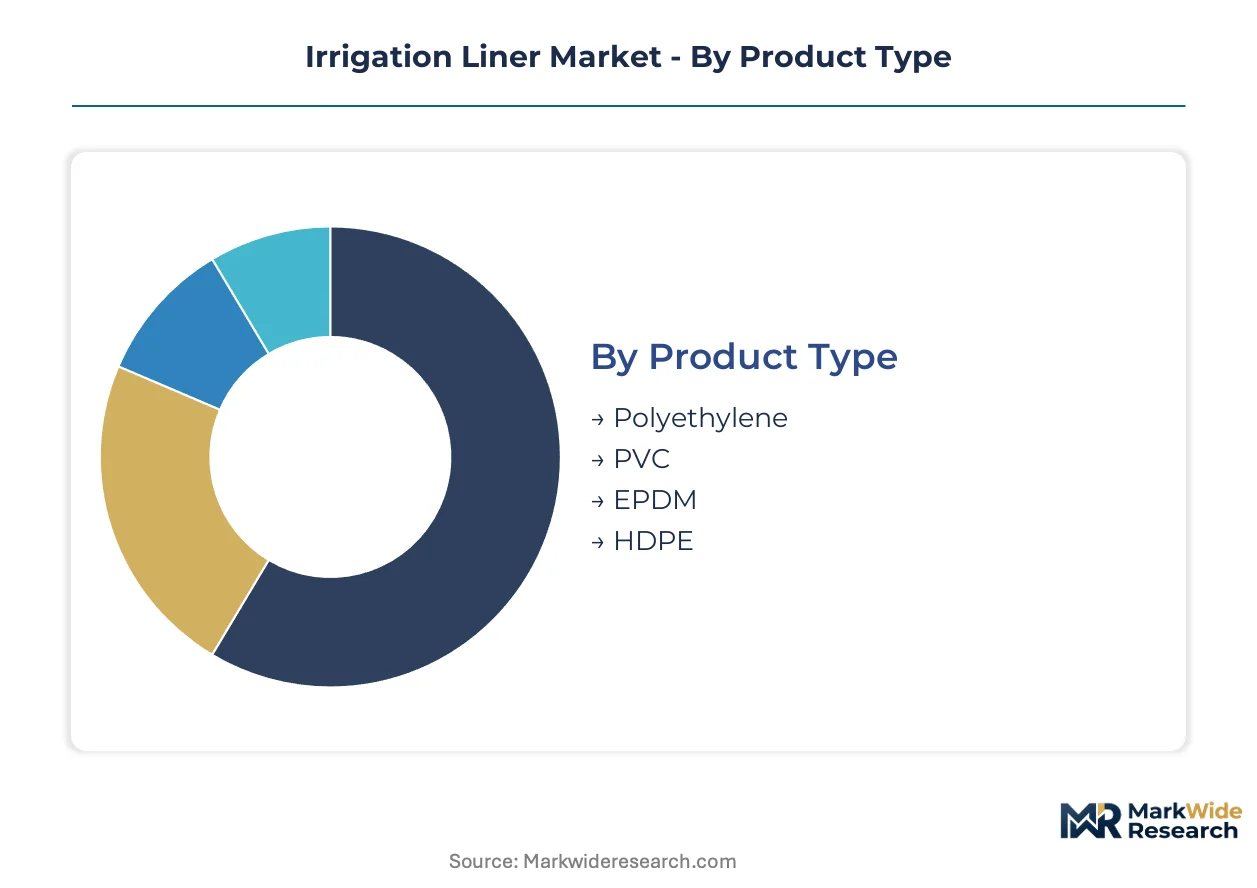
Material specifications and installation geometries diverge sharply across irrigation infrastructure deployments. Canal operators, reservoir managers, and turf irrigation specialists each impose distinct performance thresholds that reshape liner procurement criteria.
Product Type:
Customization intensity spans from commodity-grade formulations to engineered multi-layer systems with embedded quality assurance features.
- HDPE:High-density polyethylene dominates large-scale canal projects through superior chemical resistance and automated hot-wedge weldability. California's Central Valley irrigation districts specify HDPE for federally funded conveyance upgrades under tightening EPA Clean Water Act enforcement.
- Polyethylene:Linear low-density formulations serve cost-sensitive farm reservoir applications where flexibility and foldability reduce field handling labor. Demand concentrates in Australia's Murray-Darling Basin drought resilience programs prioritizing rapid deployment timelines.
- PVC:Flexible vinyl membranes retain share in golf course and landscape applications requiring complex geometric fitting around existing infrastructure. REACH phthalate restrictions in Europe are accelerating reformulation toward bio-based plasticizer alternatives.
- EPDM:Ethylene propylene diene monomer rubber excels in extreme temperature cycling environments and puncture-prone rocky subgrades. Installations persist in high-altitude Andean irrigation zones and Nordic agricultural districts.
Most installed capacity flows through HDPE formulations. Expansion is steepest in co-extruded conductive-layer HDPE enabling automated spark testing.
Application:
End-use economics range from volumetric water pricing sensitivity in commodity agriculture to aesthetic performance premiums in recreational turf management.
- Agricultural:Canal and reservoir lining for field crop and permanent horticulture operations generates the dominant revenue pool. Specialty crop growers in California and Texas High Plains are scaling lined systems to reduce seepage losses under state water board enforcement.
- Golf Courses:Municipal water restrictions in Arizona, Nevada, and Colorado are mandating impermeable conveyance and storage systems for turf irrigation. Turf managers face escalating penalties for unaccounted water losses.
- Horticultural:Nursery and greenhouse operations require liner systems compatible with fertigation chemistries and elevated UV exposure in controlled environments.
- Landscape:Commercial and residential water feature installations prioritize aesthetic integration and rapid deployment over multi-decade service life.
Agricultural deployments absorb the majority of material tonnage. Golf course mandates are climbing the fastest as municipal conservation ordinances tighten.
Thickness:
Grade selection trades material cost against failure consequence severity, with labor economics heavily favoring over-specification.
- Heavy Duty:60-80 mil specifications dominate commercial canal projects where installation labor costs dwarf material expense and failure triggers catastrophic crop loss. Water authorities in Australia's Murray-Darling Basin specify heavy duty grades for 20-year performance guarantees.
- Medium Duty:40-60 mil range serves farm-scale reservoirs and secondary conveyance where access for repair remains feasible.
- Light Duty:20-40 mil applications concentrate in temporary or seasonal installations with limited service life requirements.
- Ultra Heavy:80+ mil specialty grades address high-pressure containment, rocky subgrades, and wildlife damage risk in remote infrastructure.
Heavy duty grades command the majority of margin dollars. Ultra heavy specifications are gaining share fastest in performance-based procurement contracts transferring degradation risk to manufacturers.
Size:
Supply chain configuration ranges from inventory-intensive standard rolls to project-specific fabrication with extended lead times.
- Standard Roll:Pre-manufactured widths and lengths enable rapid fulfillment for recurring farm reservoir dimensions. Distributors across the Canadian prairie provinces maintain standard roll inventory for seasonal demand surges.
- Custom Roll:Project-specific widths reduce field seaming labor in large canal geometries. Automated fabrication lines in US Mountain West facilities serve irrigation district renewal programs.
- Sheet:Flat stock formats support on-site cutting for irregular reservoir perimeters and retrofit applications.
- Panel:Pre-fabricated modular sections with factory-welded seams accelerate installation in constrained seasonal windows.
Standard rolls move the highest volume throughput. Custom fabrication is expanding most quickly as district-scale projects prioritize labor reduction over material premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Geomembrane fabrication migrates toward jurisdictions with streamlined environmental permitting and lower polymer processing energy costs. Manufacturers exploit regulatory-arbitrage gaps between EPA-monitored US facilities and less stringent emerging-market jurisdictions. This spatial sorting concentrates HDPE liner supply in Alberta's petrochemical corridor and Australia's industrial southeast.
United States
California's Central Valley irrigation districts deploy HDPE liners under EPA Clean Water Act enforcement tightening permissible seepage rates. State water boards mandate ASTM D7176-compliant specifications for federally funded conveyance projects. Fabrication clusters in the US Mountain West serve district-scale renewals across Colorado River Basin states.
Australia
Murray-Darling Basin water recovery programs channel capital toward seepage reduction infrastructure for permanent horticulture. The country's national agricultural regulator enforces volumetric accounting that penalizes unlined canal losses. Manufacturing concentrates in Victoria's industrial corridor to serve drought resilience investments across southeastern catchments.
Canada
Alberta's petrochemical complex supplies HDPE resin to prairie irrigation districts facing seasonal water allocation constraints. Provincial environmental regulators administer liner specifications for district infrastructure receiving federal agriculture ministry funding. Distribution networks across Saskatchewan and Manitoba maintain seasonal inventory for spring installation windows.
Spain
Ebro Basin irrigation cooperatives retrofit PVC liners ahead of REACH phthalate plasticizer restrictions taking effect in 2025. The country's national chemical safety regulator accelerates compliance timelines for agricultural fluid containment. Manufacturing activity clusters in Catalonia to serve Mediterranean horticulture zones transitioning to bio-based plasticizer formulations.
Ethiopia
Awash Valley commercial farming zones develop lined distribution networks with development finance institution backing. The country's national water resources regulator establishes technical standards for foreign-funded irrigation infrastructure. Installation activity concentrates around sugar estate expansions in the Rift Valley where seepage control underpins crop yield guarantees.
Irrigation Liner Market Competitive Landscape
North American producers anchor the high-specification tier; European and Asia-Pacific specialists hold reformulation and cost-optimized segments. The vendor base separates into three functional tiers: integrated resin-to-fabrication operators, regional custom fabricators, and distribution-focused intermediaries. Consolidation pressures concentrate among mid-scale fabricators lacking captive polymer supply or automated seaming equipment. Competitive dynamics center on backward integration into resin compounding and geographic expansion into drought-stressed agricultural districts.
Among North American fabricators, BTL Liners, Raven Industries, and Layfield Group occupy distinct positioning vectors. BTL Liners exemplifies the vertically integrated archetype with in-house custom fabrication capabilities. Raven Industries represents the advanced materials R&D positioning, while Layfield Group anchors distribution network dominance across Canadian prairie provinces. These three entities collectively illustrate how scale, specialization, and channel control partition available contract value across the irrigation infrastructure value chain.
| Leading Market Players |
|---|
| BTL Liners |
| Western Ag Enterprises |
| Raven Industries |
| Layfield Group |
| Fast Ditch |
| Linerfit Irrigation |
| Netafim Ltd |
| Rivulis Pte. Ltd. |
| Valmont Industries, Inc. |
| Others |
Pricing and Supply Chain Analysis
Backward integration into HDPE resin compounding anchors pricing power for North American geomembrane producers serving western US irrigation districts. Captive polymer supply insulates integrated fabricators from ethylene feedstock volatility while forcing non-integrated competitors to absorb margin compression or cede share on municipal tenders with fixed budgets.
Pricing Analysis
Distributor margins concentrate value capture in the Canadian prairie provinces where Layfield Group's network controls last-mile access to seasonal installation windows. Project-based contract pricing dominates large canal renewals in California and Texas, with price differentiation driven by ASTM D7176 certification tier and guaranteed seepage rate performance over operational lifespans. Cost compression in standard-grade polyethylene reservoir liners is intensifying because Australian Murray-Darling Basin water authorities are consolidating procurement volumes. Commodity field crop growers exhibit highest price sensitivity, while specialty horticulture operators in permanent plantings accept premium specifications.
Supply Chain Analysis
Single-source vulnerability sits with Alberta's petrochemical corridor, where three HDPE resin plants feed continental geomembrane fabrication. Raw material flows draw from ethylene crackers, carbon black masterbatch suppliers, and automated hot-wedge seaming equipment manufacturers concentrated in the US Mountain West. Tariff exposure on Chinese-manufactured conductive-layer co-extrusion lines elevates equipment procurement risk for capacity expansion. Distribution runs through project-specific custom fabrication with extended lead times for large canal geometries, alongside standard roll inventory held by prairie distributors for seasonal farm reservoir demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Performance-based procurement contracts in Australia and US western states are shifting demand toward premium HDPE formulations with embedded leak detection and 20-year degradation guarantees.
For Market Incumbents: Lock in ASTM D7176 certification capacity ahead of third-party testing laboratory backlogs extending project commissioning timelines. Deepen captive resin supply through offtake agreements with Alberta petrochemical operators to defend margin position against ethylene price volatility. Channel control through automated fabrication investments in the US Mountain West secures district-scale renewal contracts where labor economics favor custom roll specifications over standard inventory.
For New Entrants and Emerging Players: Sub-Saharan Africa irrigation expansion presents the most penetrable white-space target, with Ethiopia's Awash Valley and Kenya's Tana River Basin developing lined distribution networks under development finance institution backing. Golf course mandates in Arizona, Nevada, and Colorado offer secondary entry through municipal water restriction compliance where turf managers face escalating penalties for unaccounted losses. Partner with regional EPC contractors possessing certified geomembrane welder networks to overcome installation labor scarcity bottlenecks.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale custom fabricators lacking automated seaming equipment because consolidation captures district-scale contract flows and compresses field installation labor costs. Target entities with in-house polymer testing laboratories positioned for performance-based procurement growth. Watch EPA Clean Water Act enforcement intensity as the inflection signal; tightening permissible leakage rates accelerate replacement demand for aging earthen infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive ethylene supply insulates margins from petrochemical volatility in Alberta corridor. |
| Automated Hot-Wedge Seaming Equipment Deployment | Automated welding compresses project labor hours for California Central Valley canal geometries. |
| Conductive-Layer HDPE Formulation Launch | Spark-testable membranes command premium positioning in Australian performance-based tenders. |
| Custom Fabrication Capacity Expansion | Project-specific roll widths reduce field seaming for Colorado River Basin district renewals. |
| Fiber-Optic Leak Detection Integration | Embedded sensor systems create recurring service contracts for Murray-Darling Basin water authorities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged HDPE geomembrane fabrication plant managers, irrigation district procurement officers in California and Texas, certified geomembrane welders concentrated in the US Mountain West and Alberta, and municipal water authority engineers in Arizona and Nevada. Secondary validation incorporated EPA enforcement action databases, ASTM D7176 certification records, state water board permitting filings in California and Colorado, Australian Bureau of Agricultural and Resource Economics irrigation investment data, and customs trade statistics for HDPE geomembrane imports. Bottom-up project pipeline enumeration triangulated against top-down polymer consumption estimates across agricultural applications.
Historical reference periods anchored volume and value trajectories across the modeling period, with segmentation dimensions spanning material formulation, thickness grade, installation geometry, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to disclosed capital expenditure flows and drought contingency planning timelines. Key forecast inputs included EPA Clean Water Act enforcement intensity indices and Murray-Darling Basin water recovery program allocation schedules.
Underlying measurement precision varies by segment; heavy duty HDPE canal specifications carry tighter precision than light duty farm reservoir applications due to concentrated procurement transparency in district-scale tenders. Forecasts reflect assumptions around petrochemical feedstock cost trajectories and certified welder labor availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Drip Irrigation Systems Market
Farm Equipment and Irrigations
Global Mechanized Irrigation Systems Market
Farm Equipment and Irrigations
South America Irrigation Machinery Market
Farm Equipment and Irrigations
Agricultural Solar Pumps Market
Farm Equipment and Irrigations
Australia Irrigation Automation Market
Farm Equipment and Irrigations
Zero Turn Mowers Market
Farm Equipment and Irrigations
Greenhouse Irrigation Systems Market
Farm Equipment and Irrigations
Global Fruit Picker Market
Farm Equipment and Irrigations
Asia Pacific Irrigation Valves Market
Farm Equipment and Irrigations
China Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Irrigation Controllers Market
Farm Equipment and Irrigations
Asia-Pacific Irrigation Machinery Market
Farm Equipment and Irrigations
Golf Irrigation Market
Farm Equipment and Irrigations
Africa Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
North America Agricultural Tires Market
Farm Equipment and Irrigations
Solar Powered Irrigation System Market