
 Crop Protection Chemicals Market | 2026-2036
Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Crop Protection Chemicals Market Intelligence
The consolidation of large-scale commercial farms into fewer, larger agricultural enterprises is rebalancing purchasing power within the supply chain. Bayer CropScience leverages its extensive portfolio of patented active ingredients to secure contracts with these key accounts. Syngenta Group competes by offering integrated chemical and biological solutions for specific agronomic challenges. BASF SE sustains its position through significant R&D investment in novel herbicide and fungicide formulations.
Crop protection chemicals are formulations containing one or more active ingredients designed to control or eliminate agricultural pests, weeds, and diseases. These substances, often supplied as emulsifiable concentrates, function by disrupting the life cycle of target organisms. Herbicides constitute the largest product segment, driven by use in large-acreage crops like cereal grains and oilseeds. The fungicides segment for high-value fruits and vegetables represents a fast-growing application due to consumer demand for quality produce.
The regulatory landscape is defined by bodies like the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA) under REACH. These agencies, along with China's Ministry of Ecology and Environment (MEE), set stringent limits on active ingredient residues and environmental persistence, influencing product registrations. Future success depends on developing solutions that meet both pest resistance challenges and tightening environmental standards.
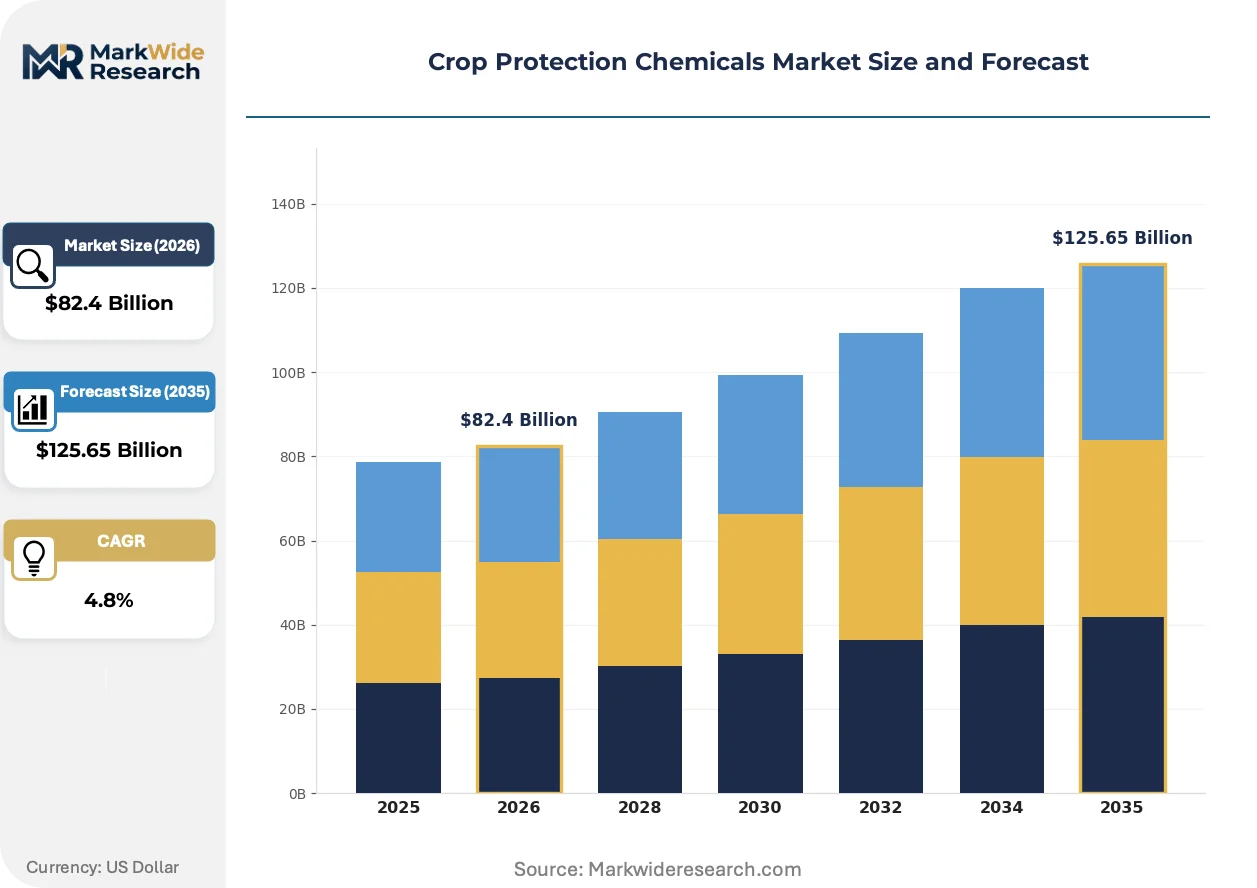
Market Dynamics
The market's central tension lies between the agricultural imperative for higher yields in staple crops and mounting regulatory pressure for sustainability. This dynamic, exemplified by the EU Green Deal, is forcing a fundamental pivot in active ingredient discovery and formulation strategies across the industry.
Growth Catalysts
- Expanding Agricultural Frontiers:Brazil's continued expansion of land for soy and corn cultivation drives significant volume demand for herbicides and insecticides to manage pests in newly developed areas.
- Food Quality Standards:Consumer and retail demand for aesthetically perfect fruits and vegetables increases the application rates of fungicides to prevent cosmetic blemishes and post-harvest diseases.
- Sustainable Farming Mandates:Policies like the EU Green Deal are accelerating R&D into biologicals and lower-impact synthetic chemistries, opening new avenues for premium-priced, compliant products.
Market Restraints
- Stringent Regulatory Hurdles:The extensive data requirements and long review timelines for product registration with agencies like the US EPA and ECHA delay market entry for novel active ingredients.
- Pest Resistance Development:The evolution of herbicide-resistant weeds and insecticide-resistant pests diminishes the efficacy of established products, requiring costly development of new modes of action.
- Input Cost Volatility:Fluctuations in the cost of petroleum-based raw materials and key intermediates sourced from manufacturing hubs in China create unpredictable production costs for formulators.
Strategic Opportunities
- Precision Agriculture Integration:Developing chemical formulations optimized for drone and variable-rate sprayer application creates opportunities for higher-margin, technology-enabled solutions for large commercial farms.
- Soil Health and Biostimulants:Expanding portfolios to include nematicides and microbial products that improve soil health addresses a growing agronomic focus beyond conventional pest and weed control.
- Underpenetrated African Markets:Increasing agricultural investment and modernization in countries like Nigeria and Ethiopia present long-term growth potential for foundational herbicides and insecticides.
Industry Challenges
- Complex Global Stewardship:Managing product stewardship programs and ensuring applicator compliance with label instructions across varied languages, climates, and regulatory jurisdictions is a major operational burden.
- Intellectual Property Defense:Defending patents for novel active ingredients against generic competition and navigating complex licensing agreements for trait and chemical combinations presents a continuous legal challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crop Protection Chemicals Market |
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $125.65 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Rodenticides, Nematicides Form: Liquid, Granules, Dust, Wettable Powder, Emulsifiable Concentrate Application: Cereal Grains, Oilseeds, Fruits & Vegetables, Pulses & Cereals, Plantation Crops End Use Industry: Commercial Farms, Organic Farming, Greenhouse Operations, Horticultural Ventures, Agroforestry |
| Companies Covered | BASF SE, Bayer CropScience, Corteva Agriscience, Syngenta Group, FMC Corporation, UPL Limited, Sumitomo Chemical, Nufarm Limited, ADAMA Agricultural Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crop Protection Chemicals Market Strategic Shifts & Innovations
A fundamental shift toward precision and biological integration is defining the next generation of crop protection. This evolution is driven by the dual pressures of maximizing agricultural output while minimizing environmental impact and meeting new regulatory standards.
RNA interference (RNAi) technology provides a novel mode of action, using targeted gene silencing to control specific insect pests or pathogens. Early adoption is concentrated among large agribusinesses focused on high-value crops and managing resistant pest populations. This biological mechanism is converging with conventional chemical applications, creating integrated pest management systems that enhance efficacy and sustainability.
China's Ministry of Ecology and Environment (MEE) has implemented stringent controls on pesticide residues and environmental persistence to support national soil and water quality objectives. This regulatory pressure is accelerating the replacement of older, high-risk chemistries with newer, low-use-rate and rapidly degrading formulations. The policy directly affects both domestic manufacturers and multinational corporations, who must now demonstrate superior environmental profiles to secure product registrations.
Consolidated agricultural enterprises are increasingly seeking bundled solutions that combine chemicals, seeds, and digital agronomic advice from a single supplier. This model displaces transactional purchases from local dealers, favoring manufacturers and large retailers capable of providing integrated, season-long support. The shift is most visible in the grain and oilseed sectors of North and South America, where farm scale demands sophisticated management.
Crop Protection Chemicals Market Segmentation
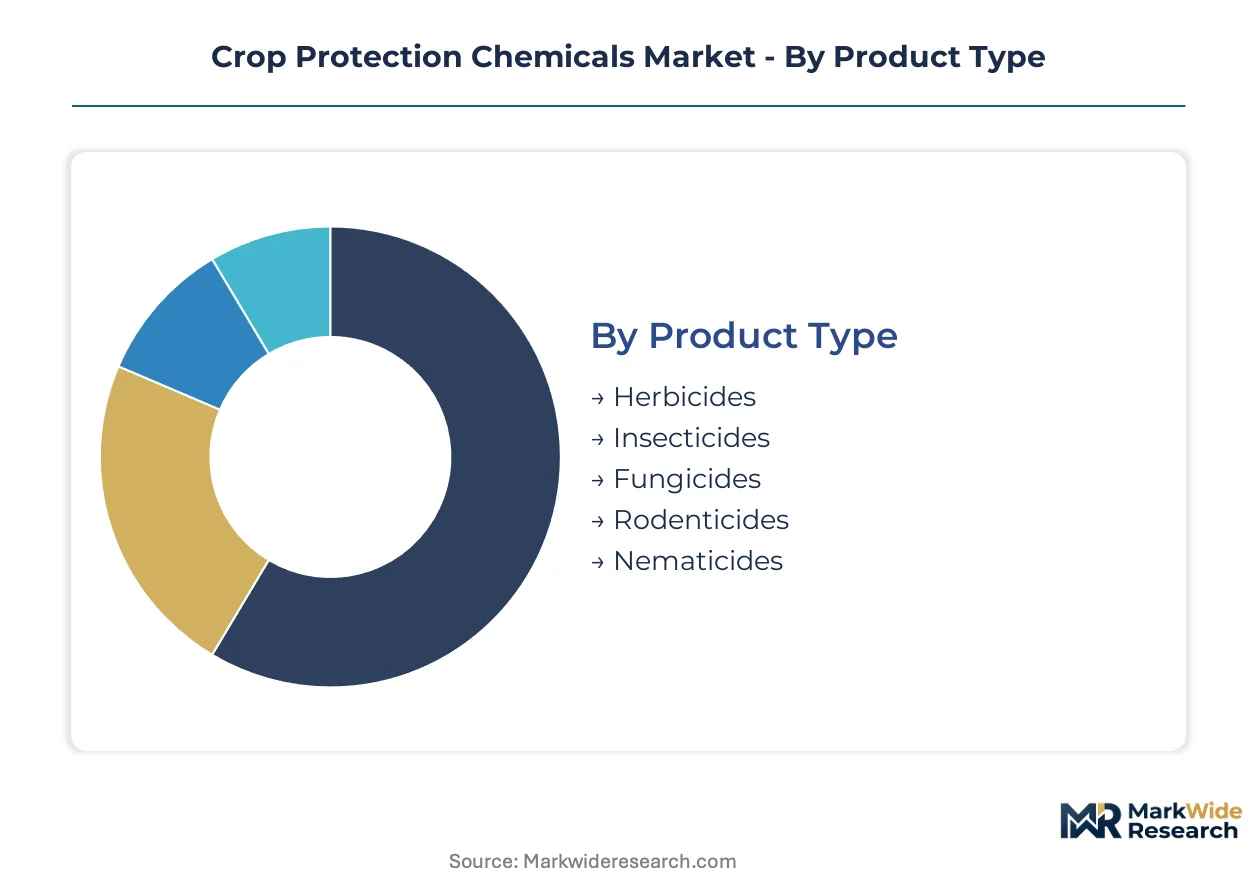
The Crop Protection Chemicals market is highly diversified, with segmentation reflecting the varied agricultural practices, pest challenges, and crop types across different geographies. Understanding these distinct segments is critical for manufacturers to tailor product portfolios and distribution strategies effectively.
Product Type:
Buyer selection within product types is primarily driven by the specific pest or disease challenge faced by growers, necessitating targeted chemical solutions for effective crop management.
- Herbicides:These formulations are designed to control or eliminate unwanted plant species that compete with cultivated crops for resources. Demand concentrates in large-acreage crops like cereal grains and oilseeds, where weed control significantly impacts yield and operational efficiency.
- Fungicides:Applied to protect crops from fungal diseases, these chemicals prevent yield losses and improve produce quality. Demand is strong for high-value fruits and vegetables, driven by consumer demand for blemish-free and healthy produce.
- Insecticides:Chemicals specifically formulated to manage insect pests that damage crops by feeding or transmitting diseases.
- Rodenticides:Products used to control rodent populations, which can cause significant damage to stored grains and field crops.
- Nematicides:Specialized compounds targeting nematodes, microscopic roundworms that attack plant roots and reduce crop vigor.
Volume sits with Herbicides; growth tilts toward Fungicides.
Form:
The physical form of crop protection chemicals dictates their application method, influencing efficacy, safety, and compatibility with various farm equipment.
- Emulsifiable Concentrate:These highly concentrated oil-based formulations mix readily with water to form stable emulsions, commonly used for broad-acre spraying due to their ease of handling and application.
- Liquid:Ready-to-use or concentrated solutions that are easily diluted and applied through sprayers, offering convenience and uniform coverage across diverse crop types.
- Granules:Dry, solid particles applied directly to the soil or foliage, often providing slow-release action or targeting specific soil-borne pests.
- Dust:Fine, dry powder formulations applied directly to plants or soil, typically used for localized pest control in specific agricultural settings.
- Wettable Powder:Powdered formulations that disperse in water to form a suspension, requiring continuous agitation during application to prevent settling.
Emulsifiable concentrates remain a foundational delivery method, while liquid forms offer versatility for modern application technologies.
Application:
Crop protection chemical application varies significantly based on the specific crop's agronomic requirements, pest susceptibility, and economic value, driving differentiated product demand.
- Cereal Grains:This segment includes crops like wheat, rice, corn, and barley, which demand high volumes of herbicides and insecticides to protect vast acreages and ensure global food security.
- Fruits & Vegetables:High-value crops such as apples, grapes, tomatoes, and leafy greens require intensive fungicide and insecticide applications to meet stringent quality standards and consumer preferences.
- Oilseeds:Crops like soybeans, rapeseed, and sunflowers rely heavily on herbicides for weed management and insecticides to protect against various destructive pests.
- Pulses & Cereals:This category encompasses lentils, chickpeas, and other staple crops, requiring specific pest and disease control strategies to maximize yield and nutritional value.
- Plantation Crops:Long-term crops such as coffee, tea, rubber, and oil palm utilize specialized crop protection chemicals tailored to their perennial growth cycles and regional pest pressures.
High-volume applications are concentrated in cereal grains, with fruits and vegetables driving value growth.
End Use Industry:
The operational scale and technological adoption rates within different agricultural industries shape their demand for crop protection chemicals, influencing product innovation and distribution channels.
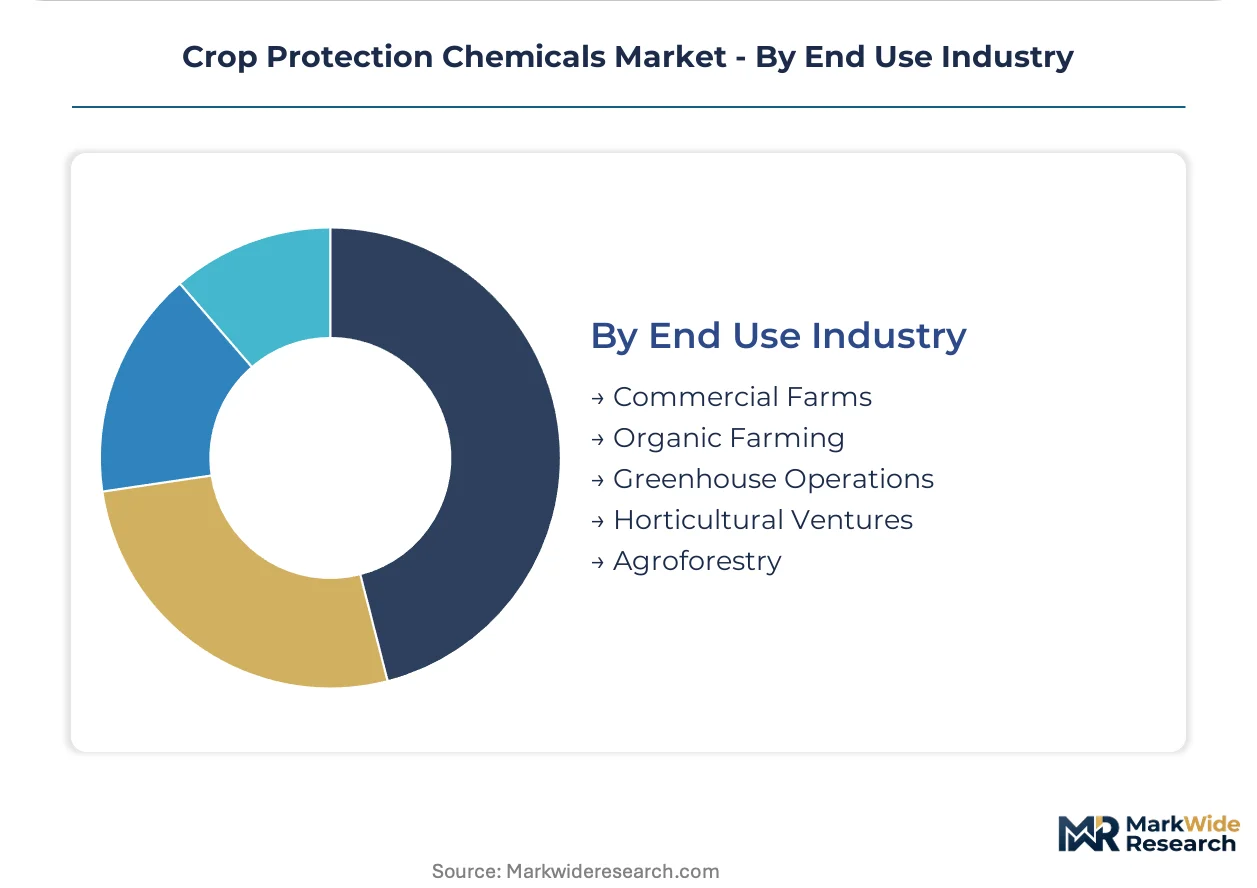
- Commercial Farms:Large-scale agricultural enterprises represent the primary consumers, utilizing advanced crop protection solutions for high-efficiency, yield-focused production across extensive land areas.
- Greenhouse Operations:Controlled environment agriculture demands specialized, often lower-residue, crop protection products tailored for intensive cultivation and year-round production of high-value crops.
- Organic Farming:This segment primarily relies on biological and naturally derived pest control methods, influencing the development of biopesticides and other compliant solutions.
- Horticultural Ventures:Smaller-scale operations focused on ornamental plants, nurseries, and specialty crops require precise and often aesthetic-preserving crop protection treatments.
- Agroforestry:Integrating trees and shrubs with crop and livestock farming, this practice requires crop protection chemicals compatible with diverse ecosystems and long-term land management.
Commercial farms represent the largest consumer base, with greenhouse operations demonstrating specialized growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for crop protection chemicals is pronounced in major agricultural economies. These regions drive significant volume due to extensive cultivation of staple and high-value crops. Policies supporting food security and export markets further amplify this demand.
United States
The United States market sees sustained demand from its vast corn and soybean belts, alongside specialized needs for high-value fruits and vegetables. The US Environmental Protection Agency (EPA) mandates rigorous product registration and residue standards. California's Central Valley, a major agricultural hub, increasingly adopts integrated pest management systems.
Brazil
Brazil's expanding agricultural frontier, especially for soy and corn, drives substantial demand for herbicides and insecticides. ANVISA, the country's health surveillance agency, oversees pesticide registration and application protocols. In the Mato Grosso region, intensive cultivation practices necessitate robust pest management solutions for high yields.
China
China's agricultural sector demands significant crop protection to ensure national food security and boost export quality. The Ministry of Ecology and Environment (MEE) implements strict policies on pesticide residues and environmental impact. Shandong province, a primary agricultural region, is a focal point for developing and adopting more sustainable chemical solutions.
India
India's large agricultural base generates consistent demand for crop protection chemicals to enhance food grain and horticulture output. The Central Insecticides Board & Registration Committee (CIBRC) governs pesticide registration and quality control. Maharashtra, a significant producer of fruits and vegetables, focuses on solutions improving produce quality and shelf life.
France
France, a major European agricultural producer, requires advanced crop protection for its diverse cereal, wine, and vegetable sectors. The EU Green Deal's Farm to Fork strategy strongly influences the approval and application of agrochemicals. The Loire Valley, known for its extensive fruit and vegetable production, drives innovation in biological and low-impact solutions.
Crop Protection Chemicals Market Key Industry Players
European producers anchor one tier of the crop protection chemicals market; Asian specialists hold another significant position. The industry exhibits a tiered structure, with a few multinational corporations dominating the patented active ingredient space. Several archetypes compete, including integrated solution providers, generic manufacturers, and niche biologicals developers. Portfolio diversification into biological solutions and strategic partnerships for technology access represent dominant competitive moves.
Within the integrated solution provider tier, Bayer CropScience and Syngenta Group exemplify companies offering comprehensive chemical and biological portfolios. These entities often leverage extensive R&D capabilities to develop novel active ingredients and advanced formulations. BASF SE also occupies a strong position, anchoring its strategy on significant investment in herbicide and fungicide innovation. Their competitive approach centers on securing contracts with large commercial farms by providing bundled offerings across seeds, chemicals, and digital agronomic services.
| Leading Market Players |
|---|
| BASF SE |
| Bayer CropScience |
| Corteva Agriscience |
| Syngenta Group |
| FMC Corporation |
| UPL Limited |
| Sumitomo Chemical |
| Nufarm Limited |
| ADAMA Agricultural Solutions |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's Farm to Fork strategy gates both qualified supply and premium-tier pricing access for compliant crop protection chemicals. This mandate drives investment into sustainable formulations and influences market value. Manufacturers must demonstrate superior environmental profiles to secure product registrations and command higher prices.
Pricing Analysis
Volume sales for foundational herbicides and insecticides often operate on thinner margins, while specialized fungicides and biologicals command premium pricing. Contract-based long-term offtake agreements dominate for large commercial farms seeking bundled solutions from major manufacturers. Price differentiation stems from patented active ingredients, advanced formulation efficacy, and superior environmental profiles validated by agencies like the US EPA. Input cost volatility, particularly for petroleum-based raw materials and intermediates sourced from China, creates pricing pressure across the commodity segments. Smaller agricultural enterprises purchasing transactional products exhibit higher price sensitivity compared to consolidated commercial operations.
Supply Chain Analysis
Workforce availability in manufacturing hubs within China and Europe significantly impacts the supply of key intermediates and finished crop protection chemicals. The supply chain draws heavily on petroleum-based raw materials and specialized chemical intermediates, often concentrated in specific manufacturing regions. Regulatory restrictions, such as those from China's MEE on environmental persistence, impose structural risks by limiting production or mandating costly reformulations. Distribution runs through a dual model: large commercial farms procure directly from integrated solution providers, while smaller growers rely on local dealers for transactional purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Crop Protection Chemicals market is undergoing a technology-transition phase, with RNA interference (RNAi) technology poised to replace older, high-risk chemistries for targeted pest control.
For Market Incumbents: Hedge against the threat of pest resistance and tightening environmental regulations by significantly diversifying into biological solutions. Leverage extensive R&D capabilities to develop novel active ingredients and advanced formulations, securing long-term contracts with large commercial farms. Invest in precision agriculture integration to optimize chemical application and demonstrate environmental stewardship, maintaining market leadership against generic competition.
For New Entrants and Emerging Players: Underpenetrated African markets, such as Nigeria and Ethiopia, present a significant opportunity for foundational herbicides and insecticides. Focus on developing lower-impact synthetic chemistries or biopesticides compliant with evolving global standards. A go-to-market angle emphasizing cost-effective, regionally adapted solutions for smallholder farmers can establish early market presence and build trust in these developing agricultural economies.
For Investors and Strategic Acquirers: Increased regulatory approvals for new biologicals or low-impact synthetic chemistries is the leading indicator that the market's long-term viability favors innovation-driven companies. Target niche biologicals developers or firms specializing in precision agriculture technologies that offer advanced application methods. Watch for significant market penetration of RNAi technology as an inflection point for disruptive growth and acquisition opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Biologicals | Bayer CropScience and Syngenta Group expand offerings to meet EU Green Deal mandates. |
| Precision Agriculture Integration | FMC Corporation develops formulations optimized for drone and variable-rate sprayer application. |
| R&D Investment in Novel Formulations | BASF SE sustains its position through significant investment in herbicide and fungicide innovation. |
| Strategic Partnerships for Technology Access | Corteva Agriscience secures access to RNAi technology for targeted insect pest control. |
| Geographic Expansion in Underpenetrated Markets | UPL Limited targets Nigeria and Ethiopia for long-term growth potential in foundational products. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a comprehensive view of market dynamics. Primary interviews with R&D directors, commercial farm managers, regulatory affairs specialists, and distribution channel partners offered critical qualitative insights. Data from the US EPA, ECHA REACH documents, China MEE policy reports, and agricultural ministry statistics were triangulated with interview findings.
Data-stream reconciliation integrated diverse information sources into a cohesive analytical framework, modeling market behavior over the projection horizon. Segmentation dimensions, including product type, form, application, end-use industry, and regional regulatory compliance, were meticulously analyzed. Compound annual growth rates were derived from historical trends and projected market drivers, incorporating inputs such as crop acreage expansion and evolving regulatory mandates.
Revisions become necessary when significant shifts in agricultural policy, technological breakthroughs, or macroeconomic conditions materialize. Forecasts reflect assumptions regarding agricultural policy stability and technological adoption rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Global Home and Garden Pesticides Market
Crop Protection
Global Termite Control Market
Crop Protection
Soybean Fungicide Seed Treatment Market
Crop Protection
Global Turf Protection Market
Crop Protection
Tebufenozide Market
Crop Protection
Chile Crop Protection Chemicals Market
Crop Protection
Middle East and Africa Turf and Ornamental Grass Protection Market
Crop Protection
Europe Nematicide Market
Crop Protection
Sweet Potato Fly Market
Crop Protection
South America Insecticide Market
Crop Protection
Synthetic Pesticide Market
Crop Protection
US Pest Control Market
Crop Protection
North America Nematicides Market
Crop Protection
Indonesia Insecticide Market
Crop Protection
US Insecticide Market
Crop Protection
Isoxaflutole Market