
 Cotton Picker Market | 2026-2036
Cotton Picker Market Size, Share, and Industry Trends Forecast 2026-2036
Cotton Picker Market Analysis
ISO 12100 safety certification for agricultural machinery is redrawing competitive boundaries in the cotton picker sector. Deere & Company leverages its North American dealer network to sustain aftermarket parts revenue across installed machine bases. CNH Industrial anchors its position through vertical integration into precision agriculture software bundled with harvesting equipment. Gomselmash competes on price in Commonwealth of Independent States markets where import substitution policies favor regional suppliers.
A cotton picker is a specialized agricultural machine that removes seed cotton from standing plants using rotating spindles or finger mechanisms, typically operating at field speeds of 4-6 miles per hour with hopper capacities exceeding 10,000 pounds. Its primary commercial purpose is to replace manual labor during narrow harvest windows, reducing crop exposure to weather damage and enabling just-in-time ginning schedules. Self-propelled units command the largest value share due to their productivity advantages in fields exceeding 500 hectares, while automated technology segments attract the fastest investment as GPS-guided row tracking and yield mapping become standard specifications. Tow-behind configurations retain relevance among smaller cooperatives in emerging markets where capital constraints limit upfront equipment expenditure.
The US EPA Tier 4 Final emissions standards and China's MEE agricultural machinery regulations jointly constrain engine technology choices available to original equipment manufacturers. India's CEA rural electrification programs create parallel compliance pathways for electric cotton picker prototypes seeking field validation. Stakeholders must monitor how precision agriculture data ownership frameworks evolve, as machine-generated yield maps become inputs for crop insurance and commodity pricing algorithms.
Market Dynamics
Mechanized cotton harvesting is decomposing the labor-intensive supply chains that historically dominated fiber production across major growing regions. Brazil's Mato Grosso expansion and China's Xinjiang modernization programs are accelerating fleet turnover toward higher-capacity self-propelled units.
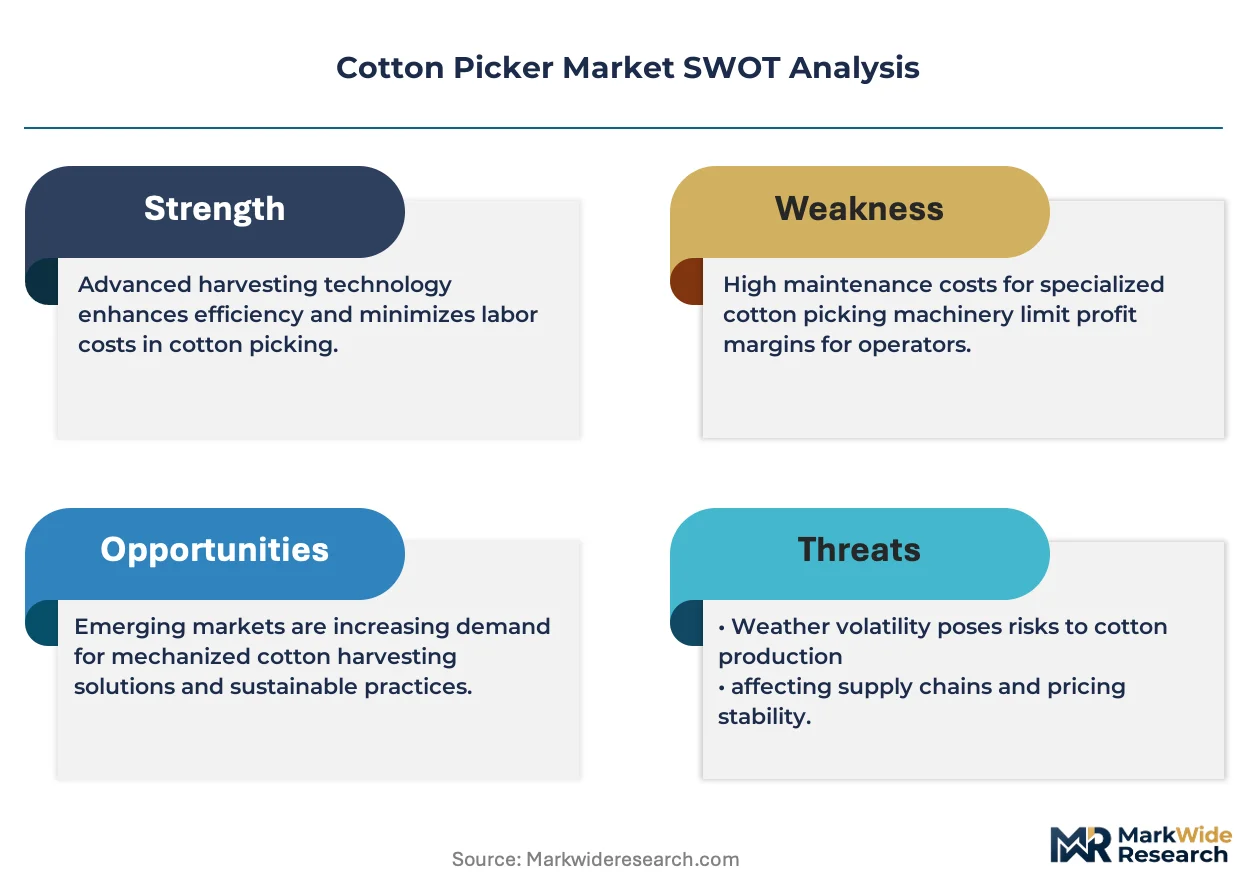
Growth Catalysts
- EPA Tier 4 Final compliance:US emissions mandates are forcing engine technology upgrades that extend equipment replacement cycles and expand aftermarket service revenue streams for dealer networks.
- Precision agriculture bundling:GPS-guided row tracking and yield mapping integration is raising equipment attach rates among large-scale cooperatives seeking operational data for crop insurance negotiations.
- Xinjiang state procurement:China's agricultural modernization subsidies prioritize domestic machinery fleets, concentrating demand within state-backed purchasing frameworks.
Market Restraints
- Steel and hydraulic component volatility:Input cost swings compress manufacturing margins and complicate long-term fleet pricing agreements with agricultural cooperatives.
- Dealer network concentration:North American parts distribution relies on limited certified service infrastructure, creating aftermarket access bottlenecks for remote growing regions.
- Manual labor substitution thresholds:Smallholder farms below 200 hectares face capital efficiency barriers that sustain hand-picking in South Asian supply chains.
Strategic Opportunities
- India's CEA rural electrification:Grid extension programs create validation pathways for electric cotton picker prototypes targeting cooperative demonstration projects.
- Autonomous spindle calibration:Machine vision integration with real-time fiber quality sensing opens premium contracting opportunities with gins seeking grade consistency.
- Commonwealth of Independent States import substitution:Regional procurement policies favor machinery assembly within customs union boundaries, rewarding localized production investments.
Industry Challenges
- ISO 12100 certification timelines:Safety standard compliance documentation delays product launches in European markets with strict machinery directive enforcement.
- Precision agriculture data ownership:Yield map monetization frameworks remain unresolved, complicating equipment financing structures that collateralize data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cotton Picker Market |
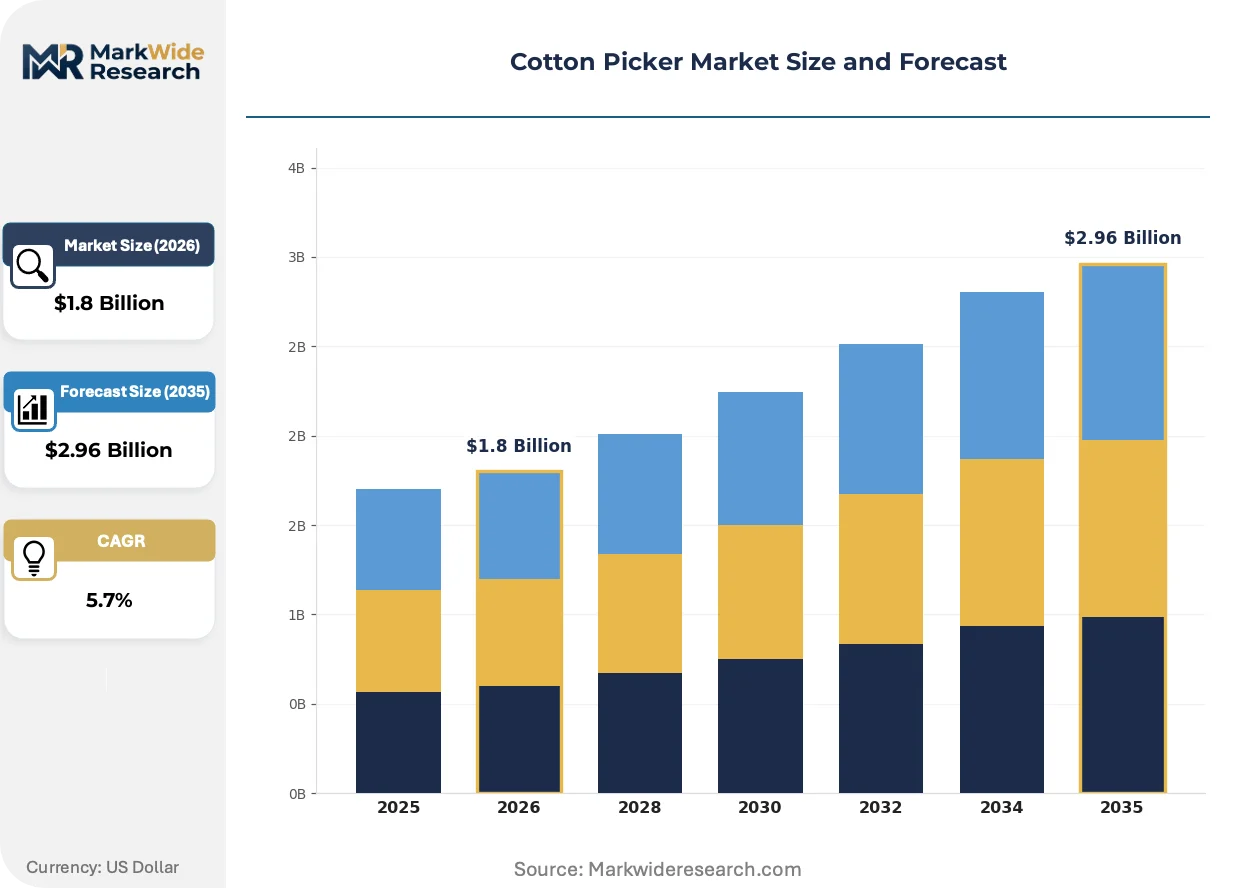
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Propelled, Tow-Behind, Walk-Behind, Harvesting Attachments Technology: Mechanical, Automated, Semi-Automated, Electric End User: Farmers, Agricultural Cooperatives, Contractors, Research Institutions Deployment: Field Operations, On-Demand Services, Rental Services, Integrated Solutions |
| Companies Covered | Gomselmash, Shandong Swan Cotton Industrial Machinery, Deere & Company, Xinjiang Boshiran Intelligent Agricultural Machinery, Mahindra & Mahindra Ltd., CNH Industrial, Kubota Corporation, Changzhou Dongfeng Agricultural Machinery Group, AGCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cotton Picker Market Emerging Trajectories
Autonomous operation capabilities and emissions-compliant powertrains are restructuring competitive requirements across cotton picker procurement. Equipment specifications now prioritize data integration over mechanical throughput alone.
Spindle-type harvesting mechanisms are decomposing the finger-stripper technology base that dominated lower-grade fiber production. Large-scale Brazilian operators are adopting high-speed spindle systems for simultaneous multiple-row harvesting. The technology shift is compressing harvest window durations and reducing weather exposure losses across Mato Grosso operations.
China's GB standards for agricultural machinery emissions are tightening import compliance requirements for foreign equipment manufacturers. The regulations mandate specific particulate matter thresholds that constrain engine supplier selection. European and North American OEMs are responding with localized assembly partnerships to maintain market access.
Cooperative procurement committees are consolidating equipment purchasing decisions through centralized tender processes rather than individual farm acquisitions. Dealer direct-sales relationships are yielding to aggregated buying consortia negotiating fleet-scale service agreements. This pattern is most visible across Australian cotton-growing regions where irrigation district boundaries align with cooperative membership.
Cotton Picker Market Segmentation
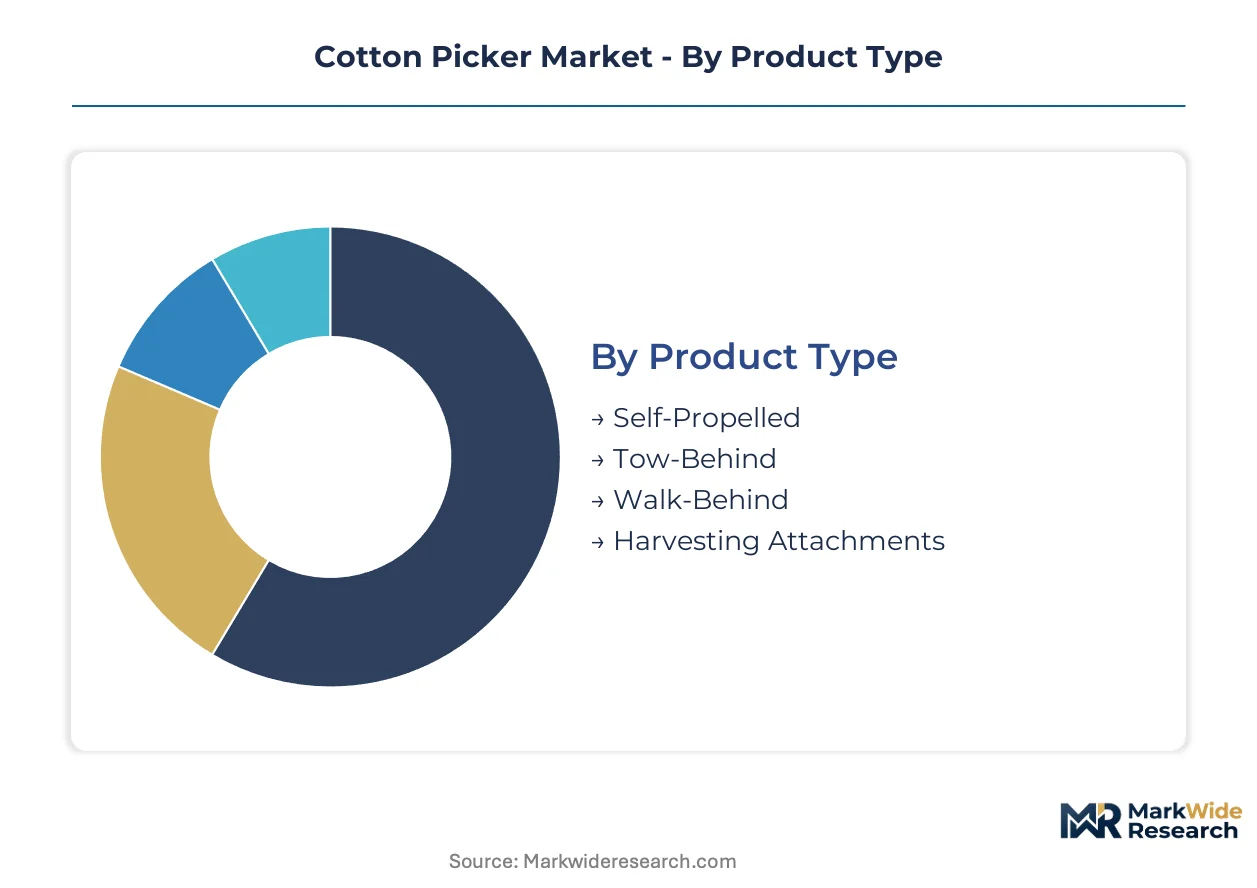
Cotton picker procurement patterns diverge sharply across operational scales and capital availability. Equipment specifications track directly to farm size thresholds and regional mechanization subsidies rather than fiber quality requirements alone.
Product Type:
Self-propelled units flow through manufacturer-direct and dealer network channels, while tow-behind configurations concentrate in cooperative bulk purchasing programs and secondary equipment markets.
- Self-Propelled:These machines integrate engines exceeding 300 horsepower with enclosed cabs and continuous harvesting systems operating across 12-24 row configurations. Demand concentrates in Brazil's Mato Grosso region where farms exceed 2,000 hectares and harvest windows compress to 45-day cycles. State-backed credit lines from Banco do Brasil sustain replacement cycles despite currency volatility.
- Tow-Behind:Tractor-pulled units with 4-8 row capacities serve mid-scale operations through cooperative procurement frameworks. India's Punjab and Haryana states exhibit concentrated uptake among 200-500 hectare farms where capital constraints limit self-propelled acquisition but labor shortages mandate mechanization.
- Walk-Behind:Compact units with 1-2 row harvesting heads target smallholder demonstration projects and research plot applications.
- Harvesting Attachments:Modular spindle or finger-stripper heads retrofit onto existing tractor platforms for incremental mechanization.
Self-propelled equipment dominates installed base value. Tow-behind units are where expansion concentrates in emerging mechanization corridors.
Technology:
Cost tier stratification separates precision-enabled automated systems from mechanical baseline equipment, with electric prototypes occupying a pre-commercial validation tier.
- Mechanical:Conventional spindle or finger-stripper mechanisms without electronic control systems constitute the volume base. These units prevail in Commonwealth of Independent States markets where Gomselmash and regional assemblers compete on acquisition cost rather than operational data integration.
- Automated:GPS-guided row tracking, yield mapping, and autonomous spindle calibration command premium positioning. Australia's Murray-Darling irrigation districts exhibit concentrated demand where cooperative procurement committees bundle precision agriculture software with equipment financing.
- Semi-Automated:Partial automation with operator-assisted steering and manual spindle control occupies mid-tier pricing.
- Electric:Battery-electric prototypes with 4-6 hour field endurance are gaining share fastest in India's CEA grid-electrified zones.
Mechanical systems anchor current fleet composition. Automated platforms are where manufacturer R&D investment concentrates.
End User:
Customer type determines specification complexity, with cooperatives demanding fleet-scale data integration and individual farmers prioritizing mechanical reliability.
- Farmers:Individual owner-operators below 500 hectares prioritize proven mechanical systems with localized parts availability. Xinjiang's state farm corporations operate as aggregated buyers despite individual field management structures.
- Agricultural Cooperatives:Consolidated purchasing entities across 10,000+ hectare footprints negotiate bundled service agreements. These buyers mandate ISO 12100 safety certification and precision agriculture data ownership clarity.
- Contractors:Custom harvest operators with 90-day annual utilization cycles demand rapid field conversion capabilities.
- Research Institutions:University and government trial stations acquire specialized configurations for variety testing protocols.
Cooperative procurement dominates new equipment volume. Contractor fleets are where utilization intensity concentrates.
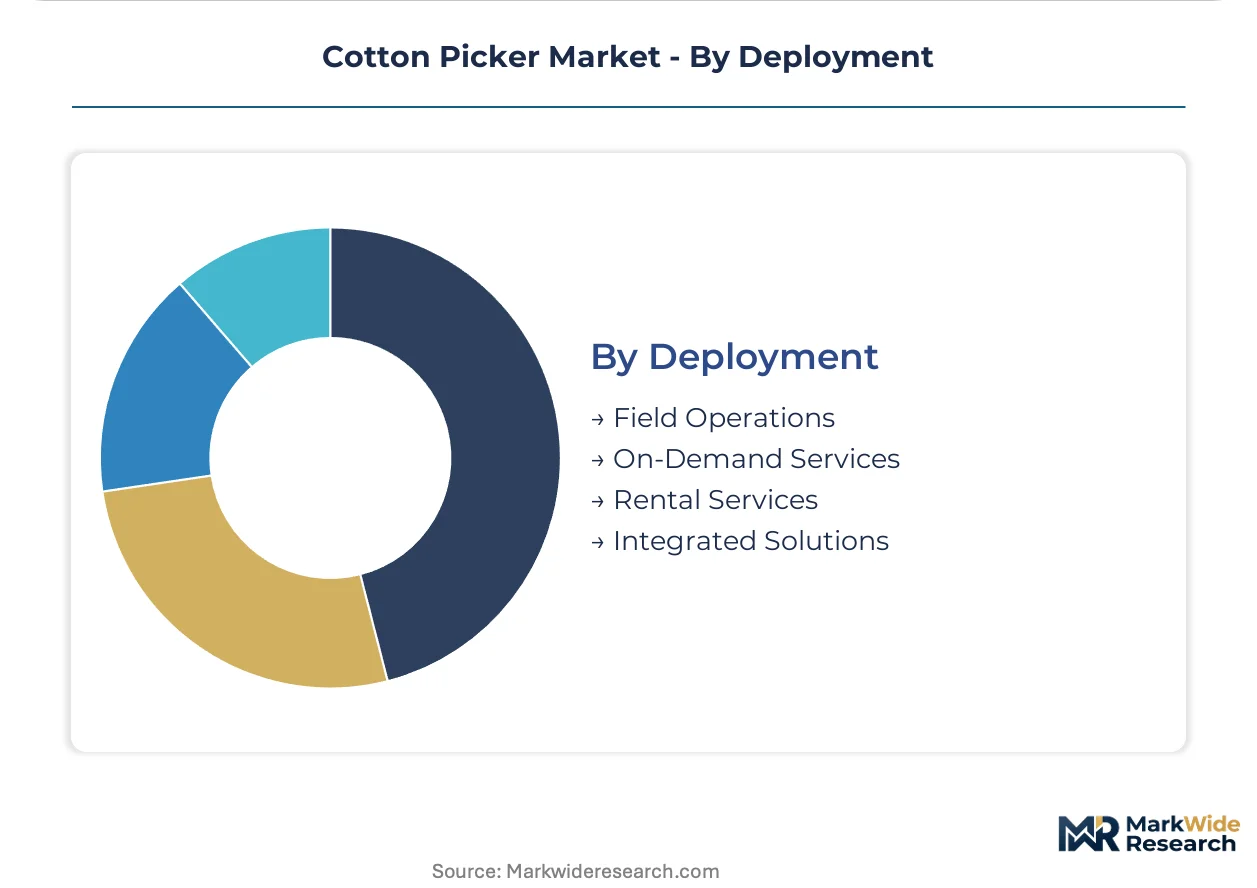
Deployment:
Volume distribution tracks operational model maturity, with integrated solutions capturing long-term service commitments and rental services addressing capital-constrained entry.
- Field Operations:Direct ownership with in-house maintenance crews constitutes the dominant deployment mode. Brazil's large-scale operators maintain captive technician teams certified by manufacturer training programs.
- On-Demand Services:Per-hectare contracting eliminates capital burden for smallholders. India's Maharashtra and Gujarat states exhibit expanding contractor networks where harvest timing arbitrage determines pricing.
- Rental Services:Seasonal equipment access through dealer or cooperative pools serves intermittent mechanization needs.
- Integrated Solutions:Full-service contracts bundling equipment, maintenance, and data analytics represent the steepest expansion trajectory among Australian irrigation cooperatives.
Field operations anchor current deployment patterns. Integrated solutions are where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agricultural mechanization subsidies are redirecting procurement flows toward state-backed purchasing frameworks in major cotton-producing jurisdictions. Fleet turnover accelerates where credit lines and import substitution policies align with harvest window compression needs.
United States
EPA Tier 4 Final compliance mandates are extending equipment replacement cycles across the Mid-South and Southwest growing belts. The USDA Farm Service Agency credit programs sustain large-scale operator acquisitions despite interest rate volatility. Texas High Plains and Mississippi Delta clusters concentrate self-propelled fleet deployments where gins coordinate just-in-time receiving schedules.
Brazil
Banco do Brasil rural credit lines are financing Mato Grosso expansion into Cerrado frontier zones with 12-24 row configurations. ANVISA agricultural machinery registration requirements align with Mercosur technical standards for cross-border fleet mobility. Rondonópolis and Sorriso processing hubs anchor contractor network density where custom harvest operators achieve 90-day utilization cycles.
China
Xinjiang Uygur Autonomous Region state procurement frameworks prioritize domestic machinery fleets under agricultural modernization subsidies. MEE agricultural machinery emissions regulations tighten particulate matter thresholds for imported equipment. Shihezi and Korla manufacturing clusters concentrate localized assembly partnerships that preserve market access for foreign OEMs.
India
CEA rural electrification programs in Punjab and Haryana create demonstration pathways for electric cotton picker prototypes. DGFT machinery import duty structures protect domestic assemblers while permitting component kits for regional integration. Ludhiana and Rajkot industrial corridors host fabrication networks serving 200-500 hectare cooperative demand.
Australia
Murray-Darling Basin irrigation cooperatives are consolidating equipment purchasing through centralized tender processes. The Australian Pesticides and Veterinary Medicines Authority machinery safety frameworks align with ISO 12100 certification requirements for precision agriculture bundling. Narrabri and Moree district boundaries align with cooperative membership structures that negotiate fleet-scale service agreements.
Cotton Picker Market Vendor Landscape
Player mix skews toward diversified agricultural machinery conglomerates with captive engine technology and precision agriculture software portfolios. Market structure exhibits tiered consolidation where premium automated systems command distinct pricing bands from mechanical baseline equipment. Two strategic archetypes dominate: integrated full-line suppliers bundling data analytics with hardware, and regional specialists exploiting import substitution policies through localized assembly. Competitive moves center on strategic partnerships for GB standards compliance and capacity expansion into customs union territories.
Among diversified machinery conglomerates, Deere & Company and CNH Industrial occupy positions exemplifying precision agriculture integration archetypes. Kubota Corporation represents the mid-scale automated tier targeting cooperative procurement committees. Gomselmash anchors the regional specialist vector within Commonwealth of Independent States markets. Xinjiang Boshiran Intelligent Agricultural Machinery exemplifies state-backed domestic champions capturing concentrated demand in autonomous regions. These named entities serve as structural anchors for understanding competitive positioning without attributing specific strategic actions or financial performance to individual firms.
| Leading Market Players |
|---|
| Gomselmash |
| Shandong Swan Cotton Industrial Machinery |
| Deere & Company |
| Xinjiang Boshiran Intelligent Agricultural Machinery |
| Mahindra & Mahindra Ltd. |
| CNH Industrial |
| Kubota Corporation |
| Changzhou Dongfeng Agricultural Machinery Group |
| AGCO Corporation |
| Others |
Supply Flow & Price Mechanics
Large-scale manufacturing scale economies in spindle-type harvesting systems concentrate supply among integrated OEMs and simultaneously establish price floors that mechanical baseline equipment struggles to breach. China's GB emissions compliance costs and Brazil's currency-denominated credit lines feed directly into regional pricing disparities that procurement committees exploit through cross-border tender arbitrage.
Pricing Analysis
ISO 12100 safety certification level creates the primary spread between premium automated platforms and mechanical baseline equipment, with three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates GPS-enabled yield mapping bundles from stripped-down spindle mechanisms, while steel and hydraulic component volatility compresses margins across all tiers. Cost compression in mechanical equipment is intensifying because Gomselmash and regional assemblers compete on acquisition cost in Commonwealth of Independent States markets. Smallholder farms below 200 hectares exhibit highest price sensitivity, whereas Australian irrigation cooperatives demonstrate lowest sensitivity due to bundled service agreements.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for engine components and precision agriculture sensors sourced from European and North American suppliers. Manufacturing concentrates in China, Brazil, and the United States, with assembly partnerships in Xinjiang and Mato Grosso serving regional procurement frameworks. Raw material dependencies center on high-strength steel alloys, hydraulic systems, and GPS module supply chains. Single-source vulnerability in semiconductor components for autonomous calibration systems poses structural risk. Distribution runs through manufacturer-direct channels for self-propelled units and cooperative bulk purchasing programs for tow-behind configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through cooperative procurement committees that consolidate equipment purchasing decisions across 10,000+ hectare footprints, fragmenting individual farm negotiation leverage.
For Market Incumbents: Fortify aftermarket parts revenue by expanding certified service infrastructure into remote growing regions where dealer network concentration creates access bottlenecks. Deepen backward integration into precision agriculture software to control data ownership frameworks that cooperative buyers now mandate. Counter emerging electric prototype threats from India's CEA demonstration zones by accelerating spindle-type R&D investment.
For New Entrants and Emerging Players: Anchor in India's 200-500 hectare cooperative segment where capital constraints limit self-propelled acquisition but labor shortages mandate mechanization. Target Punjab and Haryana demonstration pathways for electric cotton picker prototypes seeking field validation. Pursue localized assembly partnerships in Commonwealth of Independent States customs union territories to exploit import substitution policies favoring regional suppliers.
For Investors and Strategic Acquirers: Regional specialists with captive distribution in Brazil's Mato Grosso corridor present acquisition targets as credit line sustainability and harvest window compression drive fleet turnover. Long-term viability hinges on precision agriculture data monetization clarity across the analysis window. Monitor GB standards compliance timelines as inflection indicator for foreign OEM market access in China.
| Strategic Initiative | Industry Significance |
|---|---|
| Localized Assembly Partnership | Preserves market access for foreign OEMs under China's tightening GB emissions standards. |
| Precision Agriculture Software Integration | CNH Industrial anchors positioning through bundled yield mapping and GPS-guided row tracking. |
| Electric Prototype Field Validation | India's CEA grid extension programs create demonstration pathways for battery-electric units. |
| Aftermarket Service Network Expansion | Deere & Company leverages North American dealer infrastructure to sustain parts revenue. |
| Autonomous Spindle Calibration Development | Machine vision integration opens premium contracting with gins seeking fiber grade consistency. |
Methodological Framework
A spread of perspectives from OEM product managers, cooperative procurement committee chairs, aftermarket service directors, and precision agriculture software engineers converged on the working assumptions shaping this analysis. Primary interviews combined with secondary validation from customs machinery import records, agricultural mechanization subsidy disclosures, and EPA Tier 4 Final compliance documentation. Bottom-up equipment shipment data triangulated against top-down credit line disbursement figures from Banco do Brasil and China's agricultural modernization program budgets.
Segmentation dimensions modeled span product type, automation technology tier, end-user scale, and deployment mode across the projection horizon. CAGRs derived from fitted growth curves applied to equipment replacement cycles, harvest window compression rates, and state procurement framework expansion trajectories. Industry-specific forecast inputs include spindle-type adoption velocity in Brazil and electric prototype validation timelines in India's CEA-electrified zones.
Material uncertainties — steel and hydraulic component price volatility, GB standards compliance timeline delays, and precision agriculture data ownership framework evolution — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding credit line sustainability and cooperative procurement committee consolidation trajectories. Practitioners should keep alternative scenarios live as China's domestic machinery procurement preferences and India's rural electrification rollout pace evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Livestock Grow Lights Market
Agricultural Equipment
Belt Feeders Market
Agricultural Equipment
Oil Expellers Market
Agricultural Equipment
Gardening Equipment Market
Agricultural Equipment
Irrigation Syringe Market
Agricultural Equipment
Pump Feeder Market
Agricultural Equipment
Feeding Hopper Market
Agricultural Equipment
Sheep Shearing Equipment Market
Agricultural Equipment
Farm Tire Market
Agricultural Equipment
Agriculture Evaporative Cooling Pad Market
Agricultural Equipment
United States Grain Storage Silos Market
Agricultural Equipment
Air Seeder Market
Agricultural Equipment
Tree Transplanters Market
Agricultural Equipment
Vegetable Sorting Machines Market
Agricultural Equipment
Solar Fruit Dryer Market
Agricultural Equipment
Smart Rice Transplanter Market