
 Rice Paper Stand Up Pouch Market | 2026-2036
Rice Paper Stand Up Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Rice Paper Stand Up Pouch Market Analytics
Converting machine operator expertise is bifurcating the competitive landscape as legacy plastics technicians struggle to adapt heat-seal calibration for hygroscopic rice paper substrates. Amcor leverages its film-to-paper lamination R&D infrastructure to sustain pilot-line throughput for European artisan food brands. Mondi Group anchors Nordic retail private-label contracts through integrated pulp-to-pouch mill networks. Sealed Air Corporation competes on modified-atmosphere barrier coatings that extend shelf life for health supplement applications.
Rice paper stand up pouches comprise multi-ply constructions of bleached or unbleached kraft pulp laminated with moisture-resistant bio-polymers, typically achieving grease resistance below 10 Kit units and tensile strength of 30-50 N/m for vertical shelf display. Gusseted configurations dominate bulk dry-goods logistics due to superior cube utilization in palletized freight, while windowed variants command premium positioning in specialty retail where product visibility drives impulse purchase. Zip lock closures are displacing heat-seal formats in the health supplements channel as resealability becomes a subscription-commerce requirement.
EU EFSA contact-material standards and the US FDA's food substance notification process govern adhesive migration limits in rice paper food-contact layers, with REACH compliance now mandatory for silicone-based release liners used in European supply chains. China's SAMR enforces GB/T biobased content labeling that restricts synthetic polymer percentages in domestically sold pouches. Stakeholders must monitor evolving compostability certification divergence between home and industrial standards across their priority markets.
Market Dynamics
Compostable packaging mandates across the European Union and China's GB standards for biodegradable materials are forcing substrate conversions that outpace operator retraining programs, creating a capability bottleneck between equipment availability and qualified production labor.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets for 2030 are accelerating brand-owner transitions from multilayer plastics to mono-material rice paper constructions in premium dry-goods categories.
- Health supplement subscription commerce:Resealable zip lock formats are displacing heat-seal closures as monthly delivery models require repeated access without compromising barrier integrity.
- Germany's organic food processing corridor:Clustered demand from Bavarian and Baden-Württemberg artisan producers generates sufficient volume to justify dedicated rice paper converting line investments.
Market Restraints
- Kraft pulp price volatility:Bleached hardwood pulp contracts on Shanghai Futures Exchange expose converters to input cost swings that compress margin predictability in long-term private-label agreements.
- Heat-seal calibration complexity:Hygroscopic rice paper substrates require humidity-controlled production environments that legacy plastics technicians struggle to maintain, limiting qualified supplier expansion.
- Compostable film substitution:Polylactic acid and polyhydroxyalkanoate flexible films from Thai and Brazilian biopolymer producers compete for identical sustainability-positioned shelf space.
Strategic Opportunities
- Vietnam export-oriented snack manufacturing:European private-label buyers are qualifying Vietnamese co-packers for rice paper pouch conversion to diversify supply beyond Chinese and European sources.
- Modified-atmosphere barrier coatings:Oxygen-scavenging bio-polymer layers enable shelf-stable nut and seed applications previously restricted to aluminum-laminated plastics.
- Direct-to-consumer subscription channels:Specialty coffee and adaptogen brands are specifying custom-printed rice paper pouches as unboxing experience differentiators, bypassing traditional retail distribution.
Industry Challenges
- Compostability certification divergence:Home compostable TÜV Austria OK Compost HOME and industrial ASTM D6400 standards create labeling complexity for brands selling across multiple jurisdictions.
- Adhesive migration compliance:EU EFSA contact-material testing timelines for food-grade lamination adhesives extend new product qualification cycles beyond seasonal launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rice Paper Stand Up Pouch Market |
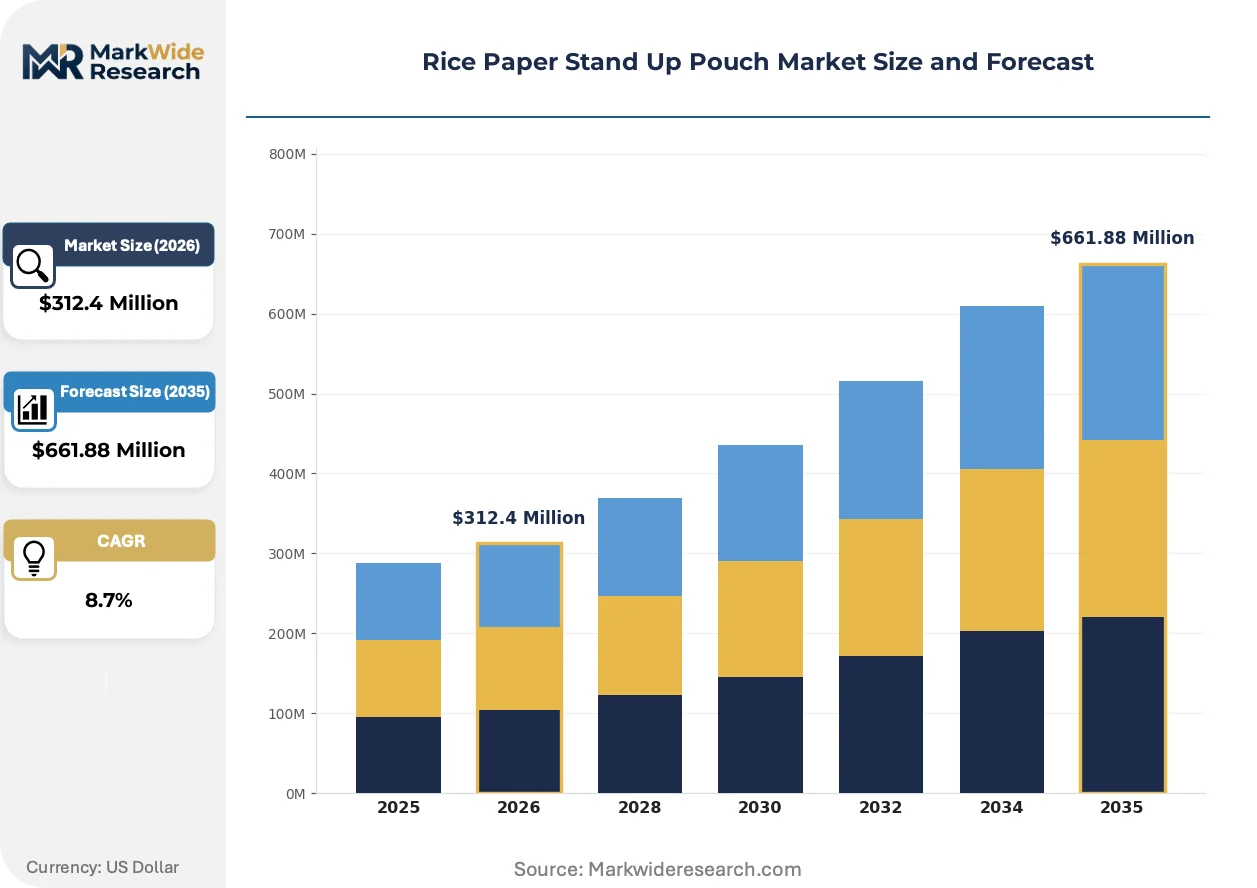
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bottom, Gusseted, Stand Up, Windowed Closure Type: Zip Lock, Heat Seal, Tear Notch, Velcro End User: Food Industry, Health Supplements, Personal Care, Pet Food Packaging Size: 100g, 250g, 500g, 1kg |
| Companies Covered | North Atlantic Specialty Bags, Amcor, TedPack, Sealed Air Corporation, Mondi Group, Impak Corporation, Paper Mart, Smurfit Kappa, Clear Bags, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rice Paper Stand Up Pouch Market Evolving Landscape
Material science advances in moisture-resistant bio-polymers and converting equipment adaptations for hygroscopic substrates are compressing the performance gap between rice paper and conventional plastic barriers.
Water-based barrier coatings derived from alginate and chitosan are supplanting petroleum-derived polyethylene extrusion layers in mid-market snack applications. German and Dutch organic brands are qualifying these constructions for six-month shelf-life targets. The shift is compressing capital recovery timelines for coating line investments as run lengths shorten and changeover frequency rises.
China's SAMR enforcement of GB/T biobased content labeling restricts synthetic polymer percentages in domestically sold pouches. Domestic converters are reformulating lamination layers to meet the 51% renewable content threshold. Export-oriented manufacturers in Zhejiang and Jiangsu provinces are dual-tracking formulations to maintain access to both domestic and European markets.
Brand-owner specification teams are consolidating supplier bases around vertically integrated converters with in-house pulp-to-pouch certification. Direct material provenance documentation is displacing third-party chain-of-custody audits in premium private-label negotiations. This concentration is most visible in Nordic retail procurement, where sustainability scorecard weighting now exceeds unit cost in final award decisions.
Rice Paper Stand Up Pouch Market Segmentation
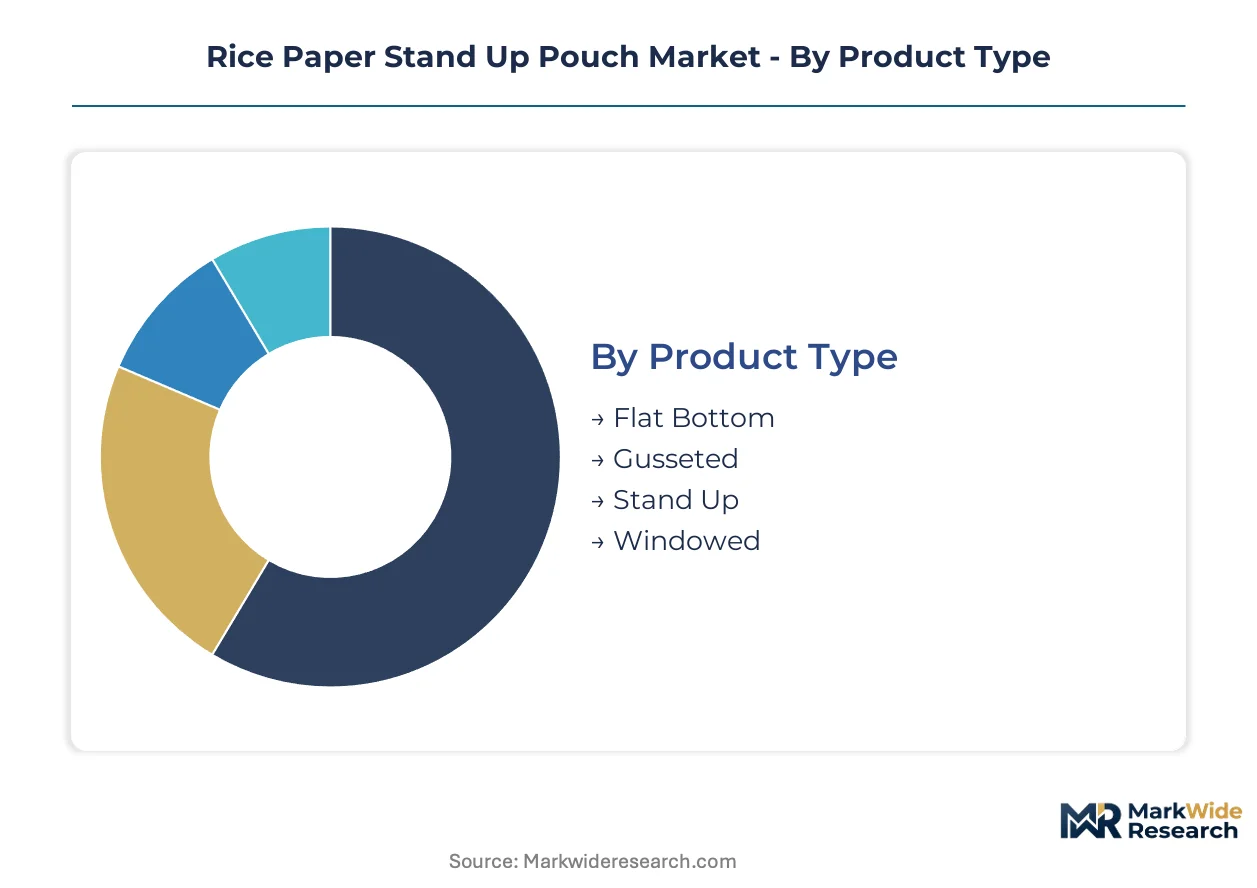
Segmentation in rice paper stand up pouches reveals how substrate limitations and converting complexity reshape competitive boundaries across format, closure, and end-use dimensions. Each category carries distinct substitution pressures from compostable films and conventional plastics.
Product Type:
Gusseted configurations face the strongest substitution threat from polylactic acid flat-bottom alternatives in bulk dry-goods logistics, while windowed variants defend premium positioning through visual differentiation that biopolymer films struggle to replicate.
- Flat Bottom:Rigid base construction using multi-ply kraft pulp with bio-polymer lamination enables stable vertical display for coffee and grain applications. German organic retailers specify this format for shelf-edge presence in Bavarian supermarket chains, though heat-seal calibration complexity limits qualified supplier pools.
- Gusseted:Side-folded base maximizes cube utilization in palletized freight for export-oriented snack manufacturers. Vietnamese co-packers serving European private-label buyers prioritize this configuration for ocean-container efficiency, but kraft pulp price volatility compresses margin predictability in long-term contracts.
- Stand Up:Self-supporting Doyen-style base dominates health supplement subscription channels requiring repeated reseal access.
- Windowed:Die-cut transparent panels laminated with cellulose film drive impulse purchase in specialty retail where product visibility commands premium shelf placement.
Gusseted retains volume leadership; windowed holds the steepest expansion curve.
Closure Type:
Cost tier stratification separates premium zip lock specifications in subscription commerce from economy heat-seal formats in single-serve retail, with tear notch bridging mid-market convenience demands.
- Zip Lock:Interlocking polyethylene-free tracks molded from bio-based polymers enable repeated access without compromising barrier integrity. Monthly delivery models for adaptogen and nootropic brands specify this closure as a subscription-commerce requirement, displacing heat-seal formats in health supplement channels.
- Heat Seal:Direct thermal bonding of rice paper layers suits high-speed form-fill-seal operations for commodity dry goods. Legacy plastics technicians struggle with humidity-controlled calibration for hygroscopic substrates, creating qualified-operator bottlenecks in China's Zhejiang converting corridor.
- Tear Notch:Perforated initiation points balance child-resistance with adult accessibility for single-serve nut and seed portions.
- Velcro:Hook-and-loop fasteners from bio-based nylon alternatives serve premium pet treat applications requiring audible closure confirmation.
Heat seal retains volume leadership; zip lock climbs the fastest as subscription models proliferate.
End User:
Application-specific barrier requirements segment the market, with food industry volume scale contrasting against health supplement margin premiums and personal care regulatory complexity.
- Food Industry:Grease resistance below 10 Kit units and oxygen barriers exceeding six-month shelf life qualify rice paper for nut, seed, and dried fruit applications. Nordic retail private-label procurement now weights sustainability scorecards above unit cost in final award decisions, concentrating demand around vertically integrated pulp-to-pouch suppliers.
- Health Supplements:Modified-atmosphere barrier coatings with oxygen-scavenging bio-polymer layers extend shelf stability for probiotic and collagen powders previously restricted to aluminum-laminated plastics. Direct-to-consumer brands specify custom-printed pouches as unboxing experience differentiators.
- Personal Care:EU EFSA contact-material adhesive migration limits and REACH compliance for silicone release liners extend qualification timelines beyond seasonal launch windows.
- Pet Food:Odor containment and puncture resistance specifications favor heavier gauge constructions in premium freeze-dried treat segments.
Food industry retains volume leadership; health supplements gain share fastest through subscription-channel expansion.
Packaging Size:
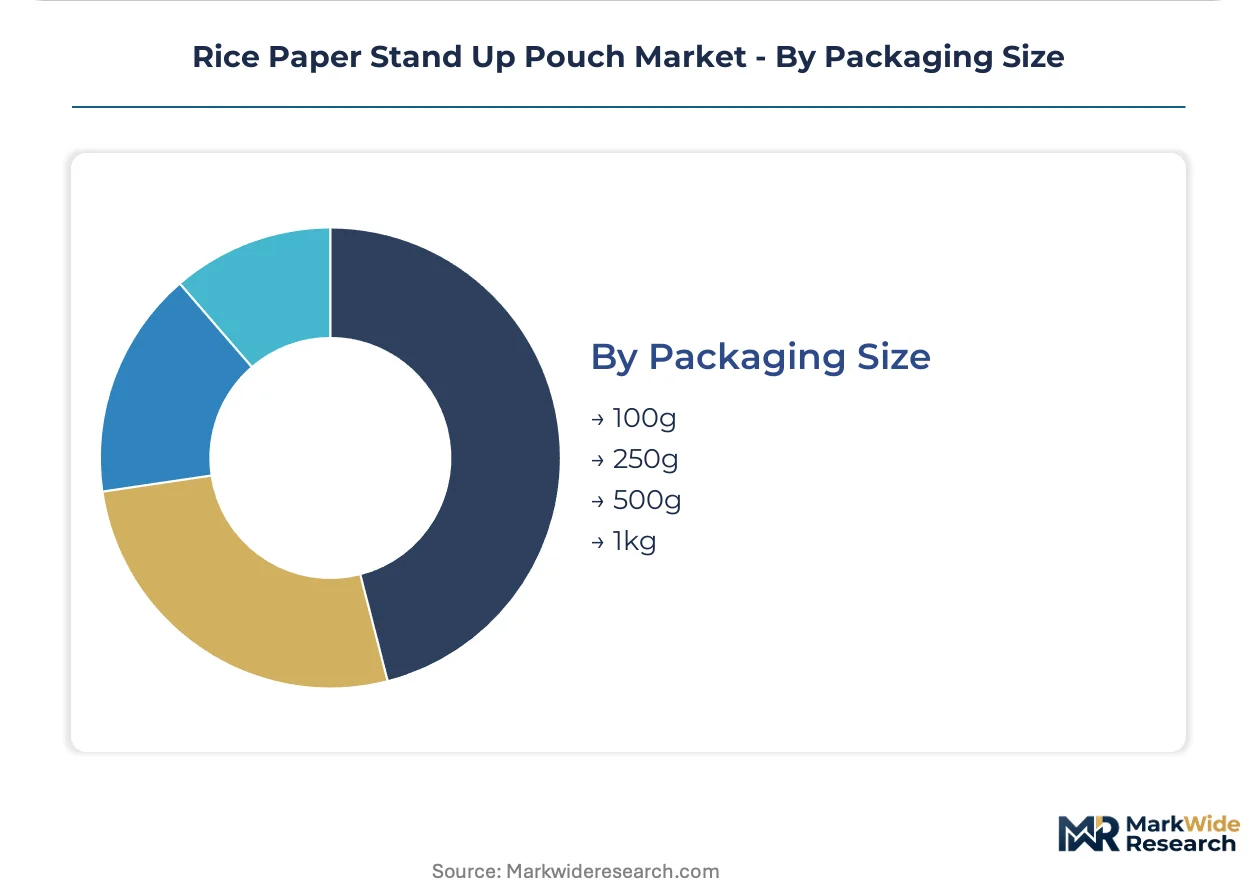
Volume-scale economics favor 500g and 1kg formats in export logistics, while 100g portions capture single-serve convenience premiums in urban retail.
- 100g:Single-serve portions for specialty coffee samples and adaptogen trial packs maximize shelf-facing density in urban convenience formats.
- 250g:Mid-tier sizing balances per-unit packaging cost with consumption velocity for artisan snack brands.
- 500g:Optimal cube utilization in European retail distribution dominates private-label dry goods specifications.
- 1kg:Bulk formats for co-packing operations serving food service and institutional buyers prioritize pallet-level freight efficiency.
500g retains volume leadership; 100g shows the steepest expansion trajectory as single-serve convenience formats proliferate in premium urban retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes rice paper stand up pouches predominantly for premium organic dry goods with strict compostability mandates, while Vietnam deploys identical formats for export-oriented snack manufacturing where freight cube efficiency outweighs certification complexity.
Germany
Bavarian and Baden-Württemberg artisan food processors generate clustered demand for gusseted and windowed formats in organic retail chains. EFSA contact-material standards and REACH compliance for silicone release liners govern adhesive migration limits in lamination layers. The organic food processing corridor around Munich and Stuttgart justifies dedicated rice paper converting line investments from vertically integrated suppliers.
China
Domestic demand concentrates in Zhejiang and Jiangsu provinces where export-oriented manufacturers dual-track formulations to access both domestic and European markets. SAMR enforces GB/T biobased content labeling that restricts synthetic polymer percentages to 51% renewable content thresholds. Converting corridors in Hangzhou and Suzhou face qualified-operator bottlenecks as legacy plastics technicians struggle with humidity-controlled calibration for hygroscopic substrates.
Vietnam
European private-label buyers are qualifying Vietnamese co-packers to diversify supply beyond Chinese and European sources for nut and seed applications. The country's export-oriented snack manufacturing sector prioritizes gusseted configurations for ocean-container cube efficiency. Ho Chi Minh City and Binh Duong province host expanding converting capacity serving Nordic and German retail procurement.
United States
Health supplement subscription brands specify zip lock rice paper pouches as unboxing experience differentiators in direct-to-consumer channels. FDA food substance notification processes govern adhesive migration limits in food-contact layers. California and Colorado specialty coffee roasters drive single-serve 100g format specifications for urban convenience retail placement.
Netherlands
Nordic retail private-label procurement concentrates sustainability scorecard weighting above unit cost in final award decisions. Dutch organic brands qualify water-based alginate and chitosan barrier coatings for six-month shelf-life targets. The Randstad logistics hub enables distribution efficiency for bleached kraft pulp imports serving integrated pulp-to-pouch mill networks.
Rice Paper Stand Up Pouch Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational packaging conglomerates controlling film-to-paper lamination R&D infrastructure while regional converters compete on custom-printing agility and shorter run lengths. The competitive terrain separates into three archetypes: vertically integrated pulp-to-pouch operators with captive fiber supply, barrier-coating technology licensors extending shelf-life performance, and flexible co-packers serving private-label qualification programs. Dominant competitive moves include backward integration into kraft pulp sourcing to hedge price volatility, and geographic expansion into Vietnamese converting corridors to capture European buyer diversification mandates.
Among diversified packaging conglomerates, Amcor and Mondi Group occupy positions reflecting distinct strategic anchoring, while Sealed Air Corporation exemplifies the barrier-technology specialization vector. Amcor represents the integrated multinational archetype with film-to-paper lamination infrastructure sustaining pilot-line throughput for European artisan brands. Mondi Group anchors Nordic retail relationships through mill-network proximity. Sealed Air sits within the modified-atmosphere coating tier where oxygen-scavenging bio-polymer layers extend addressable applications.
| Leading Market Players |
|---|
| North Atlantic Specialty Bags |
| Amcor |
| TedPack |
| Sealed Air Corporation |
| Mondi Group |
| Impak Corporation |
| Paper Mart |
| Smurfit Kappa |
| Clear Bags |
| Others |
Value Network & Pricing Analysis
Mill-scale utilization rates in Nordic pulp-to-pouch networks establish cost floors that smaller converters cannot match, compressing mid-tier pricing bandwidth while concentrating supply leverage among integrated operators with captive kraft fiber supply. This scale asymmetry forces independent converters toward custom-printing agility or niche certification tiers to defend margin positions against volume leaders.
Pricing Analysis
Long-term offtake contracts dominate procurement between European private-label buyers and Vietnamese co-packers, insulating converters from Shanghai Futures Exchange pulp volatility while locking in capacity commitments. Pricing stratifies across home-compostable premium tiers, industrial-compostable standard grades, and uncertified economy constructions. Cost compression in mid-tier gusseted formats is intensifying because polylactic acid film substitutes compete for identical sustainability shelf positioning. Bulk dry-goods buyers exhibit highest price sensitivity; direct-to-consumer subscription brands prioritize unboxing differentiation over unit cost.
Supply Chain Analysis
Strategic stockpiling of bleached hardwood pulp characterizes Nordic mill networks buffering against futures market swings, while Asian converters prefer just-in-time sourcing that amplifies margin vulnerability. Supply concentrates in Germany, Vietnam, and China's Zhejiang province, with each node serving distinct buyer archetypes. Production draws from kraft pulp, bio-polymer lamination films, and silicone release liners as critical inputs. Single-source vulnerability runs through Brazilian hardwood pulp plantations exposed to climate disruption. Distribution runs through Nordic retail procurement hubs, German organic food corridors, and Vietnamese export manufacturing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as vertically integrated pulp-to-pouch operators capture sustainability data streams that retail buyers require for ESG reporting, creating interoperability premiums beyond unit pricing.
For Market Incumbents: Secure backward integration into kraft pulp sourcing to hedge Shanghai Futures Exchange volatility that compresses margin predictability in long-term private-label agreements. Anchor Nordic retail relationships through in-house compostability certification that displaces third-party chain-of-custody audits in procurement scorecards. Defend against polylactic acid film substitution by accelerating modified-atmosphere barrier coating R&D for oxygen-sensitive applications. For New Entrants and Emerging Players: Custom short-run printing for direct-to-consumer subscription brands represents the most penetrable white-space, as incumbents optimize for volume scale and resist changeover frequency. Target Vietnamese co-packer qualification programs where European buyers actively diversify supply beyond Chinese sources. Enter through digital-printing partnerships with specialty coffee and adaptogen brands specifying unboxing experience differentiation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors barrier-coating technology licensors over commodity converters, as oxygen-scavenging bio-polymer layers expand addressable applications beyond traditional rice paper limitations. Acquisition targets should demonstrate captive pulp supply or certified home-compostable production capacity. Watch for compostability certification divergence between TÜV Austria OK Compost HOME and ASTM D6400 standards as the inflection signal requiring portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulp Supply | Captive fiber sourcing insulates margin predictability against Shanghai Futures Exchange volatility. |
| Home-Compostable Certification Investment | TÜV Austria OK Compost HOME qualification unlocks Nordic retail procurement above unit-cost weighting. |
| Modified-Atmosphere Barrier Coating Development | Oxygen-scavenging bio-polymer layers extend shelf life for nut and seed applications. |
| Vietnamese Co-Packer Qualification Program | European private-label buyer diversification mandates create capacity absorption opportunities. |
| Direct-to-Consumer Subscription Channel Partnership | Custom-printed pouch specifications capture unboxing experience premiums beyond retail distribution. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the rice paper stand up pouch value chain, including converting line operators, private-label procurement managers at Nordic retailers, sustainability compliance officers, and brand-owner specification teams. Secondary validation drew from EU EFSA contact-material standards documentation, SAMR GB/T biobased content labeling enforcement records, TÜV Austria compostability certification registries, and trade customs data for bleached kraft pulp movements. Bottom-up capacity assessments at Vietnamese and Chinese converting facilities were triangulated against top-down demand modeling from European organic food processing corridors.
Across the analysis window, volume and value projections were constructed through segmented modeling across product type, closure mechanism, end-use application, and packaging size dimensions, with additional granularity for regional regulatory cluster variations. CAGRs were derived from trend extrapolation of substrate conversion rates, compostable packaging mandate implementation timelines, and subscription commerce penetration curves. Forecast inputs incorporated heat-seal calibration complexity constraints on qualified operator supply, and pulp futures market volatility assumptions.
Forecasts assume regulatory continuity in EU EFSA contact-material standards and SAMR GB/T labeling enforcement; material policy shifts would require re-modeling of qualification timelines and domestic market access conditions. Revision becomes warranted when compostability certification divergence crosses thresholds that fragment cross-border product labeling or when kraft pulp price volatility exceeds historical bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Feed Pouches Market
Pouch
Asia-Pacific Pouch Packaging Market
Pouch
Cold Seal Lamination Pouch Market
Pouch
Indonesia Pouch Packaging Market
Pouch
Liquid Pouch Market
Pouch
Stand Up Paper Pouches Market
Pouch
Peel Pouches Market
Pouch
Colombia Pouch Packaging Market
Pouch
Doyen Style Pouches Market
Pouch
Ziplock Products Market
Pouch
Pouches Market
Pouch
Pre-Made Pouch Packaging Market
Pouch
Foil Pouch Packaging Market
Pouch
Global Medical and Pharmaceutical Pouch Market
Pouch
Europe Pouch Packaging Market
Pouch
Flexible Plastic Pouches Market