
 Global Anti Static Bubble Pouch Market | 2026-2036
Global Anti Static Bubble Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti Static Bubble Pouch Market Intelligence
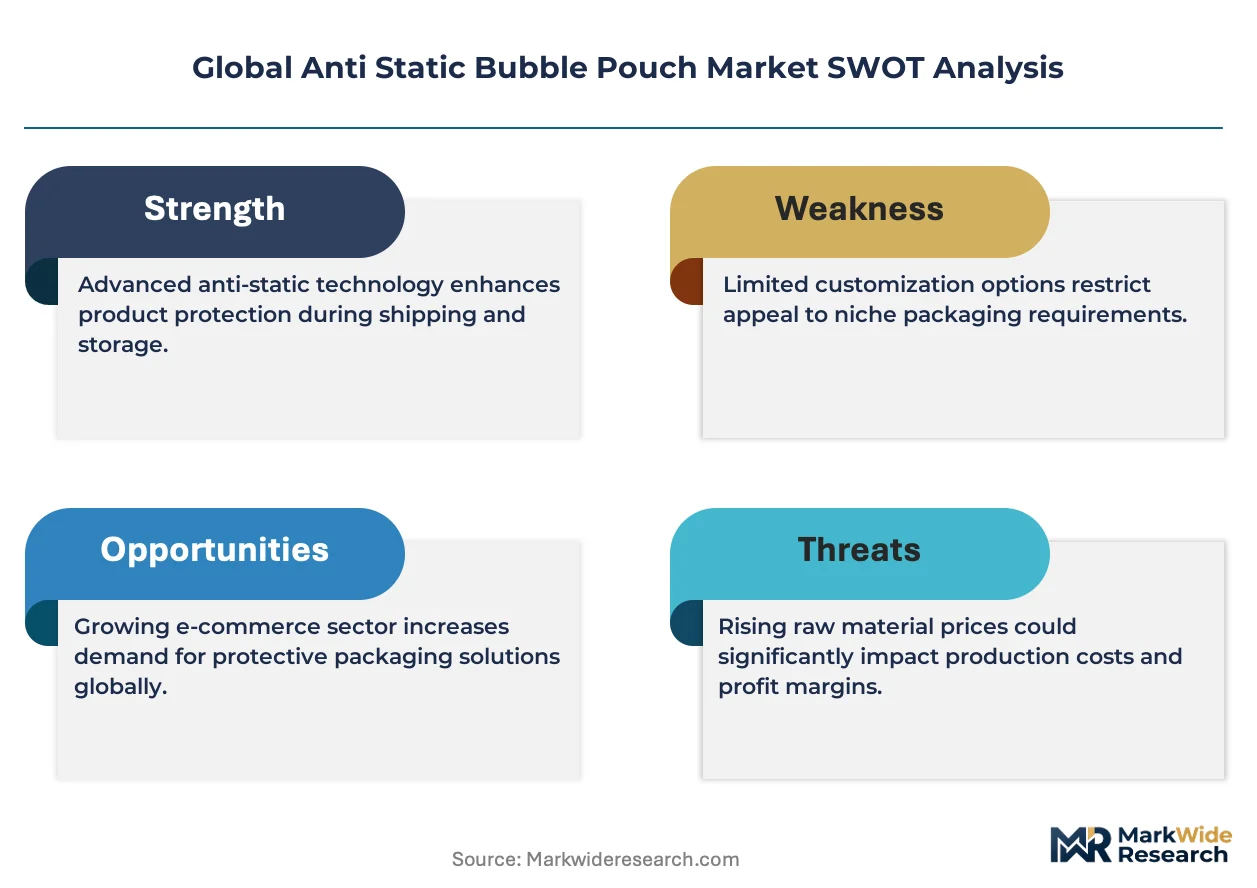
Raw material supply from key polymer producers in China and the United States is hardening the cost structure for pouch converters. Sealed Air Corporation leverages its scale in material science and extensive distribution network to manage these input volatilities. Pregis Corporation differentiates through its focus on sustainable and engineered packaging solutions. Meanwhile, 3M Company competes with specialized adhesive and film technologies integrated into its pouch offerings, targeting high-value electronics applications.
Anti static bubble pouches are specialized packaging designed to protect sensitive components from electrostatic discharge and physical impact. These pouches typically feature a multi-layer construction, with an outer bubble wrap layer for cushioning and an inner layer made of pink anti-static polyethylene film to dissipate static charges. The electronics end-user segment commands the largest share of the market, driven by the packaging needs of semiconductors and circuit boards. While polyethylene is the dominant material, co-extruded films are gaining share for applications demanding superior puncture resistance and ESD protection.
Regulatory frameworks significantly influence product specifications and market access. The European Union's RoHS directive restricts certain hazardous materials, while in the United States, the ANSI/ESD S20.20 standard sets performance requirements for ESD control programs. These regulations, alongside ISO quality standards, dictate material composition and testing protocols for manufacturers. Stakeholders must now balance the push for incorporating recycled materials with the non-negotiable need to meet stringent electrostatic discharge protection criteria.
Market Dynamics
The central dynamic in the anti static bubble pouch market is the tension between the non-negotiable performance requirements of ESD protection standards and the growing pressure from electronics OEMs for more sustainable, cost-effective packaging solutions using recycled content.
Growth Catalysts
- Miniaturization in Electronics:The trend toward smaller, more powerful components in smartphones, wearables, and automotive systems increases their sensitivity to electrostatic discharge, necessitating higher-grade protective packaging.
- Manufacturing Shift to Southeast Asia:The concentration of electronics assembly and testing facilities in hubs across Vietnam and Malaysia creates intense, localized demand for specialized packaging materials to support their export-oriented production.
- EU RoHS Directive:Strict regulations on hazardous substances in electronics force global manufacturers to use compliant materials, making RoHS-compliant anti static pouches a default specification for accessing the European market.
Market Restraints
- Polymer Price Volatility:Input costs for pouch converters are directly tied to fluctuating prices of polyethylene resins, which are heavily influenced by supply and energy cost dynamics from major producers in China and the United States.
- Performance of Recycled Content:Incorporating high levels of post-consumer recycled plastic can compromise the consistent dissipative properties required to meet strict ESD standards, creating a technical barrier to circularity.
- Foam-in-Place Alternatives:For larger electronic sub-assemblies and durable goods, custom-molded foam packaging offers a competitive substitute that can provide superior cushioning, limiting pouch use in certain applications.
Strategic Opportunities
- Medical Device Packaging:The growing market for sensitive electronic medical instruments and diagnostic kits presents a high-value opportunity for pouches that offer both sterile-readiness and certified ESD protection.
- Bio-based Anti-Static Polymers:Developing and commercializing biodegradable or bio-based films that meet ANSI/ESD performance standards offers a key differentiation pathway to attract sustainability-focused electronics brands.
- Indian Electronics Manufacturing:As India expands its domestic electronics production capabilities, a significant opportunity emerges to supply specialized anti static packaging to a historically underpenetrated and rapidly growing market.
Industry Challenges
- Complex Certification Pathways:Manufacturers face significant operational overhead in managing and maintaining separate certifications for standards like the US ANSI/ESD S20.20 and the EU's RoHS directive, which have different testing protocols.
- Material Traceability:Ensuring the full traceability of recycled content to verify its origin and quality is a major logistical challenge, yet it is essential for guaranteeing performance in critical electronics applications.
- Standardization Gaps:Minor but critical differences in ESD testing methodologies and acceptable static decay times between international standards bodies create ambiguity and can lead to redundant compliance costs for exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti Static Bubble Pouch Market |
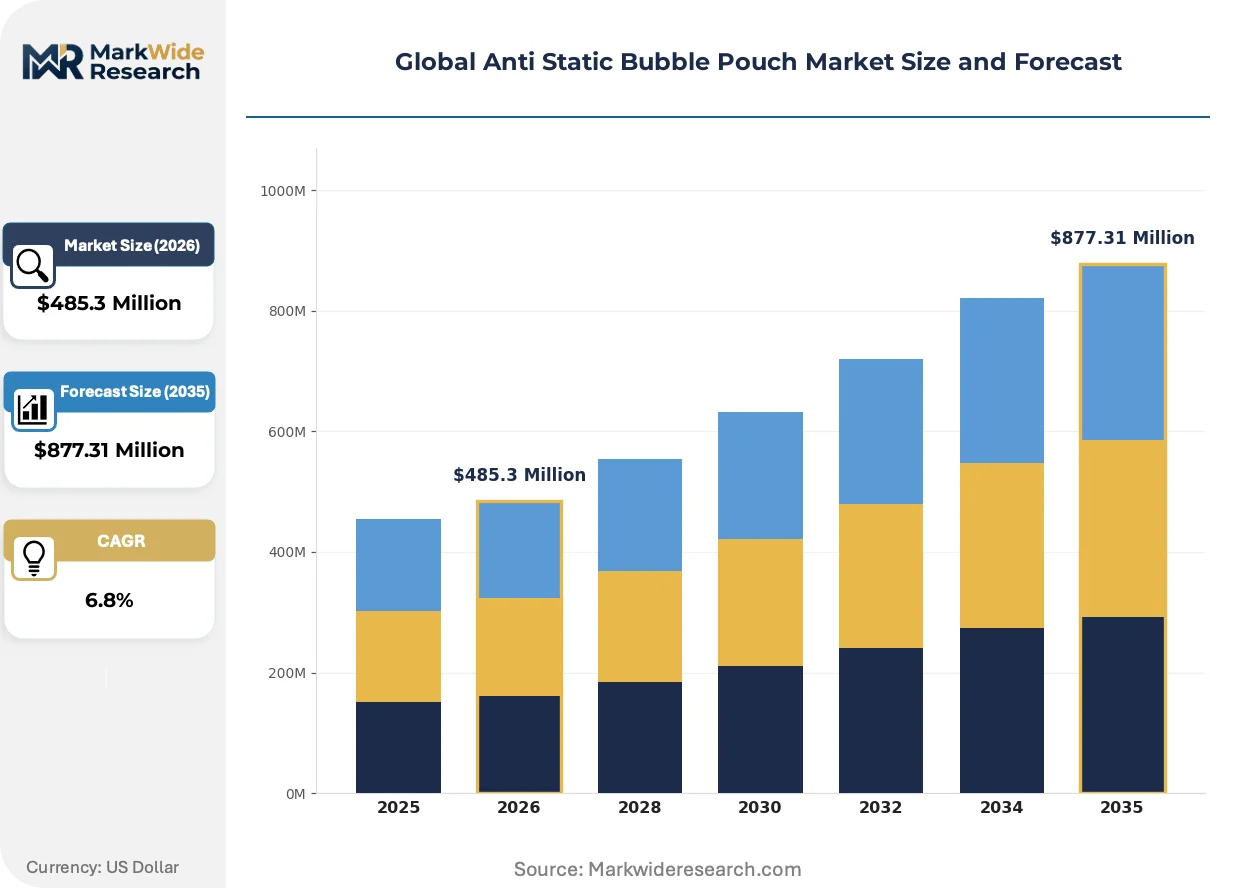
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $877.31 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Pouches, Gusseted Pouches, Roll Stock, Custom Sizes End User: Electronics, Pharmaceuticals, Automotive, Industrial Material: Polyethylene, Polypropylene, Co-extruded Films, Others Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | 3M Company, LPS Industries, Sealed Air Corporation, Uline, Inc., Kite Packaging Ltd., Pregis Corporation, Fujifilm Holdings Corporation, Storopack Hans Reichenecker GmbH, Smurfit Kappa Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti Static Bubble Pouch Market Strategic Shifts & Innovations
Material science innovation is converging with circular economy principles, fundamentally altering pouch construction. This shift pushes manufacturers to balance enhanced protective performance with demands for verifiable sustainability metrics, such as recycled content and end-of-life recyclability.
Co-extruded films integrating permanent static dissipative layers represent a significant product evolution. These advanced materials combine puncture resistance, cushioning, and reliable ESD protection into a single, thinner structure. High-value sectors like semiconductor and aerospace component packaging are the primary adopters. This technology is unifying previously separate performance attributes into a single engineered material, thereby reducing overall packaging complexity and weight.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is a major regulatory driver. It compels large electronics companies to report Scope 3 emissions, including those from their packaging supply chain. This directive pressures pouch suppliers to provide verifiable data on recycled content, carbon footprint, and recyclability, directly impacting material selection for products sold in the EU.
A notable behavioral shift is the move from commodity purchasing to a total cost of ownership (TCO) evaluation for packaging. Buyers increasingly analyze how pouch selection impacts product damage rates, warranty claims, and customer returns, rather than focusing solely on the per-unit cost. This trend is most visible in the automotive electronics and medical device sectors, where component failure costs are exceptionally high.
Global Anti Static Bubble Pouch Market Segmentation
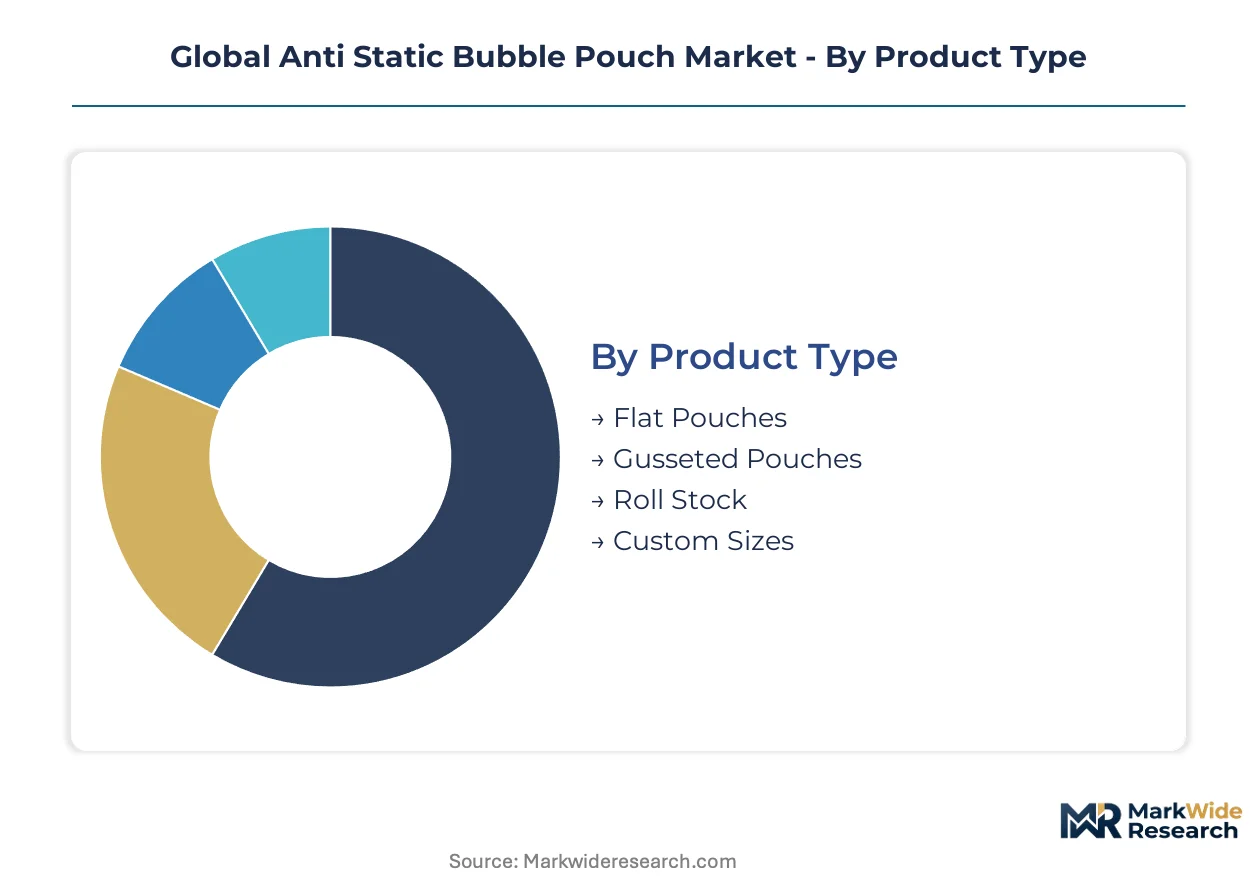
Market segmentation for anti static bubble pouches reveals the diverse needs across industries requiring sensitive component protection. Understanding these distinct segments helps manufacturers tailor product specifications, material choices, and distribution strategies to meet specific performance and regulatory demands.
Product Type:
Purchasing decisions for anti static bubble pouches often hinge on the required form factor and handling efficiency for specific packaging lines.
- Flat Pouches:These are the most common and versatile form, consisting of two sealed layers that provide a simple, protective enclosure for individual electronic components or small assemblies. Their widespread use across various industries makes them a foundational product offering.
- Roll Stock:Supplied in continuous rolls, this format is primarily used by automated packaging machinery for high-volume applications, allowing for efficient, on-demand pouch creation to specific lengths. Electronics manufacturing hubs in Vietnam and Malaysia utilize roll stock for streamlined operations.
- Gusseted Pouches:Designed with expandable sides, gusseted pouches accommodate bulkier or irregularly shaped items, offering increased internal volume without significantly expanding the footprint. These pouches are suitable for kits or multiple components.
- Custom Sizes:Tailored dimensions address unique product requirements, ensuring optimal fit and protection for specialized or oversized components.
Flat Pouches lead on scale; Roll Stock leads on momentum.
End User:
The application requirements of various industries dictate the specific anti static and physical protection features needed from bubble pouches.
- Electronics:This sector represents the largest consumer, driven by the critical need to protect semiconductors, circuit boards, and other sensitive components from electrostatic discharge and physical damage during transit and storage. Miniaturization in consumer electronics and automotive systems intensifies demand for high-performance solutions.
- Pharmaceuticals:Packaging for electronic medical devices, diagnostic kits, and sensitive laboratory equipment requires both ESD protection and often sterile-readiness, presenting a high-value niche market. The growing market for sensitive electronic medical instruments presents a significant opportunity.
- Automotive:Modern vehicles incorporate an increasing number of complex electronic control units and sensors, all requiring robust ESD protection during manufacturing, assembly, and aftermarket distribution. Component failure costs in this sector are exceptionally high.
- Industrial:This segment includes a broad range of applications for sensitive industrial controls, robotics components, and precision instruments that require protection from both static and impact.
The electronics sector drives the largest volume, with pharmaceuticals showing the steepest expansion trajectory.
Material:
Material selection is driven by a balance of cost, required ESD performance, and increasingly, sustainability mandates.
- Polyethylene:As the dominant material, polyethylene forms the base for most anti static bubble pouches due to its cost-effectiveness, flexibility, and ease of processing. Pink anti-static polyethylene film is commonly used to dissipate static charges.
- Co-extruded Films:These advanced materials combine multiple polymer layers to achieve superior properties, such as enhanced puncture resistance, improved barrier performance, and reliable permanent static dissipative layers. High-value sectors like semiconductor packaging adopt co-extruded films.
- Polypropylene:Offering higher stiffness and temperature resistance than polyethylene, polypropylene is used in applications requiring more rigid packaging or specific thermal properties. It provides an alternative for certain specialized requirements.
- Others:This category includes specialized polymers or blends designed for unique performance attributes, such as enhanced chemical resistance, optical clarity, or specific environmental compliance. Bio-based anti-static polymers are a developing area.
Polyethylene remains the foundational material, while co-extruded films offer enhanced performance for critical applications.
Distribution Channel:
Procurement patterns for anti static bubble pouches vary significantly based on the scale and operational structure of the end-user.
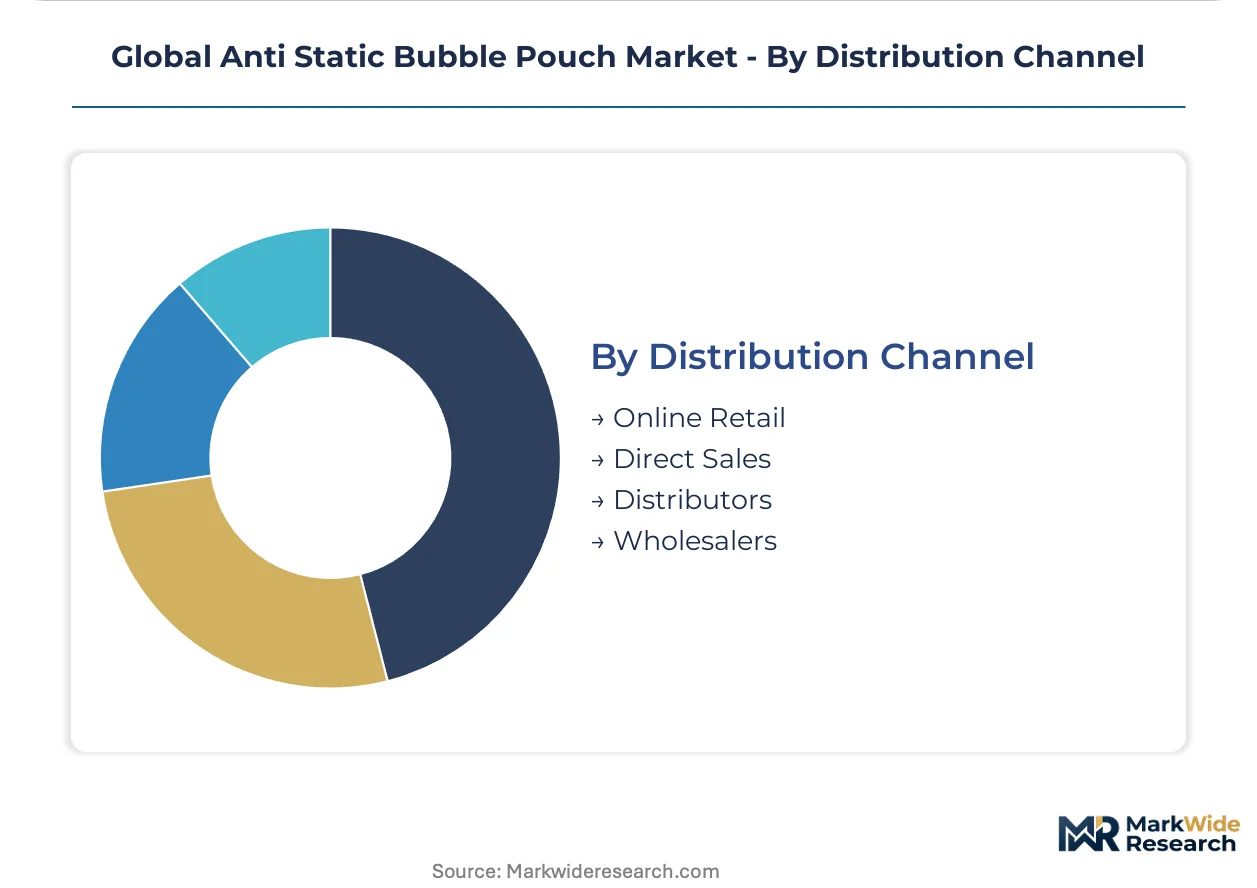
- Direct Sales:Large electronics OEMs and major industrial manufacturers often procure directly from pouch converters or large-scale suppliers to secure custom specifications, bulk pricing, and integrated supply chain solutions. This channel facilitates close technical collaboration.
- Distributors:Distributors serve a broad base of small to medium-sized enterprises and provide regional availability, inventory management, and a wider product selection. They act as critical intermediaries for market access.
- Online Retail:E-commerce platforms cater to smaller businesses, individual consumers, and niche applications requiring lower volumes or standard product configurations. This channel offers convenience and accessibility.
- Wholesalers:Wholesalers supply to smaller distributors and retailers, providing bulk purchasing options and logistical support for a diverse range of standard anti static bubble pouch products.
Direct sales channels serve large OEMs, while distributors extend market reach to a broader customer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global anti static bubble pouch market exhibits a significant regulatory-arbitrage dynamic, where varying environmental and performance standards influence manufacturing location decisions. OEMs often seek regions where compliance costs for directives like RoHS can be optimized alongside production efficiencies. This strategic balancing act drives investment and production shifts across different geographies.
United States
Demand in the United States stems from its robust advanced electronics, aerospace, and medical device manufacturing sectors. The ANSI/ESD S20.20 standard dictates rigorous performance requirements for ESD control programs. Silicon Valley in California anchors significant demand for high-performance anti static packaging for semiconductor components.
China
China's immense electronics production and consumer goods manufacturing capabilities generate substantial demand for anti static bubble pouches. Adherence to GB standards guides material specifications and product testing protocols for domestic and export markets. The Yangtze River Delta region serves as a critical electronics manufacturing hub, driving large-scale packaging procurement.
Vietnam
Vietnam's burgeoning export-oriented electronics assembly industry fuels a concentrated demand for specialized anti static packaging. Manufacturers here prioritize compliance with stringent importing region standards, such as the EU's RoHS directive. Industrial parks around Hanoi and Ho Chi Minh City house numerous electronics factories, necessitating efficient local packaging supply chains.
Malaysia
Malaysia's strong position in semiconductor manufacturing and electronics component production drives significant demand for protective packaging. Local environmental regulations, alongside international export requirements, influence material choices for anti static pouches. Penang, a prominent electronics manufacturing hub, requires high-grade ESD protection for its advanced semiconductor and testing facilities.
India
India's expanding domestic electronics manufacturing capabilities, supported by government PLI schemes, are increasing demand for anti static pouches. BIS standards for electronic goods guide product specifications and material quality for local production. Bengaluru and Chennai are developing electronics manufacturing clusters, creating new opportunities for specialized packaging suppliers.
Global Anti Static Bubble Pouch Market Key Industry Players
Established producers occupy the standard tier, offering cost-effective, high-volume anti static bubble pouches, while emerging entrants pursue niche applications in sustainable and high-performance engineered packaging. The market structure is tiered, with significant players leveraging material science expertise and extensive distribution networks. Strategic partnerships for material development and targeted acquisitions of specialized technology firms are common competitive moves.
Specialists in material science and extensive distribution, such as Sealed Air Corporation, anchor the market's high-volume segment. Pregis Corporation exemplifies a focus on sustainable and engineered packaging solutions, addressing the growing demand for environmentally conscious options. Meanwhile, 3M Company occupies a position in high-value electronics applications, leveraging its specialized adhesive and film technologies for integrated pouch offerings. These companies collectively represent the varied strategic approaches to product differentiation and market penetration within the anti static bubble pouch sector.
| Leading Market Players |
|---|
| 3M Company |
| LPS Industries |
| Sealed Air Corporation |
| Uline, Inc. |
| Kite Packaging Ltd. |
| Pregis Corporation |
| Fujifilm Holdings Corporation |
| Storopack Hans Reichenecker GmbH |
| Smurfit Kappa Group |
| Others |
Cost & Logistics Intelligence
Skilled labor concentrations in electronics manufacturing hubs like Vietnam and Malaysia influence pricing tier spreads by enabling competitive production costs for anti static bubble pouches.
Pricing Analysis
Direct-to-OEM discount structures often define pricing in the anti static bubble pouch market, reflecting contract-based long-term offtake agreements. Pricing stratifies across premium, standard, and economy tiers, driven by certification level, such as ANSI/ESD S20.20 compliance, and volume scale. Cost compression is intensifying for standard polyethylene pouches due to electronics OEMs demanding more cost-effective solutions. Electronics OEMs exhibit high price sensitivity, while aerospace and medical device manufacturers prioritize certified performance over unit cost.
Supply Chain Analysis
Reverse-logistics considerations for packaging waste are gaining traction, although the primary supply chain for anti static bubble pouches remains linear. Geographic supply concentrates significantly in China and the United States for raw polymer production, then shifts to Vietnam and Malaysia for pouch conversion. The industry relies heavily on polyethylene resins and specialized co-extruded films. Commodity price volatility for these polymer inputs presents a structural risk. Distribution runs through direct sales channels for large OEMs and through distributors serving smaller to medium-sized enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti static bubble pouch market functions as a regulatory compounder, with the EU's RoHS directive consistently driving demand for compliant packaging materials.
For Market Incumbents: Cement market leadership through sustained investment in material science R&D, particularly for bio-based anti-static polymers. Develop advanced co-extruded films offering superior performance and verifiable sustainability metrics to counter foam-in-place alternatives. Leverage extensive distribution networks for broad market reach. Strategic acquisitions of specialized technology firms can integrate new ESD protection capabilities.
For New Entrants and Emerging Players: Smaller electronics manufacturers in India represent an underserved buyer archetype with significant growth potential for anti static bubble pouches. Target the medical device packaging segment with sterile-ready, certified ESD solutions meeting stringent regulatory requirements. Focus on SMEs in emerging electronics manufacturing hubs by offering cost-effective, high-performance anti static pouches. A strong go-to-market angle emphasizes rapid customization and local technical support.
For Investors and Strategic Acquirers: Diversified packaging conglomerates are the most active acquirers in this space, seeking to consolidate specialized capabilities and expand geographic footprints. The market offers long-term viability given the non-negotiable need for essential protective packaging in electronics. Focus acquisition strategies on specialized material science firms with proven R&D in sustainable or advanced ESD film technologies. Adoption rates of bio-based anti-static polymers serve as a key signal for future market shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Bio-based Films | This initiative addresses EU CSRD mandates, attracting sustainability-focused electronics brands. |
| Expand in Indian Electronics | Capturing this rapidly growing market supports domestic electronics production. |
| Acquire Material Science Firm | Integrating advanced film technologies enhances ESD protection for high-value components. |
| Certify Sterile ESD Pouches | Accessing the medical device packaging market requires stringent sterile-readiness and ESD protection. |
| Optimize Recycled Content | Balancing cost-effectiveness with consistent dissipative properties meets ESD standards. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, informing the global anti static bubble pouch market analysis. Primary research involved discussions with R&D directors, procurement leads, packaging engineers, and supply chain managers. Secondary data sources included industry association reports, regulatory body publications like RoHS and ANSI/ESD S20.20, and company financial filings. Bottom-up and top-down triangulation validated market sizing and segmentation.
Historical reference periods anchored the forecast framework, establishing a baseline for market projections across the analysis window. The analytical framework incorporated historical data, market drivers, restraints, and opportunities. Segmentation dimensions modeled included product type, end user, material, and distribution channel. Regression models derived compound annual growth rates, informed by electronics production volumes and polymer price indices.
Inputs from company financial filings and regulatory body reports were available through the study window; gaps in real-time supply chain data introduce uncertainty bands. Forecasts reflect assumptions about future electronics production trends. Practitioners should monitor geopolitical shifts and polymer feedstock prices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Nigeria Pouch Packaging Market
Pouch
OPP Pouches Market
Pouch
PCR Pouches Market
Pouch
Retort Pouch Market
Pouch
Child Resistant Locking Pouches Market
Pouch
Foil Zipper Bags Market
Pouch
Middle East and Africa Pouch Packaging Market
Pouch
Europe Pouch Packaging Market
Pouch
Ziplock Products Market
Pouch
Box Pouch Market
Pouch
Canada Pouch Packaging Market
Pouch
Colombia Pouch Packaging Market
Pouch
Vietnam Pouch Packaging Market
Pouch
Brazil Pouch Packaging Market
Pouch
Bio PE Pouches Market
Pouch
Pouch Dispensing Fitment Market