
 Vietnam Pouch Packaging Market | 2026-2036
Vietnam Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Pouch Packaging Market Insights
Vietnamese flexible packaging converters is recalibrating capacity toward higher-barrier multilayer films to serve export-bound food customers. Huhtamaki Oyj leverages its regional technical center to transfer European barrier-coating expertise into local production. SCG Packaging Public Company anchors the upstream supply chain through integrated film extrusion and metallization assets in Binh Duong province.
Vietnam pouch packaging denotes flexible primary containers constructed from laminated plastic, aluminum foil, or paper-polymer composites, typically sealed by heat or pressure to achieve oxygen transmission rates below 0.1 cc per square meter per day for shelf-stable applications. Stand-up pouches with spout closures dominate liquid and semi-liquid food presentations due to superior shelf presence and dispensing convenience. Retort pouches represent the fastest-expanding material-format combination, as processors substitute them for metal cans in seafood and curry exports to Japan and the European Union.
Vietnam's Ministry of Health and the General Department of Customs administer food-contact material registrations and import inspections under circulars aligned with ASEAN harmonized standards. Compliance with EU REACH and Japan's Food Sanitation Law shapes export-access requirements for converters serving foreign brand owners. Stakeholders must monitor how domestic enforcement of extended producer responsibility frameworks affects virgin plastic sourcing economics versus recycled-content alternatives.
Market Dynamics
Vietnamese food exporters are abandoning metal cans for retort pouches to meet Japanese and EU shelf-life standards, forcing domestic converters to rebuild extrusion lines for high-barrier multilayer films.
Growth Catalysts
- ASEAN Harmonized Standards:Vietnam's Ministry of Health circulars on food-contact materials are accelerating registration compliance among flexible packaging converters, unlocking access to regional export markets.
- Seafood Processing:Export-oriented seafood processors in Ba Ria-Vung Tau province are converting canning lines to retort pouch formats for curry and marinated fish products bound for Japan.
- Ho Chi Minh City Industrial Cluster:Concentrated converting capacity in Binh Duong and Dong Nai provinces enables just-in-time supply to food manufacturing parks, reducing logistics costs for pouch procurement.
Market Restraints
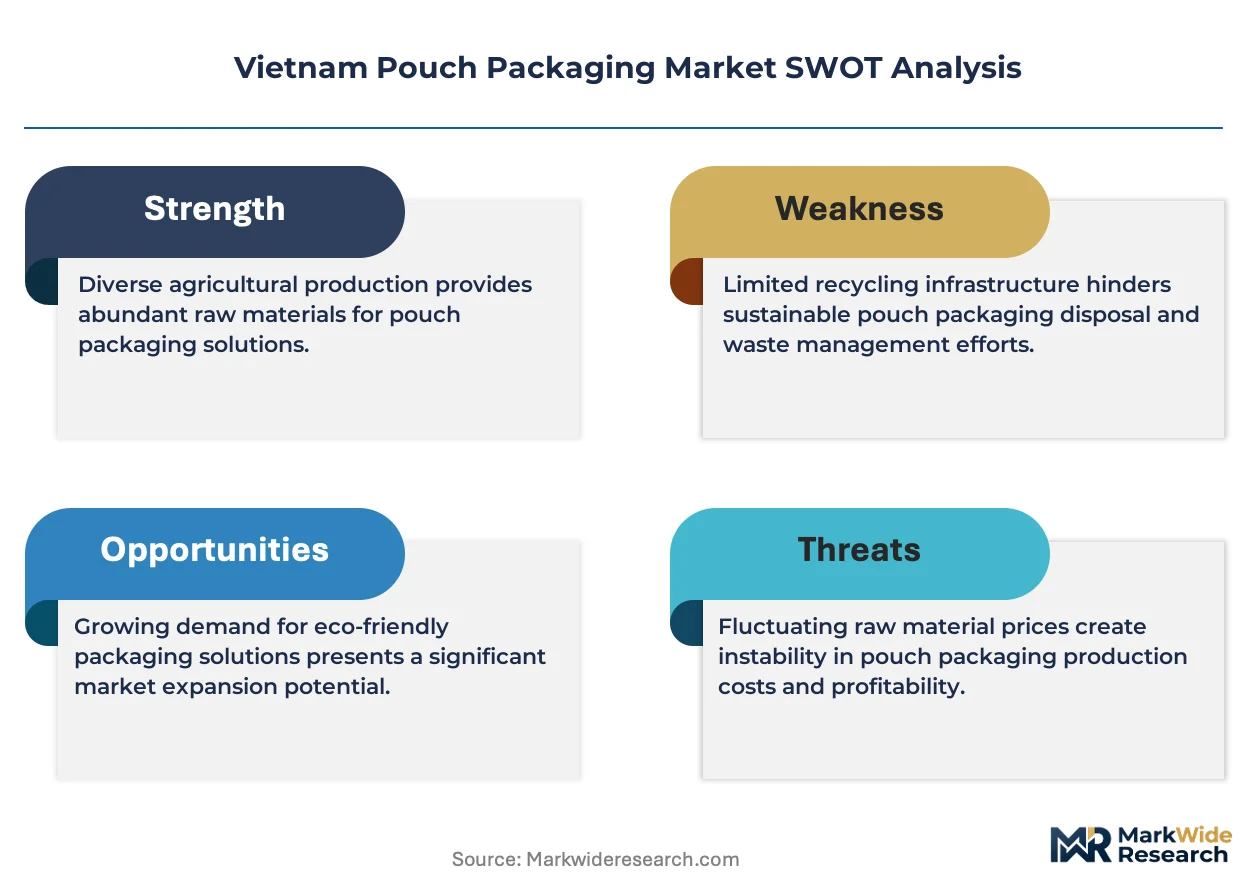
- Ethylene and Propylene Volatility:Domestic converters lack captive polyolefin production, exposing margins to import price swings from Thai and Singaporean resin suppliers.
- Metallized Film Supply Concentration:Technical-grade aluminum oxide deposition capacity concentrates in SCG Packaging's Binh Duong complex, creating single-source risk for high-barrier substrate.
- EU REACH Compliance Friction:Substance-of-very-high-concern declarations for adhesive layers delay export lot approvals by 6-8 weeks for smaller converters lacking in-house regulatory teams.
Strategic Opportunities
- Central Highlands Agriculture:Coffee and dried fruit processors in Lam Dong and Dak Lak provinces remain underpenetrated by flexible packaging, relying on bulk export formats.
- Extended Producer Responsibility:Vietnam's draft EPR framework for packaging waste creates first-mover advantage for converters investing in mono-material recyclable pouch structures.
- E-Commerce Fresh Channels:Cold-chain logistics expansion enables stand-up pouches with modified atmosphere barriers for ready-to-cook meal kits sold through Shopee and Lazada fulfillment centers.
Industry Challenges
- Multilayer Lamination Expertise:Local technical talent scarcity in adhesive formulation and coextrusion die design forces reliance on foreign equipment technicians for line commissioning.
- Retort Certification Timelines:Japan's Food Sanitation Law testing protocols for heat-seal integrity require 12-16 week validation cycles, delaying new product launches for seafood exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Pouch Packaging Market |
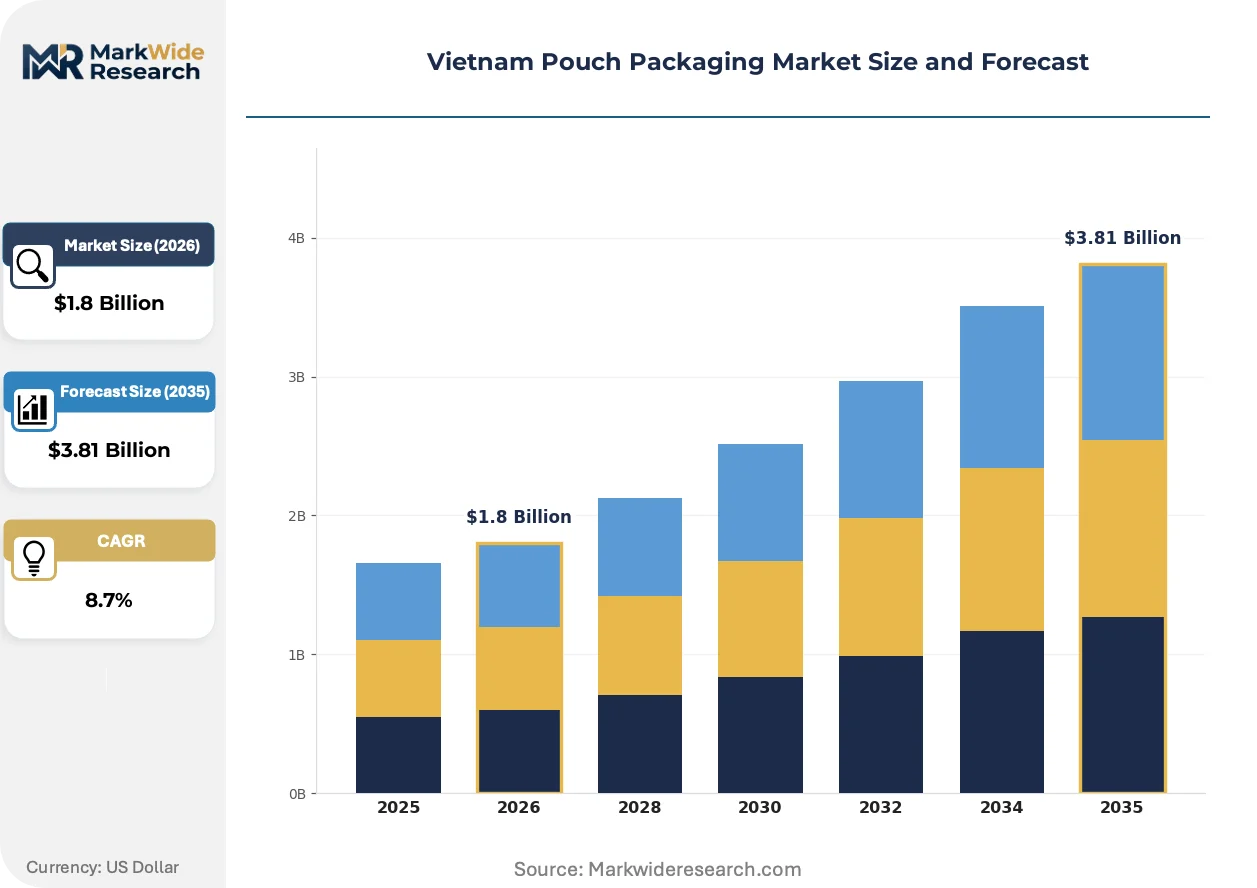
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Retort Pouches, Vacuum Bags Material: Plastic, Paper, Foil, Composites End User: Food & Beverage, Personal Care, Pharmaceutical, Household Products Closure Type: Zip Lock, Spout, Heat Seal, Adhensive |
| Companies Covered | Huhtamaki Oyj, Tetra Pak, SCG Packaging Public Company, Tan Tien Packaging Joint Stock Company, Constantia Flexibles, QLM Label Makers Pty Ltd, ALPLA Werke Alwin Lehner GmbH & Co KG, An Phat Holdings, Duy Tan Plastics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Pouch Packaging Market Trends and Innovations
Barrier-coating technologies and regulatory alignment with EU and Japanese food-contact standards are restructuring how Vietnamese converters design pouch structures for export-bound customers.
Water-based barrier coatings applied to polyethylene terephthalate substrates are electrifying the transition from aluminum foil laminates in retort applications. Seafood processors shipping to Osaka and Tokyo markets are adopting these coatings at pilot scale during 2024-2025. The technology is electrifying margin compression among metallized film suppliers while enabling converters to market recyclable mono-material claims to EU buyers.
Vietnam's Ministry of Health Circular 19/2021 on food-contact plastics is tightening migration testing for aromatic amines and heavy metals in multilayer adhesives. Domestic converters must now submit third-party laboratory reports before customs clearance of finished pouches. Small and mid-tier converters in Long An province are most affected, outsourcing testing to Ho Chi Minh City laboratories and extending delivery lead times by three weeks.
Brand owners in the sauce and condiment segment are consolidating supplier relationships from twelve vendors to three preferred partners with integrated extrusion and printing capabilities. This concentration is displacing spot-market purchasing through trading companies in District 7. The shift is most visible among Japanese-invested food manufacturers in the Vietnam-Singapore Industrial Park who now mandate annual volume commitments with penalty clauses for supply interruption.
Vietnam Pouch Packaging Market Segmentation
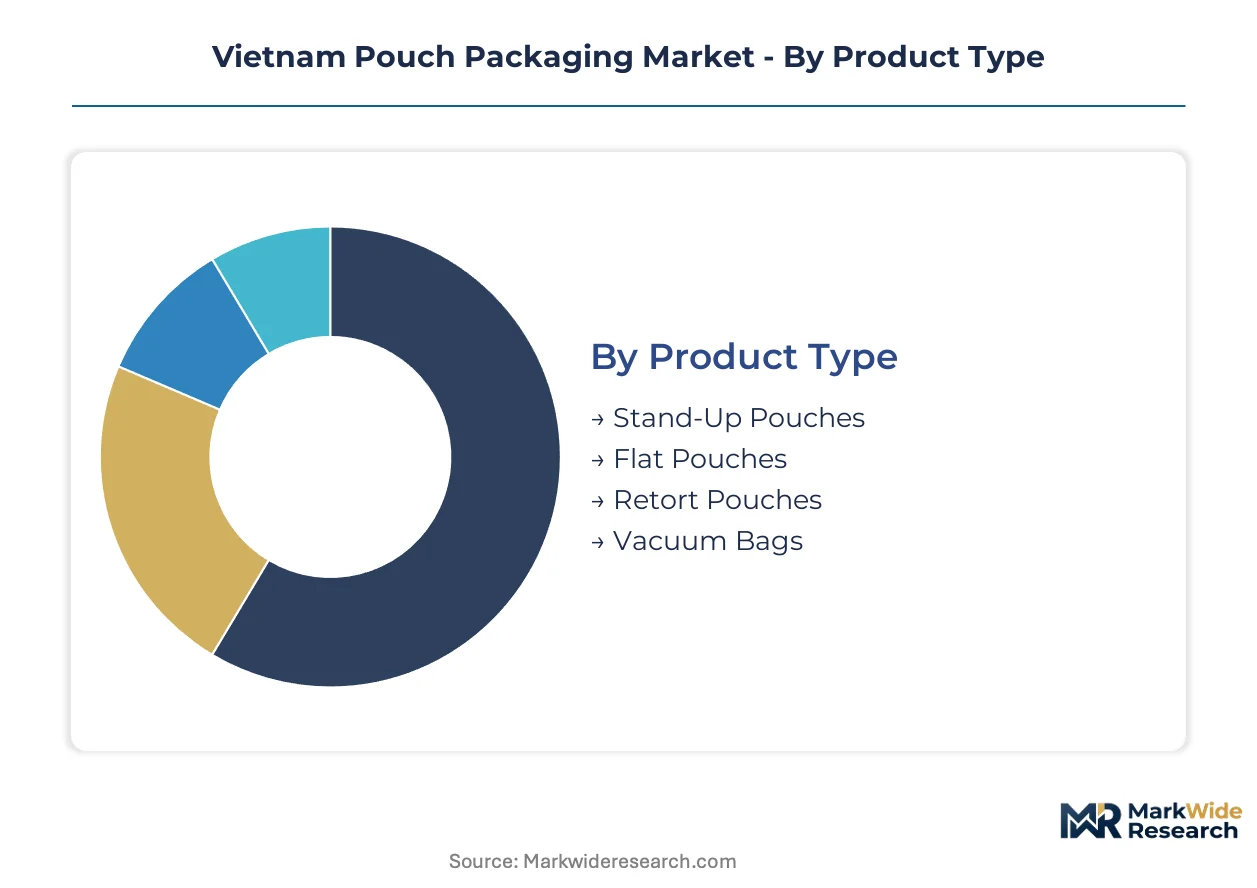
Pouch format selection in Vietnam tracks directly to shelf-life requirements and retail channel formats. Material and closure specifications diverge sharply between export-bound seafood processors and domestic condiment brands serving traditional trade.
Product Type:
Volume deployment clusters around entry-level formats for domestic dry goods, while premium structures command export seafood and ready-meal applications.
- Stand-Up Pouches:These structures incorporate bottom gussets enabling vertical shelf display and typically pair with spout fitments for liquid dispensing. Sauce and cooking oil brands in Ho Chi Minh City's modern trade channels are specifying matte-finish laminates with oxygen barriers below 0.5 cc per square meter per day to extend color stability.
- Retort Pouches:Multilayer constructions withstand 121°C sterilization cycles with aluminum oxide or foil barriers achieving near-zero oxygen transmission. Seafood processors in Ba Ria-Vung Tau province are converting metal canning lines to retort formats for Japanese curry and marinated fish exports, though Japan's Food Sanitation Law validation cycles extend commissioning timelines.
- Flat Pouches:Three-side-seal configurations dominate dried fruit and snack applications where vertical display is unnecessary. Lam Dong coffee processors utilize these for single-serve drip filter packaging.
- Vacuum Bags:Coextruded nylon-polyethylene structures for frozen seafood and meat distribution through wet markets and cold-chain logistics.
Mature deployment sits with flat pouches in traditional trade dry goods. Newer deployment is concentrated in retort structures for export seafood substitution.
Material:
Barrier performance requirements are forcing converters toward complex laminations even as mono-material recyclability pressures intensify.
- Plastic:Polyethylene terephthalate and oriented polypropylene substrates form the base for most multilayer constructions, with converters in Binh Duong province extruding custom sealant layers for tropical humidity resistance.
- Composites:Paper-polymer laminates with water-based barrier coatings are gaining traction among EU-facing exporters seeking recyclable mono-material claims. These structures eliminate aluminum foil while maintaining retort compatibility.
- Foil:Aluminum laminates remain standard for ultra-high-barrier retort applications despite recyclability penalties in European markets.
- Paper:Kraft-based pouches with polymer windows serve organic and premium positioning in domestic specialty retail, though moisture sensitivity limits penetration.
Conventional foil laminates dominate established retort lines. Water-based coated alternatives are climbing the fastest among converters targeting EU compliance.
End User:
Food sector specifications are tightening fastest, while pharmaceutical and personal care applications remain specification laggards.
- Food & Beverage:Retort pouches for seafood exports and stand-up spouted formats for sauces represent the highest specification tier, with Ministry of Health Circular 19/2021 migration testing now mandatory for all food-contact structures.
- Personal Care:Sachet and pouch formats for shampoo and conditioner samples distribute through modern trade and e-commerce sampling programs, utilizing simpler polyethylene constructions without barrier requirements.
- Pharmaceutical:Blister alternatives and unit-dose pouches for over-the-counter medications remain underdeveloped relative to ASEAN peers, with most active ingredients imported in bulk packaging.
- Household Products:Stand-up pouches for laundry detergent refills are displacing rigid bottles in urban supermarkets, driven by shelf-space efficiency and logistics cost reduction.
Established specification discipline sits with food exporters. Emerging deployment is concentrated in household refill formats for modern trade.
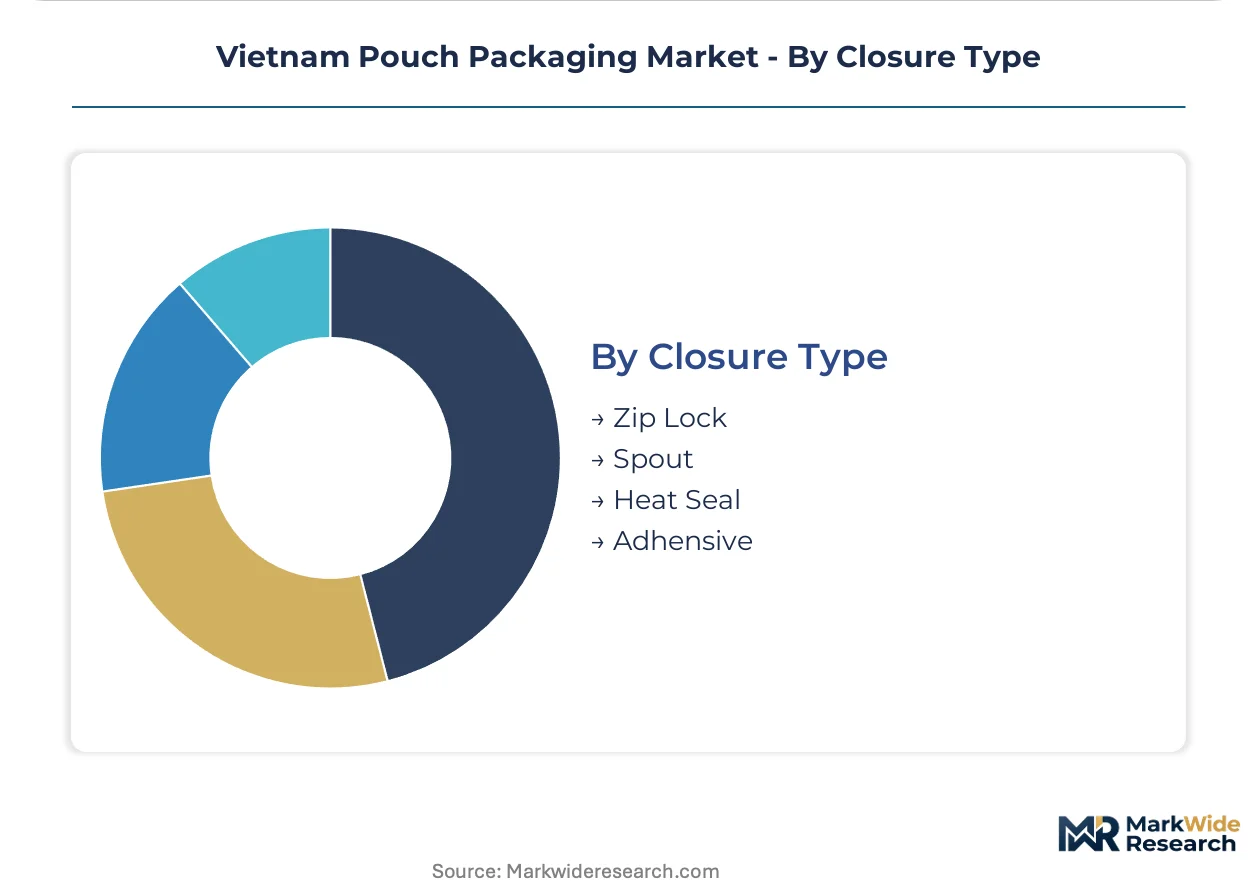
Closure Type:
Convenience features differentiate premium positioning from commodity supply, with resealability commanding substantial format premiums.
- Spout:Injection-molded fitments with tamper-evident rings enable controlled dispensing for cooking sauces and beverages. Japanese-invested manufacturers in the Vietnam-Singapore Industrial Park mandate annual volume commitments for spouted pouch supply.
- Zip Lock:Press-to-close interlocking profiles serve dried snacks and resealable condiment formats, with zipper application equipment concentrated among larger converters with integrated converting lines.
- Heat Seal:Plain seal integrity remains standard for retort and vacuum applications where resealability is unnecessary, with seal strength validation critical for Japan export approval.
- Adhesive:Peel-and-reseal labels serve limited promotional and sample applications with minimal technical barrier requirements.
Basic heat seal deployment dominates retort and vacuum formats. Spout integration represents the steepest expansion trajectory among liquid food processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyolefin resin imports from Thai and Singaporean petrochemical complexes anchor the upstream supply geography for Vietnam's pouch packaging sector. Domestic converting capacity clusters around Ho Chi Minh City's industrial periphery, where Binh Duong and Dong Nai provinces host integrated film extrusion and metallization assets.
Southeast Vietnam
Seafood processors in Ba Ria-Vung Tau province are converting metal canning lines to retort pouch formats for Japanese curry and marinated fish exports. Vietnam's Ministry of Health Circular 19/2021 mandates third-party migration testing for all food-contact plastics before customs clearance. The Vietnam-Singapore Industrial Park in Binh Duong province concentrates Japanese-invested food manufacturers who now mandate annual volume commitments with penalty clauses for supply interruption.
South Central Coast
Export-oriented aquaculture operations in Khanh Hoa and Phu Yen provinces generate demand for high-barrier vacuum bags in frozen shrimp and fish distribution. The General Department of Customs administers import inspections of flexible packaging materials under ASEAN harmonized standards. Nha Trang's cold-chain logistics hubs are expanding modified atmosphere pouch specifications for domestic supermarket distribution.
Central Highlands
Coffee and dried fruit processors in Lam Dong and Dak Lak provinces remain underpenetrated by flexible packaging, relying predominantly on bulk export formats. The country's draft extended producer responsibility framework for packaging waste creates first-mover advantage for converters investing in mono-material recyclable structures. Da Lat's specialty coffee roasting cluster is piloting stand-up pouches with degassing valves for direct-to-consumer channels.
Northern Delta
Condiment and sauce manufacturers in Hanoi and Hai Duong province are specifying matte-finish laminates with oxygen barriers below 0.5 cc per square meter per day for color stability in modern trade. The Ministry of Health's tightening compliance requirements for plastic multilayer structures are accelerating registration among flexible packaging converters. Bac Ninh's electronics manufacturing zones are spilling over demand for anti-static pouches in component logistics.
Vietnam Pouch Packaging Market Competitive Landscape
Global majors compete with regional champions across barrier technology and regulatory compliance capabilities. The vendor base stratifies between integrated multinationals with captive resin and metallization assets, mid-tier regional converters with extrusion and printing integration, and trading-dependent spot suppliers serving commodity dry goods. Three archetypes dominate: technology licensors transferring European coating expertise, upstream-integrated Thai conglomerates controlling film substrate supply, and domestic converters building spout-fitment application capabilities. Competitive intensity centers on M&A-driven consolidation of twelve-vendor relationships into three preferred partnerships, plus capacity expansion in water-based barrier coating lines.
Among technology-licensing specialists, Huhtamaki Oyj leverages its regional technical center to anchor European barrier-coating expertise within local production. SCG Packaging Public Company exemplifies upstream-integrated positioning through its Binh Duong complex controlling film extrusion and metallization substrate supply. Tan Tien Packaging Joint Stock Company occupies a position within the domestic converter tier building integrated spout application and printing capabilities for sauce and condiment brand owners. These three represent distinct competitive vectors: know-how transfer, captive raw material security, and downstream converting integration.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Tetra Pak |
| SCG Packaging Public Company |
| Tan Tien Packaging Joint Stock Company |
| Constantia Flexibles |
| QLM Label Makers Pty Ltd |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| An Phat Holdings |
| Duy Tan Plastics |
| Others |
Pricing and Supply Chain Analysis
Captive metallization capacity at SCG Packaging's Binh Duong complex anchors supply security for high-barrier substrate, simultaneously insulating integrated converters from resin price volatility while compressing margins for trading-dependent spot suppliers serving commodity dry goods.
Pricing Analysis
Annual volume commitments with penalty clauses for supply interruption bundle technical support and regulatory documentation into contract structures for Japanese-invested food manufacturers in the Vietnam-Singapore Industrial Park. Three-tier pricing structure across premium, standard, and economy levels separates EU REACH-compliant multilayer laminates from ASEAN-harmonized domestic formats and unregistered spot-market supply. Cost compression in standard-tier retort pouches is intensifying because seafood processors are consolidating twelve-vendor relationships into three preferred partnerships. Domestic condiment brands serving traditional trade exhibit highest price sensitivity, while export-bound seafood processors prioritize barrier performance over unit cost.
Supply Chain Analysis
Vietnam's Ministry of Health Circular 19/2021 on food-contact plastics is reshaping sourcing patterns by mandating third-party migration testing before customs clearance, effectively screening out unregistered imports. Polyolefin resin supply draws from Thai and Singaporean petrochemical complexes, while technical-grade aluminum oxide deposition capacity centers on SCG Packaging's domestic complex. Single-source vulnerability for metallized film substrate concentrates risk in Binh Duong province. Distribution runs through Ho Chi Minh City's industrial periphery, where Binh Duong and Dong Nai provinces host integrated converting clusters supplying food manufacturing parks with just-in-time logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's pouch packaging sector operates as a cost-of-compliance story where Ministry of Health Circular 19/2021 migration testing requirements erect barrier-to-entry moats favoring converters with in-house regulatory teams and third-party laboratory relationships.
For Market Incumbents: To counter consolidation pressure from twelve-vendor relationships compressing into three preferred partnerships, deepen captive supply of metallized film substrate through capacity expansion in Binh Duong province and secure Japan Food Sanitation Law pre-certification for retort pouch formats to accelerate customer onboarding timelines.
For New Entrants and Emerging Players: Coffee and dried fruit processors in Lam Dong and Dak Lak provinces represent the most penetrable buyer archetype currently reliant on bulk export formats, offering white-space entry through mono-material recyclable pouch structures aligned with Vietnam's draft extended producer responsibility framework and direct technical service presence bypassing Ho Chi Minh City trading intermediaries.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-tier converters with integrated extrusion and spout-fitment application capabilities serving condiment brand owners, with long-term viability hinging on five-to-ten year regulatory compliance moats rather than commodity volume scale; watch for Japan Food Sanitation Law validation cycle delays as inflection indicator for technical-capability scarcity premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Barrier Coating Capacity Expansion | Enables recyclable mono-material claims for EU-facing seafood exporters eliminating aluminum foil laminates. |
| Retort Pouch Certification Pre-Investment | Shortens Japan Food Sanitation Law validation cycles from 16 weeks for new market entrants. |
| Backward Integration into Metallized Film | Reduces single-source dependency on SCG Packaging's Binh Duong complex for high-barrier substrate. |
| Central Highlands Technical Service Deployment | Captures coffee and dried fruit processors in Lam Dong province currently underserved by flexible packaging. |
| Extended Producer Responsibility Compliance Positioning | Creates first-mover advantage for mono-material recyclable structures under Vietnam's draft EPR framework. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with flexible packaging converters, seafood processing procurement leads, Ministry of Health compliance officers, and cold-chain logistics operators. Bottom-up triangulation across extrusion line capacity surveys and top-down validation through ASEAN trade statistics ensured cross-verification of volume estimates. Secondary sources included Vietnam General Department of Customs import records, Ministry of Health Circular 19/2021 implementation guidance, and Japan External Trade Organization seafood export documentation requirements.
Granularity-level modeling deployed product-type segmentation across stand-up, retort, flat, and vacuum pouch formats; material-tier differentiation for plastic, composite, foil, and paper substrates; and closure-type specification for spout, zip-lock, heat-seal, and adhesive configurations. End-user industry splits captured food and beverage, personal care, pharmaceutical, and household product specifications. CAGRs were derived from regression analysis of historical converting capacity expansion against export seafood volume trajectories, with barrier-coating technology adoption curves and extended producer responsibility framework implementation timelines serving as industry-specific forecast modifiers across the analysis window.
Revisions become necessary when Ministry of Health enforcement intensity shifts, Japan Food Sanitation Law testing protocols change, or resin import price volatility from Thai and Singaporean suppliers exceeds historical bands. Forecasts reflect documented assumptions regarding regulatory compliance timelines and technology transfer rates from European coating specialists. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Box Pouch Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
Aluminum Foil Zipper Pouch Market
Pouch
Compostable Pouches Market
Pouch
Digital Printed Pouch Market
Pouch
Vented Stretch Wrap Market
Pouch
Rice Paper Stand Up Pouch Market
Pouch
Peelable Pouches Market
Pouch
United States Retort Pouches Market
Pouch
Germany Pouch Packaging Market
Pouch
United States Pouch Packaging Market
Pouch
Global Medical and Pharmaceutical Pouch Market
Pouch
Global Boil-In Bags Market
Pouch
Global Pouches Packaging Market
Pouch
Center Sealed Pouch Packaging Market
Pouch
South Africa Pouch Packaging Market