
 Europe Retort Pouches Market | 2026-2036
Europe Retort Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Retort Pouches Market Intelligence
Market Context
Premium-grade barrier specifications is collapsing into mainstream retort applications as European brands seek shelf-stable formats without metal can weight. Amcor Plc leverages its continental extrusion network to supply high-barrier films to ready-meal packers. Constantia Flexibles Group GmbH anchors its position through pharmaceutical-grade cleanroom capabilities repurposed for medical and food retort lines. Mondi Plc differentiates via kraft-paper hybrid retort structures targeting Scandinavian sustainability mandates.
Technical Definition and Segment Structure
Europe retort pouches are multi-layer laminated flexible containers, typically combining polyester outer webs, aluminum foil or metallized barriers, and cast polypropylene sealant layers, engineered to withstand 121°C sterilization while maintaining oxygen transmission below 0.1 cc/m²/day for shelf-stable food preservation. Stand-up pouches occupy the dominant value position in retail-facing applications, while zipper-equipped variants register the fastest structural expansion as resealability commands shelf price premiums over single-serve flat formats. Polyester-aluminum-polypropylene triplex constructions retain the largest material share, though aluminum-free barrier coatings are capturing R&D investment as ECHA scrutiny on composite recyclability intensifies.
Regulatory Framework and Outlook
REACH governs chemical migration limits across all retort contact layers, while the EU Green Deal and Packaging and Packaging Waste Regulation compel redesign for mono-material recyclability by 2030. EFSA compliance for post-consumer recycled content in food-contact layers is opening pilot lines but remains restrictive for high-acid retort applications. Stakeholders must monitor ECHA substance restriction proposals on per- and polyfluoroalkyl barrier coatings, as these rulings will force material system transitions within the decade.
Market Dynamics
REACH compliance deadlines and the EU Green Deal's 2030 recyclability mandates are forcing retort pouch converters to abandon aluminum-foil triplex structures faster than pilot lines for mono-material alternatives can scale, creating a supply bottleneck for shelf-stable food brands.
Growth Catalysts
- Ready-to-eat meal adoption:Urban consumers in Germany and France are shifting from frozen to shelf-stable formats, expanding pouch volumes in retail and foodservice channels.
- EU Green Deal packaging mandates:The Packaging and Packaging Waste Regulation is compelling brands to redesign for mono-material recyclability, accelerating R&D investment in barrier coatings.
- Aluminum-free barrier coatings:High-performance oxide and polymer barrier technologies are reaching commercial viability, enabling converters to meet ECHA scrutiny on composite recyclability.
Market Restraints
- Polypropylene supply concentration:Cast PP sealant resin production clusters in Belgium and the Netherlands create vulnerability to feedstock volatility and logistics disruptions.
- Recyclability certification delays:EFSA approval timelines for post-consumer recycled content in food-contact layers extend 18-24 months, blocking rapid material transitions.
- Metal can substitution economics:Established canning infrastructure in Southern Europe maintains cost advantages for high-volume commodity categories, limiting pouch penetration.
Strategic Opportunities
- Scandinavian sustainability premiums:Sweden and Denmark retailers are mandating plastic-reduction targets that favor kraft-paper hybrid retort structures with verified lifecycle credentials.
- Medical device sterilization:Pharmaceutical-grade cleanroom capabilities at Central European converters can pivot toward retort pouches for surgical kits and sterilized instruments.
- Zipper-equipped resealable formats:Convenience-driven consumers in Italy and Spain are paying shelf-price premiums for multi-serve pouches with integrated closure systems.
Industry Challenges
- Multi-layer lamination expertise scarcity:The specialized workforce for high-barrier adhesive lamination and retort sterilization validation is concentrated among aging technicians in Germany and Austria.
- Legacy filling line incompatibility:European canneries retrofitting for pouch formats face capital-intensive modifications to retort basket systems and sealing heads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Retort Pouches Market |
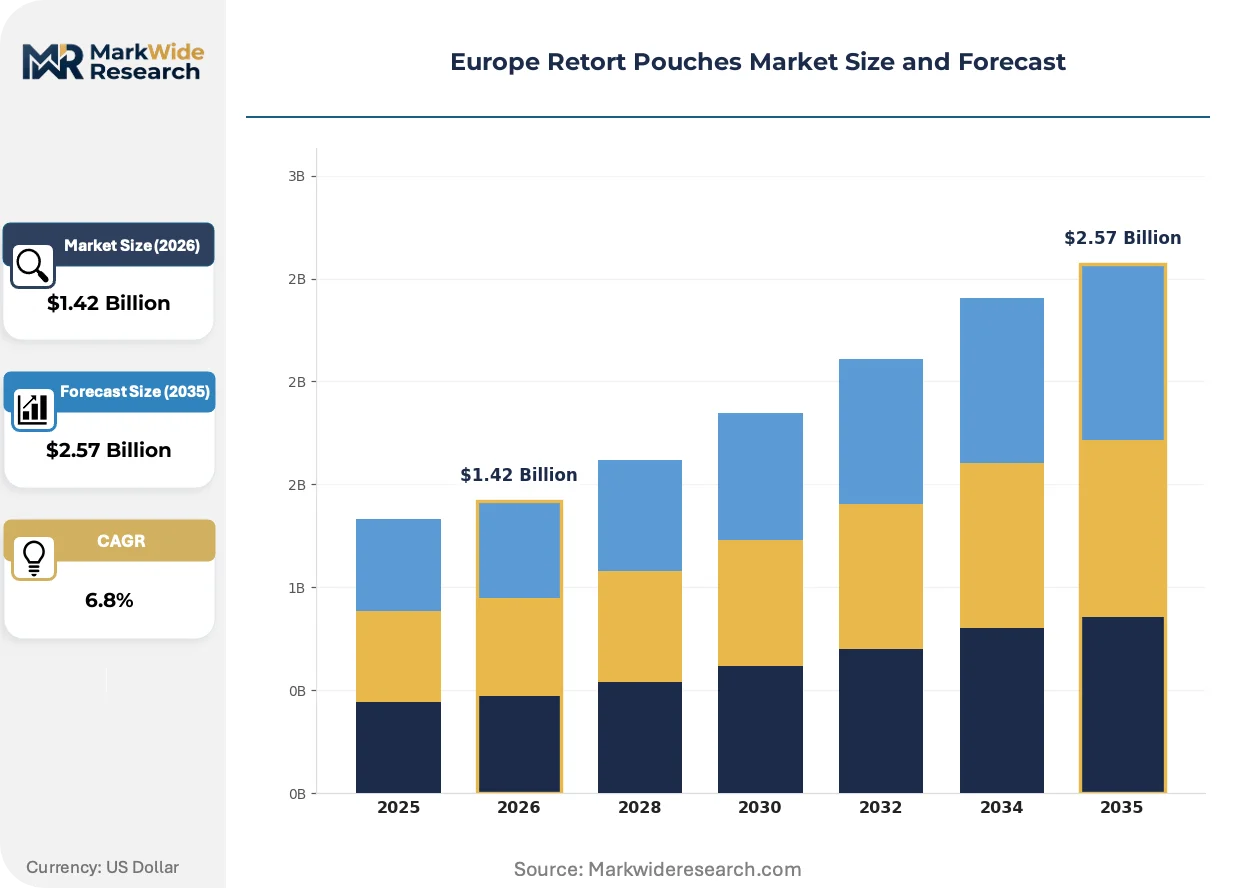
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Side Gusset Pouches, Zipper Pouches Material: Polyester, Aluminum, Polypropylene, Nylon End User: Food & Beverage, Healthcare, Pet Food, Ready-to-Eat Meals Packaging Type: Single-Serve, Multi-Serve, Flexible, Resealable |
| Companies Covered | Coveris Management GmbH, Flair Flexible Packaging Corporation, Amcor Plc, Constantia Flexibles Group GmbH, Winpak Ltd, Sonoco Products Company, Sealed Air, Huhtamaki Oyj, Mondi Plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Retort Pouches Market Strategic Shifts & Innovations
Barrier technology substitution is outpacing equipment adaptation, with converters racing to validate aluminum-free structures before regulatory deadlines eliminate legacy specifications.
Ethylene vinyl alcohol copolymer is fragmenting the oxygen barrier layer market as converters blend it with polyolefins to create mono-material recyclable structures. Italian pasta sauce and ready-meal packers are piloting these formulations at commercial scale. The shift is fragmenting converter capabilities between those with metallized film expertise and those investing in coextrusion coating lines.
REACH substance restriction proposals on per- and polyfluoroalkyl barrier coatings are forcing material system transitions across the European supply base. The European Chemicals Agency scrutiny is eliminating fluorinated options from new product development pipelines. High-acid retort applications in France and Germany are most affected, with brands accelerating trials of silicon oxide and aluminum oxide alternatives.
Retail private-label concentration is compressing supplier margins and consolidating procurement decisions among fewer category managers. Discounters in Germany and hard-format retailers in France are unbundling technical specification setting from volume purchasing, forcing mid-tier converters into toll-manufacturing arrangements. The shift is most visible in standard flat pouch formats for commodity vegetables and legumes.
Europe Retort Pouches Market Segmentation
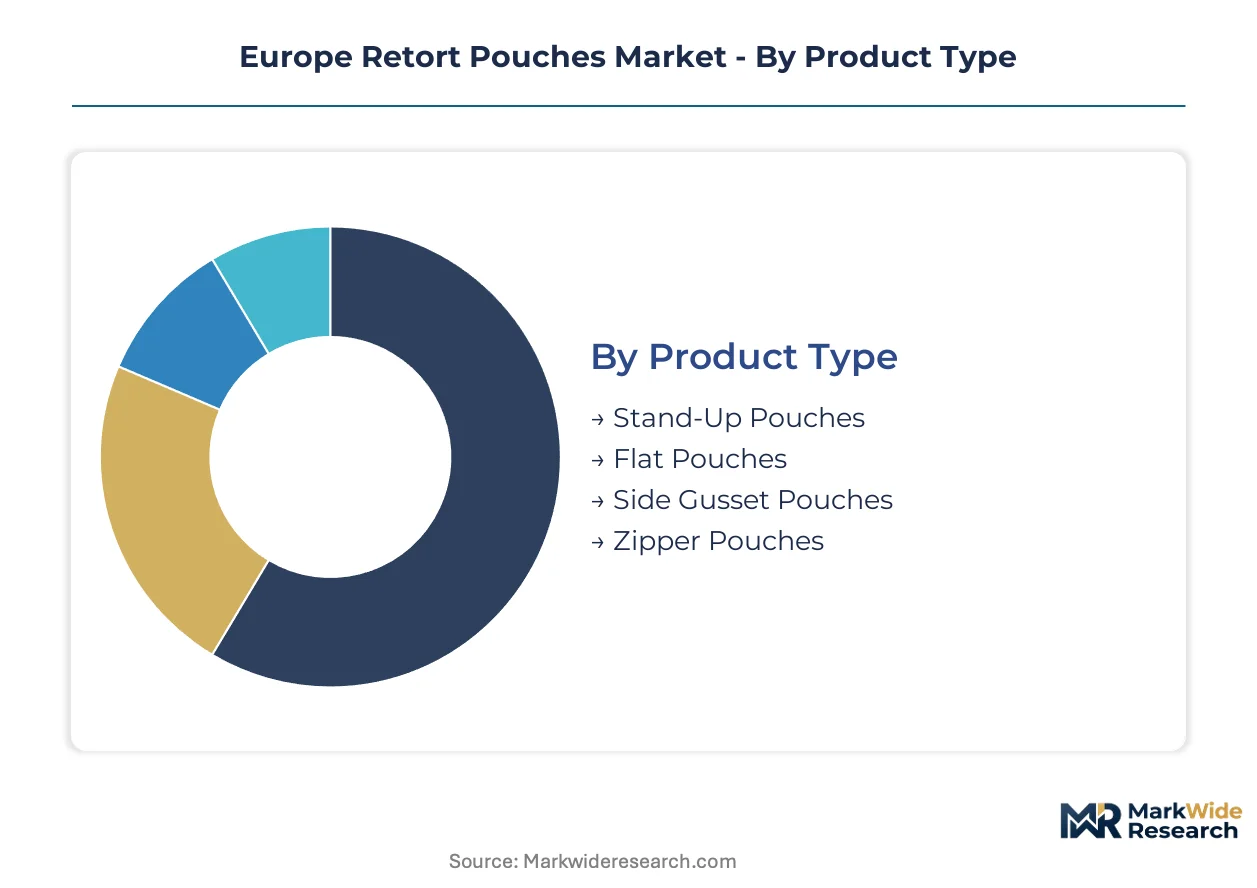
Retort pouch converters must align product architectures with diverging pressure points: metal can substitution in commodity categories, sustainability mandates in premium retail, and sterilization reliability in medical applications. Segment selection determines barrier technology investment, recyclability pathway, and margin structure.
Product Type:
Substitution pressure from rigid containers falls unevenly across formats, with flat pouches most exposed to metal can economics while stand-up configurations defend shelf presence.
- Stand-Up Pouches:These structures incorporate gusseted bases enabling vertical shelf display, commanding price premiums in German and French retail environments. Demand concentrates in ready-to-eat meal applications where brand visibility drives purchasing decisions, though material costs run higher than flat alternatives.
- Zipper Pouches:Integrated closure systems add mechanical complexity and sealant layer requirements, with Italian and Spanish consumers paying shelf premiums for multi-serve resealability. The format faces technical constraints in high-acid retort applications where zipper integrity under thermal cycling remains unproven at commercial scale.
- Flat Pouches:Lowest unit cost position makes these the default for commodity vegetable and legume categories in Southern European canneries, where established metal infrastructure limits conversion economics.
- Side Gusset Pouches:Intermediate structure offering expanded volume capacity for institutional foodservice channels, with Belgian converters specializing in four-side-seal variants for hospital and military supply contracts.
Stand-Up Pouches anchors the volume base while Zipper Pouches gains share at the steepest rate.
Material:
Cost tier stratification separates legacy triplex constructions from emerging mono-material alternatives, with margin pressure most acute in aluminum-dependent supply chains.
- Polyester:Outer web layer providing printability and mechanical strength, with biaxially oriented grades dominating retail-facing applications. German film extruders supply high-clarity variants for premium ready-meal brands seeking shelf differentiation.
- Aluminum:Foil barrier layer delivering sub-0.1 cc/m²/day oxygen transmission, now facing ECHA scrutiny on composite recyclability that threatens its long-term position in EU Green Deal compliance frameworks.
- Polypropylene:Cast PP sealant layers enable heat-seal integrity at 121°C sterilization temperatures, with production concentrated in Belgian and Dutch resin facilities vulnerable to feedstock volatility.
- Nylon:Intermediate layer providing puncture resistance and mechanical durability, with demand clustering in pet food applications where bone fragment containment requires enhanced toughness.
Polyester and Polypropylene together constitute the material foundation, though aluminum-free barrier development is climbing the fastest as regulatory deadlines approach.
End User:
Application maturity varies sharply, with foodservice channels standardizing on pouch formats while medical sterilization represents untested expansion territory.
- Ready-to-Eat Meals:Urban consumption patterns in France and Germany are shifting from frozen to shelf-stable formats, with pouch volumes expanding in both retail and foodservice channels as convenience positioning justifies price premiums.
- Food & Beverage:Broader category encompassing sauces, soups, and prepared vegetables, with Italian pasta sauce packers piloting EVOH-based mono-material structures at commercial scale.
- Pet Food:Premium wet food segments in Scandinavian markets are adopting retort pouches for portion control and freshness positioning, though volume remains constrained by canning infrastructure in mass-market tiers.
- Healthcare:Surgical kit and sterilized instrument applications leverage pharmaceutical-grade cleanroom capabilities at Central European converters, with EFSA compliance timelines blocking rapid material transitions for food-contact adjacent uses.
Food & Beverage holds the installed base while Ready-to-Eat Meals expands most quickly.
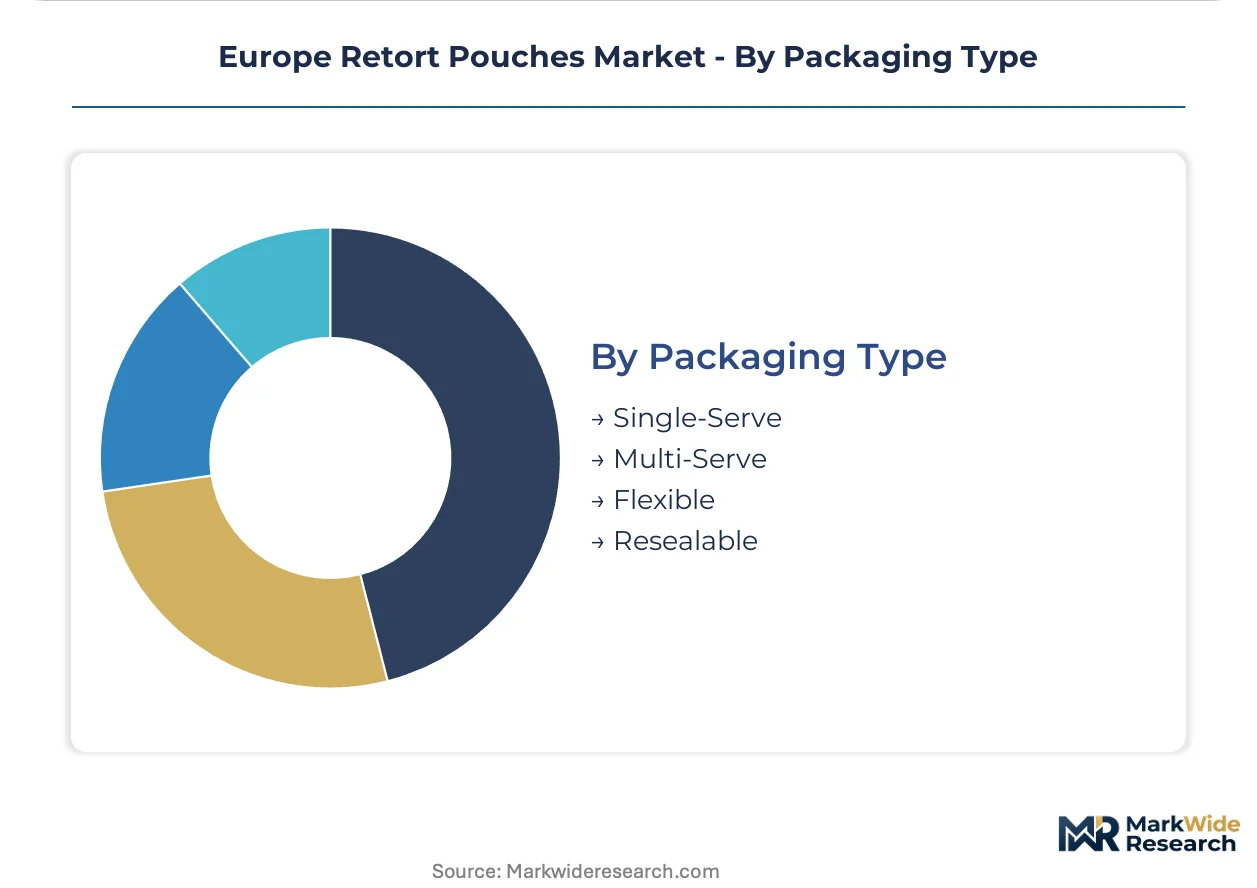
Packaging Type:
Customer type differentiation separates institutional procurement from retail convenience positioning, with volume scale favoring single-serve formats and margin capture residing in resealable multi-serve.
- Resealable:Zipper-equipped and spouted variants commanding shelf-price premiums, with French hard-format retailers and German discounters unbundling technical specification from volume purchasing.
- Multi-Serve:Larger capacity formats targeting family consumption and foodservice channels, with Spanish retail private-label concentration compressing supplier margins.
- Single-Serve:Standard flat and stand-up configurations dominating commodity categories, with Southern European canneries maintaining cost advantages through legacy filling line utilization.
- Flexible:General classification encompassing all non-rigid retort structures, with recyclability certification delays extending 18-24 months for post-consumer recycled content integration.
Single-Serve maintains volume leadership while Resealable captures the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retort pouch conversion capacity clusters in Germany, France, and Italy where food processing infrastructure and retail modernization sustain demand. Belgium and the Netherlands anchor resin supply chains for cast polypropylene sealant layers. REACH compliance deadlines and EU Green Deal recyclability mandates are forcing material transitions across all five markets.
Germany
Ready-to-eat meal demand from urban consumers in Berlin and Hamburg is shifting volumes from frozen to shelf-stable formats. The Packaging and Packaging Waste Regulation compels brands to redesign for mono-material recyclability by 2030. Bavarian converters in the Munich-Stuttgart corridor are piloting EVOH-based barrier coatings to replace aluminum foil in high-acid applications.
France
Hard-format retailers in Paris and Lyon are unbundling technical specification setting from volume purchasing, consolidating procurement among fewer category managers. ECHA scrutiny on per- and polyfluoroalkyl barrier coatings is eliminating fluorinated options from new product development pipelines. The Auvergne-Rhône-Alpes region hosts pasta sauce packers trialing silicon oxide alternatives at commercial scale.
Italy
Convenience-driven consumers in Milan and Rome are paying shelf-price premiums for zipper-equipped resealable pouches in multi-serve formats. EFSA approval timelines for post-consumer recycled content in food-contact layers extend 18-24 months, blocking rapid material transitions. Emilia-Romagna's food processing clusters maintain legacy canning infrastructure that limits pouch penetration in commodity vegetable categories.
Belgium
Cast polypropylene sealant resin production concentrates in Antwerp and Ghent, creating vulnerability to feedstock volatility and logistics disruptions. The EU Green Deal's 2030 targets are accelerating R&D investment in barrier coatings among local film extruders. Brussels-based converters supply four-side-seal variants to hospital and military foodservice contracts across the Benelux.
Netherlands
Rotterdam's port infrastructure supports import-dependent resin supply chains for retort laminate production. REACH chemical migration limits govern all contact layer formulations processed through Dutch extrusion facilities. Randstad-based converters are repurposing pharmaceutical-grade cleanroom capabilities for medical sterilization pouch lines serving surgical kit manufacturers.
Europe Retort Pouches Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the European retort pouch supply base. The market structure consolidates around integrated film extruders with continental distribution networks, mid-tier toll manufacturers serving private-label concentration, and specialty converters with pharmaceutical-grade cleanroom certifications. Three archetypes dominate: barrier technology specialists, scale-driven commodity producers, and sustainability-focused hybrid material innovators. Competitive moves center on aluminum-free barrier validation and mono-material pilot line scaling ahead of regulatory deadlines.
Among the integrated multinational tier, Amcor Plc and Mondi Plc exemplify divergent strategic positioning within the same regulatory environment. Amcor anchors the barrier technology specialist archetype through its continental extrusion network supplying high-barrier films to ready-meal packers. Mondi occupies the sustainability-focused innovator position via kraft-paper hybrid retort structures targeting Scandinavian plastic-reduction mandates. Constantia Flexibles Group GmbH represents the specialty converter archetype, sitting within the pharmaceutical-grade cleanroom certification tier that serves both medical sterilization and premium food retort applications.
| Leading Market Players |
|---|
| Coveris Management GmbH |
| Flair Flexible Packaging Corporation |
| Amcor Plc |
| Constantia Flexibles Group GmbH |
| Winpak Ltd |
| Sonoco Products Company |
| Sealed Air |
| Huhtamaki Oyj |
| Mondi Plc |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day lead times for cast polypropylene sealant resin from Belgian and Dutch producers concentrate pricing power among integrated film extruders while forcing toll manufacturers into margin-compressing contract terms. This inventory compression dynamic intensifies as REACH compliance deadlines accelerate material system transitions before alternative supply chains mature.
Pricing Analysis
REACH chemical migration limits dictate the pricing tier structure across European retort pouch supply. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade cleanroom-certified converters from commodity flat pouch producers and toll-manufacturing mid-tiers. Price differentiation stems from EFSA compliance certification and vertical integration into resin extrusion. Cost compression in standard flat formats is intensifying because retail private-label concentration unbundles technical specification from volume purchasing. Discounters and hard-format retailers exhibit highest price sensitivity; medical sterilization buyers demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Rotterdam port congestion and container availability constraints on Asia-Europe trade lanes amplify feedstock volatility for polyester and polypropylene imports. Geographic supply concentration centers on Belgium, the Netherlands, and Germany for cast PP sealant resin, biaxially oriented polyester film, and adhesive lamination chemicals. Raw material dependencies rest on ethylene and propylene feedstocks, metallized film substrates, and high-barrier coating formulations. Single-source vulnerability concentrates in Antwerp-Ghent resin production clusters. Distribution runs through converter-direct relationships with ready-meal packers and foodservice procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates durable defensive moats for converters with validated aluminum-free barrier structures, as ECHA substance restrictions and EU Green Deal deadlines compound switching costs for food brands.
For Market Incumbents: Fortify barrier technology leadership by scaling EVOH-based mono-material pilot lines ahead of 2030 recyclability mandates. Deepen upstream control over cast PP sealant resin through captive supply agreements with Belgian producers. Aluminum-foil-dependent legacy structures represent the primary threat vector; certification investment in silicon oxide and aluminum oxide alternatives anchors defensible positioning. For New Entrants and Emerging Players: EFSA fast-track approval for post-consumer recycled content in food-contact layers opens white-space entry. Target Scandinavian sustainability premiums where kraft-paper hybrid structures command shelf-price premiums. Medical sterilization pouches for surgical kits offer the most penetrable adjacent application. Go-to-market angle: pharmaceutical-grade cleanroom certification repurposed for food-adjacent healthcare uses. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational packaging parents seeking to divest non-core European flexible film assets. Five-to-ten-year viability hinges on aluminum-free barrier validation and mono-material recyclability certification. Acquisition archetype: mid-tier converters with existing EVOH coextrusion capabilities and stranded pharmaceutical cleanroom assets. Signal to watch: EFSA approval velocity for post-consumer recycled content as inflection indicator for material transition pace.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Pilot Line Scale-Up | REACH and EU Green Deal deadlines force aluminum-foil substitution before 2030 compliance windows close. |
| Pharmaceutical Cleanroom Certification | EFSA-compliant medical sterilization pouches unlock premium pricing in surgical kit adjacent markets. |
| Backward Integration into Resin Supply | Captive cast PP production from Belgian facilities insulates against Antwerp-Ghent feedstock volatility. |
| Scandinavian Sustainability Partnership | Kraft-paper hybrid structures with verified lifecycle credentials capture plastic-reduction mandates in Sweden and Denmark. |
| Zipper-Equipped Format Expansion | Italian and Spanish convenience positioning commands shelf-price premiums for resealable multi-serve configurations. |
Research Approach
Operator-level perspectives from retort line engineers, adhesive lamination technicians, food brand packaging directors, and EFSA regulatory affairs specialists anchored the qualitative base. Primary interviews combined with secondary validation from REACH substance restriction databases, EU Green Deal implementation trackers, and customs trade data for polyester and polypropylene film imports. Bottom-up capacity modeling triangulated against top-down ready-meal consumption forecasts.
Sensitivity analysis across barrier technology substitution rates, resin price volatility bands, and regulatory approval timelines shaped the analytical framework. Segmentation dimensions modeled include product format, material system, end-use application, and regional conversion cluster. CAGRs derived from installed base erosion rates for aluminum-foil triplex structures and pilot line scaling curves for mono-material alternatives. Forecast inputs incorporated ECHA substance restriction probability assessments and EFSA approval pipeline velocity.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal implementation and no EFSA regulatory reversal; material deviation would warrant model refresh. Specific risk factors include accelerated ECHA bans on barrier coatings, Antwerp-Ghent resin supply disruptions, and Southern European cannery infrastructure lock-in. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Ziplock Products Market
Pouch
Digital Printed Pouch Market
Pouch
Flexible Pouch Market
Pouch
Zipper Pouch Market
Pouch
Open Mouth Sacks Market
Pouch
Spout and Non-Spout Liquid Pouch Packaging Market
Pouch
Liquid Pouch Market
Pouch
Feed Pouches Market
Pouch
Stand Up Paper Pouches Market
Pouch
Child Resistant Locking Pouches Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
United States Pouch Packaging Market
Pouch
Utility Pouches Market
Pouch
2 Seal Pouches Market
Pouch
Horizontal Premade Pouch Packing Machine Market
Pouch
Global Medical and Pharmaceutical Pouch Market