
 Flat Bottom Pouch Market | 2026-2036
Flat Bottom Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Flat Bottom Pouch Market Analysis
Project finance for automated pouch-converting equipment is narrowing the competitive field to firms with balance-sheet capacity or leasing partnerships. Huhtamaki leverages its European converting footprint to supply branded food manufacturers at scale. Mondi Group anchors its position through captive kraft paper supply and integrated film extrusion. Sealed Air competes via outcome-based service contracts that bundle equipment with material supply.
A flat bottom pouch is a flexible packaging format with gusseted side walls and a welded rectangular base that enables vertical shelf display and optimized cube utilization during distribution; multilayer constructions typically incorporate polyethylene sealant layers, BOPP print webs, and nylon or EVOH barrier films to protect oxygen-sensitive contents. Food packaging applications dominate volume, with heat-seal closures retaining share in dry goods while zip-lock and spout variants capture margin pools in ready-to-eat and liquid segments. Polyethylene and BOPP material combinations lead unit economics, though kraft paper laminates are gaining traction where fiber-based shelf presence commands retail premiums.
FDA food-contact regulations govern material composition and migration limits for pouches distributed in the United States, while the EU Packaging and Packaging Waste Regulation and REACH chemical frameworks shape design-for-recycling mandates across European supply chains. E-commerce fulfillment requirements from major retail platforms are adding dimensional and drop-test specifications that filter supplier qualification. Stakeholders must monitor how extended producer responsibility fee structures evolve, since these will determine whether mono-material or multilayer constructions deliver lower total cost of ownership.
Market Dynamics
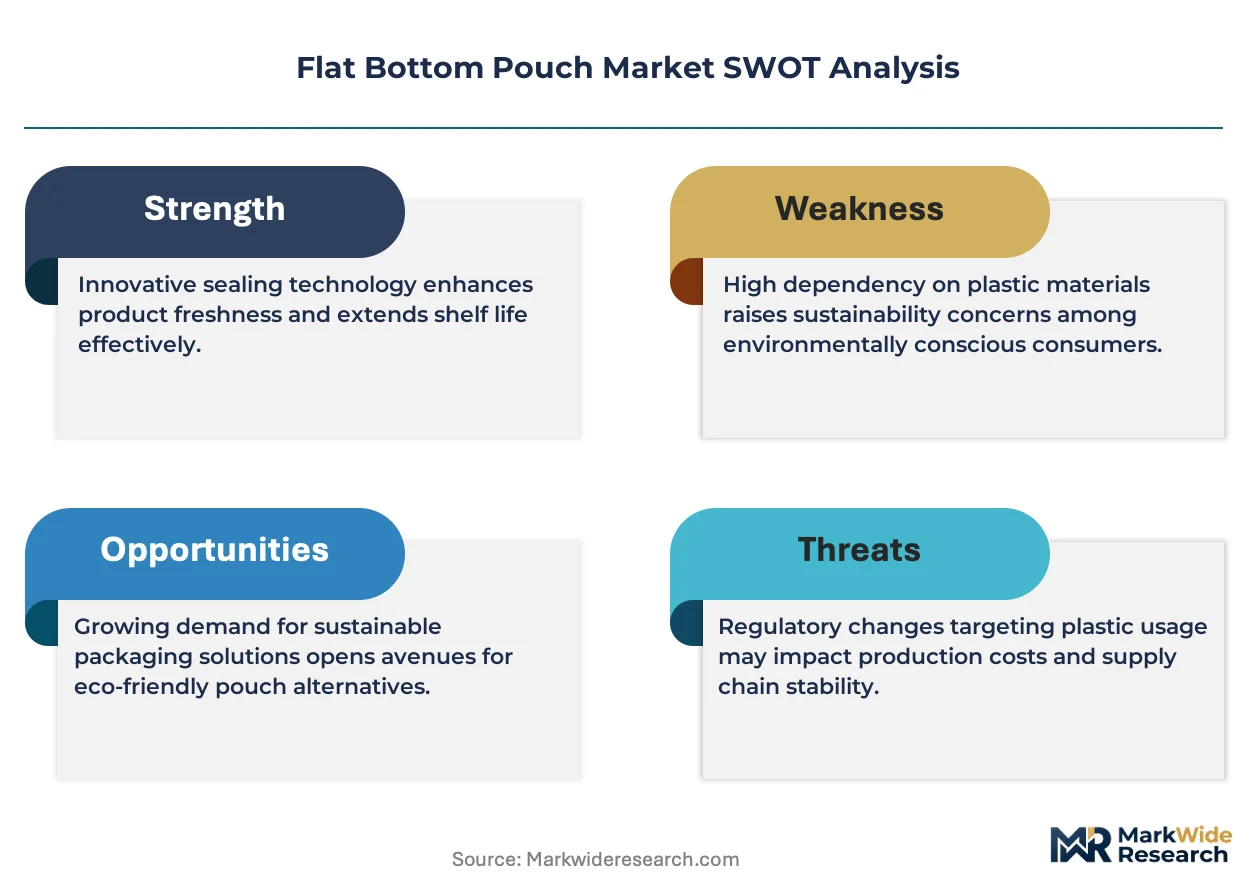
The EU Packaging and Packaging Waste Regulation is forcing material recovery redesigns across European supply chains, compressing converter margins while creating first-mover advantages for firms with mono-material capabilities.
Growth Catalysts
- Premium Pet Food Shelf Differentiation:Branded pet food manufacturers in Germany and France are retrofitting filling lines for flat-bottom formats to command retail premiums through vertical display stability.
- REACH Chemical Framework:ECHA's migration limit tightening is accelerating adoption of high-barrier EVOH laminates in oxygen-sensitive food applications.
- E-Commerce Dimensional Specifications:Major retail fulfillment platforms are mandating drop-test and cube-optimization standards that flat-bottom pouches uniquely satisfy.
Market Restraints
- Kraft Paper Supply Concentration:Captive pulp integration among Nordic producers limits independent converter access to fiber-based substrates.
- Multilayer Recycling Technical Limitation:Current mechanical separation processes cannot recover polyethylene sealant layers from nylon barrier films at commercial scale.
- Extended Producer Responsibility Fee Uncertainty:Pending EU fee structures for non-recyclable packaging create investment paralysis among mid-tier converters.
Strategic Opportunities
- Spout-Equipped Liquid Segments:Ready-to-drink beverage manufacturers in Spain and Italy represent underpenetrated demand for reclosable flat-bottom formats.
- Mono-Material Design-for-Recycling Mandates:The EU Green Deal's 2030 recyclability targets create regulatory tailwinds for all-polyethylene constructions.
- Outcome-Based Equipment Leasing:Bundled service contracts that tie material supply to line efficiency metrics are displacing traditional capex purchase models.
Industry Challenges
- Retrofit Engineering Skill Scarcity:Filling line conversion for gusseted formats requires specialized mechanical expertise concentrated among German and Austrian equipment specialists.
- Legacy ERP Integration Friction:Automated pouch-converting equipment demands real-time production data feeds that conflict with existing MRP systems at family-owned food processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flat Bottom Pouch Market |
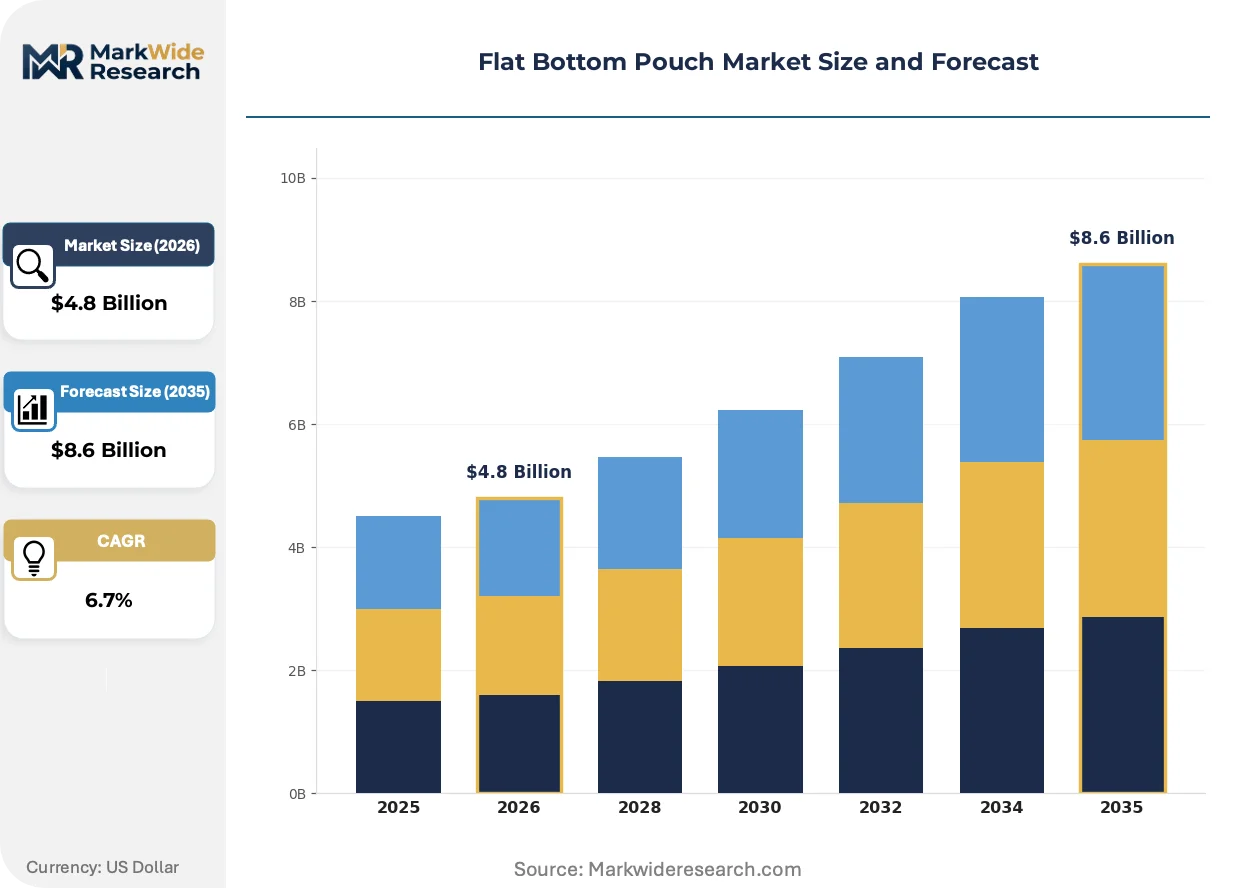
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, BOPP, Nylon, Kraft Paper Closure Type: Zip Lock, Heat Seal, Tear Notch, Spout Application: Food Packaging, Pet Food, Beverage Packaging, Healthcare Products End User: Retail Stores, E-commerce, Food Manufacturers, Pharmaceutical Companies |
| Companies Covered | Smurfit Kappa, Huhtamaki, Mondi Group, Glenroy, Sealed Air, Amcor, ProAmpac, Coveris, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flat Bottom Pouch Market Emerging Trajectories
Digital printing and smart packaging technologies are compressing minimum order quantities while enabling batch-level traceability, reshaping how converters compete for fragmented brand portfolios.
Laser scoring for easy-open features is virtualizing the traditional mechanical tear-notch approach in high-margin snack applications. Premium nut and dried fruit brands in the Netherlands and Belgium are specifying scored film constructions for 40% of new product launches. This technology is virtualizing the capital equipment requirements for format flexibility, allowing converters to serve multiple SKUs without dedicated die stations.
REACH authorization list expansion is restricting certain phthalate plasticizers in food-contact films, compelling sealant layer reformulation across European supply chains. Compounders are accelerating migration to bio-based alternatives derived from castor oil. Ready-to-eat salad producers in France face the tightest compliance timelines, with Q3 2025 as the transition deadline for existing inventory.
Brand procurement teams are consolidating supplier panels to three preferred partners per region, replacing the previous fragmented multi-source model. This concentration is compressing quotation cycles and demanding integrated design services from converters. The shift is most visible among German private-label food manufacturers, where technical packaging directors now mandate single-point accountability for format development, material supply, and equipment optimization.
Flat Bottom Pouch Market Segmentation
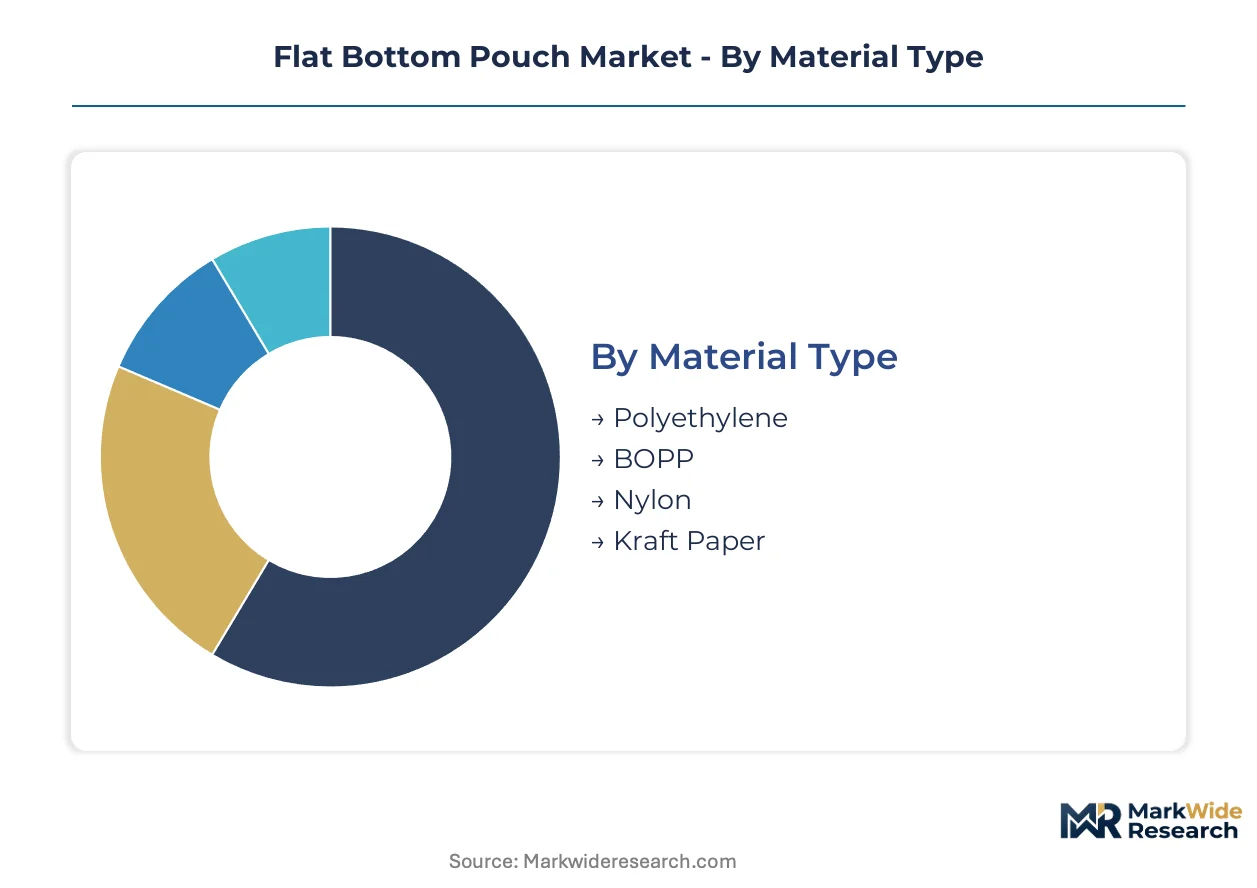
Flat bottom pouch converters must align production capabilities with divergent technical specifications across material grades and closure formats. After-sales service intensity varies sharply by segment, with spout-equipped liquid formats demanding sustained field engineering support while heat-seal dry goods require minimal post-installation intervention.
Material Type:
After-sales service intensity peaks with multilayer barrier constructions requiring calibration support for seal integrity validation.
- Polyethylene:Sealant-grade PE formulations dominate mono-material constructions targeting EU recyclability mandates. German pet food brands are retrofitting lines for all-PE formats to preempt extended producer responsibility fee structures.
- BOPP:Biaxially oriented polypropylene print webs deliver high-definition graphics for premium shelf differentiation. French and Dutch nut brands specify BOPP outer layers for 60% of new launches requiring matte or gloss aesthetic finishes.
- Nylon:PA6 and PA66 barrier layers protect oxygen-sensitive contents in extended-shelf-life applications.
- Kraft Paper:Fiber-based laminates command retail premiums where natural shelf presence differentiates organic and artisanal product lines.
By volume, polyethylene leads. By growth pace, kraft paper is expanding most quickly.
Closure Type:
Cost tier separation drives procurement patterns, with spout formats commanding 3-4x equipment investment versus heat-seal alternatives.
- Zip Lock:Reclosable interlocking profiles capture margin pools in ready-to-eat snacks and portion-controlled dried fruits. Belgian and Spanish brands are specifying zip-lock flat bottoms for 45% of new product launches in the premium nut segment.
- Heat Seal:Welded seam constructions retain unit economics leadership in dry goods and bulk commodities. German private-label manufacturers favor heat-seal formats for their compatibility with legacy filling infrastructure.
- Tear Notch:Laser-scored easy-open features are displacing mechanical notch dies in high-margin applications.
- Spout:Fitment-equipped formats enable liquid and semi-liquid dispensing with reclosure functionality.
By installed base, heat seal dominates. By margin expansion, spout formats are gaining share fastest.
Application:
Application concentration determines converter capacity planning, with food packaging absorbing the majority of extrusion and converting assets.
- Food Packaging:Dry goods, snacks, and bakery applications drive baseline volume for flat-bottom pouch converters. Italian pasta and German confectionery manufacturers are retrofitting existing lines for gusseted formats to optimize cube utilization in retail distribution.
- Pet Food:Premium kibble and treat brands leverage vertical display stability for shelf differentiation. French and German pet food manufacturers represent the most active retrofit demand for high-barrier multilayer constructions.
- Beverage Packaging:Ready-to-drink and liquid concentrates require spout integration and enhanced drop-test performance.
- Healthcare Products:Medical nutrition and pharmaceutical powders demand validated seal integrity and batch traceability.
By revenue scale, food packaging leads. By retrofit activity, pet food shows the steepest expansion trajectory.
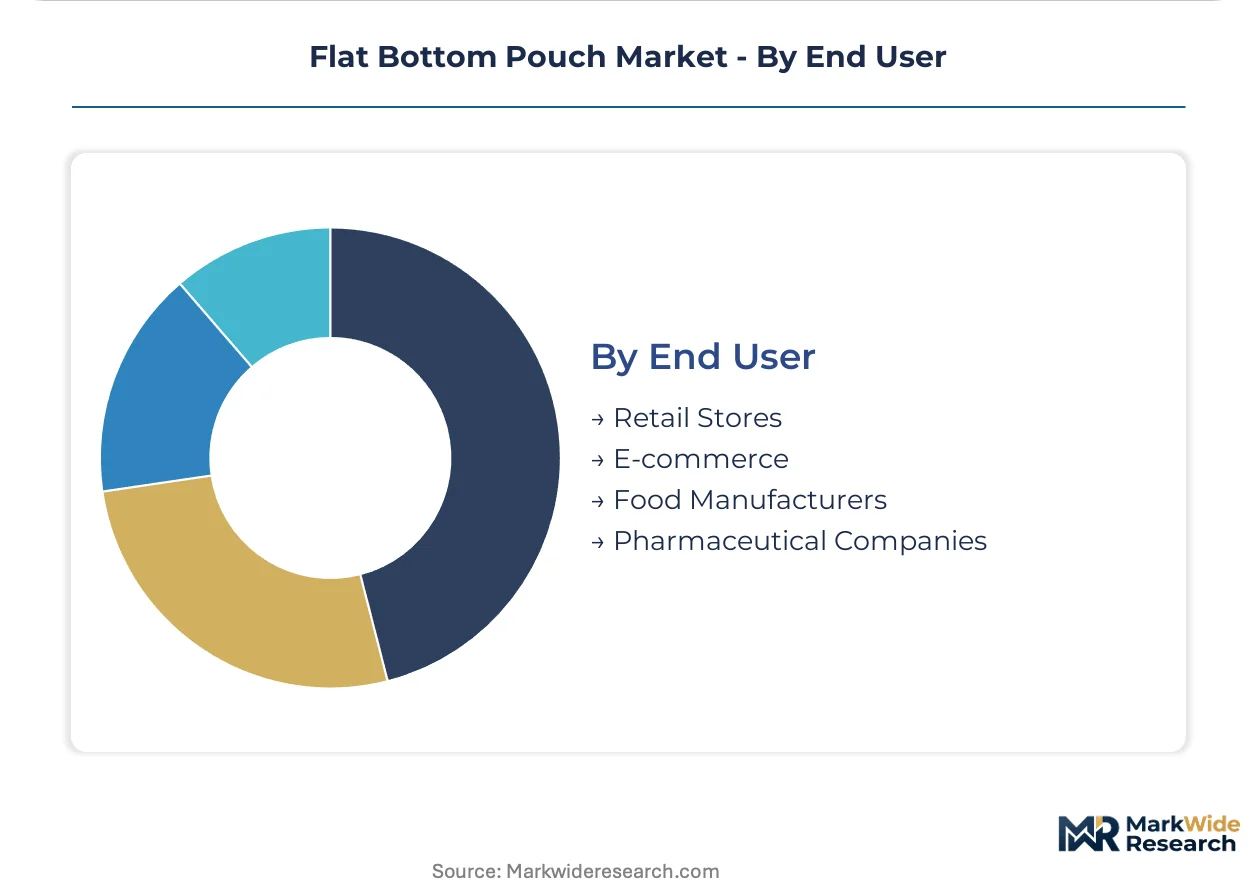
End User:
Customer type shapes service model requirements, with food manufacturers demanding integrated equipment optimization while e-commerce platforms prioritize dimensional compliance.
- Retail Stores:Traditional grocery and specialty retail channels specify pouches for vertical shelf presence and space efficiency. German and Austrian retail chains are mandating flat-bottom formats for private-label premium lines.
- E-commerce:Direct-to-consumer fulfillment platforms impose drop-test and cube-optimization specifications that filter supplier qualification. Major retail fulfillment networks in France and Spain require ISTA-certified performance for pouch-based shipments.
- Food Manufacturers:Branded and private-label processors drive equipment retrofit demand and format standardization.
- Pharmaceutical Companies:Medical nutrition and OTC product lines require validated barrier performance and serialization readiness.
By contract value, food manufacturers lead. By specification tightening, e-commerce is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Packaging and Packaging Waste Regulation is redirecting capital flows toward mono-material converting capacity across major European markets. Germany, France, and the Netherlands lead retrofit demand as branded food manufacturers preempt extended producer responsibility fee structures.
Germany
Premium pet food manufacturers in Hamburg and Bavaria are retrofitting filling lines for flat-bottom formats to secure vertical shelf differentiation. The country's national packaging regulator enforces strict material recovery quotas under the Verpackungsgesetz framework. Stuttgart-based equipment specialists concentrate the scarce mechanical engineering talent required for gusseted-format line conversions.
France
Ready-to-eat salad producers in the Île-de-France region face Q3 2025 compliance deadlines for phthalate-free sealant layers under ECHA migration limit tightening. ANSM oversight of food-contact materials is accelerating bio-based plasticizer adoption. Lyon and Lille host the densest clusters of private-label food manufacturers consolidating supplier panels to three preferred partners.
Netherlands
Premium nut and dried fruit brands specify laser-scored easy-open constructions for 40% of new product launches. The country's national environmental agency enforces extended producer responsibility fee structures that favor recyclable mono-material designs. Rotterdam and Amsterdam anchor converting capacity serving Benelux retail chains mandating flat-bottom formats for private-label premium lines.
Spain
Ready-to-drink beverage manufacturers in Catalonia and Madrid represent underpenetrated demand for spout-equipped flat-bottom formats. The national consumer affairs ministry aligns with EU Green Deal 2030 recyclability targets. Barcelona-based converters are expanding all-polyethylene production lines to capture regulatory tailwinds.
Italy
Pasta and confectionery manufacturers in Emilia-Romagna are retrofitting existing lines for gusseted formats to optimize cube utilization in retail distribution. ECHA REACH frameworks govern chemical migration limits for multilayer constructions. Bologna and Milan concentrate equipment optimization demand from family-owned food processors.
Flat Bottom Pouch Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a consolidating supplier base. The market structure shows moderate concentration, with integrated packaging conglomerates holding scale advantages in material supply and regional converters defending niche positions through format specialization. Three archetypes dominate: captive pulp integrators with kraft paper supply control, integrated film extruders with barrier technology portfolios, and outcome-based service providers bundling equipment with material contracts. Dominant competitive moves include strategic partnerships for automated converting equipment access and geographic expansion through leasing-based market entry.
Within the integrated conglomerate tier, Smurfit Kappa and Mondi Group exemplify archetypes built on captive fiber supply and integrated film operations respectively. Huhtamaki occupies a position bridging European converting scale with branded food manufacturer relationships. Among outcome-based service providers, Sealed Air represents the bundled contract model tying material supply to line efficiency metrics.
| Leading Market Players |
|---|
| Smurfit Kappa |
| Huhtamaki |
| Mondi Group |
| Glenroy |
| Sealed Air |
| Amcor |
| ProAmpac |
| Coveris |
| Berry Global |
| Others |
Supply Flow & Price Mechanics
Nordic pulp integration among Smurfit Kappa and Mondi Group concentrates kraft paper supply upstream, anchoring margin pools in premium fiber-based laminates while independent converters face input cost volatility. This concentration forces downstream pricing stratification between integrated conglomerates with captive supply and regional specialists competing on format flexibility.
Pricing Analysis
Certification level under EU Packaging and Packaging Waste Regulation creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels reflects material complexity, with mono-material all-PE formats commanding premiums for recyclability compliance. Pricing pressure stems from pending extended producer responsibility fee structures compressing mid-tier converter margins. German private-label food manufacturers exhibit highest price sensitivity, while premium pet food brands in France and the Netherlands absorb cost premiums for shelf differentiation.
Supply Chain Analysis
Contract manufacturing concentration sits with Huhtamaki, Sealed Air, and ProAmpac holding automated converting capacity across Germany, France, and the Netherlands. Raw material flows draw from Nordic kraft pulp, Middle Eastern PE resin, and Belgian BOPP film extrusion. Single-source vulnerability runs through EVOH barrier film supply concentrated among Japanese and European specialty polymer producers. Distribution runs through co-located converting facilities serving branded food manufacturers with integrated design services and equipment optimization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flat bottom pouch adoption sits in early-cycle expansion as EU Green Deal recyclability mandates force format retrofit decisions across European food manufacturing. Premium pet food shelf differentiation and e-commerce dimensional compliance provide twin tailwinds accelerating penetration beyond historical flexible packaging substitution rates.
For Market Incumbents: Pre-empt mono-material capability gaps by retrofitting existing extrusion lines for all-PE multilayer constructions before extended producer responsibility fees crystallize. Acquire German and Austrian equipment specialists to lock in scarce gusseted-format engineering talent. Defend against outcome-based service contracts from Sealed Air by bundling material supply with line efficiency guarantees. For New Entrants and Emerging Players: Build out spout-equipped liquid format capabilities targeting underpenetrated ready-to-drink beverage demand in Spain and Italy. Target family-owned pasta and confectionery processors in Emilia-Romagna with ERP-integrated converting solutions that resolve legacy MRP friction. Lead with laser-scored easy-open technology to bypass dedicated die station capital requirements. For Investors and Strategic Acquirers: Capital is best deployed toward mono-material specialists with validated EU recyclability certifications and established relationships with German pet food brands. Long-term viability hinges on regulatory tailwinds persisting through 2030 Green Deal targets. Watch for inflection in extended producer responsibility fee announcements, which will determine whether multilayer or mono-material constructions deliver superior total cost of ownership.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Line Retrofit | Captures EU Green Deal regulatory tailwinds ahead of 2030 recyclability enforcement deadlines. |
| Equipment Specialist Acquisition | Secures scarce Stuttgart and Bologna-based gusseted-format engineering talent for converter expansion. |
| Outcome-Based Service Contract | Bundles Sealed Air-style material supply with line efficiency metrics displacing traditional capex models. |
| Laser Scoring Technology Deployment | Virtualizes die station requirements enabling SKU flexibility for fragmented Netherlands nut brand portfolios. |
| Spout Integration Capability Buildout | Addresses underpenetrated Spanish and Italian ready-to-drink beverage demand with reclosable formats. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with packaging procurement directors, technical packaging managers at branded food manufacturers, and converting equipment specialists; and secondary validation through EU Packaging and Packaging Waste Regulation filings, ECHA REACH substance registrations, and trade flow data from European converting associations. Bottom-up capacity assessments across German, French, and Benelux converting facilities were triangulated against top-down demand estimates from pet food and ready-to-eat brand retrofit announcements.
Forecast inputs considered material type segmentation, closure format complexity tiers, and application-specific barrier requirements across the projection horizon. CAGRs were derived from installed base conversion rates, line retrofit timelines, and regulatory compliance deadlines rather than extrapolated trend fitting. Industry-specific inputs included extended producer responsibility fee structure scenarios and e-commerce platform dimensional specification tightening.
Stress conditions across EVOH supply disruption, kraft pulp price volatility, and German equipment specialist acquisition costs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timeline adherence and brand manufacturer capex commitment levels. Quarterly review of EU fee structure announcements and ISTA certification adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Kraft Pouch Market
Pouch
2 Seal Pouches Market
Pouch
Heat Sealed Lamination Pouch Market
Pouch
Global Pre Zippered Pouches Market
Pouch
South Africa Pouch Packaging Market
Pouch
Pouches Market
Pouch
North America Pouch Packaging Market
Pouch
Vented Stretch Wrap Market
Pouch
Europe Pouch Packaging Market
Pouch
Spain Pouch Packaging Market
Pouch
Self-Seal Pouches Market
Pouch
Egypt Pouch Packaging Market
Pouch
Doyen Style Pouches Market
Pouch
Asia-Pacific Pouch Packaging Market
Pouch
Dual-Chamber Pouches Market
Pouch
High-Barrier Pouches Market