
 Compostable Pouches Market | 2026-2036
Compostable Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Compostable Pouches Market Outlook
Consolidation among European supermarket private-label buyers is realigning supplier relationships across the compostable pouches value chain. BASF SE leverages its polymer science depth to anchor supply of certified compostable resins for high-barrier pouch films. Mondi Group competes through integrated paper-fiber operations that sustain cost positions in kraft-based compostable formats. TIPA Ltd specializes in fully compostable laminates that dominate niche premium food segments demanding home-compostable certification.
Compostable pouches are multi-layer flexible containers engineered from bio-based polymers such as PLA, PHA, or corn starch derivatives, designed to disintegrate under industrial or home composting conditions within specified temperature and humidity parameters. Their primary commercial purpose is to replace conventional plastic packaging in applications where end-of-life organic recovery is technically feasible and logistically supported. PLA-based material types currently occupy the largest production volume share, while PHA grades command premium positioning due to marine-degradability properties and broader composting certification acceptance. Food packaging applications generate the dominant demand flow, though personal care segments are extending fastest as cosmetic brands pursue plastic-free shelf commitments.
The EU Green Deal and REACH frameworks mandate phased reduction of fossil-based single-use plastics, directly elevating compostable pouch demand across member states. EFSA and national regulators enforce strict migration limits and composting certification requirements that filter non-compliant suppliers from approved vendor lists. FDA standards in the United States and Health Canada rules in North America create parallel compliance obligations for exporters serving transatlantic accounts. Stakeholders must monitor certification body harmonization between industrial and home composting standards, as divergent labeling rules threaten to fragment procurement specifications and inflate testing costs.
Market Dynamics
The EU Green Deal's phased single-use plastic bans are forcing food packaging chains to requalify their entire flexible packaging supply base around certified compostable alternatives, compressing supplier approval timelines and concentrating procurement authority among buyers with dedicated sustainability compliance teams.
Growth Catalysts
- EU Green Deal enforcement:The framework's binding reduction targets for fossil-based plastics are eliminating conventional pouch options from approved vendor lists across German, French, and Italian retail chains.
- Industrial composting infrastructure expansion:Netherlands and Belgium are deploying new anaerobic digestion facilities capable of processing certified compostable laminates at scale, validating end-of-life claims for brand owners.
- PHA material breakthroughs:Marine-degradable polymer grades are achieving broader composting certification acceptance, opening premium positioning in seafood and frozen food segments where ocean plastic leakage concerns dominate.
Market Restraints
- PLA resin supply concentration:Fermentation-based lactic acid feedstock dependence on corn and sugarcane harvests in Thailand and Brazil creates input cost volatility and geographic supply risk.
- Industrial composting access gaps:Home compostable certification remains limited to niche premium segments because municipal composting facilities in Eastern Europe lack the temperature and humidity controls required for certified pouch breakdown.
- Conventional plastic cost undercutting:Virgin polypropylene and polyethylene continue to price 40-60% below compostable alternatives, anchoring procurement decisions in price-sensitive private-label segments.
Strategic Opportunities
- Personal care plastic-free commitments:Cosmetic brands in France and Germany are extending home-compostable pouch specifications to shampoo bars and solid skincare formats, creating demand outside food packaging's dominance.
- CSRD disclosure mandates:The EU's Corporate Sustainability Reporting Directive is forcing mid-cap food manufacturers to document packaging circularity metrics, accelerating supplier switches to certified compostable formats with traceable end-of-life pathways.
- E-commerce fulfillment innovation:Direct-to-consumer subscription brands are specifying compostable mailer pouches with integrated tear strips and reseal features, opening channel-specific product development.
Industry Challenges
- Multi-layer lamination complexity:Achieving oxygen and moisture barriers comparable to aluminum-foil laminates requires bonding PLA, PHA, and bio-based adhesives with incompatible thermal processing windows, extending R&D cycles.
- Certification timeline compression:Industrial composting standards under EN 13432 and home composting certification under OK Compost HOME require separate testing protocols, doubling validation costs for suppliers serving both specification tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compostable Pouches Market |
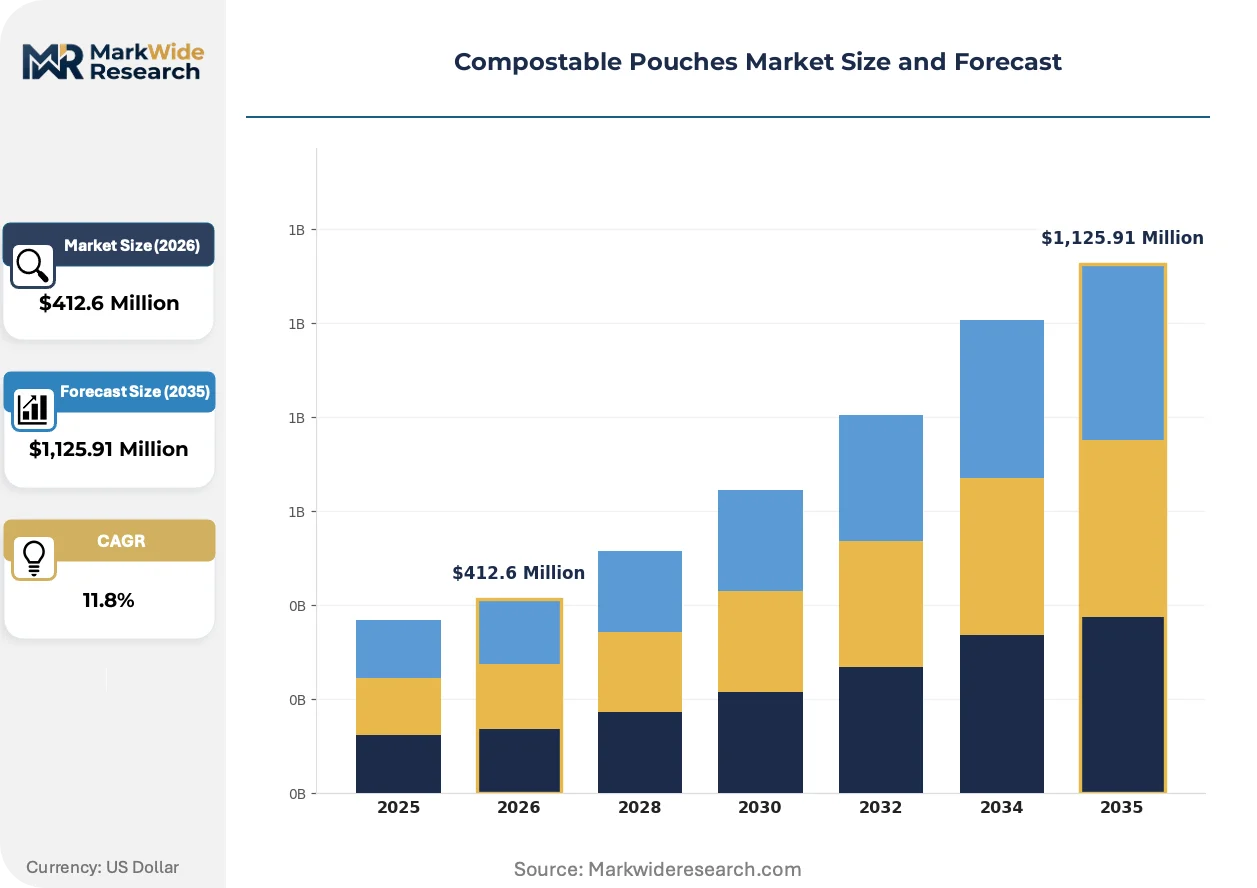
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,125.91 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Corn Starch, PLA, PHA, Paper Application: Food Packaging, Personal Care, Textile, Industrial Size: Small, Medium, Large, Custom Distribution Channel: Online Retail, Wholesale, Supermarkets, Specialty Stores |
| Companies Covered | BASF SE, Mondi Group, TIPA Ltd, Amcor plc, BioBag International AS, Novamont S.P.A., International Paper Company, Smurfit Kappa Group, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compostable Pouches Market Strategic Shifts
Active barrier technology deployment and regulatory disclosure mandates are compressing product development cycles while fragmenting procurement specifications across certification tiers. Suppliers must now engineer for dual industrial-home compostable pathways simultaneously.
Water-based barrier coatings derived from algae and cellulose nanofibers are integrating into kraft-paper compostable laminates, replacing petroleum-based polyethylene moisture seals. Premium organic snack brands in Germany and the Netherlands are specifying these formats for shelf-stable nuts and dried fruits. The technology is integrating high-speed form-fill-seal compatibility that conventional bio-based films struggled to achieve, collapsing the performance gap with conventional plastics.
REACH framework amendments on microplastic additives are tightening migration limits for processing aids in food-contact laminates. ECHA's expanded restriction proposals are forcing resin suppliers to reformulate slip agents and anti-blocking compounds around bio-based alternatives. PHA-grade producers with pre-validated additive packages are capturing accelerated qualification slots from major European retail private-label programs.
Certification-driven procurement is consolidating buyer authority within dedicated sustainability sourcing functions that bypass traditional packaging commodity desks. French and Italian supermarket chains are mandating OK Compost HOME labeling for ambient soup and sauce pouches, displacing conventional multilayer formats regardless of unit cost premiums. This specification shift is most visible in ambient ready-meal segments where shelf-life requirements previously blocked bio-based alternatives.
Compostable Pouches Market Segmentation
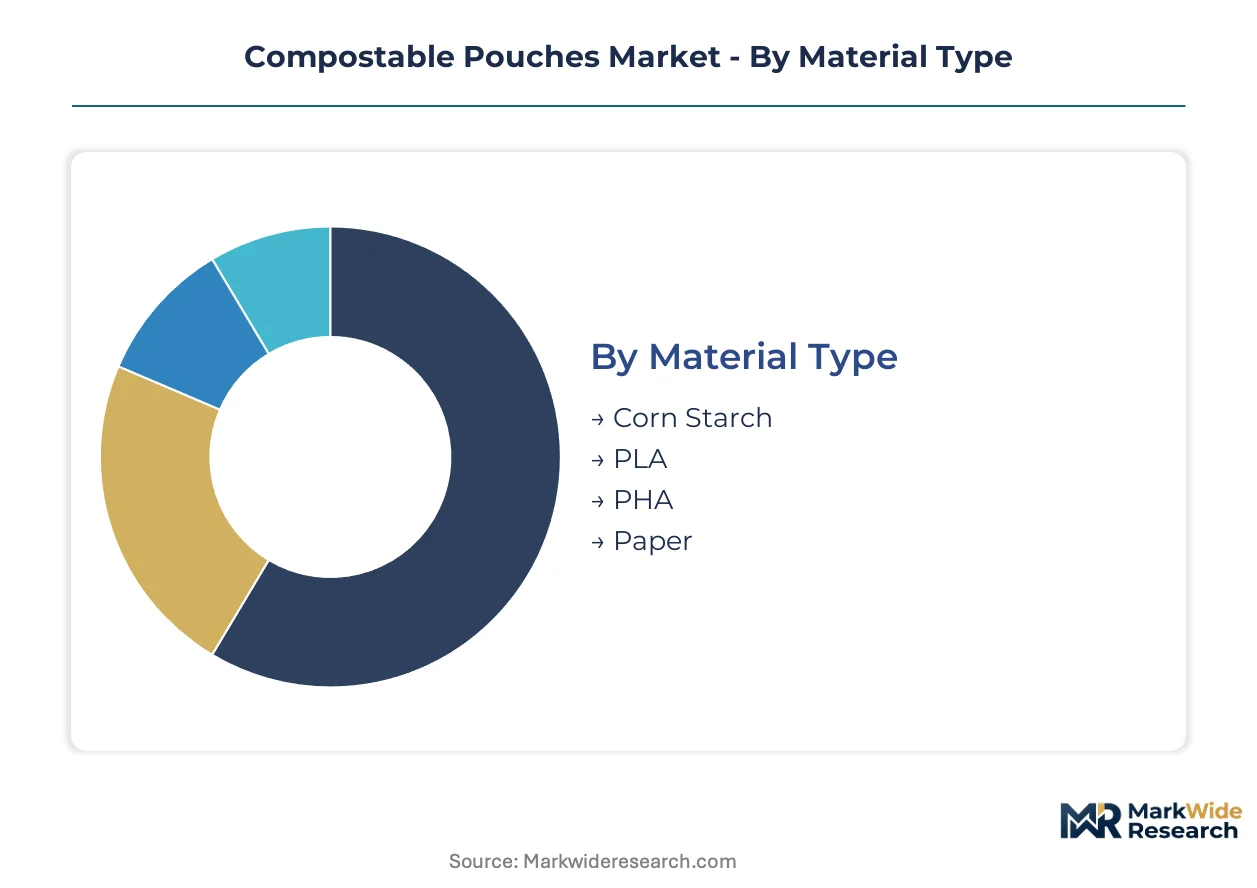
Compostable pouch specifications fragment across material chemistry, barrier performance, and end-of-life certification tiers. Procurement teams must align segment selection with composting infrastructure access and regulatory disclosure obligations.
Material Type:
Resin supply concentrates among fermentation-based producers in Thailand and Brazil, creating geographic dependency patterns that shape buyer qualification strategies.
- PLA:Polylactic acid derived from corn starch dominates current production volumes through established fermentation infrastructure. German and French retail chains specify PLA laminates for ambient dry goods where industrial composting collection exists. EFSA migration limits favor pre-qualified PLA grades with documented additive packages.
- PHA:Marine-degradable polyhydroxyalkanoates achieve broader certification acceptance including home-compostable OK Compost HOME labels. Premium seafood and frozen food segments in the Netherlands specify PHA for ocean plastic leakage mitigation. Fermentation scale-up constraints limit supply availability to qualified buyers.
- Corn Starch:Native starch blends serve cost-sensitive single-layer applications with limited barrier requirements.
- Paper:Kraft-fiber substrates integrate with bio-based coatings for moisture-sensitive formats.
Today's leader: PLA. Tomorrow's challenger: PHA.
Application:
End-use specifications diverge sharply between food-contact migration requirements and cosmetic shelf-stable demands.
- Food Packaging:Multi-layer laminates must achieve oxygen transmission rates below 1 cc/m²/day for shelf-stable nuts and dried fruits. German organic snack brands mandate industrial compostable certification with traceable end-of-life documentation. REACH framework amendments on microplastic additives compress supplier approval timelines.
- Personal Care:Solid shampoo bars and skincare formats drive fastest specification expansion. French cosmetic brands pursue plastic-free shelf commitments through home-compostable pouch formats. CSRD disclosure mandates accelerate procurement switches from conventional multilayer films.
- Textile:Apparel shipping pouches specify tear-resistant kraft laminates for e-commerce fulfillment.
- Industrial:Component packaging adopts compostable formats for closed-loop manufacturing environments.
Food Packaging retains volume dominance. Personal Care expands most quickly.
Size:
Form-fill-seal equipment compatibility constrains dimension standardization across converter operations.
- Small:Single-serve portions for sampling and travel formats.
- Medium:Standard retail units balance shelf presence with material efficiency.
- Large:Club store and foodservice formats require enhanced seal integrity.
- Custom:Brand-specific die-cuts and window features for premium positioning.
Medium sizes anchor procurement volumes. Custom specifications capture margin premiums.
Distribution Channel:
Channel-specific packaging requirements separate bulk wholesale from direct-to-consumer fulfillment needs.
- Supermarkets:Private-label buyers in Italy and France mandate OK Compost HOME labeling for ambient soup pouches. Sustainability sourcing functions bypass traditional commodity desks to enforce certification-driven procurement.
- Online Retail:Subscription brands specify integrated tear strips and reseal features for unboxing experience differentiation. E-commerce fulfillment innovation opens channel-specific product development for compostable mailer pouches.
- Wholesale:Foodservice distributors specify industrial compostable formats for institutional catering contracts.
- Specialty Stores:Premium organic retailers demand home-compostable certification with visible labeling.
Supermarkets concentrate specification authority. Online Retail drives feature innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial composting infrastructure expertise clusters in German chemical engineering hubs and Dutch waste management technology centers, anchoring European supply chain coordination for certified pouch converters.
Germany
Private-label procurement teams at Rewe and Edeka mandate OK Compost HOME certification for ambient soup pouches, displacing conventional multilayer films. The EU Green Deal's binding reduction targets eliminate fossil-based plastic options from approved vendor lists. Industrial composting facilities in Bavaria and North Rhine-Westphalia process certified laminates at scale, validating end-of-life claims for brand owners.
France
Cosmetic brands headquartered in Paris pursue plastic-free shelf commitments through home-compostable pouch formats for solid shampoo bars. EFSA enforces strict migration limits and composting certification requirements that filter non-compliant suppliers. The Auvergne-Rhône-Alpes region hosts specialty resin compounders serving premium food packaging segments demanding marine-degradable PHA grades.
Netherlands
Anaerobic digestion facilities in Gelderland and South Holland process certified compostable laminates, closing infrastructure gaps that previously blocked bio-based adoption. CSRD disclosure mandates force mid-cap food manufacturers to document packaging circularity metrics. Wageningen University research clusters accelerate water-based barrier coating commercialization for kraft-paper compostable formats.
Italy
Supermarket chains including Coop Italia and Conad specify industrial compostable certification for pasta and sauce pouches in Lombardy and Emilia-Romagna retail networks. REACH framework amendments on microplastic additives compress supplier approval timelines. Bologna-based packaging converters integrate high-speed form-fill-seal equipment compatible with bio-based film thermal processing windows.
United States
FDA standards create parallel compliance obligations for European exporters serving transatlantic accounts, particularly in organic snack and premium pet food segments. California's SB 54 extended producer responsibility law mandates phased plastic packaging reduction, elevating compostable pouch inquiries from West Coast brands. Minneapolis and Chicago distribution hubs consolidate procurement for national retail chains evaluating certified compostable alternatives.
Compostable Pouches Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across material science, integrated fiber operations, and compostable laminate engineering. The supplier base organizes into three strategic archetypes: polymer science conglomerates with fermentation-scale resin capacity, integrated paper-packaging groups with kraft-fiber substrate control, and specialty laminate developers targeting premium certification tiers. Competitive moves concentrate on backward integration into bio-based resin supply and technology licensing partnerships that accelerate qualification timelines for retail private-label programs.
Among polymer science conglomerates, BASF SE anchors supply of certified compostable resins for high-barrier pouch films. Mondi Group exemplifies integrated paper-fiber operations that sustain cost positions in kraft-based compostable formats. TIPA Ltd occupies a specialist position in fully compostable laminates that dominate niche premium food segments demanding home-compostable certification.
| Leading Market Players |
|---|
| BASF SE |
| Mondi Group |
| TIPA Ltd |
| Amcor plc |
| BioBag International AS |
| Novamont S.P.A. |
| International Paper Company |
| Smurfit Kappa Group |
| WestRock Company |
| Others |
Value Chain & Pricing Dynamics
Family-owned fermentation specialists in Thailand and Brazil anchor lactic acid feedstock supply, translating crop yield volatility directly into PLA resin pricing power for European converters. Their concentrated ownership structure limits spot market liquidity, forcing German and French buyers into long-term offtake contracts that insulate against harvest-driven cost spikes.
Pricing Analysis
Bundled certification-plus-resin contracts dominate procurement, separating integrated OK Compost HOME validation from unbundled raw material spot purchases. Three-tier pricing structure across premium, standard, and economy levels tracks certification tier and barrier performance, with PHA marine-degradable grades commanding widest spreads. Cost compression in standard PLA laminates is intensifying because Thai fermentation capacity expansions lag demand growth. Private-label supermarket buyers exhibit highest price sensitivity, while premium organic snack brands absorb certification premiums without volume elasticity.
Supply Chain Analysis
Fermentation-based lactic acid feedstock rests on corn and sugarcane harvests concentrated in Thailand, Brazil, and the United States Midwest. Bio-based polymer production draws from specialty chemical intermediates, industrial composting additive packages, and kraft-fiber substrates. Single-source vulnerability runs through Thai PLA resin suppliers dependent on monsoon-dependent crop cycles. Distribution runs through Rotterdam and Hamburg port clusters serving German, French, and Dutch converter networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's binding single-use plastic reduction targets compound regulatory demand for certified compostable formats, creating procurement urgency that outpaces supply chain readiness. This regulatory compounding accelerates qualification timelines and concentrates buyer authority among sustainability compliance teams.
For Market Incumbents: Hedge against PHA fermentation scale-up delays by securing dual-source resin agreements across Thai and Brazilian suppliers. BASF SE and Novamont S.P.A. should expand captive lactic acid production to offset feedstock volatility. Certification investment in simultaneous EN 13432 and OK Compost HOME validation defends positioning against emerging laminate specialists.
For New Entrants and Emerging Players: Mid-cap cosmetic brands in France and Germany represent underserved buyer archetypes seeking home-compostable formats for solid shampoo and skincare pouches. E-commerce subscription fulfillment channels offer lowest barrier-to-entry for compostable mailer pouch specification. Direct technical sales engagement with sustainability officers bypasses traditional packaging commodity procurement.
For Investors and Strategic Acquirers: Valuations sit cheapest among kraft-paper converters lacking bio-based coating intellectual property. Long-term viability framing centers on industrial composting infrastructure buildout pace across Eastern Europe. The signal to watch is municipal anaerobic digestion facility commissioning announcements in Poland and Romania.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstock | Captive corn starch supply from Thai agricultural cooperatives secures PLA resin cost positions against harvest volatility. |
| Dual Certification Investment | Simultaneous EN 13432 and OK Compost HOME validation opens access to both German retail chains and French cosmetic brands. |
| Water-Based Barrier Coating R&D Partnership | Wageningen University collaborations accelerate algae-derived moisture seal commercialization for kraft-paper formats. |
| E-Commerce Channel Specification Capture | Integrated tear-strip and reseal feature development targets subscription brand procurement for compostable mailer pouches. |
| Eastern European Infrastructure Pre-positioning | Polish and Romanian converter capacity placement anticipates municipal composting facility expansion under EU Green Deal funding. |
Study Parameters
Bottom-up food packaging and personal care demand modeling reconciled against top-down resin supply tracking forms the analytical core of this study. Primary interviews with sustainability procurement directors at German and French supermarket chains, compostable pouch converters in Italy, PHA fermentation plant managers in Thailand, and ECHA regulatory affairs specialists combined with secondary validation from EU Green Deal implementation reports, EFSA migration limit databases, and industrial composting facility registries. Triangulation across these sources ensures segment-level precision.
Historical trendline analysis of PLA and PHA resin pricing, certification timeline compression, and industrial composting infrastructure deployment informs the projection framework. Segmentation dimensions modeled include material chemistry tier, barrier performance specification, end-of-life certification pathway, and regional composting infrastructure maturity. CAGRs derive from regression analysis of resin supply growth against regulatory mandate enforcement schedules, incorporating food packaging volume elasticity and personal care segment acceleration patterns.
Underlying measurement precision varies by segment; PHA marine-degradable grades and home-compostable certification tiers carry tighter precision than standard PLA industrial compostable formats due to concentrated supplier bases. Forecasts reflect assumptions on EU Green Deal enforcement consistency, fermentation capacity expansion timing, and municipal composting infrastructure funding flows. A small set of triggers warrants ongoing watch: REACH microplastic additive restriction amendments, Thai monsoon patterns affecting corn starch yields, and Eastern European anaerobic digestion facility commissioning rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
GCC Retort Pouches Market
Pouch
Kraft Block Bottom Pouch Market
Pouch
Peelable Pouches Market
Pouch
Japan Pouch Packaging Market
Pouch
Pouch Equipment Market
Pouch
Monodose Packs Market
Pouch
Portion Control Packs Market
Pouch
Global Pre Zippered Pouches Market
Pouch
Twin Pouch Packaging Market
Pouch
Colombia Pouch Packaging Market
Pouch
Slider Pouches Market
Pouch
Foil Pouch Packaging Market
Pouch
Russia Pouch Packaging Market
Pouch
Global Anti Static Bubble Pouch Market
Pouch
Flat Bottom Pouch Market
Pouch
Doy Pouch Packaging Market