
 Inflatable Pouches Market | 2026-2036
Inflatable Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Inflatable Pouches Market Foresight
China's Yangtze River Delta manufacturing belt is reconfiguring regional supply chains for inflatable pouch films and conversion equipment. Sealed Air Corporation leverages its North American blown-film infrastructure to sustain cost advantages in high-volume food packaging applications. Mondi Group anchors European demand through integrated kraft paper and plastic film operations serving industrial customers. Storopack Hans Reichenecker GmbH specializes in engineered air cushion systems that dominate German automotive parts logistics.
Inflatable pouches are gas-filled flexible packaging structures fabricated from coextruded polyethylene or multilayer barrier films, thermally sealed to form individual air chambers that absorb mechanical shock during distribution; they typically achieve cushioning coefficients of 3-5 times their uninflated thickness and serve primarily as protective void-fill and surface protection in transit packaging. Barrier pouches lead value pools due to oxygen and moisture ingress requirements in medical supplies and precision electronics, while custom pouches represent the fastest-growing configuration as brand owners specify printed surfaces and exact dimensional fits for subscription box presentation. LDPE sustains material dominance across consumer goods applications, though nylon coextrusions gain traction in industrial applications requiring puncture resistance during extended storage cycles.
FDA regulations govern inflatable pouch contact layers in food packaging applications, while EPA guidelines shape recycling infrastructure and post-consumer film recovery obligations in the United States. The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility schemes that inflate compliance costs for non-recyclable multi-material constructions. Stakeholders must monitor emerging state-level recycled content mandates and decide between mono-material redesign investments or compliance fee absorption strategies.
Market Dynamics
E-commerce fulfillment networks are compressing cushioning specifications toward thinner, higher-performance films as automated packing lines demand consistent dimensional tolerance and faster cycle speeds.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates are accelerating mono-material pouch redesigns across German and French industrial corridors, creating replacement demand for legacy multi-layer constructions.
- Automotive parts logistics:Stuttgart and Munich manufacturing clusters specify engineered air cushion systems for just-in-time component delivery, standardizing inflatable protection across tiered supplier networks.
- LDPE film coextrusion advances:Five-layer blown film lines achieve barrier performance previously requiring nylon laminations, reducing material cost per unit in high-volume consumer applications.
Market Restraints
- Ethylene feedstock volatility:Crude-linked naphtha pricing transmits directly to LDPE resin costs, compressing converter margins during upstream commodity spikes.
- Film extrusion concentration:Blown film capacity clusters along the US Gulf Coast and China's Yangtze River Delta, exposing downstream pouch converters to regional supply disruptions and freight cost surges.
- Mechanical recycling incompatibility:Multi-material barrier pouches containing EVOH or metallized layers face sorted-stream rejection at European mechanical recycling facilities, triggering compliance fee structures under EU waste directives.
Strategic Opportunities
- Indian pharmaceutical cold chain:Temperature-sensitive biologics distribution creates demand for insulated inflatable thermal liners, an application segment where domestic pouch fabrication remains underdeveloped.
- US state recycled content mandates:California and New York legislative frameworks are forcing brand owners to specify post-consumer recycled LDPE, rewarding early movers with certified circular feedstock contracts.
- Digital printing convergence:UV-inkjet systems enable lot-size-one customization for subscription box presentation, collapsing minimum order quantities and opening short-run brand differentiation.
Industry Challenges
- Coextrusion technician scarcity:Five-layer blown film operation requires specialized die-gap calibration expertise that aging workforce demographics are failing to replenish.
- FDA food contact notification timelines:Novel barrier resin approvals for direct food-contact inflatable pouches extend 18-24 months, delaying product launches for converter R&D pipelines.
- Legacy warehouse management integration:Automated pouch-inflation equipment requires API connectivity with existing WMS platforms, forcing mid-cap 3PLs into unplanned IT infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inflatable Pouches Market |
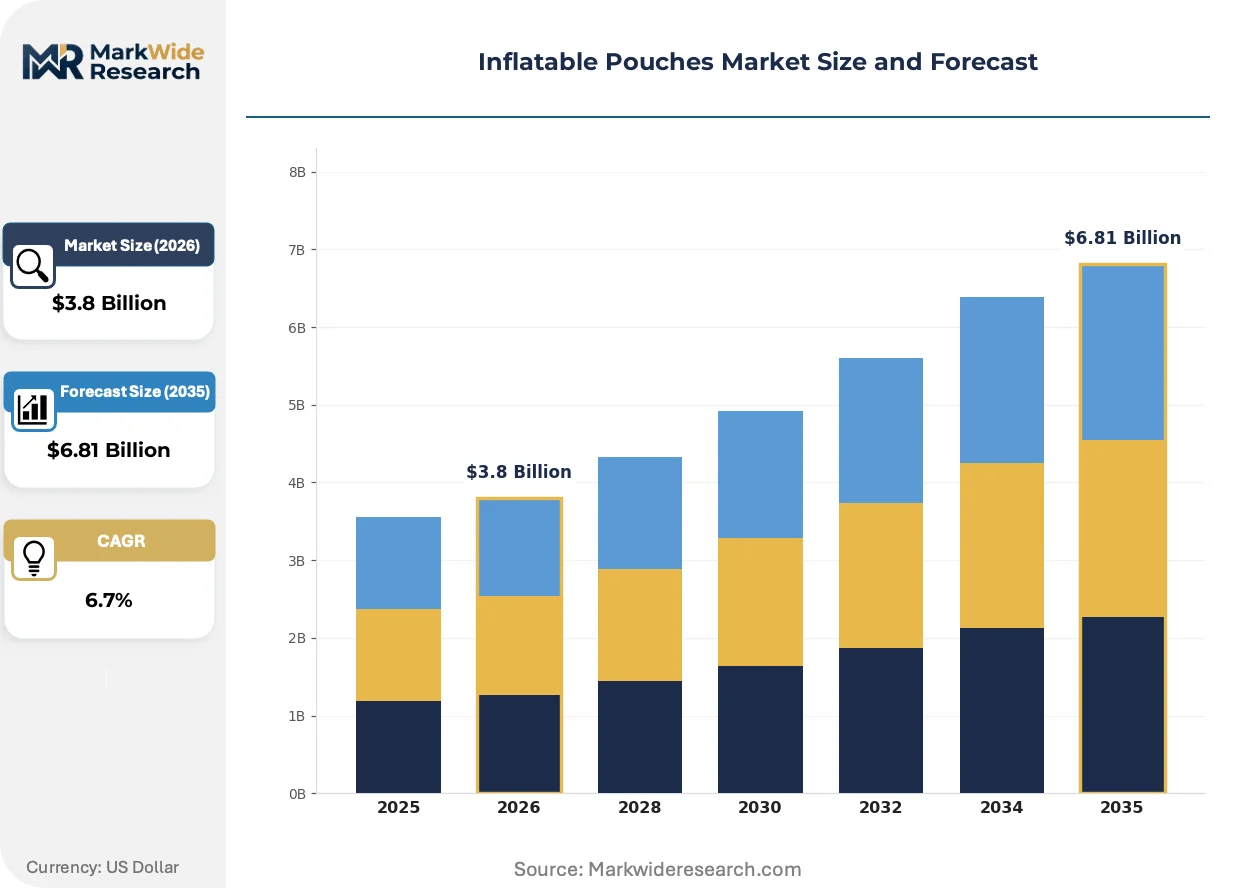
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pouches, Custom Pouches, Vacuum Pouches, Barrier Pouches Material: LDPE, HDPE, PVC, Nylon End User: Food Packaging, Medical Supplies, Consumer Goods, Industrial Applications Application: Transport, Storage, Protection, Display |
| Companies Covered | Sealed Air Corporation, Pregis Corporation, Storopack Hans Reichenecker GmbH, Fromm Packaging Systems Inc., Amcor plc, Berry Global Inc., Mondi Group, Sutton Performance Packaging, Uniqbag, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inflatable Pouches Market Shifts & Advancements
Material science breakthroughs and regulatory compliance architectures are simultaneously compressing legacy specifications and opening premium positioning for certified sustainable alternatives.
Biodegradable polyester blends are collapsing the performance gap between compostable films and conventional LDPE in protective cushioning applications. European cosmetic subscription services have adopted these materials at pilot scale, accepting 15-20% cost premiums for certified home-compostable end-of-life pathways. The structural consequence is collapsing the historical segregation between industrial protective packaging and consumer-facing sustainability claims.
REACH substance restriction evaluations are tightening scrutiny on phthalate plasticizers and certain antioxidant packages in food-contact films. Industrial consequence includes accelerated reformulation programs among European compounders, with downstream certification costs passed through converter networks. Medical device and precision electronics segments are most affected, responding with supplier qualification audits that extend 12-18 months.
Consolidated buying by mega-fulfillment networks is compressing supplier rosters and demanding outcome-based performance guarantees rather than per-unit material pricing. Third-party logistics providers in the Yangtze River Delta are displacing spot-market procurement with multi-year cushioning performance contracts indexed to damage-rate outcomes. This pattern is most visible in consumer electronics distribution, where Amazon and Alibaba fulfillment standards propagate rapidly through supplier ecosystems.
Inflatable Pouches Market Segmentation
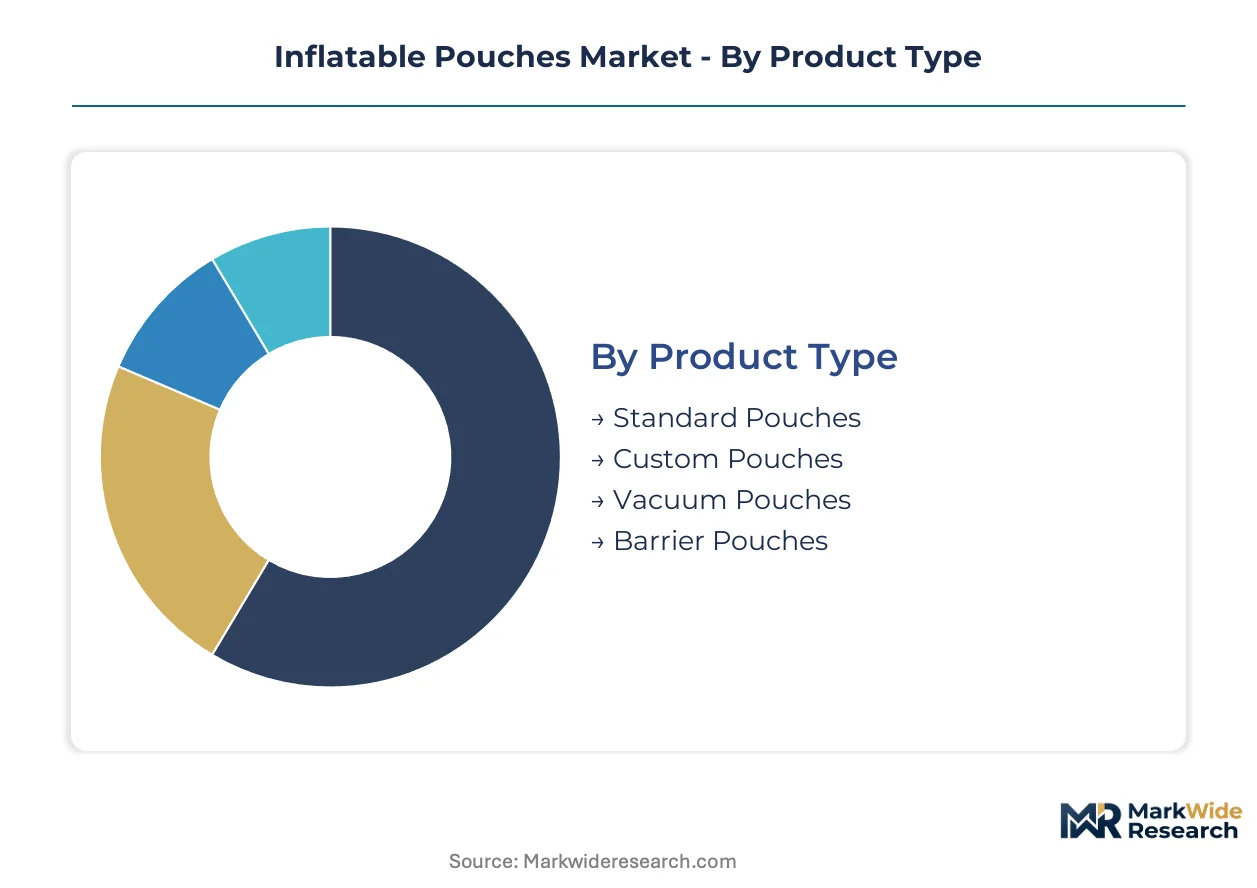
Segmentation in inflatable pouches reveals distinct technical requirements and margin profiles across protective packaging applications. Material selection and barrier specifications drive aftermarket service intensity, particularly where FDA food contact compliance or EVOH barrier validation requires ongoing technical support.
Product Type:
After-sales service intensity varies sharply across pouch configurations, with custom-engineered solutions demanding sustained technical consultation while standard formats operate on transactional procurement models.
- Barrier Pouches:Multi-layer coextrusions incorporating EVOH or metallized films achieve oxygen transmission rates below 0.5 cc/m²/day, essential for medical device sterilization integrity and precision electronics corrosion protection. German automotive suppliers around Stuttgart specify these for just-in-time component delivery, where moisture ingress during extended warehouse storage would trigger tier-one supplier rejection. By volume, Barrier Pouches lead. By growth pace, Custom Pouches is ahead.
- Custom Pouches:Dimensionally specified to exact void-fill geometries and surface-printed for subscription box presentation, these require CAD-assisted design validation and sampling cycles before production commitment. Brand owners in the Yangtze River Delta electronics corridor are collapsing minimum order quantities through digital printing convergence, accepting lot-size-one configurations for premium unboxing experiences.
- Standard Pouches:Off-the-shelf air cushion formats for high-velocity e-commerce void-fill, procured on price-per-unit metrics with minimal technical interface.
- Vacuum Pouches:Heat-sealed barrier constructions for oxygen-exclusion food preservation and compressed bulk reduction in logistics.
Service intensity concentrates in barrier and custom configurations where validation documentation and dimensional tolerance guarantees dominate procurement criteria.
Material:
Cost tier stratification separates commodity polyethylene grades from engineered coextrusions, with converter margins compressing toward standard LDPE while nylon and multi-layer constructions sustain premium positioning.
- LDPE:Dominant material across consumer goods cushioning, five-layer blown film lines now achieving barrier performance previously requiring nylon laminations. US Gulf Coast resin supply and Yangtze River Delta conversion capacity anchor global cost structures for high-volume applications.
- Nylon:Puncture-resistant coextrusions for industrial applications with extended storage cycles and mechanical stress exposure, particularly automotive parts logistics networks requiring drop-test certification to tiered OEM specifications.
- HDPE:Stiffer film option for load-bearing applications where dimensional stability under stack pressure exceeds flexibility requirements.
- PVC:Legacy material presence in specific medical and industrial formats, facing substitution pressure from polyethylene alternatives under REACH substance restriction evaluations.
Material substitution dynamics favor LDPE cost efficiency in consumer segments while nylon sustains industrial premium tiers.
End User:
Application maturity separates established food packaging specifications from emerging pharmaceutical cold chain requirements, with regulatory validation timelines creating divergent competitive moats.
- Food Packaging:FDA food contact notification requirements govern direct-contact inflatable structures, with 18-24 month novel resin approval timelines delaying R&D pipelines. Sealed Air Corporation leverages North American blown-film infrastructure to sustain cost advantages in high-volume formats.
- Medical Supplies:Sterile barrier validation and oxygen exclusion specifications concentrate demand among compounders with ISO 13485 certification and documented biocompatibility testing.
- Consumer Goods:E-commerce fulfillment compression toward thinner, higher-performance films demands consistent dimensional tolerance for automated packing line integration.
- Industrial Applications:Storopack Hans Reichenecker GmbH dominates German automotive parts logistics with engineered air cushion systems standardized across tiered supplier networks.
Medical and food segments sustain premium pricing through regulatory compliance barriers, while consumer goods volume concentrates procurement leverage.
Application:
Customer type segmentation distinguishes procurement patterns between automated fulfillment networks specifying outcome-based performance guarantees and conventional industrial buyers operating on per-unit material pricing.
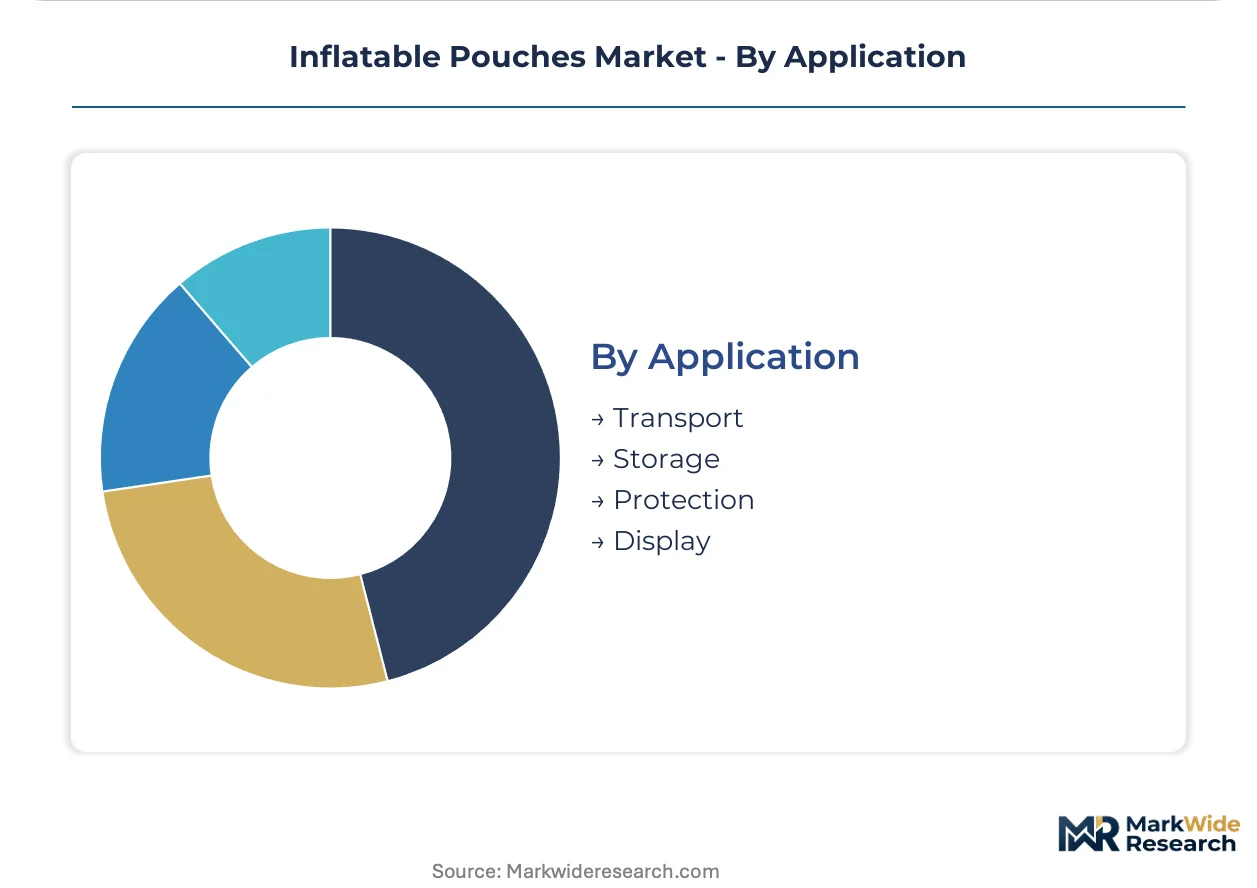
- Transport:Shock absorption and vibration damping during distribution, with cushioning coefficients of 3-5 times uninflated thickness protecting against mechanical damage in parcel networks.
- Storage:Extended warehouse protection requiring puncture resistance and barrier stability across seasonal inventory cycles, particularly relevant for German industrial corridors with just-in-time delivery constraints.
- Protection:Surface protection and void-fill functions in secondary packaging, the dominant value pool in e-commerce fulfillment center adoption.
- Display:Consumer-facing presentation formats with printed surfaces and transparent windows for retail shelf visibility, expanding fastest in cosmetic subscription services.
Transport and protection applications dominate volume, while display configurations gain share fastest through brand differentiation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA regulations anchor the United States as the dominant geography for food-contact inflatable pouch compliance, while EU Packaging and Packaging Waste Regulation mandates reshape European converter investments toward mono-material redesigns.
United States
E-commerce fulfillment networks and pharmaceutical cold chain expansion drive adoption of high-performance cushioning films. EPA guidelines shape recycling infrastructure obligations for post-consumer film recovery. The US Gulf Coast resin supply corridor anchors blown film capacity clusters serving national distribution.
Germany
Automotive parts logistics and industrial protective packaging concentrate demand for engineered air cushion systems. REACH substance restriction evaluations accelerate reformulation programs among European compounders. The Stuttgart and Munich manufacturing clusters standardize inflatable protection across tiered supplier networks.
China
Consumer electronics distribution and Yangtze River Delta manufacturing reconfiguration propel regional supply chain investments. MIIT standards and dual carbon goals pressure converters toward material efficiency improvements. The Yangtze River Delta belt hosts film extrusion and conversion capacity serving domestic and export markets.
India
Pharmaceutical cold chain expansion and temperature-sensitive biologics distribution create demand for insulated inflatable thermal liners. CDSCO regulations govern medical device packaging validation requirements. Domestic pouch fabrication capacity remains underdeveloped relative to biologics distribution growth.
France
Cosmetic subscription services and premium unboxing experiences accelerate custom pouch adoption with certified compostable materials. EU Packaging and Packaging Waste Regulation extended producer responsibility schemes inflate compliance costs for multi-material constructions. Paris-based fulfillment networks pilot biodegradable polyester blends at scale.
Inflatable Pouches Market Competitive Landscape
Vertically integrated material producers and specialized protective packaging engineers split the market into distinct capability tiers. Consolidation pressure concentrates procurement leverage among mega-fulfillment networks demanding outcome-based performance guarantees rather than per-unit material pricing. Three archetypes dominate: resin-integrated film converters, engineered air cushion specialists, and diversified global packaging conglomerates. Capacity expansion and mono-material portfolio diversification represent the dominant competitive moves as regulatory compliance architectures reshape technical specifications.
Among North American resin-integrated players, Sealed Air Corporation exemplifies the blown-film infrastructure archetype sustaining cost advantages in high-volume applications. Storopack Hans Reichenecker GmbH occupies the engineered air cushion specialist position within German automotive logistics networks. Mondi Group anchors the diversified conglomerate tier through integrated kraft paper and plastic film operations serving European industrial customers.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Pregis Corporation |
| Storopack Hans Reichenecker GmbH |
| Fromm Packaging Systems Inc. |
| Amcor plc |
| Berry Global Inc. |
| Mondi Group |
| Sutton Performance Packaging |
| Uniqbag |
| Others |
Supply & Pricing Matrix
LDPE resin concentration along the US Gulf Coast and China's Yangtze River Delta anchors cost structures for downstream pouch converters, with margin pools shifting toward barrier film specialists who command premium positioning through FDA food-contact certification and EVOH coextrusion capability.
Pricing Analysis
Geographic price spreads of 12-18% separate US Gulf Coast LDPE spot markets from European naphtha-linked resin costs, compressing converter margins in transatlantic trade lanes. Pricing stratifies across premium, standard, and economy tiers, with barrier-certified films commanding 25-35% premiums over commodity cushioning grades. Price differentiation hinges on FDA food-contact notification status and five-layer blown film technical capability. Cost compression in standard LDPE pouches is intensifying because e-commerce fulfillment networks consolidate procurement volumes and demand outcome-based damage-rate guarantees. Mega-fulfillment buyers exhibit lowest price sensitivity, while mid-cap 3PLs operating spot-market procurement face highest margin pressure.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for inflatable pouch converters serving North American e-commerce networks. Raw material sourcing draws from Saudi Arabian ethylene feedstock, US Gulf Coast polyethylene resin, and German-engineered blown film equipment. Component dependencies center on EVOH barrier resins from Japan and South Korea, nylon coextrusion grades from European compounders, and automated inflation machinery from Italian and German OEMs. Single-source vulnerability concentrates in five-layer blown film die systems, where two European suppliers control 70% of installed base maintenance and replacement. Distribution runs through regional fulfillment center hubs in the Yangtze River Delta, Rhine-Ruhr corridor, and US Midwest distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The inflatable pouches market is entering a cyclical recovery phase as e-commerce fulfillment network expansion reaccelerates post-consolidation, with Amazon and Alibaba damage-rate specifications propagating through tiered supplier ecosystems and triggering replacement demand for legacy multi-material constructions.
For Market Incumbents: Harden defensive positions through backward integration into captive LDPE blown film capacity in the US Gulf Coast corridor, securing resin cost advantages against naphtha price volatility. Accelerate mono-material pouch redesign investments to preempt EU Packaging and Packaging Waste Regulation compliance fee structures. Prioritize certification maintenance for FDA food-contact and ISO 13485 medical device barriers, as qualification audit timelines extend 12-18 months and create switching costs for tier-one automotive and pharmaceutical accounts.
For New Entrants and Emerging Players: Indian pharmaceutical cold chain infrastructure represents the most penetrable entry point, with domestic pouch fabrication capacity underdeveloped relative to temperature-sensitive biologics distribution growth. Biodegradable polyester blend thermal liners for cosmetic subscription services offer second white-space target, accepting 15-20% cost premiums for certified home-compostable end-of-life pathways. Go-to-market angle should emphasize digital printing convergence for lot-size-one customization, collapsing minimum order quantities and opening short-run brand differentiation unavailable to high-volume incumbents.
For Investors and Strategic Acquirers: Capital is best deployed toward engineered air cushion specialists with established tier-one automotive supplier relationships and documented drop-test certification to OEM specifications. Long-term viability across the projection horizon favors compounders with integrated kraft paper and plastic film operations capable of serving industrial customers through regulatory transitions. Watch for state-level recycled content mandate acceleration in California and New York as inflection indicator, rewarding early movers with certified circular feedstock contracts and creating acquisition premiums for PCR-LDPE qualified assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Redesign Program | EU Packaging and Packaging Waste Regulation extended producer responsibility schemes inflate compliance costs for multi-material EVOH constructions. |
| Backward Integration into Blown Film | Five-layer LDPE capacity capture secures margin protection against ethylene feedstock volatility transmitted through naphtha pricing. |
| Digital Printing Convergence | UV-inkjet lot-size-one capability collapses minimum order quantities for Yangtze River Delta electronics brand unboxing specifications. |
| FDA Food-Contact Certification Investment | Novel barrier resin approval timelines of 18-24 months create competitive moats against unqualified entrants in pharmaceutical segments. |
| PCR-LDPE Feedstock Contracting | California and New York legislative frameworks force brand owner specification of post-consumer recycled content in protective cushioning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, blown film equipment manufacturer disclosures, SEC 10-K filings from packaging conglomerates, and EU regulatory impact assessments. Primary interviews engaged blown film plant managers, e-commerce fulfillment center procurement leads, automotive tier-one supplier packaging engineers, pharmaceutical cold chain logistics directors, and compounder technical R&D specialists. Secondary validation drew from FDA food-contact notification databases, REACH substance restriction evaluations, and Yangtze River Delta manufacturing belt investment tracking. Bottom-up demand modeling from end-use application volumes was triangulated against top-down resin consumption estimates from regional petrochemical associations.
Forecast inputs span product type segmentation across barrier, custom, standard, and vacuum configurations; material grade stratification from commodity LDPE through nylon coextrusions; end-use industry differentiation between food packaging, medical supplies, consumer goods, and industrial applications; and geographic production cluster analysis. CAGR derivation applied logistic growth curve fitting to penetration rate assumptions, with inflection points anchored to regulatory compliance deadlines and e-commerce fulfillment network capacity expansion schedules. Industry-specific inputs incorporated five-layer blown film line commissioning timelines and FDA novel resin approval pipeline status.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories, ethylene-naphtha spreads, or transpacific container freight rates would shift the trajectory of converter margin compression and regional supply chain reconfiguration. Forecasts reflect documented assumptions regarding EU Packaging and Packaging Waste Regulation enforcement timing and state-level recycled content mandate adoption velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Child Resistant Single Dose Pouches Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
Sterilization Pouches Market
Pouch
Stand Up Paper Pouches Market
Pouch
Recyclable PE Pouch Market
Pouch
Child Resistant Pouches Market
Pouch
Aluminium Bags and Pouches Market
Pouch
Benelux Pouch Packaging Market
Pouch
Liquid Pouch Packing Machine Market
Pouch
Zipper Pouch Market
Pouch
UAE Pouch Packaging Market
Pouch
India Pouch Packaging Market
Pouch
Japan Pouch Packaging Market
Pouch
Automatic Pre-Made Pouch Packaging Machine Market
Pouch
Canada Pouch Packaging Market
Pouch
Portion Control Packs Market