
 Pharmaceutical Secondary Packaging Market | 2026-2036
Pharmaceutical Secondary Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Secondary Packaging Market Analytics
EU FMD serialization mandates is rebalancing the cost-of-entry calculus for pharmaceutical secondary packaging across European distribution networks. Amcor plc leverages its integrated film-to-carton capabilities to sustain margin pools in high-compliance markets. Catalent anchors its competitive position through specialized cold-chain secondary packaging services for biologics customers. Gerresheimer AG differentiates via glass-primary-to-secondary-packaging continuity for injectable therapies.
Pharmaceutical secondary packaging encompasses the outer protective and informational layers—cartons, blister cards, labels, and insert cards—applied after primary containment, typically constructed from paperboard, plastic films, or aluminum laminates and engineered to ensure product integrity, regulatory traceability, and patient-safe dispensing through the supply chain. Carton systems dominate volume due to universal compliance with batch coding and tamper-evidence requirements, while blister packs capture premium positioning in adherence-focused chronic disease categories. Labels and insert cards represent the fastest-growing margin segment as multilingual serialization and electronic patient information mandates expand content complexity per unit.
EMA serialization requirements, EU FMD track-and-trace standards, and national pharmacy board dispensing rules collectively shape material specifications, authentication feature placement, and market access timelines across European jurisdictions. REACH chemical restrictions and the EU Green Deal circularity targets are redirecting material procurement toward certified recyclable paperboard and reduced-plastic laminate structures. Stakeholders must monitor evolving serialization granularity requirements and pre-empt material compliance transitions to avoid supply disqualification in regulated European channels.
Market Dynamics
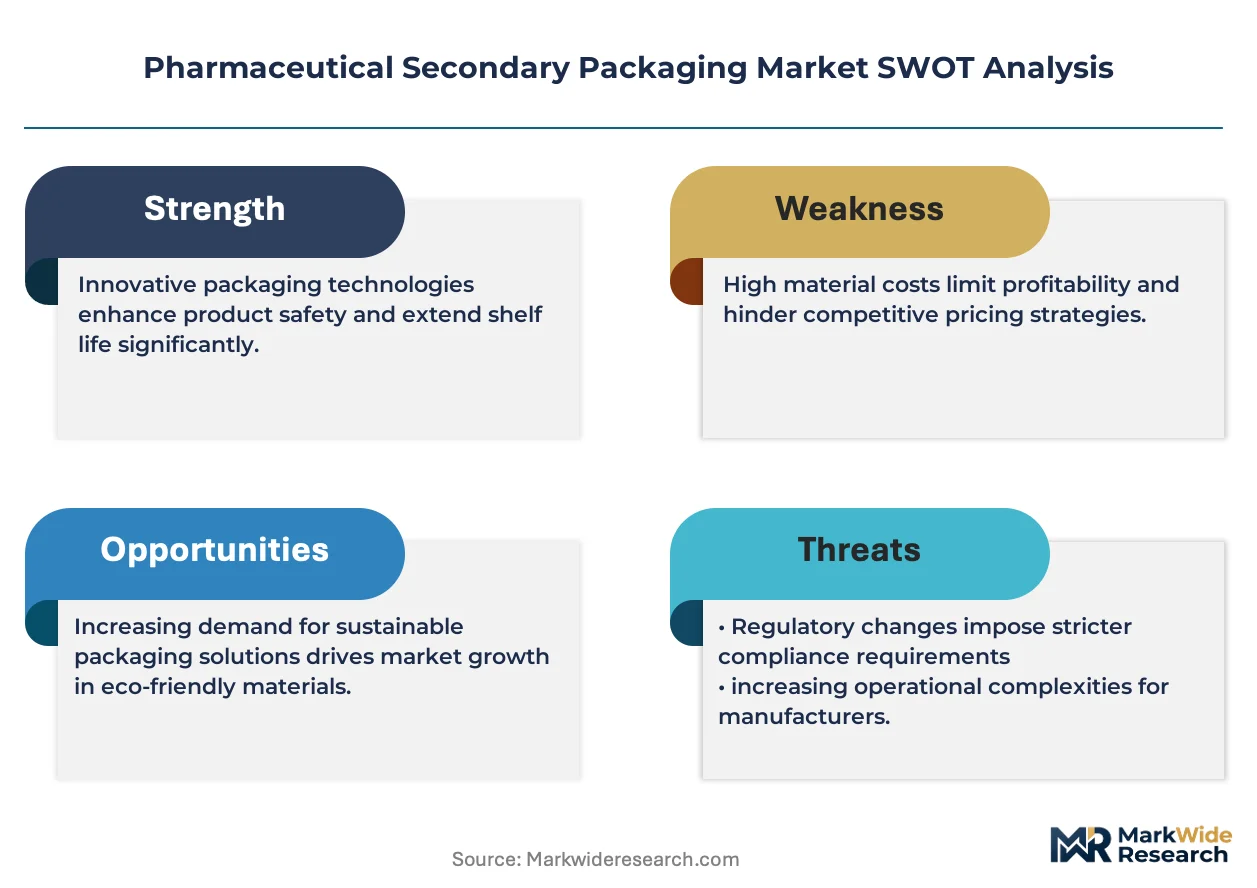
EU MDR serialization mandates are compressing compliance timelines and forcing wholesale packaging infrastructure upgrades across European distribution networks, rebalancing capital allocation toward track-and-trace capable suppliers.
Growth Catalysts
- Cold-chain biologics expansion:Temperature-sensitive therapies require specialized secondary packaging with thermal insulation and phase-change materials. Biologics manufacturers are scaling cold-chain programs to protect product integrity through last-mile distribution.
- EU FMD track-and-trace mandates:The Falsified Medicines Directive requires unique identifier serialization on every salable unit. Wholesale distributors and contract packagers must upgrade line equipment to meet authentication standards.
- Central and Eastern Europe export corridors:German contract packagers are capturing volume from pharma manufacturers routing products through Poland, Czech Republic, and Hungary into expanding regional markets.
Market Restraints
- Aluminum laminate cost volatility:Cold-chain blister and pouch structures depend on aluminum foil laminates. Input price swings compress margin pools for standard-format secondary packaging.
- Specialized equipment supplier concentration:High-speed serialization line builders cluster in Germany and Italy. Lead times for compliant machinery extend 18-24 months, constraining rapid capacity expansion.
- Plastic reduction mandates:The EU Green Deal circularity targets and REACH chemical restrictions are disqualifying conventional multi-layer plastic films from certified recyclable streams.
Strategic Opportunities
- Glass-to-carton continuity services:Injectable therapy manufacturers seek single-source suppliers bridging primary glass containment with secondary carton serialization. Integrated providers capture stickier relationships.
- Electronic patient information inserts:EMA guidance permits digital replacement of paper leaflets. QR-code-enabled cartons reduce material weight while enabling real-time safety updates.
- Certified recyclable paperboard structures:Forest Stewardship Council and Programme for the Endorsement of Forest Certification sourcing credentials unlock preferential procurement from sustainability-committing pharma multinationals.
Industry Challenges
- Serialization engineering talent scarcity:Line integration specialists who bridge mechanical packaging engineering with software track-and-trace systems command premium compensation. Recruitment lags demand in manufacturing clusters.
- Legacy MES integration complexity:Manufacturing execution systems at established pharma plants require custom API development to connect with new serialization data repositories. Implementation timelines slip.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Secondary Packaging Market |
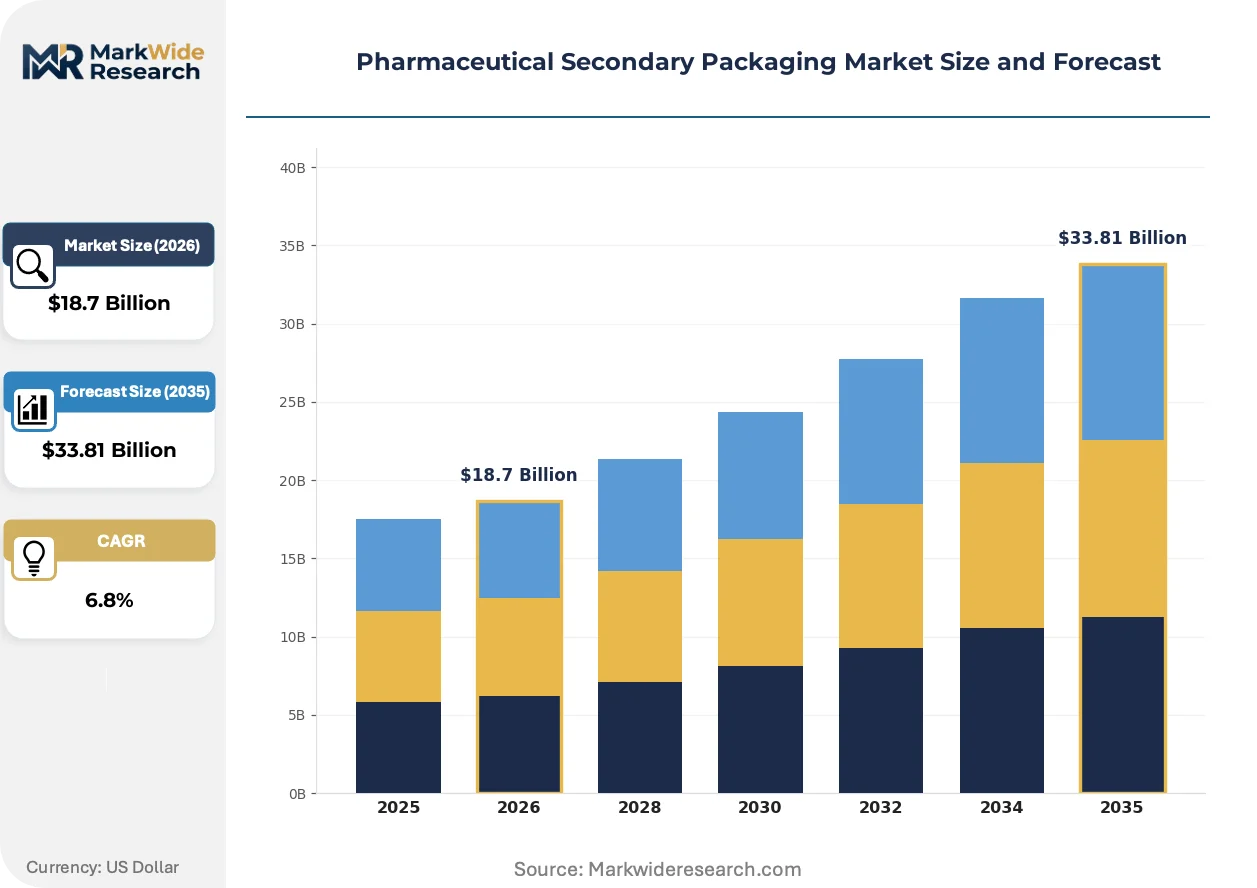
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Cartons, Blister Packs, Labels, Insert Cards Material: Plastic, Paperboard, Glass, Aluminum End User: Pharmacies, Hospitals, Clinics, Distribution Centers Form: Primary Packs, Secondary Packs, Shipping Cases, Display Units |
| Companies Covered | Sharp, Amcor plc, Catalent, AptarGroup, Inc., Gerresheimer AG, PCI Pharma Services, Almac Group, Schott Pharma, Patheon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Secondary Packaging Market Evolving Landscape
Digital authentication layers and sustainable material substitutions are converging to redefine secondary packaging specifications, with compliance architecture now inseparable from environmental credentialing.
Smart packaging with embedded NFC tags and printed electronics is modularizing how patient adherence data flows from dispensed units to healthcare providers. Chronic disease therapy manufacturers in diabetes and cardiovascular categories are piloting connected blister packs that timestamp removal events. The technology is modularizing the boundary between physical packaging and digital therapeutics infrastructure.
EMA serialization granularity requirements are tightening batch-level traceability to individual unit-level authentication across all prescription medicines. The industrial consequence is forced retirement of legacy thermal transfer printers in favor of laser-marking and digital printing systems. Injectable therapy cartons and biologics cold-chain shippers face the most acute compliance pressure, with manufacturers pre-empting 2025 enforcement windows.
Hospital and pharmacy procurement committees are consolidating supplier panels around vendors offering combined sustainability certification and serialization compliance. Single-source contracting is displacing fragmented multi-vendor arrangements for carton, label, and insert combinations. Germany's hospital procurement associations and France's regional pharmacy cooperatives exhibit the most concentrated buying power consolidation.
Pharmaceutical Secondary Packaging Market Segmentation
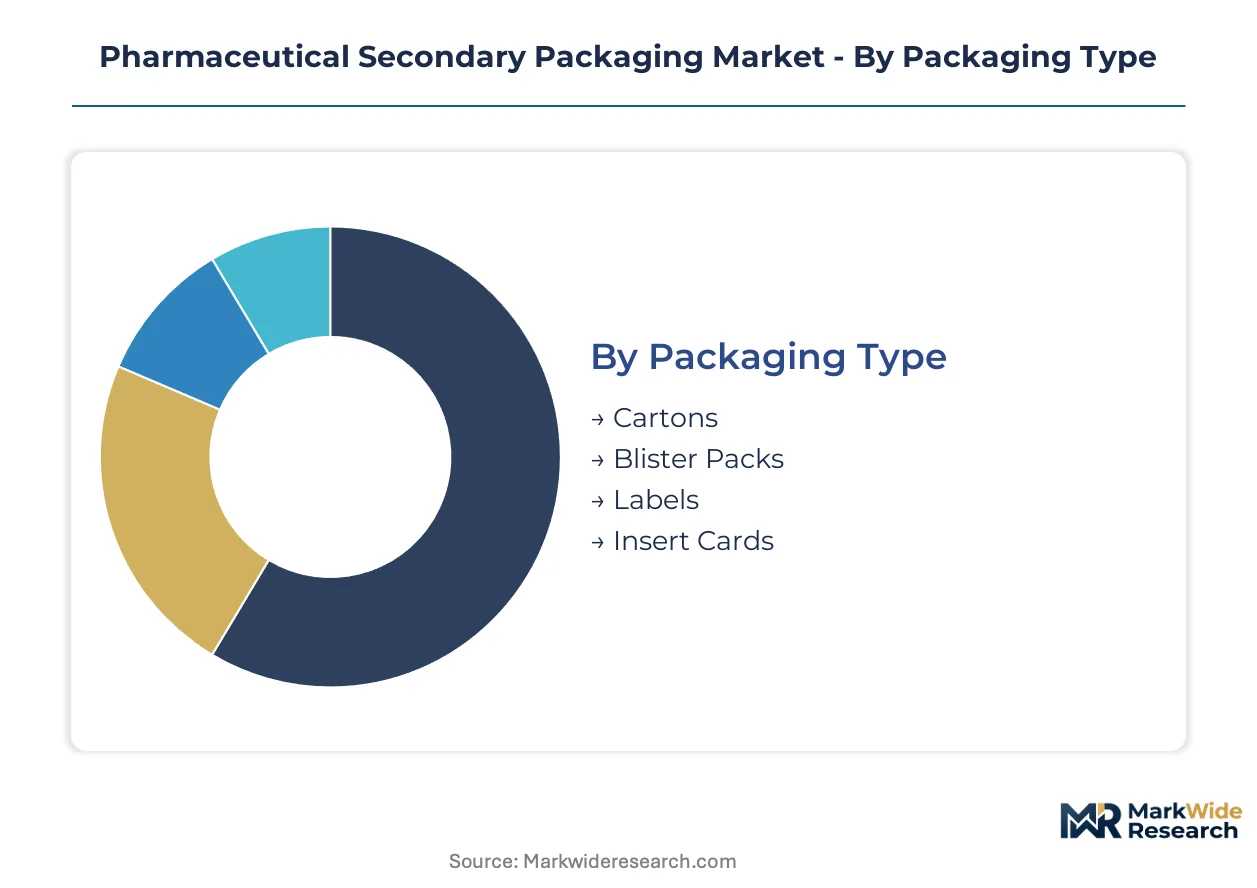
Packaging type and material choices in pharmaceutical secondary packaging determine compliance architecture, cold-chain performance, and recyclability credentials. Segmentation reveals where capital is concentrating and which specifications are gaining procurement preference.
Packaging Type:
Supply concentration tilts toward carton systems where serialization line infrastructure clusters in Germany and Northern Italy.
- Cartons:Constructed from paperboard with tamper-evident closures and batch-coded flaps. German contract packagers absorb the bulk of European volume as domestic pharma and Central European export corridors concentrate procurement. REACH-compliant substrates and EU FMD serialization mandates drive material and equipment specifications.
- Blister Packs:Aluminum-plastic laminates with push-through or peelable lidding for unit-dose protection. Demand concentrates in chronic disease therapies where patient adherence programs require timestamped dosing events. Cold-chain biologics expansion is forcing thermal insulation integration into specialized formats.
- Labels:Pressure-sensitive or shrink-sleeve constructions carrying unique identifiers and multilingual safety information.
- Insert Cards:Folded paper leaflets with dosing instructions and regulatory disclosures, now migrating toward QR-enabled digital replacements.
Cartons absorb the bulk of installed capacity; blister packs are expanding most quickly.
Material:
Cost tier stratification separates premium certified-recyclable substrates from commodity laminates facing Green Deal disqualification.
- Paperboard:Forest Stewardship Council and PEFC-certified grades dominate carton construction. German hospital procurement associations and French pharmacy cooperatives mandate certified sourcing credentials. REACH chemical restrictions and circularity targets are redirecting procurement toward mono-material recyclable structures.
- Plastic:Multi-layer films and rigid thermoforms for blister bases and shrink sleeves. Conventional petroleum-based laminates face mounting pressure from the EU Green Deal plastic reduction mandates.
- Glass:Borosilicate and soda-lime compositions for primary containment with secondary carton integration.
- Aluminum:Cold-form foil and lidding laminates providing moisture and oxygen barriers for sensitive therapies. Input price volatility compresses margin pools for standard-format packaging.
Paperboard commands the largest procurement volumes; certified recyclable grades are climbing the fastest.
End User:
Application requirements diverge sharply between high-volume retail pharmacy dispensing and specialized hospital cold-chain handling.
- Pharmacies:Community and retail dispensaries requiring tamper-evident cartons with patient-readable labeling. German pharmacy networks and Poland's expanding retail chains concentrate demand for standardized serialization-compliant formats.
- Hospitals:Inpatient and outpatient facilities handling biologics and injectable therapies. Cold-chain secondary packaging with phase-change materials and thermal monitoring is expanding fastest here as temperature-sensitive therapy administration concentrates in acute care settings.
- Clinics:Ambulatory care sites with limited on-site storage requiring compact secondary pack configurations.
- Distribution Centers:Wholesale and logistics hubs where aggregation and track-and-trace data management determine packaging specifications.
Pharmacies represent the largest addressable base; hospitals are gaining share fastest.
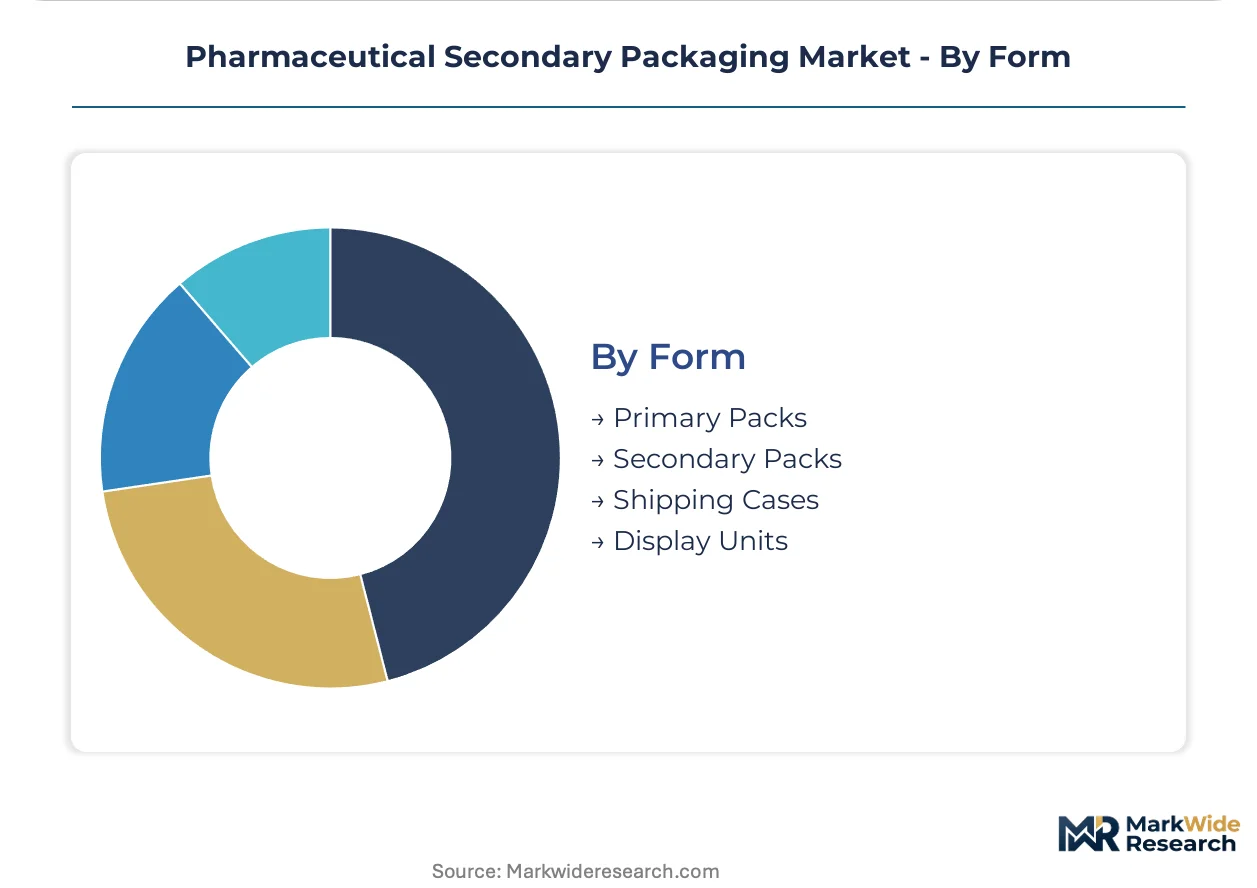
Form:
Volume scale separates high-unit-count primary and secondary packs from lower-volume specialized shipping configurations.
- Primary Packs:Immediate containers holding individual doses or short-course therapies. Blister cards and unit-dose vial cartons dominate this layer where patient adherence features and child-resistant closures concentrate engineering investment.
- Secondary Packs:Outer cartons and labels applied after primary containment. EMA serialization granularity requirements and EU FMD track-and-trace mandates are forcing wholesale equipment upgrades across this form category.
- Shipping Cases:Corrugated or insulated outer containers for bulk transport. Cold-chain biologics distribution requires specialized thermal protection with validated temperature maintenance.
- Display Units:Shelf-ready packaging for retail pharmacy environments with integrated promotional and regulatory information.
Secondary packs absorb the bulk of compliance-driven capital expenditure; shipping cases are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German contract packagers absorb the largest share of European pharmaceutical secondary packaging demand, serving both domestic manufacturers and export corridors into Central and Eastern Europe.
Germany
EMA serialization mandates and EU FMD track-and-trace requirements drive wholesale equipment upgrades across Bavarian and North Rhine-Westphalian manufacturing clusters. The country's national pharmaceutical regulator enforces batch-level to unit-level authentication transitions ahead of 2025 enforcement windows. Contract packaging specialists in Munich and Düsseldorf concentrate cold-chain secondary packaging capacity for biologics exports.
United States
FDA track-and-trace regulations and DSCSA compliance deadlines compress implementation timelines for pharmaceutical distributors. The agency's serialization guidance forces retirement of legacy thermal transfer printing systems. Packaging service providers in New Jersey and North Carolina expand serialization line capacity to capture biologics and specialty pharma volume.
Switzerland
Swissmedic regulatory requirements for injectable therapies sustain demand for glass-primary-to-secondary-packaging continuity services. The national regulator's quality standards exceed baseline EU requirements, creating premium positioning for certified suppliers. Industrial clusters in Basel and Zurich host integrated providers serving global pharma headquarters operations.
India
CDSCO serialization mandates for exported pharmaceuticals align packaging specifications with EU FMD and FDA DSCSA standards. The national pharmaceutical regulator's track-and-trace guidance pushes contract manufacturers toward compliant secondary packaging investments. Gujarat and Maharashtra packaging hubs upgrade line equipment to serve both domestic and export-market compliance requirements.
China
NMPA drug traceability regulations expand serialization requirements across domestic pharmaceutical distribution networks. The national regulator's implementation timeline accelerates equipment procurement for compliant secondary packaging. Shanghai and Jiangsu province manufacturing bases concentrate capacity for both local market supply and contract export packaging.
Pharmaceutical Secondary Packaging Market Competitive Landscape
German producers anchor one tier of pharmaceutical secondary packaging supply; Swiss and US specialists hold differentiated positions in high-compliance and biologics segments. The vendor base separates into integrated film-to-carton conglomerates, specialized cold-chain service providers, and glass-primary continuity specialists. Three strategic archetypes dominate: compliance-scale operators serving high-volume serialization mandates, biologics-dedicated cold-chain packagers, and integrated primary-to-secondary packaging houses. M&A activity concentrates among contract packaging networks acquiring regional serialization capabilities; capacity expansion focuses on German and North American cold-chain infrastructure.
Within the integrated conglomerate tier, Amcor plc and Gerresheimer AG represent archetypal positioning—Amcor as a film-to-carton capability integrator and Gerresheimer as a glass-primary continuity anchor. Catalent occupies a position exemplifying the biologics-specialized cold-chain service model. These three companies illustrate how competitive positioning in pharmaceutical secondary packaging depends on bridging primary containment expertise with secondary serialization compliance.
| Leading Market Players |
|---|
| Sharp |
| Amcor plc |
| Catalent |
| AptarGroup, Inc. |
| Gerresheimer AG |
| PCI Pharma Services |
| Almac Group |
| Schott Pharma |
| Patheon |
| Others |
Value Network & Pricing Analysis
EU Green Deal circularity targets now gate qualified supply access and premium-tier pricing power across pharmaceutical secondary packaging procurement. REACH chemical restrictions and FSC certification requirements disqualify conventional substrates from hospital and pharmacy supplier panels, compressing margin pools for non-compliant producers while elevating certified-recyclable paperboard to premium positioning.
Pricing Analysis
Short lead-time premiums now separate contract packagers with available serialization line capacity from spot-market inventory clearing at distressed rates. Three-tier pricing structure across certified-sustainable, standard-compliant, and economy-laminate levels reflects FSC sourcing credentials and EU FMD authentication capabilities. Pricing pressure stems from aluminum laminate input volatility and extended equipment procurement timelines. German hospital procurement associations exhibit lowest price sensitivity due to compliance-first mandates, while Central European export distributors face acute cost compression.
Supply Chain Analysis
Workforce scarcity for serialization engineering specialists in Bavarian and North Rhine-Westphalian manufacturing clusters extends equipment commissioning timelines and elevates labor cost structures. Supply concentrates in Germany, Italy, and Switzerland where high-speed line builders and contract packagers cluster. Raw material dependencies span FSC-certified paperboard, aluminum cold-form foils, and pharmaceutical-grade plastic films. Single-source vulnerability runs through German and Italian machinery suppliers with 18-24 month lead times. Distribution runs through wholesale pharmaceutical distributors aggregating track-and-trace data for pharmacy and hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical secondary packaging functions as a cost-of-compliance market where EU FMD serialization mandates erect barrier-to-entry moats favoring capitalized incumbents with installed track-and-trace infrastructure.
For Market Incumbents: Lock in serialization line capacity through long-term equipment reservations with German and Italian machinery suppliers before lead times extend further. Secure backward integration into FSC-certified paperboard sourcing to defend margin position against REACH-driven substrate cost inflation. Cold-chain biologics expansion and specialized thermal packaging capabilities represent the priority defensive perimeter against commodity-format competitors. For New Entrants and Emerging Players: Begin with certified-recyclable paperboard structures for French pharmacy cooperatives and German hospital procurement associations where sustainability credentials unlock panel access despite incumbent concentration. Electronic patient information inserts and QR-enabled cartons offer the most penetrable white-space as EMA guidance permits digital leaflet replacement. A go-to-market angle anchored in rapid line commissioning for mid-tier pharma manufacturers bypassing 18-24 month equipment queues captures displaced demand. For Investors and Strategic Acquirers: Swissmedic enforcement windows tightening glass-primary-to-secondary-packaging continuity requirements is the leading indicator that integrated containment suppliers command sustained premium positioning. The 5-10 year viability window favors acquisition targets with cold-chain biologics capabilities and established EMA serialization compliance rather than commodity carton producers. Monitor German contract packager utilization rates as the lead inflection signal for capacity shortage pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Line Capacity Expansion | Captures EU FMD compliance-driven demand from wholesale distributors upgrading authentication infrastructure. |
| FSC-Certified Paperboard Backward Integration | Secures preferential procurement positioning with sustainability-committing pharma multinationals facing Green Deal targets. |
| Cold-Chain Biologics Packaging Specialization | Addresses temperature-sensitive therapy expansion with phase-change material integration for hospital networks. |
| Electronic Patient Information Platform Development | Enables QR-code-enabled carton replacement of paper leaflets per EMA digital guidance. |
| Central and Eastern European Export Corridor Establishment | Captures volume from German pharma manufacturers routing products through Poland, Czech Republic, and Hungary. |
Research Methodology
EMA regulatory filings, EU FMD implementation guidance documents, and FSC certification databases formed the secondary backbone for market sizing and compliance timeline calibration. Primary interviews with contract packaging operations directors, pharmaceutical regulatory affairs leads, hospital procurement managers, and serialization line equipment specialists validated demand assumptions and capacity constraints. Bottom-up triangulation across packaging type volumes and top-down reconciliation against pharma manufacturing output estimates anchored market projections.
Historical trendline analysis of installed serialization line capacity and cold-chain packaging program expansion informed growth trajectory modeling across the projection horizon. Segmentation dimensions encompassed packaging type, material certification tier, end-user channel, and regional regulatory cluster complexity. CAGRs were derived from equipment procurement pipeline analysis and pharma manufacturer packaging upgrade disclosures. Forecast inputs incorporated biologics pipeline expansion rates and EU MDR enforcement window timing.
Underlying measurement precision varies by segment; carton systems and established EU markets carry tighter precision than emerging cold-chain formats and Central European export corridors. Forecasts reflect assumptions regarding serialization granularity implementation timelines and aluminum laminate price stability. Material deviation in Swissmedic enforcement acceleration, REACH chemical restriction expansion, or biologics cold-chain demand contraction warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Prescription Bottles Market
Pharmaceutical Packaging
Intravenous Packaging Market
Pharmaceutical Packaging
Pharmaceutical Container Market
Pharmaceutical Packaging
Advanced Empty Capsule Market
Pharmaceutical Packaging
North America Pharmaceutical Vials Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
Reefer Container for Pharmaceutical Market
Pharmaceutical Packaging
Plastic Pharma Tray Market
Pharmaceutical Packaging
Glass Medicine Bottles Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Packaging Market
Pharmaceutical Packaging
Middle East and Africa Ampoules Packaging Market
Pharmaceutical Packaging
US Clinical Trial Packaging Market
Pharmaceutical Packaging
Clinical Trial Packaging Market
Pharmaceutical Packaging
North America Ampoules Packaging Market