
 Feed Pouches Market | 2026-2036
Feed Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Pouches Market Insights
A capital-intensity divergence between extrusion-capable multinationals and regional converters is reorganizing competitive tiers in feed pouch supply. Amcor leverages integrated film production across multiple continents to sustain cost positions on high-volume laminated formats. Mondi anchors European supply through kraft-paper hybrid lines that serve agricultural cooperatives seeking fiber-based alternatives. ProAmpac competes on quick-turn custom print runs for mid-tier feed distributors in North America.
Feed pouches are multi-layer flexible containers, typically combining PET, PE, EVOH, or aluminum foil through adhesive or extrusion lamination, designed to exclude moisture and oxygen during storage and transport of nutritional products. Stand-up pouches dominate volume due to shelf efficiency and consumer convenience in pet food retail, while flat bottom pouches capture premium positioning among specialty feed supplements requiring stable palletization. Biodegradable material development remains nascent but draws R&D investment as feed manufacturers face retailer sustainability mandates.
FDA food-contact regulations govern migration limits and substrate approvals for pouches distributed in the United States, while EU REACH and F-Gas Regulation restrict certain adhesive chemistries and fluorinated barrier treatments in European production. USDA grading requirements for livestock feed labeling indirectly shape pouch print specifications and panel layouts. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to internalize recycling infrastructure or outsource compliance to specialized converter partnerships.
Market Dynamics
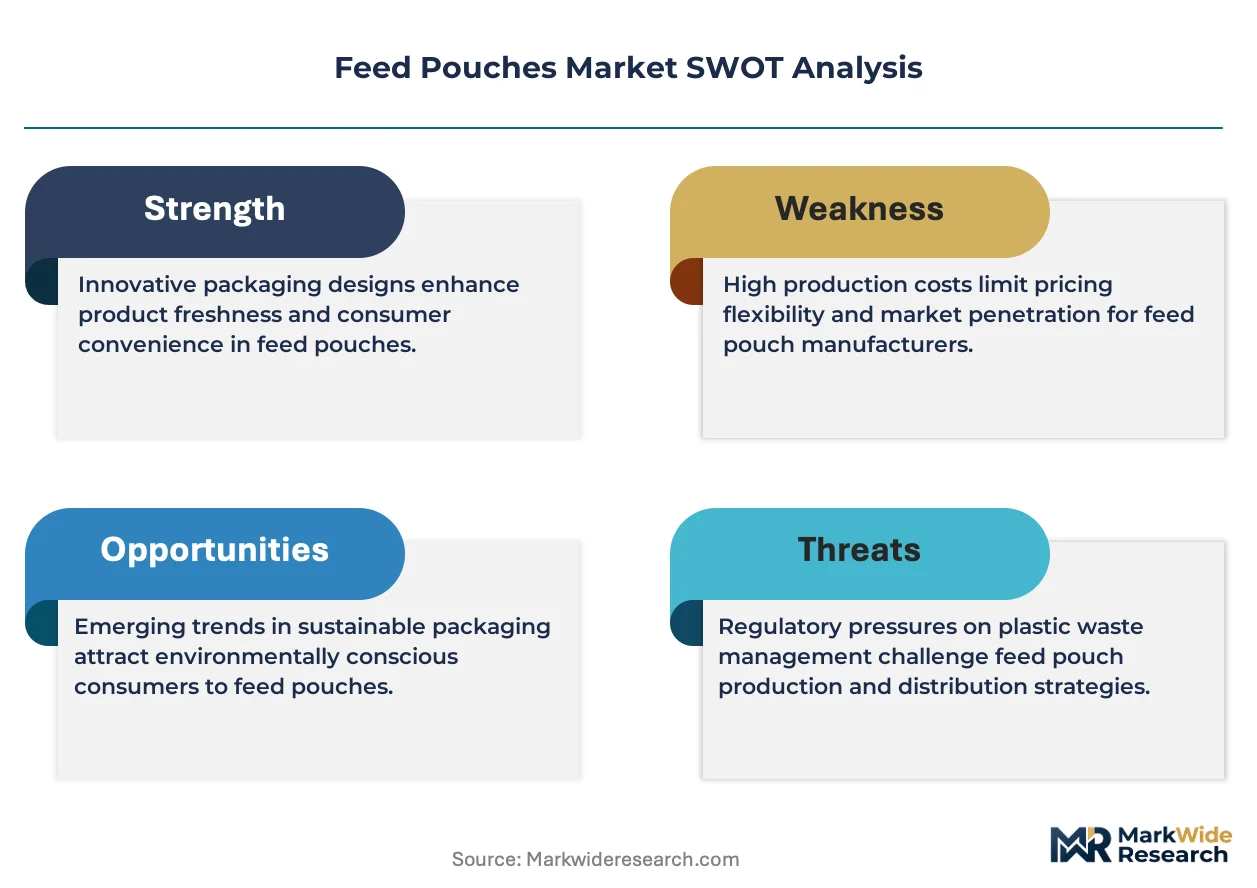
EU F-Gas Regulation and REACH compliance are forcing converters toward solvent-free lamination and mono-material structures, while premium pet food brands simultaneously accelerate adoption of high-barrier pouch formats. This dual pressure is compressing legacy multi-layer supply chains and rewarding early movers with integrated recycling pathways.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated barrier treatments are accelerating investment in EVOH and SiOx coating alternatives for oxygen-sensitive feed formulations.
- Premium pet nutrition brands:German and French retailers are mandating extended producer responsibility compliance, pulling converters toward certified recyclable mono-PE structures.
- Solvent-free lamination:Water-based and UV-curable adhesive systems are capturing share from conventional solvent lamination as converters seek VOC emission reductions.
Market Restraints
- Aluminum foil price volatility:Raw material swings for high-barrier metalized layers compress converter margins on mid-tier agricultural feed contracts.
- German converter concentration:Integrated flexible packaging clusters around Stuttgart and Hamburg control premium capacity, creating supply bottlenecks for specialized short-run orders.
- Mechanical recycling incompatibility:Legacy PET/PE/foil laminates face technical limitations in standard sorting streams, blocking circular economy claims.
Strategic Opportunities
- Poland and Czech Republic:Underpenetrated feed manufacturing bases in Central Europe offer first-mover advantage for localized pouch production serving EU export markets.
- Compostable certification pathways:Emerging TÜV Austria and DIN CERTCO standards for industrial compostability create regulatory tailwinds for PLA- and PHA-based barrier films.
- Direct-to-consumer pet food subscriptions:E-commerce fulfillment channels are demanding right-sized pouch formats with optimized cube utilization and damage-resistant seals.
Industry Challenges
- Multilayer extrusion operator scarcity:Specialized technicians capable of calibrating coextrusion die gaps for EVOH distribution are in short supply across European converter bases.
- Extended producer responsibility registration:Compliance timelines for German VerpackG and French CITEO schemes require six-month lead times that delay new product launches.
- Legacy print cylinder inventory:Rotogravure cylinder amortization cycles create friction for brands seeking rapid design changes to meet seasonal feed formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Pouches Market |
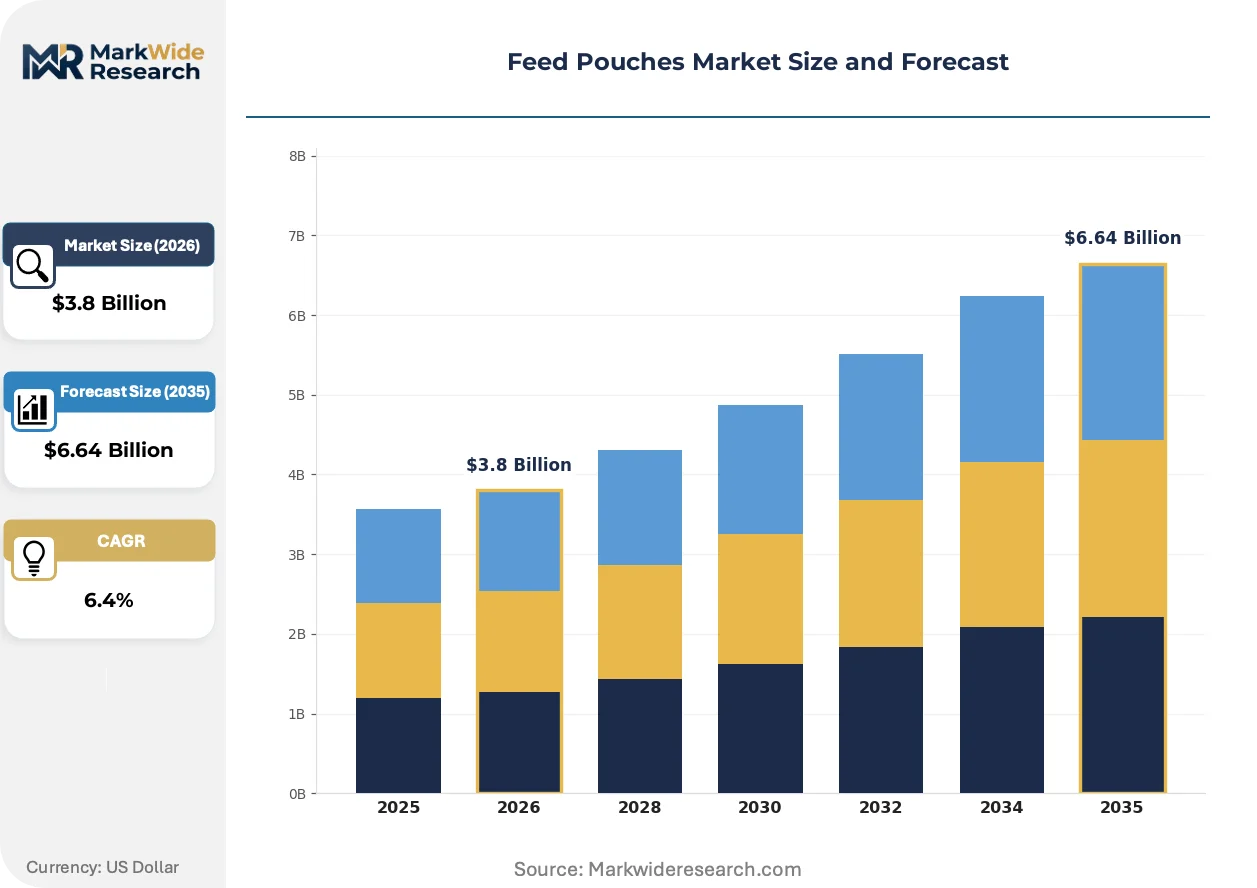
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Laminated Films, Metallized Films, Paperboard, Plastic Film, Foil, Biodegradable Packaging Type: Stand-Up Pouches, Spout Pouches, Flat Bottom Pouches, Gusseted Pouches, Retort Pouches, Vacuum Pouches Application: Animal Feed, Aquafeed, Pet Food, Livestock Nutrition, Specialty Feed Supplements, Veterinary Use End User: Feed Manufacturers, Feed Distributors, Pet Owners, Aquaculture Farms, Livestock Farmers, Agricultural Cooperatives |
| Companies Covered | Amcor, Mondi, Sealed Air, Constantia Flexibles, Coveris, ProAmpac, Huhtamaki, GUALA PACK, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Pouches Market Trends and Innovations
Mono-material polyethylene structures are displacing conventional multi-layer laminates across European feed packaging. Digital print workflows and high-barrier coating technologies are converging to enable shorter runs with equivalent shelf-life performance.
High-barrier SiOx and AlOx plasma coatings are displacing aluminum foil layers in premium pet food pouches. German and Dutch brands are adopting these transparent barrier solutions for microwaveable and see-through packaging applications. This displacement is compressing demand for metalized laminates while enabling full PE mono-material recyclability streams.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated grease barriers from paper-based feed pouches. Converters are migrating toward bio-based wax and clay coating alternatives for agricultural feed applications. Specialty supplement segments requiring oil resistance are absorbing higher material costs to maintain EU market access.
Brand procurement teams are consolidating supplier panels around converters with in-house recycling infrastructure. Mid-tier feed distributors are abandoning spot-buying relationships in favor of multi-year framework agreements with certified circular partners. This concentration is most visible in France and Benelux markets where retailer sustainability scorecards directly influence listing decisions.
Feed Pouches Market Segmentation
Feed pouch segmentation reveals divergent technical requirements across species-specific nutrition formats. Material selection and barrier specifications vary sharply between moisture-sensitive aquafeed and oxygen-critical pet food applications.
Material Type:
Domestic demand concentrates on conventional multi-layer laminates serving established feed manufacturers, while export-led growth orients toward certified recyclable and biodegradable alternatives for EU retail compliance.
- Laminated Films:PET/PE/EVOH multi-layer structures dominate high-volume production through adhesive or extrusion bonding. German and French pet food brands are pulling supply toward solvent-free lamination formats to meet F-Gas Regulation thresholds.
- Metallized Films:Aluminum oxide and silicon oxide vacuum-deposited coatings deliver transparent barrier performance without foil rigidity. Dutch converters are capturing premium share as brands seek microwaveable pouch formats with full PE recyclability.
- Paperboard:Kraft-fiber hybrid structures serve agricultural cooperatives seeking fiber-based alternatives to plastic.
- Plastic Film:Mono-PE and mono-PP structures are gaining traction for mechanical recycling compatibility.
- Foil:Aluminum foil laminates retain niche positioning for ultra-high barrier veterinary and specialty supplement applications.
- Biodegradable:PLA and PHA-based films draw R&D investment from converters targeting industrial compostability certification.
Laminated films command the established base. The steepest expansion runs through metallized films.
Packaging Type:
Volume distribution aligns with retail channel requirements: e-commerce fulfillment favors damage-resistant seals, while club retail demands stable palletization formats.
- Stand-Up Pouches:Doyen-style bottom gusset construction maximizes shelf efficiency and consumer handling convenience. German supermarket chains specify this format for premium dry pet food lines requiring front-panel billboard space.
- Spout Pouches:Fitment-integrated designs enable controlled dispensing for liquid and semi-moist feed supplements. Aquaculture farms in Norway and Scotland are adopting these for on-vessel feeding operations.
- Flat Bottom Pouches:Box-pouch construction delivers vertical stability for palletized distribution of heavy livestock nutrition products.
- Gusseted Pouches:Side-seal expansion accommodates bulk agricultural feed volumes with minimal material usage.
- Retort Pouches:High-temperature sterilization compatibility serves wet pet food and veterinary diet applications.
- Vacuum Pouches:Gas-flush and vacuum-seal configurations extend shelf life for oxygen-sensitive specialty formulations.
Stand-up pouches anchor current procurement volumes. Spout pouches are climbing the fastest as aquafeed automation spreads.
Application:
Species-specific nutrition drives divergent barrier specifications: ruminant feed tolerates higher moisture transmission, while companion animal products demand near-zero oxygen ingress.
- Pet Food:Dry kibble, wet food, and treat formats require distinct oxygen and moisture barriers. Premium brands in Germany and France are mandating mono-material recyclability for dry food pouches under extended producer responsibility frameworks.
- Aquafeed:High-fat extruded diets demand UV-stable packaging with grease-resistant seals. Norwegian salmon feed producers are specifying high-barrier metallized films for offshore storage conditions.
- Animal Feed:General-purpose nutrition products for multiple species prioritize cost-efficient multi-layer PE constructions.
- Livestock Nutrition:Cattle, swine, and poultry feed applications emphasize palletization efficiency and tear resistance.
- Specialty Feed Supplements:Probiotic and enzyme formulations require low-moisture vapor transmission rates to preserve viability.
- Veterinary Use:Prescription diet and therapeutic nutrition pouches must meet pharmaceutical-grade barrier consistency.
Pet food applications command the established base. Aquafeed is gaining share fastest as marine protein demand intensifies.
End User:
Procurement scale fragments sharply: integrated feed manufacturers negotiate multi-year framework agreements, while livestock farmers purchase through distributor spot-buying channels.
- Feed Manufacturers:Integrated compound feed producers specify custom-printed pouches with batch coding and regulatory panel layouts. German market leaders are consolidating supplier panels around converters with in-house recycling infrastructure.
- Feed Distributors:Regional agricultural supply chains demand quick-turn print runs with seasonal design flexibility. Mid-tier distributors in Poland and Czech Republic are abandoning spot relationships for certified circular partnerships.
- Pet Owners:Direct-to-consumer subscription brands are specifying right-sized pouch formats with optimized cube utilization for e-commerce fulfillment.
- Aquaculture Farms:Marine and freshwater operations prioritize puncture resistance and UV stability for outdoor storage.
- Livestock Farmers:Cattle and swine producers favor large-format gusseted pouches for bulk mineral and protein supplement purchases.
- Agricultural Cooperatives:Member-owned purchasing groups drive fiber-based and reduced-plastic packaging specifications.
Feed manufacturers command the established base. Pet owners are expanding most quickly as subscription commerce reshapes last-mile packaging requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German converter clusters while Polish and Czech producers compete on turnaround speed for mid-tier agricultural contracts. This asymmetry reshapes procurement geography across European feed packaging.
Germany
Premium pet nutrition brands in Stuttgart and Hamburg drive demand for solvent-free laminated pouches under VerpackG extended producer responsibility rules. EU F-Gas Regulation compliance requires converters to abandon fluorinated barrier treatments for EVOH alternatives. The Stuttgart flexible packaging cluster controls high-barrier capacity for specialty feed supplements.
France
Retailer sustainability scorecards through CITEO compliance schemes pull procurement toward certified mono-PE structures. REACH Annex XVII restrictions on PFAS eliminate fluorinated grease barriers from paper-based agricultural pouches. The Lyon-Toulouse corridor hosts converters migrating to bio-based wax coatings for oil-resistant feed applications.
United States
FDA food-contact regulations govern migration limits for pouches serving direct-to-consumer pet food subscriptions. USDA grading requirements for livestock feed labeling shape print specifications and regulatory panel layouts. Midwest agricultural distributors favor quick-turn custom runs for seasonal mineral supplement formulations.
Poland
Underpenetrated feed manufacturing bases attract first-mover investment for localized pouch production serving EU export markets. The country's national environmental regulator enforces packaging waste directives aligned with EU circular economy targets. Warsaw-area converters are abandoning spot-buying relationships in favor of multi-year framework agreements with certified circular partners.
Netherlands
Aquaculture automation in Norwegian and Scottish markets drives demand for spout pouches with UV-stable barriers. Dutch converters capture premium share through SiOx and AlOx plasma coatings that enable full PE recyclability. The Rotterdam-Antwerp logistics corridor supports just-in-time delivery for offshore aquafeed storage operations.
Feed Pouches Market Competitive Landscape
Concentration sits with integrated multinationals controlling extrusion and lamination assets across multiple continents. Regional converters compete on short-run flexibility and seasonal design changes. Three archetypes dominate: film-integrated multinationals, kraft-paper hybrid specialists, and quick-turn custom printers. Dominant competitive moves include backward integration into resin production and strategic partnerships with certified recycling infrastructure operators.
Within the integrated multinational tier, Amcor and Mondi exemplify divergent strategic positioning. Amcor leverages captive film production across multiple continents to sustain cost positions on high-volume laminated formats. Mondi anchors European supply through kraft-paper hybrid lines serving agricultural cooperatives seeking fiber-based alternatives. ProAmpac occupies a position among mid-tier specialists competing on rapid custom print runs for North American feed distributors.
| Leading Market Players |
|---|
| Amcor |
| Mondi |
| Sealed Air |
| Constantia Flexibles |
| Coveris |
| ProAmpac |
| Huhtamaki |
| GUALA PACK |
| Sonoco Products Company |
| Others |
Pricing and Supply Chain Analysis
Six-month lead times for German VerpackG and French CITEO compliance registrations concentrate pricing power with Stuttgart and Hamburg converter clusters, while spot-buying distributors in Poland and Czech Republic absorb volatility through quick-turn premiums. This asymmetry rewards integrated players with in-house recycling infrastructure and compresses margins for regional converters dependent on outsourced EPR fulfillment.
Pricing Analysis
The customization-premium spread widens sharply between solvent-free laminated pouches for German premium pet brands and commodity multi-layer PE formats for Central European agricultural distributors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Pricing pressure stems from aluminum foil volatility compressing converter margins on mid-tier livestock feed contracts. Feed manufacturers with multi-year framework agreements show least price sensitivity; spot-buying livestock farmers exhibit highest elasticity.
Supply Chain Analysis
Rotogravure cylinder amortization cycles create a chokepoint for brands seeking rapid seasonal design changes, locking converters into legacy print commitments. Supply concentrates in Germany, Poland, and Netherlands, with raw material dependencies on EVOH resin, SiOx coating equipment, and kraft fiber supply. Single-source vulnerability runs through specialized coextrusion die technicians capable of calibrating EVOH distribution. Distribution runs through integrated feed manufacturer procurement panels, agricultural cooperative purchasing groups, and direct-to-consumer subscription fulfillment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Extended producer responsibility registration timelines and specialized coextrusion operator scarcity create switching costs that protect incumbent positions.
For Market Incumbents: Consolidate supplier panels around converters with certified circular partnerships to preempt margin compression from aluminum foil volatility. Add solvent-free lamination capacity in Stuttgart cluster to capture premium pet brand procurement shifting from fluorinated barriers. Reinforce position through backward integration into EVOH film production.
For New Entrants and Emerging Players: DIN CERTCO industrial compostability certification fast-tracks market entry for PLA- and PHA-based barrier films targeting French retailer sustainability scorecards. White-space exists in Polish and Czech localized production serving EU export markets. Penetrate through aquafeed spout pouch specialization for Norwegian salmon feed automation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across mono-material recycling infrastructure. Long-term viability favors acquiring converter archetypes with in-house EPR compliance capabilities and digital print workflows. Signal to monitor: German converter consolidation rate and CITEO scheme participation thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Lamination Capacity Expansion | Captures German pet brand procurement migrating from fluorinated barriers under F-Gas Regulation. |
| Mono-Material Recycling Infrastructure Investment | Enables VerpackG and CITEO compliance for premium pouch formats. |
| Digital Print Workflow Integration | Reduces rotogravure cylinder dependency for seasonal feed formulation launches. |
| EVOH Film Backward Integration | Secures barrier layer supply against resin price volatility and technical operator scarcity. |
| Central European Production Footprint | Positions for Polish and Czech feed manufacturing base expansion serving EU export markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across converter procurement managers, pet food brand packaging directors, agricultural cooperative purchasing officers, and EPR compliance specialists. Secondary validation drew from EU F-Gas Regulation filings, REACH Annex XVII substance restrictions, German VerpackG registration databases, and flexible packaging trade association capacity surveys. Bottom-up volume estimates triangulated against top-down macroeconomic indicators across material type, packaging format, and application segments.
Across the analysis window, forecasts reflect segment-specific growth trajectories modeled by material barrier specification, species-specific nutrition requirements, and regional regulatory cluster. CAGRs derived from historical shipment data, capacity utilization rates, and brand procurement panel consolidation patterns. Industry-specific inputs included extended producer responsibility scheme participation rates and solvent-free lamination adoption curves.
Underlying assumptions cover sustained EU regulatory enforcement on fluorinated barriers, with deviation risk concentrated in aluminum foil price volatility and coextrusion technician availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Rice Paper Stand Up Pouch Market
Pouch
Contour Pouches Market
Pouch
Germany Pouch Packaging Market
Pouch
Saudi Arabia Pouch Packaging Market
Pouch
North America Lithium-Ion Battery Pouch Film Market
Pouch
Ziplock Products Market
Pouch
Bio PE Pouches Market
Pouch
GCC Retort Pouches Market
Pouch
Heat Seal Pouch Market
Pouch
High-Barrier Pouches Market
Pouch
Zipper Pouch Market
Pouch
Sterilization Pouches Market
Pouch
Asia-Pacific Retort Pouch Market
Pouch
Vented Stretch Wrap Market
Pouch
OPP Pouches Market
Pouch
Digital Printed Pouch Market