
 Pipe Market | 2026-2036
Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Pipe Market Insights
North American shale basin producers is realigning capacity toward higher-grade seamless output for deep-well applications. Tenaris leverages integrated mills in Argentina and Mexico to control alloy supply from melt to finished pipe. Vallourec sustains premium positioning through specialized threading technology for extreme-pressure environments. JM Eagle dominates thermoplastic distribution via direct municipal contracting across the United States.
A pipe is a hollow cylindrical conduit engineered to specified wall thickness, diameter tolerance, and pressure rating, manufactured through extrusion, rolling, or welding processes to transport fluids, gases, or slurries under controlled flow conditions. Carbon steel seamless pipe occupies the largest value share in oil and gas transmission due to fatigue resistance in high-pressure corridors, while polyvinyl chloride pipe is displacing metal alternatives in water supply networks because of corrosion immunity and lower installation mass. Welded product types command volume leadership in structural and utility applications where dimensional flexibility outweighs pressure extremes.
EPA Lead and Copper Rule compliance deadlines are redirecting municipal procurement toward certified low-lead copper and engineered thermoplastic alternatives, while ASTM International pressure ratings and ISO 4427 dimensional standards govern cross-border product acceptance in water infrastructure. China's GB standards and MEE environmental enforcement are tightening emissions controls on ductile iron foundries and steel pipe coating operations. Stakeholders must weigh material transition costs against regulatory liability exposure when specifying pipe for drinking water and chemical processing systems.
Market Dynamics
Water utility infrastructure upgrades across the United States are accelerating material substitution toward engineered thermoplastics, while EPA Lead and Copper Rule compliance deadlines force certified lead-free procurement decisions at municipal scale.
Growth Catalysts
- EPA Lead and Copper Rule revisions:Municipal water authorities in the United States face mandated material substitution timelines, redirecting procurement toward certified lead-free copper and polyethylene alternatives for distribution networks.
- Polyethylene pipe technology:Corrosion immunity and lower installation mass are displacing metal alternatives in water supply networks, particularly where trenchless installation methods reduce surface disruption costs.
- China municipal infrastructure:Gas distribution and water network expansion in provincial cities is concentrating demand for ductile iron and thermoplastic pipe systems under GB standards compliance.
Market Restraints
- Steel scrap and alloy volatility:Seamless carbon steel producers face margin compression when nickel and molybdenum prices spike, forcing inventory risk onto integrated mills without captive mining.
- Coating operation emissions:China's MEE environmental enforcement is tightening emissions controls on steel pipe coating facilities, adding compliance capital burden to export-oriented producers.
- Concrete pressure pipe substitution:Large-diameter water transmission projects in seismic zones increasingly specify concrete cylinder pipe over steel alternatives for fatigue durability.
Strategic Opportunities
- India rural water schemes:Jal Jeevan Mission deployment timelines are creating demand surges for uPVC and HDPE distribution pipe in previously unserved districts.
- Hydrogen pipeline repurposing:Existing natural gas transmission corridors in Germany and the Netherlands require high-density polyethylene liner insertion and steel integrity assessment for hydrogen service conversion.
- Smart leak detection integration:Sensor-embedded polyethylene pipe systems are enabling real-time pressure monitoring for utilities pursuing non-revenue water reduction targets.
Industry Challenges
- ISO 4427 certification timelines:Cross-border water infrastructure projects face extended approval cycles when national testing laboratories lack capacity for dimensional and pressure-rating verification.
- Welding technician scarcity:Polyethylene fusion joint certification programs are not producing qualified installers at rates matching municipal project acceleration schedules.
- Legacy asbestos-cement replacement:Utilities managing decades-old AC pipe networks confront fiber release protocols and disposal liability that complicate trenchless extraction methods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipe Market |
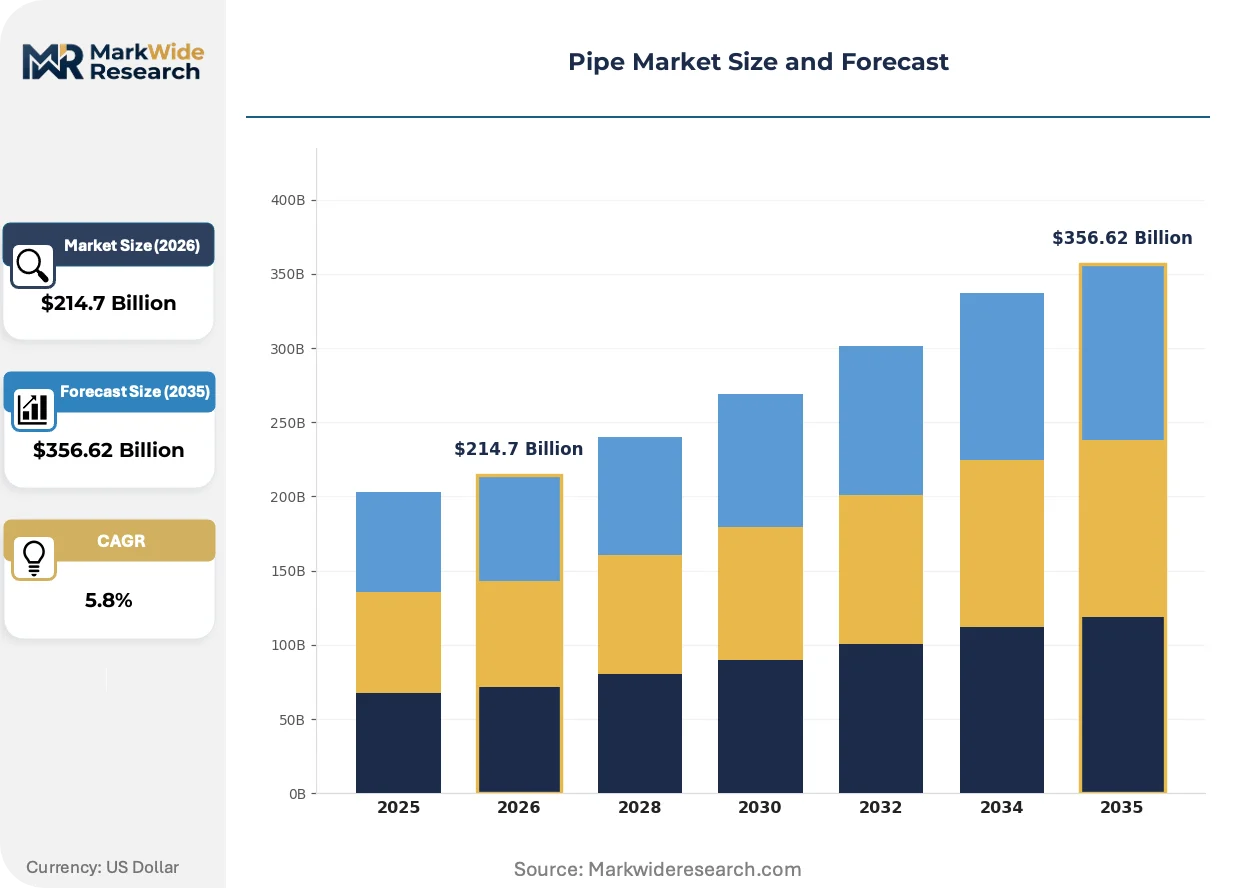
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $356.62 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Carbon Steel, Polyvinyl Chloride, Stainless Steel, Copper, Ductile Iron, Fiberglass Application: Water Supply, Oil & Gas Transmission, Sewage Disposal, Chemical Processing, Irrigation Systems, Fire Protection End User Industry: Construction, Energy Production, Chemical Manufacturing, Agriculture, Utilities, Fire Services Product Type: Seamless, Welded, Plastic, Composite, Coated, Reinforced |
| Companies Covered | Tenaris, Vallourec, Nippon Steel Corporation, JFE Steel, TMK Group, ArcelorMittal, Tata Steel, United States Steel Corporation, JM Eagle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipe Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are compressing traditional product lifecycles while enabling new application categories for thermoplastic systems.
High-density polyethylene pipe formulations with enhanced slow-crack-growth resistance are absorbing market share in directional drilling and horizontal boring applications where point-loading stresses exceed conventional material limits. Gas distribution utilities in the United States specify these grades for urban renewal projects requiring minimal excavation. The technology is absorbing specification authority from engineering firms previously defaulting to steel for all high-pressure corridors.
REACH restrictions on lead stabilizers in PVC compounding are forcing formulation transitions toward calcium-zinc and organotin alternatives across European pipe extrusion operations. The European Chemicals Agency enforcement timeline is compressing supplier qualification windows for water contact applications. Producers serving multiple geographies now maintain parallel compound inventories to satisfy divergent regulatory thresholds.
Direct municipal contracting is displacing traditional distributor networks for large-diameter thermoplastic pipe in the United States. Engineering-procurement-construction firms are consolidating specification influence through design-build contracts that bundle material selection with installation liability. California and Texas water authorities have pioneered this procurement compression, with other states observing outcomes before mandate adoption.
Pipe Market Segmentation
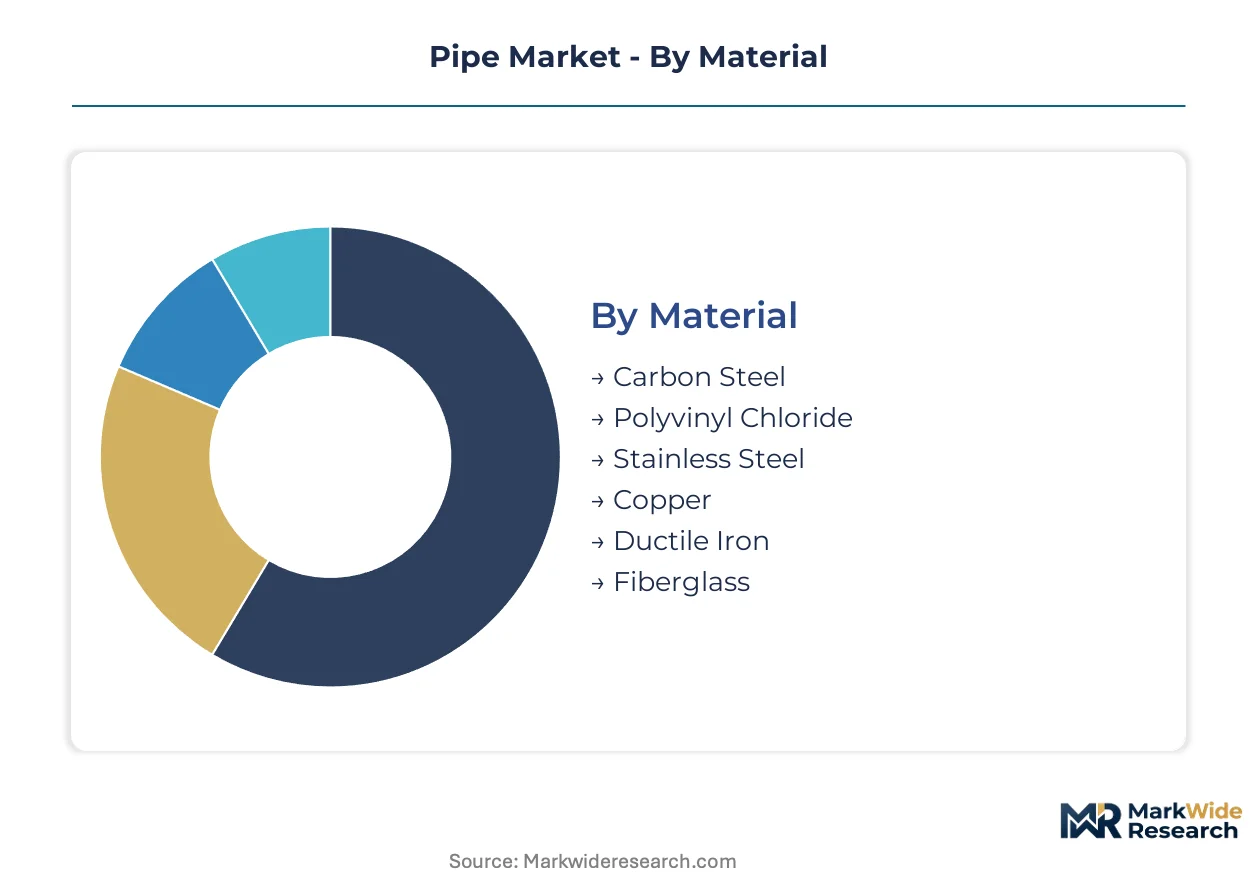
Pipe specification decisions cascade from material selection through installation method, with each segmentation layer imposing distinct regulatory, mechanical, and economic constraints on procurement workflows. Upgrade cycles in water infrastructure and energy transmission networks are fragmenting demand across incompatible technical standards and certification regimes.
Material:
Replacement-cycle intensity varies dramatically by material, with legacy metal systems facing accelerated decommissioning schedules driven by regulatory chemistry restrictions and corrosion failure rates.
- Carbon Steel:Seamless grades dominate high-pressure oil and gas corridors where fatigue resistance under cyclic loading is non-negotiable. North American shale basin producers specify thicker-wall API variants for deep-well injection strings. Demand concentrates in Permian and Bakken field developments where downhole pressure regimes exceed thermoplastic limits.
- Polyvinyl Chloride:Rigid formulations with enhanced impact modifiers are displacing metal in municipal water distribution where trenchless installation reduces surface disruption. REACH restrictions on lead stabilizers are forcing European extruders toward calcium-zinc alternatives. Volume placements concentrate in water supply; the faster expansion belongs to corrosion-immune thermoplastics.
- Stainless Steel:Austenitic grades specified for chemical processing streams requiring chloride resistance.
- Copper:Lead-free certified alloys mandated under EPA Lead and Copper Rule revisions for potable service lines.
- Ductile Iron:Cement-lined variants retain specification in large-diameter water transmission for seismic durability.
- Fiberglass:Filament-wound constructions serve corrosive chemical environments and offshore saltwater intake systems.
Procurement budgets are bifurcating between premium corrosion-resistant alloys and commodity thermoplastics with shorter design lives.
Application:
End-use severity dictates wall thickness, joint methodology, and inspection protocols, with water infrastructure commanding the most fragmented regulatory overlay across jurisdictions.
- Water Supply:Distribution networks require NSF/ANSI 61 certification for potable contact, with polyethylene fusion joints displacing mechanical couplings in United States municipal contracts. China's provincial cities under GB standards compliance are expanding ductile iron trunk lines. Specification authority is consolidating through engineering-procurement-construction design-build bundles.
- Oil & Gas Transmission:Seamless carbon steel with API 5L certification remains mandatory for interstate pipelines where pressure cycling induces fatigue crack growth. Tenaris and Vallourec compete on threading technology for extreme-pressure environments. Demand clusters in shale basin gathering systems and cross-border export corridors.
- Sewage Disposal:Gravity-flow thermoplastic systems prioritize chemical resistance over pressure rating.
- Chemical Processing:Alloy selection governed by ASME B31.3 process piping codes for hazardous fluid containment.
- Irrigation Systems:Flexible polyethylene laterals dominate center-pivot and drip installations for water efficiency.
- Fire Protection:UL-listed steel and ductile iron sprinkler systems mandated by NFPA 13 building codes.
Water supply commands the largest installed base; oil and gas transmission generates the highest per-meter value capture.
End User Industry:
Customer sophistication spans from municipal procurement departments with extended qualification timelines to agricultural operators prioritizing lowest first-cost.
- Construction:Commercial building codes drive specification diversity across mechanical, fire suppression, and drainage systems.
- Energy Production:Upstream operators specify premium seamless grades for downhole integrity under sour gas conditions.
- Chemical Manufacturing:Process safety management regulations enforce material traceability from melt to finished pipe.
- Agriculture:India's Jal Jeevan Mission is creating demand surges for uPVC and HDPE distribution pipe in previously unserved rural districts.
- Utilities:Municipal water authorities face EPA Lead and Copper Rule compliance deadlines redirecting procurement toward certified lead-free alternatives.
- Fire Services:Insurance underwriters influence material selection through premium adjustments for certified suppression system performance.
Utility procurement operates on decade-long replacement cycles; agricultural demand responds to subsidy program announcements.
Product Type:
Manufacturing methodology determines dimensional tolerance, defect detectability, and suitability for automated welding systems in field installation.
- Seamless:Rotary piercing and extrusion mills produce uniform grain structure without weld-line vulnerability. Tenaris leverages integrated Argentine and Mexican facilities to control alloy supply from melt to finished pipe. Premium positioning sustained through specialized threading for extreme-pressure environments.
- Welded:Electric resistance and submerged arc processes dominate structural and large-diameter applications where dimensional flexibility outweighs pressure extremes. China's export-oriented producers face MEE emissions enforcement on coating operations. Volume leadership in utility and construction applications.
- Plastic:Extrusion and injection molding enable complex fitting geometries with corrosion immunity.
- Composite:Filament winding combines fiberglass strength with polymer chemical resistance.
- Coated:Fusion-bonded epoxy and three-layer polyethylene extend steel pipe service life in buried service.
- Reinforced:Steel-wire or fiber reinforcement enhances pressure rating in thermoplastic pressure pipe.
Welded products capture volume leadership; seamless commands specification authority in highest-stakes applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iron ore deposits in Western Australia and the Pilbara anchor seaborne steel feedstock for Asian pipe mills. Bauxite reserves in Guinea and Jamaica concentrate alumina supply for corrosion-resistant alloy production. Natural gas liquids from the Permian Basin and Marcellus Shale underpin North American polyethylene resin capacity.
United States
Shale basin gathering systems and municipal water replacement cycles drive seamless and thermoplastic demand. EPA Lead and Copper Rule compliance deadlines redirect procurement toward certified lead-free copper and polyethylene alternatives. Houston-Gulf Coast petrochemical complexes supply high-density polyethylene resin for fusion-welded distribution networks.
China
Provincial city gas distribution and water network expansion concentrate ductile iron and thermoplastic procurement. GB standards compliance and MEE environmental enforcement tighten emissions controls on steel pipe coating operations. Yangtze River Delta manufacturing clusters integrate extrusion capacity with downstream fitting production for domestic infrastructure.
Germany
Hydrogen pipeline repurposing initiatives require high-density polyethylene liner insertion and steel integrity assessment for natural gas corridor conversion. REACH restrictions on lead stabilizers force PVC formulation transitions toward calcium-zinc alternatives. Ruhr industrial legacy networks provide testing grounds for hydrogen-ready pipe materials.
India
Jal Jeevan Mission deployment timelines generate demand surges for uPVC and HDPE distribution pipe in previously unserved rural districts. BIS certification requirements govern potable water contact materials across state procurement programs. Gujarat petrochemical corridors supply polymer feedstock for extrusion operations serving western state water schemes.
Brazil
Pre-salt offshore development sustains premium seamless pipe demand for deep-water production risers. ANVISA and environmental licensing delays compress project execution windows for subsea infrastructure. São Paulo state industrial clusters coordinate coating and logistics services for Atlantic basin export corridors.
Pipe Market Competitive Landscape
Global majors compete with regional champions across alloy supply and threading technology dimensions. Seamless carbon steel producers with captive melt shops defend margin positions against welded pipe specialists serving utility applications. Three archetypes dominate: integrated steelmakers controlling raw material through finished pipe, thermoplastic extruders with direct municipal contracting relationships, and specialty alloy fabricators serving corrosive process environments. Capacity expansion and backward integration into resin or scrap supply represent the dominant competitive vectors.
Within the integrated steelmaker tier, Tenaris and Vallourec exemplify premium positioning through specialized threading and extreme-pressure product architectures. JM Eagle occupies a distinct position as a North American thermoplastic specialist with municipal-scale distribution capabilities. These three anchors illustrate how pipe manufacturing stratifies between metallurgical intensity and polymer formulation expertise.
| Leading Market Players |
|---|
| Tenaris |
| Vallourec |
| Nippon Steel Corporation |
| JFE Steel |
| TMK Group |
| ArcelorMittal |
| Tata Steel |
| United States Steel Corporation |
| JM Eagle |
| Others |
Pricing and Supply Chain Analysis
Steel scrap and alloy volatility cascade through seamless carbon steel pricing tiers, with nickel and molybdenum spikes compressing margins at integrated mills lacking captive mining while forcing inventory risk onto buyers of premium API-certified grades for shale basin applications.
Pricing Analysis
Warranty-bundled installation liability separates municipal direct-contract polyethylene pricing from distributor-mediated steel quotations. Three-tier pricing structure across premium seamless threading, standard welded utility grades, and economy thermoplastic water service lines reflects certification intensity and fusion-joint warranty terms. Cost compression in welded carbon steel intensifies because Chinese export-oriented producers face MEE emissions enforcement on coating operations. Agricultural irrigation contractors exhibit highest price sensitivity; deep-well shale operators accept premium seamless grades with minimal negotiation.
Supply Chain Analysis
Scrap steel reclamation and pipe refurbishment flows are underdeveloped across North American and European markets, leaving end-of-life carbon steel and ductile iron largely unrecovered for remelting. Primary production concentrates in China, the United States, and India, with Yangtze River Delta clusters integrating extrusion through fitting fabrication. Feedstock draws from Western Australian iron ore, Permian Basin natural gas liquids for polyethylene resin, and Guinean bauxite for corrosion-resistant alloy inputs. Single-source vulnerability in high-density polyethylene resin supply creates exposure when Gulf Coast petrochemical complexes experience weather-related disruption. Distribution runs through engineering-procurement-construction design-build bundles for large-diameter thermoplastic contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seamless carbon steel capacity expansion timelines lag shale basin demand acceleration, propping pricing power for integrated mills with captive melt shops and threading technology differentiation.
For Market Incumbents: Hedge alloy cost exposure through long-term scrap supply agreements with demolition contractors and automotive shredder operators. Consolidate specification influence by acquiring regional thermoplastic extruders with established municipal procurement relationships, countering the threat of direct-contract displacement of traditional distributor networks.
For New Entrants and Emerging Players: Launch via sensor-embedded polyethylene systems targeting non-revenue water reduction mandates at mid-sized US municipal utilities. White-space concentrates in hydrogen pipeline repurposing services for European natural gas corridor conversion, and in Jal Jeevan Mission rural distribution contracts requiring rapid BIS certification turnaround.
For Investors and Strategic Acquirers: EPA Lead and Copper Rule enforcement acceleration is the leading indicator that certified lead-free copper and engineered thermoplastic procurement will sustain premium pricing tiers. Five-to-ten year viability favors integrated producers with backward control over alloy supply and resin feedstock. Monitor MEE environmental enforcement intensity for signals on Chinese export capacity availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Gulf Coast petrochemical complexes anchor polyethylene supply security for municipal contractors. |
| Hydrogen Service Certification Program | Ruhr industrial legacy networks provide testing grounds for hydrogen-ready steel integrity assessment. |
| Direct Municipal Contracting Expansion | California and Texas water authorities pioneered procurement compression bundling material with installation liability. |
| Smart Leak Detection Integration | Sensor-embedded polyethylene systems enable real-time pressure monitoring for utility non-revenue water targets. |
| Fusion Joint Training Certification Scale-Up | Qualified installer scarcity constrains municipal project acceleration schedules across US distribution networks. |
Research Methodology
Independent corroboration across plant managers at seamless mills, procurement leads at downstream oilfield service companies, municipal water authority engineering directors, and polyethylene resin supply specialists underwrites the qualitative findings. Secondary validation draws from API certification databases, EPA enforcement action records, SEC 10-K filings of listed steelmakers, and customs trade data on alloy and resin flows. Bottom-up project pipeline enumeration triangulates against top-down macroeconomic demand modeling.
Rate-of-change decomposition separates volume growth from price and mix effects across material grade, application severity, end-user industry sophistication, and regional regulatory cluster dimensions. CAGRs derive from segment-level demand elasticity analysis and capacity expansion schedules throughout the forecast period. Shale basin drilling intensity, EPA compliance deadline clustering, and hydrogen pipeline conversion project announcements serve as industry-specific forecast inputs.
Alloy price volatility, regulatory enforcement timing shifts, and welding technician certification bottlenecks are the dominant revision risks to projection assumptions. Practitioners should monitor LME nickel price movements, MEE emissions action schedules, and state-level Jal Jeevan Mission deployment pace for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Perfusion Tubing Systems Market
Pipes and Tubes
Industrial Blast Hoses Market
Pipes and Tubes
Industrial Tubes Market
Pipes and Tubes
Carbon Steel Pipe Fittings Market
Pipes and Tubes
Plastic Pipes and Fittings Market
Pipes and Tubes
Multiflex Tubes Market
Pipes and Tubes
Tapping Sleeves Market
Pipes and Tubes
Aluminium Tubes for OPC Drum Market
Pipes and Tubes
Global PEX (Cross-Linked Polyethylene) Market
Pipes and Tubes
Cryogenic Pipes Market
Pipes and Tubes
Global CPVC Pipes and Fittings Market
Pipes and Tubes
Gas Pipe Fittings Market
Pipes and Tubes
Steel Tubes Market
Pipes and Tubes
Bahrain PVC Pipes Market
Pipes and Tubes
Water and Wastewater Pipe Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market