
 Tapping Sleeves Market | 2026-2036
Tapping Sleeves Market Size, Share, and Industry Trends Forecast 2026-2036
Tapping Sleeves Market Analytics
Preventive maintenance contracts for leak detection and pressure management is hardening into a core revenue stream for tapping sleeve vendors. Mueller Water Products leverages its integrated water infrastructure portfolio to sustain recurring service relationships with municipal buyers. JCM Industries anchors its competitive position through specialized fabrication capabilities in ductile iron and steel variants. Romac Industries differentiates via geographic dominance in Pacific Northwest utility markets.
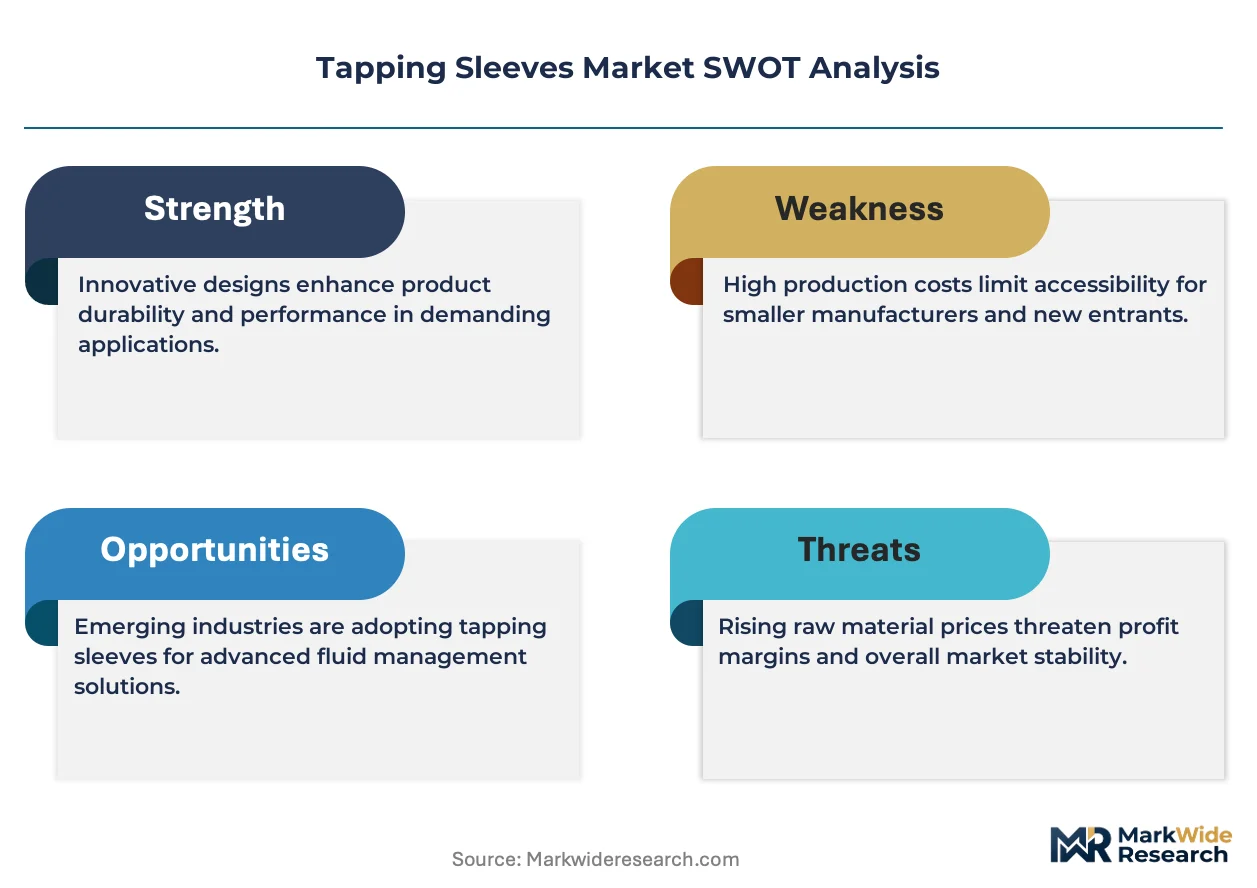
A tapping sleeve is a mechanical fitting clamped or welded onto an existing pressurized pipeline to create a branch connection without system shutdown, typically manufactured from ductile iron, stainless steel, or carbon steel with elastomer gaskets rated for operating pressures up to 250 psi. Its primary purpose is to enable safe, live-tapping operations for water main extensions, fire hydrant installations, and service line connections in distribution networks. Clamp-type products occupy the largest installed base due to versatility across pipe diameters and materials, while mechanical installation methods are expanding fastest as utilities minimize hot-work permitting and crew certification requirements. Steel and ductile iron material segments command the strongest margin pools given pressure rating premiums and longer replacement cycles versus PVC alternatives.
AWWA C223 and C600 standards govern product performance and installation protocols in the United States, while EN 545 and EN 12842 regulate dimensional and pressure specifications across European markets. EPA Lead and Copper Rule revisions and EU Drinking Water Directive updates are tightening material compliance requirements, directly shaping procurement specifications for water utility buyers. Stakeholders must monitor evolving PFAS contamination regulations and their downstream effects on gasket material approvals and replacement timelines across North American and European distribution systems.
Market Dynamics
Municipal water utilities are systematically replacing reactive repair models with predictive asset management programs, compressing replacement cycles for high-pressure distribution components and elevating specification standards for live-tapping hardware.
Growth Catalysts
- AWWA C223 Compliance Mandates:EPA enforcement of updated water infrastructure standards in the United States is disqualifying legacy PVC fittings from high-pressure applications, redirecting procurement toward ductile iron and stainless steel variants rated for 250 psi operating environments.
- Non-Revenue Water Reduction Targets:European utilities under the EU Drinking Water Directive are prioritizing leak detection and pressure management investments, with Germany and France allocating capital toward branch connection upgrades that eliminate system shutdown requirements.
- Mechanical Installation Methods:Clamp-type tapping sleeves are displacing welded alternatives across Australian distribution networks, as water authorities minimize hot-work permitting delays and reduce crew certification burdens for emergency repairs.
Market Restraints
- Stainless Steel Input Volatility:Nickel and chromium price fluctuations are compressing margin pools for high-pressure sleeve fabricators, particularly for AWWA-rated products requiring specific metallurgical certifications.
- Gasket Material Supply Concentration:EPDM and nitrile rubber compounders in East Asia dominate elastomer supply for pressure-rated seals, creating vulnerability to shipping disruptions and customs processing delays.
- PVC Substitution in Low-Pressure Zones:Cost-conscious utilities in secondary distribution networks continue specifying thermoplastic alternatives for applications below 100 psi, limiting premium material penetration in price-sensitive segments.
Strategic Opportunities
- Smart City Water Infrastructure:Integration of pressure sensors and flow monitors within tapping sleeve assemblies is creating data-rich branch connections for utilities in Singapore and the Netherlands pursuing real-time distribution analytics.
- PFAS-Compliant Gasket Formulations:EPA and ECHA evaluations of fluorinated compound safety are opening procurement windows for next-generation sealing materials that preempt regulatory exclusion of legacy chemistries.
- Preventive Maintenance Contracting:Australian water corporations are unbundling installation from lifecycle service agreements, creating recurring revenue structures for vendors capable of pressure-testing and gasket replacement scheduling.
Industry Challenges
- AWWA Certification Timelines:Third-party validation protocols for new sleeve designs extend 14-18 months, delaying product commercialization and compressing development ROI windows for mid-scale fabricators.
- Legacy System Compatibility:Pre-1980 cast iron mains with irregular outer diameters require custom-fabricated sleeve solutions, fragmenting production runs and elevating engineering overhead for one-off municipal specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tapping Sleeves Market |
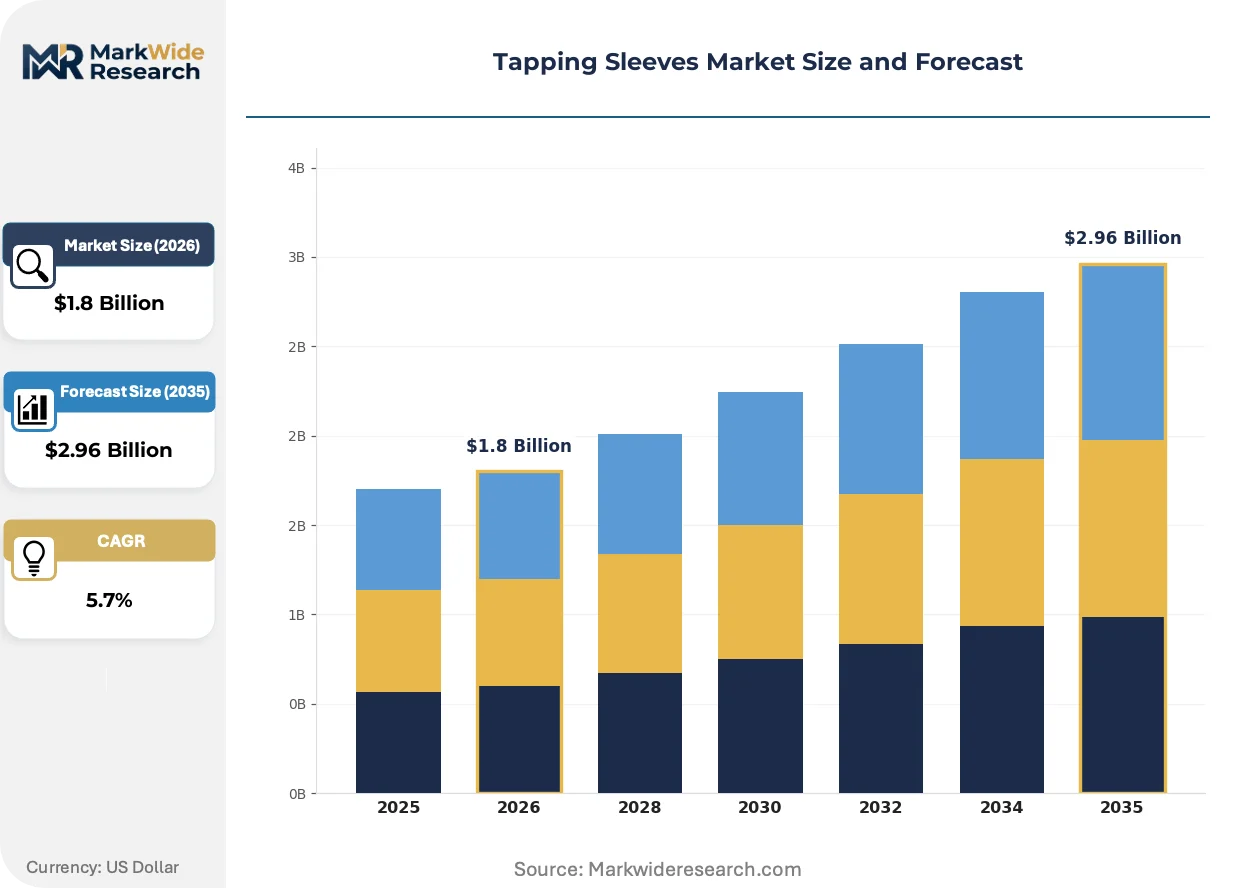
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clamp, Mechanical, Backing Ring, Ductile Iron Installation Method: Welding, Screwing, Flanging, Threaded End User: Construction, Oil & Gas, Water Utilities, Industrial Material: Steel, PVC, Composite, Others |
| Companies Covered | Mueller Water Products, AMERICAN, Ford Meter Box Company, JCM Industries, Romac Industries, Smith-Blair, PowerSeal Corporation, Robar Industries, Everett J. Prescott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tapping Sleeves Market Evolving Landscape
Live-tapping operations are converging with digital monitoring capabilities and prefabricated installation systems, transforming a mechanical fitting category into an integrated infrastructure node with embedded intelligence and compressed deployment timelines.
Robotic hot-tapping systems are automating branch connections on pressurized steel and ductile iron mains, with United States water authorities piloting remote-controlled cutting and valve insertion to minimize crew exposure to excavation hazards. These systems compress installation windows from hours to minutes while reducing labor certification requirements for confined-space entry. The technology is automating work previously requiring specialized welders and heavy equipment operators, reshaping contractor qualification standards across North American distribution networks.
REACH chemical restrictions and ECHA substance evaluations are accelerating material substitution timelines for European tapping sleeve procurement, with EN 12842 compliance now requiring full material disclosure for elastomer gaskets and metallic components in contact with potable water. Fabricators are reformulating sealing compounds and documenting supply chain provenance to maintain CE marking eligibility. German and Dutch utilities are leading specification updates that exclude non-compliant legacy inventory from tender eligibility.
Performance-based service agreements are displacing traditional equipment-only purchasing across Australian and United Kingdom water utilities, with procurement teams evaluating vendors on leak-free operational hours rather than unit cost metrics. Contractors are bundling installation, pressure testing, and scheduled gasket replacement into multi-year commitments. This model concentrates supplier relationships among firms with regional service infrastructure and certified technician networks, compressing vendor lists in metropolitan markets.
Tapping Sleeves Market Segmentation
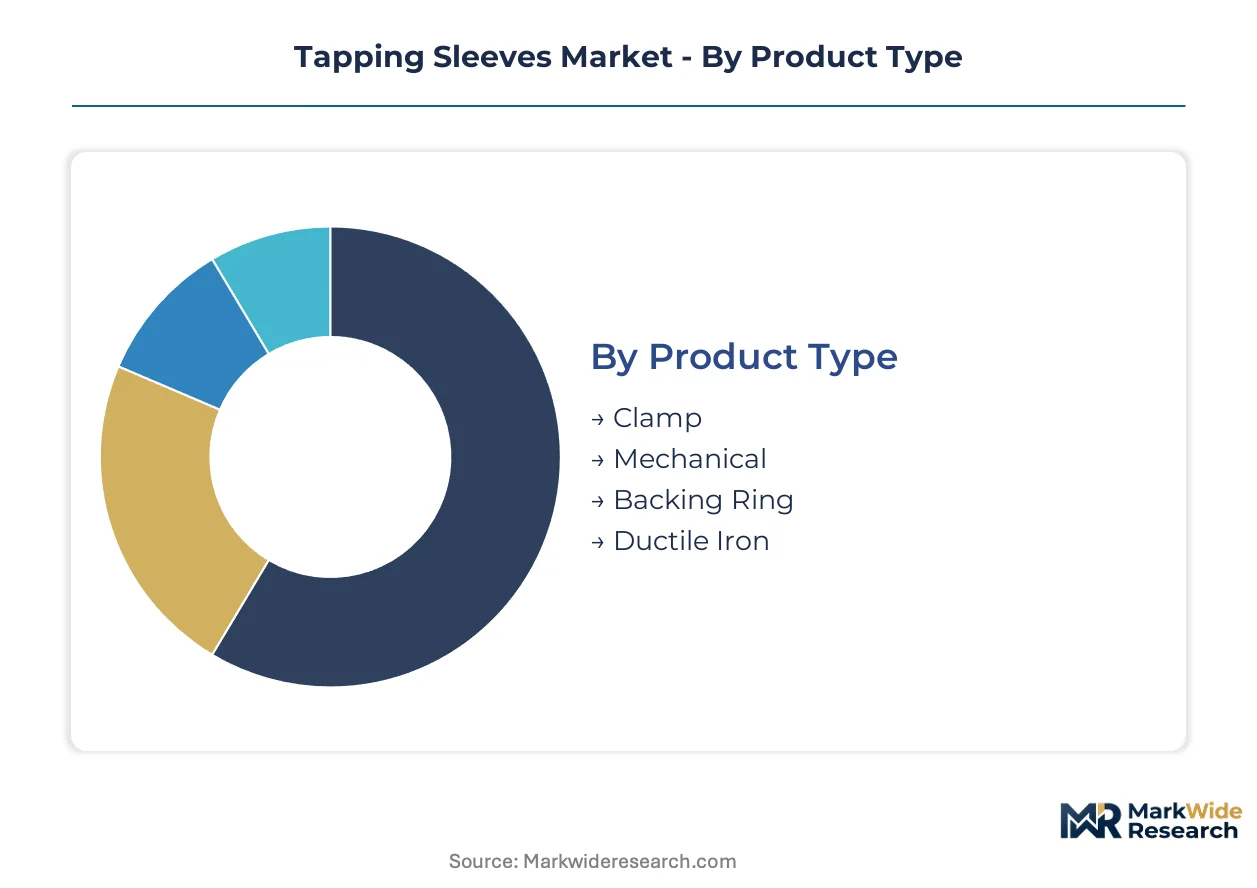
Segmentation in tapping sleeves reflects divergent pressure ratings, installation constraints, and regulatory compliance requirements across municipal and industrial buyers. Procurement specifications vary sharply between emergency repair scenarios and planned network extensions, fragmenting vendor specialization.
Product Type:
Standardized clamp designs dominate high-volume procurement, while custom-fabricated variants serve irregular pipe geometries and legacy cast iron networks.
- Clamp:Two-bolt or four-bolt configurations with elastomer gaskets seal against pressurized steel and ductile iron mains. Water utilities in the United States specify AWWA C223-rated clamp sleeves for live-tapping operations on distribution lines up to 250 psi.
- Mechanical:Compression-seal designs eliminate welding requirements and reduce crew certification burdens. Australian water authorities are expanding mechanical sleeve procurement to accelerate emergency repair timelines and minimize excavation permit delays.
- Backing Ring:Flange adapters for polyethylene pipe transitions.
- Ductile Iron:Cast body variants for high-pressure transmission mains.
Most installed capacity flows through Clamp. Expansion is steepest in Mechanical.
Installation Method:
Cost tiers separate capital-intensive welded systems from rapid-deployment mechanical alternatives, with labor certification requirements driving specification divergence.
- Welding:Full-penetration welds on steel sleeves deliver maximum pressure integrity for transmission mains. German utilities specify welded installations on EN 545-compliant ductile iron networks where mechanical failure risks exceed crew cost premiums.
- Screwing:Threaded branch connections for service lines and fire hydrant taps. United States municipal contractors favor screwing methods for PVC and polyethylene pipe networks where hot-work permits are prohibitively expensive.
- Flanging:Bolted flange assemblies for above-ground installations and valve integration.
- Threaded:Precision-machined connections for small-diameter service line extensions.
Volume concentrates in Screwing for residential service connections. Margin pools are deepest in Welding.
End User:
Customer type determines specification stringency, with regulated utilities enforcing material traceability that commercial buyers often waive.
- Water Utilities:Municipal procurement teams mandate AWWA or EN certification, pressure testing documentation, and gasket material disclosure. EPA Lead and Copper Rule compliance is redirecting specification toward stainless steel and ductile iron variants across United States distribution networks.
- Construction:Temporary branch connections for dewatering and site utility staging. Australian infrastructure contractors specify lower-pressure clamp sleeves for project-duration applications where permanent installation cost cannot be justified.
- Oil & Gas:Pipeline hot-tapping for production lateral connections.
- Industrial:Process water and cooling system branch connections.
Water Utilities command specification leadership. Construction offers the shortest sales cycles.
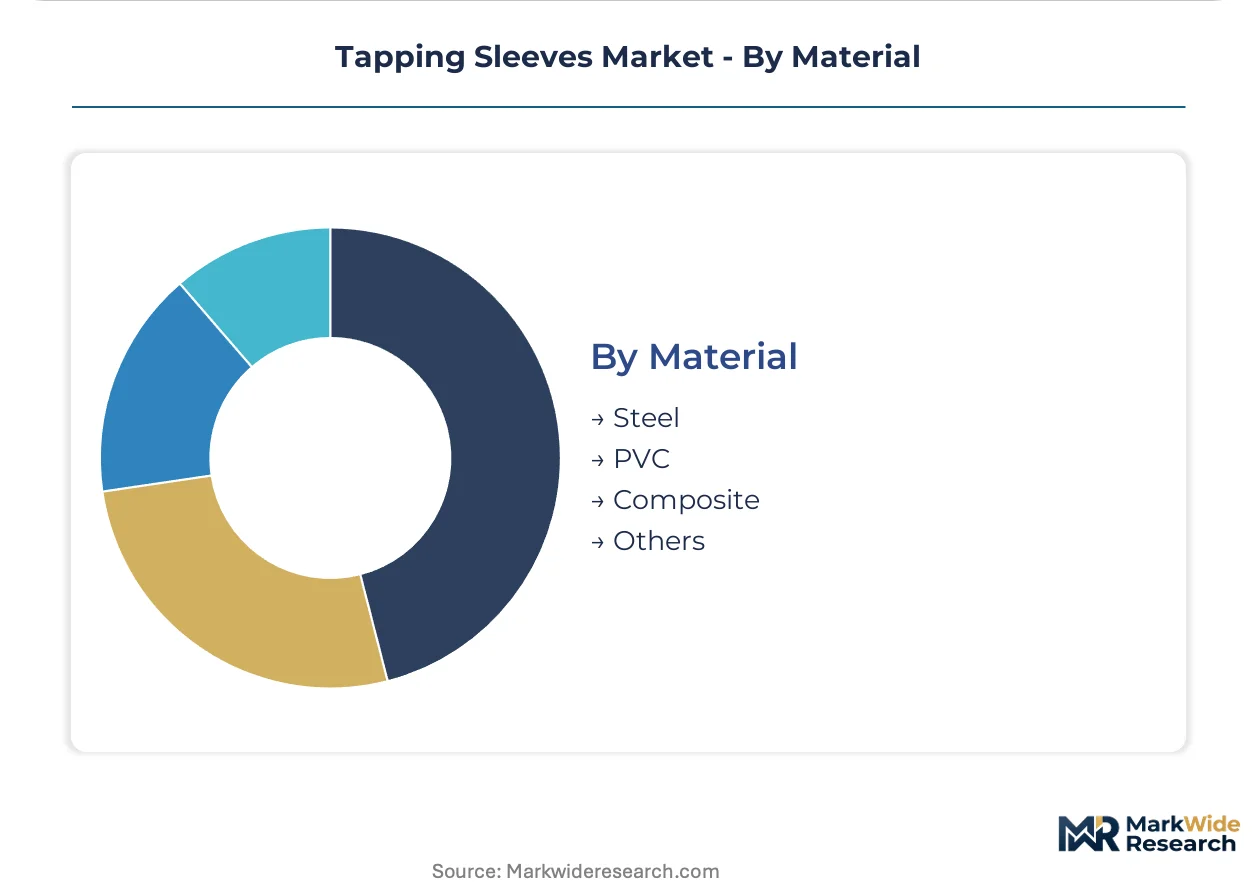
Material:
Supply concentration in steel mills and elastomer compounders shapes regional availability and certification timelines for pressure-rated components.
- Steel:Carbon steel and stainless steel sleeves rated for 250 psi operating pressure dominate high-pressure municipal applications. Nickel price volatility is compressing margins for AWWA-rated stainless fabricators dependent on specific metallurgical certifications.
- PVC:Thermoplastic sleeves for gravity systems and low-pressure distribution zones below 100 psi. Cost-conscious utilities in secondary networks continue PVC specification despite pressure rating limitations.
- Composite:Fiber-reinforced polymer sleeves for corrosion-resistant applications.
- Others:Ductile iron castings and specialty alloys for extreme pressure or chemical resistance.
Steel carries the replacement cycle premium. PVC retains price-sensitive volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States utilities prioritize ductile iron and stainless steel variants for high-pressure distribution networks, while German water authorities accelerate mechanical sleeve procurement under stricter EN standards compliance mandates.
United States
Municipal water utilities in California, Texas, and the Great Lakes region are replacing legacy cast iron infrastructure with AWWA C223-rated clamp sleeves rated for 250 psi operating pressure. EPA enforcement of updated Lead and Copper Rule revisions is disqualifying PVC fittings from potable water applications. Chicago and Detroit metropolitan water districts are consolidating procurement specifications around stainless steel variants with full material traceability documentation.
Germany
Rhineland and Bavarian water utilities under the EU Drinking Water Directive are prioritizing leak reduction investments that eliminate system shutdown requirements for branch connections. EN 545 and EN 12842 compliance now mandates complete material disclosure for elastomer gaskets and metallic components in contact with potable water. The Ruhr industrial cluster is hosting specification workshops where Dutch and Belgian utilities align procurement standards with German pressure-rating protocols.
Australia
Sydney Water and Melbourne metropolitan authorities are expanding mechanical sleeve installation to minimize hot-work permitting delays for emergency repairs. State-level water corporations are unbundling equipment procurement from multi-year preventive maintenance contracts that include pressure-testing and scheduled gasket replacement. The Perth metropolitan distribution network is piloting clamp-type sleeves for polyethylene pipe transitions in rapid-deployment scenarios.
United Kingdom
Thames Water and United Utilities are adopting performance-based service agreements that evaluate vendors on leak-free operational hours rather than unit cost metrics. The Environment Agency's non-revenue water reduction targets are redirecting capital toward live-tapping solutions that avoid excavation and traffic disruption permits. Scottish Water is consolidating branch connection specifications across Aberdeen and Glasgow metropolitan zones.
Canada
Ontario and British Columbia municipal utilities are aligning tapping sleeve procurement with Health Canada guidelines for materials in contact with potable water. The Toronto and Vancouver metropolitan water authorities are specifying ductile iron variants for high-pressure transmission mains crossing seismic zones. Prairie province utilities are evaluating mechanical installation methods to reduce crew certification burdens for seasonal repair windows.
Tapping Sleeves Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with municipal procurement favoring certified fabricators while construction contractors prioritize rapid availability. The vendor base concentrates around ductile iron and stainless steel specialists with AWWA and EN certification capabilities. Two strategic archetypes dominate: integrated water infrastructure portfolio providers and geographic-focused regional fabricators. Competitive moves center on preventive maintenance contract bundling and specialized fabrication capacity expansion for irregular pipe geometry applications.
Among North American specialists, Mueller Water Products, JCM Industries, and Romac Industries occupy distinct positioning vectors. Mueller Water Products exemplifies the integrated portfolio archetype through its breadth of water infrastructure offerings. JCM Industries represents specialized fabrication capabilities in pressure-rated metallic variants. Romac Industries anchors regional dominance in Pacific Northwest utility markets. These three fabricators illustrate how certification depth and service infrastructure concentration shape municipal procurement relationships.
| Leading Market Players |
|---|
| Mueller Water Products |
| AMERICAN |
| Ford Meter Box Company |
| JCM Industries |
| Romac Industries |
| Smith-Blair |
| PowerSeal Corporation |
| Robar Industries |
| Everett J. Prescott |
| Others |
Value Network & Pricing Analysis
Captive in-house production of ductile iron castings and stainless steel fabrication anchors margin structures for AWWA-certified vendors, while outsourced elastomer compounding exposes price volatility in sealing components. This integration choice separates premium-rated fabricators with metallurgical certifications from assemblers dependent on spot-market steel procurement.
Pricing Analysis
Capacity additions in Southeast Asian steel mills are reshaping price floors for carbon steel sleeve variants, compressing margins for non-integrated fabricators. Three-tier pricing structure across AWWA-certified premium, standard mechanical, and PVC economy levels reflects certification investment recovery and pressure-testing documentation costs. Price differentiation hinges on metallurgical traceability and gasket material disclosure compliance. Cost compression in standard-grade segments is intensifying because utilities consolidate procurement volumes through multi-year framework agreements. Construction contractors represent the most price-sensitive buyer archetype, while municipal water utilities absorb premium positioning for lifecycle reliability.
Supply Chain Analysis
Domestic-content mandates in United States infrastructure spending are reshaping sourcing patterns, redirecting ductile iron procurement toward domestic foundries. Raw material flows draw from United States ductile iron foundries, German stainless steel mills, and East Asian EPDM rubber compounders. Nickel and chromium price volatility in specialty alloys creates margin instability for high-pressure rated fabricators. Distribution runs through authorized distributor networks serving municipal procurement departments, with direct-to-utility contracting expanding for preventive maintenance bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by municipal procurement teams elevating AWWA C223 certification requirements above unit-cost minimization. Premium specification demand is displacing legacy PVC alternatives across high-pressure distribution networks.
For Market Incumbents: To counter nickel price volatility eroding stainless steel margins, deepen backward integration into captive ductile iron foundry capacity and expand AWWA certification depth across mechanical sleeve product lines. Certification investment in EN 12842 compliance opens procurement eligibility for German and Dutch utility tenders.
For New Entrants and Emerging Players: Capture fragmented demand for custom-fabricated sleeves serving pre-1980 cast iron mains with irregular outer diameters, where engineering overhead fragments incumbent production runs. Target Australian state water corporations unbundling preventive maintenance contracts from equipment procurement, leveraging rapid mechanical installation capabilities as the entry wedge.
For Investors and Strategic Acquirers: Roll-up economics work for regional fabricators with AWWA certification infrastructure because municipal procurement consolidation favors vendors with localized pressure-testing and gasket replacement service networks. Platform consolidation around certified foundry capacity and regional technician density offers five-to-ten year viability. Watch EPA enforcement intensity on Lead and Copper Rule revisions as the signal for accelerated stainless steel specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ductile Iron Foundry Capacity | Captive metallurgical certification control insulates margin pools from spot steel volatility. |
| AWWA C223 Certification Expansion | EPA enforcement disqualifies legacy PVC, redirecting procurement toward certified metallic variants. |
| Preventive Maintenance Contract Bundling | Australian utilities unbundle lifecycle service agreements, creating recurring revenue structures. |
| PFAS-Compliant Gasket Formulation Development | EPA and ECHA evaluations preempt regulatory exclusion of legacy sealing chemistries. |
| Robotic Hot-Tapping System Pilot Deployment | United States water authorities automate branch connections to minimize crew certification burdens. |
Research Methodology
Coverage spans North America, Western Europe, and Australia-Pacific, with primary inputs from each regional cluster combining structured interviews with municipal water utility procurement directors, ductile iron foundry operations managers, AWWA certification engineers, and construction contractor equipment purchasers. Secondary validation draws from EPA enforcement documentation, EU Drinking Water Directive implementation reports, AWWA standards publications, and customs trade data on steel and elastomer imports. Bottom-up unit demand estimates triangulate against top-down infrastructure spending allocations.
Rate-of-change decomposition separates replacement cycle compression from specification upgrade premiums across the projection horizon. Segmentation dimensions modeled include product type, installation method, material grade, end-user regulatory stringency, and regional certification framework. CAGRs derive from fitted curves on historical procurement volumes adjusted for infrastructure age profiles and regulatory compliance deadlines. Forecast inputs incorporate nickel price futures, municipal capital improvement plans, and EN standards revision timelines.
Steel price volatility, EPA enforcement intensity shifts, and ECHA substance evaluation outcomes are the dominant revision risks to modeled projections. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
UAE PVC Pipes Market
Pipes and Tubes
Reinforced Thermoplastic Pipes Market
Pipes and Tubes
Composite Pipes Market
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
Global Polyethylene Pipes and Fittings Market
Pipes and Tubes
Agricultural Pipes and Tubes Market
Pipes and Tubes
Multiflex Tubes Market
Pipes and Tubes
Hot Dip Galvanized Steel Pipe Market
Pipes and Tubes
US Cold Drawn Seamless Steel Pipes Market
Pipes and Tubes
Polyethylene Pipes Market
Pipes and Tubes
Clad Pipe Market
Pipes and Tubes
PVC Pipes and Fittings Market
Pipes and Tubes
Europe PVC Pipes Market
Pipes and Tubes
HDPE Corrugated Pipe Market
Pipes and Tubes
Multibore Tubes Market
Pipes and Tubes
Compressed Air Pipe Market