
 Natural Rosemarine Extract Market | 2026-2036
Natural Rosemarine Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Rosemarine Extract Market Foresight
Ingredient stewardship revenue is rewriting how extractors capture value downstream from commodity botanicals. DSM Firmenich leverages captive cultivation partnerships across the Mediterranean basin to secure carnosic acid supply chains. Kemin Industries anchors North American demand through GRAS-affirmed rosemary extract lines for protein preservation. Guangzhou Honsea Sunshine Biotech Co., Ltd competes on solvent-free supercritical CO2 extraction capacity serving Asia-Pacific flavor houses.
Natural rosemary extract comprises lipophilic diterpenes—principally carnosic acid, carnosol, and rosmarinic acid—typically standardized to 5-25% carnosic acid content via supercritical fluid or ethanol extraction from Rosmarinus officinalis L. leaves, functioning primarily as a clean-label antioxidant and antimicrobial in lipid-rich matrices. Powder formats dominate bulk industrial procurement for food and nutraceutical blending, while liquid extracts command premium placement in cosmetic serum formulations where solubility profiles matter. Skincare applications within the cosmetics end-use segment show the steepest trajectory, propelled by consumer preference for botanical actives with clinically substantiated radical-scavenging capacity.
EFSA and FDA GRAS frameworks govern antioxidant claims and usage thresholds in food matrices, while REACH and EU Cosmetics Regulation (EC) 1223/2009 mandate full substance characterization and safety dossiers for dermal exposure scenarios. These compliance architectures filter out small-scale uncertified suppliers and consolidate volume among extractors with in-house toxicology and regulatory affairs capabilities. Stakeholders must track evolving purity benchmarks and novel food application approvals to preempt displacement by synthetic antioxidant alternatives.
Market Dynamics
Ingredient stewardship revenue models are compressing margins for commodity extractors while rewarding vertically integrated suppliers with captive cultivation and in-house regulatory dossier capabilities across Mediterranean supply zones.
Growth Catalysts
- REACH compliance elevation:ECHA substance characterization mandates for dermal exposure scenarios filter uncertified competitors from EU cosmetics supply chains, consolidating procurement among dossier-capable extractors.
- Clean-label antioxidant substitution:Food manufacturers in protein preservation and lipid stabilization applications are displacing synthetic TBHQ and BHT with GRAS-affirmed rosemary-derived alternatives.
- Shanghai-Guangzhou nutraceutical corridor concentration:China's functional food processing clusters around these cities generate concentrated demand for standardized carnosic acid extracts in capsule and soft-gel formats.
Market Restraints
- Raw material geographic concentration:Mediterranean basin drought volatility threatens Rosmarinus officinalis L. leaf supply security for non-integrated extractors lacking multi-origin cultivation contracts.
- Supercritical CO2 equipment capex barriers:Solvent-free extraction capacity requires specialized high-pressure systems that small-scale producers cannot finance, limiting purity-grade supply expansion.
- Synthetic antioxidant price anchoring:Petrochemical-derived BHA and BHT maintain cost advantages in mass-market food applications, constraining rosemary extract penetration in price-sensitive categories.
Strategic Opportunities
- India nutraceutical white space:FSSAI novel food approval pathways for standardized botanical extracts remain underutilized relative to protein preservation demand from domestic processed food manufacturers.
- Cosmetic serum solubility premium:Liquid extract formats with tailored polar-lipophilic balance command placement advantages in dermal active formulations where powder formats fail.
- EU Green Deal bioeconomy incentives:CSRD-aligned sustainability reporting creates procurement preference for extraction processes with verified carbon footprint and solvent recovery credentials.
Industry Challenges
- Toxicology dossier capability scarcity:EFSA and FDA GRAS affirmation requires in-house safety assessment expertise that mid-tier extractors struggle to staff and retain.
- Batch-to-batch standardization complexity:Carnosic acid content variation across harvest cycles demands sophisticated analytical QC and blending infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Rosemarine Extract Market |
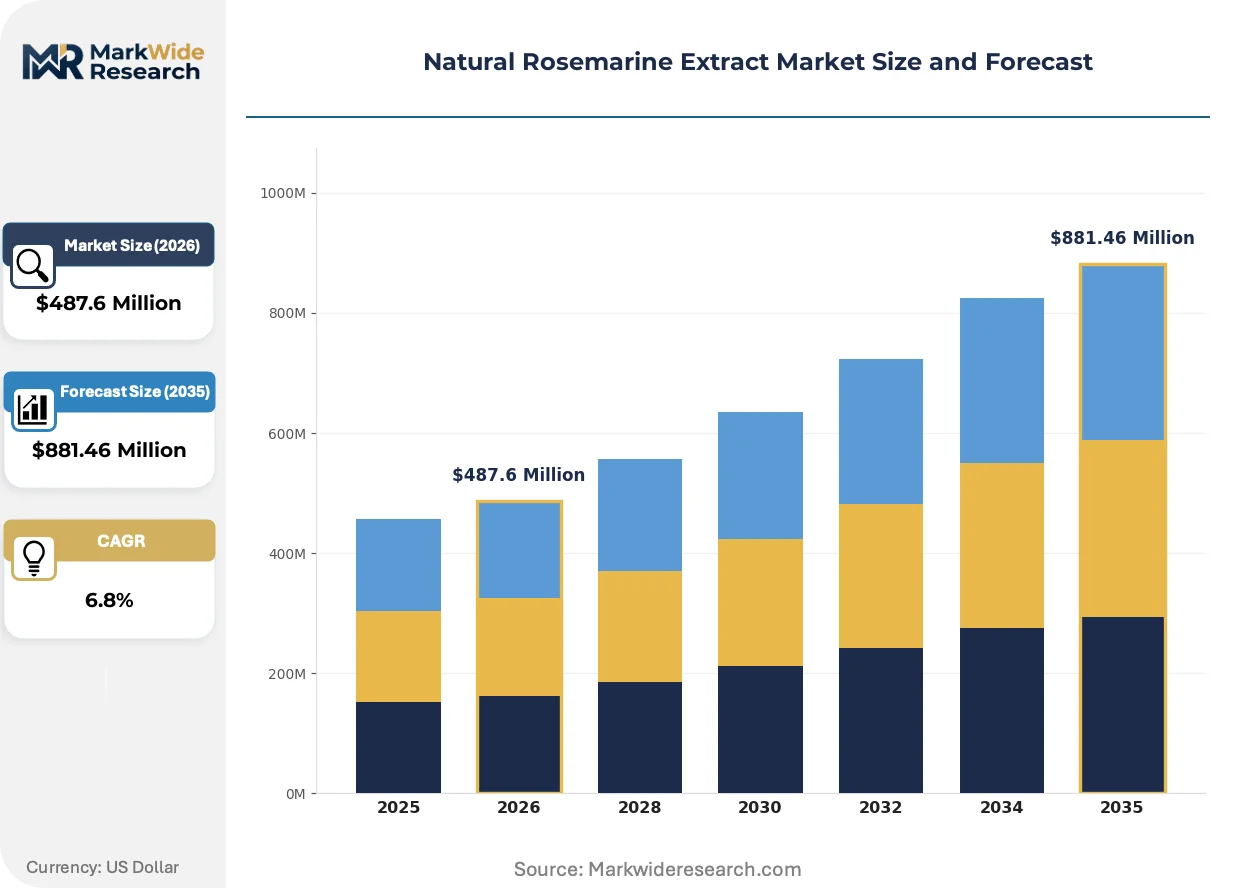
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Cream End User: Cosmetics, Pharmaceuticals, Nutraceuticals, Food & Beverage Application: Skincare, Haircare, Dietary Supplements, Flavors Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | FLAVEX Naturextrakte GmbH, DSM Firmenich, Givaudan, Archer Daniels Midland Company, Guangzhou Honsea Sunshine Biotech Co., Ltd, Symrise, Kemin Industries, Naturex, Kalsec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Rosemarine Extract Market Shifts & Advancements
Extraction technology convergence with sustainability verification systems is redefining competitive differentiation, while regulatory substance characterization requirements and procurement model evolution reshape supplier-buyer relationships across food, nutraceutical, and cosmetic end-uses.
Supercritical fluid extraction is hybridizing with in-line spectroscopic monitoring for real-time carnosic acid quantification. Premium cosmetic formulators in France and Germany are adopting these hybrid systems to secure batch-specific antioxidant activity certificates. This convergence compresses quality assurance timelines from weeks to hours while enabling premium pricing for traceability-assured extracts.
EFSA novel food approval pathways for rosemary extract applications beyond traditional use levels are tightening toxicological data requirements. Food manufacturers seeking expanded usage thresholds in emulsified meat and bakery matrices must commission new absorption-distribution-metabolism-excretion studies. Protein preservation segments in Spain and Italy are responding by consolidating procurement among extractors with existing EFSA dossier experience.
Long-term offtake agreements with cultivation cooperatives are displacing spot-market raw material purchasing among major extractors. This contractual pivot locks in multi-year carnosic acid supply security while transferring agricultural risk to processor balance sheets. The shift is most visible among North American nutraceutical brands seeking insulation from Mediterranean harvest volatility.
Natural Rosemarine Extract Market Segmentation
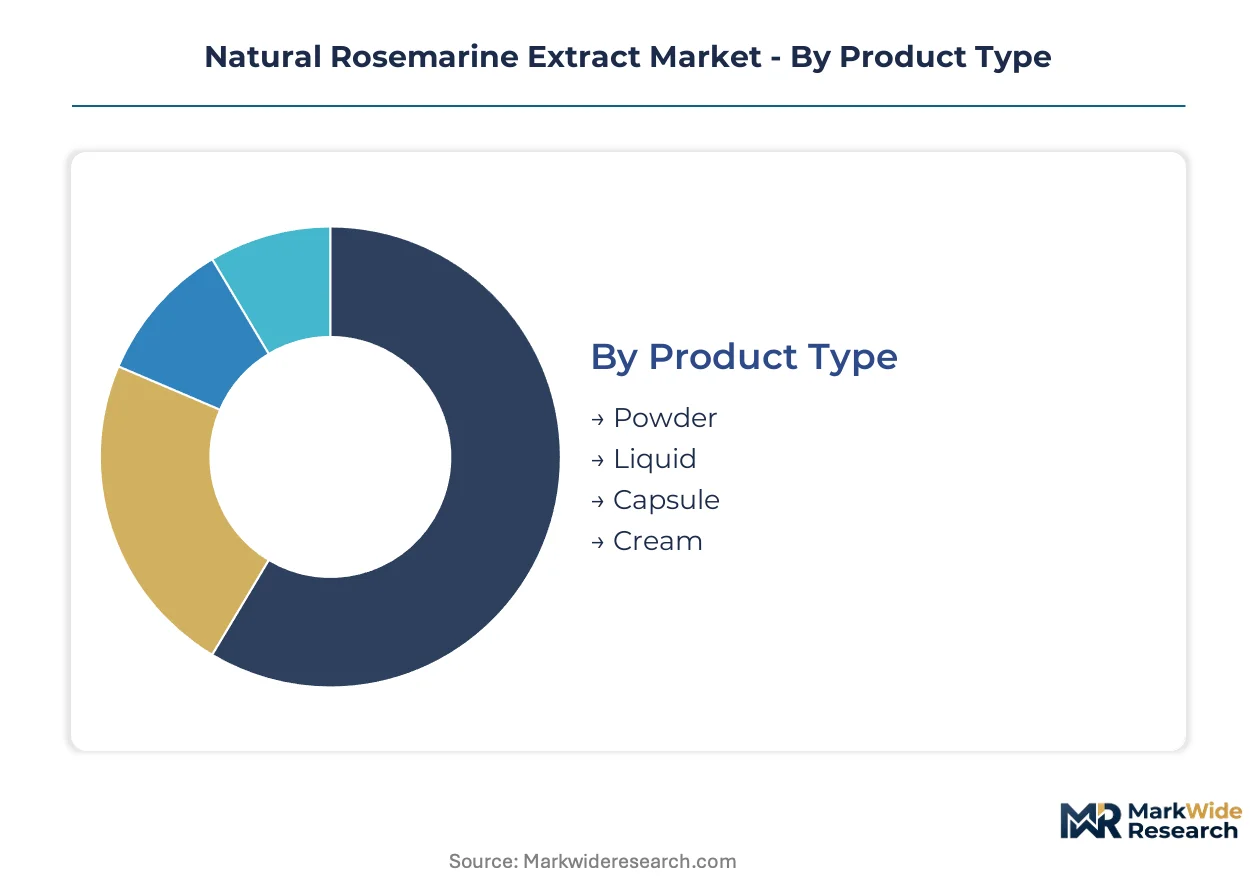
Segmentation in the rosemary extract market tracks divergent purity requirements and formulation constraints across food preservation, cosmetic actives, and nutraceutical delivery systems. Each category reveals distinct procurement patterns driven by solubility demands, regulatory thresholds, and end-use performance specifications.
Product Type:
Use-case spectrum spans industrial bulk blending to precision cosmetic formulation, with format selection determined by matrix compatibility and shelf-stability requirements.
- Liquid:Lipophilic diterpene solutions in ethanol or oil carriers deliver immediate solubility in lipid-rich cosmetic serums. French and German formulators specify liquid formats for dermal antioxidant applications where powder dispersion fails, paying premiums for batch-specific activity certificates from hybrid supercritical extraction systems.
- Powder:Standardized carnosic acid powders at 5-25% concentration dominate food and nutraceutical procurement for protein preservation and capsule filling. China's Shanghai-Guangzhou processing corridor generates concentrated bulk demand for powder formats in soft-gel manufacturing.
- Capsule:Pre-formulated gelatin or vegetable capsules containing measured rosemary extract doses target nutraceutical compliance with FDA GRAS and EFSA novel food thresholds.
- Cream:Emulsified delivery systems combine rosemary antioxidants with cosmetic base matrices for direct skincare application.
Established volume favors powder formats; emerging adoption favors liquid extracts.
End User:
Customer type segmentation maps regulatory complexity against formulation sophistication, with cosmetics and nutraceuticals demanding dossier-capable suppliers while food manufacturers prioritize cost-competitive GRAS compliance.
- Cosmetics:Skincare formulators in France, Germany, and Italy require REACH-compliant substance characterization for dermal exposure scenarios, consolidating procurement among extractors with in-house toxicology capabilities and ECHA dossier experience.
- Food & Beverage:Protein preservation and lipid stabilization applications in Spain and Italy displace synthetic TBHQ with GRAS-affirmed rosemary alternatives, though petrochemical price anchoring constrains penetration in mass-market categories.
- Nutraceuticals:China's functional food clusters demand standardized carnosic acid extracts for capsule and soft-gel formats, with India's FSSAI novel food pathways showing underutilized white space relative to domestic processed food demand.
- Pharmaceuticals:Investigational drug applications and API-grade antioxidant specifications require GMP-compliant extraction and analytical validation beyond food-grade standards.
Margin concentration sits with cosmetics; volume expansion concentrates in nutraceuticals.
Application:
Application segmentation tracks functional performance requirements from radical-scavenging efficacy in dermal matrices to flavor stability in heated lipid systems.
- Skincare:Antioxidant serums and anti-aging formulations leverage carnosic acid's clinically substantiated radical-scavenging capacity, with premium placement commanding price multiples over commodity food-grade extracts.
- Dietary Supplements:Capsule and tablet applications standardize rosmarinic acid content for cognitive and metabolic health positioning, with China's processing corridors driving volume concentration.
- Haircare:Scalp treatments and conditioning products incorporate rosemary extract for antimicrobial and circulation-promoting claims.
- Flavors:Natural flavor stabilization in culinary oils and seasonings preserves volatile compounds against oxidation during thermal processing.
Steepest expansion trajectory characterizes skincare; dietary supplements anchor current revenue base.
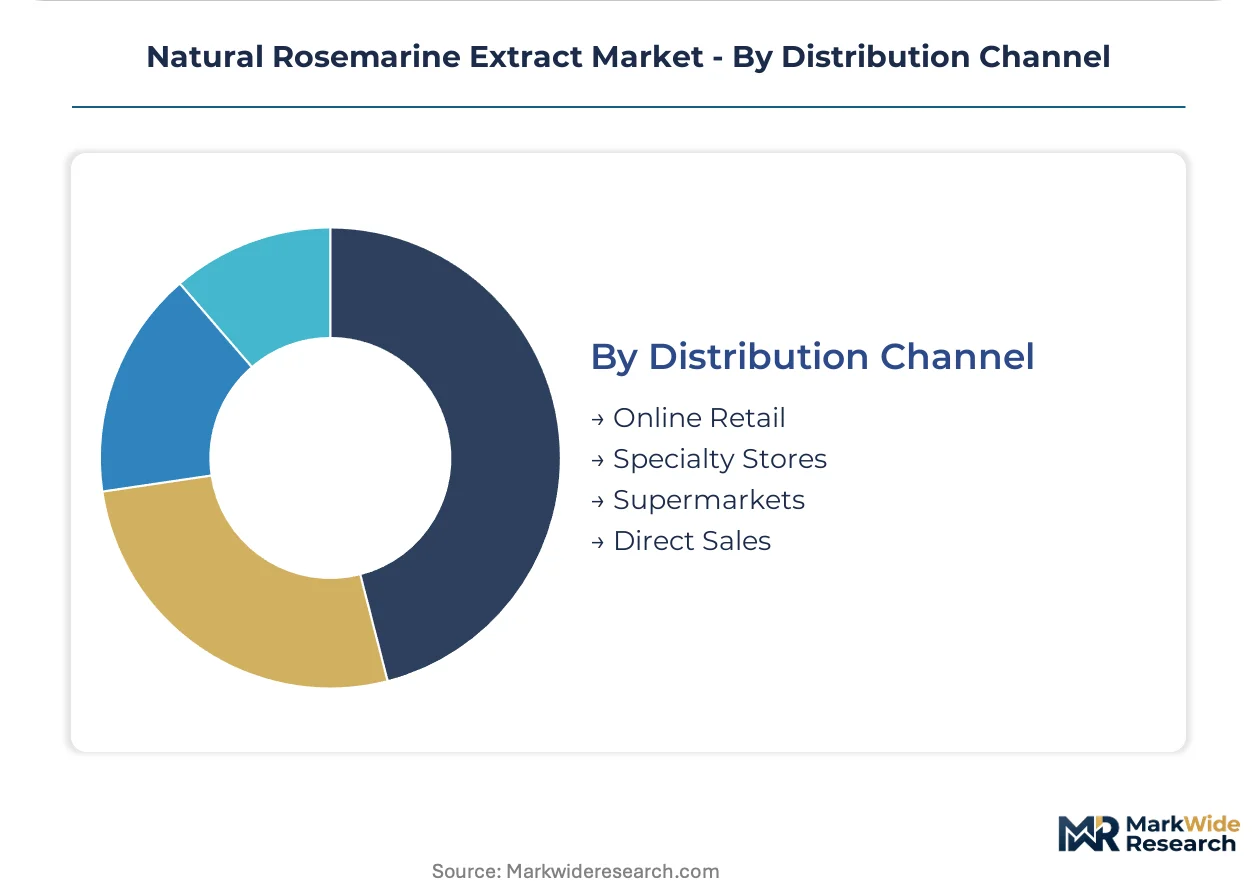
Distribution Channel:
Channel segmentation reflects procurement scale and technical service requirements, with industrial buyers favoring direct relationships while smaller formulators access extracts through intermediaries.
- Direct Sales:Long-term offtake agreements between major extractors and cultivation cooperatives lock in multi-year carnosic acid supply security, transferring agricultural risk to processor balance sheets while insulating North American nutraceutical brands from Mediterranean harvest volatility.
- Specialty Stores:Regional distributors serving mid-tier cosmetic and nutraceutical manufacturers provide technical specification matching and smaller lot flexibility.
- Online Retail:E-commerce platforms access artisanal and small-batch extractors for craft cosmetic formulators and independent supplement brands.
- Supermarkets:Mass-market retail channels distribute finished consumer products containing rosemary extract rather than bulk ingredients.
Procurement consolidation favors direct sales; channel diversification favors specialty stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. European buyers prioritize REACH-compliant cosmetic actives with full substance characterization, while Chinese processors concentrate on bulk carnosic acid powders for nutraceutical encapsulation. North American procurement emphasizes GRAS-affirmed food-grade extracts for protein preservation.
France
Skincare formulators in Paris and Lyon drive premium demand for liquid rosemary extracts with batch-specific antioxidant certificates. ANSM enforces strict dermal exposure safety dossiers under EU Cosmetics Regulation. The Provence-Alpes-Côte d'Azur region hosts extraction facilities serving L'Oréal and LVMH supply chains with carnosic acid standardization to 20-25%.
Germany
Personal care manufacturers in Hamburg and Düsseldorf specify hybrid supercritical extraction systems for real-time carnosic acid monitoring. ECHA substance characterization mandates filter uncertified suppliers from cosmetic procurement. Bavaria's botanical processing corridor concentrates solvent-free extraction capacity for export to Nordic markets.
China
Functional food processors in Shanghai and Guangzhou generate concentrated bulk demand for standardized carnosic acid powders in soft-gel formats. SAMR novel food approval pathways govern expanded usage thresholds in emulsified matrices. The Yangtze River Delta cluster anchors supercritical CO2 extraction infrastructure serving domestic and Asia-Pacific flavor houses.
United States
Protein preservation applications in Chicago and Omaha displace synthetic TBHQ with GRAS-affirmed rosemary alternatives. FDA affirmation requirements consolidate procurement among extractors with existing toxicology dossiers. California's nutraceutical brands pursue long-term offtake agreements to insulate from Mediterranean harvest volatility.
India
Processed food manufacturers in Mumbai and Ahmedabad seek FSSAI novel food approvals for standardized botanical extracts in preservation applications. CDSCO's evolving regulatory framework for plant-based actives creates compliance complexity. Maharashtra's extraction sector remains underdeveloped relative to domestic protein preservation demand.
Natural Rosemarine Extract Market Competitive Landscape
Capability concentration sits with dossier-capable extractors possessing in-house toxicology and ECHA submission expertise; scale advantage sits with agricultural integrators commanding multi-year cultivation contracts across Mediterranean supply zones. The vendor base stratifies into three archetypes: vertically integrated botanical processors with captive farms, specialized extraction technology providers with supercritical CO2 assets, and diversified ingredient houses leveraging global regulatory affairs infrastructure. Consolidation pressure favors M&A targeting EFSA and FDA dossier libraries, while capacity expansion concentrates in solvent-free extraction systems.
Within the European specialist tier, FLAVEX Naturextrakte GmbH exemplifies dossier-capable extraction with REACH-aligned substance characterization. DSM Firmenich anchors the integrated multinational archetype through Mediterranean cultivation partnerships. Guangzhou Honsea Sunshine Biotech Co., Ltd occupies the Asia-Pacific technology specialist position with supercritical CO2 capacity serving regional flavor and nutraceutical demand.
| Leading Market Players |
|---|
| FLAVEX Naturextrakte GmbH |
| DSM Firmenich |
| Givaudan |
| Archer Daniels Midland Company |
| Guangzhou Honsea Sunshine Biotech Co., Ltd |
| Symrise |
| Kemin Industries |
| Naturex |
| Kalsec |
| Others |
Supply & Pricing Matrix
Undercapacity in Mediterranean supercritical CO2 extraction facilities is compressing supplier margins while elevating carnosic acid premiums for REACH-compliant cosmetic grades. ECHA substance characterization mandates and EFSA novel food dossier requirements concentrate pricing power among extractors with in-house toxicology capabilities, forcing commodity-grade producers toward cost-competitive GRAS food preservation segments.
Pricing Analysis
Long-term offtake agreements dominate procurement between major extractors and cultivation cooperatives, locking in multi-year carnosic acid supply security while spot-market purchasing persists among smaller nutraceutical blenders. Price differentiation rests on certification tier—REACH-aligned substance characterization commands premium placement in French and German cosmetic supply chains, while GRAS-affirmed food-grade extracts compete on volume scale. Cost compression in standard-grade powder formats is intensifying because petrochemical-derived BHA and BHT maintain cost advantages in mass-market protein preservation. Food manufacturers show highest price sensitivity; premium skincare formulators demonstrate lowest sensitivity due to batch-specific antioxidant activity requirements.
Supply Chain Analysis
Extended payment terms from North American nutraceutical brands are reshaping working capital requirements for Mediterranean extraction facilities, accelerating supply-chain finance facility adoption among mid-tier processors. Raw material sourcing draws from Morocco, Spain, and Tunisia for Rosmarinus officinalis L. leaf supply, with supercritical CO2 equipment, ethanol solvents, and analytical QC infrastructure anchoring processing dependencies. Single-source vulnerability concentrates in Mediterranean basin drought exposure for non-integrated extractors lacking multi-origin cultivation contracts. Distribution runs through direct sales relationships for industrial bulk procurement, with specialty stores serving mid-tier cosmetic and nutraceutical manufacturers requiring technical specification matching.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as REACH compliance elevation filters uncertified competitors and consolidates procurement among dossier-capable extractors. EFSA novel food approval tightening and clean-label antioxidant substitution are compressing supply availability while elevating premium tier pricing.
For Market Incumbents: Harden supply security through captive cultivation partnerships across Morocco and Tunisia, insulating against Mediterranean drought volatility that threatens Rosmarinus officinalis L. leaf availability. Deepen backward integration into solvent-free supercritical CO2 extraction capacity to capture premium cosmetic serum demand from French and German formulators requiring batch-specific antioxidant certificates. ECHA dossier capability scarcity among mid-tier competitors creates consolidation opportunity through targeted acquisition of regulatory affairs expertise.
For New Entrants and Emerging Players: India's FSSAI novel food approval white space offers the most penetrable geographic entry point, with domestic processed food manufacturers in Mumbai and Ahmedabad seeking standardized botanical extracts for protein preservation applications. Target solvent-free extraction technology differentiation to serve Asia-Pacific flavor houses in China's Yangtze River Delta cluster, where Guangzhou Honsea Sunshine Biotech Co., Ltd has established supercritical CO2 capacity leadership. Pursue technical service partnerships with mid-tier cosmetic formulators requiring smaller lot flexibility and REACH-compliant substance characterization support.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid supercritical extraction systems with in-line spectroscopic monitoring, as premium cosmetic formulators demand real-time carnosic acid quantification capabilities. Long-term viability over the projection horizon favors extractors with integrated cultivation-to-dossier capabilities and EFSA submission track records. Acquisition target archetype: mid-tier Mediterranean processors with established cultivation cooperatives but lacking in-house toxicology infrastructure. Signal to watch: EFSA novel food approval velocity for expanded emulsified meat and bakery matrix applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Cultivation | Multi-origin Rosmarinus officinalis L. contracts insulate processors from Mediterranean drought volatility. |
| Hybrid Supercritical Extraction Capacity Expansion | Real-time carnosic acid monitoring secures batch-specific certificates for French cosmetic formulators. |
| EFSA Novel Food Dossier Investment | Expanded usage thresholds in emulsified matrices unlock protein preservation volume in Spain and Italy. |
| Long-term Offtake Agreement Structuring | Contractual pivot transfers agricultural risk to processor balance sheets while securing North American demand. |
| REACH-aligned Substance Characterization | ECHA compliance filters uncertified competitors from EU cosmetics procurement consolidation. |
Research Methodology
Operator-level perspectives from extraction facility managers, cosmetic formulation chemists, nutraceutical procurement leads, and regulatory affairs directors anchored the qualitative base. Primary interviews with DSM Firmenich supply chain planners, Kemin Industries technical sales heads, and Guangzhou Honsea Sunshine Biotech Co., Ltd production engineers combined with secondary validation from EFSA novel food approvals, ECHA substance characterization databases, FDA GRAS notifications, and EU Cosmetics Regulation (EC) 1223/2009 safety dossiers. Bottom-up volume modeling across product type, end user, application, and distribution channel segments triangulated against top-down macroeconomic indicators.
Scenario-bracketing around REACH compliance evolution, EFSA approval velocity, and Mediterranean climate volatility shaped the analytical framework across the modeling period. Segmentation dimensions modeled include product format (liquid, powder, capsule, cream), end-use industry (cosmetics, food and beverage, nutraceuticals, pharmaceuticals), application function (skincare, dietary supplements, haircare, flavors), and distribution structure (direct sales, specialty stores, online retail, supermarkets). CAGRs derived from regression analysis of historical procurement patterns and forward-looking substitution elasticities for synthetic antioxidant displacement, with supercritical CO2 capacity utilization and cultivation yield variance as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by technology-specialist entrants or accelerated EFSA novel food approvals would shift outcomes. Forecasts reflect documented assumptions around regulatory compliance timelines, cultivation yield stability, and synthetic antioxidant price anchoring. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Thymoquinone Market
Extracts
Palmarosa Oil Market
Extracts
Copaiba Essential Oil Market
Extracts
Lavender Oil Market
Extracts
Anise Extract Market
Extracts
Hydroglycolic Extracts Market
Extracts
Chlorophyll Extract Market
Extracts
Potassium Hydrogen Tartrate Market
Extracts
Irish Moss Extract Market
Extracts
Bidens Pilosa Extract Market
Extracts
Global Marigold Flower Extract Market
Extracts
Valerian Root Powder Market
Extracts
India Retail Mineral Turpentine Oil Market
Extracts
Cassia Seed Extract Market
Extracts
Citrus Powder Market
Extracts
Functional Extract Market