
 China Industrial Hoses Market | 2026-2036
China Industrial Hoses Market Size, Share, and Industry Trends Forecast 2026-2036
China Industrial Hoses Market Analysis
Petrochemical infrastructure is expanding its share of industrial hose procurement across eastern China. Hebei Orient Rubber & Plastic sustains manufacturing scale through integrated compounding facilities in Hebei province. Qingdao Qingflex Hose Factory leverages marine-grade specialization to dominate port-related supply contracts along the Bohai Rim. Tianjin Pengling Rubber Hose anchors its position through backward integration into synthetic rubber compounding for high-pressure applications.
Industrial hoses are reinforced flexible conduits manufactured from rubber, PVC, metal, or composite layers, designed to transport fluids, gases, and abrasive materials under pressures typically ranging from 150 to 6,000 psi depending on reinforcement architecture and end-use specification. These assemblies serve as critical connectivity components in fluid power systems, material handling operations, and process transfer lines across heavy industry. Rubber hoses occupy the largest volume share due to established supply chains for SBR and NBR compounds serving construction and mining applications. Metal hoses capture premium positioning in oil and gas sectors where temperature extremes and chemical compatibility requirements exceed polymer capabilities. Composite hoses are gaining traction in petroleum transfer operations where lightweight construction and corrosion resistance offset higher unit costs against reduced maintenance intervals.
MIIT enforces GB standards for pressure equipment and hose assemblies, while SAMR oversees product safety certification through CCC marking requirements for industrial fluid handling equipment. NMPA regulations on pharmaceutical manufacturing hygiene indirectly shape demand for specialized PTFE-lined hoses in chemical processing plants serving dual pharmaceutical-industrial markets. Stakeholders must monitor evolving dual carbon goals from MEE, as carbon intensity benchmarks increasingly influence material selection and supplier qualification protocols in state-backed infrastructure tenders.
Market Dynamics
MIIT's domestic high-performance polymer standards are compressing import dependency while reshaping supplier qualification protocols across coastal petrochemical clusters. This regulatory pressure is forcing compounders to retool formulations and documentation systems ahead of certification deadlines.
Growth Catalysts
- Dual carbon mandates:MEE carbon intensity benchmarks are accelerating demand for lightweight composite hose architectures in petroleum transfer operations. State-backed infrastructure tenders now embed material efficiency requirements.
- Petrochemical cluster expansion:Jiangsu and Shandong provinces are driving procurement volume through integrated refining-chemical complexes. Hose assemblies serve as critical connectivity in fluid power systems across these facilities.
- GB standards harmonization:MIIT's push for unified domestic polymer specifications is reducing technical friction in cross-provincial supply contracts. Standardized testing protocols shorten qualification cycles for local manufacturers.
Market Restraints
- Synthetic rubber price volatility:SBR and NBR compound costs fluctuate with crude oil derivatives, compressing margin stability for rubber hose producers serving construction and mining.
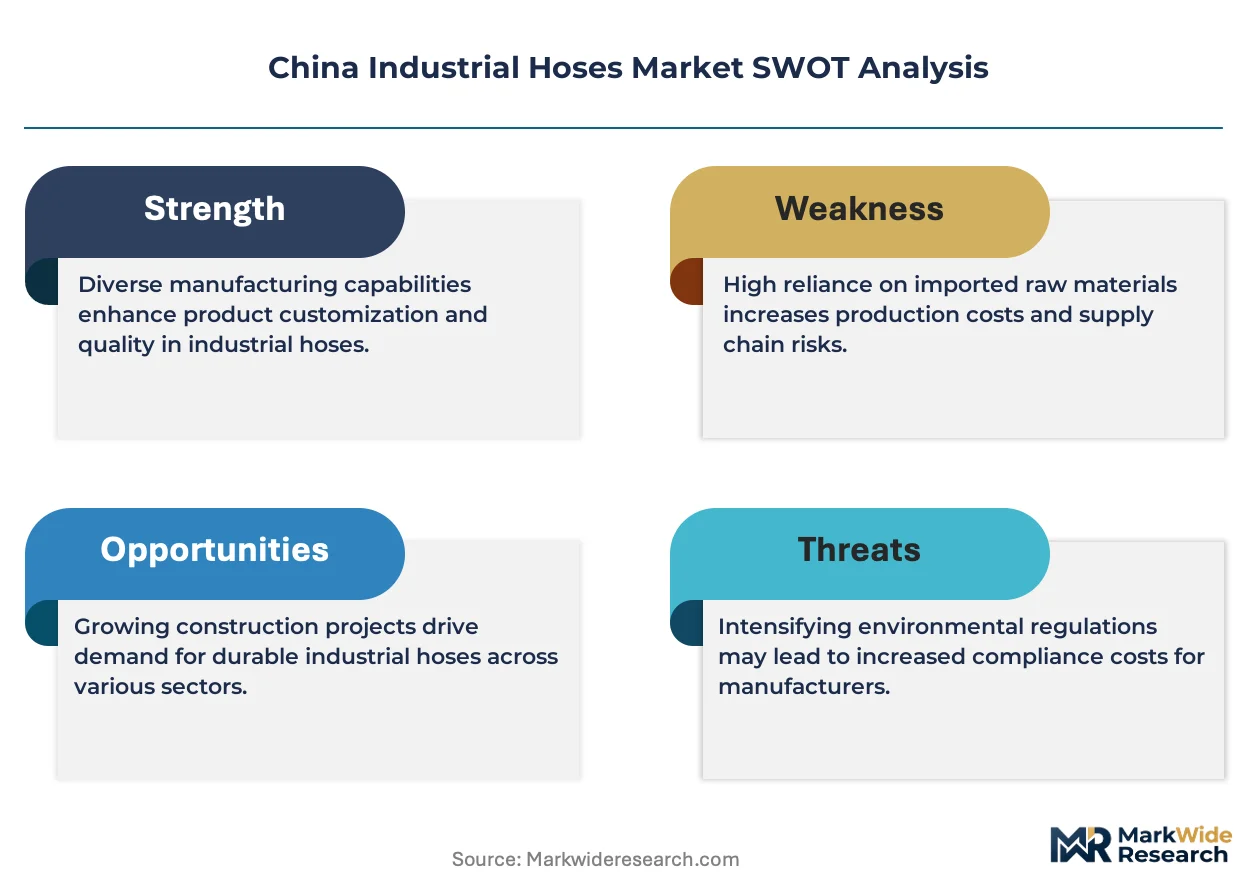
- Import dependency for specialty polymers:High-performance fluoropolymers and aramid reinforcements concentrate among foreign suppliers, creating supply security exposure for PTFE-lined and high-pressure assemblies.
- Technical limitation in extreme cryogenics:Polymer hoses face performance ceilings below minus 196 degrees Celsius, reserving metal hose dominance in LNG transfer and ultra-cold process lines.
Strategic Opportunities
- Pharmaceutical-industrial crossover demand:NMPA hygiene regulations are creating specialized PTFE-lined hose requirements in chemical plants serving dual pharmaceutical feedstock markets.
- Marine-grade specialization:Port infrastructure modernization along the Bohai Rim and Yangtze Delta is opening supply contracts for corrosion-resistant assemblies in offshore loading operations.
- Smart hose integration:Embedded pressure and temperature sensors are converging with industrial IoT platforms, enabling predictive maintenance contracts in high-risk petroleum transfer applications.
Industry Challenges
- CCC certification timeline compression:SAMR marking requirements for industrial fluid handling equipment demand extensive testing documentation, stretching product launch schedules for new hose architectures.
- Skilled compounding technician scarcity:Formulation expertise for multi-layer polymer systems with precise reinforcement integration remains concentrated among aging specialist workforces in Hebei and Tianjin.
- Legacy system integration friction:Smart hose sensor outputs require protocol translation for existing SCADA infrastructure in established petrochemical facilities, complicating retrofit deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Industrial Hoses Market |
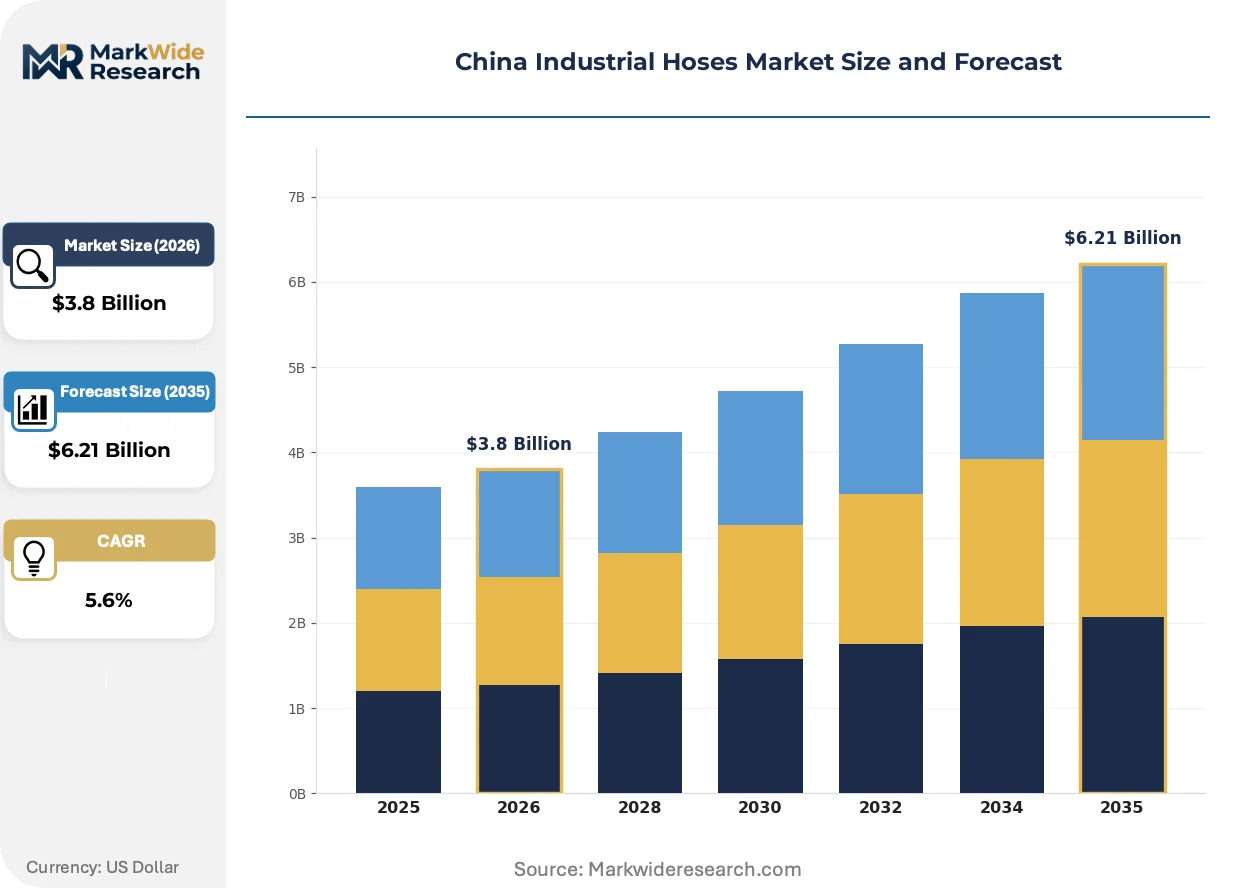
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Hoses, PVC Hoses, Metal Hoses, Composite Hoses Application: Construction, Agriculture, Mining, Oil & Gas End User: Manufacturing, Transportation, Utilities, Aerospace Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Tianjin Pengling Rubber Hose Co., Ltd., Qingdao Qingflex Hose Factory, Sinopulse Hose Factory Co., Ltd., Hebei Orient Rubber & Plastic Co., Ltd., Kingdaflex Industrial, Qingdao Techoses Industrial Co., Ltd., LUCOHOSE Co., Ltd., Qingdao Everflex Rubber & Plastic Co., Ltd., Shijiazhuang StrongFlex Industrial Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Industrial Hoses Market Emerging Trajectories
Material science advances and regulatory tightening are converging to reshape hose architecture priorities across China's industrial base. Three developments are compressing traditional design paradigms.
Composite hose construction is modularizing assembly protocols for petroleum transfer applications. Refinery operators in Shandong are adopting standardized connector modules that reduce field installation time. This architecture is compressing maintenance intervals and enabling rapid component replacement without full line shutdown.
GB/T pressure equipment standards are tightening documentation requirements for hose assemblies in chemical processing. SAMR enforcement is extending traceability mandates to raw polymer batches and reinforcement sources. High-pressure rubber hose manufacturers are responding by implementing blockchain-based material tracking systems ahead of audit cycles.
Buyer consolidation among state-owned petrochemical groups is compressing supplier rosters and extending contract durations. Tier-one refining operators are unbundling after-sales service from equipment procurement, creating standalone maintenance contract markets. This pattern is most visible in Jiangsu province where Sinopec facilities are piloting ten-year total cost of ownership agreements.
China Industrial Hoses Market Segmentation
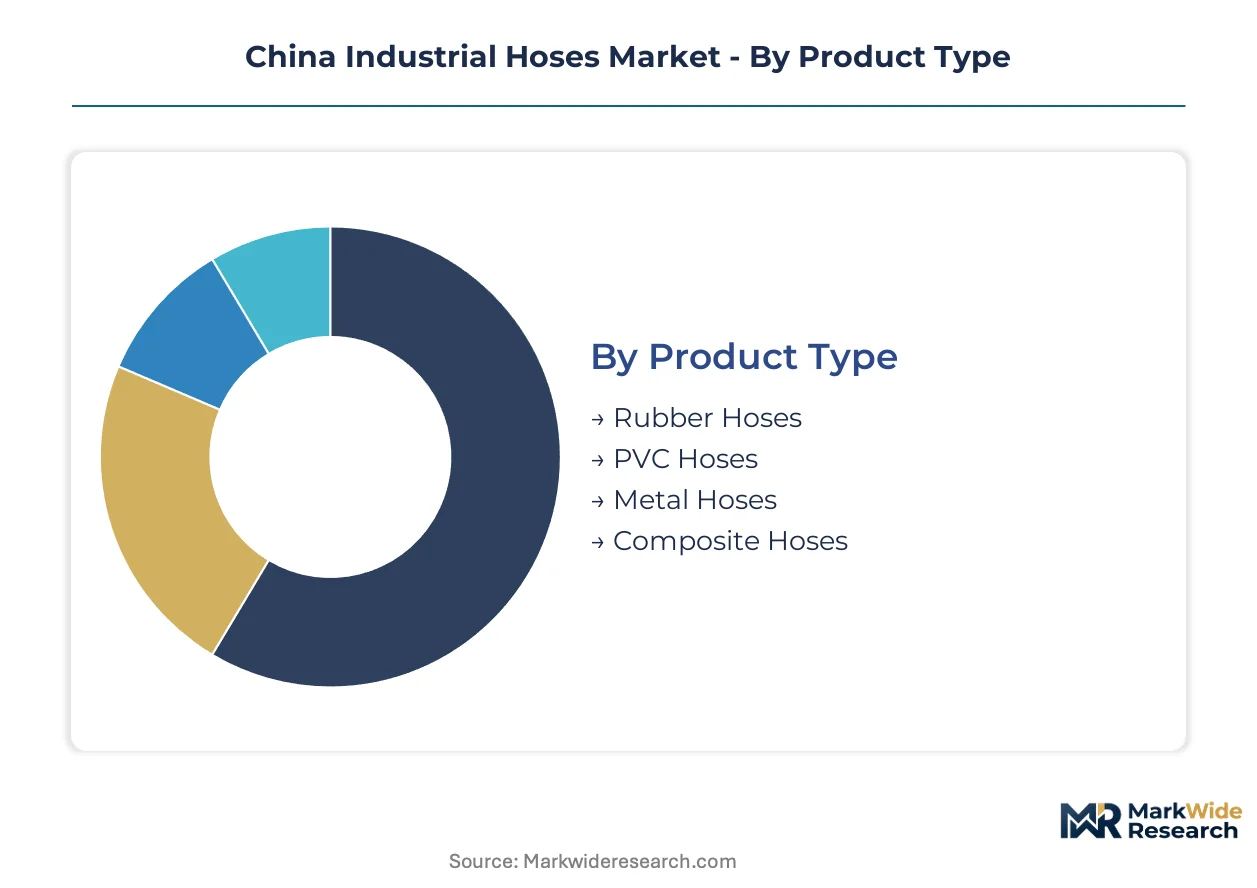
Industrial hose procurement in China fragments across material technologies, operational environments, and supply chain configurations. Understanding these divisions reveals where specification requirements diverge and where standardization opportunities exist for compounders and fabricators.
Product Type:
Material selection determines whether hoses deploy as standalone transfer lines or embed within larger fluid power systems requiring specific pressure, temperature, and chemical resistance profiles.
- Rubber Hoses:Multi-layer constructions of SBR, NBR, or EPDM compounds with textile or wire reinforcement dominate construction and mining procurement in Shandong province. Jiangsu petrochemical clusters specify these for general-purpose fluid transfer under 3,000 psi operating pressure. Rubber hoses lead volumes today; composite hoses are gaining share fastest.
- Metal Hoses:Corrugated stainless steel or bronze assemblies with braided outer jackets withstand temperature extremes from minus 196 to 650 degrees Celsius. LNG transfer terminals along the Bohai Rim specify metal hoses where polymer performance ceilings create safety-critical failure modes.
- PVC Hoses:Lightweight thermoplastic extrusions reinforced with synthetic yarn serve agricultural irrigation and low-pressure industrial washdown applications. Cost sensitivity in rural distribution channels favors PVC over rubber alternatives.
- Composite Hoses:Modular assemblies combining thermoplastic barriers, synthetic fabric layers, and external helix wires reduce weight by 30 percent versus all-rubber equivalents. Shandong refineries adopt standardized connector modules for petroleum transfer operations.
Rubber hoses anchor procurement volumes through established Hebei and Tianjin supply chains; composite architectures are climbing the fastest as dual carbon mandates favor lightweight material efficiency.
Application:
Operational intensity and environmental exposure create divergent specification requirements across China's industrial base.
- Construction:Abrasion-resistant rubber assemblies with crush-proof helix constructions endure concrete pumping and dewatering operations. Urban infrastructure spending in tier-one cities drives replacement cycles for worn hose fleets.
- Agriculture:Flexible PVC and rubber suction hoses handle irrigation, fertilization, and crop protection chemical transfer. Mechanization trends in Henan and Shandong provinces expand hose attachment points per tractor and harvester unit.
- Mining:Heavy-duty wire-braid hydraulic hoses rated to 6,000 psi withstand rock dust, moisture, and mechanical impact in underground and open-pit extraction. Shanxi coal operations specify flame-resistant compounds meeting GB/T mining safety standards.
- Oil & Gas:High-pressure rotary drilling hoses and flexible choke-and-kill lines integrate API certification requirements with MIIT domestic polymer standards. Bohai Rim offshore platforms demand marine-grade corrosion resistance.
Construction commands the largest procurement tonnage; oil and gas applications are expanding most quickly through petrochemical cluster development.
End User:
Buyer sophistication and technical specification authority vary sharply across industrial, infrastructure, and transportation sectors.
- Manufacturing:Chemical processors, metal fabricators, and food producers specify hoses for coolant, pneumatic, and process fluid handling. Dual pharmaceutical-industrial plants in Jiangsu require PTFE-lined assemblies meeting NMPA hygiene protocols.
- Transportation:Rail, trucking, and marine operators procure fuel transfer, brake system, and hydraulic steering hoses under component-level certification requirements. Port modernization along the Yangtze Delta drives marine-grade specialization.
- Utilities:Power generation and water treatment facilities specify high-temperature steam hoses and chemical dosing lines. State-backed infrastructure tenders embed carbon intensity benchmarks influencing material selection.
- Aerospace:Aircraft ground support and maintenance operations require specialized fueling and de-icing hose assemblies with precise electrical conductivity control. Military aviation specifications exceed commercial grade requirements.
Manufacturing end users generate the broadest specification diversity; utilities procurement is tightening fastest around MEE carbon accounting requirements.
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and geographic proximity to manufacturing clusters.
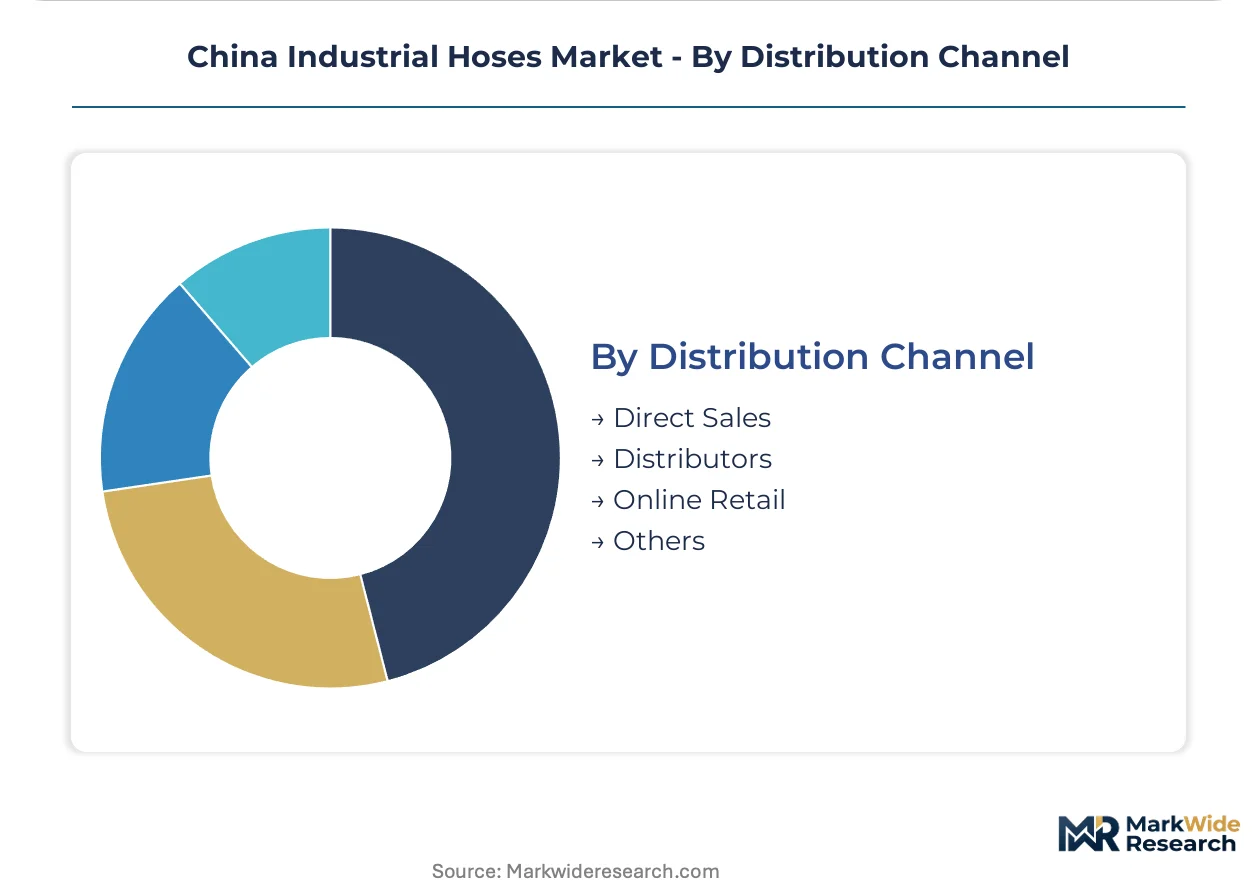
- Direct Sales:Large petrochemical groups and state-owned construction enterprises negotiate multi-year supply agreements with Hebei and Tianjin compounders. Technical collaboration on custom formulations accompanies volume commitments.
- Distributors:Regional industrial supply houses stock standard hose diameters and pressure ratings for immediate availability. Shandong and Jiangsu distribution networks maintain inventory proximity to coastal manufacturing zones.
- Online Retail:E-commerce platforms serve maintenance-repair-operations procurement for small and mid-size fabricators. Price transparency and rapid delivery compete against technical specification verification.
- Others:System integrators and original equipment manufacturers bundle hoses within packaged fluid power solutions. Agricultural machinery producers specify hoses at the design stage for factory installation.
Direct sales capture the highest-value contracts; distributor channels are broadening fastest through provincial industrial supply consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Shandong petrochemical clusters anchor procurement volume for industrial hose assemblies serving fluid power systems across coastal manufacturing zones.
Jiangsu Province
Integrated refining-chemical complexes in Nanjing and Nantong drive specification diversity for high-pressure rubber and PTFE-lined assemblies. MIIT domestic polymer standards compress import dependency for specialty compounds serving dual pharmaceutical-industrial plants. Sinopec facilities in the Yangtze River Delta pilot ten-year total cost of ownership agreements that unbundle maintenance from equipment procurement.
Shandong Province
Coastal refinery expansion in Qingdao and Yantai accelerates demand for marine-grade composite hoses in offshore loading operations. GB/T pressure equipment standards tighten documentation requirements for petroleum transfer assemblies. Standardized connector modules reduce field installation time at Shandong refineries adopting modular hose architectures.
Hebei Province
Integrated compounding facilities in Shijiazhuang and Baoding sustain manufacturing scale for SBR and NBR rubber hoses serving construction and mining sectors. SAMR CCC marking requirements stretch product launch schedules for new hose architectures entering certification cycles. Hebei compounders retool formulations ahead of MIIT domestic high-performance polymer certification deadlines.
Tianjin Municipality
Backward integration into synthetic rubber compounding anchors supply security for high-pressure hose producers serving Bohai Rim oil and gas platforms. MEE dual carbon mandates embed material efficiency requirements in state-backed infrastructure tenders. Tianjin fabricators concentrate formulation expertise for multi-layer polymer systems with precise reinforcement integration.
Guangdong Province
Pearl River Delta manufacturing diversification expands hose procurement for food processing and electronics cooling applications. NMPA hygiene regulations indirectly shape demand for specialized PTFE-lined assemblies in chemical plants serving pharmaceutical feedstock markets. Shenzhen and Dongguan industrial parks specify lightweight thermoplastic hoses for automated production line integration.
China Industrial Hoses Market Vendor Landscape
Backward integration into synthetic rubber compounding dominates the current landscape as compounders seek supply security amid specialty polymer import dependency. The vendor base clusters around three strategic tiers: integrated manufacturers with captive polymer production, specialized fabricators focusing on marine-grade or pharmaceutical-grade assemblies, and regional distributors serving maintenance-repair-operations procurement. Tier-one players consolidate through multi-year supply agreements with state-owned petrochemical groups. Technology licensing and portfolio diversification represent the two dominant competitive moves reshaping positioning.
Among Hebei and Tianjin-based compounders, Hebei Orient Rubber & Plastic Co., Ltd. and Tianjin Pengling Rubber Hose Co., Ltd. exemplify the integrated manufacturing archetype with upstream control over polymer formulation. Qingdao Qingflex Hose Factory occupies a specialist position representing marine-grade fabrication capabilities along the Bohai Rim. These three anchors illustrate how geographic proximity to petrochemical clusters and port infrastructure shapes competitive differentiation in procurement contract access.
| Leading Market Players |
|---|
| Tianjin Pengling Rubber Hose Co., Ltd. |
| Qingdao Qingflex Hose Factory |
| Sinopulse Hose Factory Co., Ltd. |
| Hebei Orient Rubber & Plastic Co., Ltd. |
| Kingdaflex Industrial |
| Qingdao Techoses Industrial Co., Ltd. |
| LUCOHOSE Co., Ltd. |
| Qingdao Everflex Rubber & Plastic Co., Ltd. |
| Shijiazhuang StrongFlex Industrial Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Composite hose modularization is compressing field installation costs while concentrating procurement power among Shandong and Jiangsu petrochemical clusters. This production-method transition simultaneously reduces per-unit labor content and reinforces volume-based pricing leverage for state-backed refining operators.
Pricing Analysis
Input-cost pass-through from SBR and NBR compound volatility shapes margin structures across Hebei and Tianjin rubber hose manufacturers. Three-tier pricing structure across premium API-certified, standard GB-compliant, and economy-grade construction tiers reflects certification investment and volume scale. Pricing pressure stems from synthetic rubber derivative costs tracking crude oil benchmarks. Construction sector buyers exhibit highest price sensitivity; oil and gas operators prioritize certification grade over unit cost.
Supply Chain Analysis
Logistics costs from Hebei compounding centers to Jiangsu petrochemical clusters anchor regional price differentials within domestic supply networks. Manufacturing concentrates in China with specialty fluoropolymer and aramid reinforcement dependencies drawing from Japan and the United States. Single-source vulnerability for high-performance polymer feedstocks creates supply security exposure. Distribution runs through direct sales channels for large petrochemical groups and regional industrial distributors for maintenance-repair-operations procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China industrial hoses market functions as a stable compounder anchored by state-backed petrochemical infrastructure spending across coastal provinces.
For Market Incumbents: To counter import substitution pressure from MIIT domestic polymer standards, deepen backward integration into synthetic rubber compounding and accelerate GB/T certification documentation ahead of SAMR audit cycles. Secure multi-year supply agreements with Sinopec facilities piloting total cost of ownership contracts. For New Entrants and Emerging Players: Embedded sensor integration for predictive maintenance represents a technology-first wedge into high-risk petroleum transfer applications. Target pharmaceutical-industrial crossover demand in Jiangsu dual-use plants. Pursue white-label manufacturing partnerships with established Hebei compounders lacking smart hose capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap fabricators with captive polymer production and underdeveloped aftermarket service revenue. Five-to-ten-year viability hinges on carbon intensity compliance positioning. Monitor MEE dual carbon mandate enforcement tightening as inflection signal for material efficiency premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Rubber Compounding | Hebei and Tianjin manufacturers secure supply security amid specialty polymer import dependency. |
| Smart Hose Sensor Integration | Embedded pressure and temperature monitoring enables predictive maintenance contracts in petroleum transfer. |
| GB/T Certification Acceleration | SAMR marking requirements compress product launch timelines for new hose architectures. |
| Marine-Grade Specialization | Qingdao and Yantai port modernization opens corrosion-resistant assembly supply contracts. |
| Pharmaceutical-Industrial Crossover Positioning | NMPA hygiene regulations create specialized PTFE-lined hose demand in Jiangsu chemical plants. |
Methodological Framework
Coverage spans Jiangsu, Shandong, Hebei, Tianjin, and Guangdong provinces, with primary inputs from each manufacturing cluster. The analysis combines interviews with plant managers at petrochemical facilities, procurement leads at state-owned construction enterprises, distribution channel partners in coastal industrial supply networks, and technical R&D directors at compounding operations. Secondary validation draws from MIIT policy circulars, SAMR certification databases, customs trade records, and Sinopec procurement disclosures. Bottom-up segment sizing triangulates against top-down infrastructure spending projections.
Rate-of-change decomposition separates volume growth from price and mix effects across the projection horizon. The analytical framework models segmentation by material technology, operational application, end-user sophistication, and distribution channel configuration. CAGRs derive from petrochemical capacity expansion schedules, dual carbon mandate implementation trajectories, and GB standards harmonization timelines. Industry-specific inputs include synthetic rubber compound cost indices and state-backed tender award patterns.
The model holds under steady MIIT domestic standard enforcement and continued petrochemical cluster investment; deviation in specialty polymer trade restrictions or LNG terminal deployment delays would shift trajectory. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Gas Fittings and Components Market
Pipes and Tubes
Global Polyolefin Pipes Market
Pipes and Tubes
Agricultural Pipes and Tubes Market
Pipes and Tubes
Piping System and Piping Spools Market
Pipes and Tubes
United States Copper Pipes and Tubes Market
Pipes and Tubes
GCC PVC Pipes Market
Pipes and Tubes
India Process Piping Market
Pipes and Tubes
HPLC Fused Silica Tube Market
Pipes and Tubes
Bahrain PVC Pipes Market
Pipes and Tubes
Compressed Air Pipe Market
Pipes and Tubes
Drum Funnel Market
Pipes and Tubes
Europe Copper Pipes and Tubes Market
Pipes and Tubes
Aluminium Tubes for OPC Drum Market
Pipes and Tubes
Tapping Sleeves Market
Pipes and Tubes
Composite Pipes Market
Pipes and Tubes
Collapsible Metal Tubes Market