
 Water Penetration Tester Market | 2026-2036
Water Penetration Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Water Penetration Tester Market Analytics
Market Context with Strategic Players
China is narrowing its import dependency for precision testing instrumentation through domestic capacity expansion in Jiangsu and Zhejiang provinces. SDL Atlas leverages extensive distributor networks across Asia-Pacific to sustain instrument availability for textile and construction laboratories. FORM+TEST GmbH anchors European demand with German-engineered hydrostatic pressure systems that comply with EN 20811 and ISO 811 protocols. Gester Instruments competes aggressively on automated tester configurations for quality control lines in Bangladesh and Vietnam garment manufacturing.
Technical Definition and Structural Segments
A water penetration tester quantifies a material's resistance to liquid ingress under controlled hydrostatic pressure, typically operating between 0 and 200 kPa with calibrated nozzle spray or immersion cell configurations to simulate rain exposure or standing water conditions. The instrument serves building envelope certification, automotive seal validation, and protective textile compliance by generating reproducible permeability data for ASTM E331, AATCC 127, and ISO 1420 test methods. Automated tester configurations command premium positioning due to programmable pressure ramping and integrated data logging that eliminates operator variability in high-volume laboratories. Portable tester demand is accelerating in field structural assessment applications where on-site building envelope diagnostics replace costly laboratory shipping. Digital tester adoption concentrates in research and development settings where real-time pressure curve visualization supports material formulation decisions.
Regulatory Framework and Forward Trajectory
ASTM International, ISO technical committee 38 on textiles, and the European Committee for Standardization shape product specifications through iterative test method revisions that directly determine instrument calibration requirements and market access eligibility. The U.S. Environmental Protection Agency's stormwater management rules and the EU Green Deal's building renovation targets tighten envelope performance verification, channeling procurement toward testers with documented traceability to accredited standards bodies. Stakeholders must monitor harmonization gaps between regional test protocols that currently force dual instrument configurations for manufacturers serving both North American and European certification streams.
Market Dynamics
Automated testing systems are compressing laboratory staffing requirements while tightening precision tolerances, forcing capital equipment decisions toward programmable configurations that eliminate operator variability in high-volume certification workflows.
Growth Catalysts
- EN 20811 Protocol Harmonization:The European Committee for Standardization's unified hydrostatic pressure testing framework eliminates dual calibration requirements for cross-border building envelope certification, accelerating instrument replacement cycles in Germany and France.
- Textile Quality Control Automation:Bangladesh and Vietnam garment manufacturers are deploying inline water penetration testers to replace batch sampling, reducing defect escape rates in export-bound protective clothing production lines.
- Stormwater Infrastructure Rehabilitation:The U.S. Environmental Protection Agency's municipal separate storm sewer system mandates require documented membrane integrity testing, expanding field-portable tester deployment for culvert and retention basin assessments.
Market Restraints
- Precision Sensor Supply Concentration:German and Japanese piezoelectric pressure transducer manufacturers control critical component supply, exposing tester assemblers to extended lead times and input cost volatility exceeding twelve-month procurement horizons.
- Dual Certification Burden:ASTM E331 and ISO 811 protocol divergence forces manufacturers serving both North American and European markets to maintain separate instrument configurations, inflating inventory carrying costs and technical support complexity.
- Skilled Metrology Technician Scarcity:Field calibration and traceability documentation requirements exceed the supply of accredited personnel in emerging manufacturing clusters, constraining aftermarket service revenue expansion.
Strategic Opportunities
- India Building Code Enforcement:The Bureau of Indian Standards' mandatory envelope performance verification for commercial structures above 15 meters creates first-mover positioning for automated hydrostatic pressure systems in Mumbai and Bangalore construction certification laboratories.
- Cloud-Connected Diagnostics:Convergence of IoT pressure sensors with laboratory information management systems enables remote instrument monitoring and predictive maintenance contracts, shifting revenue from hardware sales to recurring service subscriptions.
- Automotive Battery Enclosure Testing:Electric vehicle thermal runaway protection standards are extending water ingress validation to battery pack housings, opening new application verticals beyond traditional textile and construction end-uses.
Industry Challenges
- Multiprotocol Firmware Complexity:Programming teams must maintain simultaneous compliance with six distinct regional test methods, stretching software development resources and extending validation timelines for new product releases.
- Legacy Analog System Migration:Research laboratories with decades-old manual hydrostatic pressure equipment face capital justification barriers and technician retraining costs when upgrading to automated configurations with integrated data logging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Penetration Tester Market |
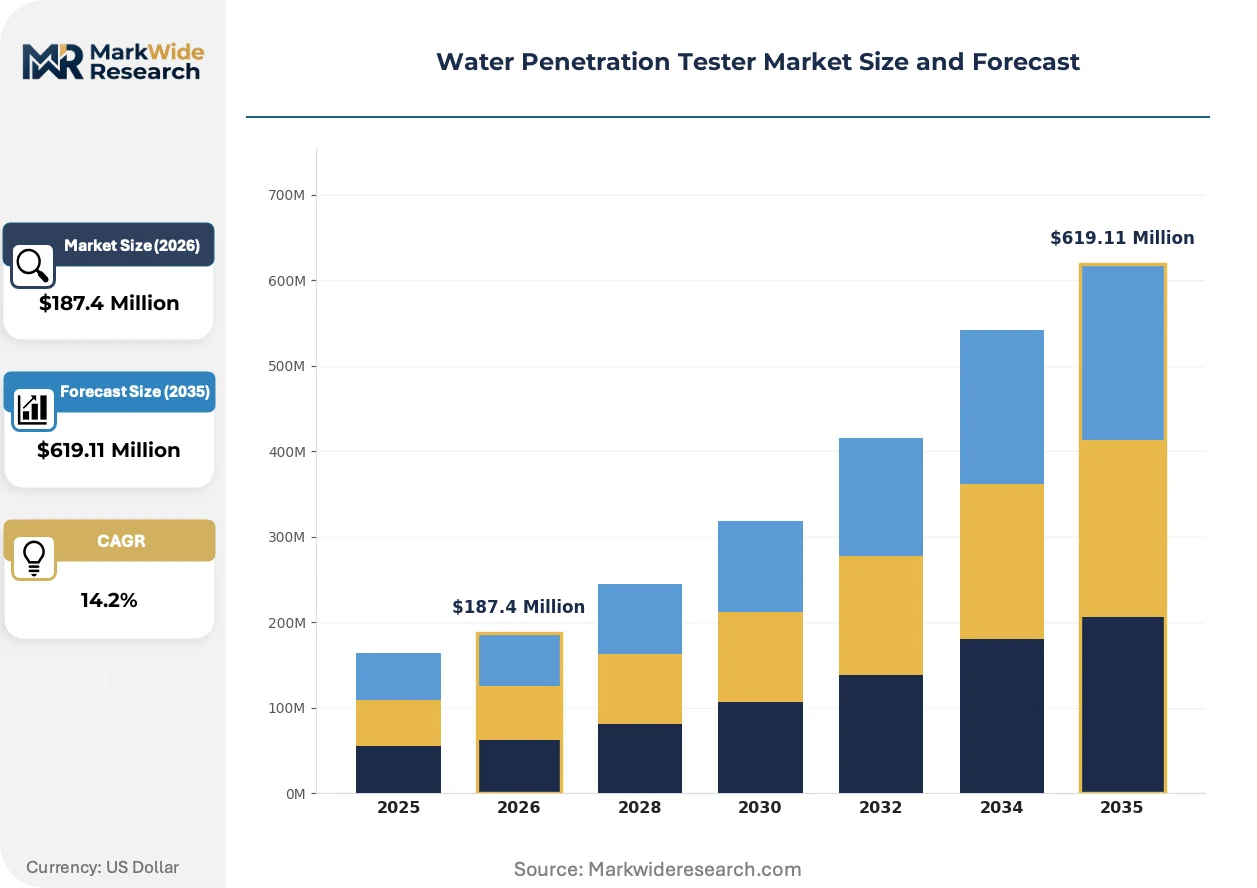
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Tester, Fixed Tester, Automated Tester, Digital Tester End User: Construction, Automotive, Aerospace, Manufacturing Technology: Capillary Action, Hydrostatic Pressure, Vacuum Testing, Ultrasonic Testing Application: Material Testing, Quality Control, Research & Development, Structural Assessment |
| Companies Covered | VWR International, SDL Atlas, Thermalwise, ATI Corporation, Cometech Testing Machines, FORM+TEST GmbH, SATRA Technology Centre, Gester Instruments, Matest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Penetration Tester Market Evolving Landscape
Digital pressure curve visualization and real-time compliance reporting are reconfiguring buyer expectations, compressing the acceptable feature gap between field-portable units and laboratory-grade systems while elevating software capabilities to parity with hardware precision.
MEMS-based pressure sensing arrays are collapsing the cost-performance boundary between research-grade and production-line water penetration testers. Automotive seal validation laboratories in Stuttgart and Detroit are adopting these solid-state configurations for continuous monitoring applications. The technology is collapsing the historical three-tier instrument segmentation by delivering laboratory precision at portable-unit price points.
The EU Green Deal's building renovation targets are mandating envelope performance verification for energy efficiency retrofits, tightening traceability requirements for hydrostatic pressure test documentation. Construction certification bodies in France and the Netherlands are rejecting manual test records lacking digital pressure curve archives. Commercial building assessors are responding by specifying automated testers with integrated audit trails compliant with CSRD disclosure standards.
Equipment-as-a-service contracting is displacing capital purchase models among mid-volume textile quality control operations. Bangladesh and Vietnam garment manufacturers are leasing automated testers with bundled calibration and firmware update services rather than owning depreciating assets. This shift concentrates procurement authority with regional distributor networks that can deliver responsive technical support and spare parts availability within 48-hour windows.
Water Penetration Tester Market Segmentation
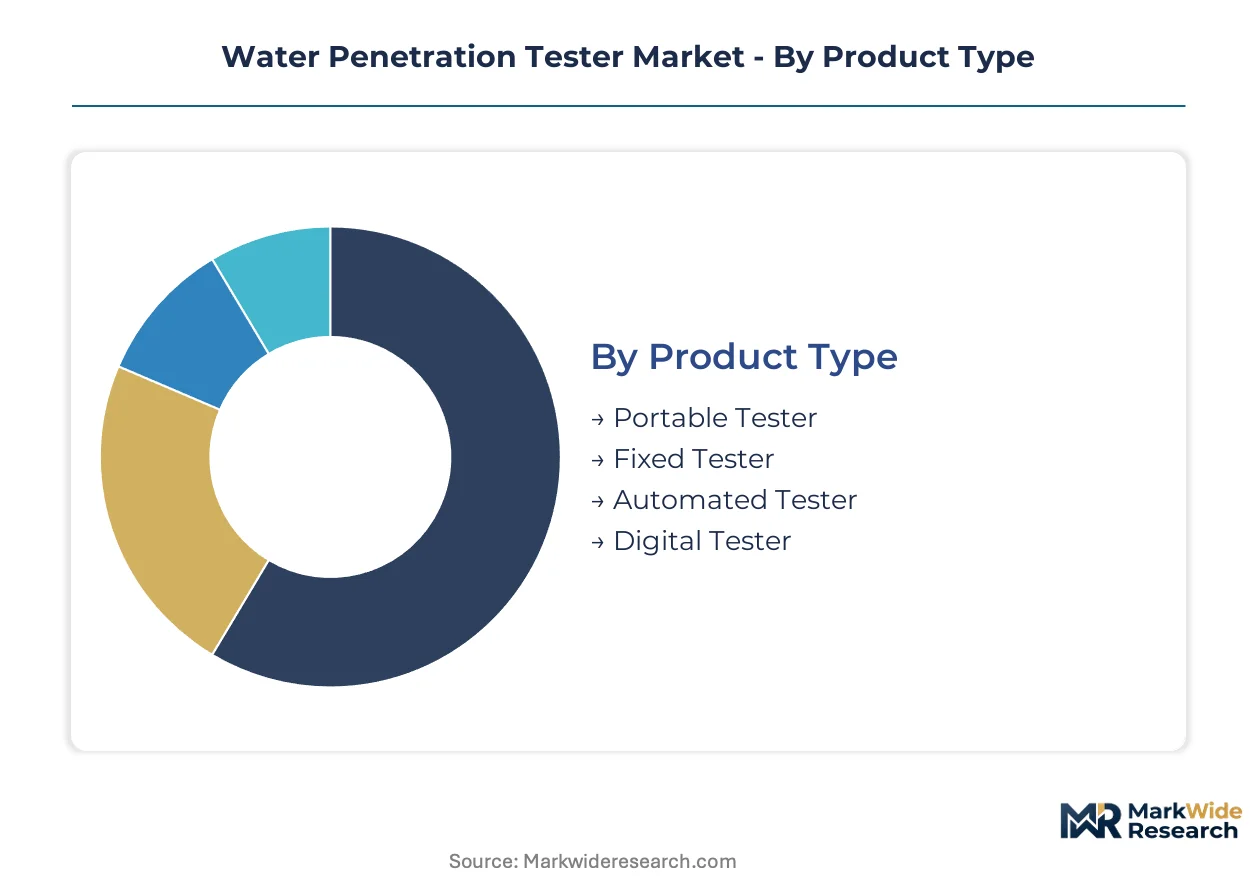
Water penetration tester procurement patterns diverge sharply across operational contexts, with laboratory certification workflows demanding precision automation while field diagnostics prioritize portability. Instrument configuration decisions cascade from end-use requirements, creating distinct competitive arenas where technical specifications and price points rarely overlap.
Product Type:
Use-case spectrum spans handheld field diagnostics through fully automated laboratory lines, with cost-performance trade-offs determining adoption patterns.
- Portable Tester:Battery-powered units with 0-100 kPa range and integrated data logging serve building envelope assessors conducting on-site structural evaluations. Demand concentrates among French and Dutch commercial building certification bodies responding to EU Green Deal renovation documentation requirements.
- Automated Tester:Programmable pressure ramping systems with robotic sample handling eliminate operator variability in high-volume textile quality control laboratories. Bangladesh and Vietnam garment manufacturers deploy these configurations for inline protective clothing testing, reducing defect escape rates in export-bound production.
- Fixed Tester:Permanent laboratory installations with immersion cell configurations serve research institutions requiring extended soak testing protocols.
- Digital Tester:Real-time pressure curve visualization capabilities support material formulation decisions in automotive seal development laboratories.
The dominant share belongs to Automated Tester configurations, while Portable Tester demand is closing the gap fastest.
End User:
Customer type determines calibration protocol requirements and procurement authority structures, with regulatory compliance timelines driving replacement cycles.
- Construction:Building envelope certification laboratories in Germany, France, and the United Kingdom procure hydrostatic pressure systems for EN 20811 compliance verification. The EU Green Deal's building renovation targets tighten traceability requirements, rejecting manual test records lacking digital pressure curve archives.
- Automotive:Seal validation laboratories in Stuttgart and Detroit adopt MEMS-based pressure sensing arrays for continuous monitoring of battery pack housings under emerging thermal runaway protection standards.
- Aerospace:Component testing facilities require vacuum-integrated configurations for altitude-simulated moisture ingress validation.
- Manufacturing:Quality control lines across Jiangsu and Zhejiang provinces deploy inline testing to replace batch sampling in textile and synthetic membrane production.
Construction maintains the largest installed base, though Automotive applications are expanding most quickly.
Technology:
Measurement principle selection hinges on material porosity characteristics and required test duration, with solid-state sensors disrupting traditional mechanical approaches.
- Hydrostatic Pressure:Direct liquid column or pneumatic pressure application against sealed specimen clamps generates quantitative resistance values in kPa. This method dominates building envelope and textile certification workflows governed by EN 20811, ISO 811, and ASTM E331 protocols.
- Ultrasonic Testing:Non-destructive acoustic emission detection identifies micro-leakage paths without specimen destruction, enabling 100% inspection of automotive seals and aerospace components where sampling is economically prohibitive.
- Capillary Action:Wicking-based assessment suits porous geotextile and construction material characterization.
- Vacuum Testing:Pressure differential methods serve sealed enclosure integrity validation in electronics and pharmaceutical packaging.
Hydrostatic Pressure commands the dominant methodology position, while Ultrasonic Testing gains share fastest through automotive battery enclosure applications.
Application:
Workflow stage determines instrumentation sophistication, with research settings demanding programmable flexibility and production lines prioritizing throughput speed.
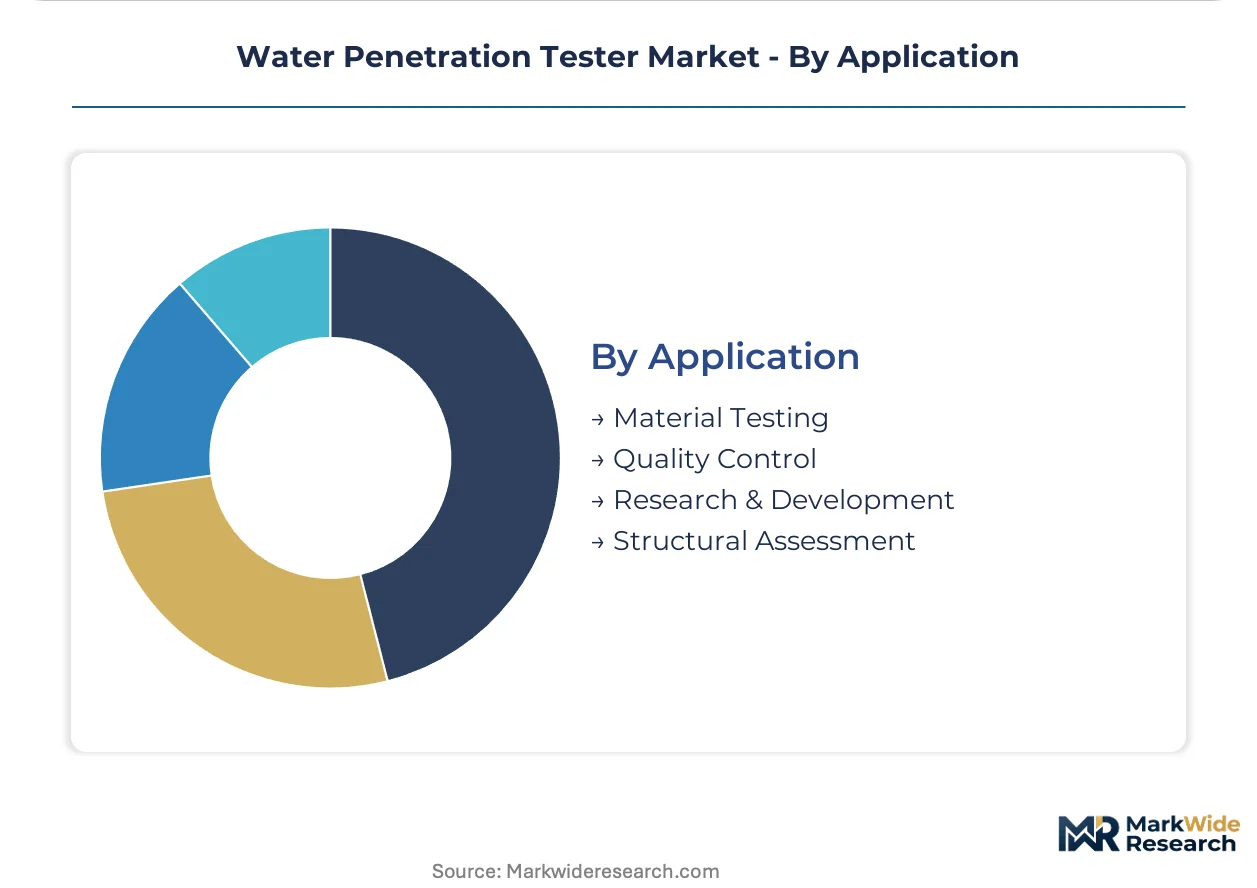
- Quality Control:Inline automated configurations with pass-fail sorting integration serve high-volume manufacturing environments where throughput directly determines unit economics. Bangladesh garment manufacturers lease these systems with bundled calibration services rather than owning depreciating assets.
- Research & Development:Multi-protocol firmware supporting six distinct regional test methods enables formulation scientists to compare material performance across ASTM, ISO, and EN certification streams from a single platform.
- Material Testing:Standardized specimen evaluation for supplier qualification and incoming inspection.
- Structural Assessment:Field-deployable diagnostics for existing building envelope condition evaluation and rehabilitation planning.
Quality Control represents the largest application segment, while Research & Development shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underpins Central European distribution networks for precision testing instrumentation, connecting manufacturing clusters in southern Germany to North Sea export terminals and Black Sea markets.
Germany
Commercial building certification programs in Frankfurt and Munich drive procurement of EN 20811-compliant hydrostatic pressure systems. The EU Green Deal's renovation targets tighten traceability requirements, rejecting manual test records without digital pressure curve archives. Stuttgart automotive laboratories deploy MEMS-based sensing arrays for battery enclosure validation under emerging thermal runaway standards.
China
Domestic capacity expansion in Jiangsu and Zhejiang provinces narrows import dependency for precision testing instrumentation. The country's national standards body accelerates GB standard harmonization with ISO protocols for building envelope materials. Manufacturing quality control lines across Suzhou and Hangzhou deploy inline automated configurations to replace batch sampling in textile production.
United States
EPA municipal separate storm sewer system mandates expand field-portable tester deployment for culvert and retention basin membrane integrity testing. Stormwater infrastructure rehabilitation programs channel procurement toward documented traceability systems. Detroit automotive seal validation laboratories adopt solid-state pressure sensing for continuous monitoring applications.
India
The Bureau of Indian Standards mandates envelope performance verification for commercial structures above 15 meters, creating first-mover positioning in Mumbai and Bangalore certification laboratories. National building code enforcement tightens procurement specifications for automated hydrostatic pressure systems. Construction material testing clusters in Pune and Chennai upgrade from manual to programmable configurations.
France
Commercial building assessors specify automated testers with integrated audit trails compliant with CSRD disclosure standards. The EU Green Deal's renovation documentation requirements concentrate demand in Paris and Lyon certification bodies. Textile quality control operations in the Hauts-de-France region lease equipment-as-a-service contracts with bundled calibration services.
Water Penetration Tester Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in sensor and pressure cell fabrication. The vendor base stratifies across three tiers: multinational laboratory supply conglomerates with established distribution networks; mid-scale European and Asian equipment fabricators with regional certification expertise; and specialized component suppliers concentrated in German and Japanese precision sensor manufacturing. Strategic moves concentrate on firmware multiprotocol expansion to cover ASTM, ISO, and EN test methods simultaneously, and equipment-as-a-service contracting models that shift revenue from hardware sales to recurring calibration subscriptions.
Among German-engineered system providers, FORM+TEST GmbH anchors European demand with hydrostatic pressure configurations. SDL Atlas leverages extensive Asia-Pacific distributor networks to sustain instrument availability. Gester Instruments occupies a position within the automated tester segment for quality control line deployment. These three exemplify distinct competitive archetypes: regional engineering heritage, distribution scale, and manufacturing automation specialization respectively.
| Leading Market Players |
|---|
| VWR International |
| SDL Atlas |
| Thermalwise |
| ATI Corporation |
| Cometech Testing Machines |
| FORM+TEST GmbH |
| SATRA Technology Centre |
| Gester Instruments |
| Matest |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese precision instrumentation manufacturing compresses margins for mid-tier automated testers while German sensor suppliers maintain pricing power through piezoelectric transducer scarcity. Utilization gaps between Jiangsu province fabricators and Stuttgart component specialists force divergent procurement strategies across buyer segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EN 20811-certified laboratory systems from field-portable units and manual configurations. Price differentiation hinges on calibration traceability documentation and bundled firmware update subscriptions. Cost compression in economy tiers intensifies because Bangladesh garment manufacturers prioritize lease-based equipment-as-a-service contracts over capital purchases. Quality control laboratories exhibit lowest price sensitivity due to regulatory compliance mandates, while small construction assessors face acute budget constraints.
Supply Chain Analysis
Contract manufacturing concentration among Suzhou and Hangzhou precision equipment fabricators supplies standard-tier instrument assembly. Component sourcing draws from German piezoelectric pressure transducer specialists and Japanese MEMS sensor foundries. Single-source vulnerability in solid-state pressure sensing arrays threatens production continuity for automotive battery enclosure testers. Distribution runs through regional distributor networks that bundle calibration services with hardware delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of firmware engineers capable of maintaining simultaneous ASTM, ISO, and EN protocol compliance constrains new product release velocity across the vendor base. This capability gap favors incumbents with established programming teams over capital-rich entrants.
For Market Incumbents: Pre-empt MEMS-based sensor disruption by acquiring solid-state pressure transducer technology or securing exclusive supply agreements with Japanese foundries. Defend against equipment-as-a-service entrants by embedding predictive maintenance algorithms that generate recurring calibration subscription revenue. Channel control through 48-hour spare parts availability remains the critical lever for textile quality control accounts.
For New Entrants and Emerging Players: India's building code enforcement for commercial structures above 15 meters offers underpenetrated demand for automated hydrostatic pressure systems in Mumbai and Bangalore certification laboratories. Target CSRD disclosure-compliant audit trail capabilities as the differentiated entry vector, since French and Dutch assessors now reject manual test records. Partner with regional calibration service providers to overcome skilled metrology technician scarcity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors offering cloud-connected diagnostics with laboratory information management system integration. Long-term viability rests on software-defined differentiation rather than hardware precision alone. Acquisition candidates should demonstrate multiprotocol firmware maintenance capabilities and established distributor relationships in Bangladesh or Vietnam garment manufacturing clusters. Monitor EN 20811 harmonization progress across European member states as inflection indicator for instrument replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Multiprotocol Firmware Expansion | Simultaneous ASTM E331, ISO 811, and EN 20811 compliance eliminates dual inventory requirements for cross-border manufacturers. |
| Equipment-as-a-Service Transition | Lease-based contracting with bundled calibration captures Bangladesh garment manufacturer procurement budgets. |
| MEMS Sensor Integration | Solid-state pressure sensing arrays collapse cost-performance boundaries for Stuttgart automotive battery enclosure laboratories. |
| Cloud-Connected Diagnostics | IoT pressure sensor convergence enables predictive maintenance contracts shifting revenue to recurring subscriptions. |
| Regional Distributor Consolidation | Control over 48-hour spare parts availability secures textile quality control accounts in Vietnam manufacturing zones. |
Research Methodology
Cross-validation between primary interviews with laboratory certification managers, aftermarket service technicians, and textile quality control directors anchors the qualitative findings. Secondary validation draws from ASTM International protocol documentation, ISO technical committee 38 publications, European Committee for Standardization harmonization notices, and customs trade data for precision instrumentation imports. Bottom-up instrument shipment analysis triangulates against top-down construction certification spending estimates.
Calibration against historical replacement cycles in German commercial building certification programs refines the analytical framework across the projection horizon. Segmentation dimensions include product configuration tier, end-use industry vertical, measurement technology principle, and application workflow stage. CAGRs derive from regression analysis of procurement intensity against regulatory compliance timeline acceleration, incorporating EN 20811 adoption curves and EPA stormwater infrastructure rehabilitation funding trajectories.
Practitioners should monitor piezoelectric transducer supply lead times and firmware validation timeline extensions for early signals of forecast deviation. Quarterly review of harmonization gaps between ASTM and ISO protocols is advised to detect inflection in dual certification burden severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Material Testing Market
Testing Equipment
Chemical Analyzer Market
Testing Equipment
Chemical Detection Equipment Market
Testing Equipment
Pellistor Bead Chemical Sensor Market
Testing Equipment
Paint Tester Market
Testing Equipment
Global Film Thickness Measurement Market
Testing Equipment
Chromatography Market
Testing Equipment
Laboratory Ware Market
Testing Equipment
In Vitro Toxicity Testing Market
Testing Equipment
Bitumen and Asphalt Testing Services Market
Testing Equipment
Ambient Temperature Gel Permeation Chromatography Market
Testing Equipment
Chloride Reagents Kits Market
Testing Equipment
Americas Testing, Inspection and Certification (TIC) Market
Testing Equipment
Benchtop Density Meter for Solids Market
Testing Equipment
Materials Testing Equipment Market
Testing Equipment
Wood Moisture Tester Market