
 Metallic Rope Cords Market | 2026-2036
Metallic Rope Cords Market Size, Share, and Industry Trends Forecast 2026-2036
Metallic Rope Cords Market Foresight
REACH compliance is decoupling low-cost suppliers from European project tenders by mandating full material disclosure and restricted substance thresholds for imported metallic rope cords. WireCo WorldGroup leverages its vertically integrated wire-drawing capacity across North American and European mills to sustain pricing flexibility on complex multi-strand constructions. NV Bekaert SA anchors its position through captive steel cord metallurgy expertise that extends into tire reinforcement and offshore mooring applications. Tokyo Rope Mfg. Co., Ltd. dominates specialty plastic-coated rope segments for Japanese bridge cable projects where fatigue resistance specifications exceed international norms.
Metallic rope cords are multi-strand wire assemblies manufactured from cold-drawn carbon steel, stainless steel, or non-ferrous alloys through processes including rotary stranding and closing, with diameters typically ranging from 1 mm to over 100 mm and breaking loads calibrated to ISO 2408 or EN 12385 standards. These constructions transmit tensile forces in lifting, pulling, and suspension systems across heavy infrastructure and transport equipment. Stainless steel rope cords command premium positioning in marine and architectural applications where chloride corrosion resistance determines replacement cycles, while carbon steel variants with galvanized or zinc-aluminum coatings occupy volume-driven construction and mining segments. Aerospace-grade titanium-nickel rope assemblies represent a concentrated margin pool where NADCAP accreditation limits qualified supplier counts.
FDA oversight of material contact surfaces in food-processing equipment shapes stainless steel grade selection for commercial end users, while OSHA hoist and crane regulations in the United States mandate documented inspection intervals that sustain aftermarket replacement demand. ECHA substance restriction proposals under REACH revision procedures threaten conventional lubricant formulations used during rope manufacturing, forcing reformulation investments across European supply chains. Buyers must monitor divergence between regional certification regimes as the EU AI Act and emerging US NIST frameworks begin embedding traceability requirements into critical infrastructure procurement protocols.
Market Dynamics
REACH substance disclosure mandates are fragmenting supplier access to European offshore wind tenders, forcing procurement officers to requalify entire vendor rosters against full material traceability requirements that low-cost Asian manufacturers cannot satisfy without metallurgical infrastructure investments.
Growth Catalysts
- Offshore wind mooring specifications:North Sea developers are specifying galvanized multi-strand assemblies for floating turbine platforms, with Hamburg port authorities accelerating crane rope replacement schedules to match vessel upsizing trends.
- MEE enforcement of GB standards:China's Ministry of Ecology and Environment is tightening factory audits for lifting equipment exports, pushing domestic manufacturers toward ISO 2408 certification to retain European market access.
- Stainless steel grade diversification:Food processing equipment builders are specifying 316L rope cords for FDA-compliant contact surfaces, creating specification pull-through from commercial kitchen OEMs into institutional procurement frameworks.
Market Restraints
- Zinc-aluminum coating input volatility:Galvanized carbon steel rope production faces margin compression from alloyed zinc price swings tied to smelter capacity constraints in concentrated supply geographies.
- Wire-drawing concentration:Captive steel cord metallurgy capabilities cluster among integrated European and North American producers, limiting independent rope assemblers' backward integration options.
- Synthetic fiber substitution:High-performance aramid and UHMWPE cables are displacing metallic ropes in select crane applications where weight reduction outweighs abrasion resistance requirements.
Strategic Opportunities
- Underpenetrated Japanese bridge cable specifications:Fatigue-resistant plastic-coated rope designs meeting JIS standards present technology licensing potential for European manufacturers seeking premium positioning in seismic engineering markets.
- EU AI Act traceability mandates:Critical infrastructure procurement protocols are embedding digital material passports, rewarding early movers with compliant supply chain documentation systems.
- Aerospace-grade titanium-nickel qualification:NADCAP accreditation scarcity limits qualified supplier counts, creating margin pools for metallurgical specialists able to satisfy FAA documentation requirements.
Industry Challenges
- Multi-strand inspection technician scarcity:Magnetic rope testing certification programs have not scaled to match fleet expansion in offshore wind maintenance operations, constraining service revenue capture.
- REACH lubricant reformulation timelines:ECHA substance restriction proposals threaten conventional drawing compounds, forcing European manufacturers to validate alternative chemistries without production interruption.
- Legacy crane fleet documentation gaps:OSHA-mandated inspection intervals require historical load records that pre-digital installations often lack, complicating replacement specification matching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metallic Rope Cords Market |
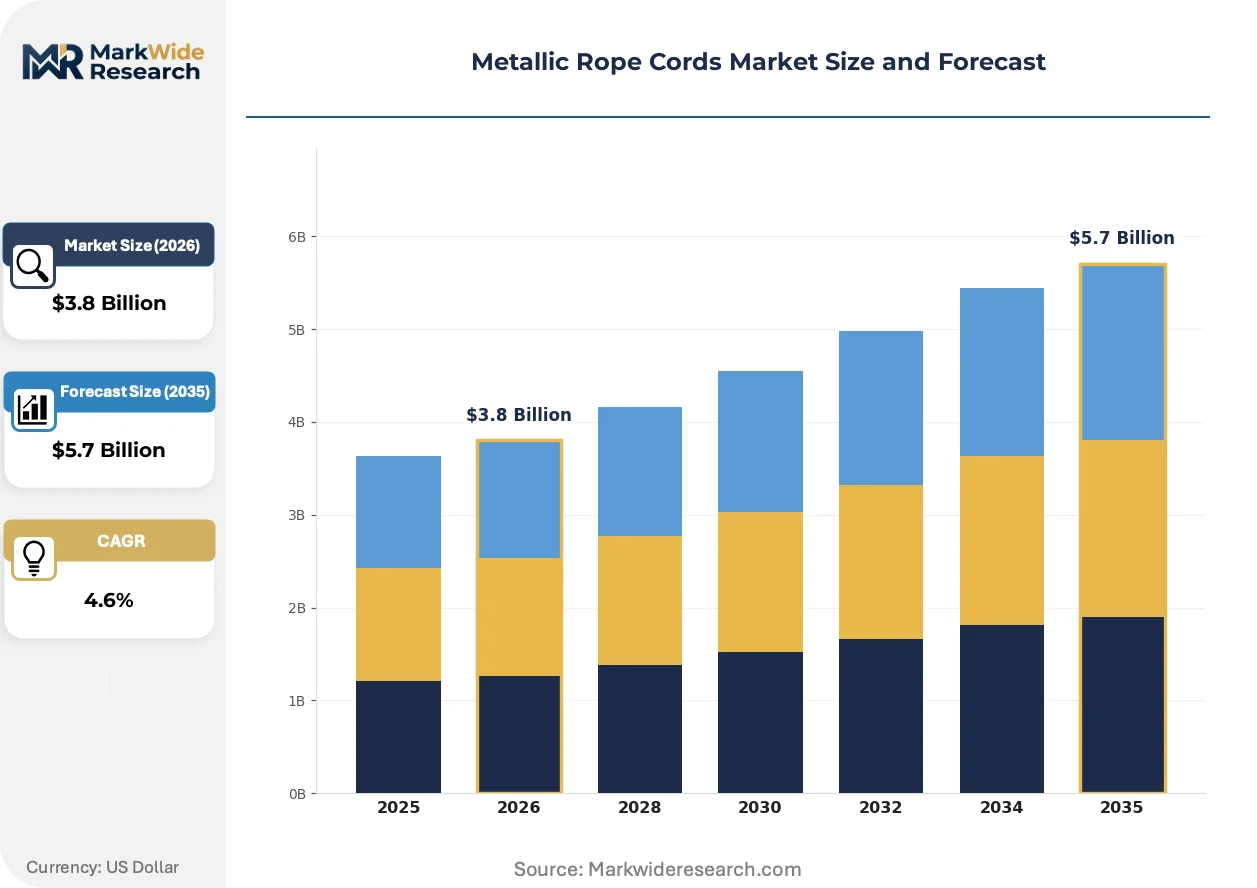
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Brass, Copper, Aluminum Application: Construction, Marine, Aerospace, Manufacturing End User: Industrial, Commercial, Residential, Automotive Packaging Type: Spools, Coils, Bundles, Hanks |
| Companies Covered | WireCo WorldGroup, NV Bekaert SA, Usha Martin Ltd., Teufelberger Holding AG, Kiswire Ltd., Bridon-Bekaert The Ropes Group, Prysmian Group, Tokyo Rope Mfg. Co., Ltd., Loos & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metallic Rope Cords Market Shifts & Advancements
Digital thread technologies and automated quality assurance systems are compressing the gap between raw wire production and certified rope assembly, collapsing traditional multi-stage inspection bottlenecks that previously governed delivery timelines.
Rotary stranding with real-time tension monitoring is automating the alignment of individual wire lays during multi-strand closing, ensuring ISO 2408 breaking load consistency across batch runs. Offshore wind turbine manufacturers in the North Sea are specifying these digitally certified assemblies for mooring systems where fatigue failure carries catastrophic replacement costs. The technology is automating away the manual gauging stations that previously required skilled operator intervention at each production stage.
REACH revision procedures under ECHA oversight are restricting conventional petroleum-based lubricants used in cold-drawing operations, compelling reformulation investments across European supply chains. Manufacturers must validate bio-based alternatives against EN 12385 corrosion resistance benchmarks without extending production cycles. Stainless steel rope cord segments face the steepest compliance costs given their premium positioning and documented material traceability requirements.
Specification-driven procurement is consolidating crane rope purchasing around certified maintenance contractors rather than direct mill relationships, compressing distributor margins while expanding aftermarket service attach rates. Port modernization programs in Germany are bundling rope replacement with inspection contracts that shift inventory risk to integrators. This pattern is most visible in heavy-lift infrastructure where unplanned downtime costs exceed material premiums by orders of magnitude.
Metallic Rope Cords Market Segmentation
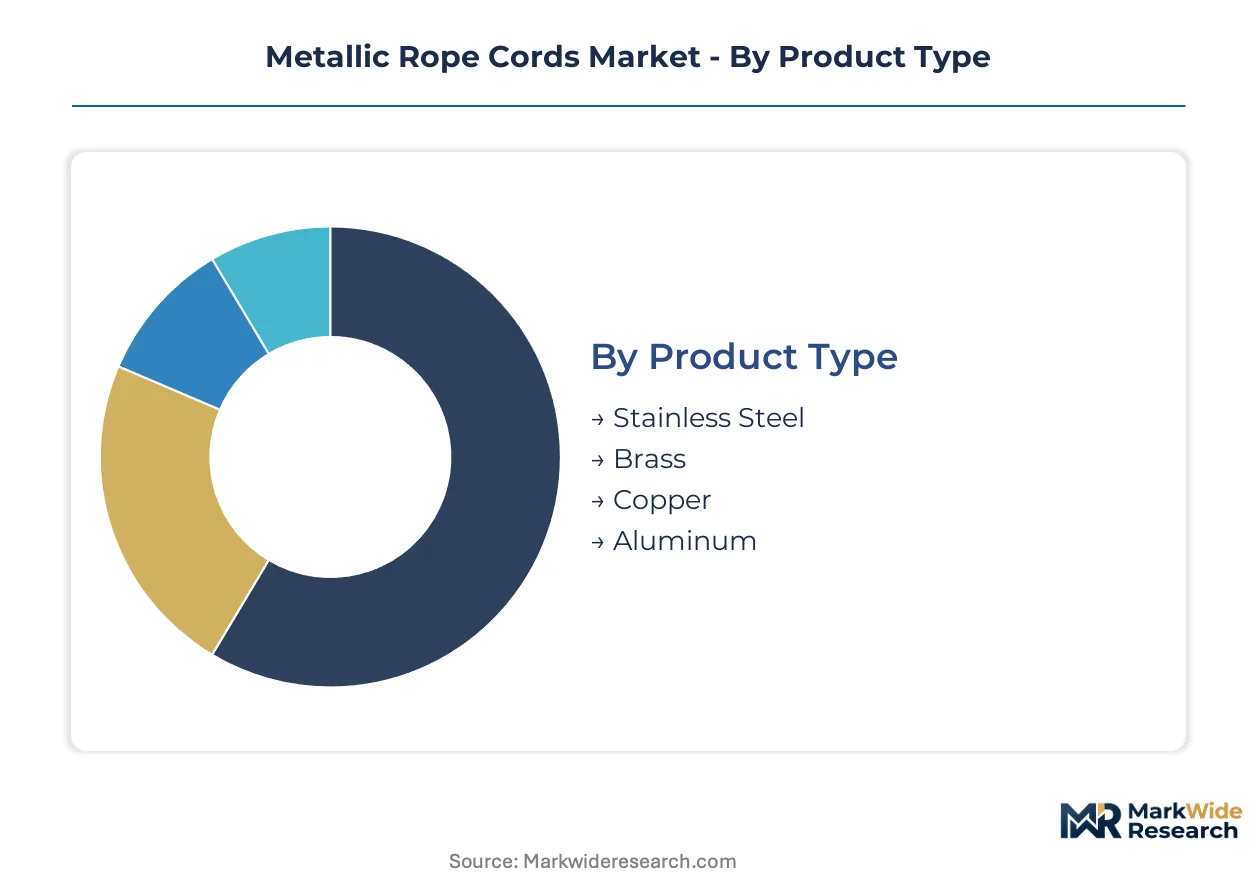
Segmentation in metallic rope cords reveals how specification requirements fragment procurement patterns across corrosion-critical marine environments, load-bearing infrastructure, and precision aerospace applications. Buyers prioritize material-grade certification, fatigue-resistance documentation, and traceability compliance that vary sharply by end-use liability exposure.
Product Type:
Material selection separates buyers by corrosion environment severity and load-cycle intensity, with alloy chemistry directly determining replacement intervals and total cost of ownership calculations.
- Stainless Steel:Cold-drawn austenitic grades deliver chloride corrosion resistance for North Sea offshore mooring systems where galvanized alternatives fail within months. German port authorities in Hamburg and Bremen specify 316L assemblies for heavy-lift crane ropes exposed to salt spray, with MEE enforcement of GB standards now requiring full metallurgical documentation for Chinese-sourced alternatives.
- Brass:Copper-zinc alloys provide non-sparking characteristics for explosive atmosphere applications in oil and gas extraction platforms, though tensile strength limitations restrict deployment to static grounding and instrumentation tethering rather than primary load bearing.
- Copper:High-conductivity rope constructions serve electrical grounding grids and lightning protection systems where low resistance paths override mechanical strength requirements.
- Aluminum:Lightweight stranded assemblies reduce dead load in architectural tension structures and theatrical rigging where human-rated safety factors demand frequent inspection cycles.
Stainless steel leads volumes today; aluminum is gaining share fastest in weight-sensitive architectural specifications.
Application:
End-use environments dictate certification complexity, with regulatory exposure ranging from voluntary industry standards to federally mandated inspection protocols that reshape supplier qualification requirements.
- Construction:Galvanized multi-strand ropes dominate tower crane hoisting and concrete pumping booms where abrasion resistance outweighs corrosion concerns on temporary installations. OSHA-mandated inspection intervals sustain replacement demand across aging fleet infrastructure in the United States.
- Marine:Stainless steel and plastic-coated specialty constructions anchor floating offshore wind platforms in the North Sea, with fatigue-resistant designs meeting JIS standards for Japanese bridge cable projects where seismic loading exceeds international norms.
- Aerospace:Titanium-nickel rope assemblies represent concentrated margin pools where NADCAP accreditation limits qualified supplier counts and FAA documentation requirements extend procurement timelines.
- Manufacturing:Food-processing equipment builders specify FDA-compliant 316L contact surfaces, creating specification pull-through from commercial kitchen OEMs into institutional procurement frameworks.
Construction absorbs the highest absolute volumes; marine applications show the steepest specification upgrade trajectory.
End User:
Procurement sophistication varies by organizational scale, with industrial buyers demanding full material traceability while residential and commercial segments prioritize availability and standardized breaking load ratings.
- Industrial:Integrated maintenance departments negotiate multi-year supply agreements bundling rope replacement with magnetic testing certification, compressing distributor margins while expanding aftermarket service attach rates.
- Commercial:Food service and hospitality operators respond to FDA oversight of material contact surfaces by upgrading to 316L grades, though price sensitivity limits penetration beyond institutional kitchen OEM specifications.
- Residential:Hardware store distribution favors pre-cut hanks and small-diameter spools for architectural railing and hobbyist applications where ISO 2408 certification carries limited buyer recognition.
- Automotive:Control cable manufacturers specify precision-drawn strands for throttle, brake, and clutch linkages where fatigue resistance determines warranty exposure.
Industrial buyers command the deepest specification expertise; commercial segment procurement is formalizing fastest around regulatory compliance mandates.
Packaging Type:
Inventory handling economics and installation labor requirements shape format selection, with large-scale infrastructure projects favoring bulk delivery while maintenance operations prioritize ready-to-deploy configurations.
- Spools:Precision-wound delivery enables automated deployment on multi-strand closing equipment during rope assembly manufacturing, with flange dimensions standardized to ISO 4344 for crane drum compatibility.
- Coils:Bulk shipping format minimizes freight cost per meter for construction site delivery of galvanized carbon steel ropes where on-site reeving handles final length adjustment.
- Bundles:Pre-cut lengths with termination fittings attached serve offshore wind maintenance contractors requiring rapid turnaround on turbine mooring replacements.
- Hanks:Hand-tied coils target retail and small-contractor distribution where immediate availability outweighs per-meter cost optimization.
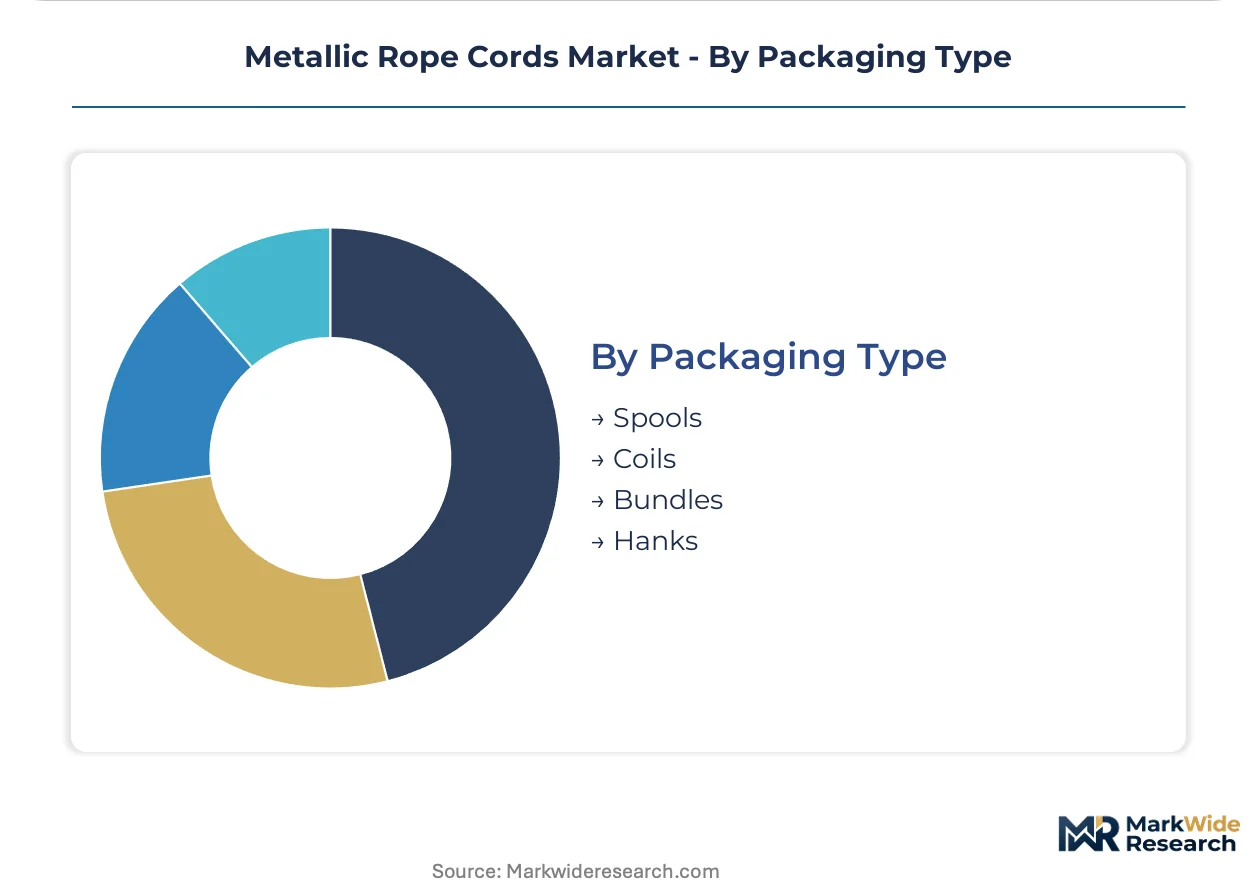
Spools dominate OEM and industrial procurement; bundles are expanding fastest in offshore wind service logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled wire-drawing technicians and metallurgical engineers concentrate in Germany, Japan, and the United States, anchoring high-specification production capacity that Asian manufacturers struggle to replicate without decade-long workforce development cycles.
Germany
Hamburg and Bremen port modernization programs drive heavy-duty crane rope replacement demand. REACH substance disclosure mandates force procurement officers to requalify vendor rosters against full material traceability requirements. The Ruhr industrial corridor hosts integrated steel cord metallurgy facilities serving offshore wind mooring specifications.
United States
OSHA-mandated inspection intervals sustain aftermarket replacement demand across aging crane fleet infrastructure. FDA oversight of material contact surfaces shapes stainless steel grade selection for food-processing equipment builders. Gulf Coast offshore energy operations specify corrosion-resistant assemblies for platform mooring systems.
China
MEE enforcement of GB standards tightens factory audits for lifting equipment exports bound for European markets. Yangtze River Delta manufacturing hubs face pressure to achieve ISO 2408 certification to retain market access. Domestic infrastructure spending absorbs volume production of galvanized carbon steel constructions.
Japan
Tokyo Rope Mfg. anchors specialty plastic-coated rope segments for domestic bridge cable projects where fatigue resistance specifications exceed international norms. METI industrial standards shape procurement frameworks for seismic engineering applications. Kansai region fabricators supply precision-drawn strands for automotive control cable manufacturers.
South Korea
Kiswire Ltd. exemplifies captive steel cord capabilities extending into tire reinforcement and industrial rope segments. Busan-Ulsan shipbuilding clusters demand marine-grade stainless steel assemblies for vessel mooring systems. National industrial policy supports metallurgical R&D investments targeting aerospace qualification pathways.
Metallic Rope Cords Market Competitive Landscape
The competitive structure tilts toward vertically integrated specialists with captive wire-drawing capacity. Three tiers separate premium-grade stainless steel producers from volume-driven galvanized carbon steel assemblers and regional maintenance contractors. Strategic moves concentrate on backward integration into steel cord metallurgy and digital material passport compliance systems for EU AI Act readiness.
Among European-anchored conglomerates, NV Bekaert SA and Bridon-Bekaert The Ropes Group occupy positions defined by captive steel cord metallurgy expertise. WireCo WorldGroup represents North American vertically integrated capacity across wire-drawing and multi-strand closing operations. Tokyo Rope Mfg. Co., Ltd. exemplifies the Japanese specialist archetype dominating fatigue-resistant plastic-coated segments for domestic infrastructure specifications.
| Leading Market Players |
|---|
| WireCo WorldGroup |
| NV Bekaert SA |
| Usha Martin Ltd. |
| Teufelberger Holding AG |
| Kiswire Ltd. |
| Bridon-Bekaert The Ropes Group |
| Prysmian Group |
| Tokyo Rope Mfg. Co., Ltd. |
| Loos & Co., Inc. |
| Others |
Supply & Pricing Matrix
Alloyed zinc input costs cascade through galvanized carbon steel rope tiers, compressing margins for independent assemblers lacking captive steel cord metallurgy while vertically integrated European and North American producers preserve pricing flexibility through in-house wire-drawing capacity.
Pricing Analysis
Bundled inspection-and-replacement contracts now command premium positioning over unbundled material-only transactions, with three-tier pricing structure across premium, standard, and economy levels separating NADCAP-accredited aerospace assemblies from ISO 2408-certified industrial grades and commodity construction spools. Price differentiation rests on certification tier and after-sales service attach rates. Cost compression in galvanized carbon steel tiers is intensifying because zinc-aluminum coating input volatility strains smelter-dependent supply chains. Commercial food-processing equipment builders show highest price sensitivity due to 316L grade premiums, while offshore wind developers demonstrate lowest sensitivity given catastrophic failure costs.
Supply Chain Analysis
Skilled wire-drawing technician scarcity in Germany, Japan, and the United States constrains capacity expansion for high-specification stainless steel and titanium-nickel constructions, while Yangtze River Delta manufacturing hubs absorb volume production of galvanized carbon steel ropes. Raw material dependencies draw from alloyed zinc feedstock, cold-drawn carbon steel rod, and austenitic stainless steel billet. Single-source vulnerability concentrates in European steel cord metallurgy facilities serving REACH-compliant documentation requirements. Distribution runs through certified maintenance contractors bundling rope replacement with magnetic testing certification rather than direct mill relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance costs in Europe run 15-25% above Chinese manufacturing outlays, creating geographic-arbitrage potential for producers achieving ISO 2408 certification with full material traceability documentation.
For Market Incumbents: Lock in backward integration into steel cord metallurgy and captive wire-drawing capacity to defend against synthetic fiber substitution in weight-sensitive crane applications. Prioritize NADCAP accreditation investments for aerospace-grade titanium-nickel segments where qualified supplier scarcity sustains margin pools. Expand digital material passport systems to capture EU AI Act procurement protocol advantages before compliance deadlines tighten. For New Entrants and Emerging Players: E-commerce platforms targeting maintenance contractors offer the lowest customer acquisition cost route into specification-driven procurement frameworks. Target underpenetrated Japanese bridge cable segments where fatigue-resistant plastic-coated designs meeting JIS standards command technology licensing premiums. Lead with rapid-turnaround bundle configurations for offshore wind service logistics where inventory risk shifting creates integrator opportunity. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH lubricant reformulation timelines force European manufacturers to validate alternative chemistries without production interruption. Long-term viability favors metallurgical specialists with demonstrated FAA documentation capabilities and captive supply of aerospace-grade alloys. Watch magnetic rope testing certification program scaling as the inflection signal for aftermarket service revenue capture potential.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Cord Metallurgy | Captive wire-drawing capacity preserves pricing flexibility against zinc input volatility. |
| NADCAP Accreditation Investment | FAA documentation requirements limit qualified supplier counts in titanium-nickel aerospace segments. |
| Digital Material Passport Deployment | EU AI Act traceability mandates reward early movers with compliant supply chain documentation. |
| Bio-based Lubricant Reformulation | ECHA substance restrictions threaten conventional drawing compounds across European mills. |
| Bundle Configuration for Offshore Wind | Pre-cut lengths with termination fittings attached accelerate turbine mooring replacement turnaround. |
Research Methodology
Multiple input streams — primary interviews with maintenance directors and plant engineers, regulatory filings from ECHA and OSHA, customs data on alloyed zinc trade flows, and SEC disclosures from integrated steel producers — were reconciled through bottom-up and top-down triangulation. Stakeholder roles spanned OEM procurement teams at crane manufacturers, aftermarket service heads at port authorities, metallurgical R&D directors, and offshore wind project developers. Secondary sources included EN 12385 and ISO 2408 certification databases, REACH substance restriction proposals, and Hamburg and Bremen port modernization procurement records.
Historical volume trajectories were cross-referenced against panel input from industry participants to construct the analytical framework across the analysis window. Segmentation dimensions modeled encompassed material grade tier, end-use application, corrosion environment severity, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating offshore wind installation schedules, port infrastructure replacement cycles, and MEE enforcement intensity on Chinese export certification.
The model assumes a particular technology adoption path; alternative pathways for synthetic fiber substitution in crane applications would alter the outlook. Forecasts reflect assumptions about REACH lubricant reformulation timelines, magnetic testing technician training program scaling, and sustained North Sea offshore wind procurement. Material deviation in zinc smelter capacity constraints or ECHA substance restriction finalization dates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Iron and Steel Market
Metals
Cobalt Market
Metals
Metal Powder Market
Metals
Metallurgical Coal Market
Metals
Stainless Steel 400 Series Market
Metals
Steel Casting Market
Metals
Global Copper Sputtering Target Market
Metals
Europe Welding Consumables Market
Metals
Metal Casting Market
Metals
Clutch Spring Wires Market
Metals
Steel Salvage Drums Market
Metals
Asia-Pacific Metal Finishing Market
Metals
Armour Steel Plate Market
Metals
Electrodeposited Copper Foil Market
Metals
High Purity Aluminium Market
Metals
High Carbon Bearing Steel Market