
 Cryogenic Pipes Market | 2026-2036
Cryogenic Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic Pipes Market Analytics
Market Context
German vacuum insulation specialists is decoupling from commodity stainless steel piping as cryogenic projects demand higher thermal efficiency. Chart Industries dominates large-scale LNG distribution systems through backward integration into brazed aluminum heat exchangers. Parker Hannifin Corporation leverages its motion and control portfolio to anchor cryogenic valve-and-pipe assemblies for aerospace test facilities. Linde sustains project engineering capabilities that bundle cryogenic pipe fabrication with on-site gas production contracts.
Technical Definition and Segment Structure
Cryogenic pipes are engineered transfer systems designed to convey fluids below minus 150 degrees Celsius, typically constructed with vacuum-insulated double-wall configurations using stainless steel or aluminum alloys to minimize heat ingress and thermal contraction stress. Their primary purpose is to maintain fluid integrity across liquefied natural gas, liquid nitrogen, and liquid hydrogen applications where boil-off losses directly erode economic viability. Stainless steel materials occupy the largest share of installed base due to weldability and fracture toughness at cryogenic temperatures, while alloy segments command premium positioning in hydrogen service where embrittlement resistance proves critical. Straight pipes generate the highest unit volumes, though elbow and tee configurations capture disproportionate margin pools in modular skid builds where field welding carries higher failure risk.
Regulatory Framework and Outlook
ASME B31.3 process piping codes, ISO 21009 cryogenic vessel standards, and the EU F-Gas Regulation collectively dictate insulation performance thresholds and leak-tightness certification requirements for cross-border equipment deployment. The US DOT PHMSA and China's SAMR enforce parallel but non-harmonized pressure equipment approval pathways that complicate supplier qualification for multinational energy projects. Stakeholders must monitor evolving hydrogen-specific codes under development at ISO and national bodies, as these will redefine material specifications and testing protocols for next-generation cryogenic infrastructure.
Market Dynamics
The transition from conventional LNG infrastructure to liquid hydrogen distribution networks is compressing thermal performance requirements and forcing material specification upgrades across cryogenic pipe procurement cycles.
Growth Catalysts
- Liquefaction Train Expansion:LNG terminal operators in the United States, Qatar, and China are commissioning larger liquefaction trains that require vacuum-jacketed piping networks with higher throughput capacity and lower boil-off rates.
- EU F-Gas Regulation:Tightening insulation performance mandates under the EU F-Gas Regulation are accelerating replacement cycles for older single-wall systems in European industrial gas distribution.
- Hydrogen Embrittlement Research:Advances in nickel-alloy metallurgy are enabling cryogenic pipe deployment in liquid hydrogen service where traditional stainless steel faces fracture toughness limitations.
Market Restraints
- Nickel Price Volatility:Specialized nickel alloys for hydrogen-resistant cryogenic piping face input cost swings tied to Indonesian and Russian supply concentration.
- ASME B31.3 Compliance Burden:Non-harmonized pressure equipment approval pathways between US DOT PHMSA and China's SAMR create duplicate certification costs for multinational projects.
- Modular Skid Substitution:Pre-fabricated modular transfer systems reduce field welding requirements and compress demand for traditional elbow and tee configurations in greenfield builds.
Strategic Opportunities
- India Industrial Gas Infrastructure:Underpenetrated cryogenic distribution networks in pharmaceutical and food processing clusters present first-mover positioning for vacuum-insulated system suppliers.
- ISO Hydrogen Standards Development:Evolving cryogenic vessel and piping codes under ISO working groups will redefine material specifications and testing protocols for next-generation infrastructure.
- Digital Twin Integration:Convergence of IoT sensor networks with predictive thermal modeling enables outcome-based service contracts for boil-off monitoring and maintenance scheduling.
Industry Challenges
- Vacuum Maintenance Technician Scarcity:Specialized skills for vacuum jacket integrity testing and repair are concentrated among aging workforce cohorts in German and Japanese fabrication centers.
- Multi-Standard Certification Timelines:Parallel ASME, ISO 21009, and national pressure equipment approvals extend project qualification cycles by 8-14 months for cross-border deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic Pipes Market |
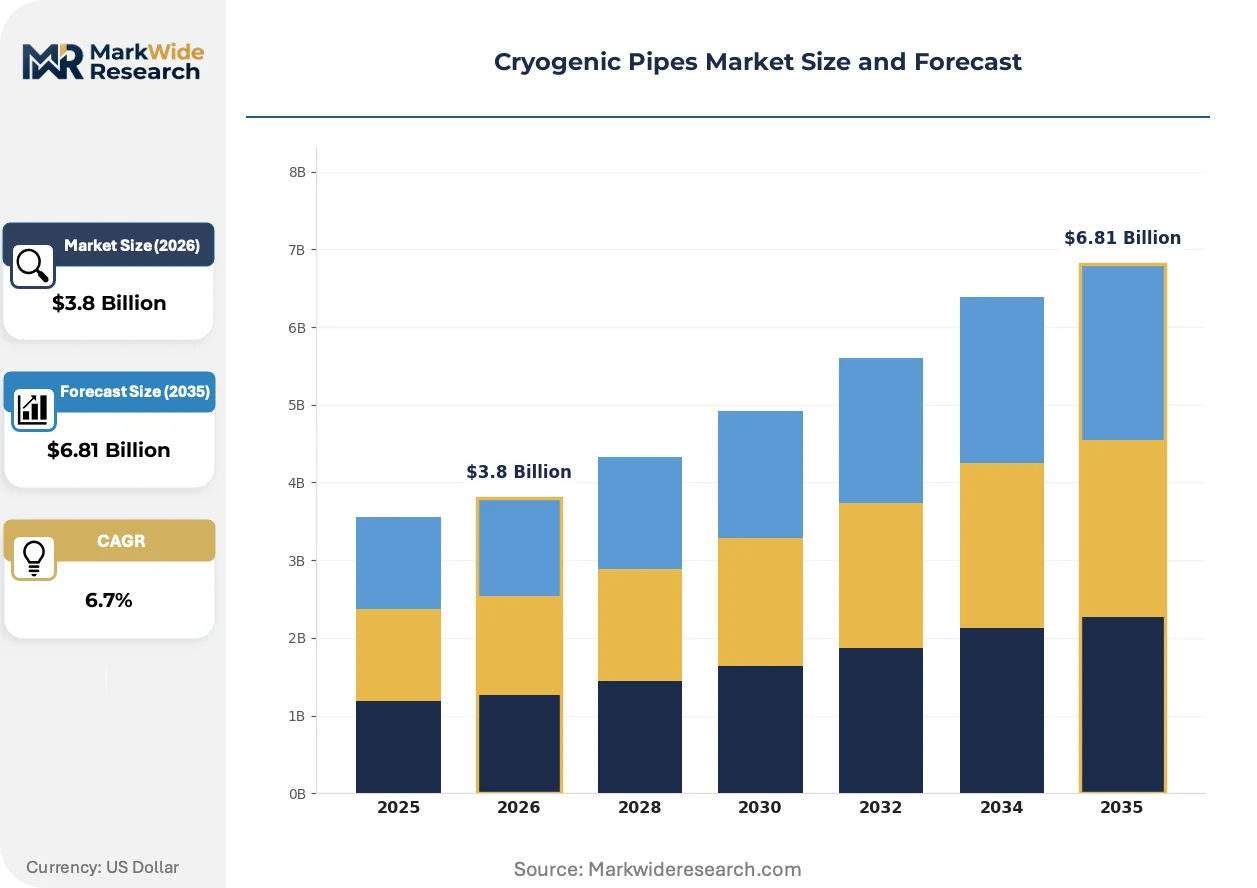
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Straight Pipes, Elbow Pipes, Tee Pipes, Reducers Material: Stainless Steel, Carbon Steel, Copper, Alloy Application: LNG Transportation, Cryogenic Storage, Industrial Gas Distribution, Aerospace End User: Oil & Gas, Power Generation, Aerospace & Defense, Chemical |
| Companies Covered | Acme Cryogenics, Parker Hannifin Corporation, Air Liquide, Cryofab Inc., Flowserve Corporation, Chart Industries, Herose GmbH, KITZ Corporation, Linde, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic Pipes Market Evolving Landscape
Material science breakthroughs and regulatory tightening are compressing traditional stainless steel dominance while elevating thermal performance as the primary procurement criterion for cryogenic infrastructure buyers.
Multilayer insulation (MLI) systems using alternating aluminum and fiberglass layers is overtaking conventional perlite powder insulation in large-diameter LNG transfer lines. Japanese shipyards and US Gulf Coast export terminals are specifying MLI for newbuild vapor return systems. This transition is overtaking established perlite suppliers and forcing insulation contractors to retool for precision-layered fabrication processes.
The EU F-Gas Regulation's phasedown of high-global-warming-potential blowing agents is mandating vacuum-insulated pipe replacements in industrial refrigeration and cold chain logistics. Equipment owners face compliance deadlines that compress replacement cycles from 15-year norms to 8-10 year intervals. Cold storage operators in Germany and the Netherlands are responding by bundling pipe upgrades with ammonia refrigeration system conversions.
Long-term service agreements with embedded thermal performance guarantees are displacing traditional equipment purchase models in aerospace test facility procurement. NASA Stennis Space Center and comparable facilities are contracting for guaranteed boil-off rates rather than capital equipment ownership. This pattern is most visible in US government and defense contractor sites where total cost of ownership calculations dominate capital allocation decisions.
Cryogenic Pipes Market Segmentation
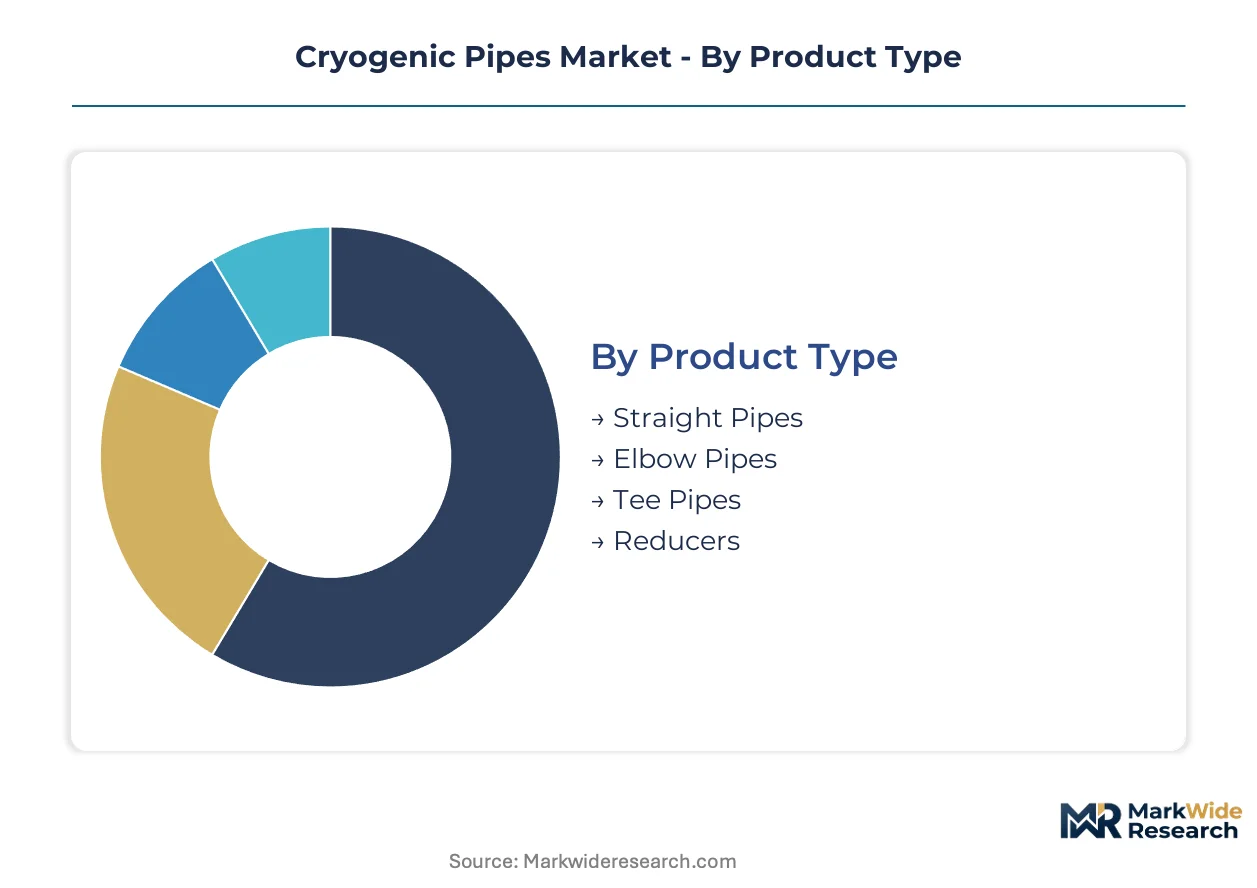
Cryogenic pipe procurement decisions hinge on thermal performance specifications, material compatibility with specific cryogenic fluids, and modular integration requirements. Buyers evaluate total cost of ownership across installation complexity, maintenance intervals, and boil-off rate guarantees rather than unit price alone.
Product Type:
Buyers prioritize thermal efficiency and field installation risk when selecting pipe configurations for cryogenic transfer networks.
- Straight Pipes:Vacuum-insulated double-wall construction dominates LNG export terminal installations where long transfer distances demand minimal heat ingress. US Gulf Coast liquefaction projects specify straight runs exceeding 500 meters for jetty-to-tank connections. Volume sits with straight pipes; growth tilts toward elbow configurations.
- Elbow Pipes:Pre-fabricated 45-degree and 90-degree configurations reduce field welding requirements in modular skid assemblies. Aerospace test facilities at NASA Stennis and comparable sites specify precision-bent elbows with embedded MLI insulation to maintain thermal performance across directional changes.
- Tee Pipes:Branch connections for vapor return lines and distribution manifolds in industrial gas networks.
- Reducers:Diameter transition fittings linking storage tanks to distribution headers in cryogenic storage facilities.
Straight runs dominate procurement volumes; elbow configurations capture premium positioning in aerospace and modular LNG applications.
Material:
Fluid-specific embrittlement risks and regulatory compliance timelines drive material selection across hydrogen, LNG, and industrial gas service.
- Stainless Steel:Austenitic grades 304 and 316L provide weldability and fracture toughness at LNG temperatures. Terminal operators in Qatar and China specify stainless for conventional liquefaction train expansions due to established ASME B31.3 qualification pathways. Stainless steel anchors installed base volumes; alloy grades are climbing the fastest.
- Alloy:Nickel-based alloys and specialized austenitic grades resist hydrogen embrittlement in liquid hydrogen distribution networks. German vacuum insulation specialists are qualifying Inconel and Hastelloy variants for next-generation hydrogen infrastructure under evolving ISO standards.
- Carbon Steel:Limited to pre-cooled service and jacket structures where cryogenic temperatures do not contact the pressure boundary.
- Copper:Restricted to small-diameter instrumentation lines and specialized heat exchanger connections.
Stainless steel retains volume leadership; alloy specifications are gaining share fastest in hydrogen service applications.
Application:
End-use thermal performance requirements and regulatory exposure determine specification stringency and replacement cycle timing.
- LNG Transportation:Vacuum-jacketed piping networks for liquefaction terminals, regasification facilities, and bunkering operations. US Gulf Coast export projects specify MLI-insulated systems with guaranteed boil-off rates below 0.5% per day.
- Cryogenic Storage:Tank connection piping and vapor recovery systems in industrial gas facilities. EU F-Gas Regulation compliance deadlines are compressing replacement cycles for older perlite-insulated storage connections in Germany and the Netherlands.
- Industrial Gas Distribution:Liquid nitrogen and oxygen transfer lines for pharmaceutical and food processing clusters.
- Aerospace:Propellant loading systems and test facility infrastructure with embedded thermal performance guarantees.
LNG transportation commands the largest project values; cryogenic storage applications are expanding most quickly under regulatory replacement mandates.
End User:
Capital deployment cycles and total cost of ownership calculations vary sharply across energy, government, and industrial procurement contexts.
- Oil & Gas:LNG terminal operators and pipeline companies specify large-diameter vacuum-jacketed systems for export infrastructure. QatarEnergy and comparable operators bundle cryogenic pipe procurement with liquefaction train engineering contracts.
- Aerospace & Defense:NASA, defense contractors, and emerging space launch providers contract for guaranteed thermal performance rather than equipment ownership. Long-term service agreements with embedded boil-off monitoring are displacing capital purchase models.
- Power Generation:Peaking plant LNG receiving terminals and hydrogen-ready gas turbine fueling systems.
- Chemical:Petrochemical crackers and ammonia production facilities with cryogenic feedstock handling requirements.
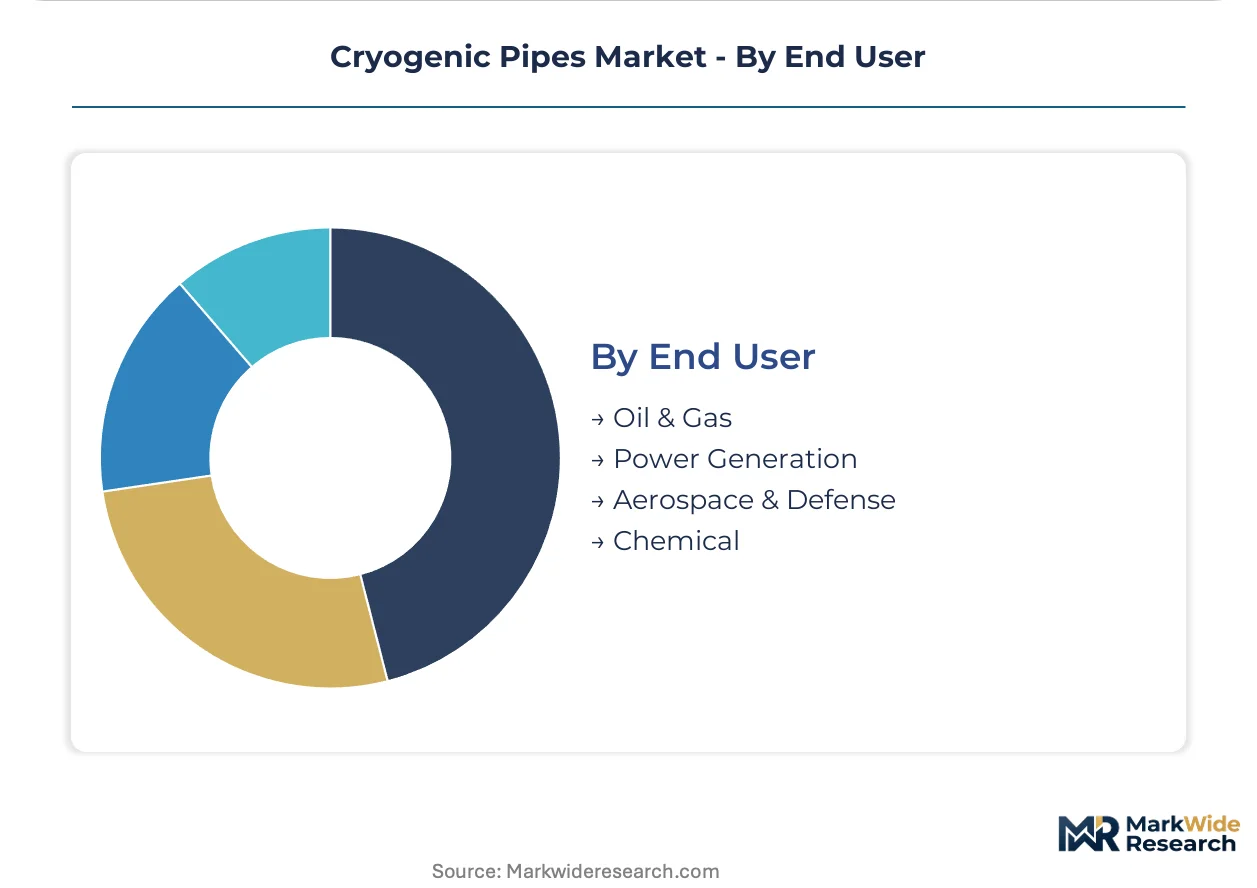
Oil and gas sector volumes dominate; aerospace and defense procurement is shifting fastest toward outcome-based service structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatari liquefaction capacity anchors the largest project pipelines for vacuum-jacketed piping networks. Demand clusters concentrate where LNG export terminals and hydrogen pilot projects overlap with tightening environmental regulations.
United States
Gulf Coast liquefaction terminals in Texas and Louisiana commission multilayer insulation systems for jetty-to-tank connections exceeding 500 meters. FERC pipeline safety mandates pressure-test protocols for cryogenic transfer lines crossing navigable waters. Houston-area fabricators specialize in modular skid assemblies for NASA Stennis Space Center propellant systems.
Germany
Industrial gas distributors in the Rhine-Ruhr corridor replace perlite-insulated storage connections under EU F-Gas Regulation compliance deadlines. ECHA chemical safety frameworks influence material qualification timelines for hydrogen service applications. Bavarian vacuum insulation specialists concentrate workforce training for multilayer insulation fabrication.
China
SAMR pressure equipment approvals govern cryogenic pipe deployment for liquefaction trains in Guangdong and Fujian provinces. National dual carbon goals accelerate hydrogen infrastructure pilots in the Yangtze River Delta. Shanghai-area engineering firms bundle pipe fabrication with on-site gas production contracts.
Qatar
North Field expansion projects specify large-diameter vacuum-jacketed networks for the world's largest liquefaction capacity additions. QatarEnergy bundles cryogenic procurement with engineering contracts for integrated LNG-to-power systems. Ras Laffan Industrial City concentrates specialized welding certification programs for nickel-alloy piping.
Japan
METI hydrogen roadmap funding supports liquid hydrogen import terminal pilots in Kansai and Kyushu regions. JIS standards development for cryogenic vessels proceeds in parallel with ISO working groups. Osaka-area shipyards specify precision-bent elbows with embedded multilayer insulation for vapor return systems.
Cryogenic Pipes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue hydrogen-specific alloy qualifications and digital service models. The vendor base stratifies across three tiers: integrated industrial gas conglomerates with captive fabrication, specialized vacuum insulation houses with regional workforce concentration, and modular system integrators displacing field-welded configurations. Two dominant competitive moves define positioning: backward integration into brazed aluminum heat exchangers and long-term service contracts with embedded thermal performance guarantees.
Among US-based diversified industrials, Parker Hannifin Corporation occupies a position anchoring valve-and-pipe assemblies for aerospace test facilities. German vacuum insulation specialists exemplify the specialized fabrication tier, with Herose GmbH representing pressure equipment expertise concentrated in European industrial clusters. Chart Industries sits within the integrated tier, exemplifying backward integration into heat exchange equipment bundled with distribution system engineering.
| Leading Market Players |
|---|
| Acme Cryogenics |
| Parker Hannifin Corporation |
| Air Liquide |
| Cryofab Inc. |
| Flowserve Corporation |
| Chart Industries |
| Herose GmbH |
| KITZ Corporation |
| Linde |
| Others |
Value Network & Pricing Analysis
The EU F-Gas Regulation's insulation performance mandates gate qualified supply access for vacuum-jacketed piping systems, restricting premium-tier pricing to fabricators with ASME B31.3 and ISO 21009 certifications. Buyers face 8-14 month qualification cycles that compress price competition and sustain margin pools for certified suppliers.
Pricing Analysis
Warranty and service bundling separates equipment-only transactions from performance-guaranteed contracts. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and thermal performance guarantees, with aerospace buyers contracting for guaranteed boil-off rates rather than capital ownership. Cost compression in standard stainless steel segments intensifies because modular skid integrators displace field-welded configurations. Industrial gas distributors in Germany and the Netherlands exhibit highest price sensitivity due to compressed replacement cycles under regulatory deadlines.
Supply Chain Analysis
ASME B31.3 and ISO 21009 certification requirements concentrate qualified fabrication capacity in Germany, Japan, and the United States. Raw material sourcing draws from Indonesian and Russian nickel concentrate for hydrogen-resistant alloys, austenitic stainless steel from Chinese and European mills, and multilayer insulation films from Japanese specialty chemical producers. Single-source vulnerability runs through Indonesian nickel processing concentration for specialized alloys. Distribution runs through EPC contractors and industrial gas conglomerates bundling fabrication with on-site gas production contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vacuum maintenance technician scarcity in German and Japanese fabrication centers constrains qualified supply expansion, propping pricing power for certified incumbents.
For Market Incumbents: Extend thermal performance guarantee offerings into long-term service contracts to lock out modular skid competitors displacing traditional elbow and tee configurations. Deepen backward integration into brazed aluminum heat exchangers to capture bundled LNG distribution system procurement. Invest in Bavarian and Osaka-area workforce training pipelines to defend against technician scarcity threatening capacity expansion. For New Entrants and Emerging Players: Enter via underpenetrated pharmaceutical and food processing clusters in India where vacuum-insulated distribution networks remain nascent. Target liquid hydrogen infrastructure pilots in the Yangtze River Delta and Kansai region where evolving ISO standards create qualification windows before incumbent lock-in. Pursue digital twin integration partnerships with IoT sensor networks to differentiate on predictive boil-off monitoring. For Investors and Strategic Acquirers: First commercial liquid hydrogen import terminal operations in Japan's Kansai region is the leading indicator that nickel-alloy cryogenic piping demand is crossing from pilot to scalable deployment. Position for 5-10 year infrastructure buildout cycles by targeting specialized vacuum insulation houses with regional workforce concentration and hydrogen-specific material qualifications. Monitor SAMR approval timelines for Chinese liquefaction train projects as signals of demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchangers | Chart Industries exemplifies bundled LNG distribution system engineering capturing liquefaction train contracts. |
| Long-term Service Agreement Expansion | NASA Stennis Space Center contracts signal aerospace shift from capital purchase to guaranteed performance models. |
| Hydrogen-specific Alloy Qualification | German vacuum insulation specialists pursue Inconel variants under evolving ISO cryogenic vessel standards. |
| Digital Twin Platform Development | IoT sensor convergence with predictive thermal modeling enables outcome-based boil-off monitoring contracts. |
| Regional Workforce Training Investment | Bavarian and Osaka-area fabrication centers concentrate scarce vacuum jacket integrity testing capabilities. |
Research Methodology
Independent corroboration across LNG terminal engineering directors, vacuum insulation fabrication managers, and industrial gas procurement leads underwrites the qualitative findings. Primary interviews with EPC contractors, aerospace test facility operators, and hydrogen infrastructure developers combined with secondary validation from FERC filings, EIA liquefaction project databases, EU F-Gas Regulation implementation reports, and SAMR pressure equipment approval records. Bottom-up project pipeline enumeration and top-down industrial gas consumption modeling triangulate market sizing.
Rate-of-change decomposition across the projection horizon segments volume and value by material grade, product configuration, application thermal performance tier, and end-user capital deployment cycle. Cryogenic pipe procurement patterns, liquefaction train commissioning schedules, and regulatory replacement mandate timelines feed analytical frameworks. CAGRs derive from weighted average of project-based demand curves and replacement cycle compression effects.
Revisions become necessary when nickel price volatility disrupts alloy input costs, ASME-ISO harmonization accelerates certification timelines, or modular skid substitution rates exceed baseline assumptions. A model refresh is warranted upon material change in hydrogen infrastructure pilot commercialization rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
PVC Pipes and Fittings Market
Pipes and Tubes
Global Flexible Pipes Market
Pipes and Tubes
Hydrogen Tube Skids Market
Pipes and Tubes
FEP Tubing Products Market
Pipes and Tubes
FRP Pipes and Tanks Market
Pipes and Tubes
Aluminium Tubes for OPC Drum Market
Pipes and Tubes
Piping System and Piping Spools Market
Pipes and Tubes
Kuwait PVC Pipes Market
Pipes and Tubes
China Industrial Hoses Market
Pipes and Tubes
India PVC Pipes Market
Pipes and Tubes
Coiled Tubing Manufacturing Market
Pipes and Tubes
Steel Pipes and Tubes Market
Pipes and Tubes
Seamless Pipe Market
Pipes and Tubes
India Process Piping Market
Pipes and Tubes
Global Tracer Wires Market
Pipes and Tubes
Plastic Pipe Jointing and Welding Market