
 Polyethylene Pipes Market | 2026-2036
Polyethylene Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethylene Pipes Market Insights
Utility procurement channels is tilting toward direct manufacturer engagement as municipal buyers consolidate vendor lists. JM Eagle leverages its integrated resin-to-pipe manufacturing footprint across multiple US states to sustain price competitiveness. Chevron Phillips Chemical Company anchors the upstream resin supply chain, giving captive feedstock security to its pipe affiliates. Advanced Drainage Systems differentiates through corrugated HDPE stormwater solutions that dominate North American infrastructure bids.
Polyethylene pipes are thermoplastic conduits manufactured from polymerized ethylene monomers, typically extruded in densities ranging from 0.930 g/cm³ to 0.960 g/cm³ depending on grade, and engineered to withstand pressures from 80 psi to 250 psi while resisting chemical corrosion and soil stress. HDPE commands the largest product-type position due to its stiffness-to-density ratio and fusion-welded joint integrity for buried water and gas mains. Horizontal directional drilling as an installation method is gaining share fastest among trenchless techniques, as urban density limits open-cut permissions and municipalities prioritize traffic disruption reduction.
EPA underground storage tank regulations and EU F-Gas Phase-down requirements are tightening material performance standards for gas distribution and industrial containment piping, forcing resin reformulation and third-party certification upgrades. India's BIS certification for PE100-grade pipes and China's GB standards for municipal water infrastructure are creating parallel compliance tracks that favor manufacturers with multi-jurisdiction testing capabilities. Stakeholders must monitor regulatory divergence between North American and European pressure-rating protocols, as misalignment in fusion qualification standards threatens cross-border product portability and project bidding scope.
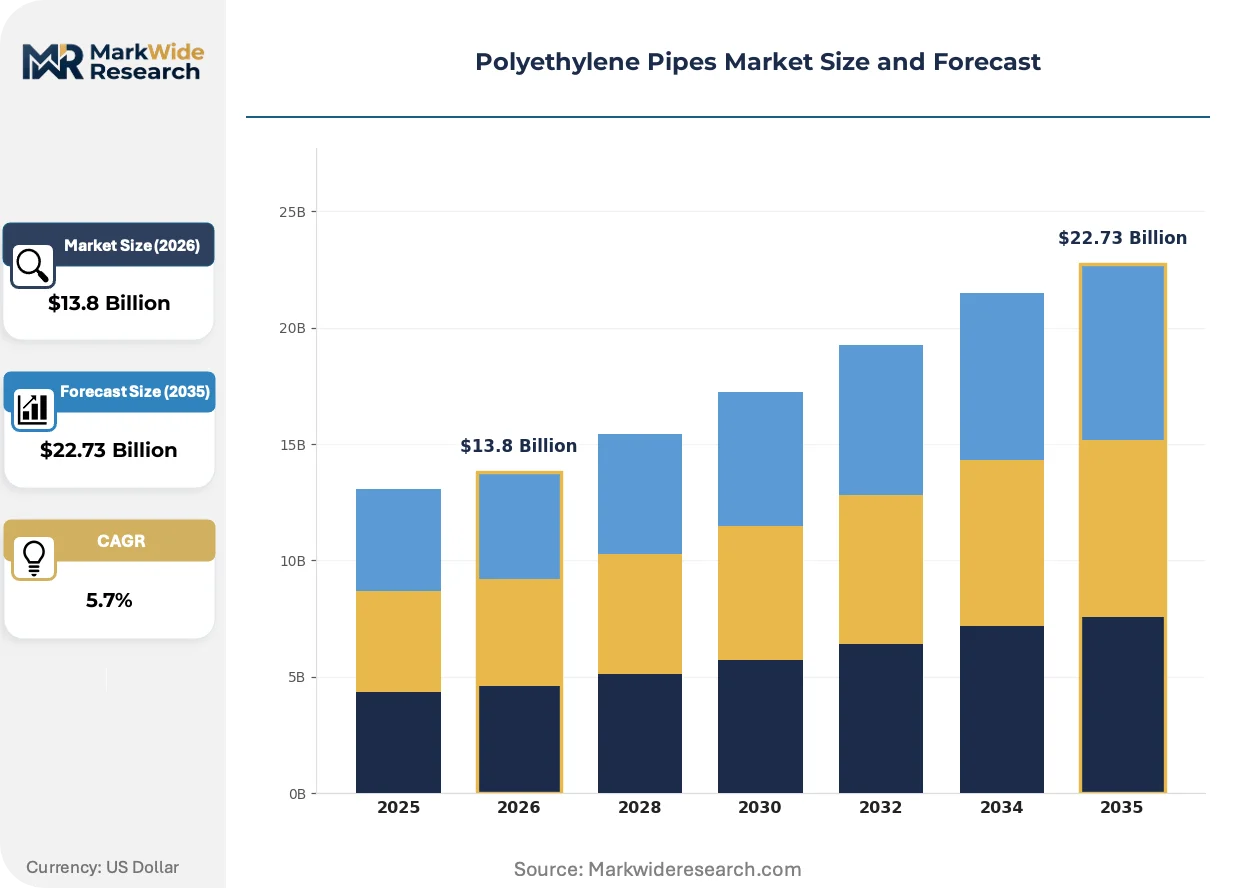
Market Dynamics
Utility infrastructure replacement cycles are compressing pipe procurement timelines as municipalities accelerate water main rehabilitation programs ahead of regulatory compliance deadlines. Federal funding mechanisms in the United States and state-level mandates in Germany are forcing asset managers to abandon reactive maintenance models.
Growth Catalysts
- Jal Jeevan Mission procurement:India's rural water connectivity targets are generating sustained demand for large-diameter HDPE distribution networks across drought-prone states.
- EPA underground storage tank standards:Leak detection mandates are accelerating metal-to-polyethylene substitution in fuel containment and vapor recovery piping.
- Horizontal directional drilling adoption:Urban density constraints are favoring trenchless installation methods that exploit HDPE's fusion-welded joint integrity.
Market Restraints
- Ethylene feedstock volatility:Cracker output fluctuations and naphtha price swings compress resin converter margins during contract renegotiations.
- Resin supply concentration:North American ethylene capacity clusters along the Gulf Coast expose pipe extruders to hurricane-related production interruptions.
- Fusion qualification fragmentation:Divergent pressure-rating protocols between ASTM and ISO standards block cross-border product portability for multinational contractors.
Strategic Opportunities
- Stormwater management retrofitting:Aging combined sewer overflow infrastructure in legacy US cities creates demand for corrugated HDPE detention systems.
- Biogas and hydrogen blending:Gas distribution operators are testing PE100-RC grades for renewable fuel conveyance ahead of network decarbonization timelines.
- Direct municipal engagement:Consolidated vendor lists are opening procurement channels that bypass traditional distributor markups for qualified manufacturers.
Industry Challenges
- Fusion technician certification backlog:Qualified butt-fusion and electrofusion operators remain scarce relative to installation project pipelines.
- Multi-jurisdiction testing overhead:Manufacturers serving both North American and European markets face redundant certification costs for PE100-grade conformance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethylene Pipes Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $22.73 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDPE, MDPE, LDPE, LLDPE Application: Water Supply, Gas Distribution, Sewage Disposal, Irrigation Systems, Cable Protection Installation Method: Trenching, Horizontal Directional Drilling, Plowing, Pneumatic Piercing, Surface Mounting End User Industry: Municipal Corporations, Agricultural Contractors, Oil & Gas Firms, Telecommunication Providers, Construction Firms |
| Companies Covered | JM Eagle, Chevron Phillips Chemical Company, Advanced Drainage Systems, WL Plastics, Aliaxis, Wavin, LESSO, Jain Irrigation Systems, Pipelife International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethylene Pipes Market Trends and Innovations
Material science advances and installation method evolution are redefining performance benchmarks for buried infrastructure. Pipe producers are reformulating resin grades while contractors adopt mechanized fusion equipment to reduce field variability.
PE100-RC (resistance to crack) resin formulations are migrating from niche mining applications into mainstream municipal water specifications. German utilities pioneered adoption of these slow-crack-growth grades for trenchless installations without sand bedding. The technology is migrating from premium project tiers into standard procurement specifications as asset managers prioritize design-life extension over first-cost minimization.
EU F-Gas Phase-down requirements are tightening material performance standards for industrial refrigeration and gas distribution containment. Resin suppliers must demonstrate permeation resistance under accelerated aging protocols. European gas network operators are responding by specifying bimodal PE grades with enhanced barrier properties for hydrogen-blended fuel streams.
Buyer consolidation among US municipal water authorities is compressing vendor qualification cycles and favoring manufacturers with integrated resin-to-pipe production. Large-diameter procurement teams now demand direct engineering engagement rather than distributor-mediated support. The shift is most visible in Texas and California, where regional water districts have centralized technical specification authority away from individual municipalities.
Polyethylene Pipes Market Segmentation
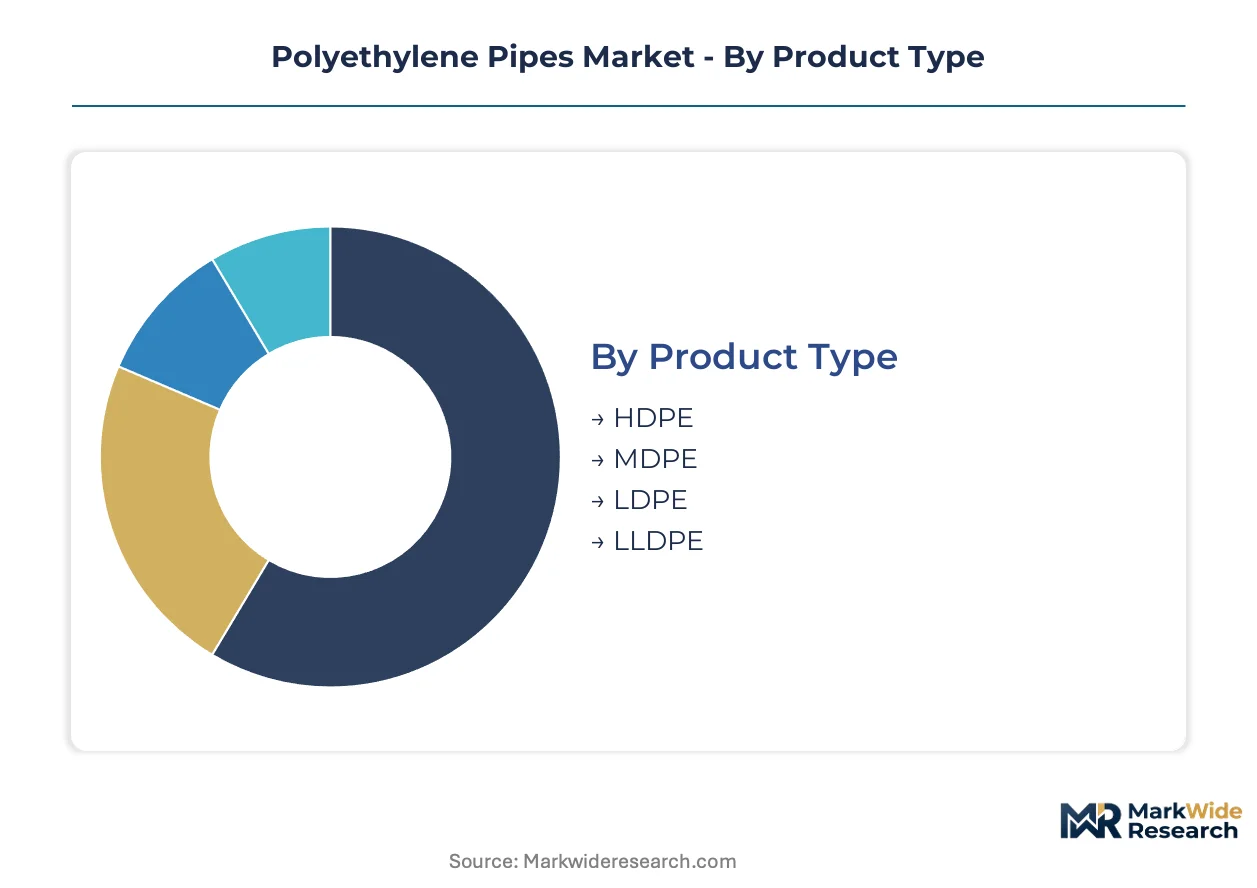
Polyethylene pipe procurement varies sharply across density grades, installation constraints, and end-user technical specifications. Understanding how demand fragments across these dimensions reveals where margin pools concentrate and where specification authority resides.
Product Type:
Density grade determines pressure rating, flexibility, and fusion compatibility for specific buried applications.
- HDPE:High-density formulations (0.941-0.965 g/cm³) deliver the stiffness-to-density ratio required for municipal water mains and gas distribution networks. India's Jal Jeevan Mission procurement concentrates demand for PE100-grade HDPE in large-diameter rural distribution systems across drought-prone states.
- MDPE:Medium-density grades balance flexibility with pressure containment for residential gas service lines and small-diameter water connections. German utilities specify MDPE for urban renewal projects where trenchless installation methods demand greater conformability than HDPE permits.
- LDPE:Low-density formulations serve low-pressure drip irrigation laterals and protective conduit applications where flexibility trumps structural load-bearing.
- LLDPE:Linear low-density grades dominate agricultural film and flexible tubing segments outside pressure-pipe specifications.
HDPE holds installed capacity. MDPE is rotating up the share rankings.
Application:
End-use function dictates pressure class, joint methodology, and regulatory compliance burden.
- Water Supply:Potable water transmission demands PE100 or PE100-RC grades with fusion-welded joint integrity for leak-free performance across 50-100 year design lives. EPA Lead and Copper Rule revisions are accelerating metal replacement in US municipal distribution networks.
- Gas Distribution:Fuel containment applications require bimodal resin grades with enhanced permeation resistance under EU F-Gas Phase-down protocols. Network operators are testing PE100-RC for hydrogen-blended fuel streams ahead of decarbonization timelines.
- Sewage Disposal:Corrugated HDPE stormwater detention systems address combined sewer overflow mandates in legacy US infrastructure.
- Irrigation Systems:Agricultural deployment favors lower-density formulations for drip laterals and center-pivot distribution.
- Cable Protection:Telecommunication and power infrastructure uses smooth-wall or corrugated conduits for fiber and electrical line burial.
Water Supply commands specification authority. Gas Distribution is climbing the fastest as hydrogen compatibility testing advances.
Installation Method:
Subsurface constraints and surface disruption permissions determine technique selection and pipe grade requirements.
- Trenching:Open-cut excavation remains standard for greenfield development and rural deployments where surface restoration costs are minimal.
- Horizontal Directional Drilling:Trenchless installation exploits HDPE's fusion-welded joint integrity to pull continuous pipe strings beneath obstacles without surface excavation. Urban density constraints in the United States and Germany are expanding this method's share fastest.
- Plowing:Vibratory or static plowing suits agricultural field installations where shallow burial depths and soft soils permit rapid mechanical deployment.
- Pneumatic Piercing:Impact moling creates short crossings under roadways and driveways for service line connections.
- Surface Mounting:Above-grade applications include temporary bypass lines and industrial process piping where burial is impractical.
Trenching retains volume dominance. Horizontal Directional Drilling is expanding most quickly as urban permitting tightens.
End User Industry:
Procurement scale and technical specification authority vary dramatically across buyer categories.
- Municipal Corporations:Public water and sewer authorities consolidate vendor lists and demand direct manufacturer engagement for large-diameter projects. Federal funding mechanisms in the United States compress procurement timelines.
- Agricultural Contractors:Farm-scale irrigation deployment favors price-competitive lower-density grades with distributor-mediated procurement.
- Oil & Gas Firms:Upstream gathering lines and midstream transmission specify high-performance grades with third-party certification for sour service and high-temperature exposure.
- Telecommunication Providers:Fiber network burial drives demand for small-diameter conduit with cable-pulling lubricity specifications.
- Construction Firms:Commercial and residential building connections represent fragmented, specification-diverse demand.
Municipal Corporations anchor specification authority. Telecommunication Providers are gaining procurement scale as fiber deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-setting power concentrates with resin-integrated manufacturers in the United States while European converters absorb higher feedstock costs from import-dependent positions. German utilities command specification authority for PE100-RC grades that command 15-20% premiums over standard HDPE. Indian procurement velocity under Jal Jeevan Mission timelines is compressing supplier qualification windows and favoring domestic extruders with BIS certification already in hand.
United States
Federal infrastructure funding through the Bipartisan Infrastructure Law is accelerating water main replacement timelines across legacy municipal systems. EPA Lead and Copper Rule revisions are mandating lead service line removal by 2034, forcing metal-to-polyethylene substitution at scale. The Gulf Coast ethylene production corridor anchors resin supply security for pipe extruders in Texas and Louisiana, though hurricane exposure remains a concentration risk.
Germany
Gas network operators are piloting PE100-RC grades for hydrogen-blended fuel streams ahead of 2045 decarbonization targets. EU F-Gas Phase-down requirements are tightening permeation resistance standards for industrial refrigeration piping. The Ruhr industrial basin and Bavarian manufacturing clusters host specification-setting utilities that influence procurement standards across Central European markets.
India
Jal Jeevan Mission rural connectivity targets are generating sustained demand for large-diameter HDPE distribution networks across Maharashtra, Gujarat, and Rajasthan. BIS certification for PE100-grade pipes creates compliance barriers that favor domestic manufacturers with established testing capabilities. The Delhi-Mumbai Industrial Corridor and Gujarat's petrochemical complexes are emerging as procurement coordination hubs for drought-prone state water authorities.
China
GB standards for municipal water infrastructure are creating parallel compliance tracks that favor manufacturers with multi-jurisdiction testing capabilities. Provincial governments in Shandong and Jiangsu are consolidating water utility procurement to achieve scale economies in pipe procurement. The Yangtze River Delta manufacturing belt concentrates extrusion capacity serving both domestic infrastructure and export markets.
Saudi Arabia
Vision 2030 infrastructure investments are expanding water transmission and distribution networks across arid regions with high salinity exposure. The country's national standards body is aligning pipe specifications with ISO pressure-rating protocols to facilitate technology transfer. The Eastern Province petrochemical complexes provide captive ethylene feedstock for integrated pipe manufacturing serving Gulf Cooperation Council markets.
Polyethylene Pipes Market Competitive Landscape
Resin-integrated majors and specialized extruders split the market between specification-driven municipal contracts and price-sensitive agricultural segments. Consolidation is proceeding along geographic lines rather than product lines, with North American and European players maintaining distinct procurement ecosystems. Three archetypes dominate: integrated resin-to-pipe manufacturers with captive feedstock security, corrugated stormwater specialists with trenchless installation expertise, and regional extruders serving distributor-mediated agricultural demand. Capacity expansion and direct municipal engagement represent the dominant competitive moves as buyer consolidation compresses vendor lists.
Among integrated manufacturers, JM Eagle exemplifies the resin-captive archetype with multi-state production footprints enabling price competitiveness in large-diameter municipal bids. Chevron Phillips Chemical Company anchors upstream resin supply chains that secure feedstock access for affiliated pipe operations. Advanced Drainage Systems occupies a specialized position in corrugated HDPE stormwater solutions that dominate North American infrastructure specifications. These three represent distinct strategic postures: scale-driven integration, upstream supply security, and application-specific engineering differentiation.
| Leading Market Players |
|---|
| JM Eagle |
| Chevron Phillips Chemical Company |
| Advanced Drainage Systems |
| WL Plastics |
| Aliaxis |
| Wavin |
| LESSO |
| Jain Irrigation Systems |
| Pipelife International |
| Others |
Pricing and Supply Chain Analysis
The Houston Ship Channel freight corridor anchors polyethylene pipe cost dynamics, with resin barge movements from Gulf Coast crackers creating geographic price gradients that favor integrated manufacturers while squeezing import-dependent converters. This logistics concentration amplifies supply-side pricing power for captive ethylene producers and forces distributor-mediated buyers into volume-commitment contracts to secure freight-advantaged delivery.
Pricing Analysis
The customization-premium spread separates configured-to-order PE100-RC grades for trenchless municipal projects from standard PE80 water distribution stock, with certification tier and fusion qualification status driving price differentiation. Contract-based long-term offtake dominates municipal procurement, while spot purchasing persists in agricultural segments where buyers exhibit highest price sensitivity. Cost compression in standard HDPE grades is intensifying because resin converter overcapacity in Texas and Louisiana compresses extrusion margins during contract renegotiations.
Supply Chain Analysis
Contract manufacturing concentration rests with integrated resin-to-pipe operators along the US Gulf Coast, Saudi Arabia's Eastern Province, and China's Yangtze River Delta belt. Raw material dependencies draw from ethylene cracker output, naphtha feedstock, and bimodal catalyst systems for PE100-RC grades. Single-source vulnerability concentrates hurricane exposure threatens Gulf Coast resin supply interruptions. Distribution runs through direct municipal engagement for large-diameter projects and distributor networks for fragmented agricultural demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through multi-jurisdiction certification requirements creates switching costs that lock municipal buyers into qualified vendor relationships. Fusion technician scarcity and BIS/ASTM/ISO protocol divergence deepen incumbent advantages.
For Market Incumbents: Build certification moats by accelerating PE100-RC qualification across EPA, EU F-Gas, and India's BIS frameworks simultaneously. Backward integration into bimodal resin production secures feedstock during ethylene volatility cycles. Capacity addition in Gujarat and Texas reinforces geographic proximity to Jal Jeevan Mission and Bipartisan Infrastructure Law procurement hubs. Threat substitution from ductile iron in large-diameter segments demands continuous fusion-joint performance demonstration. For New Entrants and Emerging Players: Pursue stormwater detention retrofitting in legacy US cities where corrugated HDPE specifications remain less entrenched than water main standards. Agricultural drip irrigation laterals in drought-prone Indian states present penetrable white-space with lower certification barriers. Direct engagement with consolidated Texas and California regional water districts bypasses distributor markups for qualified manufacturers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors resin-integrated manufacturers with captive Gulf Coast ethylene access over pure-play extruders facing margin compression. Long-term viability hinges on hydrogen-blended gas distribution compatibility testing and PE100-RC adoption velocity. Acquisition target archetype: regional extruders with established BIS certification and Jal Jeevan Mission supplier status. Signal to watch: EPA fusion qualification standard harmonization with ISO protocols as inflection indicator for cross-border product portability expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bimodal Resin | Captive PE100-RC supply secures margins during ethylene cracker turnaround cycles. |
| Multi-Jurisdiction Certification Investment | Simultaneous BIS, ASTM, and ISO qualification opens bidding scope across India, US, and EU tenders. |
| Direct Municipal Engagement Program | Bypassing distributor networks captures margin compression from consolidated vendor lists in Texas and California. |
| Horizontal Directional Drilling Partnership | Alignment with trenchless contractors exploits HDPE fusion integrity for urban infrastructure bids. |
| Hydrogen Compatibility Testing Program | PE100-RC validation for blended fuel streams positions suppliers for German gas network decarbonization timelines. |
Research Methodology
Cross-validation between plant manager interviews at Gulf Coast extrusion facilities and customs/trade data from USITC and Eurostat anchors the qualitative findings in this study. Primary discussions with municipal procurement officers at Texas and California regional water districts, fusion technician training program administrators, and resin procurement leads at downstream pipe manufacturers combined with secondary validation through SEC 10-K filings, EPA underground storage tank regulatory dockets, and BIS certification registries. Bottom-up capacity utilization estimates and top-down infrastructure spending allocation models triangulate market sizing.
Calibration against historical resin price elasticity and municipal procurement cycle timing shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include density grade tier, end-use application function, installation methodology, and regional regulatory cluster. CAGRs were derived from infrastructure spending trajectory correlation with pipe procurement velocity. Industry-specific forecast inputs incorporate Jal Jeevan Mission rural connectivity targets and EPA Lead and Copper Rule compliance deadlines.
Macroeconomic conditions sit as an overlay; deviation in naphtha feedstock pricing and federal infrastructure appropriation timing would shift the trajectory. Forecasts reflect underlying assumptions about resin supply continuity and regulatory harmonization pace. Quarterly review of ethylene cracker operating rates, municipal bond issuance for water infrastructure, and fusion technician certification backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
North America PVC Pipes Market
Pipes and Tubes
Cold Drawn Seamless (CDS) Steel Pipes Market
Pipes and Tubes
Steel Tubes Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
Agricultural Pipes and Tubes Market
Pipes and Tubes
Industrial Tubes Market
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
Global Butt Weld Fittings Market
Pipes and Tubes
GCC Polyethylene (PE) Pipes Market
Pipes and Tubes
Global Titanium Tube Market
Pipes and Tubes
France PVC Pipes Market
Pipes and Tubes
Drum Funnel Market
Pipes and Tubes
Oman PVC Pipes Market
Pipes and Tubes
Saudi Arabia Copper Pipes and Tubes Market
Pipes and Tubes
Collapsible Metal Tubes Market
Pipes and Tubes
Glass Reinforced Plastic (GRP) Piping Market