
 Global Tracer Wires Market | 2026-2036
Global Tracer Wires Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tracer Wires Market Outlook
Chinese insulated-cable producers is repositioning capacity toward tracer-wire grades to serve Asia-Pacific pipeline construction. Copperhead Industries LLC leverages vertical integration from copper rod to finished jacketed conductor. Southwire Company sustains manufacturing scale across multiple US plant locations. Performance Wire and Cable specializes in high-density polyethylene formulations for direct-burial applications.
Tracer wires are electrically conductive cables, typically copper or aluminum cores with insulating jackets rated for 30V to 600V, manufactured through continuous extrusion and designed to emit a detectable electromagnetic signal for underground utility location. Single-conductor designs dominate volume due to cost efficiency in standard pipeline installations, while multi-conductor configurations capture margin pools in complex telecommunications and power-distribution corridors where simultaneous tracing of multiple utilities reduces excavation risk. Composite material variants, blending conductive cores with polymer strength members, represent the fastest-growing structural category as contractors seek combined mechanical durability and signal integrity in harsh soil conditions.
The US Department of Transportation's PHMSA pipeline safety regulations and the EPA's Underground Injection Control program shape product standards by mandating corrosion-resistant, continuously traceable underground infrastructure. EMA's CE marking requirements and REACH substance restrictions govern material composition for European tracer-wire imports, while China's GB standards through SAMR establish domestic testing protocols for insulation integrity. Stakeholders must monitor evolving national mandates for smart-city utility mapping and the shifting material-certification thresholds that determine cross-border market access.
Market Dynamics
The US Infrastructure Investment and Jobs Act has triggered a structural demand surge by mandating locator-wire inclusion in federally funded pipeline projects, forcing contractors to source corrosion-resistant, continuously traceable conductors ahead of project bid deadlines.
Growth Catalysts
- PHMSA pipeline safety regulations:The US Department of Transportation mandates corrosion-resistant, continuously traceable underground infrastructure across interstate pipeline networks. Contractors must install certified tracer-wire systems to maintain operating licenses.
- Petrochemical corridor replacement cycles:Aging infrastructure along the US Gulf Coast accelerates procurement of high-density polyethylene jacketed conductors as facilities upgrade buried utility mapping.
- Smart-city utility mapping mandates:Municipal digitization programs in China through SAMR's GB standards drive tracer-wire specification in new urban pipeline installations.
Market Restraints
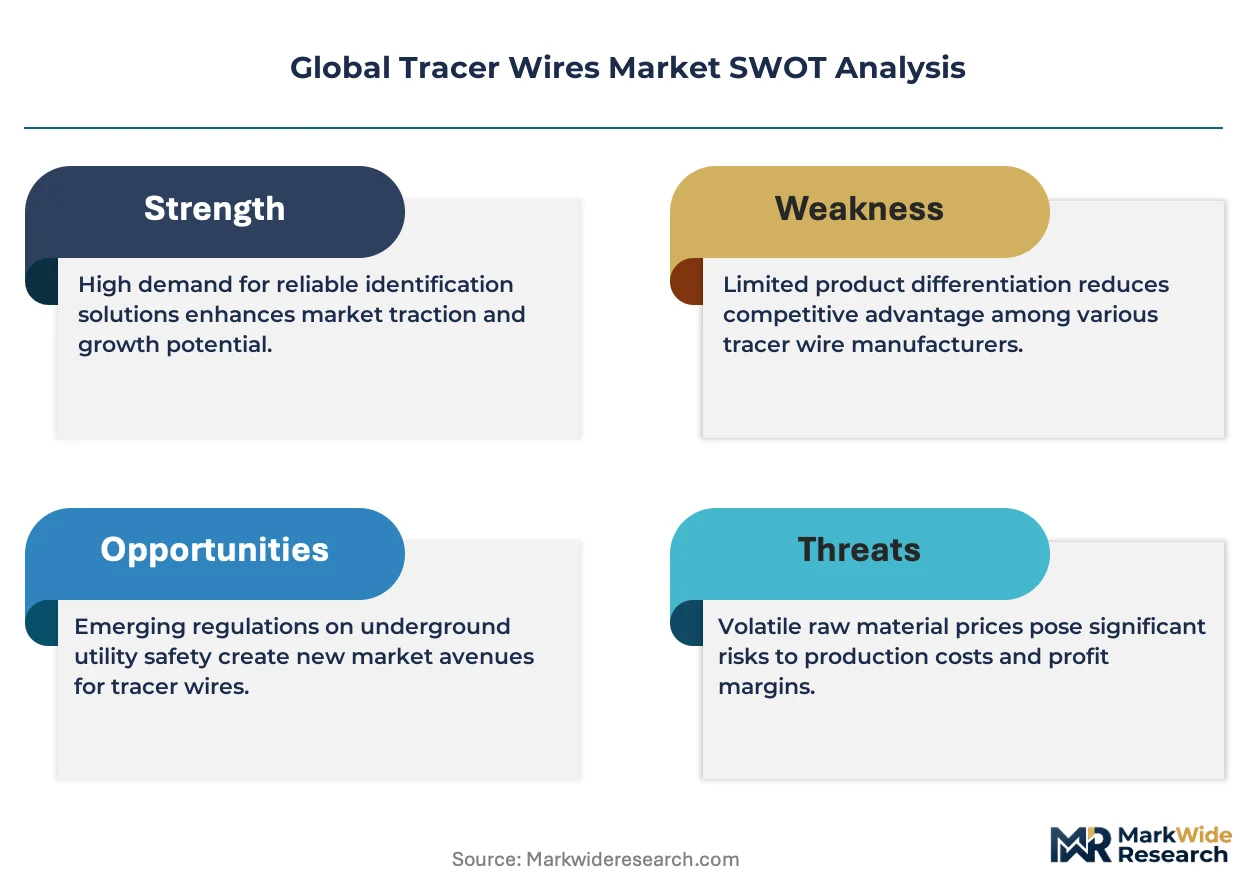
- Copper price volatility:Raw material cost swings for conductive cores compress margin predictability for jacketed-cable manufacturers.
- REACH substance restrictions:ECHA's evolving chemical compliance thresholds create friction for European tracer-wire imports, delaying market entry.
- Aluminum core substitution:Lower-conductivity alternatives threaten copper-dominant specifications in cost-sensitive municipal contracts.
Strategic Opportunities
- Composite material convergence:Polymer strength members blended with conductive cores open harsh-soil applications previously closed to single-conductor designs.
- Asia-Pacific pipeline construction:Chinese insulated-cable producers reposition capacity toward tracer-wire grades to serve regional infrastructure buildouts.
- EPA Underground Injection Control expansion:Class VI well monitoring requirements create new specification channels for high-voltage-rated jacketed conductors.
Industry Challenges
- Multi-standard certification timelines:Manufacturers face parallel testing protocols under PHMSA, EMA CE marking, and SAMR GB standards.
- Electromagnetic interference mitigation:Dense utility corridors require signal-isolation expertise that strains contractor technical capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tracer Wires Market |
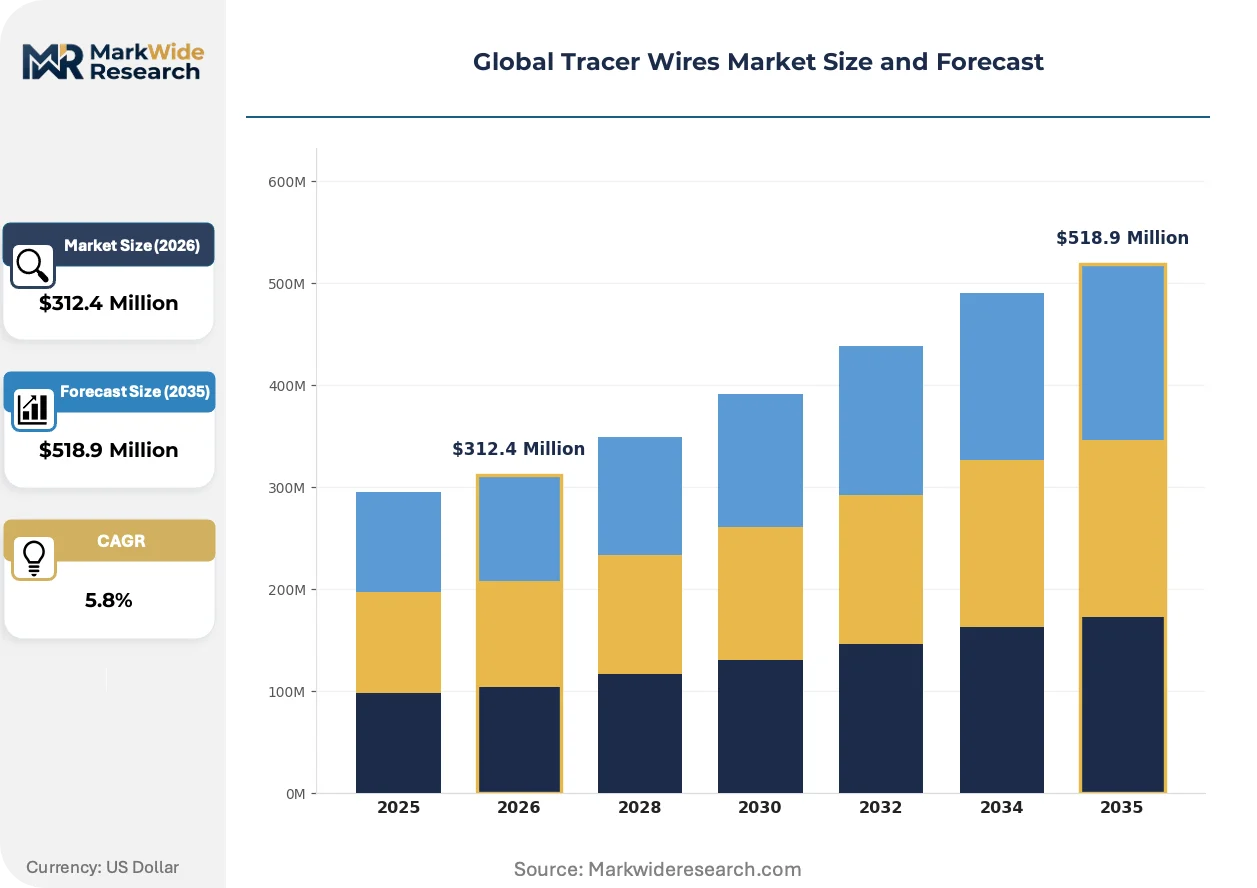
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Conductor, Multi-Conductor, Composite, Specialty Material: Copper, Aluminum, Stainless Steel, Plastic Application: Telecommunications, Power Distribution, Safety Systems, Heating End User: Utilities, Contractors, Homeowners, Industrial Users |
| Companies Covered | Copperhead Industries LLC, AIM Utility Products, Tracer Wire Technologies, LLC, Pro-Line Safety Products Company, Nehring Electrical Works Company, Kris-Tech Wire, Performance Wire and Cable, Ramcorp Wire and Cable, Inc., Southwire Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tracer Wires Market Strategic Shifts
Material science advances and regulatory digitization mandates are compressing product lifecycles while opening specification channels for hybrid conductor-strength member designs.
Composite tracer-wire architectures blending copper cores with polymer strength members are electrifying contractor preferences in high-corrosion soil environments. Water utilities and petrochemical operators in coastal zones are specifying these variants at accelerating rates. The technology is electrifying procurement patterns by collapsing the traditional separation between mechanical protection and signal integrity into single-installation solutions.
REACH substance restrictions through ECHA are tightening material-certification thresholds for European tracer-wire imports. Manufacturers must reformulate jacket compounds to eliminate restricted phthalates and heavy-metal stabilizers. The regulatory pressure is compressing formulation cycles most severely for mid-tier suppliers serving cross-border distribution channels.
Specification bundling is consolidating contractor purchasing decisions around integrated utility-mapping packages. Traditional wire-only vendors face displacement by full-system providers offering conductor-plus-locator equipment combinations. This pattern concentrates most visibly in North American municipal procurement, where integrated bids reduce vendor management overhead for public works departments.
Global Tracer Wires Market Segmentation
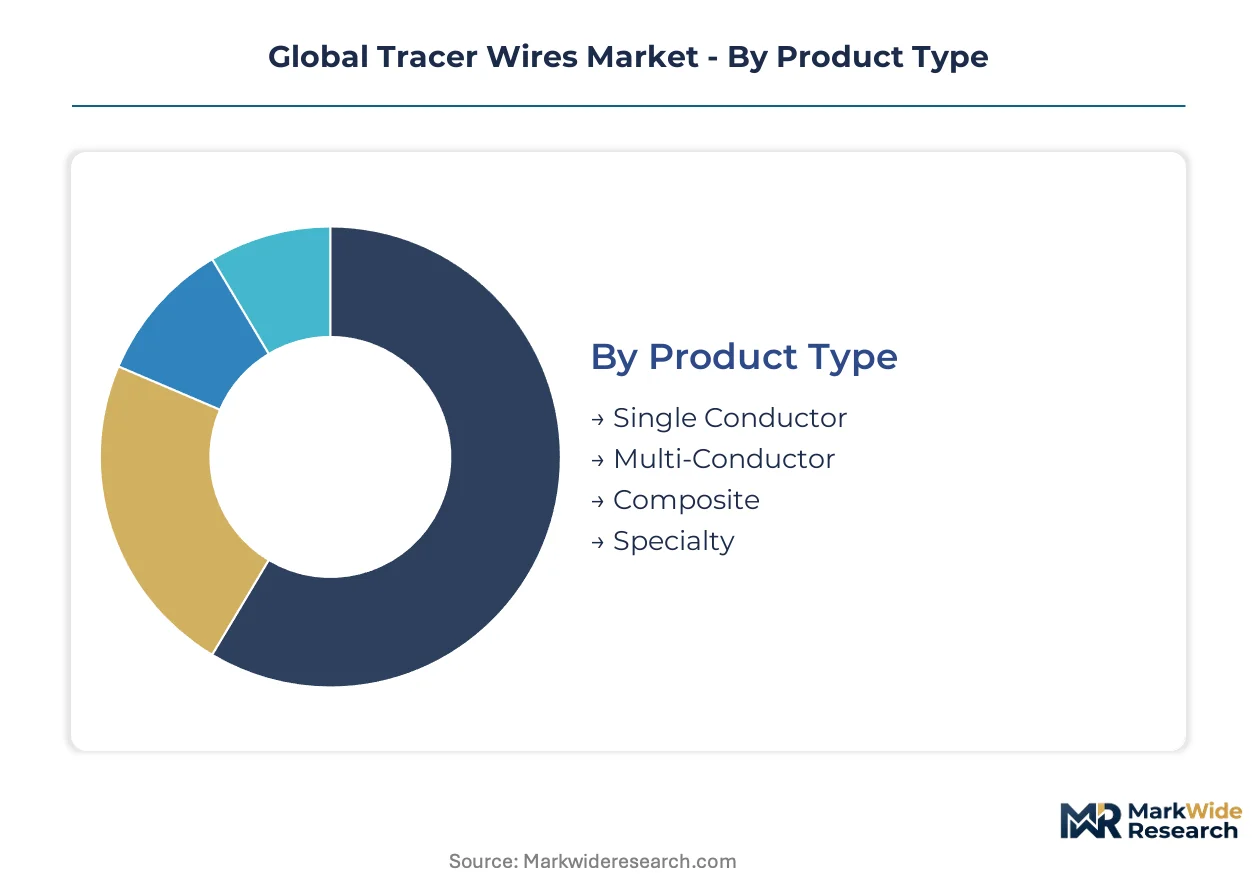
Tracer wire procurement patterns diverge sharply across installation complexity, soil chemistry, and regulatory exposure. Contractors select conductor configurations based on electromagnetic detection requirements, burial depth, and the cost of excavation failure.
Product Type:
Buyers differentiate primarily by installation labor cost versus signal reliability trade-offs.
- Single Conductor:One copper or aluminum core with high-density polyethylene jacketing dominates standard pipeline installations. Municipal contractors across Texas and Louisiana specify this grade for cost efficiency in straight-run gas distribution networks where single-frequency detection suffices.
- Multi-Conductor:Bundled configurations with isolated signal paths serve complex utility corridors. Telecommunications infrastructure in Germany's Ruhr industrial zone demands these variants to trace fiber-optic and power conduits simultaneously through dense underground networks.
- Composite:Hybrid designs blending conductive cores with aramid or fiberglass strength members resist mechanical stress in rocky soils.
- Specialty:Custom jacket compounds address extreme temperature or chemical exposure scenarios.
Single Conductor leads volumes today; Composite is gaining share fastest.
Material:
Conductivity requirements and corrosion risk determine metal selection against total installed cost pressure.
- Copper:Oxygen-free high-conductivity cores deliver superior signal propagation for long-distance pipeline tracing. PHMSA regulations for interstate transmission lines effectively mandate copper in US federally funded projects where detection reliability carries liability weight.
- Aluminum:Lighter cores with 61% copper conductivity suit cost-sensitive municipal water districts. Brazilian utilities specify aluminum for non-critical distribution networks where excavation frequency remains low.
- Stainless Steel:Corrosion-resistant cores survive coastal and high-salinity soils.
- Plastic:Non-metallic tracer elements serve electromagnetic-sensitive environments.
Copper dominates premium specifications; Aluminum is climbing the fastest in emerging markets.
Application:
Regulatory mandates and infrastructure replacement cycles create divergent specification intensity across utility sectors.
- Telecommunications:Dense fiber-optic deployments require precise lateral location to prevent backhoe strikes. 5G backhaul construction in South Korea drives multi-conductor procurement for simultaneous power and data cable tracing.
- Power Distribution:High-voltage underground circuits demand continuously traceable grounding systems. French grid operator RTE specifies tracer integration in new 63kV urban tunnel installations.
- Safety Systems:Emergency shutdown and leak detection networks require redundant signal paths.
- Heating:District energy and geothermal systems need corrosion-resistant conductors in high-moisture environments.
Telecommunications leads current procurement; Power Distribution shows the steepest expansion trajectory.
End User:
Contracting structure and technical capability separate price-sensitive volume buyers from specification-driven premium purchasers.
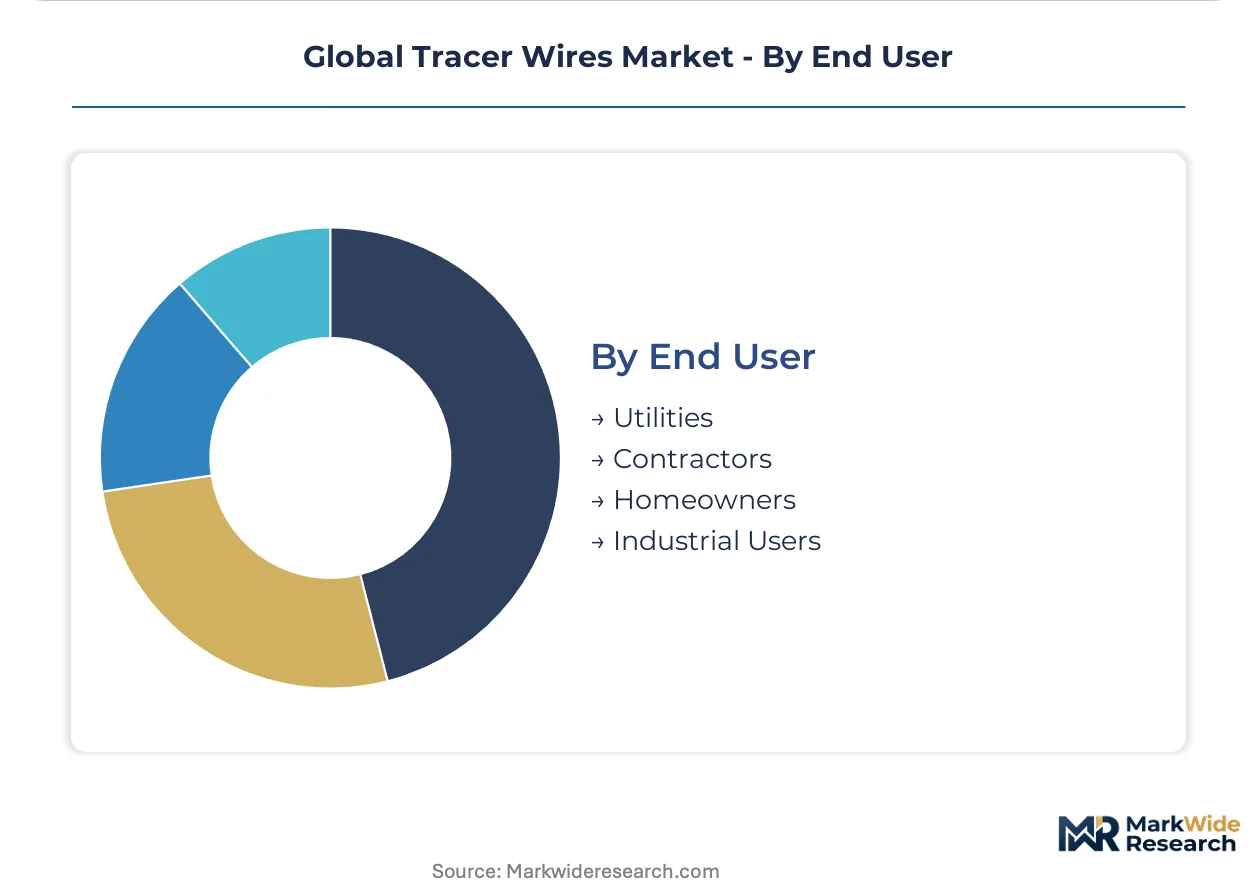
- Utilities:Vertically integrated network operators standardize tracer-wire specifications across multi-decade asset bases. Tokyo Electric Power Company mandates copper-core HDPE jacketing for all new 6.6kV distribution circuits to unify maintenance protocols.
- Contractors:Competitive bid environments drive material cost minimization within compliance boundaries. Australian civil contractors serving NBN fiber rollout projects bundle tracer-wire procurement with directional drilling services to capture margin.
- Homeowners:Residential propane and irrigation systems generate sporadic low-volume demand.
- Industrial Users:Petrochemical and mining operators specify heavy-duty composite variants for harsh soil conditions.
Utilities anchor specification standards; Contractors represent the most price-elastic demand pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German utility digitization programs demand higher specification intensity than Brazilian municipal contracts, reflecting divergent infrastructure investment cycles across tracer wire procurement geographies.
United States
PHMSA pipeline safety regulations mandate corrosion-resistant, continuously traceable infrastructure across interstate networks. The Infrastructure Investment and Jobs Act forces federally funded projects to source certified locator-wire systems. The Gulf Coast petrochemical corridor accelerates replacement of aging buried utility mapping systems.
Germany
Dense telecommunications corridors in the Ruhr industrial zone require multi-conductor configurations for simultaneous fiber-optic and power cable tracing. EMA CE marking requirements and ECHA REACH substance restrictions govern material composition for jacket compounds. Munich-based grid operators specify tracer integration in new urban tunnel installations.
China
Smart-city utility mapping mandates through SAMR's GB standards drive tracer-wire specification in new urban pipeline networks. Insulated-cable producers reposition manufacturing capacity toward tracer-wire grades. Yangtze River Delta municipal digitization programs concentrate procurement for underground infrastructure projects.
Brazil
Cost-sensitive municipal water districts specify aluminum-core conductors for non-critical distribution networks. The country's national infrastructure regulator shapes certification requirements for buried utility materials. São Paulo state utilities anchor procurement volume for regional pipeline construction.
South Korea
5G backhaul construction drives multi-conductor procurement for simultaneous power and data cable tracing. The national telecommunications regulator mandates precise lateral location standards to prevent excavation damage. Seoul metropolitan area fiber deployments concentrate specification intensity for complex utility corridors.
Global Tracer Wires Market Competitive Environment
US producers anchor the premium-tier specification market; Chinese manufacturers hold cost-competitive positions for emerging-market municipal contracts. The vendor base separates into three tiers: vertically integrated copper processors, specialized jacket-compound formulators, and regional cable fabricators serving localized procurement. Dominant competitive moves include backward integration into copper rod production and strategic partnerships with utility-locator equipment manufacturers.
Among US-based specialists, Copperhead Industries LLC and Southwire Company occupy positions in the integrated-manufacturing archetype, while Performance Wire and Cable exemplifies the formulation-specialist tier. These named entities represent the competitive spectrum from captive raw-material supply through differentiated polymer chemistry.
| Leading Market Players |
|---|
| Copperhead Industries LLC |
| AIM Utility Products |
| Tracer Wire Technologies, LLC |
| Pro-Line Safety Products Company |
| Nehring Electrical Works Company |
| Kris-Tech Wire |
| Performance Wire and Cable |
| Ramcorp Wire and Cable, Inc. |
| Southwire Company |
| Others |
Value Chain & Pricing Dynamics
Backward integration into copper rod production anchors both supply security and pricing power for North American tracer-wire specialists serving federally mandated pipeline projects. This captive supply structure insulates jacketed-cable manufacturers from London Metal Exchange volatility while compressing procurement cycles for PHMSA-certified installations.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade single-conductor products across Asia-Pacific municipal contracts. Three-tier pricing structure across premium, standard, and economy levels separates PHMSA-certified copper-core specifications from aluminum alternatives and uncertified imports. Cost compression in the economy tier intensifies because Chinese insulated-cable producers reposition manufacturing capacity toward tracer-wire grades. Municipal contractors in Brazil exhibit the highest price sensitivity, while US Gulf Coast petrochemical operators prioritize detection reliability over unit cost.
Supply Chain Analysis
Dual-sourcing qualification requirements from US pipeline operators mandate at least two approved jacket-compound suppliers per project, fragmenting raw material concentration. Geographic supply concentration centers on China for high-density polyethylene resin, the US for oxygen-free copper rod, and Germany for specialized multi-conductor extrusion equipment. Raw material dependencies draw from LME copper cathode, petrochemical-derived jacket polymers, and aramid fiber strength members. Single-source vulnerability persists in certified jacket-compound formulations meeting REACH substance restrictions. Distribution runs through direct OEM supply agreements for utilities and regional electrical distributors for contractor spot purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where PHMSA pipeline safety mandates create irreversible specification lock-in for corrosion-resistant, continuously traceable infrastructure.
For Market Incumbents: Acquire polymer strength-member production capabilities to capture composite tracer-wire growth in coastal and rocky soil applications. Aluminum core substitution in emerging markets threatens copper-dominant specifications; counter by deepening certification investment for PHMSA and SAMR GB standards to maintain premium positioning. Channel control through exclusive locator-equipment bundling consolidates contractor purchasing decisions against wire-only vendors. For New Entrants and Emerging Players: E-commerce procurement platforms serving Brazilian municipal water districts offer the most penetrable entry route for cost-optimized aluminum-core specifications. White-space targets include EPA Underground Injection Control Class VI well monitoring channels and South Korean 5G backhaul multi-conductor deployments. A specification-bundling go-to-market angle pairing conductor supply with electromagnetic detection training accelerates technical credibility acquisition. For Investors and Strategic Acquirers: Roll-up economics work for regional cable fabricators because multi-standard certification timelines create barriers that favor scaled testing infrastructure. The five-to-ten-year viability window hinges on smart-city utility mapping mandate expansion beyond current SAMR GB standard jurisdictions. Acquisition target archetypes include specialized jacket-compound formulators with REACH-compliant formulations. The signal to watch is EPA Underground Injection Control program expansion into carbon sequestration monitoring networks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Rod Production | Captive supply from rod to finished conductor insulates margin from LME volatility for PHMSA-certified producers. |
| Composite Material R&D Investment | Polymer strength-member blending opens harsh-soil applications previously closed to single-conductor designs in coastal zones. |
| REACH-Compliant Jacket Reformulation | Elimination of restricted phthalates preserves European market access against ECHA tightening thresholds. |
| Locator Equipment Bundling Partnerships | Integrated conductor-plus-detector packages displace wire-only vendors in North American municipal procurement. |
| SAMR GB Standards Pre-Certification | Early compliance with Chinese smart-city utility mapping mandates secures Yangtze River Delta pipeline construction allocation. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pipeline construction contractors, utility procurement managers, jacket-compound technical directors, and electromagnetic equipment specialists with secondary validation. Primary fieldwork drew from PHMSA regulatory filings, SAMR GB standard documentation, ECHA REACH substance restriction updates, and customs trade data for copper rod and insulated cable flows. Bottom-up project pipeline assessment and top-down infrastructure spending allocation triangulated market sizing across the analysis window.
Segment-weighting approaches modeled product type, material composition, application sector, and end-user contracting structure dimensions throughout the forecast period. CAGRs derived from regression against historical infrastructure replacement cycles and regulatory mandate implementation timelines. Industry-specific forecast inputs included petrochemical corridor age profiles, telecommunications fiber deployment schedules, and municipal digitization program budgets.
The model assumes a particular technology adoption path; alternative pathways for composite conductor-strength member architectures would alter the outlook if mechanical durability improvements accelerate beyond current signal-integrity trade-offs. Deviation in copper price volatility or REACH substance restriction expansion timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Welded Pipes Market
Pipes and Tubes
Stainless Steel Tank Container Market
Pipes and Tubes
Hydrogen Tube Skids Market
Pipes and Tubes
Europe Copper Pipes and Tubes Market
Pipes and Tubes
Compressed Air Pipe Market
Pipes and Tubes
Tapping Sleeves Market
Pipes and Tubes
Global CPVC Pipes and Fittings Market
Pipes and Tubes
GCC CPVC Pipes Market
Pipes and Tubes
Saudi Arabia PE Pipes Market
Pipes and Tubes
Multiflex Tubes Market
Pipes and Tubes
Polyethylene Pipes Market
Pipes and Tubes
Global Polyethylene Pipes and Fittings Market
Pipes and Tubes
Drum Funnel Market
Pipes and Tubes
US Cold Drawn Seamless Steel Pipes Market
Pipes and Tubes
Seamless Pipe Market
Pipes and Tubes
Global Polyolefin Pipes Market