
 Styrene Ethylene Butylene Styrene (SEBS) Market | 2026-2036
Styrene Ethylene Butylene Styrene (SEBS) Market Size, Share, and Industry Trends Forecast 2026-2036
Styrene Ethylene Butylene Styrene (SEBS) Market Analytics
Software-defined formulation services is pivoting how SEBS suppliers monetize technical relationships beyond resin volumes. Kraton Corporation leverages its hydrogenation technology leadership to command premium positions in medical and personal care segments. TSRC Corporation anchors its competitiveness through backward integration into butadiene feedstock and regional manufacturing scale across Asia.
Styrene Ethylene Butylene Styrene is a hydrogenated styrenic thermoplastic elastomer produced by catalytic hydrogenation of styrene-butadiene-styrene block copolymers, yielding a saturated midblock with Shore A hardness typically ranging from 30 to 95 and service temperatures between minus 60 and 110 degrees Celsius. Its primary industrial purpose centers on replacing vulcanized rubber and flexible PVC in applications requiring elasticity, UV stability, and processability via standard thermoplastic equipment. SEBS block copolymer formulations dominate volume consumption in adhesives and sealants where clarity and low melt viscosity command formulation preference. Medical devices represent the fastest-expanding application segment as healthcare OEMs phase out plasticized PVC and latex in fluid-contact components.
REACH registration requirements and EU MDR compliance are elevating testing burdens for European medical and consumer goods applications, while FDA biocompatibility standards govern US market access for device-grade SEBS compounds. China's GB standards and evolving SAMR polymer safety protocols are simultaneously reshaping import specifications and domestic production benchmarks. Stakeholders must monitor regulatory divergence between jurisdictions to avoid fragmented certification costs that erode margin pools in cross-border supply chains.
Market Dynamics
Medical device OEMs are phasing out plasticized PVC and latex in fluid-contact components, forcing SEBS compounders to recertify formulations against tightening biocompatibility standards while scaling hydrogenation capacity to meet specification-grade demand.
Growth Catalysts
- EU MDR compliance deadlines:European medical device manufacturers are accelerating SEBS adoption to replace legacy elastomers ahead of stricter clinical evidence requirements for permanent implant contact materials.
- China's hydrogenated styrenic block copolymer capacity expansion:Domestic polymer producers are scaling specialized SEBS production lines, reducing import dependency for high-hardness medical grades.
- Adhesive formulation shifts:Hot-melt pressure-sensitive adhesive manufacturers are specifying low-melt-viscosity SEBS grades to enable high-speed coating lines without thermal degradation.
Market Restraints
- Butadiene feedstock volatility:SEBS producers face margin compression when butadiene spot prices spike, as the hydrogenated midblock retains full exposure to cracker-derived C4 stream economics.
- Specialized hydrogenation catalyst scarcity:Noble metal catalyst supply concentrates with a limited supplier base, creating bottleneck risk for medical-grade SEBS batch certification.
- Thermoplastic polyurethane substitution:TPU compounders are capturing select wearable device applications through superior abrasion resistance and overmolding compatibility with polycarbonate housings.
Strategic Opportunities
- India's medical device PLI scheme:Domestic catheter and IV set manufacturers are qualifying SEBS tubing compounds to capture production-linked incentive benefits for import substitution.
- 3D-printed soft robotics:Extrusion-grade SEBS filaments are enabling programmable elastomer actuators for prosthetic and industrial gripper applications previously served by molded silicone.
- REACH-registered circular feedstocks:Pyrolysis-derived styrene streams are achieving certification for SEBS block copolymer synthesis, opening premium positioning for sustainability-mandated European personal care packaging.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization protocols for new SEBS grades extend qualification cycles to 18-24 months, freezing formulation iterations for medical OEMs.
- Compounder technical service bandwidth:Custom color-matching and hardness tuning for mid-sized medical device accounts strain application development teams at specialty distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Styrene Ethylene Butylene Styrene (SEBS) Market |
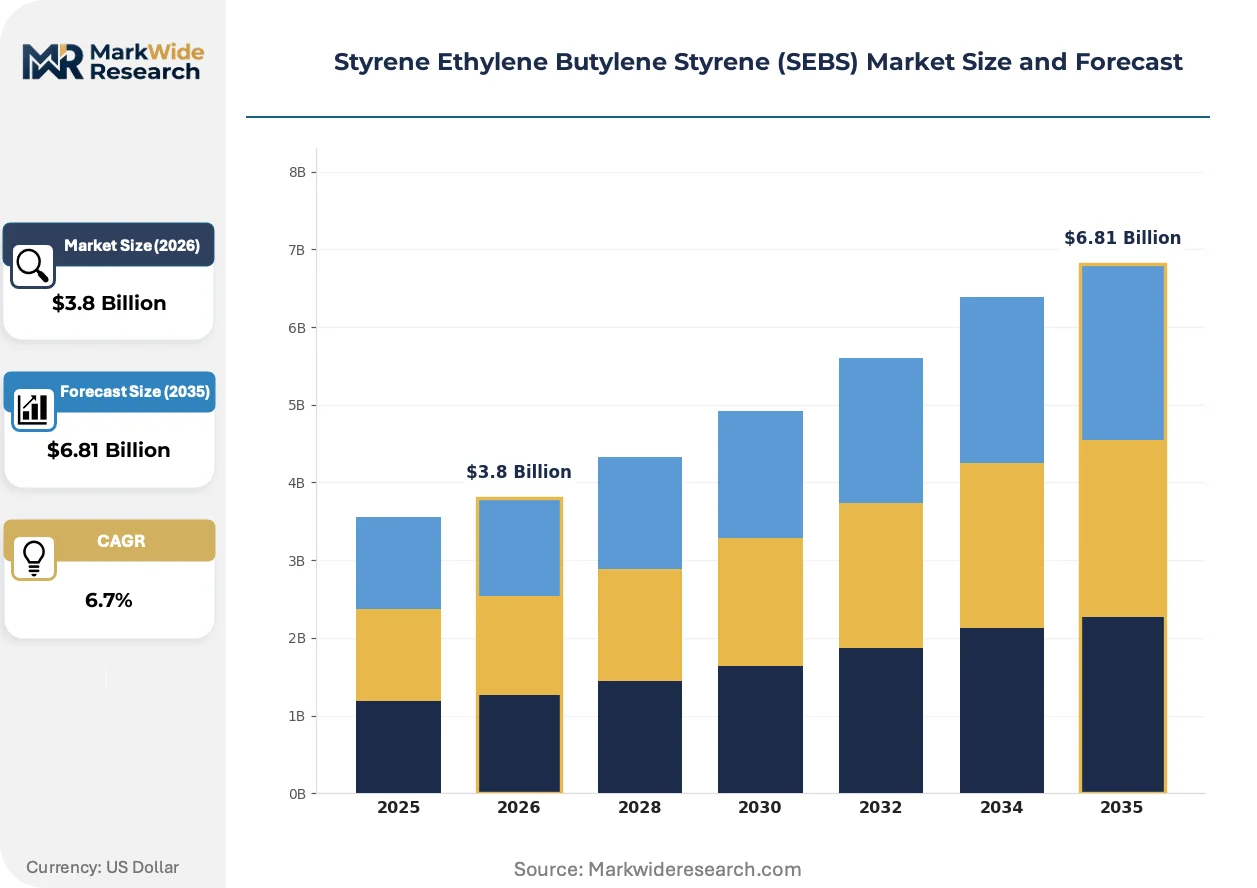
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SEBS Block Copolymer, SEBS Grafted Copolymer, SEBS Polymer Blends, SEBS Modified Composites Application: Adhesives, Sealants, Automotive Parts, Medical Devices End User: Automotive, Consumer Goods, Electronics, Healthcare Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Kraton Corporation, China Petrochemical Corporation, LCY Group, TSRC Corporation, KURARAY CO., LTD., Asahi Kasei Corporation, BASF SE, Versalis S.p.A., Dynasol Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Styrene Ethylene Butylene Styrene (SEBS) Market Evolving Landscape
Digital formulation platforms are compressing the SEBS compound development cycle from months to weeks, while regulatory divergence between FDA biocompatibility guidance and EU MDR technical documentation requirements is fragmenting certification pathways.
Reactive extrusion with in-situ silane grafting is converging with standard twin-screw compounding lines to produce moisture-crosslinkable SEBS grades. Wire and cable manufacturers in Korea and Japan are adopting these materials for flexible jacketing that survives autoclave sterilization cycles without plasticizer migration. The technology is converging with medical tubing extrusion to enable thin-wall catheters that maintain kink resistance at reduced durometer.
REACH Annex XIV authorization requirements for legacy phthalate plasticizers are accelerating SEBS displacement of flexible PVC in European consumer goods. Compounders must now maintain dual formulation portfolios: REACH-compliant grades for EU-bound production and cost-optimized alternatives for markets without equivalent restrictions. Personal care applicators and kitchen grip products represent the most affected categories, with brand owners mandating certified elastomer documentation for shelf placement.
Healthcare procurement departments are consolidating approved material lists to reduce supplier audit burdens, compressing the SEBS compounder landscape to those with dedicated medical device quality systems. Tier-one medical OEMs in the US and Germany now require ISO 13485 certification and dedicated clean compounding suites as table stakes for tubing and seal quotations. This concentration is squeezing regional compounders without capital to segregate medical-grade production infrastructure.
Styrene Ethylene Butylene Styrene (SEBS) Market Segmentation
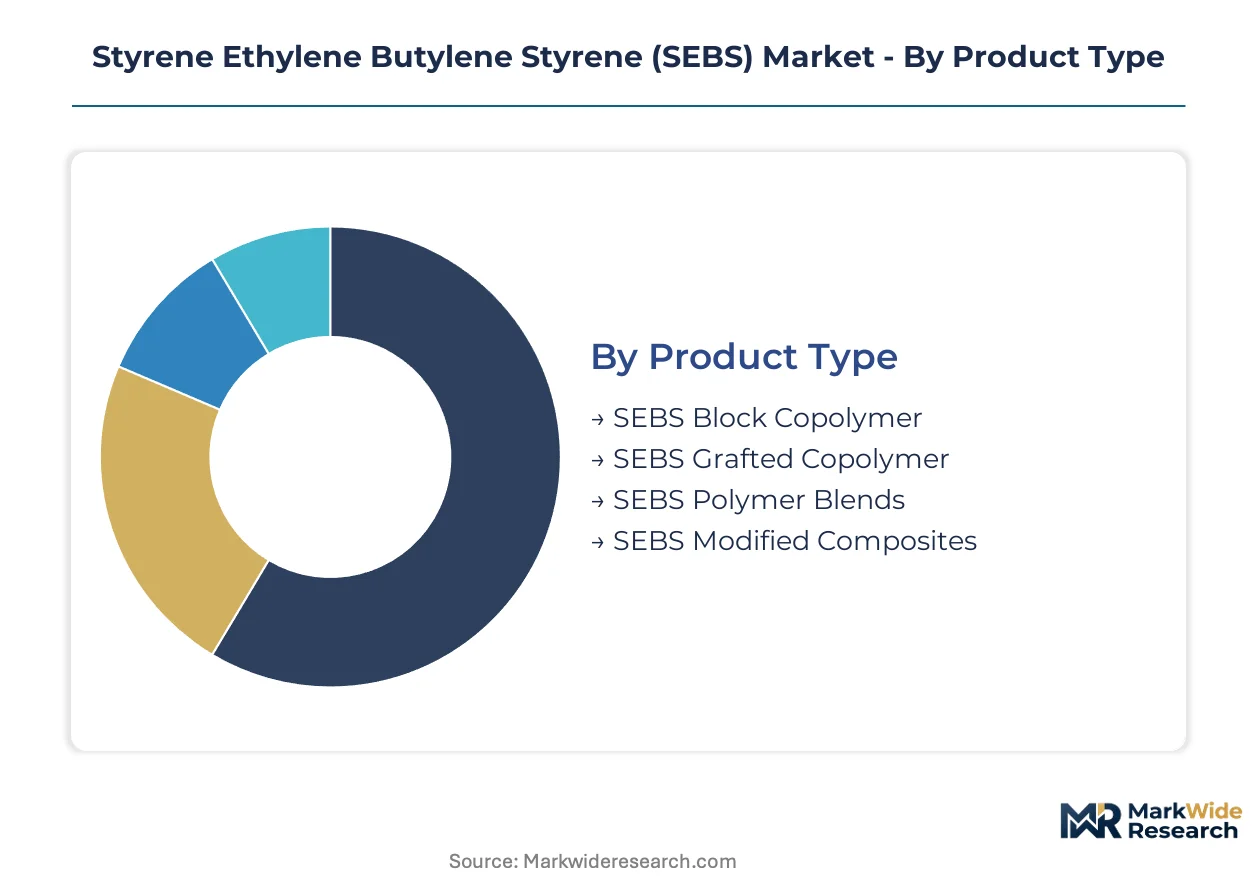
SEBS formulation diversity creates distinct margin pools across molecular architectures, while application-driven certification requirements fragment procurement patterns by end-use. Buyers prioritize hydrogenation grade, Shore hardness range, and regulatory documentation depth when selecting among chemically similar but functionally differentiated material offerings.
Product Type:
Cost tier determines specification flexibility — premium hydrogenation grades command dedicated production lines while commodity blends compete on volume throughput.
- SEBS Block Copolymer:Linear triblock architecture with saturated ethylene-butylene midblock delivers Shore A 30-95 hardness range and UV stability. Medical tubing manufacturers in Germany and the US specify this grade for ISO 10993-compliant fluid-contact components, absorbing 18-24 month qualification cycles to secure supply continuity.
- SEBS Grafted Copolymer:Functionalized variants with maleic anhydride or silane grafting enable moisture-crosslinking and polar substrate adhesion. Wire and cable jacketing producers in Korea and Japan adopt these materials for autoclave-resistant flexible insulation, displacing peroxide-cured EPDM in healthcare facility infrastructure.
- SEBS Polymer Blends:Compounded with polyolefins or oils for cost-optimized Shore A 50-70 grades serving consumer grip applications.
- SEBS Modified Composites:Mineral-filled or fiber-reinforced formulations targeting structural automotive interior parts with reduced fogging.
Volume sits with SEBS Block Copolymer; growth tilts toward SEBS Grafted Copolymer.
Application:
Certification burden intensity separates segments — medical device applications require batch-level biocompatibility documentation while adhesives prioritize melt viscosity consistency.
- Adhesives:Low-melt-viscosity SEBS grades enable high-speed hot-melt coating lines without thermal degradation. Pressure-sensitive adhesive manufacturers specify these formulations for tape and label applications where clarity and tack retention command formulation preference.
- Medical Devices:Fluid-contact tubing, seals, and gaskets represent the steepest expansion trajectory as healthcare OEMs phase out plasticized PVC and latex. FDA biocompatibility guidance and EU MDR technical documentation requirements fragment certification pathways, freezing formulation iterations for 18-24 month ISO 10993 protocol completion.
- Sealants:Construction and automotive gap-filling applications demand UV-stable elastomeric recovery.
- Automotive Parts:Interior soft-touch surfaces and weatherstrip profiles compete with TPV and TPU alternatives.
Adhesives anchor current volume; Medical Devices capture the steepest expansion trajectory.
End User:
Procurement sophistication varies — healthcare buyers mandate ISO 13485 certification while automotive purchasers prioritize just-in-time delivery reliability.
- Healthcare:Catheter, IV set, and respiratory device manufacturers consolidate approved material lists to reduce supplier audit burdens. Tier-one OEMs in the US and Germany require dedicated clean compounding suites as table stakes for tubing quotations, squeezing regional compounders without segregated medical-grade infrastructure.
- Automotive:Interior soft-touch components and sealing systems specify SEBS for UV stability and processability via standard thermoplastic equipment. REACH Annex XIV phthalate restrictions are accelerating displacement of flexible PVC in European consumer-facing cabin elements.
- Consumer Goods:Personal care applicators and kitchen grips face brand-owner mandates for certified elastomer documentation.
- Electronics:Wearable device straps and protective cases compete with TPU for abrasion resistance requirements.
Automotive holds installed volume; Healthcare gains share fastest.
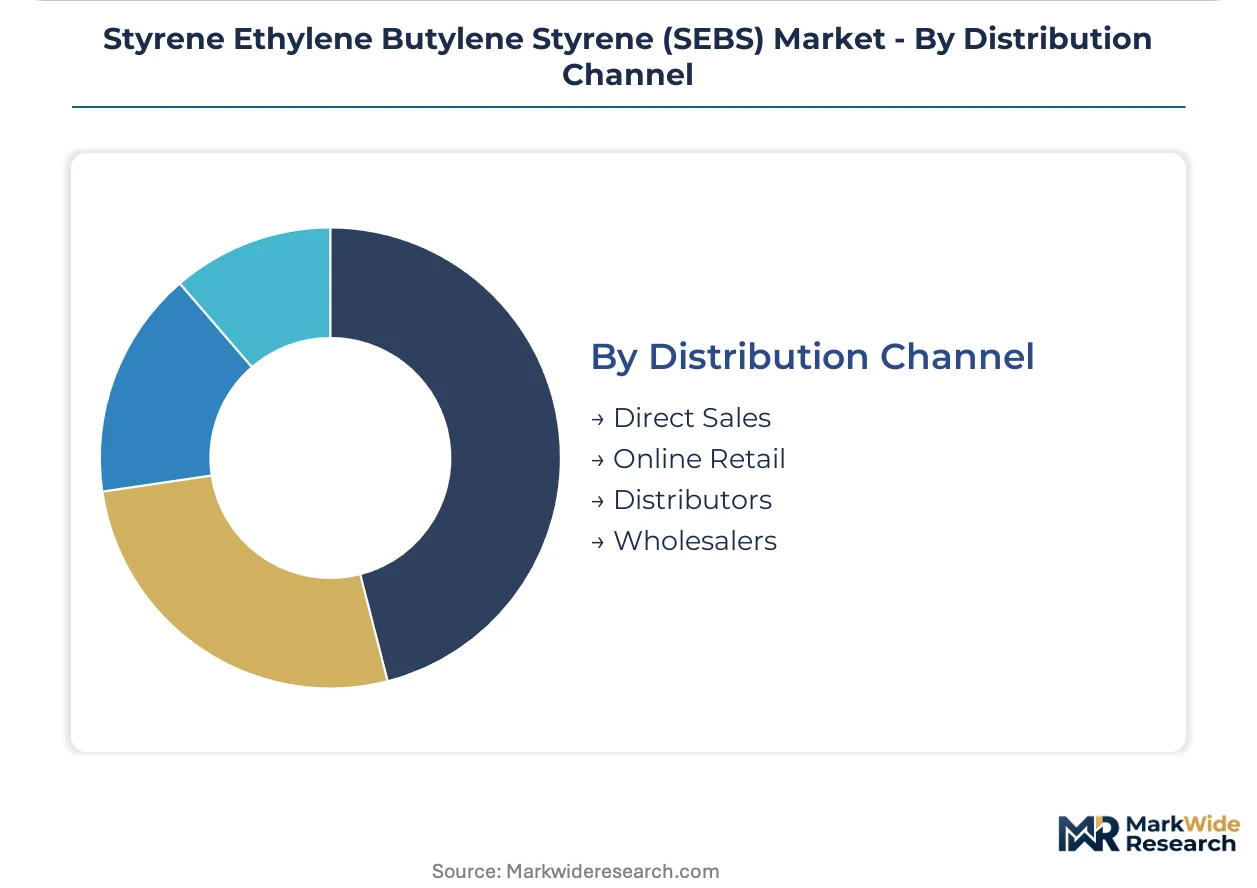
Distribution Channel:
Customer scale and technical service requirements determine channel selection — large OEMs demand direct formulation support while mid-tier buyers rely on distributor inventory buffers.
- Direct Sales:Medical device and automotive OEMs with annual volume commitments receive dedicated technical service teams for color-matching and hardness tuning. Kraton Corporation and TSRC Corporation leverage direct relationships to monetize formulation expertise beyond resin volumes.
- Distributors:Regional compounders and mid-sized processors access inventory pooling and credit terms through specialty chemical distributors. Custom color-matching and hardness tuning for mid-sized medical device accounts strain application development bandwidth at these intermediaries.
- Online Retail:Small-batch extrusion and 3D printing filament buyers procure sample quantities and technical datasheets digitally.
- Wholesalers:Commodity-grade SEBS blends for non-critical consumer applications flow through volume-oriented intermediaries.
Direct Sales commands premium segment value; Distributors handle fragmented mid-tier demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors hydrogenated styrenic block copolymer capacity expansion as domestic polymer producers scale medical-grade SEBS production lines to reduce import dependency for high-hardness specifications.
China
Domestic catheter and IV set manufacturers in Jiangsu and Zhejiang provinces are qualifying SEBS tubing compounds under SAMR polymer safety protocols. GB standards for medical-grade elastomers are tightening import specifications while Yangtze River Delta chemical parks concentrate hydrogenation capacity expansion. Shanghai and Ningbo port clusters handle bulk styrene feedstock arrivals for block copolymer synthesis.
Germany
Medical device OEMs in Baden-Württemberg are accelerating SEBS adoption to replace plasticized PVC ahead of EU MDR clinical evidence deadlines. ECHA REACH Annex XIV authorization requirements for phthalate plasticizers are displacing flexible PVC in consumer goods. The Rhine-Main industrial corridor hosts compounders with dedicated clean suites for ISO 13485-certified medical grade production.
United States
FDA biocompatibility guidance is governing market access for device-grade SEBS compounds in fluid-contact tubing and seals. Healthcare procurement departments in Minnesota and Massachusetts are consolidating approved material lists to reduce supplier audit burdens. The Gulf Coast petrochemical corridor supplies butadiene feedstock for hydrogenated midblock production.
Japan
Wire and cable manufacturers in Osaka and Nagoya industrial zones are adopting moisture-crosslinkable SEBS grades for autoclave-resistant flexible jacketing. METI industrial standards are converging with medical device quality protocols for elastomer certification. The Chubu region maintains specialized hydrogenation catalyst supply relationships for batch-level medical compound verification.
India
Domestic catheter manufacturers in Maharashtra and Gujarat are qualifying SEBS formulations to capture PLI scheme production-linked incentives for import substitution. CDSCO medical device regulations are elevating testing burdens for European and US-imported elastomer compounds. The Mumbai-Pune industrial corridor is emerging as a compounding hub for mid-tier medical device accounts.
Styrene Ethylene Butylene Styrene (SEBS) Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the SEBS value chain. The market structure concentrates hydrogenation technology leadership among integrated petrochemical groups while regional compounders fragment around application-specific formulation services. Three archetypes dominate: integrated upstream producers with captive butadiene supply, specialized hydrogenation technology licensors, and downstream compounders with medical-grade quality systems. Competitive moves center on backward integration into butadiene feedstock and geographic expansion of medical-certified compounding capacity.
Within the integrated producer tier, Kraton Corporation and TSRC Corporation exemplify archetypes built on hydrogenation technology control and regional manufacturing scale respectively. Among Asia-Pacific-based petrochemical groups, China Petrochemical Corporation and LCY Group occupy positions anchored by domestic market demand concentration. Kuraray and Asahi Kasei represent Japanese specialists with historical strength in precision hydrogenation for specification-grade medical applications. These named entities serve as structural anchors for understanding how technology access, feedstock position, and regulatory certification depth stratify competitive positioning across the SEBS market.
| Leading Market Players |
|---|
| Kraton Corporation |
| China Petrochemical Corporation |
| LCY Group |
| TSRC Corporation |
| KURARAY CO., LTD. |
| Asahi Kasei Corporation |
| BASF SE |
| Versalis S.p.A. |
| Dynasol Group |
| Others |
Value Network & Pricing Analysis
Catalytic hydrogenation technology upgrades are simultaneously compressing production economics and concentrating supply among producers with proprietary noble-metal catalyst access. Medical-grade SEBS batch certification costs now stratify pricing power between integrated hydrogenation specialists and regional compounders lacking dedicated clean-suite infrastructure.
Pricing Analysis
ISO 10993 biocompatibility documentation anchors value-based pricing for medical device-grade SEBS compounds. Three-tier pricing structure across medical-certified, industrial-specification, and commodity-blend grades reflects hydrogenation completeness and regulatory file depth. Pricing pressure stems from butadiene feedstock volatility spilling into medical-grade margins. Small-batch medical device accounts exhibit highest price sensitivity; tier-one catheter OEMs with volume commitments absorb premium positioning for supply security.
Supply Chain Analysis
Scrap SEBS reprocessing and pyrolysis-derived styrene recovery flows are emerging as secondary feedstock channels for circular-grade production. China, South Korea, and Germany concentrate hydrogenation capacity and medical-grade compounding infrastructure. Butadiene monomer, noble-metal catalysts, and hydrogen supply constitute critical input dependencies. Single-source vulnerability concentrates in specialized hydrogenation catalyst suppliers. Distribution runs through direct technical-service relationships for medical OEMs and specialty chemical distributors for mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR clinical evidence requirements and FDA biocompatibility guidance are erecting compliance cost barriers that favor incumbent compounders with amortized certification investments. This cost-of-compliance dynamic protects qualified suppliers from price-based disruption.
For Market Incumbents: Deploy backward integration into butadiene feedstock to buffer margin compression from C4 stream volatility. Expand medical-certified compounding capacity in the Yangtze River Delta to capture China's import substitution trajectory. TPU compounders threaten wearable device applications through superior polycarbonate overmolding compatibility. For New Entrants and Emerging Players: The mid-tier pricing gap between Kraton-premium medical grades and commodity Asian blends creates entry space for ISO 13485-certified regional compounders. India's PLI scheme for catheter manufacturing offers the most penetrable geography for qualified SEBS tubing supply. Target domestic medical device OEMs in Maharashtra and Gujarat with technical service partnerships rather than volume commodity plays. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty chemical conglomerates seeking hydrogenation technology platforms and medical-grade quality systems. Five-to-ten-year viability hinges on regulatory certification depth rather than scale economics alone. Watch for SAMR polymer safety protocol finalization as inflection signal for China market access restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butadiene Feedstock | Captive C4 supply buffers margin compression from cracker economics volatility. |
| Medical-Grade Clean Suite Certification | ISO 13485 infrastructure qualifies compounders for tier-one catheter OEM supplier lists. |
| Hydrogenation Catalyst Supply Agreement | Long-term noble metal access secures batch certification continuity for specification-grade production. |
| Regional Compounding Hub Expansion | Yangtze River Delta and Mumbai-Pune corridors capture medical device manufacturing migration. |
| Circular Feedstock Certification | REACH-registered pyrolysis-derived styrene opens premium positioning for sustainability-mandated European personal care packaging. |
Research Methodology
Multi-period observation of hydrogenation capacity additions, medical device OEM supplier qualification timelines, and butadiene contract pricing anchored the trend analysis, supplemented by interviews with SEBS plant managers, medical device procurement leads, specialty chemical distribution partners, and hydrogenation R&D directors. Secondary validation drew from customs trade data, Cefic polymer reports, FDA 510(k) filings referencing SEBS materials, and SEC disclosures from listed petrochemical groups. Bottom-up volume modeling triangulated against top-down market sizing across product architectures.
Segment-weighting applied hydrogenation grade, Shore hardness specification, and end-use certification intensity as primary dimensions across the analysis window. CAGRs derived from fitted growth curves calibrated to medical device OEM phase-out schedules for plasticized PVC and latex. Forecast inputs incorporated SAMR protocol evolution timelines, EU MDR transition deadlines, and India's PLI scheme disbursement trajectories.
Inputs from hydrogenation technology licensors and medical compounder quality systems were available through the study window; gaps in real-time butadiene spot price correlation with medical-grade contract pricing introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and OEM consolidation patterns. Practitioners should monitor ECHA REACH Annex XIV authorization expansion and FDA guidance updates on medical-grade elastomer biocompatibility for early signals of certification burden shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Polyolefin Elastomer Market
Elastomeric Membrane
Hot Cast Elastomers Market
Elastomeric Membrane
Elastomeric Foam Insulation Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
Thermoplastic Polyester Elastomer Market
Elastomeric Membrane
Polydimethylsiloxane (PDMS) Market
Elastomeric Membrane
Ethylene Propylene Elastomers Market
Elastomeric Membrane
Ethylene Propylene Diene Monomer(EPDM) Market
Elastomeric Membrane
North America Performance Elastomer Market
Elastomeric Membrane
UV Stabilized Thermoplastic Elastomer Market
Elastomeric Membrane
Ultra-Soft Thermoplastic Elastomer Market
Elastomeric Membrane
Europe Single-Ply Membrane Market
Elastomeric Membrane
Modified Silicone Fluids Market
Elastomeric Membrane
Global Fluoroelastomers Market
Elastomeric Membrane
Elastomeric Polyolefins Market
Elastomeric Membrane
Global Elastomeric Sealants Market