
 Middle East and Africa Biomedical Sensors Market | 2026-2036
Middle East and Africa Biomedical Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Biomedical Sensors Market Foresight
The capability gap between integrated device manufacturers and component assemblers is collapsing across the Middle East and Africa biomedical sensors landscape. Medtronic leverages its end-to-end manufacturing footprint to dominate high-margin implantable sensor categories in Gulf markets. Abbott Laboratories anchors its regional position through deep channel partnerships with tertiary hospital networks in South Africa and the UAE. Texas Instruments competes on semiconductor cost curves, supplying analog front-ends to regional OEMs building non-invasive monitoring devices.
Biomedical sensors are transducers that convert physiological signals—electrical, optical, chemical, or mechanical—into quantifiable data streams for clinical decision-making, typically operating across detection ranges from millivolt bio-potentials to pico-ampere ionic currents. These devices serve primary commercial purposes in continuous patient monitoring, closed-loop drug delivery, and point-of-care diagnostics where real-time physiological feedback reduces intervention latency. Wearable sensors lead volume deployment in home healthcare settings across the region, while implantable sensors command premium pricing in cardiac and neurological applications. Optical technology platforms are gaining fastest in diagnostic laboratories, displacing electrochemical methods in glucose and oxygen saturation measurement.
Saudi Food and Drug Authority and South African Health Products Regulatory Authority govern device registration, clinical evidence requirements, and post-market surveillance across the two largest national markets. CE marking under EU MDR remains a de facto entry standard for imported devices, even as both regulators develop localized conformity assessment pathways. Stakeholders must monitor how Gulf standardization bodies harmonize electromagnetic compatibility and biocompatibility testing protocols, as divergence would fragment procurement specifications and raise compliance costs for multi-country suppliers.
Market Dynamics
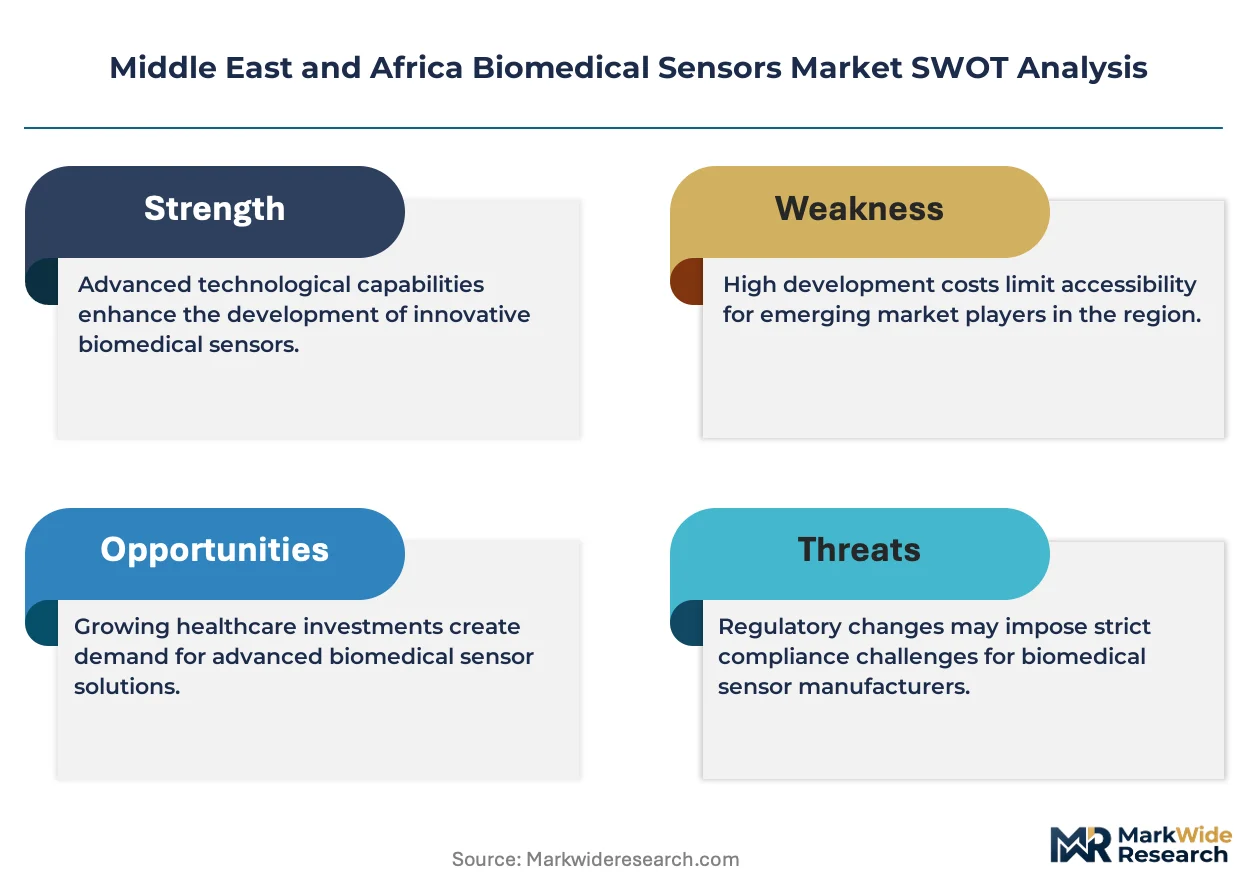
Hospital procurement consolidation across Gulf Cooperation Council states is compressing vendor margins while elevating technical compliance requirements, forcing sensor suppliers to embed regulatory certification costs directly into product development cycles.
Growth Catalysts
- Vision 2030 Health Privatization:Saudi Arabia's hospital privatization program mandates remote patient monitoring infrastructure in all new tertiary facilities, creating dedicated procurement channels for connected biometric devices.
- SAHPRA Electromagnetic Compatibility Enforcement:South Africa's tightened EMC standards for imported medical electronics are accelerating distributor migration toward certified OEM partnerships with pre-validated component architectures.
- Optical Platform Advancement:Photoplethysmography and near-infrared spectroscopy methods are expanding from pulse oximetry into continuous glucose and hydration monitoring applications.
Market Restraints
- Semiconductor Input Volatility:Analog front-end chip supply from East Asian foundries experiences price swings that compress margins for regional non-invasive monitor assemblers.
- Biocompatibility Testing Fragmentation:Divergent Gulf standardization protocols for ISO 10993 compliance raise per-market registration costs for multi-country suppliers.
- Implantable Battery Limitations:Energy density constraints in biocompatible power cells restrict continuous monitoring duration for subcutaneous glucose and cardiac sensors.
Strategic Opportunities
- Home Healthcare Channel Expansion:Retail pharmacy chains in Egypt and Nigeria are building direct-to-consumer distribution for wearable vital sign monitors, bypassing hospital procurement.
- AI-Enabled Predictive Diagnostics:Machine learning inference at the sensor edge converges with low-power Bluetooth Low Energy transmission to enable pre-symptomatic arrhythmia detection.
- Local Manufacturing Incentives:Saudi Industrial Development Fund financing for medical device production creates captive supply opportunities for sensor module assembly within the Kingdom.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Clinical instrumentation design expertise concentrates in South Africa and the UAE, leaving other markets dependent on expatriate technical support.
- MDR Transition Certification Backlogs:EU MDR technical documentation requirements are extending CE marking timelines for regional distributors, delaying product launches.
- Legacy Hospital IT Integration:HL7 FHIR interoperability gaps between new wireless sensors and existing electronic health record systems in public hospitals complicate deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Biomedical Sensors Market |
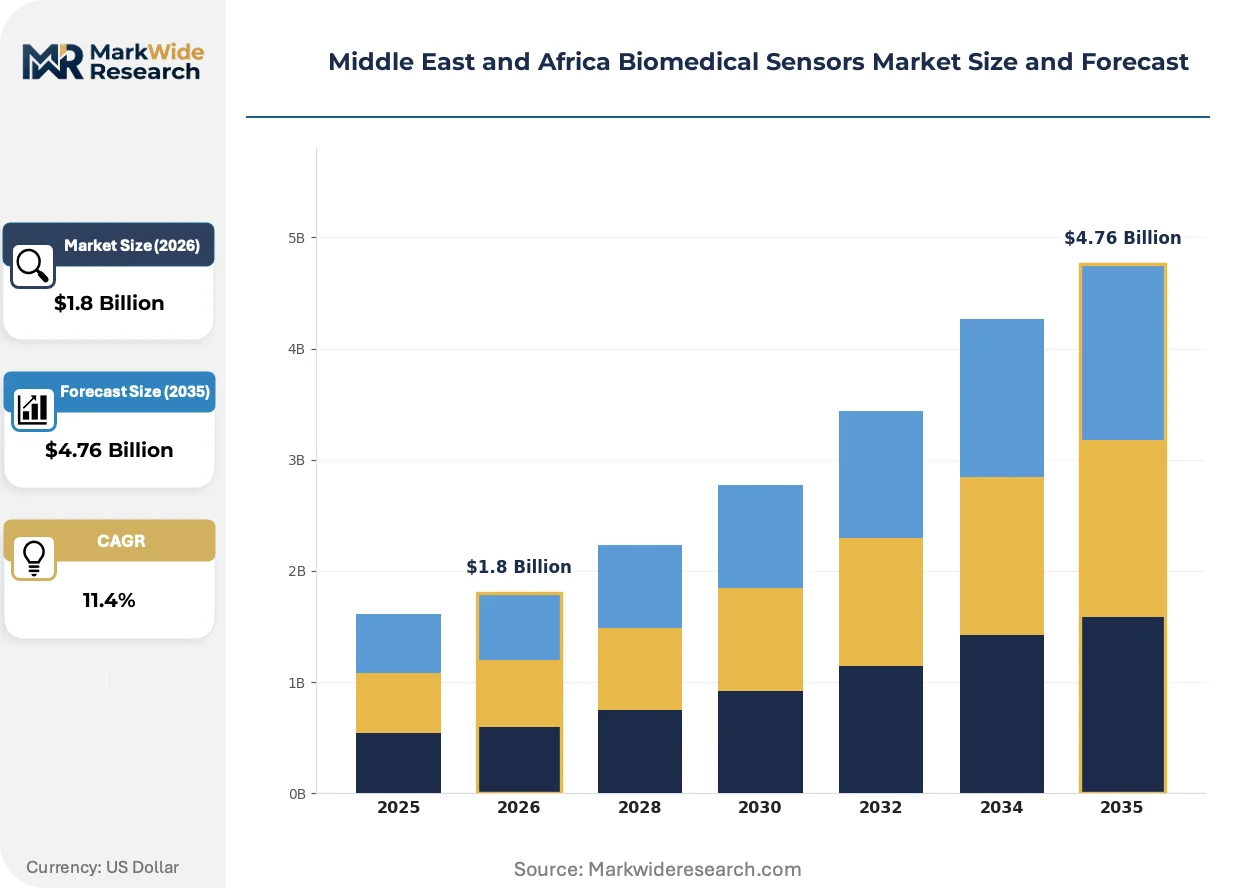
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Implantable Sensors, Invasive Sensors, Non-Invasive Sensors Technology: Optical, Piezoelectric, Electromechanical, Chemical End User: Hospitals, Diagnostic Laboratories, Research Institutions, Home Healthcare Application: Patient Monitoring, Drug Delivery, Diagnostics, Fitness Tracking |
| Companies Covered | Medtronic, Abbott Laboratories, GE Healthcare, Siemens Healthineers, Analog Devices, Inc., Honeywell International Inc., NXP Semiconductors N.V., TE Connectivity Ltd., Texas Instruments Incorporated, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Biomedical Sensors Market Shifts & Advancements
Continuous glucose monitoring architectures are migrating from factory-calibrated to user-calibration-free systems, while regulatory bodies across the Middle East and Africa accelerate localized conformity assessment pathways to reduce import dependency.
Photoplethysmography-based blood pressure estimation is displacing traditional cuff-based sphygmomanometry in ambulatory care settings across tertiary hospital networks in the UAE and Saudi Arabia. Cardiology departments are adopting these optical wrist-worn devices for post-operative hypertension surveillance. The technology is displacing pneumatic measurement modules and compressing the addressable market for conventional cuff manufacturers.
CE marking under EU MDR remains the de facto entry standard for imported biomedical sensors, even as Saudi Food and Drug Authority and South African Health Products Regulatory Authority develop localized conformity assessment pathways. This dual-track compliance environment raises documentation burdens for suppliers serving both Gulf and Sub-Saharan markets. Diagnostic laboratory equipment manufacturers are responding by pre-certifying optical glucose analyzers to both EU MDR and emerging national standards simultaneously.
Hospital procurement committees in the Gulf are unbundling sensor hardware from proprietary software ecosystems, demanding open API access for electronic health record integration. This specification shift disrupts integrated device manufacturers who previously locked customers into closed monitoring platforms. The pattern is most visible in Saudi Arabia's National Unified Procurement Company tenders, where interoperability clauses now outweigh brand preference in vendor selection criteria.
Middle East and Africa Biomedical Sensors Market Segmentation
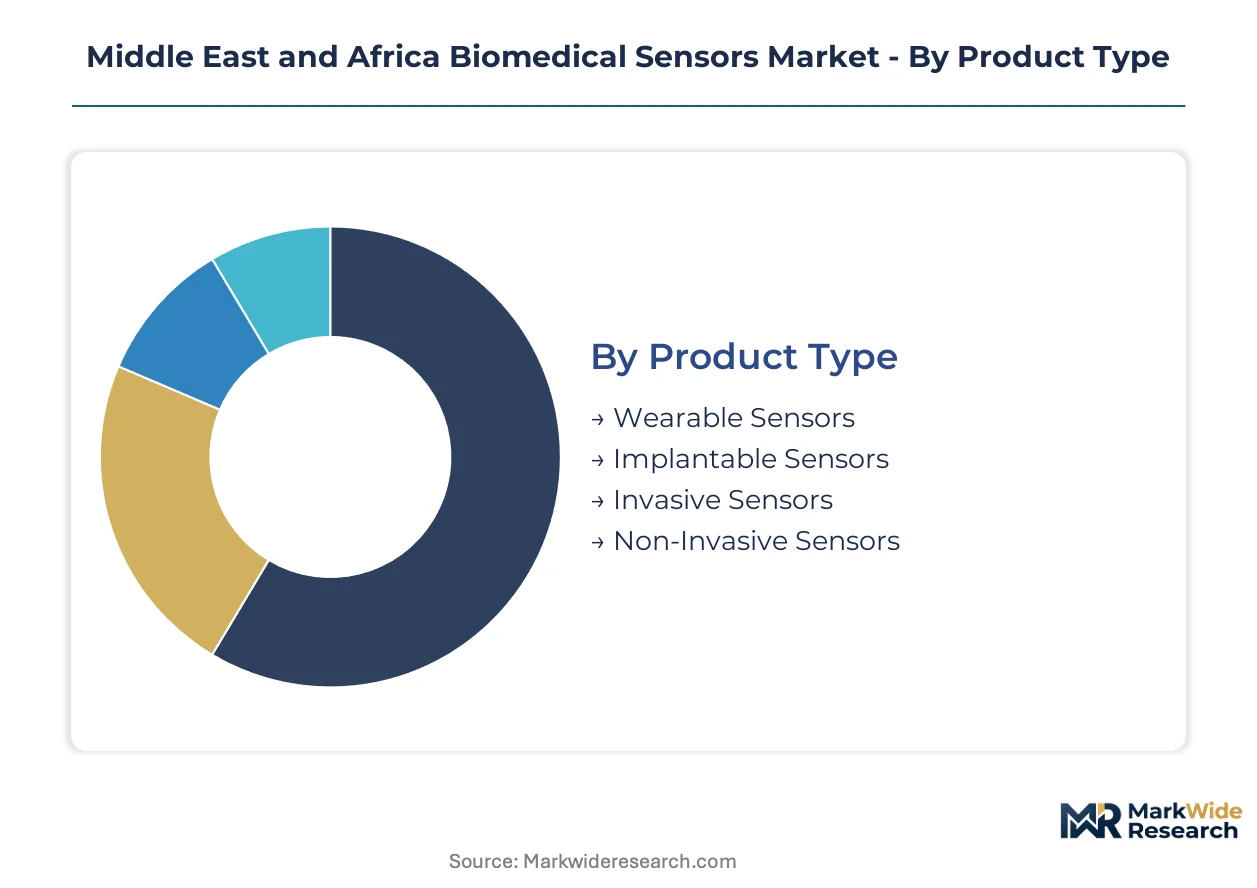
Biomedical sensor procurement across the Middle East and Africa fragments across four intersecting dimensions: product form factor, underlying transduction principle, care setting, and clinical use case. Regulatory pathways from SFDA and SAHPRA apply differentially across these boundaries, shaping vendor certification strategies and distributor specialization.
Product Type:
SFDA registration timelines diverge sharply between externally worn and implanted devices, with biocompatibility documentation requirements scaling with patient contact duration and invasiveness level.
- Wearable Sensors:Photoplethysmography and accelerometer-based devices dominate home healthcare channels across Saudi Arabia and the UAE. Retail pharmacy networks in Egypt and Nigeria are building direct-to-consumer distribution for wrist-worn vital sign monitors, bypassing hospital procurement committees entirely.
- Implantable Sensors:Cardiac pacemakers and continuous glucose monitors require ISO 14155 clinical evidence packages for SFDA approval. Abbott Laboratories and Medtronic leverage pre-validated biocompatibility portfolios to compress registration timelines against regional competitors lacking implantable track records.
- Invasive Sensors:Catheter-mounted pressure and temperature transducers serve interventional cardiology suites in tertiary hospital networks. Sterilization validation protocols under SAHPRA's tightened EMC frameworks extend distributor onboarding cycles.
- Non-Invasive Sensors:Surface electrodes and optical probes for pulse oximetry and ECG monitoring. Texas Instruments supplies analog front-end semiconductors to regional OEMs assembling these devices for price-sensitive procurement tenders.
Established volume favors wearable sensors; emerging adoption favors implantable sensors.
Technology:
Transduction method determines semiconductor input requirements, analog front-end complexity, and susceptibility to Gulf electromagnetic interference standards.
- Optical:Photoplethysmography and near-infrared spectroscopy platforms are expanding from pulse oximetry into continuous glucose and hydration monitoring. Diagnostic laboratories across the UAE are displacing electrochemical analyzers with optical glucose measurement systems.
- Piezoelectric:Ceramic and polymer transducers for pressure and vibration sensing in patient monitoring applications. Demand concentrates in cardiac catheterization laboratories requiring high-frequency response characteristics.
- Electromechanical:Strain gauges and capacitive sensors for force and displacement measurement. These devices face margin pressure from semiconductor input volatility affecting regional assembly operations.
- Chemical:Ion-selective electrodes and enzymatic biosensors for blood gas and metabolite detection. SAHPRA's electromagnetic compatibility enforcement is pushing distributors toward certified OEM partnerships with pre-validated electrochemical architectures.
Optical platforms are gaining share fastest; electrochemical methods retain installed base in legacy laboratory equipment.
End User:
Procurement authority and technical specification complexity vary dramatically across institutional buyer types, from consolidated Gulf hospital networks to fragmented home healthcare consumers.
- Hospitals:Tertiary facilities across the Gulf Cooperation Council states are consolidating vendor relationships and demanding open API access for electronic health record integration. Saudi Arabia's National Unified Procurement Company tenders now weight interoperability clauses above brand preference.
- Diagnostic Laboratories:Centralized testing facilities in South Africa and the UAE drive demand for high-throughput optical analyzers. These buyers pre-certify equipment to both EU MDR and emerging national standards simultaneously.
- Research Institutions:Academic medical centers and clinical trial sites require customizable sensor configurations with raw data output capabilities. Procurement volumes remain limited but carry premium pricing for technical support.
- Home Healthcare:Retail channels in Egypt and Nigeria are expanding distribution for consumer-facing wearable monitors. Vision 2030 health privatization in Saudi Arabia is creating dedicated infrastructure for remote patient monitoring outside hospital walls.
Hospital procurement commands revenue concentration; home healthcare channels are expanding most quickly.
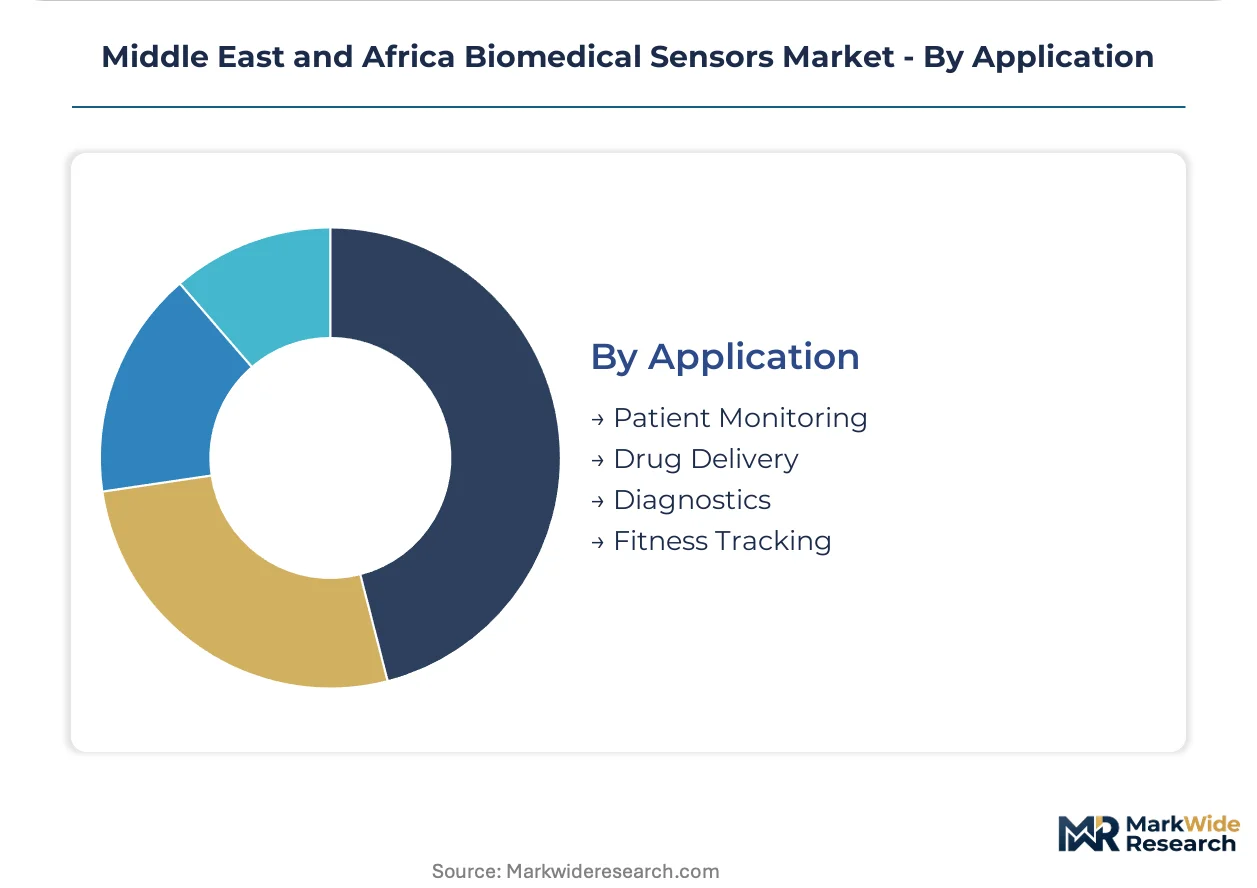
Application:
Clinical outcome requirements and reimbursement pathways shape sensor performance specifications and pricing tolerance across use cases.
- Patient Monitoring:Continuous vital sign surveillance in intensive care and post-operative settings. Photoplethysmography-based blood pressure estimation is displacing pneumatic cuff modules in ambulatory care across tertiary networks in the UAE and Saudi Arabia.
- Drug Delivery:Closed-loop insulin pumps and infusion systems with integrated glucose sensing. Factory-calibrated to user-calibration-free system migration is reshaping competitive requirements.
- Diagnostics:Point-of-care testing devices for glucose, oxygen saturation, and cardiac markers. Optical platforms are displacing electrochemical methods in laboratory and near-patient settings.
- Fitness Tracking:Consumer wellness devices with limited clinical validation requirements. These products bypass SFDA medical device registration through wellness device classification loopholes.
Patient monitoring anchors installed value; diagnostics applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for finished biomedical sensors exceeds domestic manufacturing capacity across most Middle East and Africa markets, though Gulf states are narrowing this gap through localization incentives. Saudi Arabia and the UAE currently account for the largest share of regional device imports, while South Africa maintains the continent's most developed regulatory infrastructure for medical electronics.
Saudi Arabia
Vision 2030 health privatization is mandating remote patient monitoring infrastructure in all new tertiary facilities, creating dedicated procurement channels for connected biometric devices. SFDA registration timelines for implantable devices now require ISO 14155 clinical evidence packages, compressing market entry for uncertified suppliers. Riyadh's King Faisal Specialist Hospital anchors demand for cardiac and neurological implantable sensors, with procurement committees prioritizing open API interoperability over brand loyalty.
United Arab Emirates
Tertiary hospital networks in Dubai and Abu Dhabi are consolidating vendor relationships and demanding unbundled sensor hardware with proprietary software ecosystem access. MOHAP's medical device registration framework maintains alignment with EU MDR standards while developing localized conformity assessment pathways. Dubai Healthcare City clusters diagnostic laboratory equipment manufacturers pre-certifying optical glucose analyzers to both EU MDR and emerging national standards simultaneously.
South Africa
SAHPRA's tightened electromagnetic compatibility standards for imported medical electronics are accelerating distributor migration toward certified OEM partnerships with pre-validated component architectures. The regulator's post-market surveillance requirements now extend to semiconductor input traceability for analog front-end devices. Gauteng Province's academic medical centers concentrate clinical instrumentation design expertise, leaving other markets dependent on expatriate technical support for deployment.
Egypt
Retail pharmacy chains are building direct-to-consumer distribution channels for wearable vital sign monitors, bypassing hospital procurement committees entirely. The country's national pharmaceutical regulator maintains import dependency for high-value implantable devices while permitting wellness-classification loopholes for consumer fitness trackers. Cairo's private hospital networks are piloting photoplethysmography-based blood pressure estimation devices for post-operative hypertension surveillance.
Nigeria
Home healthcare channels are expanding most quickly through retail pharmacy distribution for consumer-facing wearable monitors, though regulatory enforcement for medical device registration remains fragmented across federal and state jurisdictions. The national standards body is harmonizing electromagnetic compatibility testing protocols with Gulf Cooperation Council specifications to reduce multi-country supplier compliance costs. Lagos anchors West African distribution for non-invasive sensor assemblies sourced from East Asian semiconductor suppliers.
Middle East and Africa Biomedical Sensors Market Competitive Landscape
Concentration sits with integrated device manufacturers possessing end-to-end manufacturing footprints and pre-validated biocompatibility portfolios that compress registration timelines against regional competitors. The vendor base stratifies across three tiers: multinational conglomerates with implantable sensor track records, semiconductor suppliers competing on analog front-end cost curves, and regional assemblers serving price-sensitive procurement tenders. Dominant competitive moves include strategic partnerships with tertiary hospital networks and backward integration into sensor module assembly within high-growth national markets.
Within the integrated device manufacturer tier, Medtronic and Abbott Laboratories exemplify archetypes leveraging deep channel partnerships and pre-validated regulatory documentation to dominate high-margin implantable categories. Among semiconductor suppliers, Texas Instruments occupies a position supplying analog front-ends to regional OEMs building non-invasive monitoring devices for price-sensitive tenders. These three companies represent the competitive spectrum from premium implantable systems through component-level supply.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| GE Healthcare |
| Siemens Healthineers |
| Analog Devices, Inc. |
| Honeywell International Inc. |
| NXP Semiconductors N.V. |
| TE Connectivity Ltd. |
| Texas Instruments Incorporated |
| Others |
Supply & Pricing Matrix
Optical glucose measurement systems displacing electrochemical analyzers across Gulf diagnostic laboratories simultaneously shift procurement geography toward East Asian semiconductor suppliers and compress pricing power for legacy European instrument manufacturers. This substitution dynamic reconfigures both component sourcing patterns and margin structures for regional distributors navigating SFDA and SAHPRA compliance pathways.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Middle East and Africa biomedical sensors market. Premium implantable sensors from certified manufacturers command significant markups based on ISO 14155 clinical evidence packages and pre-validated biocompatibility portfolios, while standard-tier non-invasive monitors face cost compression from analog front-end chip price volatility. Pricing pressure stems from semiconductor input swings affecting regional assemblers, with hospital procurement committees in Saudi Arabia and the UAE exhibiting lowest price sensitivity for cardiac implantables and highest sensitivity for consumer-facing wearable vital sign monitors distributed through Egyptian and Nigerian retail pharmacy channels.
Supply Chain Analysis
Container availability constraints on Asia-Middle East trade lanes elevate inbound logistics costs for analog front-end semiconductors and optical sensor components. Manufacturing concentration centers on Taiwan, South Korea, and China for piezoelectric transducers and electrochemical biosensor substrates, with regional OEMs drawing from East Asian foundries for Bluetooth Low Energy modules and near-infrared spectroscopy emitters. Single-source vulnerability in biocompatible battery cells for implantable devices creates structural risk, while distribution runs through certified OEM partnerships with pre-validated EMC architectures rather than direct component spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of clinical instrumentation design expertise across the Middle East and Africa concentrates technical capability in South Africa and the UAE, leaving other markets dependent on expatriate support and creating acquisition premiums for firms with embedded biomedical engineering talent.
For Market Incumbents: Shield high-margin implantable sensor franchises by deepening backward integration into sensor module assembly within Saudi Arabia's Industrial Development Fund incentive zones, while accelerating open API development to meet National Unified Procurement Company interoperability mandates that now outweigh brand preference in vendor selection criteria. For New Entrants and Emerging Players: Anchor in Egypt's direct-to-consumer retail pharmacy distribution channels for wearable vital sign monitors, bypassing consolidated Gulf hospital procurement committees entirely, and pursue white-space opportunities in AI-enabled predictive diagnostics at the sensor edge for pre-symptomatic arrhythmia detection applications. For Investors and Strategic Acquirers: EU MDR transition certification backlogs reshaping the acquisition landscape compress valuation multiples for regional distributors lacking technical documentation capabilities, with long-term viability favoring vertically integrated mid-cap specialists possessing captive biocompatibility testing infrastructure and pre-validated component architectures.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Dual-track EU MDR and emerging national standard pre-certification reduces multi-country registration costs for optical glucose analyzers. |
| Hospital System Partnership | Open API interoperability clauses in Saudi National Unified Procurement Company tenders now determine vendor selection outcomes. |
| Backward Integration | Saudi Industrial Development Fund financing creates captive supply opportunities for sensor module assembly within the Kingdom. |
| Software Companion Development | HL7 FHIR integration gaps between wireless sensors and legacy EHR systems in public hospitals complicate deployment without dedicated software investment. |
| Reimbursement Strategy | Vision 2030 health privatization mandates remote patient monitoring infrastructure, establishing dedicated procurement channels for connected biometric devices. |
Research Methodology
A standing panel of biomedical engineers, hospital procurement committee members, GPO contracts managers, and regulatory affairs specialists provided ongoing calibration across the analysis window, combining structured primary interviews with secondary validation from SFDA device registration databases, SAHPRA electromagnetic compatibility filings, hospital procurement tender records, and CE marking documentation under EU MDR. Bottom-up sensor shipment estimates triangulated against top-down healthcare infrastructure spending projections.
Consistency checks against external benchmarks validated volume and value outputs across product form factor, underlying transduction principle, care setting, and clinical use case segmentation dimensions. CAGRs were derived from modeled adoption curves for optical platform displacement of electrochemical methods and privatization-driven remote patient monitoring infrastructure deployment, with semiconductor input cost indices and regulatory timeline assumptions feeding directly into pricing trajectory projections.
Underlying assumptions cover SFDA and SAHPRA harmonization trajectories, with deviation risk concentrated in Gulf standardization body divergence on electromagnetic compatibility testing protocols and EU MDR technical documentation backlog persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Carpal Tunnel Release Systems Market
Medical Devices
Rigid Laparoscope Market
Medical Devices
3D Printed Implants Market
Medical Devices
Europe Otoscope Market
Medical Devices
Global Brachytherapy Devices Market
Medical Devices
Portable Medical Electronic Products Market
Medical Devices
Canada Ultrasound Devices Market
Medical Devices
Body Contouring Devices and Procedures Market
Medical Devices
India Hemostats Market
Medical Devices
Cranial Navigation Systems Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
North America 3D Printing in Healthcare Market
Medical Devices
Brachytherapy Catheters Market
Medical Devices
Europe Clear Aligners Market
Medical Devices
Peripheral Interventions Market
Medical Devices
Digital Ureteroscopes Market