
 Memory Implants Market | 2026-2036
Memory Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Memory Implants Market Analysis
Biocompatibility-grade polymer encapsulation is unwinding cost barriers that previously constrained memory implant commercialization. Medtronic leverages its neuromodulation infrastructure to anchor deep brain stimulation expertise into memory-focused applications. Boston Scientific Corporation competes through specialized microelectrode arrays designed for hippocampal-cortical interfaces. Abbott Laboratories differentiates via wireless communication protocols that eliminate percutaneous leads in chronic implant settings.
Memory implants comprise biocompatible electrode arrays and semiconductor chips surgically positioned to record, stimulate, or modulate neural activity associated with memory encoding and retrieval, typically operating at impedance thresholds below 1 MΩ and utilizing platinum-iridium or carbon nanotube conductor materials. These devices serve primarily to restore or augment cognitive function in patients with traumatic brain injury, Alzheimer's disease, or other neurodegenerative conditions. Neurostimulators command the dominant revenue share within product types due to established reimbursement pathways and mature surgical implantation protocols. Neural interfaces represent the fastest-expanding technology segment as closed-loop feedback architectures advance. Research institutions constitute the most concentrated end-user margin pool, driven by NIH, DARPA, and European Research Council grant funding cycles.
FDA breakthrough device designation and EMA's Medical Device Regulation (MDR) Class III requirements shape premarket clinical evidence burdens and post-market surveillance obligations for memory implant manufacturers. The FDA's Center for Devices and Radiological Health maintains specific guidance on brain-computer interface devices, while ISO 14155 governs clinical investigation standards across jurisdictions. Stakeholders must monitor evolving CMS national coverage determinations for neurotechnology reimbursement and anticipate how the EU AI Act's risk classification framework may apply to adaptive, learning-enabled neural implants.
Market Dynamics
Closed-loop neural feedback architectures are compressing development cycles for implantable cognitive devices, pulling capital toward real-time signal processing capabilities and away from static stimulation protocols.
Growth Catalysts
- NIH BRAIN Initiative funding cycles:Sustained federal grant flows are underwriting preclinical validation studies at neurological research institutions, de-risking early-stage device development.
- DARPA Restoring Active Memory program:Military neurotechnology procurement is creating concentrated demand pull for hippocampal prosthetics with demonstrated encoding-restoration capabilities.
- Carbon nanotube electrode arrays:These conductor materials are lowering impedance thresholds below 1 MΩ, enabling higher-fidelity neural recording with reduced power consumption.
Market Restraints
- Platinum-iridium supply concentration:Biocompatibility-grade conductor sourcing clusters with South African and Russian mining operations, exposing manufacturers to input cost volatility and geopolitical disruption.
- EMA MDR Class III clinical evidence burdens:Post-market surveillance obligations for neurotechnology extend follow-up timelines to 15 years, compressing return-on-investment horizons for implantable devices.
- Non-invasive neuromodulation substitutes:Transcranial magnetic stimulation and focused ultrasound are capturing mild cognitive impairment cases that might otherwise advance to surgical implant candidacy.
Strategic Opportunities
- Underpenetrated Japan market:METI's aging-society technology roadmap prioritizes dementia care infrastructure, creating regulatory tailwinds for hippocampal-cortical interface adoption.
- Wireless power and data transmission convergence:Elimination of percutaneous leads through inductive coupling and Bluetooth Low Energy is enabling chronic implant settings previously precluded by infection risk.
- Research-to-clinic channel innovation:Direct-to-hospital contracting models are bypassing traditional device distribution, capturing margin from academic medical centers with established neurosurgical volumes.
Industry Challenges
- Neural signal processing talent scarcity:The intersection of computational neuroscience and implantable hardware engineering commands premium compensation, constraining workforce scaling.
- ISO 14155 certification timeline compression:Multi-site clinical investigations across jurisdictions require synchronized ethics approvals, extending time-to-CE-mark by 18-24 months.
- Legacy deep brain stimulation system integration:New memory-focused devices must interface with existing neuromodulation infrastructure, complicating firmware and hardware compatibility testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Memory Implants Market |
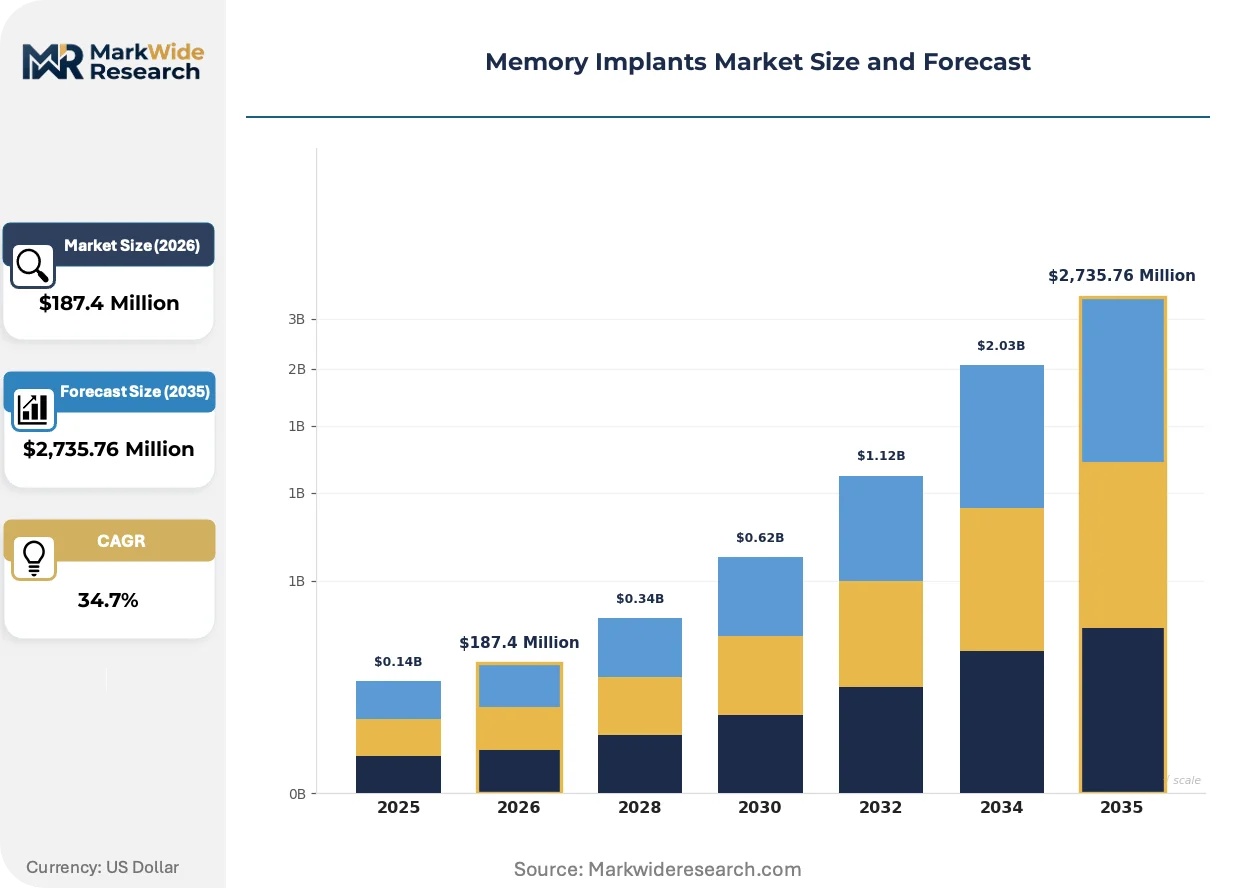
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,735.76 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrode Implants, Chip Implants, Neurostimulators, Memory Enhancement Devices Technology: Optogenetics, Microelectrodes, Neural Interfaces, Wireless Communication End User: Research Institutions, Healthcare Providers, Academic Institutions, Rehabilitation Centers Application: Cognitive Disorders, Memory Loss Treatment, Neural Restoration, Brain Research |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott Laboratories, LivaNova, NeuroPace, Inc., Bausch and Lomb Incorporated, Alcon Laboratories, Biomet Incorporated, Nevro Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Memory Implants Market Emerging Trajectories
Adaptive learning algorithms are embedding directly into implantable processors, shifting competitive advantage from hardware miniaturization toward real-time computational capability at the tissue interface.
Carbon nanotube-based microelectrode arrays are supplanting traditional platinum-iridium conductors in next-generation hippocampal interfaces. Research institutions in Germany and the United States are scaling procurement of these systems for preclinical validation studies. The structural consequence is a compression in signal-to-noise ratios that previously constrained closed-loop feedback architectures.
EU AI Act risk classification frameworks are extending to adaptive, learning-enabled neural implants, triggering pre-market conformity assessments for algorithmic decision-making components. Manufacturers must now document training data provenance and bias mitigation protocols alongside traditional biocompatibility testing. European neurological device sponsors are responding by segregating AI-enabled and fixed-algorithm product lines to manage regulatory exposure.
Academic medical centers are consolidating procurement authority into centralized neurotechnology evaluation committees, displacing individual surgeon preference as the primary purchasing determinant. These committees demand health-economic evidence and institutional volume commitments before contract authorization. The United States exhibits the most pronounced concentration, where NIH-funded brain research consortia coordinate multi-site purchasing to extract price concessions.
Memory Implants Market Segmentation
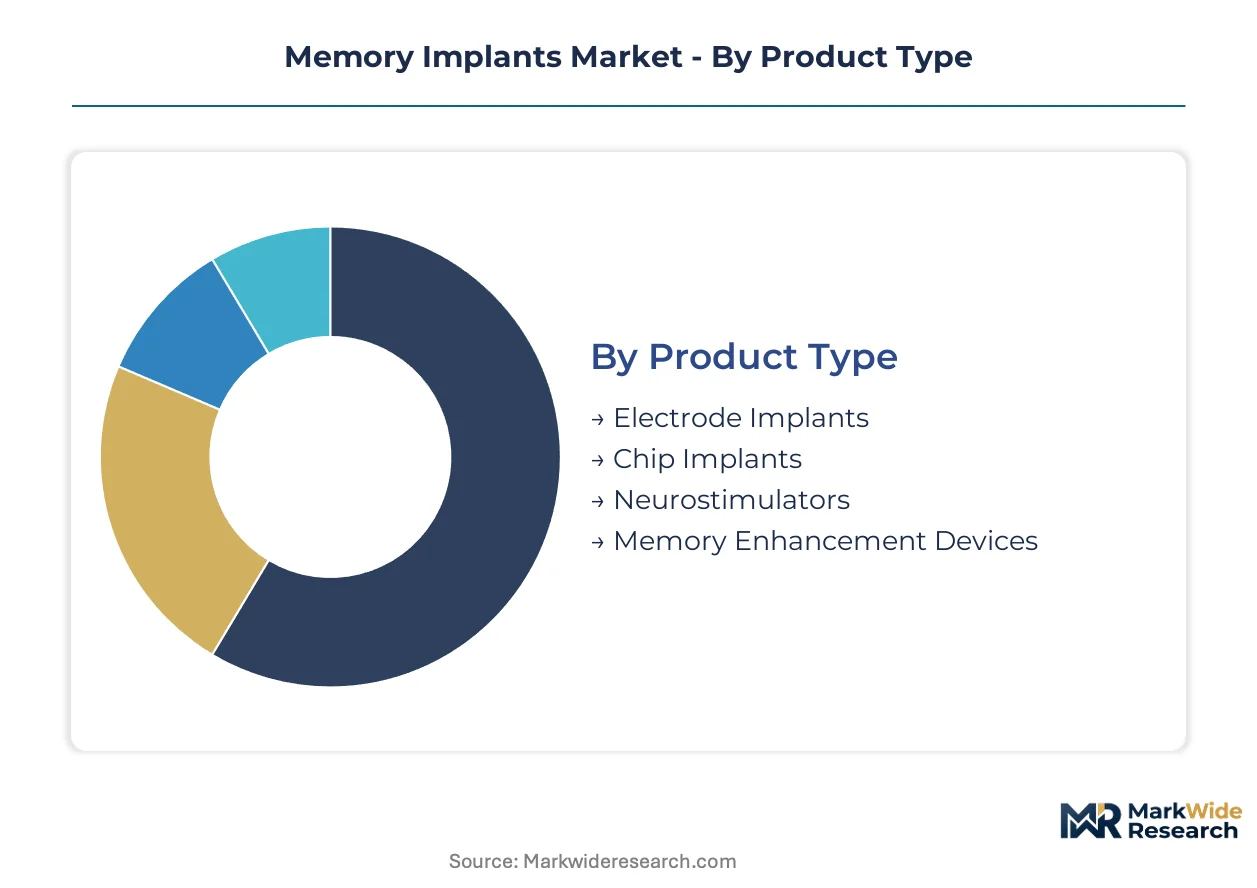
Segmentation in memory implants determines capital allocation toward reimbursable clinical applications versus grant-funded research platforms. Product architecture choices—electrode materials, signal processing capabilities, and wireless protocols—create divergent margin structures and regulatory pathways.
Product Type:
Non-invasive neuromodulation substitutes exert substitution pressure most acutely on peripheral stimulation devices, while intracranial implants maintain surgical exclusivity.
- Electrode Implants:Biocompatible platinum-iridium or carbon nanotube arrays positioned at impedance thresholds below 1 MΩ for high-fidelity neural recording. Demand concentrates at NIH-funded brain research consortia in the United States, where DARPA Restoring Active Memory program procurement underwrites preclinical validation volumes.
- Neurostimulators:Implantable pulse generators with established CMS reimbursement codes and mature surgical protocols. Healthcare providers in Germany and the United States anchor procurement volumes, driven by FDA breakthrough device designation pathways that compress time-to-market for cognitive restoration indications.
- Chip Implants:Semiconductor-based processors enabling real-time signal computation at the tissue interface. Research institutions in Germany scale procurement for closed-loop feedback architecture development.
- Memory Enhancement Devices:Integrated systems combining sensing, stimulation, and adaptive learning algorithms. Academic institutions pilot these in human-subject protocols under ISO 14155 clinical investigation standards.
Neurostimulators anchor the volume base while electrode implants gain share at the steepest rate.
Technology:
Cost tier stratification separates capital-intensive surgical implantation from lower-cost external research tools, with wireless capabilities commanding premium positioning.
- Neural Interfaces:Closed-loop architectures integrating recording and stimulation functions with real-time feedback. Research institutions in the United States and Germany drive procurement, propelled by NIH BRAIN Initiative funding cycles that de-risk early-stage device development.
- Microelectrodes:Miniaturized conductor arrays enabling single-neuron resolution in hippocampal-cortical applications. Carbon nanotube electrode arrays from this category are supplanting platinum-iridium in next-generation procurement at neurological research institutions.
- Optogenetics:Light-activated protein systems for cell-type-specific neural modulation. Academic institutions deploy these in preclinical brain research protocols requiring genetic targeting capabilities.
- Wireless Communication:Inductive coupling and Bluetooth Low Energy protocols eliminating percutaneous leads. Rehabilitation centers prioritize these for chronic implant settings where infection risk previously precluded surgical candidacy.
Neural interfaces dominate current revenue while wireless communication climbs the fastest as lead elimination enables new chronic-use indications.
End User:
Customer type determines purchasing authority concentration, with centralized neurotechnology evaluation committees displacing individual surgeon preference at high-volume academic medical centers.
- Research Institutions:Primary demand source for preclinical validation systems and exploratory neural interface architectures. NIH, DARPA, and European Research Council grant funding cycles create concentrated procurement pull in the United States and Germany.
- Healthcare Providers:Hospitals and health systems with established neurosurgical volumes and CMS reimbursement infrastructure. These entities demand health-economic evidence and institutional volume commitments before contract authorization.
- Academic Institutions:Universities conducting human-subject research under FDA and EMA clinical investigation frameworks. METI's aging-society technology roadmap in Japan is creating regulatory tailwinds for procurement expansion in this segment.
- Rehabilitation Centers:Post-acute facilities managing traumatic brain injury and stroke recovery protocols. Wireless-enabled memory implants are penetrating this segment as lead-free designs reduce long-term complication rates.
Research institutions anchor the volume base while rehabilitation centers gain share at the steepest rate.
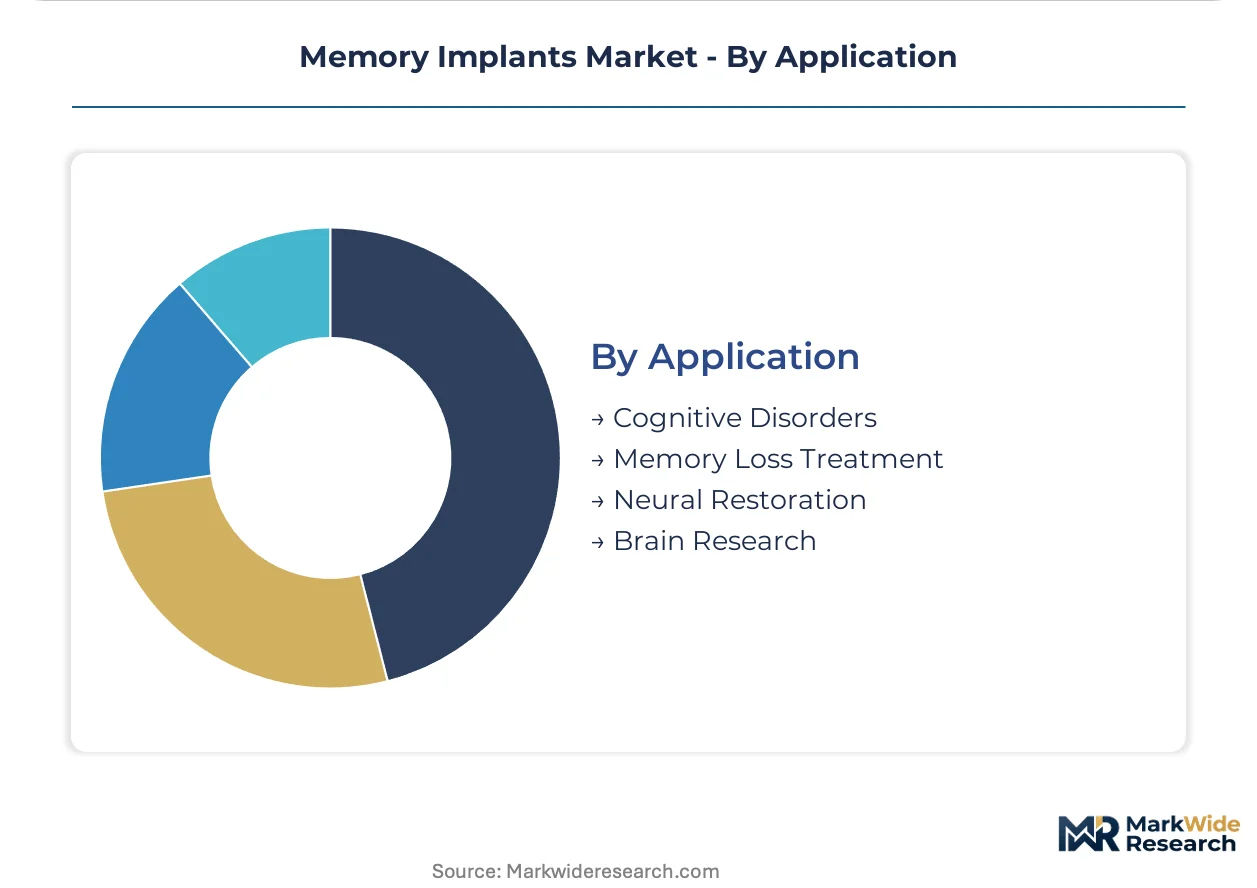
Application:
Application maturity varies sharply, with cognitive disorder treatments facing established reimbursement pathways while neural restoration indications require de novo clinical evidence development.
- Cognitive Disorders:Alzheimer's disease and dementia interventions targeting memory encoding deficits. Healthcare providers in the United States concentrate procurement, supported by NIH-funded brain research consortia coordinating multi-site purchasing.
- Memory Loss Treatment:Traumatic brain injury and stroke-related impairment interventions. Rehabilitation centers and academic medical centers drive demand, with DARPA military neurotechnology programs creating concentrated pull for hippocampal prosthetics.
- Neural Restoration:Functional recovery of damaged neural circuits through targeted stimulation. Research institutions pilot these applications under FDA breakthrough device designation and EMA MDR Class III frameworks.
- Brain Research:Fundamental neuroscience investigation using implantable recording systems. Academic institutions in Germany and the United States scale procurement for preclinical validation studies.
Cognitive disorders anchor the volume base while neural restoration gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for memory implants varies sharply by geography. Research institutions in Germany and the United States absorb premium pricing for preclinical systems, while rehabilitation centers in emerging markets prioritize cost-optimized wireless configurations.
United States
NIH BRAIN Initiative funding cycles and DARPA military neurotechnology programs concentrate procurement pull at neurological research institutions. FDA breakthrough device designation pathways compress time-to-market for hippocampal prosthetics. The Boston-Cambridge corridor anchors preclinical validation volumes for closed-loop neural interfaces.
Germany
Neurological research institutions scale procurement of carbon nanotube electrode arrays for hippocampal-cortical interface development. EMA MDR Class III requirements extend post-market surveillance timelines, compressing ROI horizons for manufacturers. The Munich-Heidelberg-Stuttgart triangle hosts dense clusters of academic medical centers with established neurosurgical volumes.
Japan
METI's aging-society technology roadmap prioritizes dementia care infrastructure, creating regulatory tailwinds for memory implant adoption. PMDA accelerated review pathways for neurotechnology reduce premarket approval durations. Tokyo-Osaka metropolitan corridors concentrate rehabilitation center demand for wireless-enabled chronic implants.
United Kingdom
NHS England neurotechnology procurement frameworks emphasize health-economic evidence for cognitive restoration indications. MHRA alignment with EMA MDR standards shapes clinical evidence requirements for implantable devices. The Oxford-Cambridge-London arc consolidates academic institution demand for neural interface research platforms.
Switzerland
Swissmedic's streamlined neurotechnology review processes attract device sponsors seeking European market entry. ETH Zurich and University of Geneva research consortia drive preclinical procurement of adaptive learning-enabled implants. The Basel-Zurich corridor concentrates biocompatibility-grade polymer encapsulation development.
Memory Implants Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the memory implant sector. Established neuromodulation conglomerates leverage deep brain stimulation infrastructure to anchor cognitive restoration applications, while specialized microelectrode developers compete on signal fidelity metrics. The market structure stratifies into three archetypes: diversified medtech conglomerates with neuromodulation franchises, focused neural interface specialists, and academic spin-outs commercializing research-to-clinic transitions. Dominant competitive moves include strategic partnerships with NIH-funded research consortia and portfolio diversification into wireless-enabled chronic implant configurations.
Within the diversified medtech tier, Medtronic, Boston Scientific Corporation, and Abbott Laboratories exemplify distinct positioning strategies. Medtronic represents the neuromodulation infrastructure anchor, Boston Scientific Corporation occupies a position in specialized microelectrode array development, and Abbott Laboratories exemplifies wireless protocol differentiation for lead-free chronic implants. These three players collectively illustrate how scale, specialization, and connectivity architectures segment competitive advantage in implantable cognitive devices.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott Laboratories |
| LivaNova |
| NeuroPace, Inc. |
| Bausch and Lomb Incorporated |
| Alcon Laboratories |
| Biomet Incorporated |
| Nevro Corporation |
| Others |
Supply Flow & Price Mechanics
FDA breakthrough device designation gates both supplier qualification and price differentiation in memory implants, compressing time-to-market for sponsors while segmenting procurement budgets between grant-funded research systems and reimbursable clinical devices. EMA MDR Class III requirements extend post-market surveillance obligations, stretching manufacturer cash conversion cycles and amplifying working capital demands across biocompatibility-grade polymer encapsulation tiers.
Pricing Analysis
After-sales revenue from firmware updates and extended clinical support contracts drives lifetime value in memory implant deployments. Three-tier pricing structure across premium, standard, and economy levels separates closed-loop neural interfaces with adaptive learning algorithms from fixed-protocol neurostimulators and basic electrode arrays. Pricing pressure stems from carbon nanotube electrode array commoditization as manufacturing scales at German and United States research institutions. Academic medical centers with centralized neurotechnology evaluation committees exhibit highest price sensitivity, while DARPA-funded military neurotechnology programs demonstrate lowest sensitivity due to mission-critical procurement mandates.
Supply Chain Analysis
South Africa and Russia anchor platinum-iridium conductor supply for biocompatibility-grade electrode arrays, with secondary concentration in German precision metallurgy operations. Taiwan and South Korea feed semiconductor chip fabrication for implantable pulse generators, while United States-based foundries handle specialized neural signal processors. Raw material dependencies center on carbon nanotube synthesis feedstocks, biocompatibility-grade polymer precursors, and rare earth elements for wireless inductive coupling components. Single-source vulnerability concentrates in South African mining operations, exposing manufacturers to geopolitical disruption and input cost volatility. Distribution runs through direct-to-hospital contracting models at academic medical centers, bypassing traditional device distribution layers to capture margin from NIH-funded brain research consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Memory implants constitute a defensive-moat market anchored by regulatory entrenchment, where FDA breakthrough device designation and EMA MDR Class III frameworks create multi-year approval barriers that protect incumbent positions while constraining new entrant speed-to-market.
For Market Incumbents: Shield market position by deepening backward integration into carbon nanotube electrode array manufacturing, capturing margin from research institution procurement volumes while reducing exposure to South African platinum-iridium supply concentration. Fortify firmware ecosystems around existing deep brain stimulation infrastructure, creating switching costs that complicate new entrant compatibility testing with legacy neuromodulation systems deployed across German and United States hospital networks.
For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks offer the most penetrable regulatory pathway for hippocampal-cortical interface developers seeking to compress time-to-market against established neurostimulator franchises. Target Japan's rehabilitation center segment, where METI's aging-society technology roadmap creates regulatory tailwinds for wireless-enabled chronic implants and procurement authority remains less consolidated than United States academic medical centers. Pursue research-to-clinic channel innovation through direct contracting with NIH-funded brain research consortia, bypassing traditional distribution markups while building clinical evidence under ISO 14155 frameworks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across closed-loop neural interface development, as real-time signal processing capabilities demand specialized computational neuroscience talent and adaptive learning algorithm validation. Long-term viability across the analysis window favors sponsors with demonstrated FDA breakthrough device designations and established CMS reimbursement infrastructure. Target acquisition archetypes include academic spin-outs with carbon nanotube electrode array IP and wireless protocol patents for lead-free chronic implants. Monitor EMA MDR Class III post-market surveillance obligation extensions as the critical inflection signal compressing manufacturer return-on-investment horizons and triggering consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Compresses premarket review timelines for hippocampal prosthetics targeting traumatic brain injury restoration. |
| CE Marking Pathway under MDR Class III | Extends post-market surveillance to 15 years, reshaping capital allocation for European market entry. |
| Hospital System Partnership | Centralized neurotechnology evaluation committees at academic medical centers displace surgeon preference in procurement. |
| Software Companion Development | Adaptive learning algorithms embedding directly into implantable processors shift competitive advantage toward computational capability. |
| Reimbursement Strategy | CMS national coverage determinations for neurotechnology gate commercial scalability in United States healthcare provider segments. |
Methodological Framework
A spread of perspectives from neurosurgeons, hospital purchasing committee chairs, biomedical engineers at neurological research institutions, and GPO contracts managers converged on the working assumptions underlying this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) and PMA filings, EMA MDR submission databases, NIH BRAIN Initiative grant award records, and CMS national coverage determination documents. Bottom-up triangulation across electrode implant, neurostimulator, and chip implant product categories integrated with top-down cross-checks against DARPA military neurotechnology program budgets and European Research Council funding cycles.
Segmentation dimensions modeled span product type, technology architecture, end-user category, and application indication across the projection horizon. Neural interfaces, microelectrodes, optogenetics, and wireless communication technology segments were projected based on closed-loop feedback architecture advancement rates and carbon nanotube electrode array adoption curves. CAGRs derived from NIH funding cycle trajectories, METI aging-society technology roadmap implementation timelines, and PMDA accelerated review pathway utilization rates. Industry-specific forecast inputs incorporated ISO 14155 clinical investigation enrollment velocities and EMA MDR Class III post-market surveillance obligation compliance costs.
Underlying assumptions cover carbon nanotube manufacturing scale economics, platinum-iridium supply chain stability, and regulatory pathway duration consistency, with deviation risk concentrated in geopolitical disruption to South African mining operations and EU AI Act risk classification extensions to adaptive neural implants. Recalibration cycles align with material shifts in FDA breakthrough device designation approval velocities and CMS neurotechnology reimbursement policy updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US C-Arms Market
Medical Devices
Automatic Pill Dispenser Machine Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Italy Ultrasound Devices Market
Medical Devices
Italy Medical Device Regulatory Affairs Market
Medical Devices
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Asia-Pacific Integrated Operating Room System Market
Medical Devices
India Minimally Invasive Surgery Devices Market
Medical Devices
Global Healthcare Nanotechnology (Nanomedicine) Market
Medical Devices
Minimally Invasive Neurosurgery Devices Market
Medical Devices
Global Uterine Manipulation Devices Market
Medical Devices
Intracranial Pressure Monitors Market
Medical Devices
Drug Delivery Devices Market
Medical Devices
Pneumatic Nebulizers Market
Medical Devices
Nasal Atomizer Devices Market
Medical Devices
IV Fluid Monitoring Device Market