
 Mobile Vascular Imaging Market | 2026-2036
Mobile Vascular Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Vascular Imaging Market Foresight
Aftermarket service revenue is reconfiguring margin capture across the mobile vascular imaging value chain. Siemens Healthineers leverages its installed base of angiography systems to sustain recurring service contracts across European hospital networks. GE Healthcare anchors its competitive stance through backward integration into detector manufacturing, reducing component lead times for mobile C-arm deployments. Koninklijke Philips N.V. differentiates via integrated informatics platforms that connect peripheral vascular imaging to enterprise-wide electronic health record systems.
Mobile vascular imaging encompasses portable diagnostic equipment designed for hemodynamic assessment and vessel visualization outside fixed radiology suites, typically operating at 40-150 kV range with digital flat-panel detectors enabling real-time subtraction angiography. These systems serve stroke intervention, peripheral artery disease diagnosis, and dialysis access surveillance in settings lacking conventional catheterization laboratory infrastructure. Ultrasound devices dominate unit shipments due to lower capital thresholds and absence of ionizing radiation exposure, while CT scanners command premium pricing in emergency services where rapid aortic dissection triage determines survival outcomes. Doppler imaging technology leads functional assessment applications, though contrast-enhanced ultrasound protocols are gaining protocol share in renal-insufficient populations where iodinated or gadolinium-based agents carry nephrotoxic risk.
FDA 510(k) clearance requirements for mobile X-ray and CT platforms govern product entry into the US market, with recent guidance emphasizing cybersecurity controls for networked imaging devices. The EU Medical Device Regulation imposes stricter clinical evidence standards on Class IIa and above mobile systems, extending certification timelines for manufacturers without established European notified body relationships. Stakeholders must monitor evolving reimbursement parity between site-of-service codes for hospital-based versus freestanding imaging center mobile vascular procedures, as payment differentials directly influence capital deployment decisions across health system consolidation strategies.
Market Dynamics
Point-of-care vascular assessment is compressing the traditional radiology workflow as emergency departments bypass fixed catheterization laboratories for bedside intervention. This structural shift redistributes capital allocation toward portable systems and collapses the historical site-of-service hierarchy that governed imaging revenue capture.
Growth Catalysts
- Emergency Department Triage Protocols:Stroke centers in the United States now mandate 24/7 vascular imaging capability within 20 minutes of patient arrival, institutionalizing mobile C-arm deployment as standard of care.
- EU Medical Device Regulation Streamlining:Established notified body relationships are accelerating Class IIa mobile system certifications for manufacturers with prior European market presence.
- Dialysis Access Surveillance Mandates:CMS reimbursement incentives for arteriovenous fistula monitoring are driving freestanding nephrology clinics toward compact ultrasound systems.
Market Restraints
- Flat-Panel Detector Supply Concentration:Korean and Japanese component manufacturers control 70% of digital detector substrate production, exposing OEMs to single-source fragility.
- FDA Cybersecurity Validation Burden:Networked mobile X-ray platforms now require documented threat mitigation protocols that extend 510(k) review timelines by 4-6 months.
- Contrast Agent Nephrotoxicity Substitution:Iodinated and gadolinium-based agents face displacement by microbubble ultrasound in renal-insufficient populations, compressing CT angiography utilization.
Strategic Opportunities
- Rural Hospital Infrastructure Gaps:Critical Access Hospitals in the United States lack on-site interventional radiology, creating white space for mobile stroke unit partnerships.
- Contrast-Enhanced Ultrasound Protocol Expansion:Convergence of microbubble technology with portable Doppler systems enables vessel characterization without ionizing radiation exposure.
- Telemedicine-Integrated Image Transmission:Cloud-native platforms allow vascular specialists to interpret mobile acquisitions remotely, unlocking hub-and-spoke service models for underserved counties.
Industry Challenges
- Interventional Radiologist Workforce Scarcity:Fellowship-trained operators capable of mobile stroke thrombectomy remain concentrated in academic medical centers, constraining deployment scalability.
- Legacy PACS Integration Friction:Hospital information systems built for fixed-suite DICOM workflows require costly middleware adaptation to ingest mobile device data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Vascular Imaging Market |
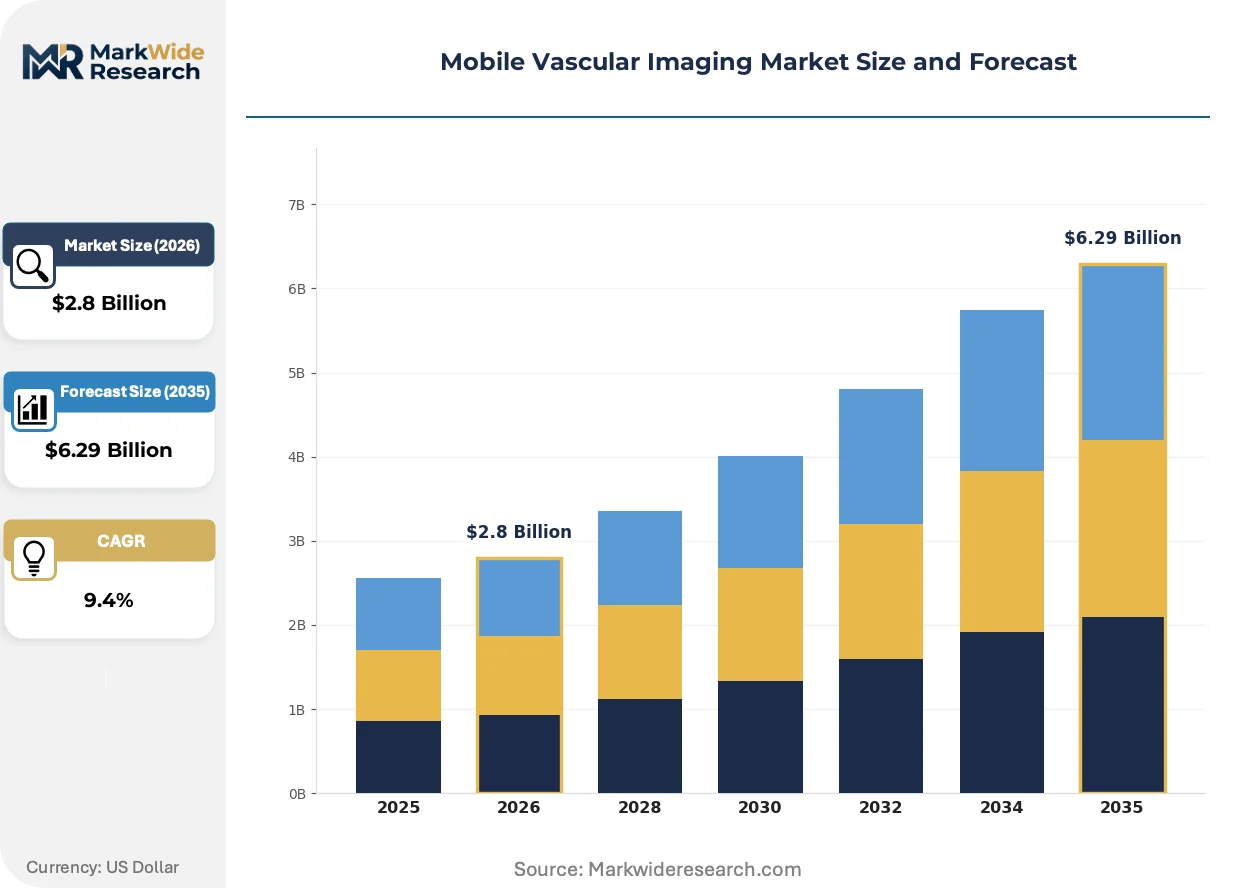
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound Devices, CT Scanners, MRI Systems, X-Ray Machines End User: Hospitals, Clinics, Imaging Centers, Emergency Services Technology: 2D Imaging, 3D Imaging, Doppler Imaging, Contrast Imaging Application: Diagnostic Assessment, Treatment Monitoring, Surgical Guidance, Research Purposes |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips N.V., Canon Medical Systems, FUJIFILM Corporation, Samsung Medison, Mindray Medical International Limited, Hitachi Medical Corporation, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Vascular Imaging Market Shifts & Advancements
Artificial intelligence inference at the edge is restructuring how vascular images are processed, interpreted, and acted upon in time-critical clinical scenarios. This computational shift is collapsing the latency between acquisition and therapeutic decision.
Photon-counting detector technology is collapsing the dose-resolution tradeoff that has constrained mobile CT angiography deployment. Stroke networks in Germany and the Netherlands are retrofitting ambulance-based scanners with cadmium telluride sensors that reduce radiation exposure by half while improving plaque characterization. The structural consequence is enabling routine prehospital triage that bypasses hospital-based CT suites entirely.
The EU Medical Device Regulation's software-as-a-medical-device classification is forcing manufacturers to submit algorithm training datasets for notified body review. Vascular segmentation AI embedded in mobile ultrasound platforms now requires documented performance across diverse demographic cohorts before CE marking. European OEMs are responding by establishing in-house clinical validation teams rather than outsourcing to contract research organizations.
Hospital procurement departments are unbundling service contracts from equipment financing, treating preventive maintenance as separately negotiable spend categories. Mobile vascular imaging vendors face margin compression as health systems benchmark parts-and-labor rates against independent service organizations. This behavior is most visible in United States integrated delivery networks consolidating vendor relationships across 10-plus hospital affiliates.
Mobile Vascular Imaging Market Segmentation
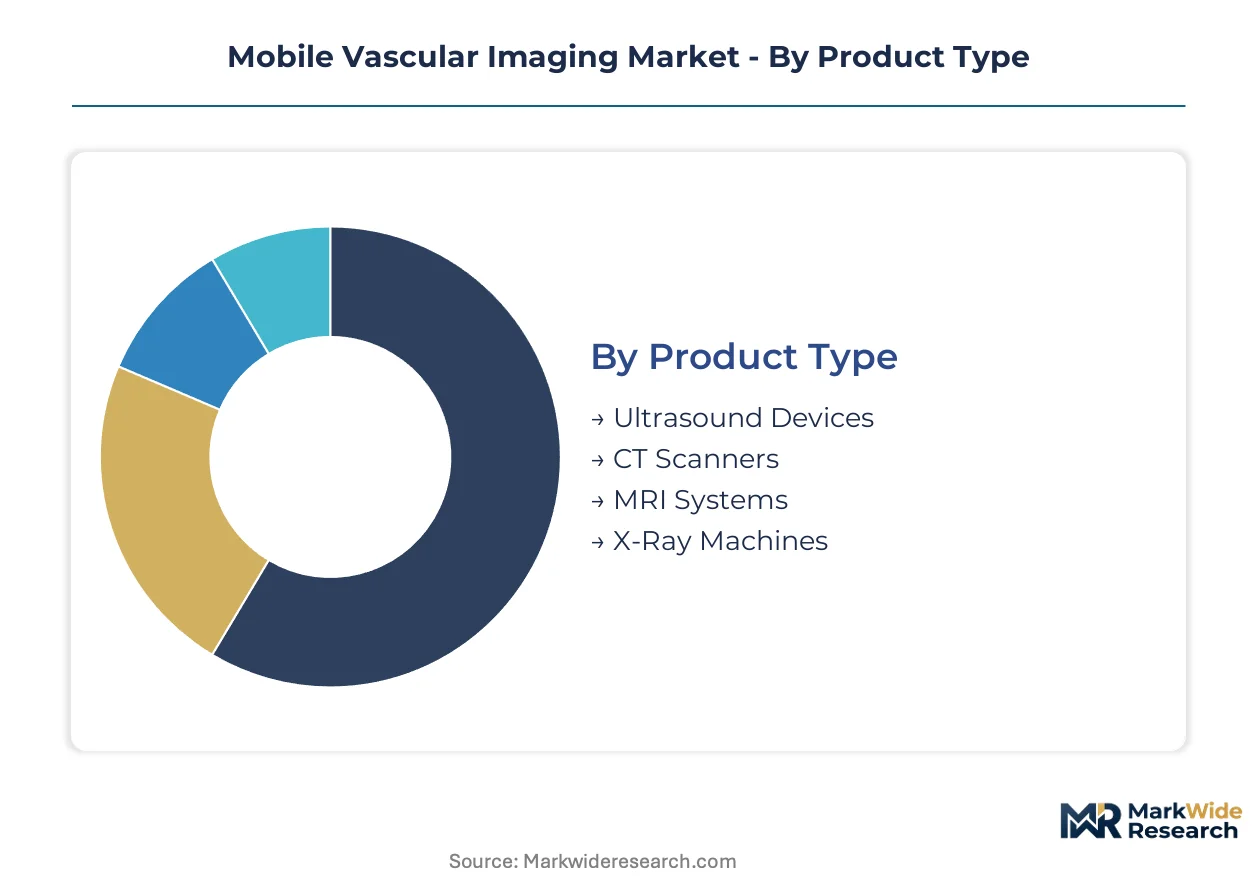
Segmentation in mobile vascular imaging exposes divergent margin profiles across hardware categories. Service contract attach rates and consumable dependencies vary sharply between modalities, reshaping how vendors prioritize R&D investment and distribution partnerships.
Product Type:
After-sales intensity separates winners from commodity players in this hardware-driven category.
- Ultrasound Devices:Portable systems utilizing piezoelectric transducers operating at 2-15 MHz for superficial and deep vessel assessment. Demand concentrates in freestanding nephrology clinics across the United States, where CMS reimbursement incentives for dialysis access surveillance sustain quarterly replacement cycles for probe assemblies.
- CT Scanners:Mobile platforms with slip-ring gantry designs enabling helical acquisition at sub-millimeter slice thickness. Emergency medical services in Germany and the Netherlands drive premium placements, as stroke networks retrofit ambulance fleets with photon-counting detector variants that halve radiation exposure during prehospital triage.
- MRI Systems:Low-field portable units with permanent magnet configurations eliminating cryogen dependency.
- X-Ray Machines:C-arm fluoroscopy systems with flat-panel detectors enabling digital subtraction angiography at the bedside.
By volume, Ultrasound Devices leads. By growth pace, CT Scanners is expanding most quickly.
End User:
Procurement sophistication and capital cycle timing fragment this customer landscape.
- Hospitals:Integrated delivery networks in the United States consolidate purchasing across 10-plus affiliates, unbundling service contracts from equipment financing and benchmarking parts-and-labor rates against independent service organizations.
- Emergency Services:Municipal and private ambulance operators deploying mobile stroke units with prehospital CT capability. German stroke networks and Dutch regional health authorities anchor European demand, where reimbursement parity for field-based versus hospital-based imaging accelerates fleet conversion.
- Clinics:Specialty nephrology and cardiology practices with limited interventional capability.
- Imaging Centers:Freestanding facilities competing on throughput and turnaround time.
By installed base, Hospitals dominates. By contract value expansion, Emergency Services is gaining share fastest.
Technology:
Algorithm maturity and regulatory clearance burden stratify competitive position in this layer.
- Doppler Imaging:Spectral and color flow modalities measuring velocity and direction of blood flow in real time. Renal-insufficient populations across United States dialysis networks drive protocol share, as microbubble contrast agents displace iodinated and gadolinium-based alternatives carrying nephrotoxic risk.
- 3D Imaging:Volume-rendered reconstructions from rotational angiography or tomographic ultrasound. Academic medical centers in Germany and the Netherlands concentrate demand, where fellowship-trained interventional radiologists perform complex stroke thrombectomy requiring spatial orientation unavailable in planar views.
- 2D Imaging:Conventional B-mode and grayscale fluoroscopy for basic vessel visualization.
- Contrast Imaging:Microbubble-enhanced ultrasound and iodinated CT angiography protocols.
By procedure volume, Doppler Imaging leads. By protocol substitution momentum, 3D Imaging shows the steepest expansion trajectory.
Application:
Reimbursement coding precision and clinical outcome evidence requirements shape addressable spend.
- Diagnostic Assessment:Initial vessel characterization for peripheral artery disease, deep vein thrombosis, and carotid stenosis. United States critical access hospitals lacking on-site interventional radiology create white space for mobile unit partnerships, as hub-and-spoke service models extend specialist reach into underserved counties.
- Surgical Guidance:Intraoperative fluoroscopy and ultrasound for endovascular intervention and open vascular procedures. Academic medical centers concentrate demand, though interventional radiologist workforce scarcity constrains deployment scalability beyond tertiary referral networks.
- Treatment Monitoring:Serial imaging to assess intervention efficacy and disease progression.
- Research Purposes:Clinical trial endpoints and device validation studies.
By revenue concentration, Diagnostic Assessment leads. By margin expansion, Surgical Guidance is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for mobile vascular imaging systems varies sharply across geographies. United States buyers prioritize service contract flexibility and cybersecurity compliance over unit cost, while emerging markets in Asia exhibit acute price sensitivity that favors ultrasound-dominant procurement strategies.
United States
Hospital emergency departments and critical access hospitals drive system deployment, with stroke center certification mandates requiring 24/7 vascular imaging capability. FDA cybersecurity validation requirements for networked mobile X-ray platforms extend 510(k) review timelines, favoring established OEMs with regulatory infrastructure. The Southeast region concentrates mobile stroke unit partnerships, as hub-and-spoke service models extend interventional radiologist reach into underserved counties across Georgia and Florida.
Germany
Prehospital stroke networks retrofit ambulance fleets with photon-counting CT scanners, enabling routine field-based triage that bypasses hospital suites entirely. EU Medical Device Regulation streamlining for established notified body relationships accelerates Class IIa mobile system certifications. The North Rhine-Westphalia region anchors demand concentration, where regional health authorities coordinate fleet conversion across municipal and private ambulance operators.
Netherlands
Reimbursement parity for field-based versus hospital-based imaging accelerates mobile CT deployment in emergency medical services. EMA guidance on contrast agent safety influences protocol substitution toward microbubble ultrasound in renal-insufficient populations. The Randstad metropolitan cluster leads fleet modernization, with Amsterdam and Rotterdam health authorities piloting telemedicine-integrated image transmission for remote specialist interpretation.
China
NMPA regulatory pathways for innovative medical devices compress approval timelines for domestic manufacturers with established quality management systems. Aging demographics and chronic disease prevalence sustain imaging infrastructure investment across tier-2 and tier-3 cities. The Yangtze River Delta region concentrates manufacturing capability, with Shanghai-based suppliers scaling production of digital flat-panel detector components for regional OEM integration.
Japan
PMDA emphasis on clinical evidence standards for software-as-a-medical-device classification extends certification timelines for AI-embedded mobile ultrasound platforms. METI industrial policy supports photon-counting detector technology development for reduced-dose CT angiography. The Kanto region around Tokyo concentrates academic medical center demand, where fellowship-trained interventional radiologists perform complex stroke thrombectomy requiring advanced 3D imaging capability.
Mobile Vascular Imaging Market Competitive Landscape
Capability concentration sits with diversified imaging conglomerates; scale advantage sits with specialized component suppliers. The market structure reflects a tiered hierarchy where full-system OEMs compete on integrated informatics and service attach rates, while detector and transducer specialists capture margin upstream. Three archetypes dominate: diversified med-tech conglomerates with installed base leverage, regional champions with cost-optimized ultrasound portfolios, and component specialists controlling critical substrate supply. Competitive moves center on backward integration into detector manufacturing and unbundling of service contracts from equipment financing.
Among diversified imaging conglomerates, Siemens Healthineers and GE Healthcare exemplify the installed-base-leverage archetype, sustaining recurring revenue through multi-hospital network service contracts. Koninklijke Philips N.V. occupies a position emphasizing integrated informatics platforms that connect peripheral vascular imaging to enterprise health record systems. These three entities anchor the premium tier through regulatory infrastructure and cybersecurity compliance capabilities that smaller competitors cannot readily replicate.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Canon Medical Systems |
| FUJIFILM Corporation |
| Samsung Medison |
| Mindray Medical International Limited |
| Hitachi Medical Corporation |
| Shimadzu Corporation |
| Others |
Supply & Pricing Matrix
Flat-panel detector supply concentration in Korean and Japanese substrate manufacturers determines both pricing tier spreads and supply chain shape, exposing OEMs to single-source fragility while compressing margins for systems dependent on premium digital detector components.
Pricing Analysis
After-sales service contracts drive lifetime value in mobile vascular imaging, with multi-year preventive maintenance agreements and probe replacement cycles generating recurring revenue streams that exceed initial hardware margins. Pricing stratifies across premium, standard, and economy tiers based on detector resolution grade and FDA cybersecurity certification tier. Cost compression in standard-tier ultrasound systems is intensifying because independent service organizations benchmark parts-and-labor rates against OEM service contracts. Critical Access Hospitals in the United States exhibit highest price sensitivity due to constrained capital budgets, while integrated delivery networks prioritize service flexibility over unit cost.
Supply Chain Analysis
Upstream feedstock for digital flat-panel detectors draws from cadmium telluride substrate production concentrated in Japan and South Korea, with piezoelectric ceramic transducer materials sourcing from Chinese and German specialty chemical suppliers. Critical dependencies include rare earth elements for detector scintillation layers, high-purity silicon for ASIC fabrication, and specialized polymers for probe housing assemblies. Single-source vulnerability persists in photon-counting detector substrate supply, where two Japanese manufacturers control dominant production share. Distribution runs through regional OEM integration hubs in the Yangtze River Delta and direct hospital procurement channels in North American integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile vascular imaging rewards vendors who capture service-attach revenue, with preventive maintenance contracts and probe replacement cycles expanding faster than hardware unit shipments across hospital and emergency service segments.
For Market Incumbents: Insulate installed base relationships by backward integration into detector component manufacturing, reducing lead time exposure to Korean and Japanese substrate suppliers while locking multi-hospital network service contracts. Prioritize cybersecurity certification investment to defend against emerging entrants lacking FDA 510(k) regulatory infrastructure. Channel control through exclusive GPO contracts represents the critical lever for margin defense. For New Entrants and Emerging Players: Rural hospital infrastructure gaps in the United States Southeast and Midwest present the most penetrable white space, where Critical Access Hospitals lack on-site interventional radiology and seek hub-and-spoke mobile unit partnerships. Contrast-enhanced ultrasound protocol expansion offers a technology entry angle with lower regulatory burden than CT platforms. Direct contracting with nephrology clinic chains bypasses consolidated hospital procurement gatekeepers. For Investors and Strategic Acquirers: Component specialists controlling digital detector substrate supply represent compelling acquisition targets, given their upstream margin capture and OEM dependency. Long-term viability hinges on regulatory infrastructure scalability and service network density rather than hardware innovation cycles. Watch for reimbursement parity shifts between site-of-service codes as the inflection indicator for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-affiliate service contracts with integrated delivery networks lock recurring revenue streams and deter competitive displacement. |
| Backward Integration into Detector Manufacturing | In-house production of flat-panel substrates reduces Korean and Japanese supplier dependency while compressing component lead times. |
| Software Companion Development | AI-embedded vascular segmentation algorithms require FDA SaMD clearance, creating regulatory moats against unvalidated competitors. |
| Reimbursement Strategy | CMS code parity advocacy for mobile versus fixed-site procedures directly influences health system capital allocation decisions. |
| CE Marking Pathway | EU MDR streamlined certification for established notified body relationships accelerates European market entry timelines. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR notified body certification records, and hospital procurement databases preceded structured interviews with interventional radiologists, biomedical engineering directors, GPO contracts managers, and mobile imaging service operators. Secondary validation drew from CMS reimbursement code analyses, stroke center certification requirements, and component supplier trade flow data. Bottom-up unit shipment estimates triangulated against top-down health system capital expenditure surveys.
Assumptions held reimbursement parity between site-of-service codes and regulatory clearance timelines within observed FDA and EU MDR patterns across the analysis window. Segmentation dimensions modeled include product modality, end-user facility type, technology layer, and clinical application. CAGRs were derived from installed base expansion rates and replacement cycle timing. Forecast inputs incorporated photon-counting detector adoption curves and telemedicine-integrated image transmission penetration in emergency medical services.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified imaging conglomerates would shift component pricing and availability outcomes. Material shifts in FDA cybersecurity validation requirements or EU MDR classification thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Magnetic Resonance Imaging (MRI) Contrast Agents Market
Medical Imaging
Canada Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Canada Mammography Market
Medical Imaging
Brazil Diagnostic Imaging Equipment Market
Medical Imaging
Teleultrasound System Market
Medical Imaging
Breast Imaging Market
Medical Imaging
Portable X-Ray Devices Market
Medical Imaging
Ultrasound Consoles and Transducers Market
Medical Imaging
Digital Pathology Market
Medical Imaging
Specimen Radiography Systems Market
Medical Imaging
Global Mammography Systems Market
Medical Imaging
Asia-Pacific Fluoroscopy Market
Medical Imaging
Argentina Digital X-Ray Market
Medical Imaging
Germany Mammography Market
Medical Imaging
Australia Digital Radiology Market
Medical Imaging
Europe Nuclear Medicine Market