
 Europe Implantable Medical Devices Market | 2026-2036
Europe Implantable Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Implantable Medical Devices Market Intelligence
Connected sensor integration and AI-enabled diagnostics is rewriting how implantable devices capture, transmit, and act on patient data in real time. Medtronic plc leverages its deep neuromodulation portfolio to anchor European market presence across neurostimulator and cardiac implant categories. Abbott Laboratories competes through its leadless pacemaker technology and glucose-sensing implant platforms. BIOTRONIK SE & Co. KG specializes in cardiac rhythm management with particular strength in home-monitoring-enabled devices across German-speaking markets.
Implantable medical devices encompass instruments placed entirely within or on the surface of the body to replace missing biological structures, support damaged tissues, or deliver therapeutic agents, typically manufactured from titanium alloys, cobalt-chrome, medical-grade silicone, or bioresorbable polymers through precision machining, additive manufacturing, or cleanroom molding processes. Cardiac implants command the largest product type position due to sustained procedural volumes for pacemakers, ICDs, and CRT devices across European hospital systems. Neurostimulators represent the fastest-expanding application segment as spinal cord stimulation and deep brain therapy gain traction for chronic pain and movement disorders. Smart implants incorporating closed-loop feedback and wireless telemetry are capturing disproportionate R&D investment as manufacturers pursue differentiation through real-time physiological optimization.
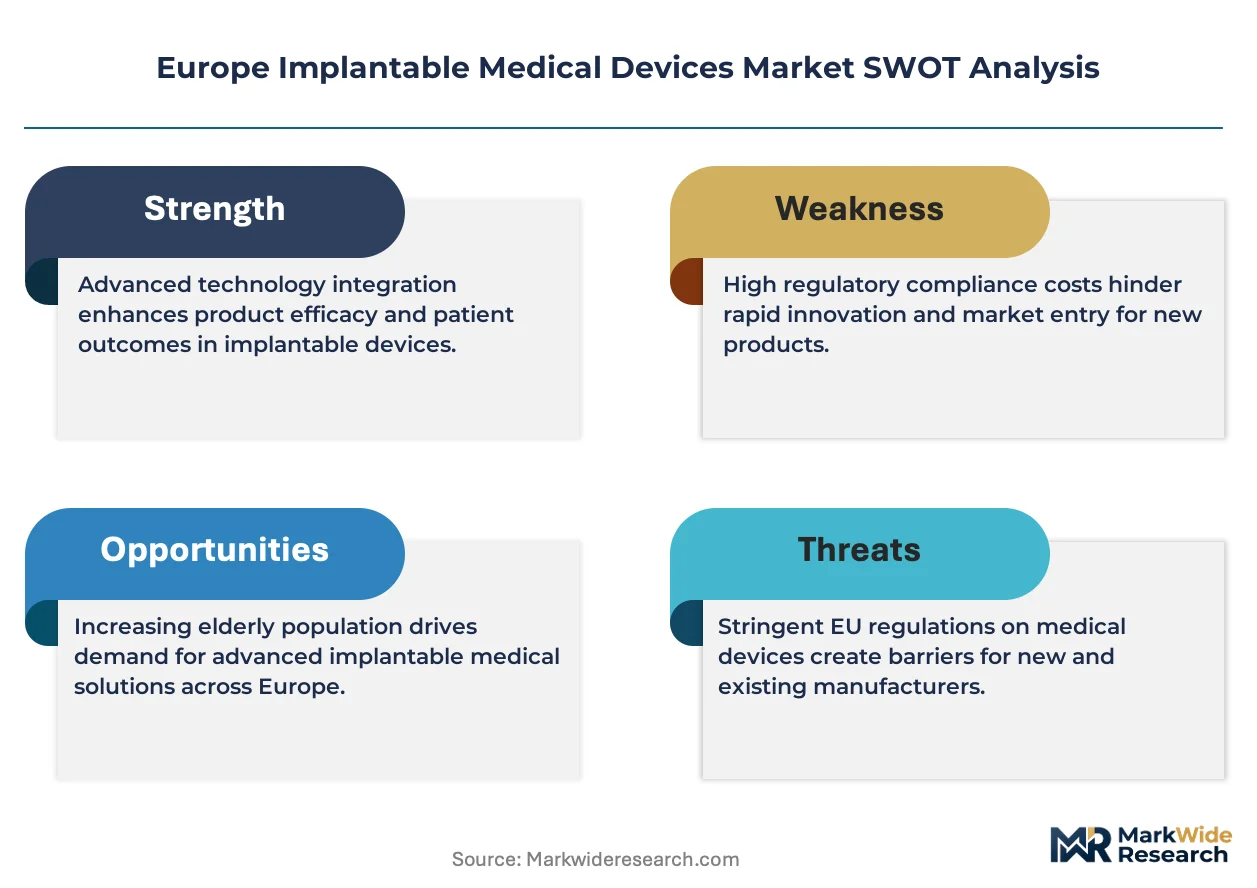
The EU Medical Device Regulation and CE marking framework administered by notified bodies govern market access, while the EMA coordinates pharmaceutical aspects of drug-device combination implants such as insulin pumps and infusion systems. REACH and RoHS directives constrain material selection for implantable components, pushing manufacturers toward validated biocompatible substitutes and comprehensive substance documentation. The EU AI Act introduces additional conformity obligations for implants employing machine-learning-based diagnostic algorithms, reshaping development timelines and clinical validation requirements. Stakeholders must monitor evolving notified body capacity constraints and the interplay between MDR technical documentation demands and emerging AI governance to preserve timely market entry pathways.
Market Dynamics
The EU Medical Device Regulation is compressing approval timelines while simultaneously elevating clinical evidence standards, forcing manufacturers to restructure regulatory affairs functions and front-load validation expenditure before CE marking submission.
Growth Catalysts
- Aging demographics:Germany, France, and the United Kingdom host expanding elderly populations requiring cardiac rhythm management and orthopedic restoration interventions.
- EU AI Act compliance:The regulatory framework for machine-learning diagnostic algorithms creates first-mover advantages for manufacturers completing conformity assessments ahead of notified body bottlenecks.
- Home-monitoring telemetry:Wireless-enabled implants reduce hospital readmission rates and align with national health system cost-containment objectives.
Market Restraints
- Titanium alloy supply concentration:Primary feedstock for orthopedic and dental implants originates from a limited supplier base in Eastern European refining corridors.
- Notified body capacity constraints:MDR technical documentation reviews face 12-18 month backlogs at designated conformity assessment organizations.
- Bioresorbable polymer performance limitations:Degradation rate unpredictability restricts application in load-bearing structural implants.
Strategic Opportunities
- Poland and Czech Republic hospital expansion:Central European health infrastructure investment outpaces Western European procedural volume growth rates.
- Neurostimulator therapy extension:Deep brain stimulation for psychiatric indications awaits formal reimbursement coding in multiple EU member states.
- Closed-loop glucose-insulin integration:Convergence of continuous glucose monitoring with automated insulin delivery creates combination product white space.
Industry Challenges
- Biocompatibility assessment expertise scarcity:ISO 10993 biological evaluation competency shortages extend preclinical testing timelines.
- Cleanroom manufacturing capex intensity:MDR-mandated quality management system upgrades require facility revalidation expenditure.
- Legacy device MDR transition:Certificate of conformity expiration deadlines force simultaneous portfolio remediation across multiple product families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Implantable Medical Devices Market |
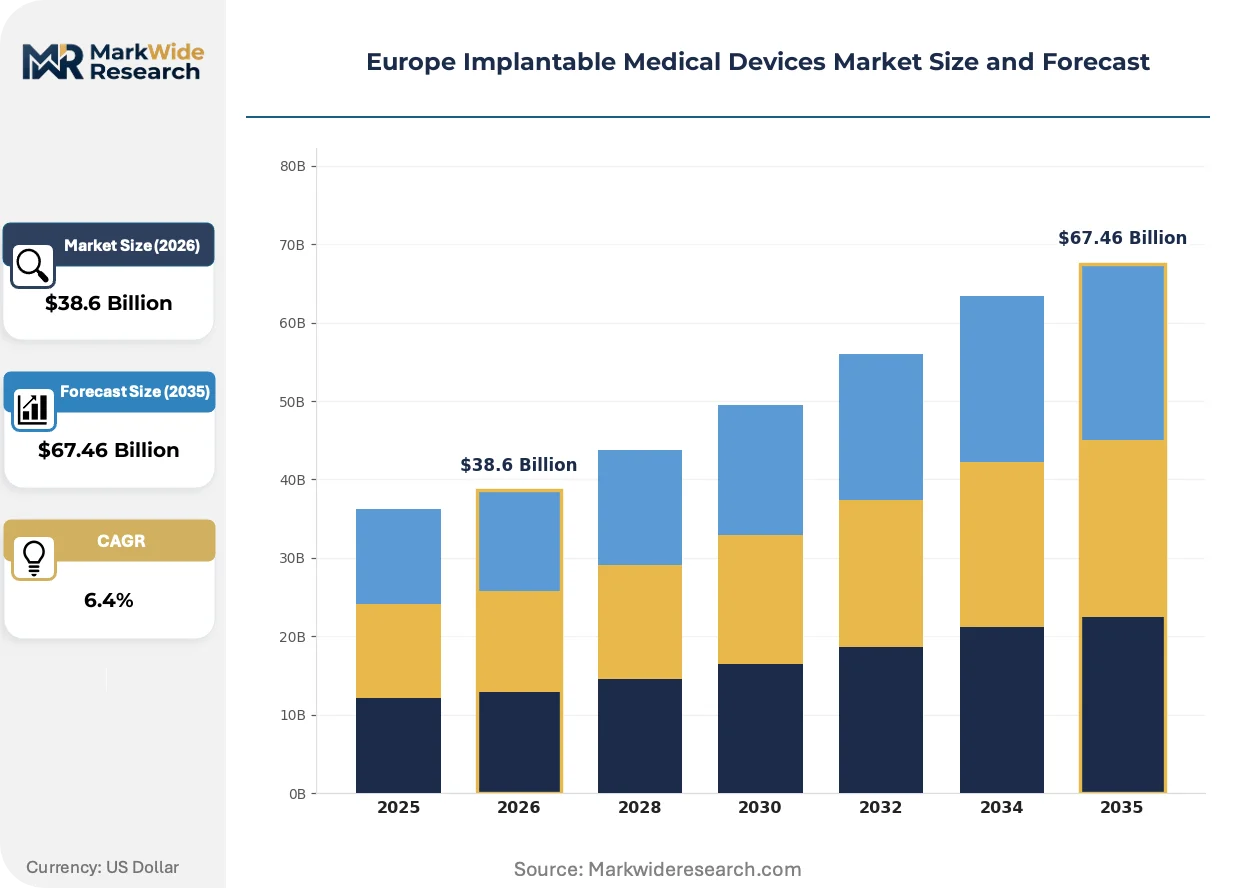
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $67.46 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Implants, Orthopedic Implants, Neurostimulators, Drug Delivery Systems Application: Cardiology, Orthopedics, Neurology, Endocrinology End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Home Healthcare Technology: Active Implants, Passive Implants, Biodegradable Implants, Smart Implants |
| Companies Covered | Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, BIOTRONIK SE & Co. KG, Stryker Corporation, Johnson & Johnson, Smith & Nephew plc, Cochlear Limited, LivaNova PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Implantable Medical Devices Market Strategic Shifts & Innovations
Implantable device architecture is converging around sensor-enabled physiological feedback loops that transform passive prosthetics into active therapeutic systems requiring new regulatory classification pathways.
Leadless cardiac pacing technology is migrating from investigational status to standard-of-care positioning for bradycardia management. Electrophysiology departments in German and French tertiary centers are expanding catheter-based implant volumes while conventional transvenous procedures plateau. The structural shift compresses hardware supply chains toward miniaturized energy storage and bidirectional telemetry subsystems.
REACH substance restriction amendments are forcing cobalt-chrome alloy substitution in articulating joint surfaces. The ECHA authorization list expansion triggers material requalification campaigns across hip and knee implant portfolios. Orthopedic manufacturers with validated titanium-niobium alternatives capture accelerated market access as competitors face supply interruption.
Hospital procurement consortia are consolidating implantable device purchasing across regional health system boundaries. French university hospital networks and English NHS integrated care boards negotiate multi-year framework agreements displacing single-site tender processes. The concentration trend is most visible in cardiac rhythm management and spinal fixation categories where volume commitments secure preferential pricing tiers.
Europe Implantable Medical Devices Market Segmentation
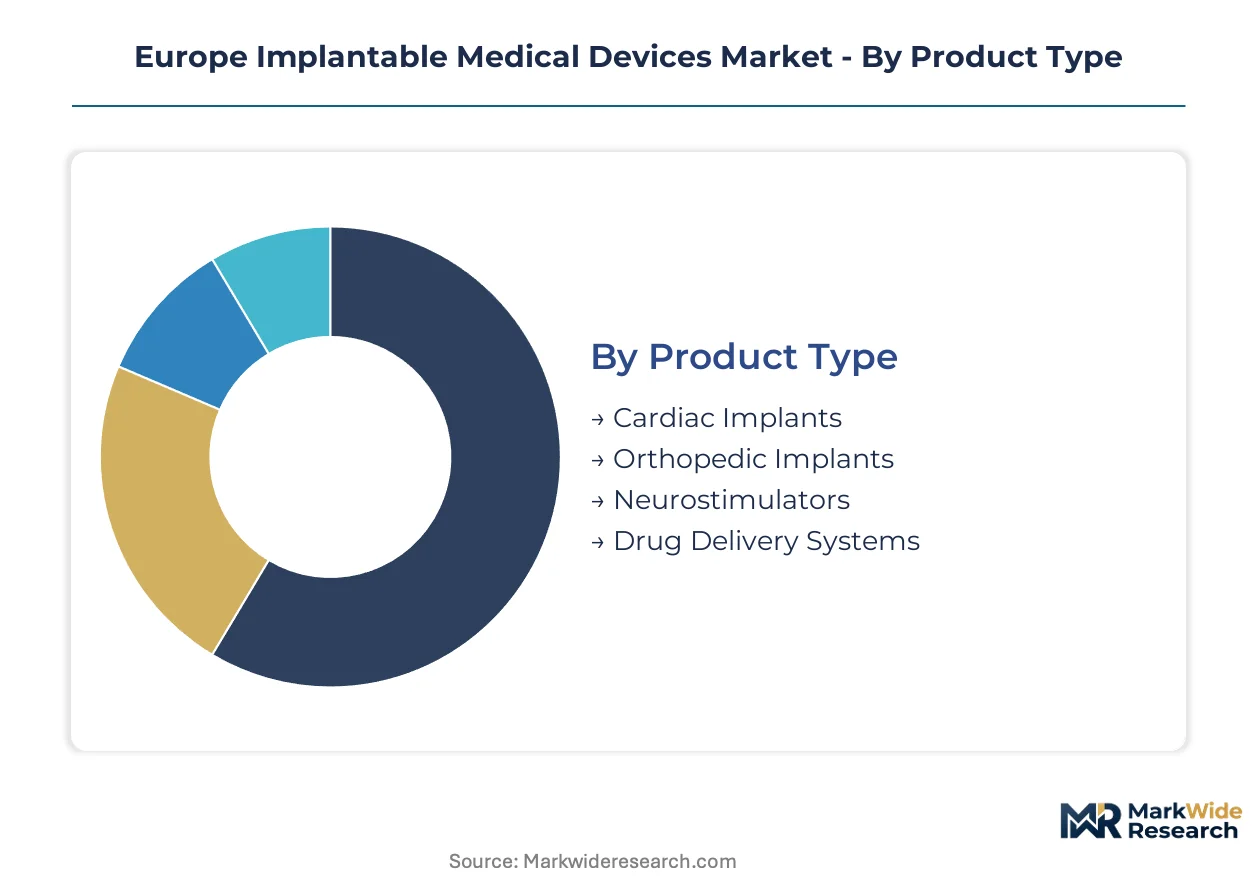
Implantable device procurement in Europe fragments across clinical settings with divergent service intensity requirements, reimbursement pathways, and technical sophistication thresholds. Manufacturers configure pricing, training, and remote monitoring support differently for each segment cluster.
Product Type:
After-sales service intensity varies sharply across implant categories, with cardiac and neurostimulation devices requiring continuous remote monitoring infrastructure while orthopedic implants demand revision surgery support networks.
- Cardiac Implants:Pacemakers, ICDs, and CRT devices incorporate lithium-iodine batteries and titanium enclosures with 5-15 year longevity. German university hospitals and French cardiac centers drive replacement volumes as aging device cohorts reach elective exchange thresholds. Remote monitoring subscription revenue now matches hardware margins for manufacturers with established telemetry platforms.
- Neurostimulators:Spinal cord stimulators and deep brain implants deliver electrical pulses through lead arrays to modulate neural signaling. UK pain management centers and German movement disorder clinics are expanding implant volumes for refractory chronic pain and Parkinson's disease as reimbursement coding formalizes.
- Orthopedic Implants:Hip, knee, and spinal fixation constructs manufactured from titanium alloys or cobalt-chrome.
- Drug Delivery Systems:Implantable pumps and reservoirs for localized pharmaceutical administration.
Cardiac implants hold the largest share; momentum sits with neurostimulators.
Application:
Clinical application determines regulatory pathway complexity, with cardiology and neurology facing EMA coordination for drug-device combinations while orthopedics navigates pure MDR technical documentation.
- Cardiology:Arrhythmia management, heart failure therapy, and structural interventions dominate procedural calendars in European electrophysiology departments. Leadless pacemaker adoption is climbing fastest as German and French tertiary centers transition from transvenous systems.
- Neurology:Movement disorders, epilepsy, and chronic pain conditions access implantable therapy through specialized functional neurosurgery units. Deep brain stimulation for psychiatric indications awaits formal reimbursement coding in multiple EU member states.
- Orthopedics:Joint replacement and spinal stabilization address degenerative conditions in aging populations.
- Endocrinology:Insulin pumps and glucose sensors manage diabetes through subcutaneous or intraperitoneal placement.
Cardiology captures the largest revenue pool; neurology is expanding most quickly.
End User:
Procurement authority concentrates differently across settings, with hospital consortia negotiating multi-year frameworks while ambulatory centers purchase through group purchasing organizations with shorter commitment horizons.
- Hospitals:Tertiary cardiac centers and university hospitals perform complex implant procedures with full catheterization laboratory infrastructure. German hospital networks and French university hospital groups consolidate purchasing across regional boundaries to secure volume-based pricing tiers.
- Ambulatory Surgical Centers:Standalone facilities perform low-acuity orthopedic and cardiac device implants with same-day discharge protocols. UK independent sector treatment centers and German Schwerpunktkliniken are capturing select cardiac rhythm management procedures from hospital settings.
- Specialty Clinics:Dedicated neurology and pain management practices focus on neurostimulator programming and patient follow-up.
- Home Healthcare:Remote monitoring service providers manage telemetry data transmission and alert triage for implanted devices.
Hospitals dominate volume; ambulatory surgical centers are gaining share fastest.
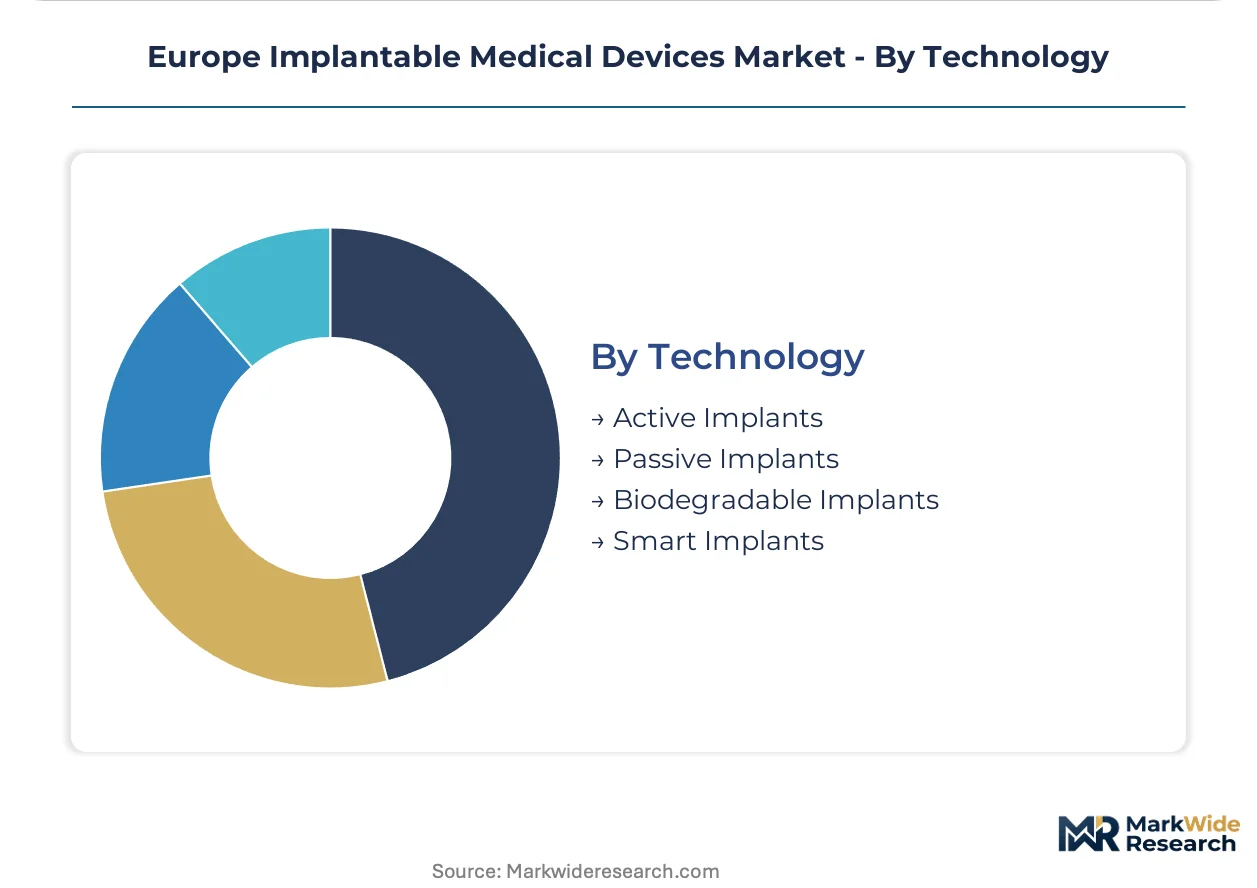
Technology:
Technology tier determines manufacturing complexity and regulatory classification, with active and smart implants facing notified body scrutiny for electrical safety and electromagnetic compatibility while passive devices navigate simpler conformity assessment.
- Active Implants:Battery-powered devices with electronic circuitry including pacemakers, ICDs, and neurostimulators. German notified bodies are experiencing 12-18 month review backlogs for MDR technical documentation of active implantable medical devices.
- Smart Implants:Sensor-enabled systems with closed-loop feedback and wireless telemetry capabilities. EU AI Act compliance requirements for machine-learning diagnostic algorithms are reshaping development timelines and clinical validation protocols.
- Passive Implants:Structural devices without electronic components including orthopedic fixation and dental implants.
- Biodegradable Implants:Bioresorbable polymers for temporary structural support with controlled degradation profiles.
Active implants hold the largest share; smart implants show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe maintains a modest trade surplus in implantable medical devices, with Germany and Switzerland exporting precision-manufactured cardiac and orthopedic hardware while importing raw titanium feedstock and specialized polymers from Eastern European refiners.
Germany
Bavarian cardiac centers in Munich and Erlangen are expanding electrophysiology department capacity to accommodate rising pacemaker and ICD replacement volumes. The Federal Institute for Drugs and Medical Devices enforces MDR technical documentation standards that extend approval timelines for active implantable devices. Berlin-Brandenburg hosts clustered notified body operations where manufacturers face 12-18 month review backlogs for conformity assessments.
France
Île-de-France university hospital networks are consolidating implantable device procurement across regional boundaries to secure volume-based pricing for cardiac rhythm management systems. ANSM coordinates post-market surveillance requirements with EMA for drug-device combination products including insulin pumps. Lyon-based manufacturing facilities specialize in bioresorbable polymer development for temporary orthopedic fixation.
United Kingdom
London and Southeast England electrophysiology departments are transitioning toward leadless pacemaker adoption as transvenous procedure volumes plateau. The Medicines and Healthcare products Regulatory Agency aligns MDR implementation timelines with EU notified body coordination frameworks. Midlands independent sector treatment centers are capturing select cardiac device implants from traditional hospital settings through same-day discharge protocols.
Switzerland
Swissmedic maintains autonomous medical device oversight while recognizing MDR technical documentation for streamlined cross-border market access. Basel and Zurich host concentrated orthopedic and cardiac implant R&D operations where manufacturers develop titanium-niobium alloy alternatives to cobalt-chrome. Geneva-based research institutions are advancing closed-loop neurostimulator algorithms for movement disorder applications.
Poland
Warsaw and Krakow hospital systems are expanding cardiac catheterization laboratory infrastructure faster than Western European procedural growth rates. The Office for Registration of Medicinal Products, Medical Devices and Biocidal Products administers national MDR implementation with focus on notified body capacity building. Silesian manufacturing corridors are attracting contract sterilization and cleanroom molding investments from Western European implant suppliers.
Europe Implantable Medical Devices Market Key Industry Players
On the supply side, the industry is consolidating around diversified medtech conglomerates with full cardiac, neurological, and orthopedic portfolios alongside specialized mid-cap firms with concentrated therapeutic focus. The vendor base stratifies into three archetypes: integrated multinationals with telemetry platform ecosystems, regional specialists with home-monitoring-enabled device portfolios, and component suppliers with validated biocompatible material expertise. Dominant competitive moves include strategic partnerships for AI-enabled diagnostic algorithm development and backward integration into titanium alloy refining to secure feedstock continuity.
Within the integrated multinational tier, Medtronic plc and Abbott Laboratories anchor European market presence through diversified active implant portfolios spanning cardiac rhythm management and glucose-sensing platforms. BIOTRONIK SE & Co. KG exemplifies the regional specialist archetype with concentrated strength in German-speaking cardiac markets and established home-monitoring telemetry infrastructure. These three entities collectively represent the competitive spectrum from global scale to regional therapeutic depth that characterizes European implantable device supply.
| Leading Market Players |
|---|
| Medtronic plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| BIOTRONIK SE & Co. KG |
| Stryker Corporation |
| Johnson & Johnson |
| Smith & Nephew plc |
| Cochlear Limited |
| LivaNova PLC |
| Others |
Cost & Logistics Intelligence
Eastern European titanium refining corridors feed orthopedic and dental implant manufacturers, concentrating margin capture in German and Swiss precision-machining tiers while downstream hospital consortia squeeze hardware pricing through multi-year framework agreements.
Pricing Analysis
Hospital purchasing committees anchor contract-based long-term offtake structures across cardiac rhythm management and spinal fixation categories. Pricing stratifies across premium, standard, and economy tiers based on CE marking tier and remote monitoring service bundling. Cost compression in economy-tier orthopedic implants is intensifying because REACH-mandated cobalt-chrome substitution forces material requalification expenditure. Ambulatory surgical centers exhibit highest price sensitivity due to same-day discharge reimbursement constraints, while German university hospital networks prioritize telemetry platform reliability over unit cost.
Supply Chain Analysis
Dual-use technology export controls limiting flows of advanced sensor components and lithium-iodine battery chemistries constrain smart implant manufacturing scale-up. Supply concentration rests on Germany, Switzerland, and Poland for precision machining and cleanroom molding, with titanium alloy feedstock drawing from Ukrainian and Russian refining corridors before processing. Single-source vulnerability characterizes bioresorbable polymer supply as validated grades originate from limited Lyon-area production facilities. Distribution runs through hospital procurement consortia and group purchasing organizations with divergent contract horizons.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Implantable Medical Devices Market sits in procedural volume recovery as deferred cardiac rhythm management exchanges from aging device cohorts rescheduled during health system strain now clear surgical calendars.
For Market Incumbents: Pre-empt notified body capacity bottlenecks by front-loading MDR technical documentation for active implant portfolios ahead of certificate expiration deadlines. Secure backward integration into titanium-niobium alloy refining to offset cobalt-chrome substitution risks from REACH amendments. Telemetry platform subscription retention is the critical lever against hardware margin compression. For New Entrants and Emerging Players: Build out neurostimulator programming capabilities for psychiatric deep brain stimulation applications awaiting formal reimbursement coding in France and Germany. Poland and Czech Republic hospital expansion offers the most penetrable geographic entry point with faster procedural growth than Western European saturation. Target ambulatory surgical center partnerships for leadless pacemaker same-day discharge protocols. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across smart implant manufacturing as EU AI Act compliance demands expanded clinical validation infrastructure and electromagnetic compatibility testing. Five-to-ten-year viability favors acquiring mid-cap firms with validated biocompatible material expertise and established notified body relationships. Watch notified body designation expansion rates as the inflection signal for market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | MDR technical documentation pre-submission to Berlin-Brandenburg notified bodies reduces review queue positioning risk. |
| Hospital System Partnership | French university hospital network consolidation creates volume commitment leverage for cardiac rhythm management pricing tiers. |
| Software Companion Development | EU AI Act-compliant machine-learning diagnostic algorithms differentiate smart implant positioning against passive device commoditization. |
| Backward Integration into Feedstock | Captive titanium-niobium alloy supply insulates orthopedic portfolios from ECHA authorization list disruption. |
| Reimbursement Strategy | Formal coding acquisition for deep brain stimulation psychiatric indications unlocks neurostimulator volume expansion in German movement disorder clinics. |
Research Approach
Initial hypotheses were tested against primary input from electrophysiology department heads, hospital purchasing committee chairs, biomedical engineers at notified bodies, and GPO contracts managers, then refined against secondary validation from EMA MDR guidance documents, CE marking databases, hospital procurement records, and REACH substance restriction amendments. Bottom-up segmentation modeling and top-down macroeconomic anchoring were cross-checked for consistency.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions spanned product type, application, end user, and technology tier with regional regulatory cluster overlays. CAGRs were derived from procedural volume trajectories and replacement cycle dynamics. Forecast inputs incorporated aging device cohort demographics and notified body capacity expansion schedules.
Stress conditions across titanium alloy supply interruption, notified body review timeline extension, and EU AI Act implementation sequencing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about reimbursement coding formalization and MDR transition completion. Material shifts in REACH substance restriction scope or EMA drug-device combination coordination would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Glass Syringe Market
Medical Devices
Actigraphy Sensors & PSG Devices Market
Medical Devices
Minimally Invasive Deformity Correction System Market
Medical Devices
Europe Breast Pumps Market
Medical Devices
Global Next Generation Surgical Robotics Market
Medical Devices
Global Cardiac Resuscitation Device Market
Medical Devices
Bedwetting Alarm Market
Medical Devices
Global Surgical Drills Market
Medical Devices
Global Smart Wearable Healthcare Devices Market
Medical Devices
Global Electroceuticals Market
Medical Devices
Disposable Medicine Measuring Cups Market
Medical Devices
Global Digital Pathology Systems Market
Medical Devices
DLIF and XLIF Implants Market
Medical Devices
Transplant Monitoring Kits Market
Medical Devices
Global Motion Preservation Devices Market
Medical Devices
Smart Pills Drug Delivery Market