
 Global Tracheal Tube and Airway Products Market | 2026-2036
Global Tracheal Tube and Airway Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tracheal Tube and Airway Products Market Foresight
Hospital procurement channels for airway products is narrowing as group purchasing organizations consolidate vendor lists across integrated delivery networks. Medtronic leverages its broad critical care portfolio to sustain presence across multiple product lines in high-acuity settings. Teleflex anchors its position through specialized laryngeal mask airway designs that dominate ambulatory surgical workflows. Smiths Medical competes on manufacturing scale, operating high-volume production facilities that supply national health systems across Europe and North America.
Tracheal tube and airway products encompass endotracheal tubes, laryngeal mask airways, tracheostomy tubes, and related devices manufactured from medical-grade silicone or polyvinyl chloride with specifications for inner diameter, cuff pressure control, and radiopaque line integration to enable ventilatory support and airway protection during anesthesia, emergency intubation, or prolonged critical care. Endotracheal tubes lead product type revenue due to universal surgical and ICU utilization, while supraglottic airway devices represent the fastest-expanding category as anesthesiologists shift toward less invasive ventilation management in appropriate cases. Application demand concentrates in anesthesia and critical care segments where procedure volume and ventilator dependency create recurring consumption patterns.
FDA 510(k) clearance pathways and EMA Medical Device Regulation conformity assessments shape product development timelines and market access conditions for airway device manufacturers seeking commercialization across major jurisdictions. ISO 10993 biocompatibility testing and ASTM material standards further define technical barriers that filter out undercapitalized entrants. Stakeholders must monitor evolving FDA guidance on reusable versus single-use airway devices and EU MDR transition deadlines to calibrate product portfolio investments and regulatory submission strategies.
Market Dynamics
Hospital procurement consolidation through group purchasing organizations is compressing vendor margins while simultaneously raising technical qualification barriers for airway device suppliers seeking integrated delivery network contracts.
Growth Catalysts
- EU MDR Implementation:Stricter conformity assessment requirements under the Medical Device Regulation are filtering out low-quality competitors and expanding addressable market share for compliant manufacturers across European health systems.
- Ambulatory Surgical Center Expansion:Supraglottic airway device utilization is accelerating in outpatient settings as anesthesiologists prioritize rapid recovery protocols and same-day discharge eligibility.
- Silicone Material Substitution:Medical-grade silicone formulations with enhanced biocompatibility profiles are displacing polyvinyl chloride in premium tube segments across Japanese and German critical care procurement.
Market Restraints
- Polymer Feedstock Volatility:Medical-grade PVC and silicone resin prices fluctuate with petrochemical commodity cycles, squeezing gross margins for manufacturers without backward integration into raw material supply.
- Single-Source Supplier Concentration:Specialized cuff inflation valve components rely heavily on concentrated precision molding capacity in southern China, creating geographic vulnerability in tier-two supplier networks.
- Reusable Device Regulatory Friction:FDA draft guidance on reprocessing validation for multi-use airway devices is extending development timelines and raising compliance costs versus single-use alternatives.
Strategic Opportunities
- Brazilian Critical Care Infrastructure:ANVISA regulatory harmonization with international standards is opening procurement pathways for foreign manufacturers as Brazil expands ICU bed capacity in southeastern state hospital systems.
- Pediatric Subglottic Suction Integration:Underserved neonatal and pediatric segments present white space for cuff pressure monitoring and micro-aspiration prevention technologies adapted to smaller anatomical specifications.
- Digital Tethering via RFID:Embedding traceable identification chips in airway devices enables automated inventory management and expiration tracking, creating subscription-like revenue streams through hospital information system integration.
Industry Challenges
- ISO 10993-5 Cytotoxicity Testing Bottlenecks:Contract laboratory capacity constraints are extending biocompatibility validation timelines, delaying product launches and freezing working capital in pre-commercial inventory.
- Legacy Anesthesia Machine Interoperability:Proprietary connector standards across ventilator platforms force manufacturers to maintain multiple SKUs, fragmenting production runs and complicating supply chain forecasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tracheal Tube and Airway Products Market |
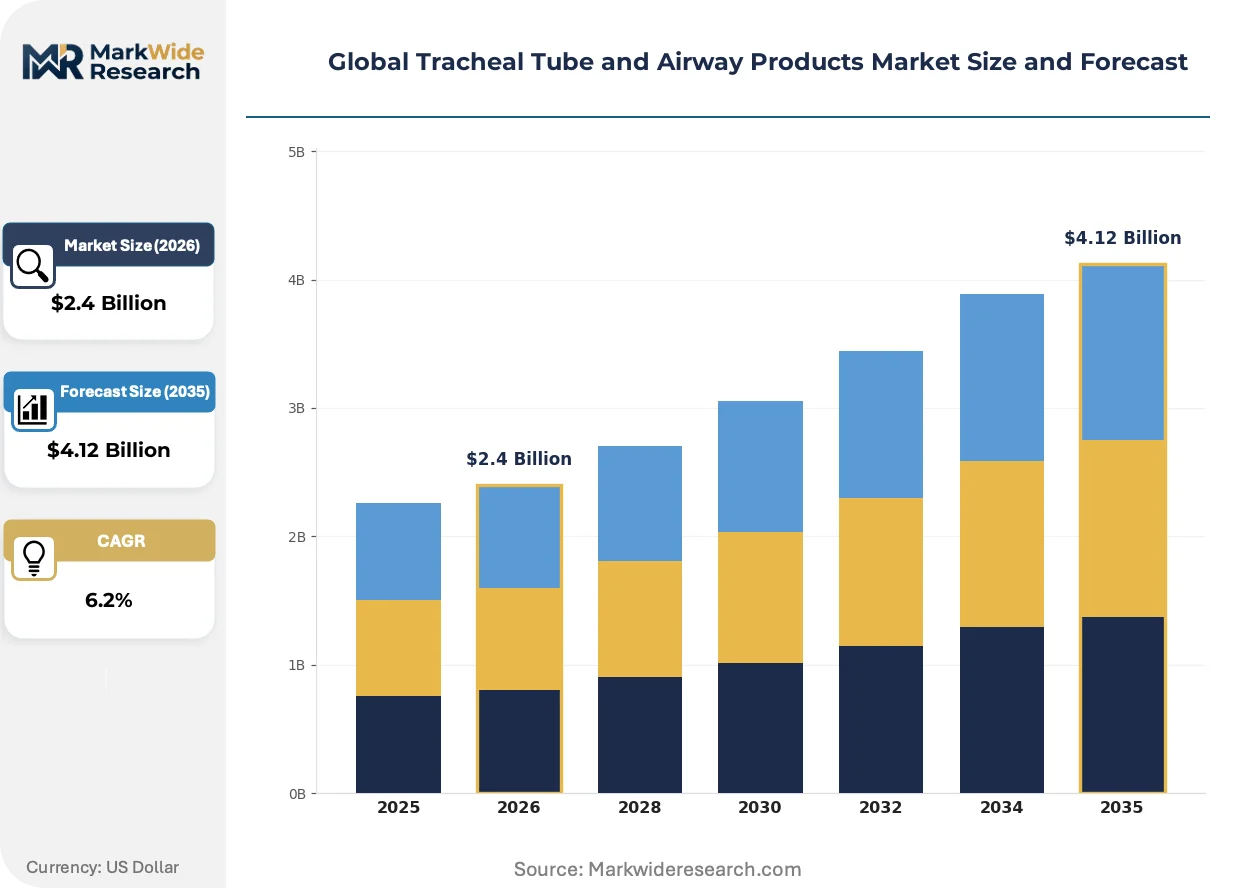
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endotracheal Tubes, Laryngeal Mask Airways, Tracheostomy Tubes, Supraglottic Airway Devices, Airway Exchange Catheters Application: Anesthesia, Emergency Medicine, Critical Care, Neonatal Care, Diagnostic Procedures End User: Hospitals, Ambulatory Surgical Centers, Emergency Medical Services, Specialized Clinics, Home Healthcare Technology: Silicone, Polyvinyl Chloride, Reinforced Tubes, Cuffed Tubes, Uncuffed Tubes |
| Companies Covered | Medtronic, Teleflex, Smiths Medical, Boston Medical Products, Cook Medical, TRACOE Medical, Mercury Medical, ICU Medical, Ambu A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tracheal Tube and Airway Products Market Shifts & Advancements
Digital integration and material science advances are restructuring how airway devices are specified, procured, and monitored across acute care settings, with implications for both product architecture and commercial relationships.
Subglottic suction endotracheal tubes with integrated secretion management channels are virtualizing the traditional separation between airway maintenance and ventilator-associated pneumonia prevention. Critical care units in tertiary hospitals across the United States and Germany are specifying these devices in standard protocols, collapsing what were previously distinct product categories and service lines into unified procurement decisions.
EMA Medical Device Regulation transition deadlines are forcing systematic portfolio rationalization as legacy certificates expire. Manufacturers are withdrawing marginal SKUs rather than absorbing conformity assessment costs, concentrating commercial attention on high-volume tube configurations. This regulatory compression is most acute in tracheostomy tube portfolios, where smaller product variants face disproportionate per-unit compliance burdens relative to revenue contribution.
Hospital material management departments are consolidating supplier relationships through committed volume agreements that bundle airway devices with adjacent critical care consumables. Integrated delivery networks in the United States are replacing transactional purchasing with multi-year contracts tied to utilization benchmarks, transferring demand forecasting risk to manufacturers while securing price predictability. This contractual evolution is most visible in systems managing anesthesia services across multiple surgical sites.
Global Tracheal Tube and Airway Products Market Segmentation
Airway device procurement varies sharply across clinical settings and material specifications. Manufacturers must align production capacity with procedure-specific requirements rather than treating tubes as interchangeable commodities.
Product Type:
Volume concentration and technology intensity diverge across airway device architectures, with invasive versus non-invasive designs serving fundamentally different clinical workflows.
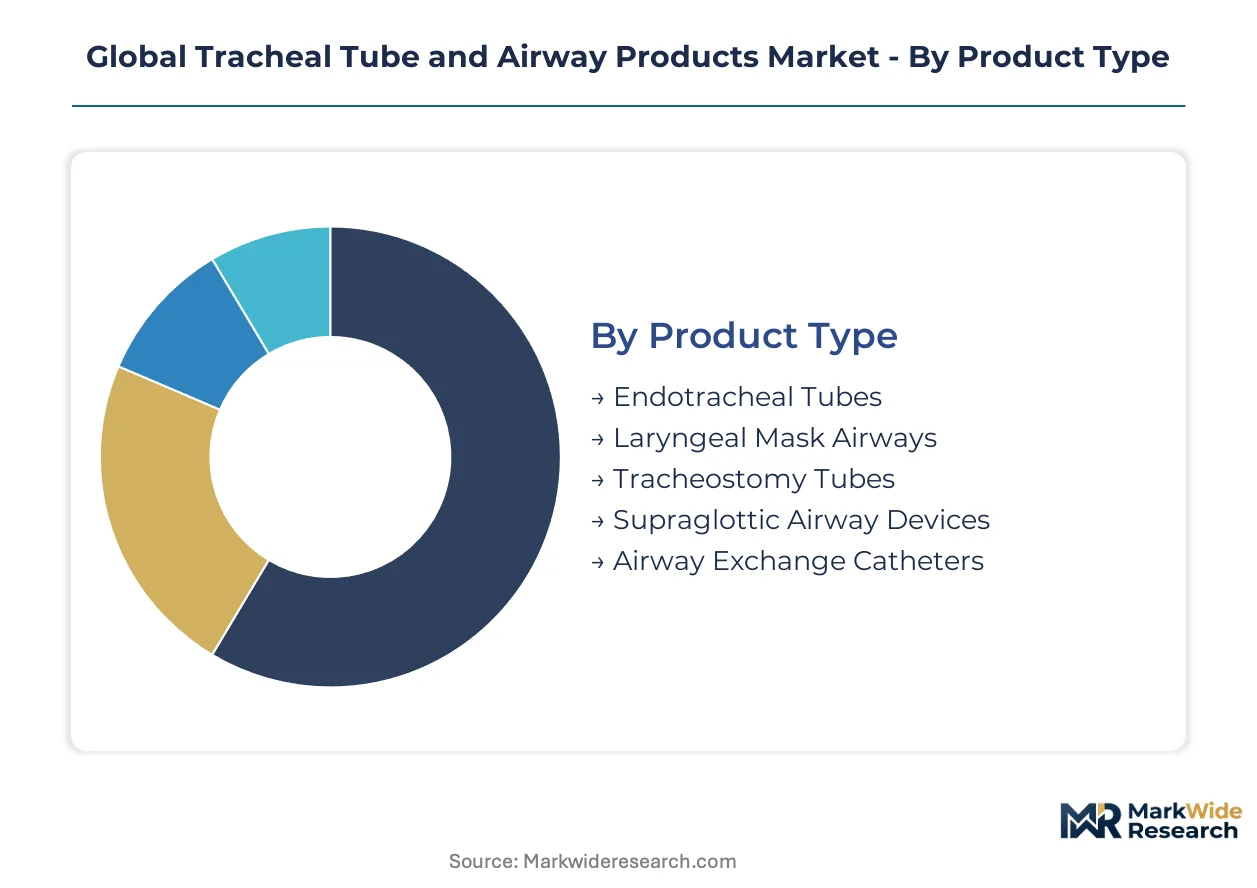
- Endotracheal Tubes:Polyvinyl chloride or silicone construction with high-volume low-pressure cuffs and radiopaque lines for ventilator circuit integration. Demand concentrates in United States tertiary ICUs where ventilator-associated pneumonia prevention protocols mandate subglottic suction variants. Cuff pressure monitoring systems are becoming standard specification in German critical care procurement.
- Laryngeal Mask Airways:Supraglottic devices with inflatable silicone cuffs and anatomically curved shafts for spontaneous or controlled ventilation without tracheal intubation. Ambulatory surgical centers in Japan and the United Kingdom are specifying these for short-duration procedures to accelerate post-anesthesia recovery and same-day discharge eligibility.
- Tracheostomy Tubes:Cuffed or uncuffed designs with inner cannula systems for prolonged airway access in ventilator-dependent patients.
- Supraglottic Airway Devices:Advanced seal mechanisms and gastric access channels for emergency airway management and difficult intubation scenarios.
- Airway Exchange Catheters:Hollow-bore designs for safe endotracheal tube replacement in patients with difficult airways or deteriorating respiratory status.
Endotracheal tubes command the established base. The steepest expansion runs through supraglottic airway devices.
Application:
Clinical workflow characteristics determine device selection criteria, with scheduled procedures versus emergency interventions creating divergent performance requirements.
- Anesthesia:Standard endotracheal and supraglottic devices for operative airway management with predictable duration and controlled conditions. Operating rooms in Germany and the United States are consolidating around single-use silicone laryngeal masks for intermediate-duration cases.
- Emergency Medicine:Rapid-sequence intubation equipment and rescue airway devices for uncontrolled pre-hospital and trauma settings. Emergency departments in Chinese tier-one cities are upgrading difficult airway carts with video laryngoscopy-compatible tube designs.
- Critical Care:Prolonged mechanical ventilation support with specialized tubes for secretion management and pressure injury prevention.
- Neonatal Care:Micro-scale uncuffed tubes with precise diameter specifications for premature infant ventilation.
- Diagnostic Procedures:Temporary airway protection during bronchoscopy, imaging, or other interventions requiring sedation.
Anesthesia maintains the largest installed consumption base. Critical care applications are climbing the fastest as ICU bed expansion accelerates across emerging health systems.
End User:
Procurement authority and volume scale separate institutional buyers, with integrated delivery networks negotiating fundamentally different terms than independent providers.
- Hospitals:High-volume purchasers with centralized materials management and group purchasing organization contracts spanning multiple device categories. United States health systems are bundling airway products with ventilator consumables under multi-year utilization agreements.
- Ambulatory Surgical Centers:Cost-conscious facilities prioritizing rapid turnover and minimal post-procedure monitoring. Japanese day-surgery clinics are driving adoption of disposable supraglottic devices to eliminate reprocessing validation costs.
- Emergency Medical Services:Mobile providers requiring compact, field-durable packaging and intuitive deployment protocols.
- Specialized Clinics:Sleep medicine and interventional pulmonology practices with procedure-specific device preferences.
- Home Healthcare:Long-term tracheostomy care providers managing chronic respiratory support outside institutional settings.
Hospitals anchor procurement volume. Ambulatory surgical centers are gaining share fastest as surgical migration accelerates.
Technology:
Material science differentiation creates tiered performance profiles, with polymer selection directly impacting biocompatibility validation requirements and clinical outcomes.
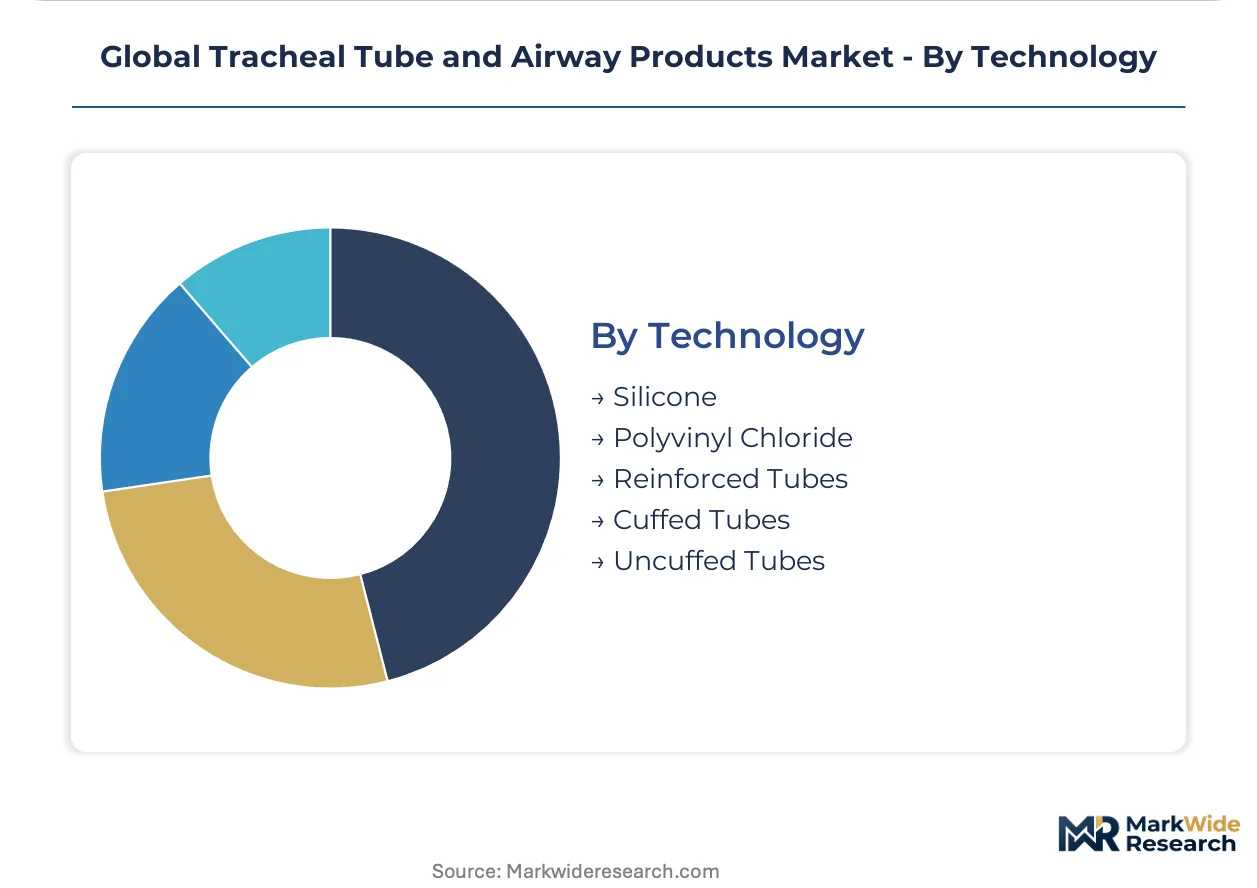
- Silicone:Medical-grade formulations with superior tissue tolerance and extended dwell time compatibility for prolonged intubation. Japanese and German critical care units are specifying silicone endotracheal tubes for anticipated ventilation courses exceeding 72 hours despite 40-60% cost premiums over PVC alternatives.
- Polyvinyl Chloride:Standard thermoplastic construction with adequate performance for short-duration procedures and cost-sensitive procurement. Chinese and Indian hospital systems rely heavily on PVC tubes for high-volume surgical programs where material cost dominates selection criteria.
- Reinforced Tubes:Wire-embedded designs resisting kinking in head-neck positioning or patient movement scenarios.
- Cuffed Tubes:Inflatable seal mechanisms for positive pressure ventilation and aspiration protection.
- Uncuffed Tubes:Pediatric and neonatal designs avoiding subglottic pressure injury in developing airways.
Polyvinyl chloride retains volume leadership. Silicone formulations are expanding most quickly as biocompatibility standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical distribution corridors underwrite European supply chain reliability for airway device logistics, while Shanghai Pudong International Airport's cold-chain cargo terminals anchor Asia-Pacific distribution networks.
United States
Tertiary ICU bed expansion and ventilator-associated pneumonia prevention protocols drive procurement intensity. FDA 510(k) clearance pathways shape product development timelines for domestic manufacturers. The Boston-Cambridge medical device cluster concentrates R&D activity for next-generation airway technologies.
Germany
Cuff pressure monitoring systems and silicone tube specifications dominate critical care procurement standards. EU MDR conformity assessment requirements filter market access for foreign suppliers. The Baden-Württemberg industrial corridor hosts precision molding capacity for high-performance airway components.
China
Tier-one city hospital systems upgrade difficult airway carts and ICU infrastructure at accelerating pace. NMPA medical device registration rules harmonize with international standards. The Yangtze River Delta manufacturing belt concentrates PVC tube production for cost-sensitive domestic and export markets.
Japan
Medical-grade silicone formulations command premium positioning for prolonged intubation protocols. PMDA biocompatibility validation requirements exceed baseline international standards. The Kansai region's polymer processing industry supplies specialized resin formulations to domestic device fabricators.
Brazil
Southeastern state hospital systems expand ICU capacity with foreign manufacturer participation. ANVISA regulatory harmonization opens procurement pathways previously restricted to domestic suppliers. São Paulo's healthcare distribution hub consolidates import logistics for South American markets.
Global Tracheal Tube and Airway Products Market Competitive Landscape
On the supply side, the industry is consolidating around integrated critical care portfolios that bundle airway devices with adjacent consumables. Tier-one manufacturers leverage multi-product contracts across anesthesia and ventilation categories. Three strategic archetypes dominate: diversified medtech conglomerates with broad hospital relationships, specialized airway-focused manufacturers with deep clinical workflow expertise, and regional scale players serving national health systems through cost-competitive production. Dominant competitive moves include portfolio rationalization under tightening regulatory compliance costs and geographic expansion into Brazilian and Southeast Asian procurement channels.
Within the diversified conglomerate tier, Medtronic and Teleflex exemplify portfolio breadth strategies that sustain presence across multiple acute care settings. Smiths Medical occupies a position as a scale-driven manufacturer supplying European and North American health systems through high-volume production infrastructure. Among specialized players, Ambu A/S represents the focused airway expertise archetype with concentrated product development in supraglottic device categories.
| Leading Market Players |
|---|
| Medtronic |
| Teleflex |
| Smiths Medical |
| Boston Medical Products |
| Cook Medical |
| TRACOE Medical |
| Mercury Medical |
| ICU Medical |
| Ambu A/S |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta manufacturing belt concentrates polyvinyl chloride tube production for cost-sensitive procurement, with its capacity utilization rates directly transmitting into pricing power for tier-one medical device distributors across Asian and export markets. Hospital group purchasing organizations leverage this supply concentration to extract volume discounts while silicone formulation specialists in the Kansai region maintain premium positioning through biocompatibility certification scarcity.
Pricing Analysis
Three-tier pricing structure across premium silicone, standard PVC, and economy-grade configurations dominates hospital procurement negotiations, with ISO 10993 biocompatibility validation tier separating premium from standard offerings and raw material grade differentiating standard from economy. Price differentiation hinges on cuff pressure monitoring integration and radiopaque line quality. Cost compression in economy PVC segments is intensifying because Chinese domestic manufacturers are expanding molding capacity. Ambulatory surgical centers exhibit highest price sensitivity; German tertiary ICUs demonstrate lowest sensitivity due to outcome-based procurement protocols.
Supply Chain Analysis
Contract manufacturing concentrates among precision molding specialists in southern China, medical-grade silicone processors in Germany's Baden-Württemberg corridor, and high-volume extrusion facilities in India's Gujarat pharmaceutical zone. Raw material sourcing draws from petrochemical feedstock networks in the Middle East, medical-grade silicone resin suppliers in Japan, and specialized cuff valve component foundries in Taiwan. Single-source vulnerability persists in precision inflation valve molding capacity concentrated in Guangdong province. Distribution runs through hospital group purchasing organization contracts, direct institutional sales teams, and regional medical device distributors serving ambulatory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat defensive structure where FDA 510(k) clearance timelines and EU MDR conformity assessment costs create entrenched switching costs for hospital procurement committees.
For Market Incumbents: Entrench market position by accelerating silicone material substitution R&D to capture German and Japanese premium procurement specifications, while securing backward integration into medical-grade resin supply to offset polymer feedstock volatility. Defend against emerging Chinese manufacturers by deepening GPO contract exclusivity clauses across integrated delivery networks. Prioritize pediatric subglottic suction technology development to occupy underserved neonatal segments before specialized entrants establish clinical evidence.
For New Entrants and Emerging Players: Brazilian southeastern state hospital systems offer the most penetrable geographic entry point given ANVISA regulatory harmonization and ICU bed expansion outpacing domestic manufacturing capacity. Target ambulatory surgical center supraglottic device segments in Japan where reprocessing cost elimination drives disposable preference. Pursue RFID-enabled digital tethering as a service-layer wedge to bypass capital-intensive molding infrastructure requirements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized airway-focused manufacturers with concentrated supraglottic expertise over diversified conglomerates facing portfolio rationalization pressure. Long-term viability across the projection horizon rests on regulatory compliance infrastructure rather than manufacturing scale alone. Acquisition targets should demonstrate EU MDR technical documentation completion and established hospital pharmacy formulary position. Monitor FDA draft guidance finalization on reusable device reprocessing as an inflection signal for single-use demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Completion | Market access preservation for European health system contracts depends on notified body certification renewal. |
| Silicone Material Formulation Partnership | Japanese PMDA biocompatibility validation requires specialized resin sourcing from Kansi polymer processors. |
| Hospital GPO Contract Consolidation | Multi-year utilization agreements with IDNs transfer demand forecasting risk while securing volume commitments. |
| Pediatric Subglottic Suction Development | Neonatal ICU specification gaps present white space for cuff pressure monitoring adapted to micro-scale anatomy. |
| RFID Digital Tethering Integration | Automated inventory management through hospital information system integration creates recurring service revenue streams. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EMA Medical Device Regulation conformity assessment records, and hospital procurement contract disclosures. Primary interviews engaged biomedical engineers at tertiary ICU facilities, group purchasing organization contracts managers, anesthesia department heads, and regulatory affairs specialists at notified bodies. Secondary validation incorporated ISO 10993 biocompatibility testing laboratory capacity reports, ASTM material standard updates, and customs trade data for medical-grade polymer imports. Bottom-up demand modeling triangulated against top-down health system expenditure benchmarks.
Forecast inputs span product type segmentation across endotracheal tubes, laryngeal mask airways, tracheostomy tubes, and supraglottic devices; application segmentation across anesthesia, emergency medicine, critical care, and neonatal protocols; technology segmentation across silicone, PVC, reinforced, and cuffed configurations; and end-user segmentation across hospitals, ambulatory surgical centers, and emergency medical services. CAGRs were derived from procedure volume elasticity modeling, ventilator-associated pneumonia prevention protocol adoption curves, and ICU bed expansion trajectories across emerging health systems.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic manufacturers or sudden polymer feedstock supply disruptions would shift outcomes beyond modeled ranges. Quarterly review of FDA guidance publication timelines, EU MDR certificate expiration schedules, and ANVISA registration approval velocities is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electroceutical Devices Market
Medical Devices
Pannus Retraction Device Market
Medical Devices
Europe Otoscope Market
Medical Devices
Hearing Devices 3D Printing Market
Medical Devices
Active Wheelchair Market
Medical Devices
Orthodontic Headgear Market
Medical Devices
Stimulation Therapies Market
Medical Devices
Superficial Radiation Therapy System Market
Medical Devices
Ligament Augmentation Market
Medical Devices
Active Implantable Devices Market
Medical Devices
US Nebulizer Market
Medical Devices
Global Smart Implants Market
Medical Devices
Next-Generation Neurofeedback Device Market
Medical Devices
Bone Growth Stimulators Market
Medical Devices
Pacemaker Devices Market
Medical Devices
Keratoprosthesis (Kpro) Market