
 Europe Aligner Sheet Market | 2026-2036
Europe Aligner Sheet Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aligner Sheet Market Foresight
Market Context
Orthodontic technician shortages across Central Europe is reorganizing production priorities, pushing laboratories toward automated CAD/CAM workflows and sheet-forming standardization. Align Technology, Inc. leverages its vertically integrated scanner-to-aligner ecosystem to dominate digital case submission volumes across the continent. SCHEU-DENTAL GmbH anchors its position through deep specialization in vacuum-forming materials and regional dental school partnerships. Erkodent Erich Kopp GmbH competes by sustaining a focused portfolio of thermoplastic blanks calibrated for European orthodontic protocols.
Technical Definition and Segments
Europe aligner sheets are precision-engineered thermoplastic films, typically 0.5–1.0 mm in thickness, that dental laboratories thermoform over 3D-printed dental models to fabricate sequential orthodontic appliances. PETG and polyurethane grades deliver the controlled elasticity and optical clarity required for multi-stage tooth movement protocols. Customized aligner sheets command premium positioning due to patient-specific thickness gradients and embedded force systems, while standard aligner sheets serve high-volume orthodontic chains with predictable material economics. Multi-layer aligner sheets represent the fastest-growing material architecture as manufacturers stack rigid and elastomeric substrates to optimize biomechanical control.
Regulatory Environment
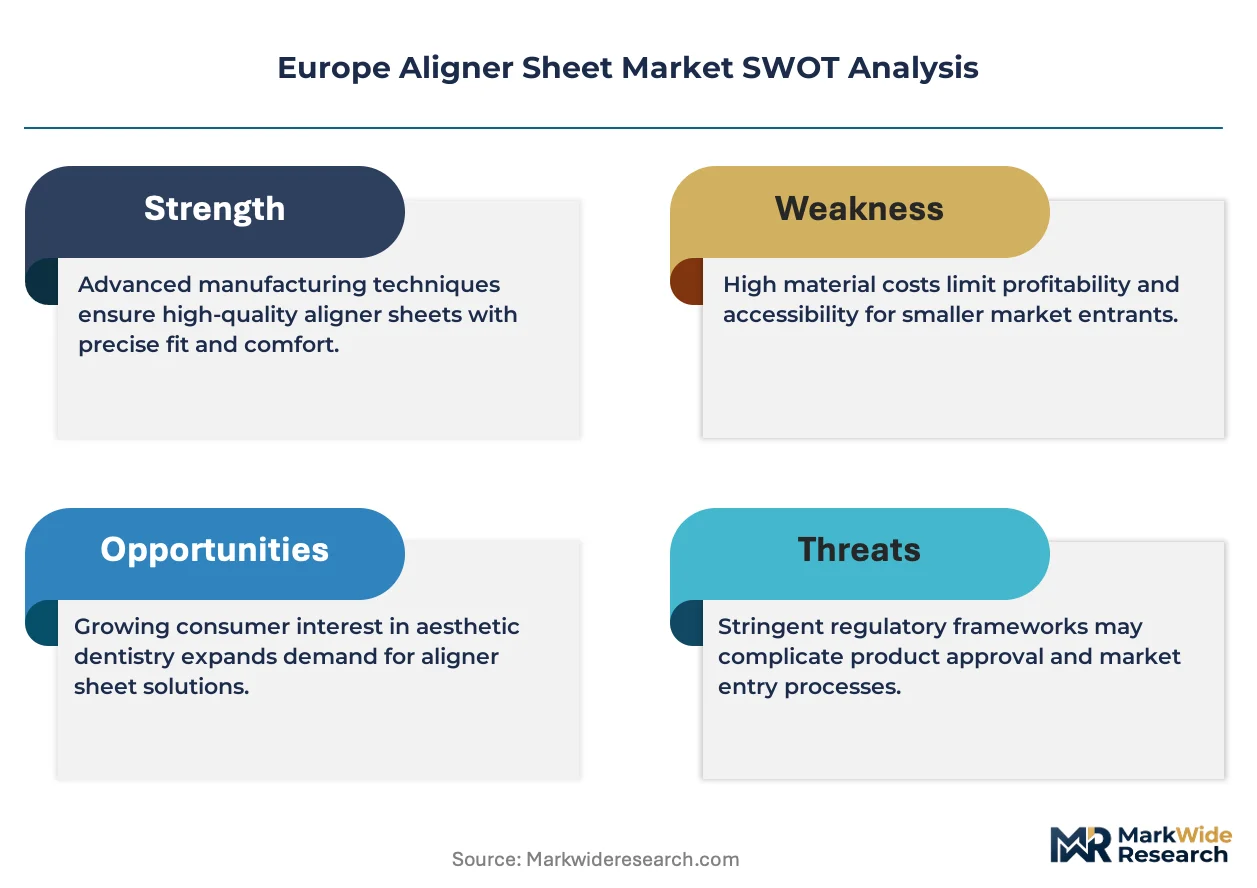
The EU Medical Device Regulation and REACH framework jointly govern biocompatibility certification and chemical disclosure for aligner sheet polymers marketed across member states. EMA-coordinated notified bodies enforce ISO 10993 testing protocols for prolonged mucosal contact, while national health technology assessment agencies in Germany and France increasingly scrutinize cost-effectiveness evidence for clear aligner therapy reimbursement. Stakeholders must monitor evolving MDR classification interpretations and polymer recycling mandates that could reshape raw material sourcing and end-of-life obligations for dental thermoplastic waste streams.
Market Dynamics
EU MDR classification tightening and REACH polymer disclosure mandates are forcing dental thermoplastic suppliers to restructure certification pipelines and raw material traceability systems across the continent.
Growth Catalysts
- EU Medical Device Regulation harmonization:MDR Article 10 quality management system requirements are standardizing biocompatibility documentation across member states, reducing regulatory fragmentation for cross-border sheet distribution.
- Multi-layer material architecture:Stacked rigid-elastomeric substrates enable precise force modulation in complex orthodontic cases, expanding treatable malocclusion severity beyond mild crowding.
- Rhine-Ruhr metropolitan concentration:Dense orthodontic laboratory clustering in Germany's industrial heartland creates efficient just-in-time sheet supply networks with sub-48-hour thermoforming turnaround.
Market Restraints
- Petrochemical feedstock volatility:Purified terephthalic acid and diol prices for PETG synthesis fluctuate with crude oil benchmarks, compressing margin predictability for sheet manufacturers.
- Notified body capacity bottleneck:EMA-coordinated conformity assessment organizations face 12-18 month backlog for MDR Class IIa medical device certification, delaying new polymer grade market entry.
- Fixed appliance substitution resilience:Lingual brackets and self-ligating systems retain cost advantages for complex skeletal discrepancies, limiting clear aligner penetration in severe malocclusion segments.
Strategic Opportunities
- Eastern European orthodontic expansion:Poland and Czech Republic private dental chains are adopting clear aligner protocols, creating demand for standardized sheet grades outside established Western European clusters.
- CE marking mutual recognition:MDR-compliant sheet manufacturers can leverage conformity assessment portability into Swissmedic-regulated Swiss and Turkish markets without redundant testing.
- AI-driven treatment planning convergence:Machine learning algorithms for tooth movement prediction integrate with CAD/CAM nesting software, optimizing sheet yield per thermoforming cycle.
Industry Challenges
- Orthodontic technician labor scarcity:Central European dental laboratory associations report 23% vacancy rates for certified thermoforming specialists, constraining production scale-up despite automated equipment deployment.
- ISO 10993-5 cytotoxicity retesting:REACH substance of very high concern list updates trigger recurring biocompatibility validation for legacy polymer formulations, extending recertification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aligner Sheet Market |
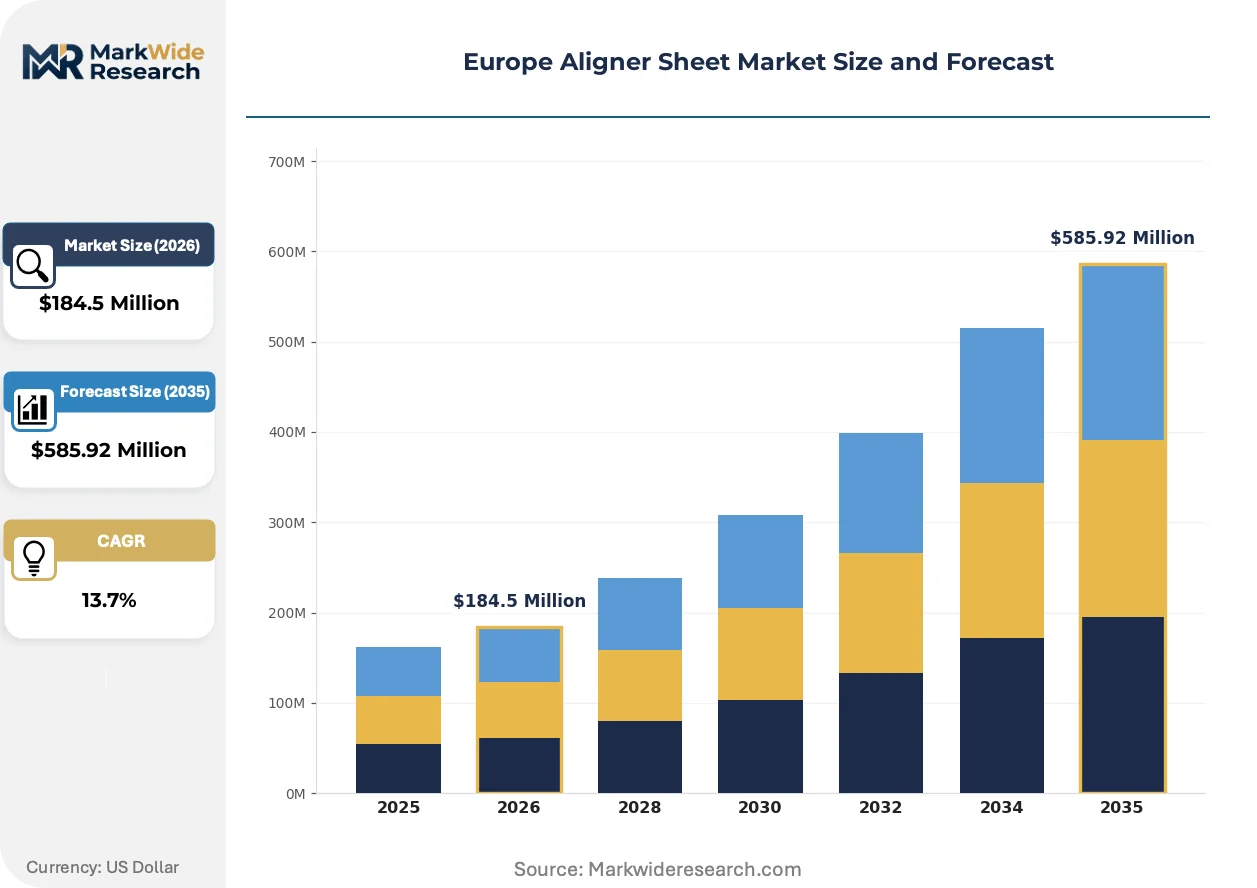
| Market Size in 2026 | $184.5 Million |
| Market Size in 2035 | $585.92 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Aligner Sheets, Customized Aligner Sheets, Multi-Layer Aligner Sheets, Thermoplastic Aligner Sheets End User: Orthodontists, Dental Clinics, Hospitals, Homecare Providers Material: Polycarbonate, Polyurethane, PETG, Biodegradable Plastics Technology: 3D Printing, Injection Molding, CAD/CAM Systems, Vacuum Forming |
| Companies Covered | Align Technology, Inc., Dentsply Sirona, Institut Straumann AG, Ormco Corporation, Dreve Group, SCHEU-DENTAL GmbH, Erkodent Erich Kopp GmbH, 3M Company, Henry Schein, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aligner Sheet Market Shifts & Advancements
Digital workflow integration and material science advances are compressing the traditional separation between diagnostic scanning and physical appliance fabrication across European orthodontic practices.
Multi-layer aligner sheet technology is decomposing the historical trade-off between force delivery precision and patient comfort. PETG-polyurethane hybrid substrates allow orthodontic laboratories to fabricate appliances with zone-specific stiffness gradients. High-volume clear aligner chains in the Paris basin are adopting these materials for moderate complexity cases previously referred to fixed appliance specialists.
REACH SVHC candidate list expansion is compelling polymer suppliers to reformulate plasticizer chemistries and disclose full substance composition down to 0.1% weight thresholds. ECHA notification requirements now cover residual monomers in polyurethane grades used for prolonged mucosal contact. German dental thermoplastic distributors are consolidating supplier base to reduce compliance audit burden across fragmented raw material portfolios.
Direct-to-laboratory digital platforms are compressing traditional dental supply distribution hierarchies. Orthodontic practices in France and Benelux territories increasingly submit intraoral scan files to centralized production hubs, bypassing regional dental dealer networks. This channel reconfiguration concentrates sheet procurement decisions among fewer large-scale laboratory operators with volume pricing leverage.
Europe Aligner Sheet Market Segmentation
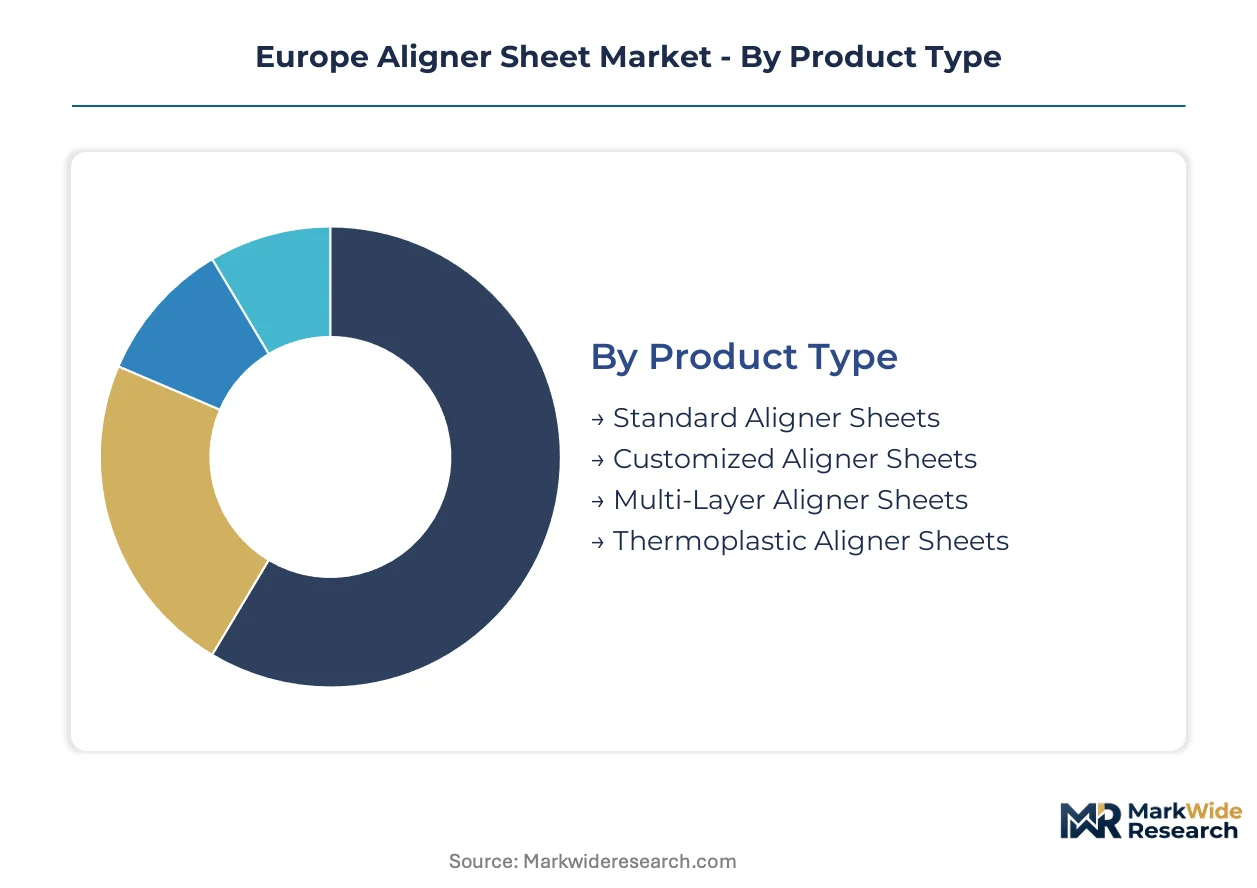
Segmentation in the Europe aligner sheet market reveals how material specifications, fabrication technologies, and clinical settings create distinct margin structures. Understanding these divides helps suppliers allocate R&D resources and optimize regional distribution footprints across Western and Eastern European orthodontic clusters.
Product Type:
Premium margin pools concentrate in patient-specific and multi-layer configurations, while standardized grades compete on throughput efficiency in high-volume laboratory networks.
- Multi-Layer Aligner Sheets:Stacked rigid-elastomeric substrates enable zone-specific stiffness gradients for complex tooth movement protocols. Demand concentrates in the Paris basin and Rhine-Ruhr metropolitan region, where orthodontic chains treat moderate complexity cases previously referred to fixed appliance specialists.
- Customized Aligner Sheets:Patient-specific thickness gradients and embedded force systems command premium positioning through CAD/CAM-integrated production workflows. German and French orthodontic laboratories prioritize these materials for differentiated case outcomes despite higher per-unit material costs.
- Standard Aligner Sheets:Predictable material economics serve high-volume clear aligner chains with simplified thermoforming requirements.
- Thermoplastic Aligner Sheets:General-purpose PETG and polyurethane grades support baseline orthodontic appliance fabrication across Central European dental laboratories.
The dominant share belongs to Standard Aligner Sheets, while Multi-Layer Aligner Sheets is closing the gap fastest.
End User:
Procurement authority and volume scale diverge sharply between institutional settings and independent practice networks across the continent.
- Dental Clinics:Private dental chains in Poland and the Czech Republic are adopting clear aligner protocols, creating concentrated demand for standardized sheet grades outside established Western European clusters.
- Orthodontists:Specialist practices in Germany and France drive specification decisions for premium customized and multi-layer materials through direct laboratory relationships.
- Hospitals:Academic medical centers with orthodontic residency programs source materials through centralized procurement with extended certification documentation requirements.
- Homecare Providers:Direct-to-consumer aligner companies bypass traditional distribution hierarchies, concentrating sheet procurement among fewer large-scale production hubs with volume pricing leverage.
Dental Clinics capture the widest geographic expansion opportunity, though Orthodontists retain the highest per-case material specification authority.
Material:
REACH compliance timelines and biocompatibility certification burdens reshape competitive positioning across polymer categories.
- PETG:Purified terephthalic acid-based copolyesters deliver controlled elasticity and optical clarity for multi-stage protocols. German dental thermoplastic distributors consolidate supplier bases to reduce compliance audit burden across fragmented raw material portfolios.
- Polyurethane:Residual monomer disclosure requirements under ECHA notification protocols now cover prolonged mucosal contact applications. French and Benelux laboratories face reformulation pressures as SVHC candidate list expansion compels plasticizer chemistry changes.
- Polycarbonate:Higher stiffness grades serve specific orthodontic anchorage applications with limited penetration in aesthetic-focused clear aligner segments.
- Biodegradable Plastics:Emerging alternatives face extended ISO 10993-5 cytotoxicity retesting cycles as polymer suppliers navigate end-of-life obligations for dental thermoplastic waste streams.
PETG holds the installed base advantage, while Polyurethane faces the steepest regulatory compliance cost escalation.
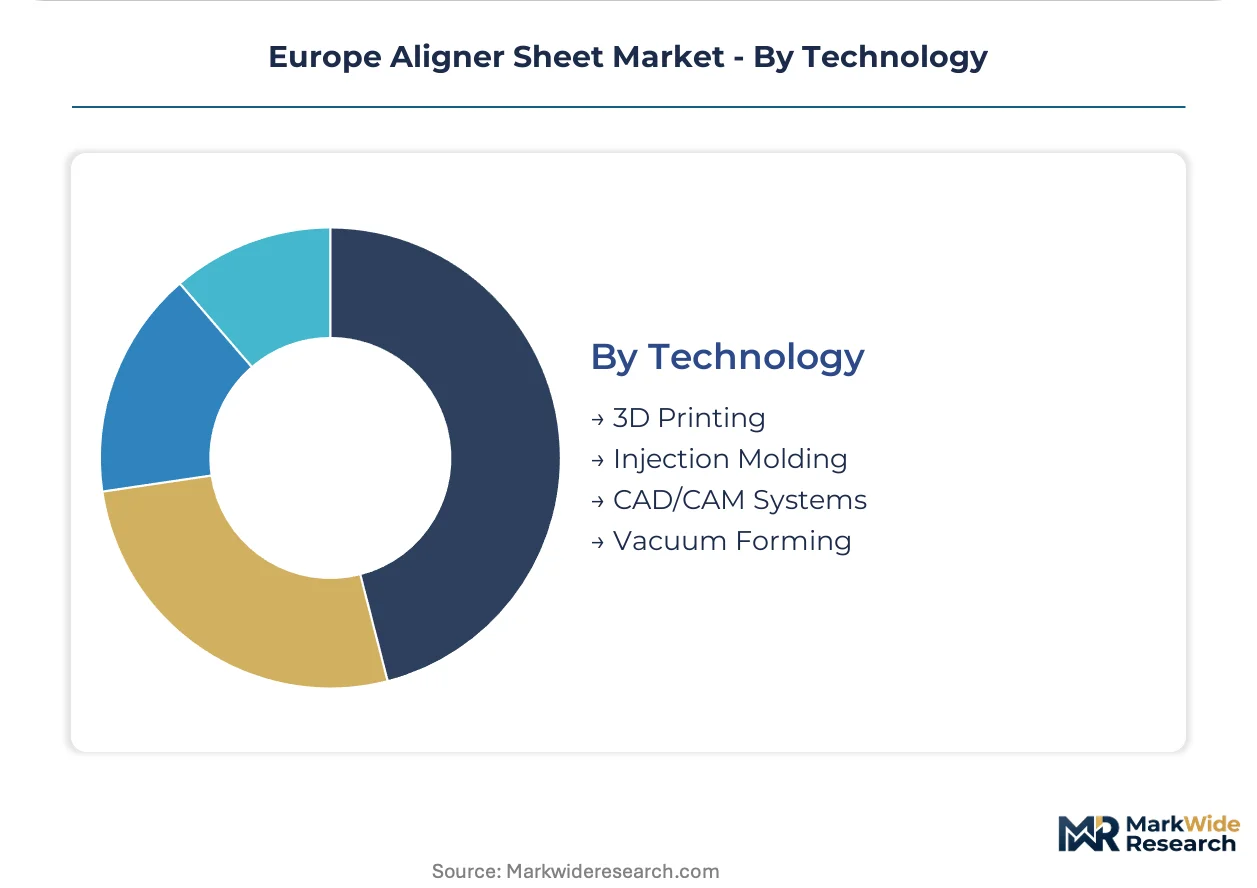
Technology:
Fabrication method selection determines labor efficiency, capital intensity, and integration depth with digital orthodontic workflows.
- CAD/CAM Systems:Machine learning algorithms for tooth movement prediction integrate with nesting software to optimize sheet yield per thermoforming cycle. Central European dental laboratory associations report technician vacancy rates constraining production scale-up despite automated equipment deployment.
- Vacuum Forming:SCHEU-DENTAL GmbH anchors regional specialization through deep expertise in vacuum-forming materials and dental school partnerships across German-speaking markets.
- 3D Printing:Direct aligner fabrication bypasses thermoforming entirely, though material property limitations restrict adoption to specific case types.
- Injection Molding:Mass production economics apply poorly to patient-specific orthodontic appliances, limiting relevance in personalized aligner fabrication.
CAD/CAM Systems command the highest growth trajectory, while Vacuum Forming retains the deepest installed base in traditional laboratory networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA coordinates notified body oversight across member states, anchoring regulatory harmonization efforts that reshape material certification pipelines from the Rhine-Ruhr corridor to the Paris basin.
Germany
The Rhine-Ruhr metropolitan region concentrates Europe's densest orthodontic laboratory clustering, with sub-48-hour thermoforming turnaround networks serving high-volume clear aligner chains. BfArM enforces MDR Article 10 quality management system requirements that standardize biocompatibility documentation for cross-border sheet distribution. Bavaria's dental school partnerships with vacuum-forming material specialists anchor regional expertise development.
France
Private dental chains in the Paris basin adopt multi-layer aligner sheet technology for moderate complexity cases previously referred to fixed appliance specialists. ANSM scrutinizes cost-effectiveness evidence for clear aligner therapy reimbursement alongside EMA-coordinated ISO 10993 testing protocols. The Île-de-France region hosts centralized production hubs that bypass traditional dental dealer networks through direct-to-laboratory digital platforms.
United Kingdom
Orthodontic practices leverage MHRA-recognized CE marking portability to access MDR-compliant sheet supplies from continental manufacturers without redundant testing. London and Southeast England concentrate demand for premium customized aligner sheets with patient-specific thickness gradients. The Medicines and Healthcare products Regulatory Agency enforces prolonged mucosal contact biocompatibility standards that align with EMA-coordinated frameworks.
Italy
Lombardy and Piedmont dental laboratories face REACH SVHC candidate list expansion pressures that compel plasticizer chemistry disclosure for polyurethane grades. The Italian Medicines Agency (AIFA) coordinates with EMA on MDR classification interpretations for dental thermoplastic imports. Northern Italian orthodontic clusters increasingly source PETG-based materials through consolidated supplier bases to reduce compliance audit burden.
Poland
Private dental chains in Warsaw and Kraków adopt clear aligner protocols, creating demand for standardized sheet grades outside established Western European clusters. The Office for Registration of Medicinal Products, Medical Devices and Biocidal Products enforces EU MDR alignment for imported dental thermoplastics. Polish orthodontic laboratory networks benefit from proximity to German supply chains while building independent CAD/CAM integration capabilities.
Europe Aligner Sheet Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European aligner sheet market. Vertically integrated scanner-to-aligner ecosystems dominate digital case submission volumes, while specialized vacuum-forming material suppliers anchor regional production networks through dental school partnerships. The competitive terrain separates into three strategic archetypes: full-stack digital orthodontic platforms, thermoplastic material specialists, and diversified dental supply conglomerates. Market participants defend position through M&A activity targeting CAD/CAM software capabilities and strategic partnerships with centralized production hubs.
Among Germany-based specialists, SCHEU-DENTAL GmbH and Erkodent Erich Kopp GmbH exemplify the material-focused archetype, occupying positions defined by deep regional expertise in vacuum-forming workflows and calibrated thermoplastic portfolios. Align Technology, Inc. represents the vertically integrated platform model, anchoring digital case submission infrastructure across the continent. These three entities illustrate how competitive positioning splits between specialized material science depth and full-stack digital control.
| Leading Market Players |
|---|
| Align Technology, Inc. |
| Dentsply Sirona |
| Institut Straumann AG |
| Ormco Corporation |
| Dreve Group |
| SCHEU-DENTAL GmbH |
| Erkodent Erich Kopp GmbH |
| 3M Company |
| Henry Schein |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Rhine-Ruhr orthodontic laboratories and PETG resin distributors lock in both supply access and price visibility across multi-quarter planning horizons. These arrangements insulate high-volume clear aligner chains from purified terephthalic acid volatility while compressing margin flexibility for smaller independent laboratories.
Pricing Analysis
Price spreads between Paris basin and Warsaw laboratory networks reflect differential REACH compliance cost absorption and logistics clustering. Three-tier pricing structure across premium customized, standard PETG, and economy thermoplastic grades separates orthodontic chains by case complexity and volume scale. Pricing pressure stems from petrochemical feedstock volatility compressing margin predictability for polyurethane grades. Independent dental clinics in Poland and Czech Republic exhibit highest price sensitivity, while German specialist orthodontists prioritize biomechanical performance over per-unit material cost.
Supply Chain Analysis
Inventory cycles stretching 12-18 weeks for MDR-certified polymer grades create working capital intensity for laboratories scaling clear aligner production. Supply concentrates in Germany, Belgium, and Netherlands for REACH-compliant PETG resin, with polyurethane raw materials drawing from French and Italian chemical processors. Single-source vulnerability persists for ECHA-notified plasticizer formulations subject to SVHC candidate list revisions. Distribution runs through consolidated dental thermoplastic distributors serving centralized production hubs, bypassing fragmented regional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward centralized production hubs as direct-to-laboratory digital platforms consolidate procurement authority among fewer large-scale operators across France and Benelux territories.
For Market Incumbents: Shield margin position by deepening backward integration into MDR-certified polymer compounding and securing exclusive capacity reservations with notified body-accredited resin suppliers. The 12-18 month certification backlog for new polyurethane grades threatens supply continuity for competitors lacking pre-qualified material pipelines. Prioritize CAD/CAM nesting software acquisitions to optimize sheet yield per thermoforming cycle against emerging AI-driven competitors. For New Entrants and Emerging Players: Lead with biodegradable plastic formulations targeting sustainability-positioned orthodontic chains in Northern Italy and Scandinavia, where end-of-life waste stream obligations are tightening fastest. Eastern European dental clinics in Poland and Czech Republic represent the most penetrable white-space, with demand for standardized PETG grades outpacing local supply infrastructure. Deploy direct-to-laboratory digital platforms to bypass entrenched distributor hierarchies and capture volume pricing leverage. For Investors and Strategic Acquirers: Capital is best deployed toward specialized vacuum-forming material suppliers with embedded dental school partnerships and pre-MDR certification pipelines, offering defensive positioning through regulatory moats. The 5-10 year viability window favors acquisition targets with demonstrated ISO 10993-5 cytotoxicity validation and consolidated raw material supplier bases. Monitor ECHA SVHC candidate list expansion velocity as the critical inflection signal for polymer reformulation cost spikes and competitive shakeouts.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Pipeline Investment | Pre-qualified polymer grades bypass 12-18 month notified body backlogs that stall competitor market entry. |
| CAD/CAM Software Acquisition | Machine learning nesting algorithms compress sheet waste and defend margin against automated competitors. |
| Biodegradable Plastic R&D Partnership | Early positioning for REACH-mandated end-of-life obligations reshapes material specifications in Italian markets. |
| Eastern European Distribution Buildout | Warsaw and Kraków laboratory networks lack localized supply infrastructure for standardized PETG grades. |
| Dental School Partnership Expansion | SCHEU-DENTAL's Bavaria relationships demonstrate how clinical education channels lock in specification authority. |
Research Methodology
Desk research of ECHA regulatory filings, EU MDR notified body databases, and dental thermoplastic trade flow records preceded structured interviews with orthodontic laboratory directors, CAD/CAM equipment specialists, polymer procurement managers at dental supply distributors, and notified body conformity assessment officers. Primary fieldwork across Rhine-Ruhr, Paris basin, and Warsaw orthodontic clusters was cross-validated against BfArM and ANSM certification registries. Bottom-up laboratory capacity estimates and top-down resin consumption data were triangulated to anchor market sizing.
Variance decomposition across product type, material grade, end-user category, and fabrication technology dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate modeling calibrated to orthodontic case submission volumes and laboratory automation penetration curves. Forecast inputs incorporated REACH SVHC candidate list expansion timelines and MDR classification interpretation drift observed across EMA-coordinated notified bodies.
The analysis sits within stated boundaries; outcomes outside sustained MDR enforcement intensity or abrupt petrochemical feedstock discontinuities would require recalibration. Forecasts reflect documented assumptions regarding laboratory automation adoption curves and regulatory compliance cost pass-through elasticity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Implantable Medical Devices Market
Medical Devices
Global Transcatheter Embolization and Occlusion Devices Market
Medical Devices
Latin America Insulin Syringes Market
Medical Devices
Cannula Market
Medical Devices
Global Vertebral Compression Fracture Devices Market
Medical Devices
Nonvascular Interventional Radiology Devices Market
Medical Devices
Global Tympanostomy Products Market
Medical Devices
China Anesthesia Devices Market
Medical Devices
Hormonal Implants Market
Medical Devices
Support Surfaces Market
Medical Devices
Implantable Medical Devices Market
Medical Devices
Internal Nasal Dilators Market
Medical Devices
Surgical Robotic Services Market
Medical Devices
North America and Europe Group 2 Powered Mobility Devices Market
Medical Devices
Upper Limb Prosthetics Market
Medical Devices
Hearing Aid Dehumidifier Market