
 Korea Pharmaceutical Market | 2026-2036
Korea Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Korea Pharmaceutical Market Outlook
Hospital procurement channels is reconfiguring as consolidated purchasing organizations gain leverage over regional distributors. Celltrion leverages its vertically integrated biomanufacturing campus in Incheon to control costs across biosimilar production. Yuhan Corporation anchors its position through deep R&D partnerships with global innovators in oncology. Samsung Bioepis competes aggressively on price in the European and US biosimilar markets, sustaining margins through scale.
Korea pharmaceuticals encompass chemically synthesized small molecules, recombinant biologics, and complex generics formulated for therapeutic efficacy against acute and chronic diseases, with manufacturing governed by PIC/S GMP standards requiring validated aseptic filling and continuous process verification. Prescription drugs dominate value generation due to reimbursement anchoring within the National Health Insurance Service, while biologics captures the fastest expansion as biosimilar substitution policies deepen. Oncology leads therapy area concentration, reflecting demographic aging and precision medicine infrastructure investments across major university hospitals.
MFDS enforces bioequivalence standards for generics and oversees clinical trial approvals, directly shaping product development timelines and market entry sequencing for domestic manufacturers. KFDA legacy frameworks and Ministry of Health and Welfare reimbursement panels determine which therapies achieve national formulary inclusion, conditioning commercial viability before launch. Stakeholders must monitor evolving biosimilar interchangeability guidelines and hospital procurement centralization to anticipate margin compression and partnership requirements.
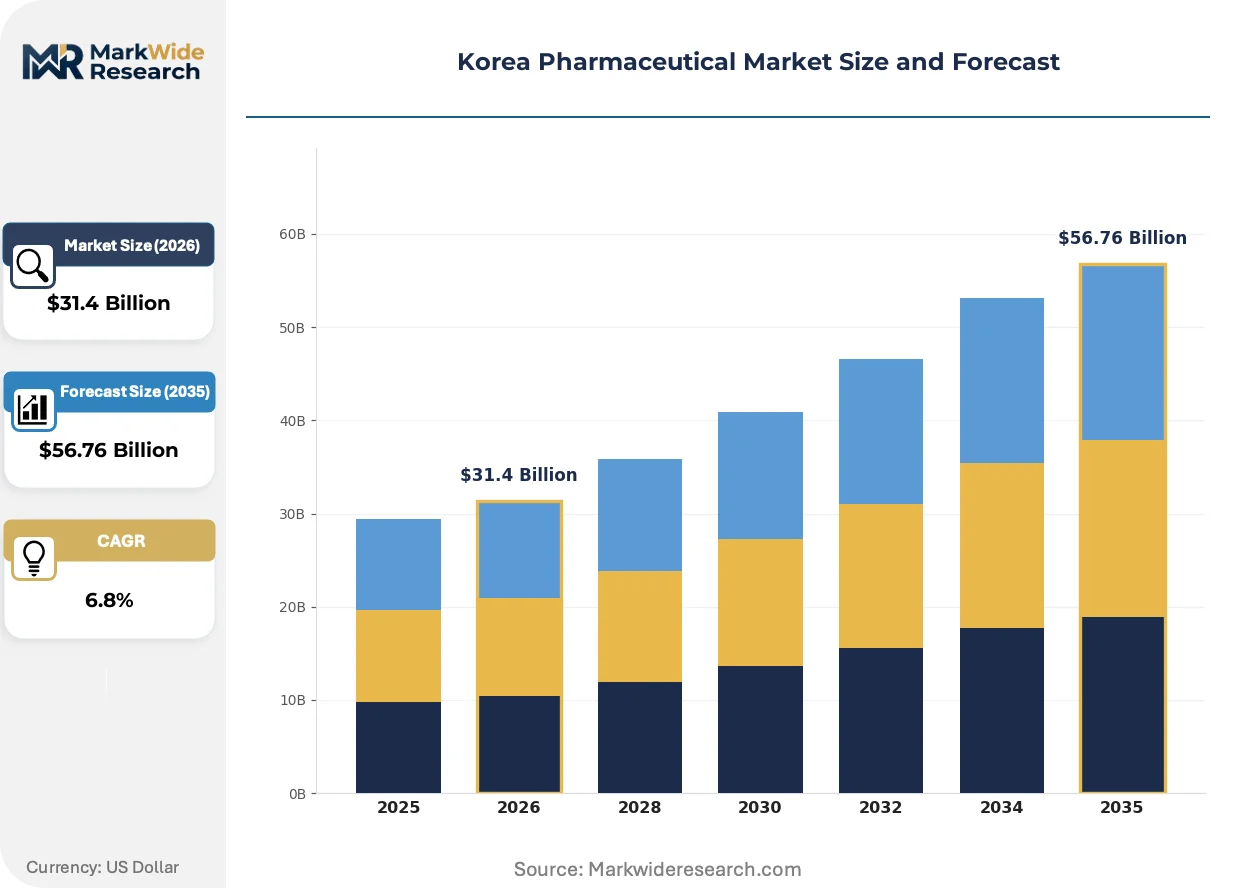
Market Dynamics
Consolidated hospital purchasing organizations are reconfiguring procurement leverage across South Korea's pharmaceutical distribution tier, compressing margins for regional wholesalers while favoring manufacturers with direct-to-institution logistics capabilities.
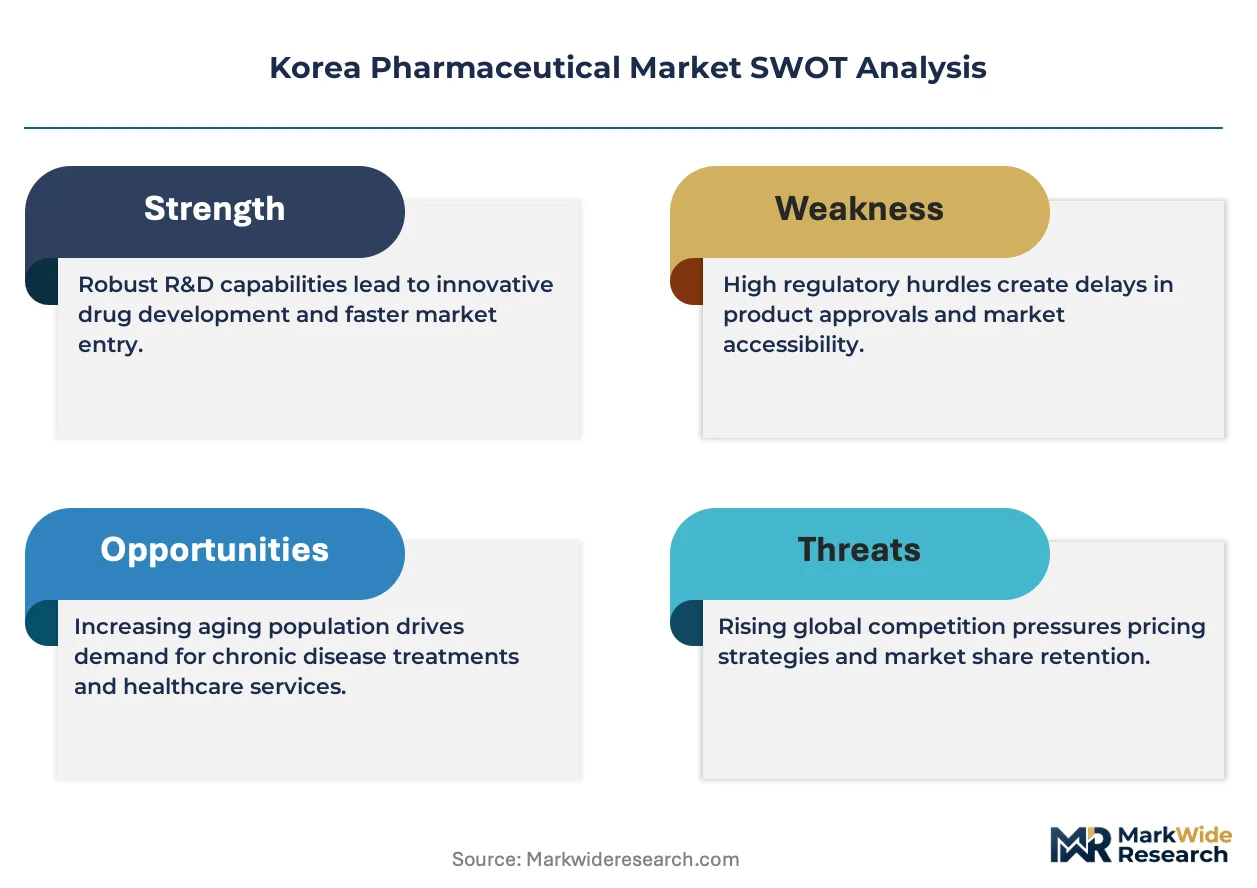
Growth Catalysts
- NHIS reimbursement expansion:The National Health Insurance Service broadened coverage for cell and gene therapies, pulling novel biologics into hospital formularies faster than historical adoption curves.
- Oncology infrastructure:Major university hospitals in Seoul anchored precision medicine investments, concentrating demand for targeted therapies and companion diagnostics.
- MFDS GMP harmonization:South Korea's pharmaceutical regulator aligned verification protocols with PIC/S standards, accelerating import approvals for compliant overseas manufacturers.
Market Restraints
- API import concentration:Active pharmaceutical ingredient sourcing clusters heavily in Chinese chemical manufacturing zones, exposing Korean formulators to geopolitical supply interruptions.
- Biosimilar margin compression:Aggressive substitution policies within NHIS reimbursement panels erode pricing power for originator biologics facing multi-source competition.
- Clinical trial site scarcity:Patient recruitment bottlenecks at Seoul's tertiary hospitals extend development timelines for domestic innovators competing for investigator attention.
Strategic Opportunities
- Busan-Ulsan corridor:Underpenetrated regional hospitals outside the Seoul metropolitan area present whitespace for specialty therapy administration infrastructure.
- Digital therapeutics integration:Convergence of prescription pharmaceuticals with software-based interventions opens reimbursement pathways under evolving MFDS digital health frameworks.
- Outbound biosimilar licensing:Korean manufacturers with demonstrated bioequivalence data capture partnership value in Southeast Asian markets seeking proven regulatory dossiers.
Industry Challenges
- Bioprocessing talent scarcity:Cell culture and aseptic filling expertise concentrates among a limited pool of specialists trained at Samsung Biologics and Celltrion facilities.
- Legacy ERP integration:Hospital procurement systems require costly customization to interface with consolidated purchasing organization platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Korea Pharmaceutical Market |
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $56.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter, Biologics, Generics Therapy Area: Oncology, Cardiovascular, Neurology, Endocrinology Delivery Mode: Oral, Injectable, Topical, Transdermal End User: Hospitals, Pharmacies, Clinics, Research Institutions |
| Companies Covered | Celltrion, Yuhan Corporation, Hanmi Pharmaceutical, Daewoong Pharmaceutical, GC Pharma, Samsung Bioepis, Chong Kun Dang Pharmaceutical, Boryung Pharmaceutical, SK Biopharmaceuticals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Korea Pharmaceutical Market Strategic Shifts
Continuous manufacturing platforms and real-time release testing are compressing batch cycle times while MFDS adapts inspection protocols for process analytical technology submissions.
Single-use bioreactor systems are rendering obsolete stainless steel fermentation infrastructure across Korean contract manufacturing organizations. CDMOs serving both domestic innovators and multinational licensees adopt disposable downstream processing to reduce cross-contamination risk and facility turnaround time. This shift is rendering obsolete capital-intensive cleanroom investments that previously anchored competitive moats for established biomanufacturers.
MFDS tightened data integrity requirements for computerized systems in GMP environments, mandating audit trail completeness for chromatography and spectroscopy platforms. Pharmaceutical manufacturers face validation cost burdens for legacy laboratory information management systems. Domestic generics producers with limited IT budgets defer ANDA filings rather than upgrade documentation infrastructure.
Hospital pharmacy committees increasingly source through centralized procurement consortia rather than maintaining independent vendor relationships. Regional distributors lose access to formulary placement decisions as purchasing power concentrates among GPOs anchored at Asan Medical Center and Seoul National University Hospital. This concentration is most visible in the Seoul-Gyeonggi corridor where tertiary institutions account for disproportionate specialty drug volume.
Korea Pharmaceutical Market Segmentation
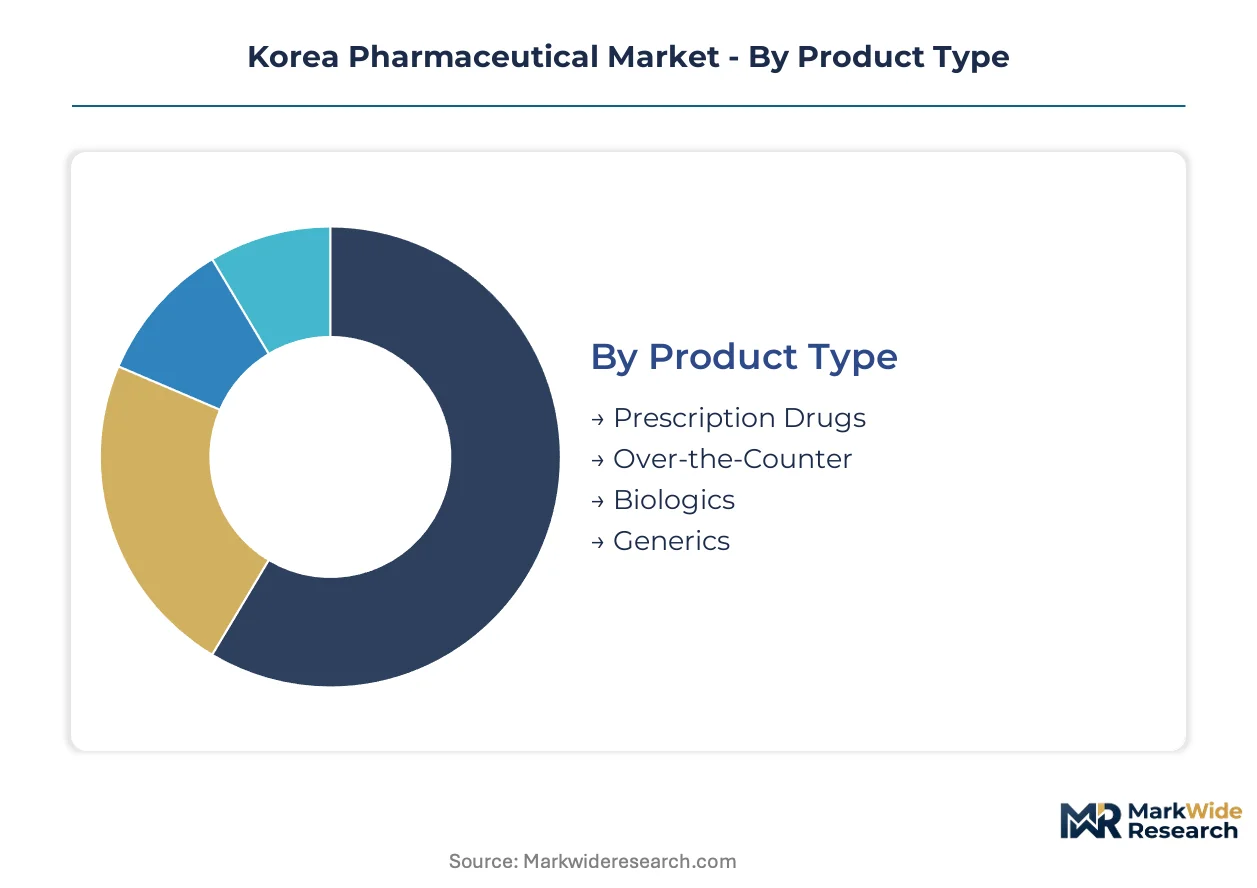
Segmentation in the Korean pharmaceutical market reveals how NHIS reimbursement tiers, MFDS approval pathways, and hospital procurement concentration allocate commercial value across product categories. Manufacturers calibrate portfolio investments against these structural boundaries.
Product Type:
Cost tier differentiation separates originator therapies from substitutable alternatives, with reimbursement anchoring determining commercial viability before launch.
- Prescription Drugs:Chemically synthesized small molecules requiring MFDS new drug approval and NHIS formulary inclusion. Demand concentrates at Asan Medical Center and Seoul National University Hospital where specialist prescribing anchors volume. Reimbursement panels condition pricing power through reference-based benchmarks.
- Biologics:Recombinant proteins and monoclonal antibodies manufactured through mammalian cell culture. Samsung Biologics and Celltrion control domestic capacity. Biosimilar substitution policies within NHIS accelerate uptake while compressing originator margins.
- Over-the-Counter:Self-medication products distributed through community pharmacy networks without prescription requirements.
- Generics:Bioequivalent small molecules competing on price through MFDS abbreviated approval pathways.
Biologics holds installed capacity. Prescription Drugs is rotating up the share rankings.
Therapy Area:
Application concentration reflects disease burden demographics and precision medicine infrastructure investments across Korean university hospitals.
- Oncology:Targeted therapies and immuno-oncology agents commanding premium reimbursement. Major Seoul tertiary hospitals anchor clinical trial recruitment and companion diagnostic integration. Aging demographics deepen addressable patient pools.
- Cardiovascular:Chronic disease management protocols spanning statins, anticoagulants, and heart failure therapies. Regional hospitals outside Seoul metropolitan corridor present whitespace for specialty therapy penetration.
- Neurology:Alzheimer's and Parkinson's treatments facing development timeline extensions due to patient recruitment bottlenecks.
- Endocrinology:Diabetes and thyroid therapies with established generic substitution profiles.
Oncology captures the steepest expansion trajectory. Cardiovascular maintains volume leadership through chronic administration patterns.
Delivery Mode:
Volume distribution reflects administration site economics and patient compliance requirements across Korean healthcare settings.
- Injectable:Biologics and hospital-administered therapies requiring cold chain logistics and aseptic handling. Consolidated purchasing organizations favor manufacturers with direct-to-institution capabilities. Single-use bioreactor systems reduce batch contamination risk.
- Oral:Small molecule tablets and capsules dominating outpatient prescriptions. Community pharmacy networks handle fulfillment with MFDS bioequivalence standards governing generic substitution.
- Topical:Dermatological and localized pain management formulations.
- Transdermal:Controlled-release patches for chronic conditions requiring steady plasma concentration.
Injectable commands manufacturing complexity premiums. Oral rotates up through biosimilar conversion programs.
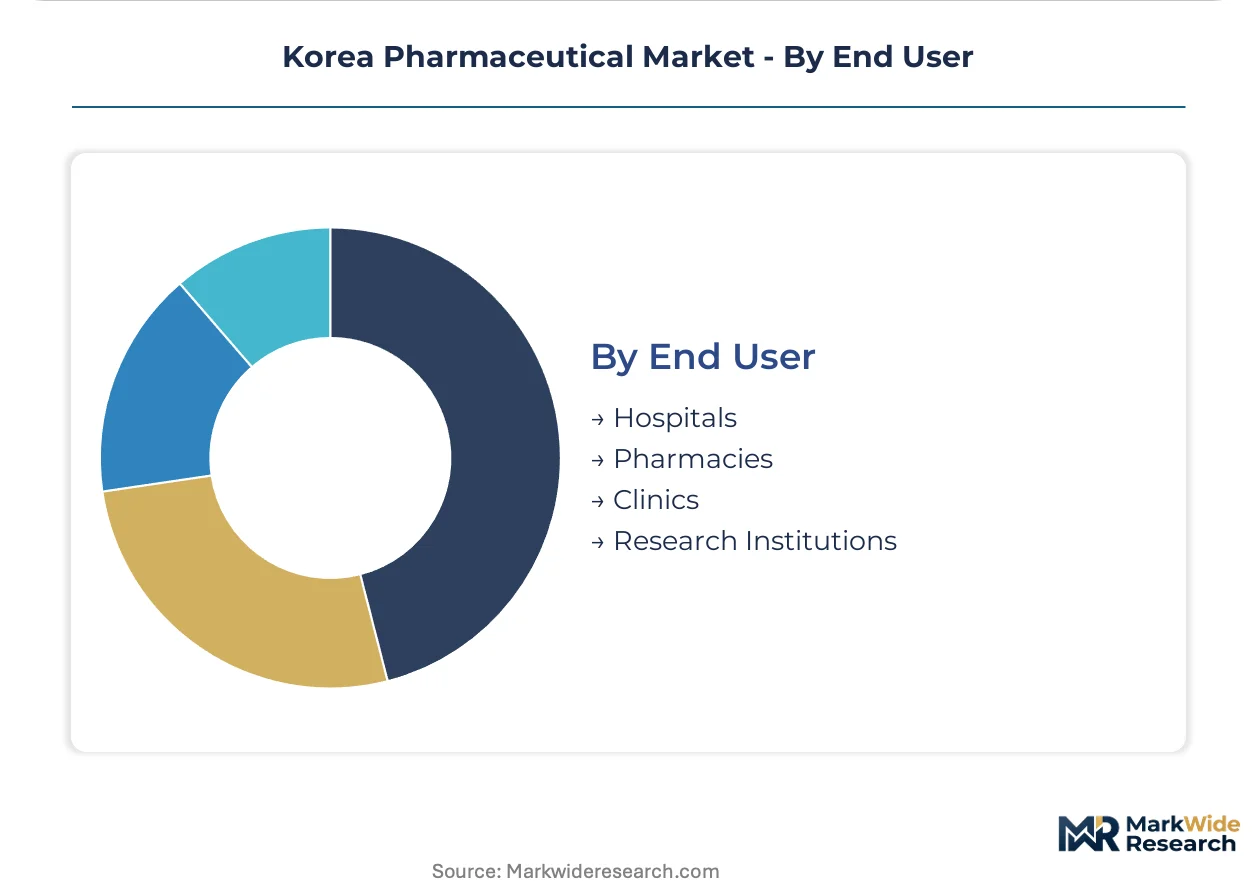
End User:
Customer type concentration determines channel strategy and margin structure for pharmaceutical manufacturers operating in Korea.
- Hospitals:Tertiary institutions in Seoul-Gyeonggi corridor accounting for disproportionate specialty drug volume. Centralized procurement consortia compress distributor margins while amplifying manufacturer scale requirements.
- Pharmacies:Community dispensaries handling outpatient prescriptions with NHIS reimbursement anchoring. Regional wholesalers lose leverage as purchasing power concentrates.
- Clinics:Specialist outpatient facilities with limited formulary autonomy.
- Research Institutions:Academic medical centers conducting investigator-initiated trials and early-phase clinical development.
Hospitals holds procurement concentration. Pharmacies is rotating up through digital therapeutics integration pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHIS reimbursement expansion and MFDS regulatory harmonization are redistributing pharmaceutical demand across Korean metropolitan corridors. Provincial governments compete for biomanufacturing investment through tax incentives and specialized zone designations.
Seoul Capital Area
Asan Medical Center and Seoul National University Hospital anchor specialty drug procurement through centralized purchasing consortia. The Ministry of Health and Welfare operates reimbursement panels that condition formulary inclusion on cost-effectiveness benchmarks. Songdo's bio cluster attracts CDMO investment with streamlined MFDS inspection protocols.
Busan-Ulsan Corridor
Underpenetrated regional hospitals present whitespace for oncology and cardiovascular therapy administration infrastructure. Ulsan's industrial chemical base supplies API precursors to domestic formulators. Busan port logistics handle temperature-controlled biologics imports for Gyeongsang provinces.
Daegu-Gyeongbuk
Celltrion's vertically integrated biomanufacturing campus in Incheon sources talent from regional universities with bioprocessing programs. The Daegu metropolitan government offers subsidized land for pharmaceutical logistics facilities. Gyeongbuk's medical device cluster converges with drug delivery system innovation.
Daejeon-Sejong
Korea Research Institute of Bioscience and Biotechnology anchors public-sector drug discovery collaboration. Sejong City's administrative relocation concentrates regulatory affairs professionals near MFDS headquarters. Daejeon's KAIST and Chungnam National University feed clinical trial investigator pools.
Gwangju-Honam
Chonnam National University Hospital anchors Honam region specialty prescribing with limited biosimilar penetration relative to Seoul benchmarks. Gwangju's free economic zone incentives target pharmaceutical distribution center investment. Jeolla provinces remain dependent on Seoul-based wholesalers for cold chain biologics.
Korea Pharmaceutical Market Competitive Environment
On the supply side, the industry is consolidating around integrated biomanufacturers with captive capacity and research-intensive innovators with global partnership networks. Three archetypes dominate: vertically integrated biosimilar producers controlling fermentation through fill-finish, mid-cap specialty pharmaceutical firms with therapeutic area concentration, and contract development organizations serving multinational licensees. Competitive moves center on backward integration into active pharmaceutical ingredient production and strategic alliances for cell and gene therapy platform access.
Among Korean pharmaceutical producers, Celltrion exemplifies the integrated biomanufacturer archetype through its Incheon campus operations. Yuhan Corporation occupies a position among research-intensive innovators with oncology partnership networks. Samsung Bioepis sits within the biosimilar specialization tier competing in external markets.
| Leading Market Players |
|---|
| Celltrion |
| Yuhan Corporation |
| Hanmi Pharmaceutical |
| Daewoong Pharmaceutical |
| GC Pharma |
| Samsung Bioepis |
| Chong Kun Dang Pharmaceutical |
| Boryung Pharmaceutical |
| SK Biopharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
API import concentration in Chinese chemical manufacturing zones exposes Korean formulators to geopolitical supply interruptions that simultaneously widen pricing tier spreads between secured-originator and at-risk-generic portfolios while compressing margins across both tiers. NHIS reimbursement panels exploit this vulnerability by accelerating biosimilar substitution policies that erode originator pricing power while regional distributors absorb cost volatility through inventory carrying positions.
Pricing Analysis
Certification level under MFDS GMP verification protocols creates the primary spread between premium biologics and standard generic tiers. Pricing stratifies across premium originator biologics, standard biosimilars, and economy small-molecule generics with reimbursement anchoring determining commercial viability before launch. Cost compression in the biosimilar tier is intensifying because aggressive NHIS substitution policies force multi-source competition. Hospital procurement organizations demonstrate lowest price sensitivity due to captive patient volumes, while regional pharmacies face highest sensitivity as reimbursement benchmarks tighten.
Supply Chain Analysis
Extended payment terms from consolidated hospital purchasing organizations strain working capital for regional distributors serving secondary cities. Active pharmaceutical ingredient sourcing clusters heavily in China and India, with specialized fermentation inputs drawing from Japan and Singapore. Korean formulators face single-source vulnerability for mammalian cell culture media and chromatography resins. Distribution runs through temperature-controlled logistics networks anchored at Incheon International Airport and Busan port facilities, with direct-to-institution delivery capabilities becoming the decisive competitive filter.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Korea pharmaceutical market sits at a platform-economics inflection where digital therapeutics integration under evolving MFDS frameworks restructures reimbursement pathways and partnership requirements across the value chain.
For Market Incumbents: Entrench formulary positioning through backward integration into active pharmaceutical ingredient production, securing supply continuity against Chinese import concentration risks. Deepen vertical control over cold chain logistics capabilities to satisfy consolidated purchasing organization requirements at Asan Medical Center and Seoul National University Hospital. Prioritize certification investment for PIC/S GMP alignment to accelerate overseas manufacturing site approvals. For New Entrants and Emerging Players: Pursue the Busan-Ulsan corridor where underpenetrated regional hospitals present whitespace for oncology and cardiovascular therapy administration infrastructure. Target digital therapeutics convergence opportunities under evolving MFDS frameworks that open reimbursement pathways for software-based interventions. Deploy partnership-based go-to-market models with established CDMOs to bypass bioprocessing talent scarcity constraints. For Investors and Strategic Acquirers: MFDS digital health framework finalization reshapes the acquisition landscape by validating platform economics for therapeutics-software convergence. Long-term viability centers on targets with demonstrated bioequivalence data and regulatory dossiers transferable to Southeast Asian markets. Watch biosimilar interchangeability guideline evolution as the decisive signal for margin compression velocity and partnership premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Production | Reduces exposure to Chinese supply interruptions while securing MFDS GMP verification compliance. |
| Digital Therapeutics Platform Development | Opens reimbursement pathways under evolving MFDS frameworks for prescription-software convergence. |
| CDMO Capacity Expansion in Incheon | Leverages Songdo bio cluster inspection protocols to attract multinational licensee contracts. |
| Hospital Procurement Consortium Alignment | Secures formulary placement through direct-to-institution logistics capabilities at tertiary centers. |
| Southeast Asian Regulatory Dossier Licensing | Captures partnership value in markets seeking proven MFDS bioequivalence documentation. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation through MFDS filings, NHIS reimbursement panel decisions, ClinicalTrials.gov records, and customs import data. Bottom-up modeling of manufacturer capacity and top-down reconciliation against NHIS expenditure reports provided triangulation across the analysis window.
Forecast inputs span product type segmentation by reimbursement tier, therapy area concentration by hospital infrastructure, delivery mode by administration site economics, and end user channel structure by procurement consolidation. CAGRs derive from patient population projections, biosimilar penetration curves, and MFDS approval velocity assumptions across the modeling period. Treatment line positioning and regional regulatory cluster differentiation anchor the analytical framework.
Macroeconomic conditions sit as an overlay; deviation in Korean won exchange rates, API import tariff regimes, or NHIS budget allocation priorities would shift the trajectory. Forecasts reflect documented assumptions about biosimilar substitution policy continuity and MFDS inspection protocol stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Human Growth Hormone (HGH) Market
Pharmaceuticals
Long-Acting Monoclonal Antibodies Market
Pharmaceuticals
Global Anti-Fungal Drugs Market
Pharmaceuticals
Global Fondaparinux Market
Pharmaceuticals
Prothrombin Complex Concentrate (PCC) Market
Pharmaceuticals
Veterinary Insulin Drugs Market
Pharmaceuticals
GCC Generic Injectables Market
Pharmaceuticals
Antiandrogens Market
Pharmaceuticals
Global Antipyretic Drugs for Children Market
Pharmaceuticals
Global Gout Therapeutics Market
Pharmaceuticals
Rosuvastatin Market
Pharmaceuticals
HIV Antivirals Market
Pharmaceuticals
Global Varicella Vaccine Market
Pharmaceuticals
RAS-Acting Agents Market
Pharmaceuticals
Global Topical Analgesic Market
Pharmaceuticals
Intravenous (IV) Iron Drugs Market