
 Bare Metal Stents Market | 2026-2036
Bare Metal Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Bare Metal Stents Market Analysis
Multi-sourced component procurement is pivoting toward captive manufacturing as stent makers seek tighter metallurgical control. Abbott Laboratories leverages its in-house wire-drawing capabilities to secure cobalt-chromium supply chains. Medtronic plc anchors North American production through vertically integrated balloon-expandable platforms. Boston Scientific Corporation competes on precision laser-cutting scale across its Massachusetts and Ireland facilities.
A bare metal stent is a tubular mesh scaffold manufactured from biocompatible alloys such as 316L stainless steel or cobalt-chromium, deployed via catheter-based systems to mechanically prop open narrowed arterial lumens and restore blood flow. Coronary stents occupy the dominant revenue position given established percutaneous coronary intervention protocols, while peripheral stents represent the fastest-expanding application segment driven by rising diabetic limb ischemia cases. Ureteral stents command narrower volumes but sustain premium pricing through specialized urological deployment requirements.
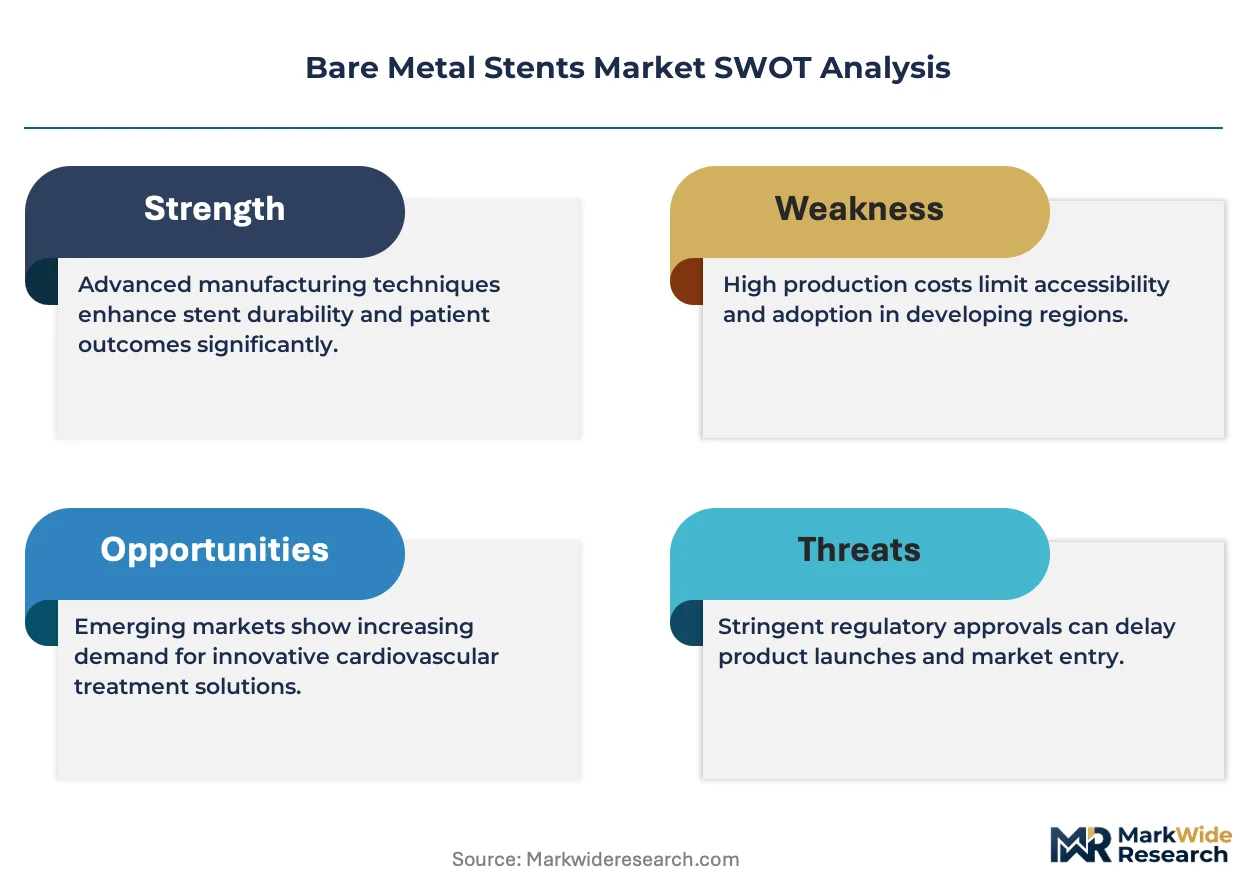
FDA premarket notification and EU MDR conformity assessment create divergent compliance burdens that filter market entrants by certification capacity. ISO 25539 standards govern endovascular stent mechanical validation, while Japan's PMDA mandates separate clinical bridging studies for alloy composition changes. Stakeholders must monitor evolving bioresorbable scaffold trial outcomes that could abruptly redirect interventional cardiology procurement preferences.
Market Dynamics
Metallurgical supply concentration is compressing margin structures as cobalt-chromium alloy procurement tightens around a handful of certified wire-drawing facilities. This concentration is forcing stent manufacturers to secure captive production capacity or accept extended lead times from third-party suppliers.
Growth Catalysts
- India's tertiary cardiac expansion:Government health schemes including Ayushman Bharat are extending percutaneous coronary intervention access to previously uninsured patient pools, driving procedural volume growth in metropolitan hospital clusters.
- EU MDR transition completion:The Medical Device Regulation's full enforcement is filtering out non-compliant manufacturers and consolidating market access for certified producers with robust quality management systems.
- Laser-cutting precision advances:Femtosecond laser systems are enabling strut thickness reduction below 80 microns, improving deliverability and expanding treatable lesion complexity in coronary applications.
Market Restraints
- Cobalt-chromium price volatility:Mining concentration in the Democratic Republic of Congo and processing bottlenecks in China create input cost instability that erodes predictable margin planning for alloy-dependent manufacturers.
- Bioresorbable scaffold substitution threat:Abbott's Absorb and competing polymer platforms, despite prior setbacks, continue advancing through redesigned iterations that could redirect interventional cardiology procurement away from permanent metal implants.
- Japan PMDA clinical bridging requirements:Alloy composition changes trigger mandatory domestic safety studies that extend time-to-market by 18-24 months versus FDA 510(k) pathways, creating regulatory friction for product line refreshes.
Strategic Opportunities
- Peripheral artery disease underpenetration:Diabetic limb ischemia prevalence in Brazil and Mexico exceeds stent deployment rates by a factor of three, creating procedural expansion potential as vascular surgery capacity builds.
- Drug-coated balloon convergence:Combination therapy protocols pairing bare metal stents with paclitaxel-eluting balloons are opening hybrid reimbursement categories in Germany's DRG system.
- Direct hospital procurement channels:Cardiac catheterization laboratories in Poland and Czech Republic are consolidating purchasing through group procurement organizations, bypassing traditional distributor markups for high-volume accounts.
Industry Challenges
- Precision welding skill scarcity:Cobalt-chromium laser welding for stent joints requires specialized metallurgical expertise that outpaces vocational training pipeline output in Ireland and Massachusetts manufacturing clusters.
- ISO 25539-2 fatigue testing capex:Accelerated durability validation equipment for 400 million cycle simulations demands capital allocations exceeding smaller manufacturers' annual R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bare Metal Stents Market |
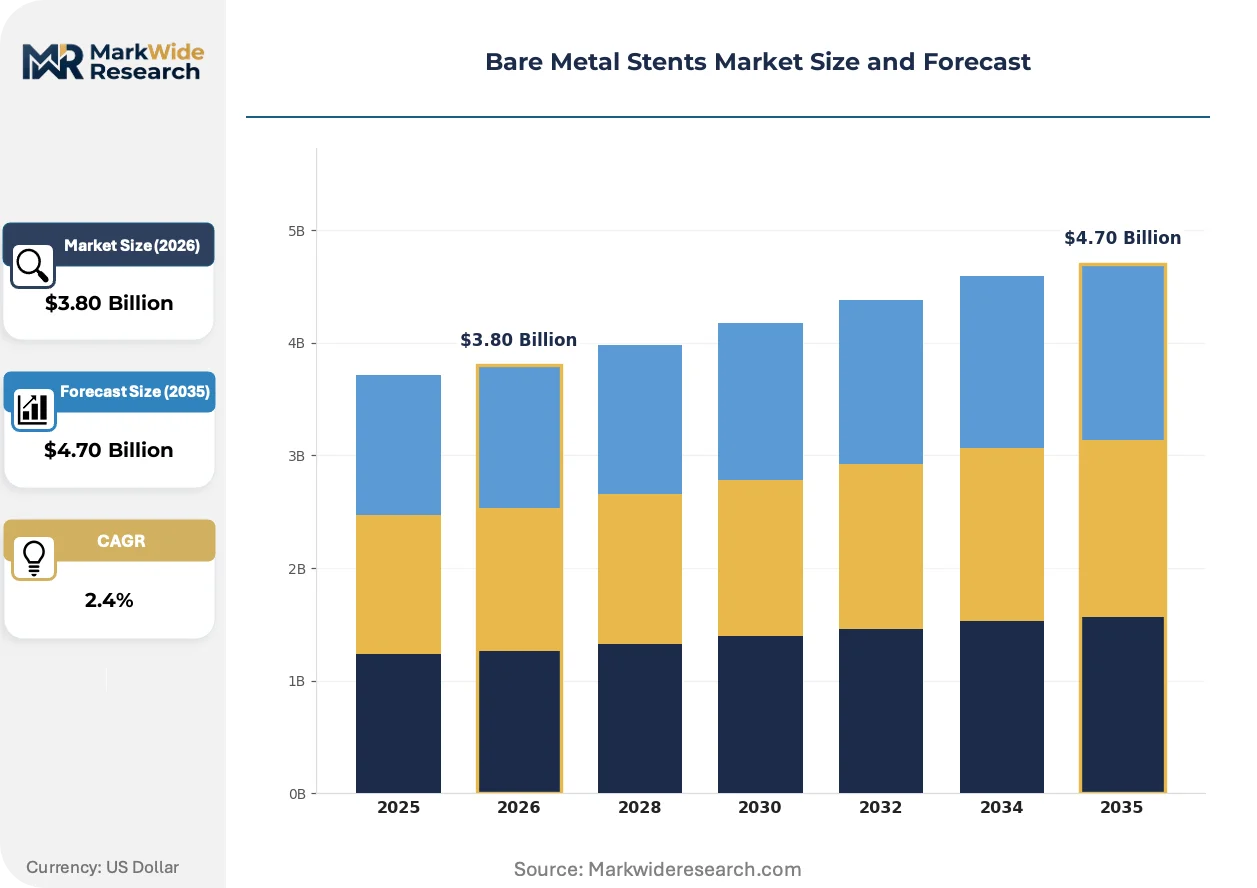
| Market Size in 2026 | $3.80 Billion |
| Market Size in 2035 | $4.70 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coronary Stents, Peripheral Stents, Carotid Stents, Ureteral Stents Application: Cardiovascular Diseases, Peripheral Artery Disease, Renal Diseases, Vascular Surgery End User: Hospitals, Clinics, Ambulatory Surgical Centers, Cardiovascular Institutions Delivery Mode: Transluminal Delivery, Direct Access Delivery, Intravascular Delivery, Open Surgical Delivery |
| Companies Covered | Abbott Laboratories, Medtronic plc, Boston Scientific Corporation, B. Braun Melsungen AG, Terumo Corporation, Biotronik SE & Co. KG, Biosensors International Group, Cook Medical, Meril Life Sciences Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bare Metal Stents Market Emerging Trajectories
Interventional cardiology is experiencing a platform convergence phase where mechanical scaffold performance and biocompatibility surface engineering are merging into unified product specifications. This integration is compressing the traditional separation between structural and biological performance metrics.
Thin-strut cobalt-chromium platforms with sub-100 micron dimensions are unifying deliverability and radial strength requirements that previously demanded trade-offs. Tertiary cardiac centers in South Korea and Spain are adopting these platforms for complex bifurcation lesions at rates outpacing conventional stainless steel alternatives. The technology is unifying previously segmented price tiers as performance differentiation narrows between premium and standard product categories.
EU MDR's enhanced clinical evidence requirements are extending conformity assessment timelines and redirecting notified body capacity toward high-risk device categories. Manufacturers with legacy technical documentation gaps face certificate suspension risks that threaten market continuity. Coronary stent portfolios with pre-2017 clinical data are experiencing the most acute compliance pressure, driving retrospective literature synthesis and registry publication investments.
Hospital procurement committees are consolidating vendor relationships around full catheterization laboratory suppliers rather than discrete device transactions. Cardiovascular service line directors in India's corporate hospital chains are negotiating multi-year supply agreements bundling stents, balloons, and diagnostic catheters. This concentration is most visible in Mumbai and Delhi NCR metropolitan clusters where tertiary center consolidation has reduced active supplier counts by half over five years.
Bare Metal Stents Market Segmentation
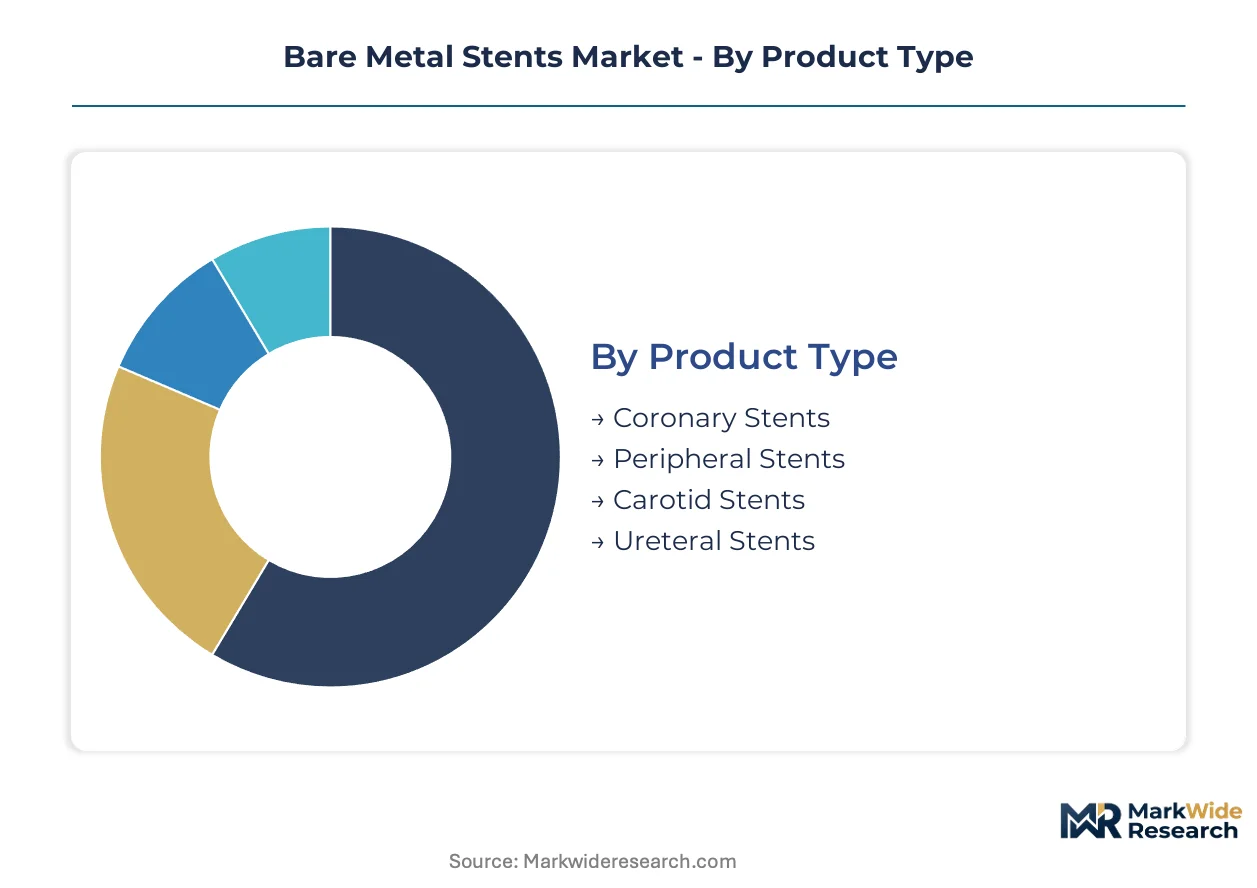
Segmentation in bare metal stents reveals how clinical requirements fragment manufacturing priorities across anatomical sites, procedural settings, and deployment techniques. Each dimension carries distinct metallurgical specifications, regulatory pathways, and procurement economics that reshape competitive positioning.
Product Type:
Customization intensity varies sharply across this category, from mass-produced coronary platforms to specialized urological configurations demanding unique surface engineering.
- Coronary Stents:Cobalt-chromium and 316L stainless steel tubular mesh scaffolds deploy via balloon-expandable catheter systems to restore coronary lumen patency. Demand concentrates in India's tertiary cardiac centers where Ayushman Bharat scheme expansion is extending percutaneous coronary intervention access to previously uninsured patient pools.
- Peripheral Stents:Self-expanding nitinol or balloon-expandable cobalt-chromium designs address femoropopliteal and below-the-knee occlusions with enhanced flexibility and fatigue resistance. Diabetic limb ischemia prevalence in Brazil and Mexico exceeds current stent deployment rates by a factor of three, creating procedural expansion potential as vascular surgery capacity builds.
- Carotid Stents:Embolic protection-integrated systems with open-cell or closed-cell designs for cervical carotid artery revascularization.
- Ureteral Stents:Polymer-coated or bare metal double-J configurations with retrieval strings for temporary urinary drainage.
Most installed capacity flows through Coronary Stents. Expansion is steepest in Peripheral Stents.
Application:
Cost tier differentiation separates high-volume standardized protocols from specialized procedures commanding premium device economics.
- Cardiovascular Diseases:Established percutaneous coronary intervention protocols for coronary artery disease, acute coronary syndromes, and post-infarction revascularization. South Korea and Spain are adopting thin-strut cobalt-chromium platforms for complex bifurcation lesions at rates outpacing conventional stainless steel alternatives.
- Peripheral Artery Disease:Lower extremity and visceral artery interventions addressing atherosclerotic and diabetic vascular complications. Femtosecond laser systems enabling sub-80 micron strut thickness are improving deliverability and expanding treatable lesion complexity in femoropopliteal applications.
- Renal Diseases:Renal artery stenosis interventions and transplant-related vascular access maintenance.
- Vascular Surgery:Hybrid open-endovascular procedures and open surgical bypass adjuncts.
Volume concentration sits with Cardiovascular Diseases. Peripheral Artery Disease is gaining share fastest.
End User:
Customer type determines procurement scale, with consolidated hospital systems extracting volume discounts versus fragmented clinic purchasing.
- Hospitals:Tertiary and secondary acute care facilities with cardiac catheterization laboratories performing high-volume interventional procedures. Mumbai and Delhi NCR metropolitan clusters have reduced active supplier counts by half over five years as corporate hospital chains negotiate multi-year supply agreements bundling stents, balloons, and diagnostic catheters.
- Cardiovascular Institutions:Dedicated heart centers and cardiovascular specialty hospitals with concentrated procedural expertise. Poland and Czech Republic cardiac catheterization laboratories are consolidating purchasing through group procurement organizations, bypassing traditional distributor markups for high-volume accounts.
- Clinics:Outpatient interventional facilities with limited procedure rooms and lower device throughput.
- Ambulatory Surgical Centers:Same-day discharge facilities performing selected peripheral and diagnostic interventions.
Procurement scale peaks at Hospitals. Contract sophistication is advancing fastest at Cardiovascular Institutions.
Delivery Mode:
Maturity gradients separate decades-old transluminal techniques from emerging direct access approaches requiring specialized training infrastructure.
- Transluminal Delivery:Catheter-based endoluminal deployment through femoral or radial access, the dominant technique for coronary and peripheral interventions. FDA premarket notification pathways and CE marking requirements under EU MDR shape competitive access conditions for balloon-expandable and self-expanding platforms.
- Intravascular Delivery:Advanced catheter systems with integrated imaging and navigation for complex anatomical challenges.
- Direct Access Delivery:Percutaneous or cut-down access for vascular beds unsuitable for remote catheter navigation.
- Open Surgical Delivery:Intraoperative stent deployment during concomitant bypass or endarterectomy procedures.
Procedural volume concentrates in Transluminal Delivery. Technical advancement is steepest in Intravascular Delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting bare metal stent manufacturing toward jurisdictions with streamlined compliance pathways. Producers migrate capacity to exploit cost-of-compliance gaps between FDA 510(k) notification requirements and EU MDR conformity assessment timelines.
United States
FDA premarket notification pathways accelerate product refreshes for coronary stent platforms. Medicare reimbursement rates for percutaneous coronary intervention procedures sustain hospital purchasing volumes across tertiary cardiac centers. Massachusetts and Minnesota manufacturing clusters concentrate precision laser-cutting capacity for cobalt-chromium scaffold production.
Germany
DRG system hybrid reimbursement categories now cover combination therapy protocols pairing bare metal stents with drug-coated balloons. EU MDR full enforcement filters non-compliant manufacturers from market access. Bavaria and Baden-Württemberg host notified body concentration for cardiovascular device conformity assessment.
India
Ayushman Bharat government health schemes extend percutaneous coronary intervention access to previously uninsured patient pools. CDSCO medical device regulations align with global harmonization initiatives for stent safety standards. Mumbai and Delhi NCR metropolitan clusters reduce active supplier counts by half through corporate hospital chain consolidation.
Japan
PMDA clinical bridging requirements for alloy composition changes extend time-to-market by 18-24 months versus FDA pathways. Domestic safety studies create regulatory friction for product line refreshes. Kanto region cardiovascular institutions adopt thin-strut cobalt-chromium platforms for complex bifurcation lesions.
Brazil
Diabetic limb ischemia prevalence exceeds peripheral stent deployment rates by a factor of three. ANVISA medical device registration pathways shape competitive access conditions for self-expanding nitinol platforms. São Paulo vascular surgery capacity builds toward procedural expansion in femoropopliteal applications.
Bare Metal Stents Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue peripheral artery disease specialization and hybrid therapy convergence. The vendor base consolidates around full catheterization laboratory suppliers rather than discrete device transactions. Three archetypes dominate: diversified cardiovascular conglomerates with captive metallurgical supply, mid-scale specialists with precision fabrication focus, and regional fabricators serving government procurement channels. M&A activity concentrates on laser-cutting capability acquisition; strategic partnerships bundle stent-balloon-catheter portfolios for hospital group procurement organizations.
Among diversified cardiovascular conglomerates, Abbott Laboratories, Medtronic plc, and Boston Scientific Corporation exemplify scale-driven positioning. Abbott Laboratories represents backward integration into cobalt-chromium wire-drawing capabilities. Medtronic plc anchors North American production concentration. Boston Scientific Corporation occupies precision laser-cutting scale positions across Massachusetts and Ireland manufacturing clusters.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic plc |
| Boston Scientific Corporation |
| B. Braun Melsungen AG |
| Terumo Corporation |
| Biotronik SE & Co. KG |
| Biosensors International Group |
| Cook Medical |
| Meril Life Sciences Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
Performance-tier divergence between sub-80 micron cobalt-chromium platforms and conventional stainless steel alternatives manifests in procurement economics and metallurgical sourcing configurations. Premium thin-strut designs command elevated positioning through femtosecond laser precision, while standard-tier products compete on volume scale in government health scheme channels across India and Brazil.
Pricing Analysis
Distributor margin compression in European markets is accelerating direct hospital procurement consolidation. Three-tier pricing structure across premium thin-strut, standard cobalt-chromium, and economy stainless steel levels separates certification-grade products from commodity alternatives. Pricing pressure stems from bioresorbable scaffold substitution threats redirecting interventional cardiology procurement. Government health scheme buyers in India exhibit highest price sensitivity; tertiary cardiac centers in South Korea and Spain show lowest sensitivity for complex lesion applications.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for medical devices are reshaping cobalt-chromium sourcing toward local wire-drawing investments. Manufacturing concentration rests on the United States, Ireland, and Germany for precision laser-cutting capacity. Raw material dependencies center on cobalt-chromium alloys, nitinol wire, and polymer coating substrates. Single-source vulnerability concentrates in Democratic Republic of Congo mining and Chinese processing facilities. Distribution runs through group procurement organizations in Poland and Czech Republic, bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play exploiting the 18-24 month time-to-market gap between Japan PMDA clinical bridging requirements and FDA 510(k) notification pathways. Producers can capture margin premiums by prioritizing regulatory-efficient jurisdictions for product line refreshes.
For Market Incumbents: Deploy captive metallurgical supply as the defensive anchor. Abbott Laboratories exemplifies backward integration into cobalt-chromium wire-drawing capabilities that insulate against Democratic Republic of Congo mining volatility. Incumbents must secure ISO 25539-2 fatigue testing capacity to defend against certificate suspension risks under EU MDR full enforcement. Capacity addition in Massachusetts and Ireland manufacturing clusters reinforces precision laser-cutting scale positions against mid-scale specialists.
For New Entrants and Emerging Players: Enter via peripheral artery disease specialization in Brazil and Mexico, where diabetic limb ischemia prevalence exceeds stent deployment rates by a factor of three. Femoropopliteal and below-the-knee applications represent the most penetrable segment given vascular surgery capacity expansion. Drug-coated balloon convergence protocols in Germany's DRG system offer a specific go-to-market angle for hybrid therapy positioning.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale specialists possessing precision fabrication focus and laser-cutting capability acquisition targets. Long-term viability across the analysis window hinges on EU MDR compliance completion and bioresorbable scaffold trial outcome monitoring. The signal to watch is retrospective literature synthesis investments for legacy coronary stent portfolios facing enhanced clinical evidence requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment completion filters non-compliant manufacturers from market access. |
| Hospital System Partnership | Multi-year supply agreements bundling stents, balloons, and diagnostic catheters consolidate vendor relationships in India. |
| Backward Integration | Captive cobalt-chromium wire-drawing capabilities secure supply chains against Democratic Republic of Congo mining concentration. |
| Software Companion Development | Integrated imaging and navigation catheter systems advance intravascular delivery technical capabilities. |
| Reimbursement Strategy | Hybrid DRG categories in Germany enable combination therapy protocols pairing bare metal stents with drug-coated balloons. |
Methodological Framework
Bottom-up hospital procurement modeling reconciled against top-down metallurgical supply tracking forms the analytical core. Primary interviews with interventional cardiologists, biomedical engineers, GPO contracts managers, and CDSCO regulatory affairs specialists combined with secondary validation. Secondary sources include FDA 510(k) filings, EU MDR notified body databases, CMS Medicare reimbursement data, and hospital procurement databases. Triangulation across stakeholder inputs and regulatory filings anchors volume and value estimates.
Input-output matrices segment the market by product type, application, end user, and delivery mode across the projection horizon. Modeled dimensions include coronary versus peripheral versus urological stent configurations, balloon-expandable versus self-expanding platforms, and tertiary cardiac center versus clinic procurement scale. CAGRs derive from procedural volume trajectories, reimbursement rate evolution, and alloy substitution elasticity. Forecast inputs incorporate Ayushman Bharat scheme expansion rates and femtosecond laser adoption curves.
Inputs from FDA premarket notification databases and EU MDR certificate registries were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around volume estimates. Forecasts reflect assumptions regarding regulatory timeline stability and bioresorbable scaffold commercialization delays. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Human Anatomy Model Market
Medical Devices
Global Bone Cement Market
Medical Devices
Europe Ventilator Market
Medical Devices
Electromagnetic Navigation Bronchoscopy Market
Medical Devices
Echogenic Catheters Market
Medical Devices
Transcatheter Mitral Valve Market
Medical Devices
Video Dermatoscope Market
Medical Devices
Bioimpedance Analyzers Market
Medical Devices
Asia-Pacific Arthroscopy Devices Market
Medical Devices
Pressure Mapping Systems in Healthcare Market
Medical Devices
Retinal Surgery Devices Market
Medical Devices
Bluetooth Hearing Aids Market
Medical Devices
Japan Anesthesia Devices Market
Medical Devices
Telehealth Device Market
Medical Devices
Nonvascular Interventional Radiology Devices Market
Medical Devices
Global Medical Suction Devices Market