
 US Medical Device Manufacturers Market | 2026-2036
US Medical Device Manufacturers Market Size, Share, and Industry Trends Forecast 2026-2036
US Medical Device Manufacturers Market Intelligence
Minnesota's expanding medtech manufacturing corridor is rewriting the competitive landscape for device production. Medtronic leverages its extensive portfolio and distribution network to maintain a dominant market position. Boston Scientific differentiates through its intense R&D focus on less-invasive cardiovascular and neurological technologies. Stryker competes by specializing in orthopedic and surgical equipment, targeting high-volume procedures in hospitals.
US medical device manufacturing encompasses the design and production of instruments for diagnosing, monitoring, or treating medical conditions. These devices must adhere to the FDA's stringent Quality System Regulation (QSR) and often require specific material biocompatibility testing. Cardiovascular Devices and Diagnostic Equipment constitute major product categories by value. Hospitals remain the largest end-user segment, but demand from Ambulatory Surgical Centers is accelerating.
The Food and Drug Administration (FDA) governs market access through its 510(k) and Premarket Approval (PMA) pathways. Regulations like HIPAA dictate data security protocols for connected devices, influencing design and software development. Manufacturers must now decide how to best integrate AI-enabled systems and IoT connectivity to align with the healthcare industry's shift toward preventative and personalized medicine.
Market Dynamics
The convergence of data analytics with traditional hardware manufacturing is the central force shaping the US medical device market. This integration is compelling manufacturers to build new capabilities in software development, cybersecurity, and data management to meet healthcare provider demands for connected, intelligent systems.
Growth Catalysts
- Specialized Manufacturing Corridors:The concentration of orthopedic and cardiovascular device expertise in states like Minnesota and California creates an ecosystem of skilled labor and specialized suppliers, attracting further investment and fostering rapid product development cycles for complex devices.
- FDA AI/ML Framework:The Food and Drug Administration's evolving pre-market review framework for artificial intelligence and machine learning-based software accelerates the approval process for adaptive algorithms, encouraging manufacturers to invest in smarter diagnostic and therapeutic systems.
- Shift to Ambulatory Care:Accelerating patient volume in Ambulatory Surgical Centers (ASCs) creates demand for specialized, cost-effective surgical equipment and diagnostic tools designed for outpatient procedures, opening a new channel separate from traditional hospital procurement.
Market Restraints
- Biocompatible Material Costs:The high cost and supply chain volatility of medical-grade polymers, titanium, and specialty alloys create significant margin pressure. Securing a stable supply of materials that meet stringent biocompatibility testing requirements remains a primary constraint for manufacturers.
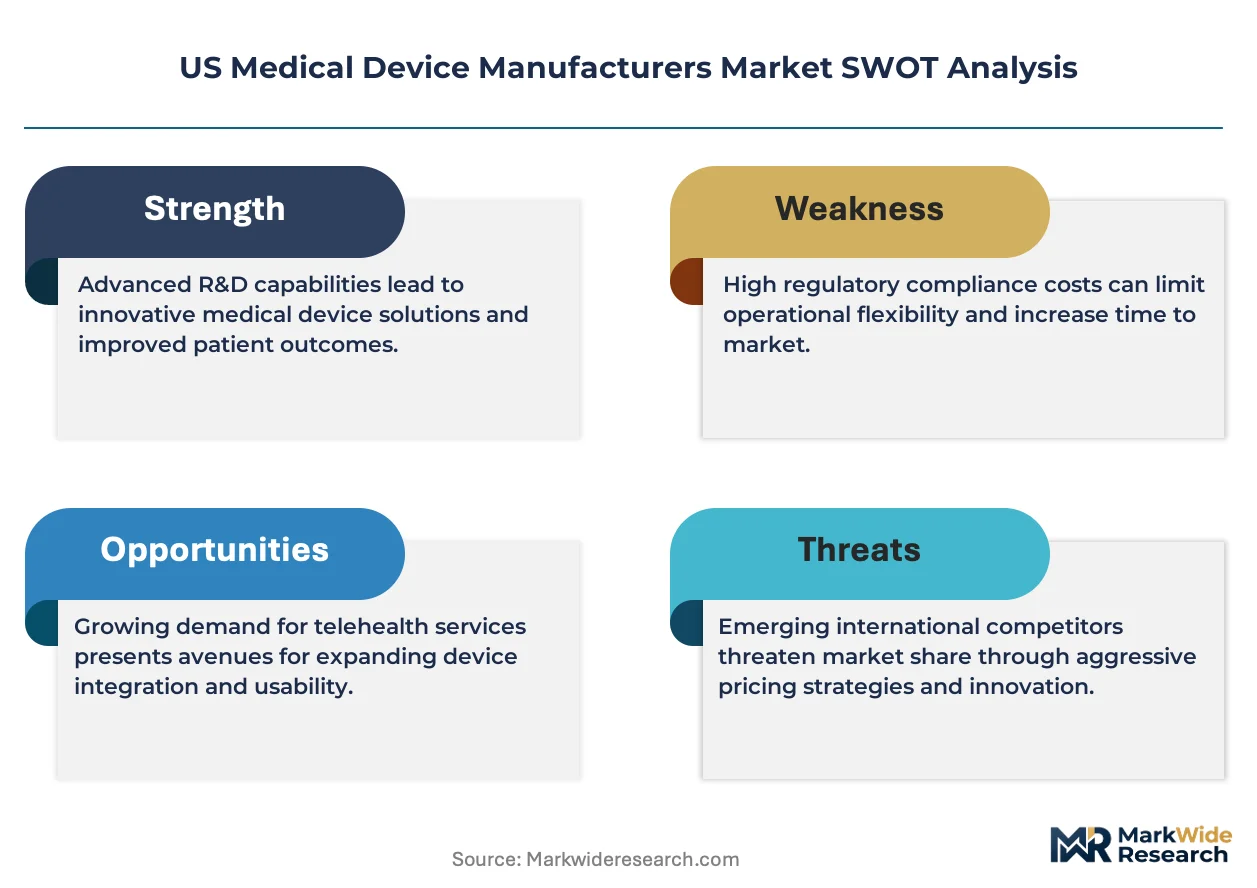
- Stringent Regulatory Hurdles:The FDA's Quality System Regulation (QSR) imposes rigorous design, production, and documentation standards. Compliance requires substantial upfront investment and long development timelines, acting as a significant barrier to entry for new companies.
- Data Security Compliance:Adherence to HIPAA's data security and privacy rules for connected medical devices introduces significant complexity and cost into the design process. Ensuring end-to-end encryption and breach-proof software can delay product launches.
Strategic Opportunities
- Remote Patient Monitoring Systems:Integrating IoT connectivity with diagnostic devices like glucose monitors and cardiac sensors enables real-time data collection outside of clinical settings. This supports the healthcare industry's push toward preventative care and chronic disease management.
- Personalized Medical Devices:Advances in additive manufacturing, or 3D printing, allow for the creation of patient-specific surgical guides, implants, and prosthetics. This opportunity is most pronounced in complex orthopedic and craniomaxillofacial procedures.
- Telehealth Integration:Developing devices that seamlessly integrate with major telehealth platforms presents a clear opportunity. This includes diagnostic peripherals for remote examinations, which are increasingly used by providers for virtual consultations across the US.
Industry Challenges
- Specialized Talent Scarcity:A significant challenge is the shortage of software engineers and data scientists who possess expertise in both medical device regulatory pathways and AI development. This talent gap slows the development of next-generation intelligent devices.
- Legacy System Interoperability:Integrating new, connected medical devices with disparate and often outdated hospital IT infrastructure and electronic health record (EHR) systems is a major operational hurdle, limiting the immediate utility of advanced data features.
- Sterilization and Validation Costs:The capital expenditure needed to build, validate, and maintain manufacturing facilities compliant with FDA standards for sterile products is substantial. This is particularly challenging for startups and smaller firms in the implantable device sector.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Medical Device Manufacturers Market |
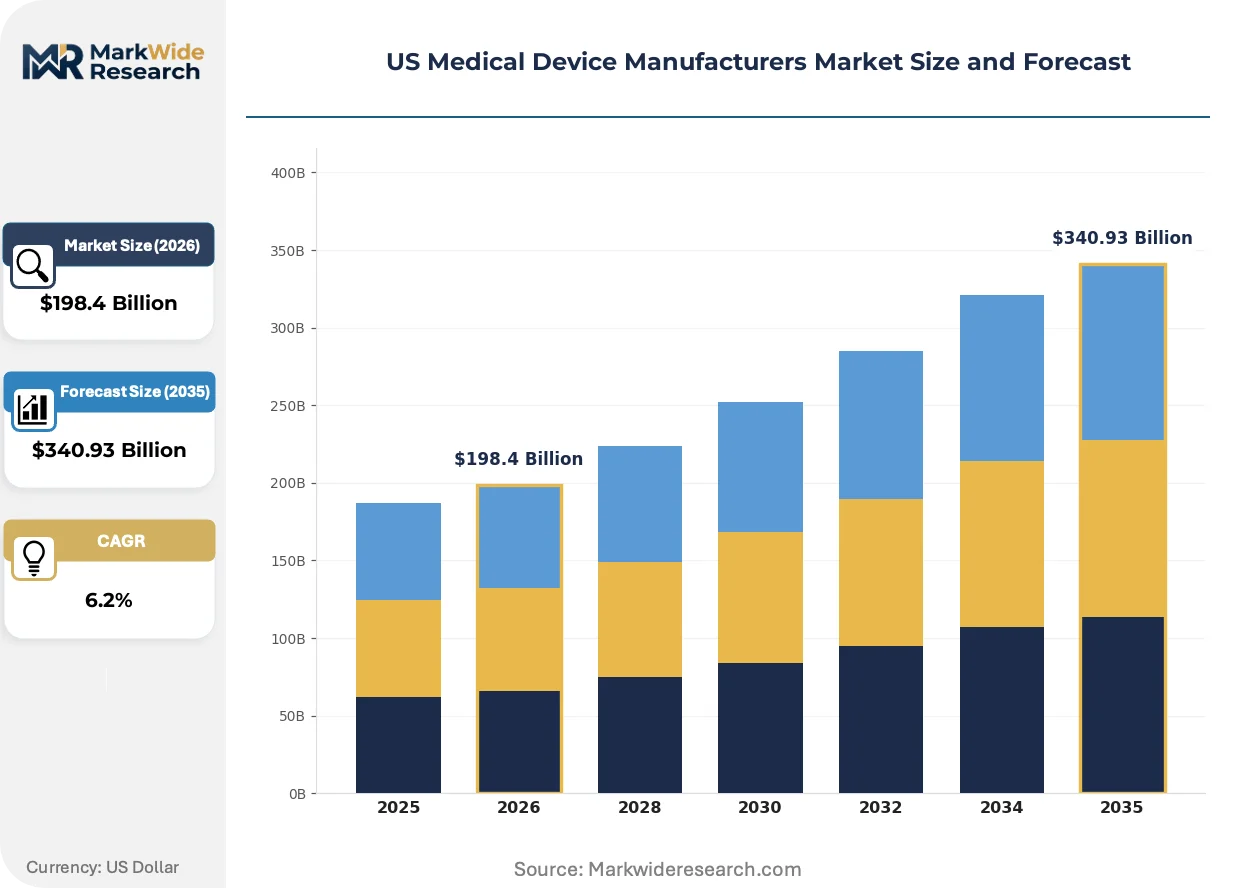
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $340.93 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Equipment, Surgical Instruments, Cardiovascular Devices, Orthopedic Implants, Monitoring Devices Technology: 3D Printing, Nanotechnology, IoT Integration, AI-enabled Systems, Wireless Connectivity Application: Cardiology, Orthopedics, Neurology, Gastroenterology, Oncology End User: Hospitals, Ambulatory Surgical Centers, Research Laboratories, Diagnostic Centers, Specialty Clinics |
| Companies Covered | Boston Scientific, Siemens Healthineers, Medtronic, Edwards Lifesciences, GE Healthcare, Johnson & Johnson MedTech, Stryker, Cardinal Health, Abbott Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Medical Device Manufacturers Market Strategic Shifts & Innovations
Product evolution in the US medical device sector centers on embedding intelligence and connectivity directly into devices. This shift transforms standalone hardware into integrated components of a broader digital health ecosystem, with data generation becoming as critical as the primary therapeutic function.
Software as a Medical Device (SaMD) defines a new category of products where algorithms perform diagnostic or therapeutic functions. Diagnostic imaging centers and cardiology clinics are early adopters, using SaMD for clinical decision support and treatment planning. The market is migrating from a hardware-centric model, where value is tied to the physical instrument, to a system where software and data analytics increasingly define clinical efficacy and competitive differentiation.
Regulatory frameworks from the FDA are adapting to the unique nature of digital health technologies. The agency's guidance on pre-market pathways for AI/ML-enabled devices allows for modifications based on real-world learning without requiring a full new submission each time. This policy directly benefits developers of diagnostic imaging and remote monitoring systems, enabling faster iteration and improvement of their algorithms in response to new clinical data.
A notable behavioral shift is occurring in how healthcare providers acquire technology, moving from capital expenditure purchases to more flexible, service-oriented models. This change disrupts traditional sales cycles, as providers increasingly favor subscriptions or pay-per-use contracts that align costs with patient volume. This trend is most visible among large hospital networks in the US seeking to manage technology costs for high-volume diagnostic equipment.
US Medical Device Manufacturers Market Segmentation
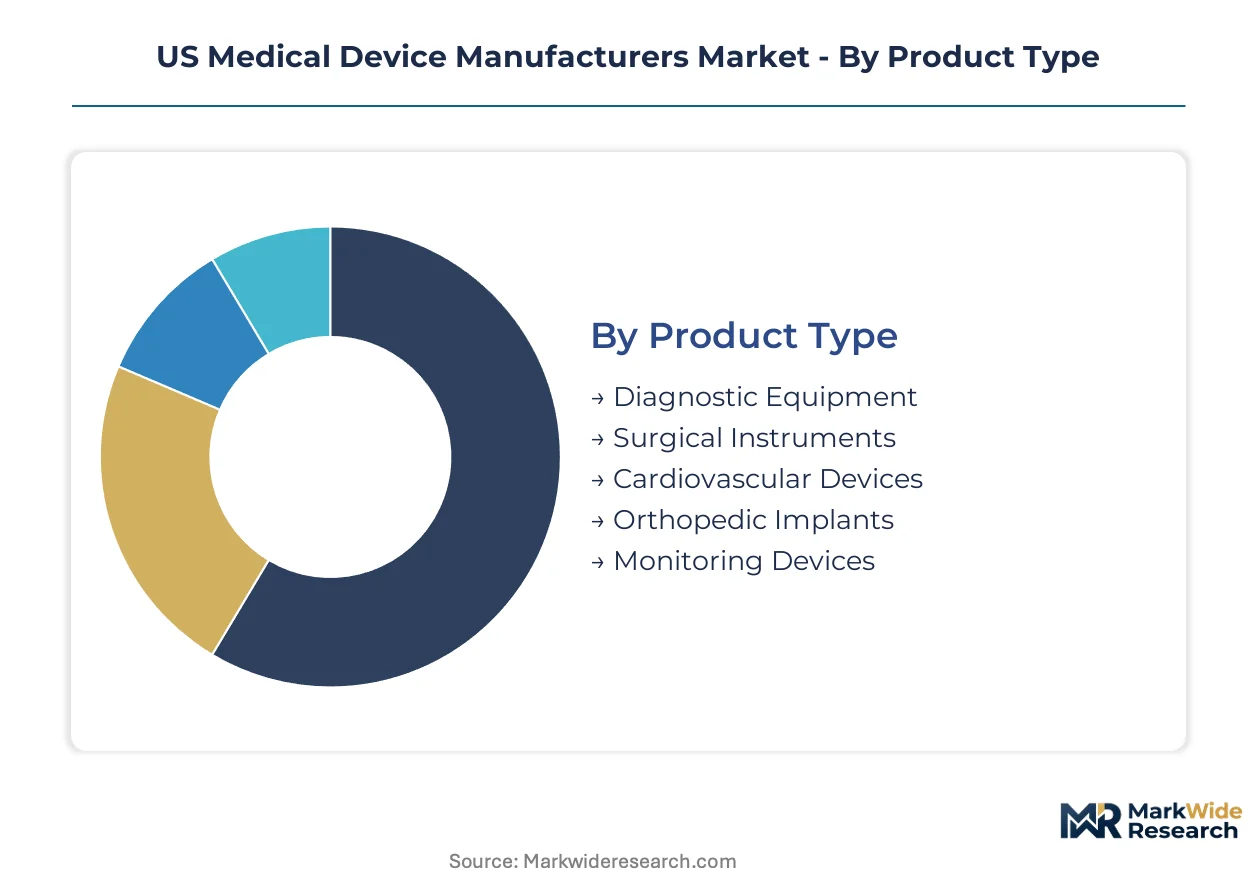
The US medical device market exhibits diverse segmentation, reflecting varied clinical needs and technological advancements. Understanding these distinct categories provides critical insights into market dynamics and strategic investment areas for manufacturers. This granular analysis illuminates where innovation and demand are most concentrated.
Product Type:
The product type segmentation delineates the functional spectrum of medical devices, from initial diagnosis through long-term patient monitoring.
- Cardiovascular Devices:These instruments, including pacemakers, stents, and catheters, directly support cardiac function and vascular health. Demand concentrates in specialized surgical centers and hospitals due to the high incidence of cardiovascular diseases in the US population.
- Diagnostic Equipment:This category encompasses imaging systems, laboratory analyzers, and in-vitro diagnostics crucial for identifying medical conditions. Demand is concentrating in both hospitals and diagnostic centers, driven by the increasing need for early and accurate disease detection.
- Surgical Instruments:This segment includes a range of tools used in operative procedures across various medical specialties.
- Orthopedic Implants:These devices, such as joint replacements and spinal fixation systems, restore musculoskeletal function.
- Monitoring Devices:This category covers equipment like vital sign monitors and glucose meters, essential for continuous patient data collection.
Established volume favors Cardiovascular Devices; emerging adoption favors Monitoring Devices for remote patient care.
Technology:
Technology segmentation reflects the maturity curve of innovations driving the next generation of medical device capabilities.
- AI-enabled Systems:These systems integrate artificial intelligence algorithms for diagnostic support, predictive analytics, and personalized treatment planning. Demand is accelerating in diagnostic imaging and remote monitoring applications, supported by the FDA's evolving pre-market framework.
- IoT Integration:This involves embedding internet of things connectivity into devices for real-time data collection, remote monitoring, and interoperability. Demand is growing across chronic disease management and preventative care, enabling continuous patient oversight outside clinical settings.
- 3D Printing:This additive manufacturing technique enables patient-specific implants and surgical guides, particularly in orthopedics.
- Nanotechnology:This field explores materials and devices at the nanoscale for advanced drug delivery and diagnostic applications.
- Wireless Connectivity:This technology facilitates data transfer between devices and healthcare systems, enhancing mobility and accessibility.
The steepest expansion trajectory is observed in AI-enabled Systems, while Nanotechnology represents a longer-term development horizon.
Application:
Application segmentation highlights the specific medical disciplines where device usage volume concentrates.
- Cardiology:This application area focuses on devices for heart and vascular conditions, including diagnostic tools, interventional devices, and implants. High procedure volumes in US hospitals and specialized clinics drive significant demand for advanced cardiovascular technologies.
- Orthopedics:This segment addresses musculoskeletal disorders with implants, surgical instruments, and rehabilitation devices. Demand is strong in states like California and Minnesota, where specialized manufacturing corridors support rapid product development for aging populations.
- Neurology:This category covers devices for brain and nervous system disorders, from diagnostics to therapeutic interventions.
- Gastroenterology:This application involves devices for digestive system conditions, including endoscopic equipment and related accessories.
- Oncology:This segment encompasses devices for cancer diagnosis, treatment, and monitoring, such as radiation therapy equipment.
High-volume patient needs drive Cardiology and Orthopedics, while Neurology applications demonstrate specialized growth.
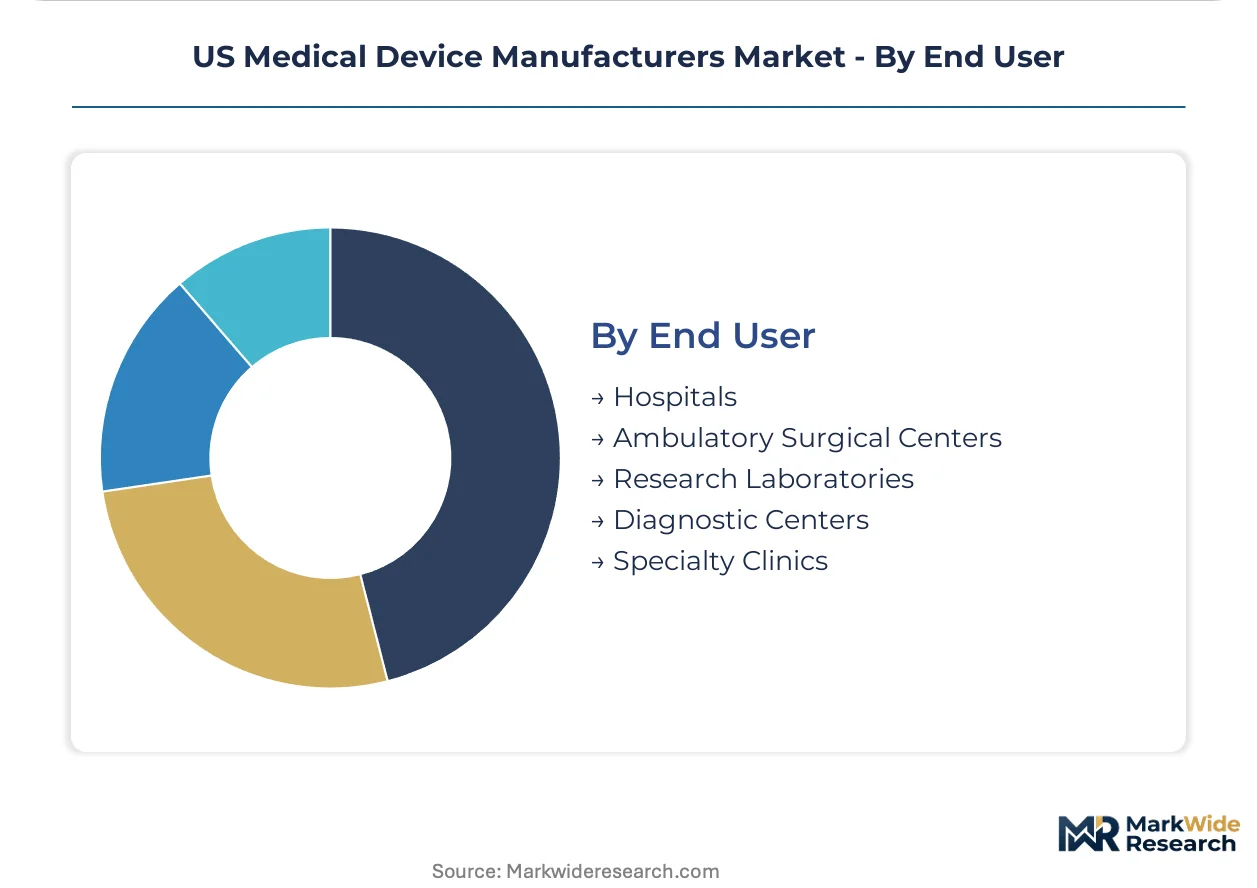
End User:
End-user segmentation reveals how procurement patterns and margin pressures vary across different healthcare delivery settings.
- Hospitals:As the largest end-user segment, hospitals procure a wide array of medical devices for diagnostics, surgery, and patient care. Their purchasing decisions are often influenced by volume discounts and the need for interoperability with existing IT infrastructure.
- Ambulatory Surgical Centers:ASCs are increasingly demanding specialized, cost-effective devices for outpatient procedures, driving growth in specific product categories. Their focus on efficiency and rapid patient turnover shapes procurement for less-invasive surgical equipment.
- Research Laboratories:These facilities utilize specialized diagnostic and analytical equipment for scientific inquiry and product development.
- Diagnostic Centers:These centers focus on imaging and laboratory testing, requiring high-throughput and accurate diagnostic equipment.
- Specialty Clinics:These clinics cater to specific medical conditions, requiring tailored devices for focused patient populations.
Hospitals remain the dominant purchasing force, but Ambulatory Surgical Centers are rapidly expanding their device procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US medical device market, underwritten by its extensive network of advanced medical research institutions and specialized healthcare facilities, exhibits distinct regional concentrations. This infrastructure facilitates both the development of cutting-edge technologies and their rapid adoption across diverse patient populations. These regional hubs contribute significantly to the overall market growth.
California
Demand for high-value orthopedic and cardiovascular devices drives innovation in California. The FDA's evolving pre-market pathways for AI-enabled systems encourage local development. Silicon Valley and Southern California host a concentration of medtech startups and established manufacturers, fostering rapid product development cycles. This ecosystem attracts significant investment.
Minnesota
Minnesota's expanding medtech manufacturing corridor fuels significant market expansion. Strict adherence to the FDA's Quality System Regulation supports high-quality device production. The Minneapolis-St. Paul metropolitan area serves as a major hub for orthopedic and cardiovascular device manufacturing, attracting skilled labor and specialized suppliers. This concentration supports the entire value chain.
Massachusetts
A robust biotech and medtech ecosystem in Massachusetts spurs investment in new device technologies. Compliance with HIPAA's data security protocols influences device design and software development. The Boston-Cambridge cluster is a global center for medical innovation, with numerous research institutions and companies collaborating on next-generation diagnostic and therapeutic systems. This region benefits from academic partnerships.
Texas
Texas's large and growing population creates demand for a wide array of medical devices, particularly in diagnostic equipment. Reimbursement policies from the Centers for Medicare & Medicaid Services (CMS) impact procurement decisions for hospitals. The Texas Medical Center in Houston represents the world's largest medical complex, driving significant demand for advanced surgical and monitoring devices. This complex attracts substantial healthcare investment.
US Medical Device Manufacturers Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing specialized materials and sub-assemblies across the US medical device market. The market structure is tiered, featuring large diversified players alongside highly specialized R&D-focused firms. Strategic archetypes include broad-portfolio manufacturers, niche technology innovators concentrating on specific medical conditions, and surgical equipment providers targeting high-volume procedures. Dominant competitive moves include portfolio diversification to capture new segments and strategic partnerships to integrate new AI-enabled systems and IoT connectivity.
Within the diversified portfolio archetype, Medtronic, a leading global medical technology company, exemplifies broad market reach across multiple product categories. Boston Scientific, a US-based firm, occupies a position as a specialist in less-invasive cardiovascular and neurological technologies, emphasizing R&D-driven differentiation. Stryker, another prominent US corporation, represents a significant player in orthopedic and surgical equipment, targeting high-volume procedures in hospital settings. These major companies anchor distinct segments of the market, influencing product development and distribution strategies nationwide.
| Leading Market Players |
|---|
| Boston Scientific |
| Siemens Healthineers |
| Medtronic |
| Edwards Lifesciences |
| GE Healthcare |
| Johnson & Johnson MedTech |
| Stryker |
| Cardinal Health |
| Abbott Laboratories |
| Others |
Cost & Logistics Intelligence
The US domestic freight corridor's cost dynamics directly influence medical device supply concentration and downstream price differentiation. Rising transportation expenses for specialized components impact manufacturer margins, which then affects pricing strategies for end-users.
Pricing Analysis
Volume-discount tiering structures dominate procurement for high-volume medical devices across US hospital systems. Price differentiation stems from FDA certification levels, brand premium, and comprehensive after-sales service agreements. Pricing softness stems from intense competition among manufacturers and large buyer negotiation power. Ambulatory Surgical Centers demonstrate the highest price sensitivity, favoring cost-effective, specialized equipment, while specialized research laboratories prioritize advanced features and data integration over initial acquisition cost.
Supply Chain Analysis
Extended payment terms from specialized component suppliers are common, impacting medical device manufacturer working capital. Geographic supply concentration for critical materials like medical-grade polymers, titanium, and specialty alloys heavily involves the US, Germany, and Japan. Single-source vulnerability for specific biocompatible coatings presents a significant structural supply chain risk. Downstream distribution runs primarily through established Group Purchasing Organizations and direct sales channels to major hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US medical device market exhibits strong defensive moat characteristics, primarily due to significant regulatory entrenchment. FDA approval processes create high barriers to entry, protecting incumbent market positions.
For Market Incumbents: Insulate core product lines by deepening vertical integration into specialized component manufacturing. Enhance proprietary software platforms to counter emerging AI-enabled system threats from technology firms. Invest in rigorous clinical trials to reinforce product efficacy claims, maintaining a competitive edge against new entrants offering less-proven solutions. Expand distribution networks within Ambulatory Surgical Centers to capture growing outpatient procedure volumes.
For New Entrants and Emerging Players: Rural and underserved geographic regions present significant underpenetration for advanced diagnostic equipment. Target specialized niches within telehealth integration or personalized medical devices, where rapid innovation can displace legacy systems. Focus on developing cost-effective, AI-enabled diagnostic peripherals for remote examinations. A strong go-to-market angle involves direct partnerships with smaller clinics or regional health systems seeking affordable, accessible technology.
For Investors and Strategic Acquirers: Niche technology innovators specializing in AI-enabled systems or IoT connectivity represent attractive acquisition targets. Long-term viability for the sector remains robust, driven by an aging US population and chronic disease prevalence. The signal to watch is the successful integration of novel software-as-a-medical-device solutions into existing hospital IT infrastructure, indicating scalable adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-market Pathway Acceleration | Streamlines approval for AI-enabled systems, enabling faster market entry for diagnostic and monitoring devices. |
| AI-enabled Software Companion Development | Integrates advanced algorithms with existing hardware, enhancing diagnostic accuracy and treatment planning capabilities for clinicians. |
| Ambulatory Surgical Center Partnership | Secures distribution channels and tailored product feedback for specialized, cost-effective surgical equipment designed for outpatient settings. |
| Biocompatible Material Supply Chain Diversification | Mitigates cost volatility and single-source risks for critical components, ensuring stable production of implantable devices. |
| Telehealth Platform Integration | Expands market reach for diagnostic peripherals and remote monitoring systems by aligning with virtual consultation trends. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews. Clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers provided direct insights. Secondary validation drew from FDA filings, CMS Medicare data, and industry association reports. A robust bottom-up and top-down triangulation process ensured data accuracy and comprehensive market understanding.
The calibration approach integrated historical market performance with future growth projections across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional demand patterns within the US. Compound Annual Growth Rates were derived from proprietary regression models. Key forecast inputs included US healthcare spending trends and evolving FDA regulatory guidance for novel devices.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large diversified players or niche technology innovators would shift outcomes. Projections reflect current market dynamics and regulatory stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Aneurysm Clips Market
Medical Devices
Double-Lumen Biliary Catheters Market
Medical Devices
Middle East and Africa Surgical Equipment Market
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
Global Lithotripsy Device Market
Medical Devices
Chordal Suture Systems Market
Medical Devices
US Medical Bionic Implants & Artificial Organs Market
Medical Devices
Stimulation Therapies Market
Medical Devices
Ultrasonic Electrosurgical Devices Market
Medical Devices
Global Patient-Controlled Analgesic Pumps Market
Medical Devices
Global Artificial Organs and Bionics Market
Medical Devices
Percutaneous Nephrostomy Catheters Market
Medical Devices
Global Implantable Loop Recorder Market
Medical Devices
South Africa Neurology Devices Market
Medical Devices
Global Medical Grade Coating Market
Medical Devices
Bioimpedance Devices Market