
 Extremity Reconstruction Market | 2026-2036
Extremity Reconstruction Market Size, Share, and Industry Trends Forecast 2026-2036
Extremity Reconstruction Market Analysis
The capital-intensity divergence between large-scale manufacturers and mid-tier specialists is reorganizing competitive dynamics across extremity reconstruction. Stryker leverages its integrated implant-instrument ecosystems to dominate high-volume trauma accounts. Zimmer Biomet anchors its position through proprietary shoulder and ankle arthroplasty platforms that command premium positioning in orthopedic clinics.
Extremity reconstruction encompasses surgical restoration of function to the shoulder, elbow, wrist, hand, hip, knee, ankle, and foot through osteosynthesis devices, joint replacement systems, and biological grafts, typically fabricated from titanium alloys, cobalt-chrome, or polyether ether ketone composites engineered for load-bearing fatigue resistance and osseointegration. Titanium implants sustain the largest revenue pool due to biocompatibility and modulus-matching properties, while bio-resorbable polymers represent the fastest-expanding material class as surgeons seek to eliminate secondary removal procedures in pediatric and sports medicine applications. Ambulatory surgical centers now compete directly with hospital outpatient departments for extremity trauma and elective joint reconstruction, reshaping instrument sterilization logistics and disposable kit configurations.
FDA 510(k) clearances govern implant commercialization in the United States, while the EU Medical Device Regulation imposes enhanced clinical evidence requirements for Class III orthopedic devices entering European markets. The FDA's evolving predicates policy and EMA's scrutiny of metal-on-metal bearing surfaces are forcing manufacturers to rebuild premarket submission strategies around patient-specific instrumentation and additive-manufactured implants. Stakeholders must monitor how regulator convergence on real-world performance surveillance reshapes post-market obligations and liability exposure across jurisdictions.
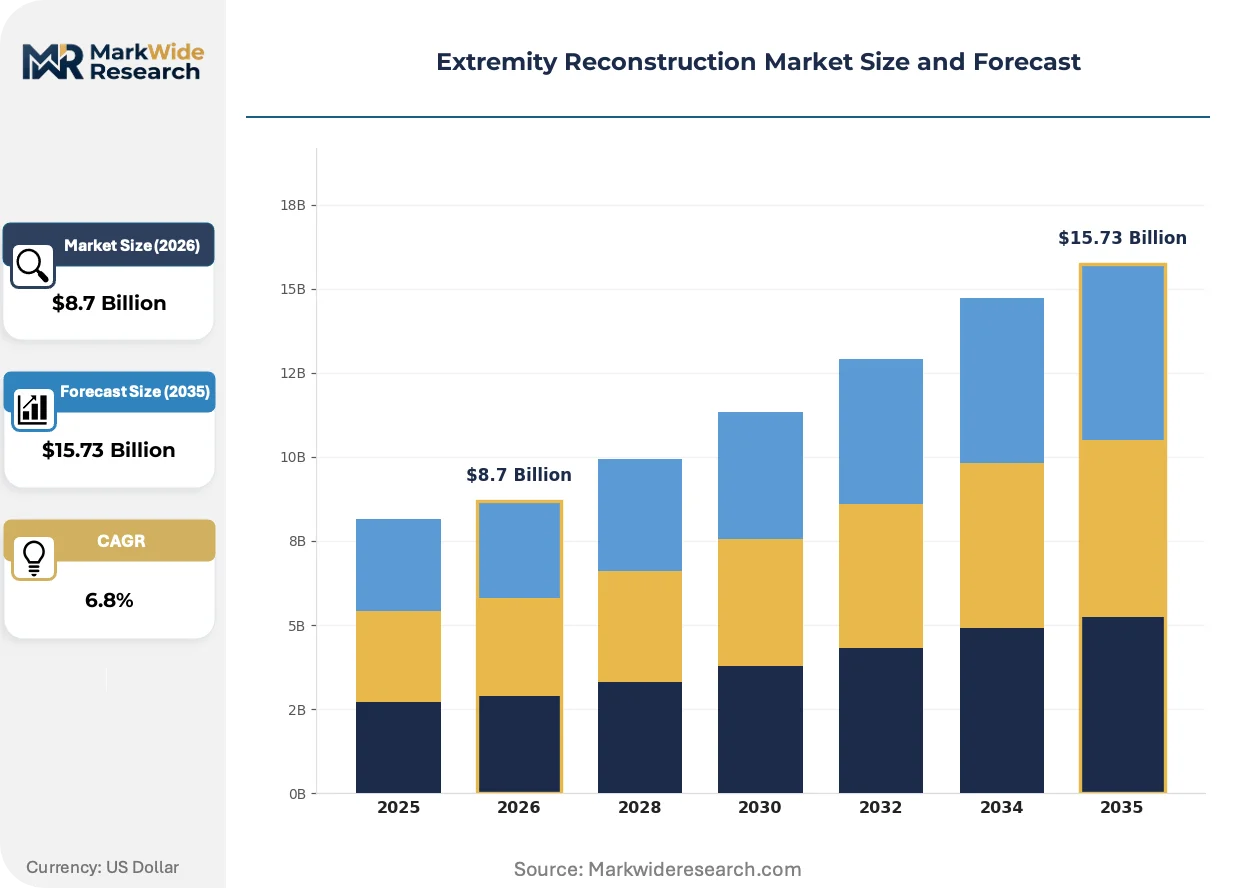
Market Dynamics
Ambulatory surgical centers are consolidating extremity trauma and elective joint procedures into same-day discharge protocols, compressing sterilization cycles and forcing instrument manufacturers to reconfigure disposable kit economics around compressed turnaround windows.
Growth Catalysts
- Aging Demographics:The United States sustains procedure volumes through Medicare-eligible populations requiring shoulder and ankle arthroplasty. Sports-related trauma among active aging segments expands revision surgery pipelines.
- EU Medical Device Regulation:Enhanced clinical evidence requirements for Class III orthopedic devices accelerate patient-specific instrumentation adoption as manufacturers rebuild submission strategies around additive-manufactured implants.
- Titanium Alloys:Biocompatibility and modulus-matching properties sustain titanium's dominance in load-bearing applications, while osseointegration improvements expand indications to younger, higher-activity patients.
Market Restraints
- Cobalt-Chrome Input Volatility:Mining concentration in southern Africa and refining bottlenecks create price instability for bearing surface materials, compressing margin buffers on premium joint systems.
- FDA 510(k) Predicate Erosion:The agency's evolving predicates policy narrows acceptable equivalence pathways, extending premarket timelines and elevating clinical trial expenditures for novel implant geometries.
- Bio-Resorbable Performance Ceiling:Polymer degradation kinetics and mechanical strength trade-offs limit resorbable screws and plates to pediatric and small-bone applications, capping addressable volume.
Strategic Opportunities
- India's Orthopedic Infrastructure:Underpenetrated joint replacement access in tier-two cities creates white space for modular, cost-optimized implant systems tailored to hospital outpatient departments.
- Point-of-Care 3D Printing:Convergence of additive manufacturing with preoperative planning software enables same-day custom instrumentation production, collapsing logistics layers in trauma centers.
- US IRA Device Pricing Transparency:Medicare negotiation frameworks for orthopedic implants create first-mover advantage for manufacturers with disclosed cost structures and domestic manufacturing footprints.
Industry Challenges
- Additive Manufacturing Certification:FDA validation protocols for laser-sintered titanium lattice structures lack standardization, forcing device sponsors to negotiate individualized quality agreements with agency reviewers.
- Sterile Processing Workforce Gap:ASC instrument reprocessing departments face technician shortages, elevating infection risk exposure and complicating liability allocation between manufacturers and surgical facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extremity Reconstruction Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Plates, Screws, Implants, Surgical Instruments End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Ambulatory Surgical Centers Material: Titanium, Stainless Steel, Polyether Ether Ketone, Bio-resorbable Polymers Application: Trauma Surgery, Joint Reconstruction, Sports Medicine, Deformity Correction |
| Companies Covered | Stryker, Zimmer Biomet, Smith & Nephew, DePuy Synthes, Wright Medical, Integra LifeSciences, Acumed, Exactech, Orthofix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extremity Reconstruction Market Emerging Trajectories
Patient-specific instrumentation and bio-resorbable polymers are compressing the gap between trauma repair and biological healing, while regulatory convergence on real-world performance surveillance rewrites post-market obligations.
Polyether ether ketone composites are miniaturizing fixation hardware for hand and wrist reconstruction, enabling anatomic plates that match cortical bone stiffness. ASC hand surgeons are adopting these systems at twice the rate of hospital-based peers. This material transition is miniaturizing incision footprints and accelerating rehabilitation protocols for sports trauma.
The EU Medical Device Regulation's enhanced clinical evidence requirements for Class III orthopedic devices are forcing manufacturers to rebuild premarket submission strategies around patient-matched implants. Metal-on-metal bearing surfaces face heightened scrutiny, compressing predicate availability and elevating biomechanical testing expenditures. European shoulder arthroplasty platforms are responding with ceramic-on-polyethylene conversions and expanded follow-up registries.
Surgeon ownership in ambulatory surgical centers is consolidating procurement authority away from hospital materials management departments. Device representatives now negotiate directly with physician-partners on implant pricing and instrument tray configurations, displacing centralized contracting in orthopedic trauma. This channel compression is most visible in Florida and Texas, where ASC joint replacement volumes exceed hospital outpatient departments.
Extremity Reconstruction Market Segmentation
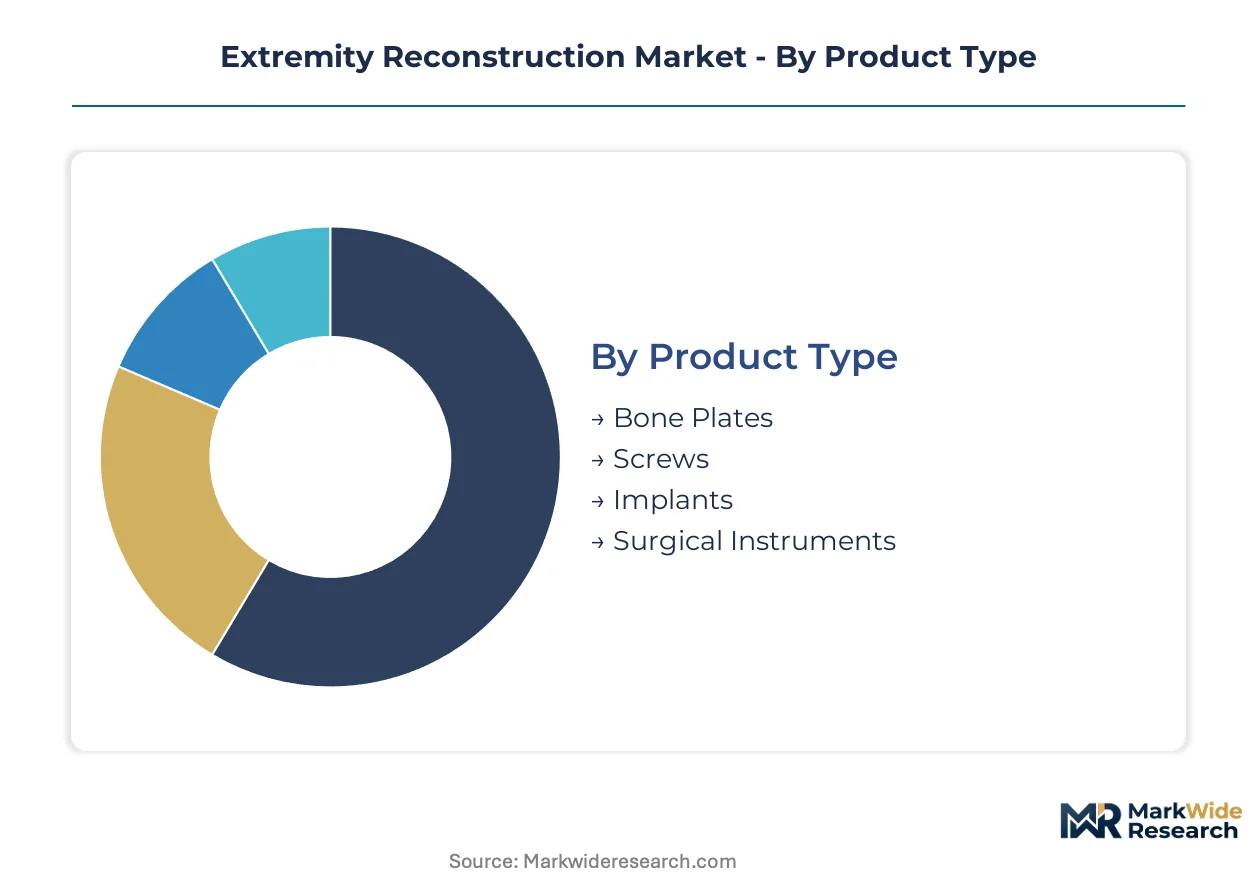
Segmentation in extremity reconstruction reveals how material selection, procedural setting, and clinical application intersect to determine pricing power and channel strategy. Manufacturers must align product portfolios with the diverging economics of hospital outpatient departments versus ambulatory surgical centers.
Product Type:
Channel mix varies sharply by product complexity — implants and instrument systems flow through direct sales to hospitals, while bone plates and screws penetrate ASCs through distributor networks.
- Implants:Joint replacement systems and osteosynthesis devices fabricated from titanium alloys or cobalt-chrome bearing surfaces. Demand concentrates in Medicare-eligible populations across the United States requiring shoulder and ankle arthroplasty, with revision surgery pipelines expanding among active aging segments.
- Screws:Cortical, cancellous, and cannulated fixation hardware spanning titanium, stainless steel, and bio-resorbable polymer compositions. Ambulatory surgical centers in Florida and Texas are consolidating procurement authority for these disposable-intensive products, displacing hospital materials management departments.
- Bone Plates:Anatomic and locking plate systems for fracture fixation.
- Surgical Instruments:Reusable and disposable instrumentation kits sterilized for same-day discharge protocols.
By volume, Screws lead due to trauma frequency. By growth pace, Implants are climbing the fastest on arthroplasty expansion.
End User:
Cost tier stratification separates premium hospital contracts from mid-tier ASC arrangements and economy rehabilitation center supply.
- Ambulatory Surgical Centers:Same-day discharge protocols for extremity trauma and elective joint reconstruction. Surgeon ownership in Florida and Texas ASCs consolidates procurement authority, forcing device representatives to negotiate directly with physician-partners on implant pricing.
- Hospitals:Inpatient and outpatient departments managing complex polytrauma and revision arthroplasty. Hospital outpatient departments in the United States retain dominance for shoulder replacement volumes where overnight observation remains standard.
- Orthopedic Clinics:Preoperative planning and postoperative rehabilitation sites.
- Rehabilitation Centers:Post-surgical recovery and physical therapy facilities.
By procedure count, Hospitals retain the largest share. By expansion trajectory, Ambulatory Surgical Centers are gaining share fastest on channel compression.
Material:
Application severity drives material selection — load-bearing joints demand titanium modulus-matching, while pediatric and sports applications tolerate bio-resorbable strength trade-offs.
- Titanium:Ti-6Al-4V and commercially pure titanium alloys engineered for fatigue resistance and osseointegration. The United States sustains the largest revenue pool for titanium implants due to biocompatibility and modulus-matching properties, with osseointegration improvements expanding indications to younger, higher-activity patients.
- Bio-resorbable Polymers:Polylactic acid and polyglycolic acid compositions eliminating secondary removal procedures. Pediatric and sports medicine applications in ASCs are driving the steepest expansion trajectory as surgeons seek to eliminate hardware removal surgeries.
- Stainless Steel:Cost-optimized fixation hardware for trauma applications.
- Polyether Ether Ketone:Radiolucent composites matching cortical bone stiffness for hand and wrist reconstruction.
By revenue concentration, Titanium leads. By growth pace, Bio-resorbable Polymers are expanding most quickly.
Application:
Customer type fragmentation separates high-acuity trauma centers from elective joint practices and sports-focused clinics.
- Joint Reconstruction:Shoulder, elbow, wrist, hip, knee, ankle, and foot arthroplasty procedures. Medicare-eligible populations in the United States sustain procedure volumes, with ceramic-on-polyethylene conversions responding to EMA scrutiny of metal-on-metal bearing surfaces.
- Trauma Surgery:Acute fracture fixation and polytrauma management. Point-of-care 3D printing convergence with preoperative planning software is collapsing logistics layers in United States trauma centers through same-day custom instrumentation production.
- Sports Medicine:Ligament repair and cartilage restoration procedures.
- Deformity Correction:Osteotomy and limb lengthening interventions.
By procedure volume, Trauma Surgery leads. By value per case, Joint Reconstruction is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while European markets absorb regulatory compliance premiums. Germany and Japan maintain premium positioning through precision manufacturing clusters. India's cost-optimized infrastructure attracts modular implant sourcing.
United States
Medicare-eligible populations drive shoulder and ankle arthroplasty volumes across Florida and Texas ASC clusters. The FDA's 510(k) pathway governs implant commercialization timelines. Greater Boston's orthopedic innovation corridor anchors patient-specific instrumentation development.
Germany
EMA scrutiny of metal-on-metal bearing surfaces accelerates ceramic-on-polyethylene conversions in shoulder platforms. The EU Medical Device Regulation imposes enhanced clinical evidence requirements for Class III orthopedic devices. Baden-Württemberg's precision engineering belt concentrates additive-manufactured implant production.
Japan
PMDA's evolving predicates policy narrows equivalence pathways for novel implant geometries. METI standards support titanium alloy modulus-matching innovations. The Kansai region's medical device manufacturing base specializes in osseointegration surface technologies.
India
Tier-two city hospital outpatient departments present white space for cost-optimized modular systems. CDSCO regulates orthopedic device imports and domestic manufacturing licensing. Maharashtra's Mumbai-Pune corridor consolidates trauma implant contract manufacturing.
Switzerland
Swissmedic's quality protocols sustain premium positioning for bearing surface materials. Geneva and Basel clusters specialize in cobalt-chrome refining and precision finishing. Domestic manufacturers command margin buffers through vertical control of critical input supply.
Extremity Reconstruction Market Vendor Landscape
Concentration sits with integrated implant-instrument ecosystems that dominate high-volume trauma accounts. Large-scale manufacturers leverage capital intensity advantages over mid-tier specialists. Three archetypes define competitive positioning: diversified orthopedic conglomerates, extremity-focused specialists, and materials-science pure-plays. M&A activity and patient-matched manufacturing partnerships constitute the dominant competitive moves reshaping vendor relationships.
Within the diversified orthopedic tier, Stryker and Zimmer Biomet exemplify integrated platform strategies. Stryker's direct sales infrastructure anchors hospital outpatient department relationships. Zimmer Biomet occupies a premium positioning through proprietary shoulder and ankle arthroplasty systems. Among extremity-focused specialists, Wright Medical and Acumed represent the mid-cap archetype competing through surgeon-centric instrument configurations. Smith & Nephew sits within the materials-science tier, leveraging biological graft competencies.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| Smith & Nephew |
| DePuy Synthes |
| Wright Medical |
| Integra LifeSciences |
| Acumed |
| Exactech |
| Orthofix |
| Others |
Supply Flow & Price Mechanics
FDA 510(k) predicate requirements and EU MDR clinical evidence thresholds simultaneously gate supplier qualification and stratify implant pricing across premium patient-matched systems and standard off-the-shelf configurations. This dual certification burden compresses margin buffers for mid-tier manufacturers while rewarding integrated players with pricing power in high-volume trauma accounts.
Pricing Analysis
Configured-to-order pricing for patient-specific instrumentation commands 40-60% premiums over standard implant geometries, with differentiation anchored in FDA predicate availability and surgeon-specific instrument tray bundling. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, volume scale, and after-sales service intensity. Cost compression in economy screws and plates is intensifying because ASC procurement committees in Florida and Texas consolidate purchasing authority. Hospital outpatient departments exhibit lowest price sensitivity due to Medicare reimbursement stability, while independent ASCs negotiate aggressively on disposable kit economics.
Supply Chain Analysis
Strategic stockpiling of cobalt-chrome and titanium sponge dominates over just-in-time preferences given southern African mining concentration and geopolitical exposure. Supply concentrates in the United States for precision finishing, Germany for additive manufacturing equipment, and China for rare earth processing. Raw material dependencies center on titanium sponge, cobalt-chrome alloys, and high-performance polymers. Single-source vulnerability in electron beam melting equipment creates qualification bottlenecks for lattice-structured implants. Distribution runs through direct sales forces to hospital systems and distributor networks penetrating ASC clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against bio-resorbable polymer systems that threaten titanium screw and plate volumes in pediatric and sports medicine segments. Incumbents must navigate material transitions while preserving load-bearing joint replacement dominance.
For Market Incumbents: Fortify predicate libraries through biomechanical testing investments that preempt FDA equivalence pathway erosion. Anchor hospital outpatient department relationships with integrated implant-instrument ecosystems that resist ASC channel compression. Backward integration into titanium sponge refining secures margin buffers against cobalt-chrome price volatility.
For New Entrants and Emerging Players: Lead with point-of-care 3D printing partnerships that collapse logistics layers in United States trauma centers. India's tier-two city hospital outpatient departments present the most penetrable geography for cost-optimized modular systems. Target surgeon-owned ASCs in Florida and Texas with disposable-intensive screw and plate configurations that bypass centralized hospital contracting.
For Investors and Strategic Acquirers: EU MDR enhanced clinical evidence requirements reshape the acquisition landscape toward patient-matched manufacturing capabilities with established European notified body relationships. Long-term viability favors platforms with additive manufacturing validation protocols and real-world performance registries. The signal to watch is FDA predicate policy convergence on metal-on-metal bearing surfaces, which would accelerate ceramic-on-polyethylene conversion investments.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Expansion | Broadens equivalence pathways for novel implant geometries while compressing premarket timelines. |
| Patient-Specific Instrumentation Partnership | Enables same-day custom production in trauma centers through additive manufacturing convergence. |
| ASC Direct Procurement Channel | Displaces hospital materials management in Florida and Texas joint replacement volumes. |
| Bio-Resorbable Polymer R&D Investment | Captures pediatric and sports medicine applications eliminating secondary hardware removal. |
| EU MDR Clinical Evidence Registry | Satisfies enhanced Class III orthopedic device requirements for European market access. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) databases, EU MDR notified body guidance, hospital procurement records, and orthopedic surgeon society publications. Primary interviews engaged orthopedic surgeons, hospital purchasing committee members, biomedical engineers specializing in additive manufacturing, GPO contracts managers, and ASC operations directors. Secondary validation drew from CMS Medicare procedure data, SEC orthopedic manufacturer filings, and trade customs records for titanium and cobalt-chrome imports. Bottom-up procedure volume estimates triangulated against top-down implant manufacturer revenue segmentation.
Segmentation dimensions modeled include product type, end-user facility tier, material composition, and application severity across the projection horizon. Joint reconstruction, trauma surgery, sports medicine, and deformity correction categories were cross-tabulated with ambulatory surgical center, hospital outpatient, and inpatient settings. CAGRs derived from procedure volume elasticity to aging demographic projections and sports trauma incidence trends. Forecast inputs incorporated FDA 510(k) clearance velocity, EU MDR transition timelines, and ASC joint replacement migration rates.
Forecasts assume regulatory continuity in FDA 510(k) predicates and EU MDR Class III orthopedic device pathways; material policy shifts would require re-modeling. Revision becomes warranted when bio-resorbable polymer mechanical strength thresholds cross load-bearing application viability or when ASC joint replacement volume share crosses hospital outpatient parity in key states.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ambulatory Polysomnography (Psg) Systems Market
Medical Devices
Americas Wearable Medical Device Market
Medical Devices
South Korea ECG Market
Medical Devices
Brazil Medical Devices Market
Medical Devices
Europe Renal Denervation Devices Market
Medical Devices
Global Laparoscopy Devices Market
Medical Devices
Electrosurgery Accessories Market
Medical Devices
Permanent Artificial Skin Market
Medical Devices
Creatinine Meter Market
Medical Devices
Alpha Emitter Market
Medical Devices
X-Ray Stretchers Market
Medical Devices
Global Cosmetic Implants Market
Medical Devices
Silastic Implant Market
Medical Devices
North America Invisible Orthodontics Market
Medical Devices
High Viscosity Bone Cement Market
Medical Devices
Intravenous Transportation System Market