
 GCC Hydroxypropyl Methylcellulose Market | 2026-2036
GCC Hydroxypropyl Methylcellulose Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Hydroxypropyl Methylcellulose Market Intelligence
Construction firms are reorganizing their cellulose ether procurement priorities as pharmaceutical and food manufacturers compete for tighter HPMC supply. Ashland leverages its pharmaceutical-grade specialization to command premium positioning across Gulf formulation houses. Dow Inc. anchors its regional presence through industrial-grade bulk supply to cement and mortar producers. Shin-Etsu Chemical Co., Ltd. differentiates via high-purity cosmetic-grade output targeting premium personal care brands in Dubai and Riyadh.
Hydroxypropyl methylcellulose is a semi-synthetic polymer derived from cellulose etherification with propylene oxide and methyl chloride, yielding a water-soluble compound with gelation temperatures between 50°C and 70°C that functions as a thickener, film-former, and controlled-release matrix across multiple industries. Pharmaceutical-grade HPMC leads value generation due to stringent purity mandates for tablet coatings and ophthalmic formulations, while construction-grade volume dominates tonnage flows into tile adhesives and self-leveling compounds. Food-grade applications sustain steady offtake from Gulf dairy and bakery processors seeking plant-based stabilizers compliant with halal certification frameworks.
SASO, the UAE's Ministry of Industry and Advanced Technology standards arm, and Saudi Food and Drug Authority collectively shape product registration pathways, with construction material codes tightening VOC thresholds and pharmaceutical monographs aligning with Gulf Central Committee for Drug Registration harmonized standards. Manufacturers must monitor evolving halal certification requirements for food-grade HPMC and biocompatibility testing protocols for pharmaceutical excipient approvals. Stakeholders should track how Red Sea Project and NEOM construction timelines alter industrial-grade demand patterns relative to specialty-grade commitments.
Market Dynamics
Megaproject construction timelines across Saudi Arabia's Red Sea corridor are compressing procurement cycles for cellulose ether additives, forcing suppliers to align production schedules with phased cementitious material deliveries rather than traditional inventory stocking patterns.
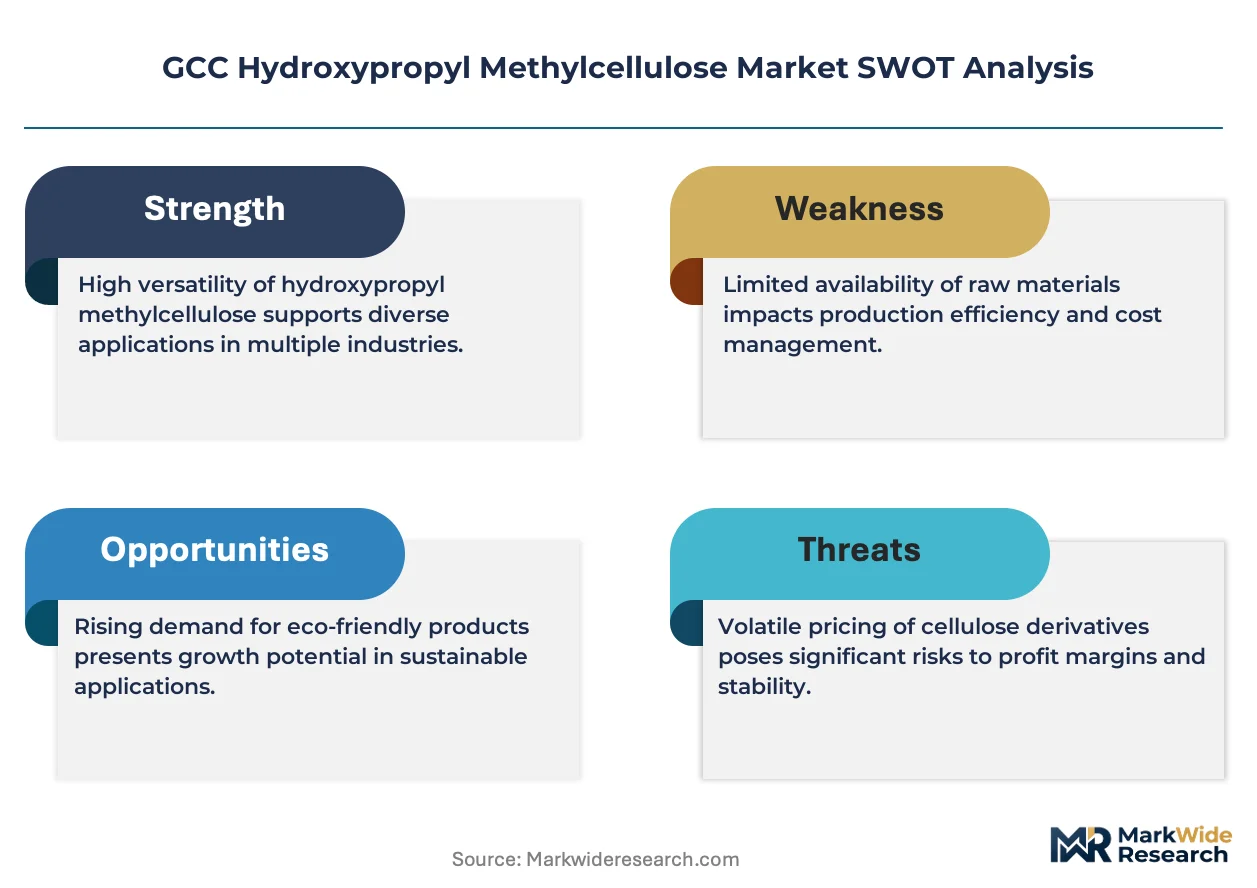
Growth Catalysts
- NEOM and Red Sea Project construction waves:Saudi Arabia's giga-project pipeline is pulling industrial-grade HPMC volumes into pre-mixed mortar and self-leveling compound formulations at unprecedented scale.
- SASO building material standard revisions:Tightened performance specifications for tile adhesives and renders are mandating higher-grade cellulose ether incorporation, upgrading specification tiers across Riyadh and Jeddah construction supply chains.
- Halal-certified food stabilizer demand:UAE and Saudi dairy processors are substituting gelatin with plant-based HPMC in yogurt and dessert applications, opening new offtake channels for food-grade producers.
Market Restraints
- Propylene oxide feedstock volatility:HPMC production costs fluctuate with propylene oxide pricing, which tracks naphtha and propylene market swings tied to regional petrochemical output.
- Pharmaceutical-grade supply concentration:Ultra-pure HPMC for tablet coatings and ophthalmic solutions relies on a narrow base of certified producers, creating bottleneck risk for Gulf formulation houses.
- Cement substitution in dry-mix mortars:Geopolymer and alkali-activated binder formulations are displacing conventional Portland cement systems in select UAE green building projects, compressing addressable volume for construction-grade additives.
Strategic Opportunities
- Qatar's infrastructure renewal cycle:Post-World Cup asset repurposing and Lusail City completion are generating fresh demand for high-performance tile adhesives and exterior insulation finish systems.
- Cosmetic-grade HPMC for premium personal care:Dubai and Riyadh beauty brands are formulating halal-certified skincare with high-purity cellulose ethers as texture modifiers and film-formers.
- Saudi Food and Drug Authority excipient harmonization:Alignment with Gulf Central Committee for Drug Registration standards is streamlining pharmaceutical-grade product registration, reducing time-to-market for compliant suppliers.
Industry Challenges
- Cellulose ether process engineering expertise:Gulf-based manufacturers face scarcity of technical specialists capable of optimizing etherification reactor conditions for viscosity grade consistency.
- Multi-jurisdiction halal certification complexity:Food-grade HPMC producers must navigate divergent halal authority requirements across Saudi Arabia, UAE, and Qatar, extending compliance timelines.
- Construction procurement payment cycle compression:Tier-one contractors are extending supplier payment terms to 90-120 days, straining working capital for regional distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Hydroxypropyl Methylcellulose Market |
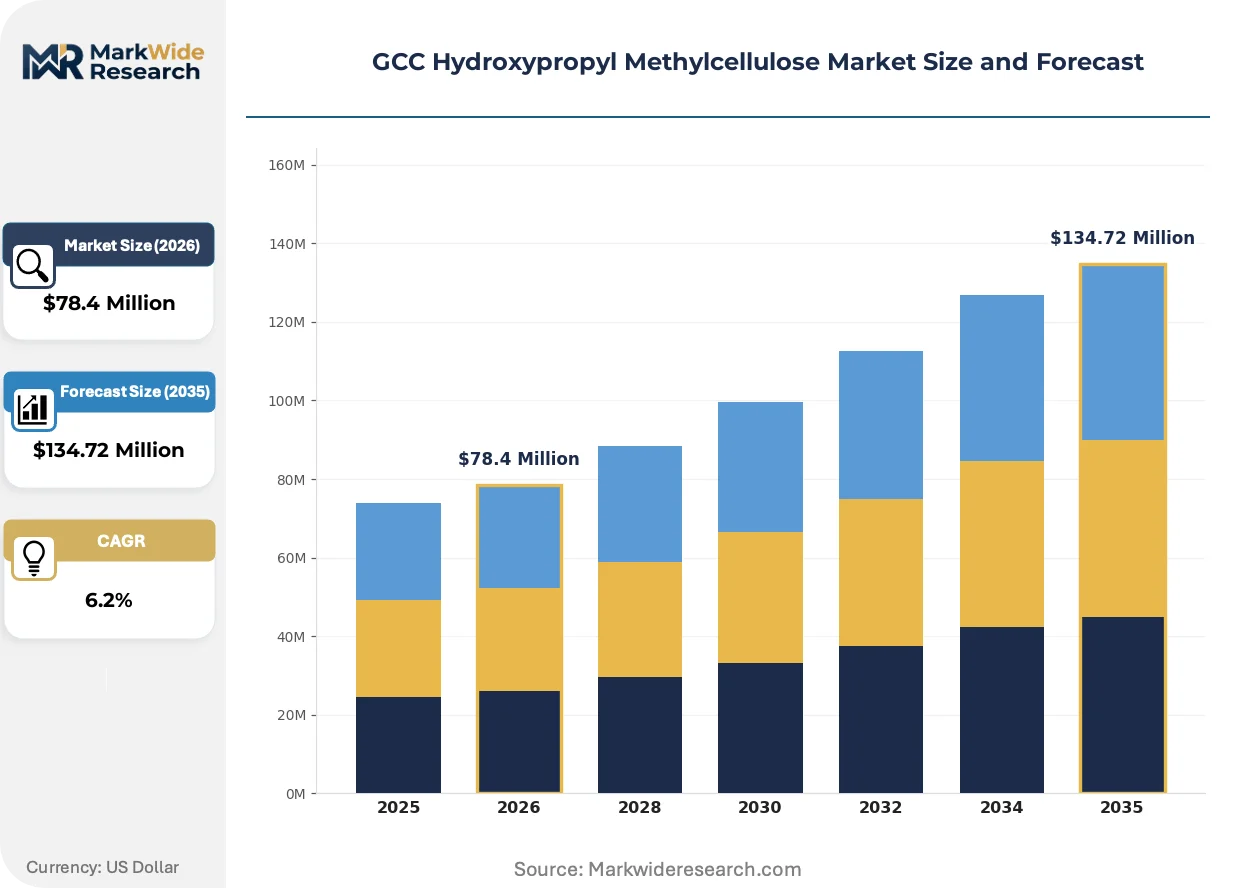
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $134.72 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Food Grade, Industrial Grade, Cosmetic Grade Application: Pharmaceuticals, Food & Beverages, Construction, Personal Care End User: Pharmaceutical Companies, Food Manufacturers, Construction Firms, Cosmetic Brands Packaging Type: Bag, Drum, Carton, Sachet |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., Ashland, DuPont de Nemours, Inc., Dow Inc., Mitsubishi Chemical Corporation, CP Kelco U.S., Inc., Chemcolloid Limited, Zhejiang Haishen New Materials, Celotech Chemicals Co., Ltd., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Hydroxypropyl Methylcellulose Market Strategic Shifts & Innovations
Low-viscosity HPMC grades engineered for spray-applied cementitious systems are gaining specification share as mechanized construction methods displace manual plastering across Gulf megaproject sites.
Modified HPMC architectures with delayed dissolution kinetics are displacing conventional grades in self-leveling underlayment applications, enabling extended open times critical for large-format flooring installations. Saudi ready-mix mortar producers are specifying these grades at accelerating rates, compressing demand for standard construction-grade ether variants.
SASO's updated building material codes are tightening volatile organic compound thresholds for interior finishes, compelling reformulation of tile adhesives and joint compounds toward low-emission cellulose ether systems. Construction chemical distributors in Riyadh and Jeddah are rebuilding product portfolios to meet these specifications, with compliance deadlines driving inventory turnover through Q3 2026.
Buying committees at major Gulf contractors are consolidating cellulose ether sourcing through nominated supplier agreements, replacing fragmented spot purchasing with annual volume commitments tied to project milestone deliveries. This concentration is most visible in Saudi Arabia's Red Sea coastal developments, where EPC firms are locking in multi-year supply contracts to secure grade consistency across phased construction programs.
GCC Hydroxypropyl Methylcellulose Market Segmentation
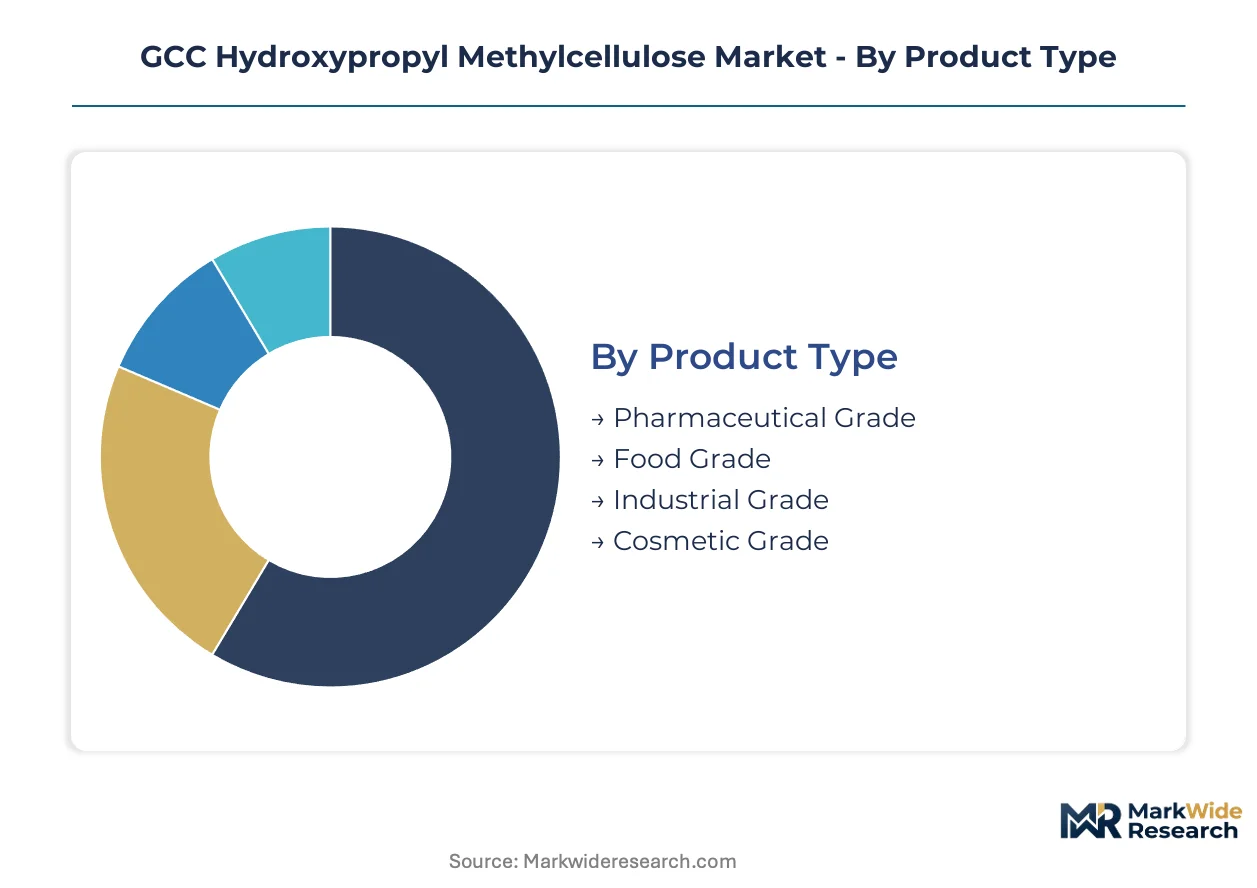
Cellulose ether procurement patterns across the Gulf Cooperation Council diverge sharply by purity tier, with each grade carrying distinct regulatory burdens and margin profiles. Construction-grade tonnage flows dominate logistics networks, while pharmaceutical and food grades command certification-intensive supply chains.
Product Type:
Saudi Food and Drug Authority monographs and SASO building material standards create divergent compliance pathways across purity grades, segmenting supplier capabilities and pricing power.
- Pharmaceutical Grade:Ultra-pure HPMC meeting Gulf Central Committee for Drug Registration standards serves tablet coatings, controlled-release matrices, and ophthalmic formulations. Saudi formulation houses in Riyadh and Jeddah concentrate procurement through certified excipient distributors to secure batch-to-batch consistency for SFDA submissions.
- Industrial Grade:Standard-viscosity cellulose ethers modified for cementitious applications dominate tonnage flows into Saudi megaproject corridors. NEOM and Red Sea Project contractors specify these grades for tile adhesives and self-leveling compounds under tightened SASO performance codes.
- Food Grade:Halal-certified HPMC substitutes for gelatin in UAE and Saudi dairy applications, with processors navigating divergent certification requirements across national halal authorities.
- Cosmetic Grade:High-purity cellulose ethers function as texture modifiers and film-formers in premium skincare formulations targeting Dubai and Riyadh beauty markets.
Industrial grade handles the majority of throughput; pharmaceutical grade is expanding most quickly on share as Gulf formulation houses upgrade excipient specifications.
Application:
End-use concentration tracks construction cycle intensity, with megaproject timelines compressing procurement patterns relative to steady-state pharmaceutical offtake.
- Construction:Pre-mixed mortars, tile adhesives, and renders across Saudi Arabia's giga-projects absorb bulk cellulose ether volumes. Mechanized application methods are displacing manual plastering, favoring low-viscosity HPMC grades engineered for spray systems.
- Pharmaceuticals:Tablet coating and controlled-release formulations drive value concentration despite smaller volumes. Saudi and UAE formulation houses compete for limited certified excipient supply.
- Food & Beverages:Plant-based stabilizer substitution in yogurt and dessert applications sustains steady offtake from Gulf dairy processors seeking halal-compliant alternatives to animal-derived thickeners.
- Personal Care:Premium skincare and haircare formulations in Dubai and Riyadh incorporate cosmetic-grade cellulose ethers as rheology modifiers and film-forming agents.
Construction commands the volume base; personal care is climbing the fastest as regional beauty brands expand halal-certified product lines.
End User:
Customer procurement sophistication varies by sector, with construction firms consolidating through nominated supplier agreements while pharmaceutical houses maintain multi-source excipient strategies.
- Construction Firms:Tier-one Saudi EPC contractors are locking in multi-year cellulose ether contracts tied to phased Red Sea Project deliveries, replacing fragmented spot purchasing.
- Pharmaceutical Companies:Gulf formulation houses in Riyadh, Jeddah, and Dubai manage excipient qualification timelines spanning 18-24 months for SFDA and MOHAP registrations.
- Food Manufacturers:UAE and Saudi dairy processors specify halal-certified HPMC through approved supplier lists, with procurement committees auditing certification chain integrity.
- Cosmetic Brands:Premium beauty houses in Dubai and Riyadh source high-purity grades through specialized distributors serving the regional personal care sector.
Construction firms drive the largest aggregate orders; cosmetic brands are gaining share fastest as regional halal beauty markets mature.
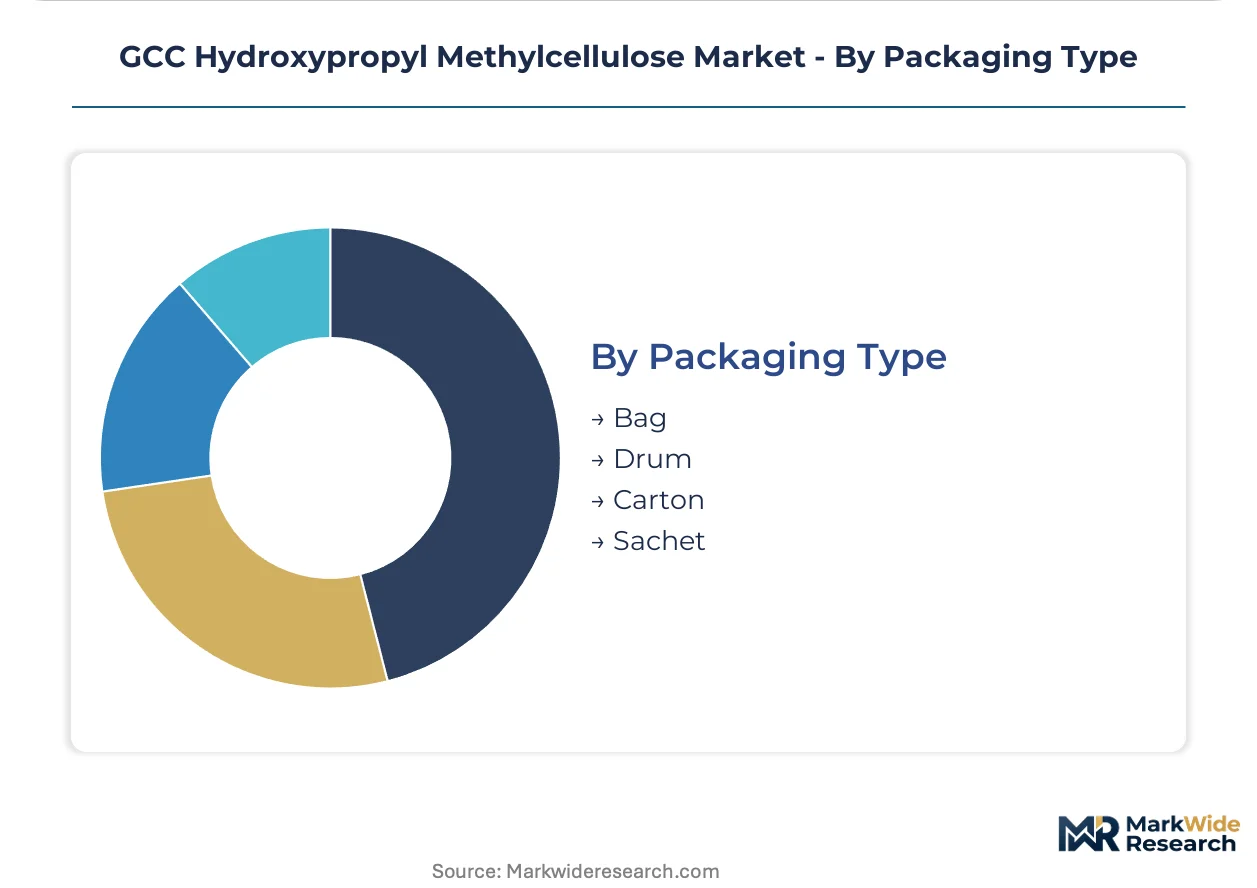
Packaging Type:
Logistics configuration reflects grade sensitivity and handling scale, with bulk industrial shipments contrasting against contamination-controlled pharmaceutical units.
- Bag:Multi-layer kraft bags with polyethylene liners protect construction-grade HPMC from moisture during Saudi megaproject site deliveries.
- Drum:Steel and fiber drums serve pharmaceutical and food-grade requirements, enabling sealed storage through Gulf humidity extremes.
- Carton:Folding carton configurations package cosmetic-grade cellulose ethers for premium personal care ingredient distribution.
- Sachet:Single-use sachets support sampling and small-batch pharmaceutical formulation development across Gulf R&D facilities.
Bags handle the majority of throughput; drums are expanding fastest as certified grade volumes rise across pharmaceutical and food applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cellulose ether supply chains converge on Saudi Arabia and the UAE, where megaproject construction and pharmaceutical formulation clusters generate divergent demand profiles. The Gulf Cooperation Council's regulatory fragmentation across national halal authorities and building codes shapes distinct procurement corridors in each member state.
Saudi Arabia
NEOM and Red Sea Project construction waves absorb industrial-grade HPMC volumes for self-leveling compounds and tile adhesives. SASO building material standard revisions mandate upgraded cellulose ether specifications for cementitious applications. Riyadh and Jeddah construction supply chains are consolidating procurement through nominated supplier agreements tied to phased megaproject deliveries.
United Arab Emirates
Dubai's premium personal care brands and Abu Dhabi's pharmaceutical formulation houses compete for high-purity HPMC supply. MOHAP pharmaceutical regulations and Dubai Municipality green building codes create dual compliance pathways for cellulose ether suppliers. The Jebel Ali industrial corridor hosts distributors serving both construction chemical and cosmetic ingredient markets.
Qatar
Post-World Cup infrastructure repurposing and Lusail City completion generate fresh demand for high-performance tile adhesives and exterior insulation systems. The country's national standards body enforces construction material specifications that align with Gulf Cooperation Council harmonized codes. Doha-based contractors are locking in multi-year cellulose ether contracts for remaining megaproject phases.
Kuwait
Residential and commercial construction recovery drives steady offtake for construction-grade HPMC in pre-mixed mortar applications. The national construction authority maintains building material codes that reference SASO performance standards. Kuwait City construction chemical distributors are expanding inventories to meet renewed project activity.
Oman
Industrial zone development and tourism infrastructure projects sustain niche demand for cellulose ether additives in specialty renders. The national ministry of commerce and industry oversees product registration for imported construction chemicals. Muscat and Salalah port zones serve as transshipment nodes for HPMC destined for broader Gulf markets.
GCC Hydroxypropyl Methylcellulose Market Key Industry Players
Concentration sits with multinational chemical conglomerates possessing integrated cellulose ether production and Gulf distribution infrastructure. The supplier base stratifies into three tiers: pharmaceutical-grade specialists commanding premium positioning, industrial-grade bulk suppliers anchoring construction volumes, and regional traders filling spot demand gaps. Capacity expansion and strategic distribution partnerships represent the dominant competitive moves as suppliers align with megaproject procurement cycles.
Among Japanese chemical conglomerates, Shin-Etsu Chemical Co., Ltd. exemplifies the high-purity specialization archetype serving cosmetic and pharmaceutical segments. Ashland occupies a position within the pharmaceutical-grade tier, leveraging excipient certification capabilities across Gulf formulation houses. Dow Inc. anchors the industrial-grade vector, supplying bulk cellulose ethers to cement and mortar producers. DuPont de Nemours, Inc. and Mitsubishi Chemical Corporation represent diversified materials science players with regional presence across multiple HPMC purity grades.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| Ashland |
| DuPont de Nemours, Inc. |
| Dow Inc. |
| Mitsubishi Chemical Corporation |
| CP Kelco U.S., Inc. |
| Chemcolloid Limited |
| Zhejiang Haishen New Materials |
| Celotech Chemicals Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Production scale economies at integrated cellulose ether facilities in China and Southeast Asia establish cost floors that Gulf distributors cannot match through toll-manufacturing arrangements. This scale concentration compresses margins for regional traders while granting multinational suppliers pricing power over pharmaceutical-grade volumes where certification barriers limit substitution.
Pricing Analysis
Three-tier pricing structure across pharmaceutical, industrial, and food-grade levels dominates GCC HPMC procurement. Price differentiation rests on halal certification stringency and viscosity grade consistency, with pharmaceutical-grade commanding substantial premiums due to SFDA excipient registration requirements. Cost compression in construction-grade volumes is intensifying because Saudi megaproject contractors are consolidating annual volume commitments. Food manufacturers exhibit highest price sensitivity due to gelatin substitution economics, while cosmetic brands show lowest sensitivity for high-purity film-forming grades.
Supply Chain Analysis
Inventory cycles stretching 90-120 days strain working capital across Gulf distributor networks serving construction chemical markets. Manufacturing concentration in China, South Korea, and Germany feeds GCC demand through Jebel Ali and Dammam port hubs. Raw material dependencies on propylene oxide, methyl chloride, and refined cotton linter create feedstock cost volatility tracking naphtha markets. Single-source vulnerability sits with pharmaceutical-grade producers holding Gulf Central Committee for Drug Registration certifications. Distribution runs through nominated supplier agreements at tier-one Saudi EPC firms replacing fragmented spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical specialists capable of optimizing etherification reactor conditions for viscosity grade consistency remain scarce across Gulf-based manufacturing operations. This capability gap constrains regional production ambitions and reinforces dependence on imported cellulose ether volumes.
For Market Incumbents: Shield pharmaceutical-grade positioning through accelerated SFDA excipient pre-qualification investments before harmonized standards tighten. Anchor construction-grade market share via backward integration into regional propylene oxide storage at Jebel Ali and Dammam logistics hubs. Cement relationships with Saudi EPC contractors through multi-year nominated supplier agreements tied to Red Sea Project milestone deliveries.
For New Entrants and Emerging Players: Anchor in Qatar's post-World Cup infrastructure renewal cycle where tile adhesive specifications are upgrading but supplier relationships remain fluid. Target cosmetic-grade white space serving Dubai and Riyadh halal-certified beauty brands seeking texture modifier alternatives to conventional thickeners. Pursue technical partnership routes with Japanese high-purity specialists rather than greenfield manufacturing investments.
For Investors and Strategic Acquirers: Gulf-certified excipient distributors with established SFDA registration track records represent the most defensible acquisition profile. Long-term viability hinges on pharmaceutical-grade volume growth as Gulf formulation houses expand generic drug manufacturing capacity. Monitor SASO building code revision timelines as inflection indicators for construction-grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide Storage | Jebel Ali and Dammam captive storage buffers feedstock volatility for GCC distributors. |
| SFDA Excipient Pre-Qualification Investment | Early registration secures pharmaceutical-grade supply priority ahead of harmonized standards. |
| Long-Term Supply Agreement with Saudi EPC Firms | NEOM and Red Sea Project nominated supplier status locks construction-grade volume commitments. |
| Halal Certification Chain Audit Capability | Food-grade HPMC suppliers gain procurement committee approval across Saudi and UAE dairy processors. |
| Low-Viscosity Spray-Grade Product Line Extension | Mechanized plastering adoption across Saudi megaproject sites favors engineered dissolution kinetics. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and Gulf petrochemical output statistics. Primary interviews engaged construction chemical procurement managers at Saudi EPC firms, pharmaceutical formulation directors in Riyadh and Dubai, and cellulose ether technical specialists at regional distributors. Bottom-up volume estimates derived from megaproject cementitious material specifications triangulate against top-down trade flow analysis across GCC import records.
Segmentation dimensions modeled span grade tier, end-use industry, packaging format, and regional production hub across the analysis window. CAGRs were derived through regression analysis of historical trade volumes against construction cycle intensity and pharmaceutical formulation expansion. Industry-specific forecast inputs include SASO building code revision timelines and SFDA excipient harmonization progress with Gulf Central Committee for Drug Registration standards.
Material uncertainties — propylene oxide feedstock volatility, megaproject construction delays, and halal certification authority divergence — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained Red Sea Project execution pace and continued gelatin substitution in Gulf dairy processing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Eggshell Membrane Derivatives Market
Specialty Compounds
N-Propyl Propionate Market
Specialty Compounds
Propoxylates Market
Specialty Compounds
Methane Sulfonyl Chloride Market
Specialty Compounds
Potting Compound Market
Specialty Compounds
Dextran Sulfate Sodium Market
Specialty Compounds
Phenylacetyl Chloride Market
Specialty Compounds
Low Density Sheet Moulding Compound (SMC) Market
Specialty Compounds
Lithium Compound Market
Specialty Compounds
Specialty Sorbents Market
Specialty Compounds
Mexico Masterbatch Market
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Flexible Foam Market
Specialty Compounds
Calcium Sulphite Market
Specialty Compounds
Dip Molding and Coating Market
Specialty Compounds
Polypeptide Market