
 Dip Molding and Coating Market | 2026-2036
Dip Molding and Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Dip Molding and Coating Market Insights
Equipment leasing and contract manufacturing arrangements is fragmenting competitive tiers in dip molding, lowering capital barriers for mid-scale entrants. DipTech Systems, Inc. leverages captive toolmaking capabilities to shorten prototype cycles for medical device clients. Carlisle Plastics Company, Inc. anchors its position through backward integration into custom compound formulation. Molded Devices, Inc. specializes in multi-dip processes for complex geometries in automotive cable harnesses.
Dip molding and coating deposits liquid polymer onto a heated mandrel or substrate, forming uniform thickness layers typically ranging from 0.1 to 2.0 millimeters that cure into protective skins; the process serves primarily to insulate electrical conductors, cushion medical instruments, and seal industrial components against chemical ingress. Plastic coatings dominate current volume due to cost efficiency in high-run consumer electronics applications, while polyurethane coatings represent the fastest-expanding product category as manufacturers seek solvent-free alternatives with superior abrasion resistance. Thermal dip coating remains the most widely deployed technology, though electrophoretic coating is gaining share in automotive precision parts where film uniformity specifications are tightest.
FDA device regulations and REACH chemical restrictions jointly determine acceptable plasticizer chemistries and biocompatibility testing protocols for dip-coated medical products entering US and European markets. EPA air quality standards for volatile organic compound emissions constrain solvent-based coating operations, pushing capital allocation toward thermal and powder coating infrastructure. Stakeholders must track evolving material certification requirements across multiple regulatory jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
Equipment leasing and contract manufacturing arrangements are fragmenting competitive tiers in dip molding, lowering capital barriers for mid-scale entrants while redirecting formulation priorities toward phthalate-free vinyl alternatives under tightening chemical regulations.
Growth Catalysts
- EU MDR material traceability rules:Medical device manufacturers in Germany's Stuttgart-Mannheim corridor are accelerating procurement of dip-coated surgical instruments and catheter assemblies to meet biocompatibility documentation requirements.
- Polyurethane solvent-free alternatives:Manufacturers seeking superior abrasion resistance are displacing conventional plastic coatings in automotive precision parts where film uniformity specifications are tightest.
- Thermal dip coating infrastructure:EPA air quality standards for volatile organic compound emissions are pushing capital allocation away from solvent-based operations toward thermal and powder coating systems.
Market Restraints
- Plasticizer input cost volatility:REACH compliance is redirecting demand toward specialized phthalate-free chemistries with constrained supplier bases and price premiums.
- Multi-jurisdiction certification friction:FDA device regulations and REACH chemical restrictions jointly determine acceptable formulation paths, extending qualification timelines for products entering both US and European markets.
- Electrophoretic coating substitution:Automotive suppliers are adopting electrophoretic deposition for precision parts where thermal dip coating cannot achieve specified thickness uniformity tolerances.
Strategic Opportunities
- Multi-dip process convergence:Complex geometries in automotive cable harnesses are creating demand for specialized contractors capable of sequential polymer deposition with interlayer adhesion control.
- Captive toolmaking integration:Medical device clients are compressing prototype cycles by partnering with molders maintaining in-house mandrel fabrication capabilities.
- Custom compound formulation backward integration:Compound development expertise represents a defensible position as material certification requirements evolve across multiple regulatory jurisdictions.
Industry Challenges
- Biocompatibility testing skill scarcity:ISO 10993 protocol execution and FDA submission preparation require specialized toxicology and materials science expertise that mid-scale molders struggle to retain.
- Legacy thermal system capex intensity:Conversion from solvent-based to thermal coating infrastructure demands furnace and emission control investments that strain contract manufacturers with thin margin profiles.
- Cross-regulatory qualification timeline compression:Simultaneous FDA 510(k) and EU MDR technical documentation preparation is forcing smaller players to defer market entry or accept revenue concentration in single jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dip Molding and Coating Market |
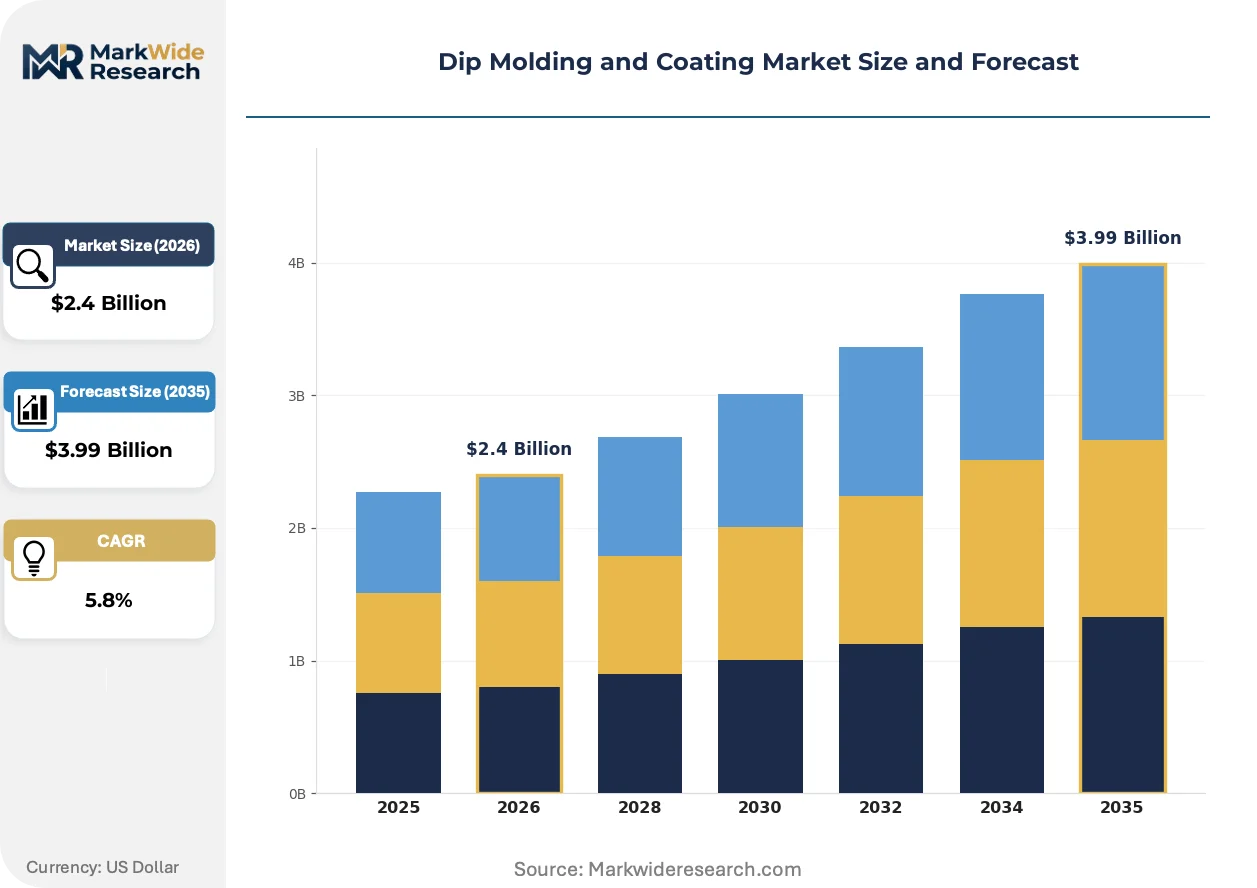
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Coatings, Rubber Coatings, Vinyl Coatings, Polyurethane Coatings End User: Automotive Industry, Consumer Electronics, Medical Devices, Industrial Applications Application: Protective Coating, Insulation, Sealing, Aesthetics Technology: Thermal Dip Coating, Electrophoretic Coating, Spray Coating, Powder Coating |
| Companies Covered | DipTech Systems, Inc., Rubber & Plastics Co., Precision Dip Coating LLC, Carlisle Plastics Company, Inc., Innovative Coatings, Inc., Piper Plastics Corp., Production Sciences, Inc., Molded Devices, Inc., Peerless Plastics & Coatings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dip Molding and Coating Market Trends and Innovations
Digital process control and closed-loop thickness monitoring are compressing variation in dip-coated medical components while regulatory chemical restrictions are accelerating material substitution cycles across all end-use verticals.
Closed-loop thermal imaging systems with real-time viscosity adjustment are virtualizing quality assurance for medical catheter mandrel coating. Surgical instrument manufacturers in Germany and the United States are adopting these systems at pilot scale to eliminate post-process inspection bottlenecks. The technology is virtualizing the traditional separation between production and metrology functions, allowing single-shift operations to achieve lot-release timelines previously requiring dedicated quality laboratories.
REACH Annex XVII restrictions on phthalate plasticizers in articles with prolonged skin contact are forcing reformulation of vinyl dip coatings for medical and consumer applications. Compound suppliers are accelerating bio-based plasticizer development programs to maintain formulation portfolios ahead of sunset dates. Medical device segments with the longest qualification cycles are responding earliest, with some German manufacturers already completing multi-year stability studies on alternative chemistries.
Automotive cable harness buyers are consolidating supplier panels and demanding vendor-managed inventory with consignment stocking arrangements. Tier-1 harness assemblers in Stuttgart are displacing spot procurement with multi-year coating service agreements that transfer demand forecasting risk to dip molders. This pattern is most visible in Germany's industrial corridor, where just-in-sequence delivery requirements from OEM final assembly plants are propagating upstream to coating subcontractors.
Dip Molding and Coating Market Segmentation
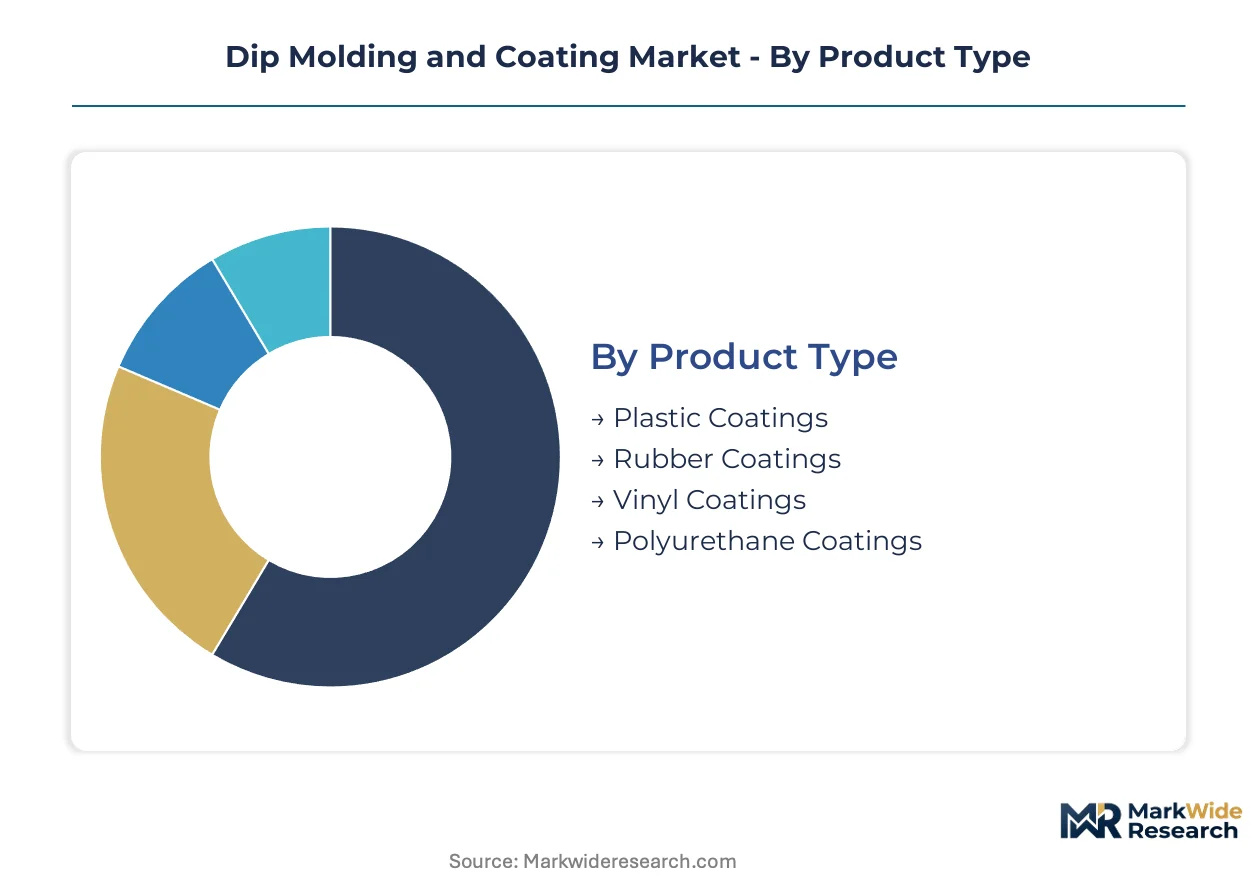
Dip molding and coating market segmentation reveals divergent cash conversion cycles across material chemistries and application technologies. Medical device coatings require extended qualification timelines, while automotive procurement operates on compressed annual sourcing rhythms.
Product Type:
Plastic coatings turn inventory fastest in high-volume consumer electronics runs, whereas polyurethane formulations linger longest in automotive validation pipelines.
- Plastic Coatings:Cost-efficient vinyl and acrylic formulations dominate consumer electronics wire harness protection. Demand concentrates in Shenzhen and Dongguan manufacturing clusters where OEMs specify 0.1-0.5 millimeter thickness ranges for smartphone cable assemblies.
- Polyurethane Coatings:Solvent-free two-component systems cure into abrasion-resistant skins with superior chemical resistance. Automotive cable harness assemblers in Germany's Stuttgart-Mannheim corridor are displacing conventional plastics here to meet OEM durability specifications.
- Rubber Coatings:Natural and synthetic latex deposits provide elastic recovery for industrial grip applications.
- Vinyl Coatings:Phthalate-free formulations are reformulating under REACH Annex XVII pressure in medical device segments.
Plastic coatings dominate installed base. Polyurethane coatings are where expansion concentrates.
End User:
Automotive procurement operates on 12-18 month contract cycles, while medical device coatings extend across multi-year stability studies and regulatory submissions.
- Automotive Industry:Tier-1 harness assemblers demand just-in-sequence delivery with vendor-managed inventory arrangements. Stuttgart-based OEMs are consolidating supplier panels and transferring demand forecasting risk to coating subcontractors through consignment stocking agreements.
- Medical Devices:Surgical instrument and catheter manufacturers face the longest qualification cycles. FDA 510(k) and EU MDR technical documentation preparation is compressing procurement timelines for German manufacturers around Mannheim.
- Consumer Electronics:High-run wire protection for smartphones and laptops operates on quarterly procurement cycles.
- Industrial Applications:Chemical-resistant seals and grips serve maintenance-replacement demand with irregular order patterns.
Automotive industry commands volume leadership. Medical devices are where margin expansion concentrates.
Application:
Protective coating applications scale across the widest customer base, while insulation specifications concentrate in electrical infrastructure with the most demanding thickness uniformity tolerances.
- Protective Coating:Chemical and mechanical barrier functions serve automotive underhood components and industrial hardware. EPA volatile organic compound emission constraints are pushing capital allocation toward thermal curing systems for these applications.
- Insulation:Dielectric strength specifications govern electrical conductor sheathing in automotive and electronics verticals. Film uniformity requirements here are tightest, driving adoption of closed-loop thermal imaging with real-time viscosity adjustment.
- Sealing:Environmental ingress prevention for connectors and junction boxes.
- Aesthetics:Color-matched surface finishes for consumer-facing components.
Protective coating spans the broadest installed base. Insulation is where technology investment concentrates.
Technology:
Thermal dip coating infrastructure amortizes across the highest throughput volumes, while electrophoretic systems serve precision niches with extended equipment payback periods.
- Thermal Dip Coating:Heated mandrel immersion with convection or infrared curing remains the most widely deployed platform. Contract manufacturers favor this technology for its compatibility with high-mix production and lower emission control capital requirements.
- Electrophoretic Coating:Electric field-driven deposition achieves superior film uniformity for automotive precision parts. Tier-1 suppliers are adopting this technology where thermal dip coating cannot meet specified thickness tolerance bands.
- Spray Coating:Robotic application for complex geometries unsuited to immersion.
- Powder Coating:Solvent-free thermoplastic deposition for heavy-duty industrial components.
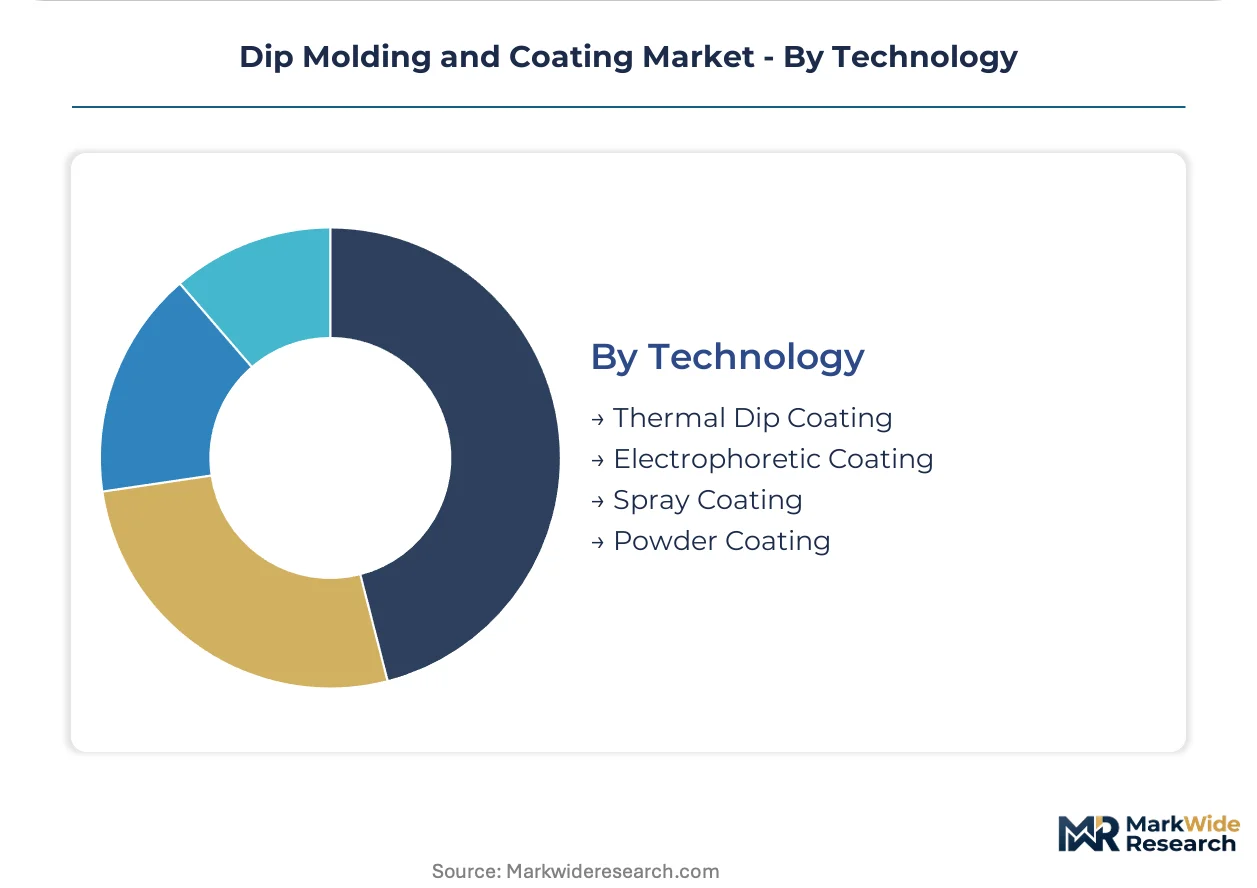
Thermal dip coating dominates installed capacity. Electrophoretic coating is where specification creep concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's Stuttgart-Mannheim corridor where automotive OEMs dictate vendor-managed inventory terms, while Chinese manufacturers in Shenzhen and Dongguan absorb margin compression through high-volume consumer electronics runs.
Germany
EU MDR material traceability requirements and automotive cable harness consolidation drive procurement of dip-coated surgical instruments. ECHA REACH Annex XVII phthalate restrictions accelerate reformulation timelines for vinyl coatings. The Stuttgart-Mannheim industrial corridor hosts tier-1 harness assemblers transferring demand forecasting risk to coating subcontractors through consignment stocking agreements.
United States
FDA 510(k) submission requirements and EPA volatile organic compound emission standards reshape capital allocation toward thermal curing infrastructure. Medical device manufacturers in Greater Boston and the Midwest face extended biocompatibility testing protocols under ISO 10993. Closed-loop thermal imaging systems with real-time viscosity adjustment are virtualizing quality assurance for catheter mandrel coating in pilot-scale operations.
China
Consumer electronics wire protection for smartphone and laptop cable assemblies operates on compressed quarterly procurement cycles. MIIT industrial standards and dual carbon goals pressure solvent-based coating operations toward thermal system conversion. Manufacturing clusters in Shenzhen and Dongguan specify 0.1-0.5 millimeter thickness ranges for high-run OEM assemblies.
Japan
METI energy efficiency guidelines and PMDA medical device regulations jointly determine acceptable plasticizer chemistries for dip-coated products. Automotive precision parts manufacturers seek superior film uniformity through electrophoretic deposition where thermal dip coating cannot meet tolerance bands. Kanto and Kansai industrial zones concentrate demand for abrasion-resistant polyurethane formulations.
India
BIS standards compliance and CDSCO medical device rules extend qualification timelines for imported coating formulations. Industrial grip applications and electrical insulation segments show irregular maintenance-replacement demand patterns. Maharashtra and Gujarat manufacturing hubs are attracting contract manufacturing arrangements that lower capital barriers for mid-scale dip molding entrants.
Dip Molding and Coating Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in captive toolmaking and custom compound formulation. The vendor base separates into three functional layers: equipment and technology providers, integrated molders with backward compound control, and pure-play coating contractors serving spot demand. Two dominant competitive moves are reshaping positioning: equipment leasing arrangements fragmenting tier boundaries, and multi-year service agreements transferring inventory risk from automotive buyers to molders.
Among North American fabricators, DipTech Systems, Inc. and Carlisle Plastics Company, Inc. exemplify divergent strategic postures. DipTech Systems occupies a position anchored in captive toolmaking capabilities that compress prototype cycles for medical device clients. Carlisle Plastics Company, Inc. represents backward integration into custom compound formulation, a defensible posture as material certification requirements evolve across FDA and EU MDR jurisdictions. Molded Devices, Inc. sits within the specialized contractor tier, serving multi-dip process demand for complex automotive geometries.
| Leading Market Players |
|---|
| DipTech Systems, Inc. |
| Rubber & Plastics Co. |
| Precision Dip Coating LLC |
| Carlisle Plastics Company, Inc. |
| Innovative Coatings, Inc. |
| Piper Plastics Corp. |
| Production Sciences, Inc. |
| Molded Devices, Inc. |
| Peerless Plastics & Coatings |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's Shenzhen-Dongguan manufacturing corridor is compressing spot pricing for standard plastic coatings while simultaneously elevating premiums for configured-to-order polyurethane formulations serving German automotive OEMs.
Pricing Analysis
The customization-premium spread separates commodity vinyl coatings from engineered polyurethane systems by a factor reflecting certification burden and formulation complexity. Contract-based long-term offtake dominates automotive procurement, with price differentiation driven by FDA biocompatibility tier and volume scale. Cost compression in consumer electronics wire protection is intensifying because Chinese manufacturers absorb margin erosion through high-volume throughput. Tier-1 automotive harness assemblers exhibit the least price sensitivity due to just-in-sequence delivery requirements, while spot buyers in industrial maintenance segments negotiate most aggressively.
Supply Chain Analysis
Upstream feedstock availability for specialty plasticizers draws from Germany, China, and the United States, with phthalate-free compound development concentrated in Mannheim-area formulation labs. Polymer resin, bio-based plasticizers, and precision-machined mandrels constitute critical input dependencies. Single-source vulnerability sits with REACH-compliant plasticizer suppliers possessing qualified medical-grade chemistries. Distribution runs through tier-1 coating contractors maintaining vendor-managed inventory arrangements with Stuttgart-based automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment leasing platforms are reconfiguring this market toward ecosystem economics, where interoperability between captive toolmaking, compound formulation, and multi-dip process capabilities determines competitive survival.
For Market Incumbents: Pre-empt electrophoretic coating substitution in automotive precision parts by embedding closed-loop thermal imaging systems with real-time viscosity adjustment. Consolidate backward integration into custom compound formulation ahead of REACH Annex XVII sunset dates to defend margin position against phthalate-free reformulation cost pass-through.
For New Entrants and Emerging Players: Mid-scale medical device coating contractors in India's Maharashtra and Gujarat hubs represent the most penetrable entry point, given equipment leasing arrangements that lower capital barriers and CDSCO regulatory timelines that lag EU MDR compliance requirements. A contract manufacturing go-to-market angle bypasses the biocompatibility testing skill scarcity that constrains established Western players.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across thermal dip coating infrastructure as equipment leasing fragments tier boundaries. Long-term viability favors platform integrators with captive toolmaking and compound formulation control. Watch for FDA 510(k) submission volume acceleration as an inflection signal for medical-grade coating demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Custom Compound Formulation | Defends margin position against REACH plasticizer restrictions and extends qualification timelines. |
| Captive Toolmaking Capability Investment | Compresses prototype cycles for medical device clients facing EU MDR documentation pressure. |
| Closed-Loop Thermal Imaging System Deployment | Virtualizes quality assurance for catheter mandrel coating in FDA-regulated production environments. |
| Multi-Dip Process Specialization | Captures complex automotive cable harness demand with interlayer adhesion control requirements. |
| Equipment Leasing Platform Development | Lowers capital barriers for mid-scale entrants and fragments traditional competitive tier boundaries. |
Research Methodology
Initial hypotheses were tested against primary input from coating plant managers, procurement leads at automotive tier-1 suppliers, biomedical engineers at medical device OEMs, and compound formulation R&D directors, then refined through secondary validation against SEC 10-K filings, ECHA REACH registration databases, FDA 510(k) submission records, and customs/trade flow data. Bottom-up capacity estimates and top-down demand projections were triangulated to converge on segment-level outputs.
Demand-supply-balance dynamics across material chemistry, application technology, and end-use verticals structured the analytical framework over the projection horizon. Segmentation dimensions modeled include coating material type, curing technology platform, end-use industry cluster, and regional regulatory jurisdiction. CAGRs were derived from elasticity-adjusted volume trajectories incorporating automotive production forecasts and medical device approval pipeline data.
Macroeconomic conditions sit as an overlay; deviation in automotive OEM production schedules or medical device capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions regarding REACH enforcement timelines and FDA inspection resource allocation. Cross-checking against IHS Markit vehicle production databases and hospital procurement spend indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Alginates and Derivatives Market
Specialty Compounds
Liquid Ammonium and Liquid Potassium Thiosulfate Market
Specialty Compounds
Film Dressing Market
Specialty Compounds
Compounds Market
Specialty Compounds
Polyurea Market
Specialty Compounds
Solketal Market
Specialty Compounds
Automated Compound Storage and Retrieval (ACSR) Market
Specialty Compounds
Acetyl Serine Market
Specialty Compounds
Global Specialty Zeolites Market
Specialty Compounds
Asia-Pacific Collagen Market
Specialty Compounds
Global Specialty Polymer Market
Specialty Compounds
Hydroxypropyl Methylcellulose Market
Specialty Compounds
Global Specialty Amines Market
Specialty Compounds
Chemical Hardener Compounds Market
Specialty Compounds
Polypeptide Market
Specialty Compounds
Global Stable Isotope Labeled Compounds Market