
 Germany Adhesives Market | 2026-2036
Germany Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Adhesives Market Foresight
Specialty chemical distribution in Germany is tilting toward direct technical service partnerships with midsize industrial accounts. Henkel AG & Co. KGaA leverages its Düsseldorf headquarters to anchor premium automotive adhesive supply relationships with OEMs in Stuttgart and Wolfsburg. Sika AG competes through construction-focused formulations that dominate infrastructure rehabilitation projects across the country. DELO Industrie Klebstoffe GmbH & Co. KGaA specializes in high-precision electronics adhesives, occupying a defensible niche in semiconductor packaging applications.
Germany adhesives comprise formulated bonding substances that create structural or semi-structural joints between substrates through polymerization, evaporation, or cooling mechanisms, typically achieving shear strengths from 5 to 40 MPa depending on chemistry and cure conditions. These materials serve primarily to replace mechanical fasteners, reduce component weight, and enable assembly of dissimilar materials in manufacturing environments. Water-based acrylic and polyurethane platforms lead volume consumption in packaging and woodworking applications where emission regulations are most stringent, while reactive epoxy and silicone systems capture disproportionate margin pools in automotive and electronics segments where thermal cycling resistance and dielectric properties command premium positioning. Hot melt technology sustains growth in corrugated board and consumer goods packaging through speed-of-set advantages on high-speed production lines.
KBA enforcement of EU REACH chemical restrictions and the Federal Environment Agency's implementation of the F-Gas Regulation shape formulation roadmaps by restricting specific isocyanates and fluorinated compounds in adhesive chemistries. BIS-equivalent conformity assessment through Germany's national standards body ensures construction adhesive products meet load-bearing certification requirements for structural glazing and cladding applications. Stakeholders must monitor evolving EU Green Deal taxonomy criteria that will reclassify bonding process emissions intensity and determine capital access for facility upgrades.
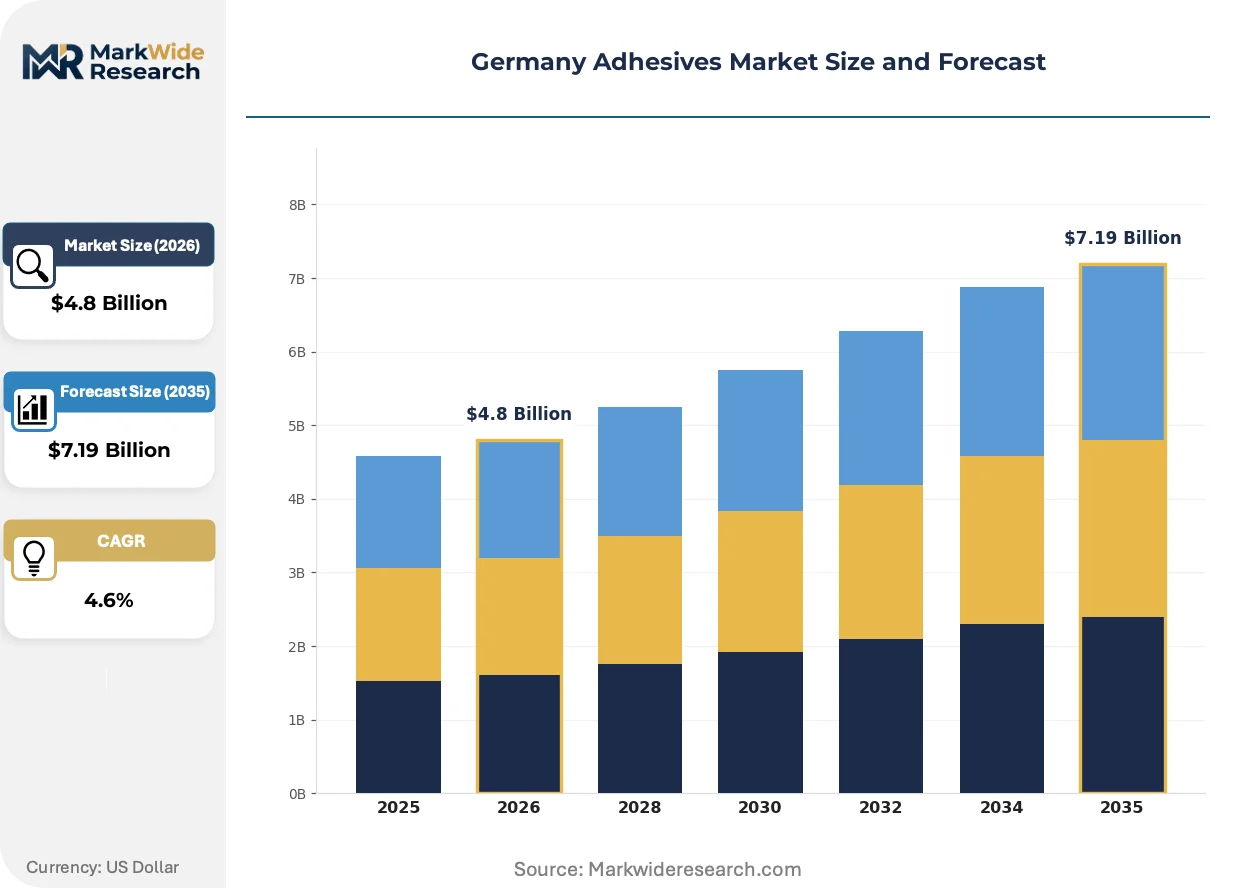
Market Dynamics
Automotive lightweighting mandates from Stuttgart OEMs are compressing bonding cycle times while demanding higher thermal resistance, forcing formulation houses to abandon legacy mechanical fastening specifications entirely.
Growth Catalysts
- EU REACH Annex XVII restrictions:Tightening VOC thresholds in industrial coatings are redirecting solvent-based adhesive volumes toward water-borne polyurethane platforms in packaging applications.
- Baden-Württemberg electric vehicle battery assembly:Cell-to-pack bonding protocols require thermally conductive structural adhesives with dielectric isolation properties.
- Reactive hot-melt advancement:Moisture-curing polyurethane technology is eliminating clamping stations in Bavarian furniture manufacturing through instant green strength development.
Market Restraints
- Petrochemical feedstock volatility:Propylene oxide and MDI price swings compress margin predictability for polyurethane formulators serving Rhine-Ruhr industrial accounts.
- Isocyanate supply concentration:Three European producers control aromatic diisocyanate availability, creating vulnerability for German adhesive manufacturers dependent on just-in-time raw material flows.
- Technical limitation in dissimilar substrate bonding:Polypropylene and polyethylene surface energy challenges persist despite plasma treatment advances, restricting adhesive options in automotive interior trim applications.
Strategic Opportunities
- Thuringia underpenetration:Eastern German manufacturing clusters lack localized technical service coverage for electronics miniaturization adhesives, creating whitespace for precision chemistry specialists.
- EU Green Deal taxonomy alignment:Capital allocation advantages await facilities demonstrating carbon-intensity reductions in curing energy consumption through UV-LED adoption.
- AI-driven formulation optimization:Machine learning convergence with high-throughput rheology testing is compressing new product development timelines from months to weeks.
Industry Challenges
- Adhesive process engineer scarcity:Rheology and surface science expertise gaps in Saxony technical universities delay production line commissioning for advanced reactive systems.
- CE marking timeline compression:Construction product regulation conformity assessment for structural glazing adhesives now requires 18-month documentation cycles versus historical 9-month windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Adhesives Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Silicone, Acrylic Application: Construction, Automotive, Packaging, Woodworking End User: Manufacturing, DIY, Aerospace, Electronics Technology: Water-Based, Solvent-Based, Hot Melt, Reactive |
| Companies Covered | H.B. Fuller Company, Dow, Henkel AG & Co. KGaA, Avery Dennison Corporation, DELO Industrie Klebstoffe GmbH & Co. KGaA, Sika AG, Arkema Group, Jowat SE, 3M, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Adhesives Market Shifts & Advancements
Digital twin integration and sustainable chemistry roadmaps are converging to redefine how adhesive specifications get validated, with real-time cure monitoring displacing destructive batch testing protocols across German manufacturing floors.
UV-LED curable acrylic platforms are virtualizing traditional thermal oven infrastructure in automotive assembly plants. BMW and Mercedes-Benz operations in Munich and Sindelfingen have retrofitted bonding stations with solid-state curing arrays. This technology is virtualizing capital-intensive heating equipment while eliminating thermal damage risks to sensitive electronics substrates.
ECHA's 2023 restriction proposal on aromatic amine curing agents is forcing epoxy formulators toward aliphatic alternatives with modified kinetics. Industrial consequence includes extended pot-life requirements and adjusted dispensing equipment calibration. Electronics packaging segments in Nuremberg are responding with hybrid anhydride-catalyzed systems that maintain throughput while meeting emerging substance restrictions.
Buyer technical service expectations are compressing distributor roles toward specification co-development rather than transactional supply. Midsize industrial accounts in the Rhine-Ruhr corridor now demand on-site rheology optimization and substrate pretreatment validation. This pattern concentrates procurement authority with formulation houses maintaining regional application laboratories, marginalizing traditional chemical distributors lacking bonded substrate testing capabilities.
Germany Adhesives Market Segmentation
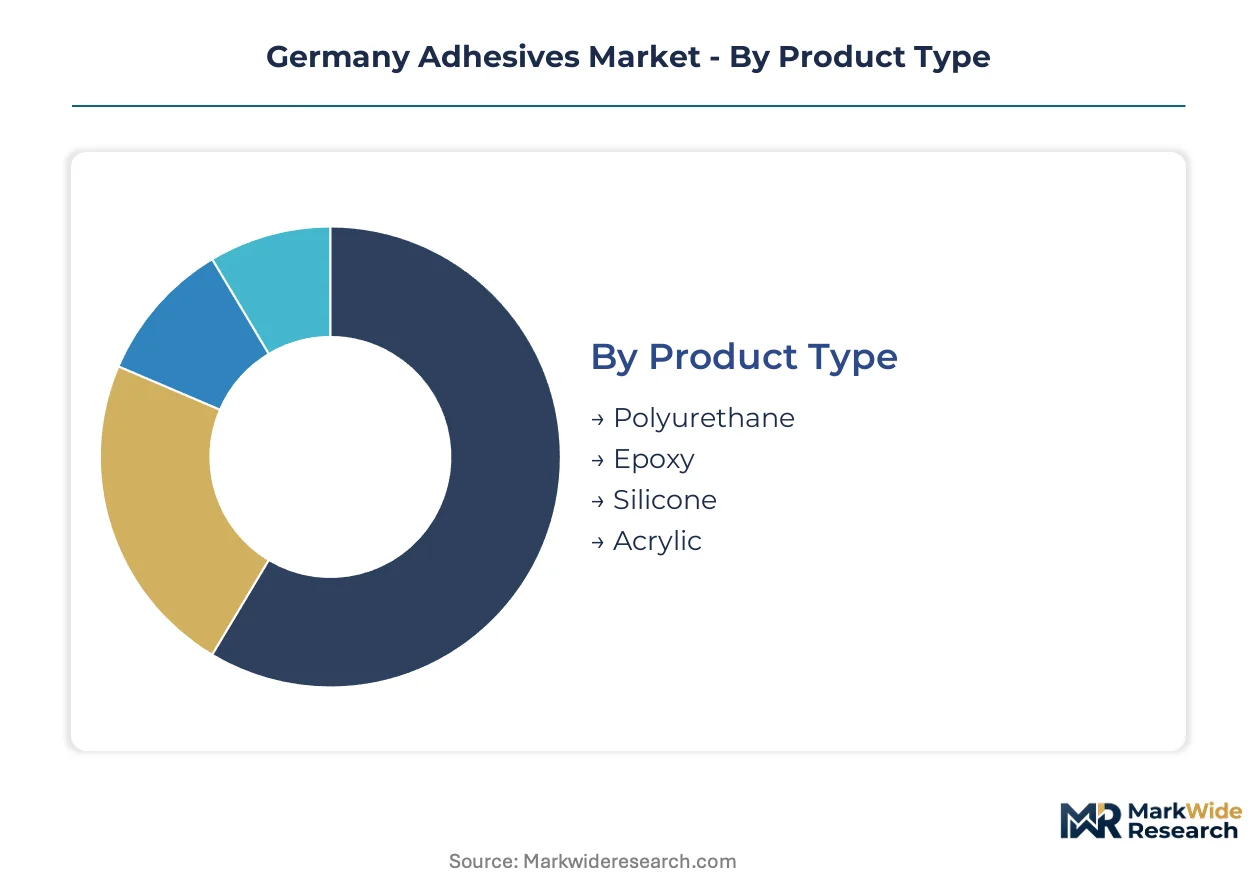
Segmentation in the Germany adhesives market reveals how formulation chemistry, application requirements, and regulatory pressure intersect to create distinct competitive arenas. Each dimension carries different margin profiles, technical service intensity, and exposure to EU REACH compliance timelines.
Product Type:
Polyurethane and epoxy systems command extended sales cycles due to qualification protocols, while acrylic platforms turn inventory fastest through standardized packaging grades.
- Polyurethane:Moisture-curing and two-component systems dominate structural bonding in Baden-Württemberg automotive assembly. Cell-to-pack battery applications in Stuttgart OEM plants are compressing cure-time specifications while demanding enhanced thermal conductivity. KBA enforcement of isocyanate exposure limits is forcing reformulation toward low-monomer content variants.
- Epoxy:High-performance structural grades achieve shear strengths exceeding 30 MPa for wind turbine blade bonding in northern Germany. ECHA's 2023 restriction proposal on aromatic amine curing agents is redirecting formulation toward aliphatic alternatives with modified pot-life characteristics.
- Silicone:RTV and heat-cure grades serve construction glazing and electronics potting across the Rhine-Ruhr corridor.
- Acrylic:Water-borne emulsions and UV-curable systems lead packaging adhesive consumption in Bavaria.
Acrylic anchors the volume base while polyurethane gains share at the steepest rate.
Application:
Construction and automotive applications absorb the highest technical service overhead, whereas packaging lines run with minimal formulation support.
- Construction:Structural glazing and cladding adhesives require BIS-equivalent conformity assessment through Germany's national standards body. Load-bearing certification cycles now extend to 18 months, compressing product refresh rates. Infrastructure rehabilitation projects across federal states sustain demand for high-modulus silicone and hybrid polymer systems.
- Automotive:Lightweighting mandates from Munich and Sindelfingen OEMs are eliminating mechanical fasteners in favor of bonded aluminum-steel joints. BMW and Mercedes-Benz operations have retrofitted assembly lines with UV-LED curing stations to accelerate bonding cycle times.
- Packaging:Corrugated board and consumer goods applications in the Rhine-Ruhr metropolitan region favor hot melt speed-of-set advantages.
- Woodworking:Bavarian furniture manufacturers are adopting reactive hot-melt polyurethane to eliminate clamping infrastructure.
Construction absorbs the deepest technical service investment while automotive shows the steepest technology upgrade trajectory.
End User:
Manufacturing accounts drive formulation co-development relationships, but DIY channels turn standardized product most rapidly.
- Manufacturing:Midsize industrial accounts in the Rhine-Ruhr corridor now demand on-site rheology optimization and substrate pretreatment validation. Procurement authority is concentrating with suppliers maintaining regional application laboratories.
- DIY:Retail-grade cyanoacrylate and epoxy syringe packs serve home repair applications with minimal technical support requirements.
- Aerospace:Frankfurt and Hamburg maintenance operations specify certified structural films for composite repair.
- Electronics:Nuremberg semiconductor packaging operations require dielectric adhesives with precision dispensing compatibility. DELO Industrie Klebstoffe maintains defensible positioning through localized technical coverage.
Manufacturing commands the premium pricing tier while electronics climbs fastest on miniaturization demand.
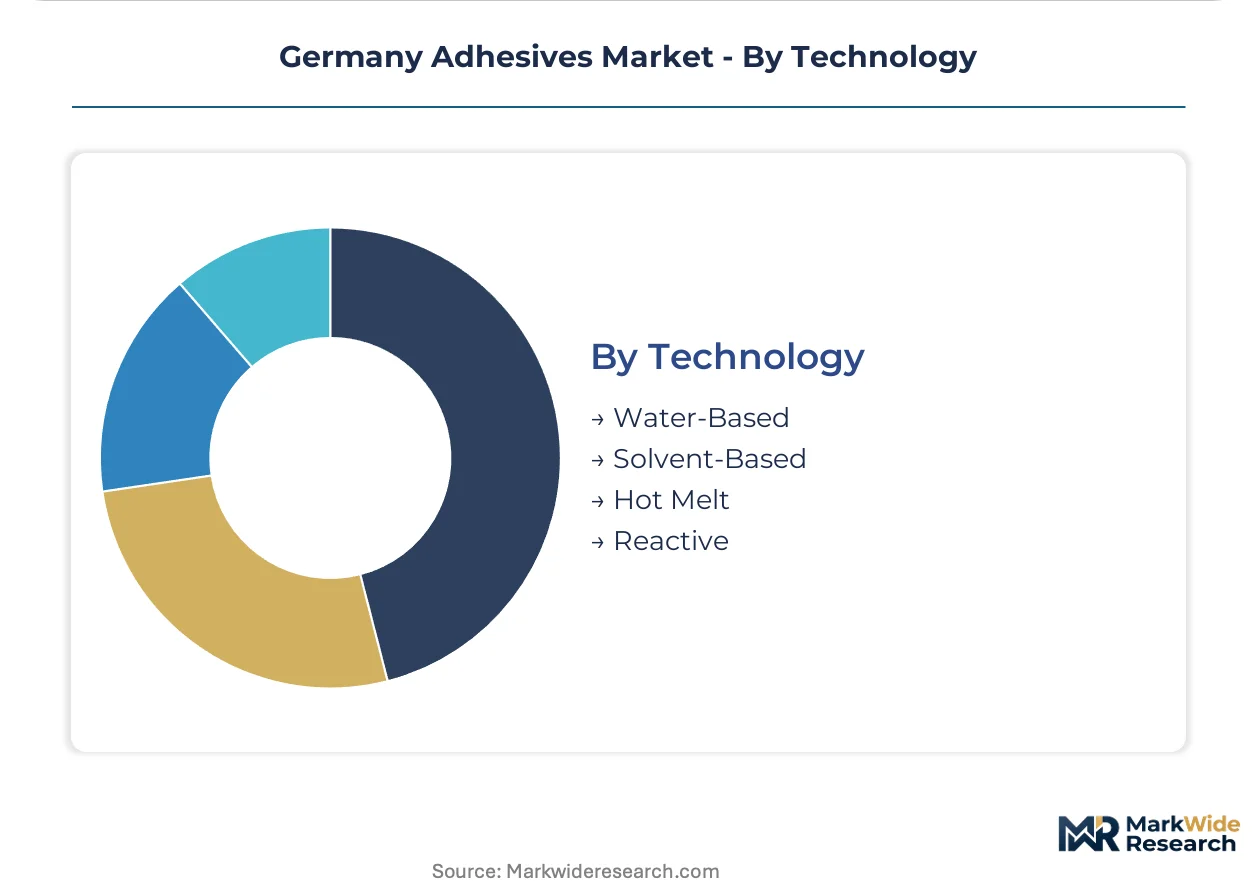
Technology:
Water-based platforms face the steepest regulatory pressure cycle, while reactive systems carry the longest validation timelines.
- Water-Based:Acrylic and polyurethane emulsions lead packaging and woodworking applications where EU REACH VOC thresholds are most stringent. Federal Environment Agency implementation of emission regulations is accelerating solvent displacement.
- Solvent-Based:Remaining volumes concentrate in specialty tape and label applications where rapid tack development remains irreplaceable.
- Hot Melt:EVA and metallocene polyolefin systems sustain corrugated board operations through speed-of-set advantages on high-speed production lines.
- Reactive:Moisture-curing polyurethane and two-component epoxy systems capture disproportionate margin pools in automotive and electronics segments where thermal cycling resistance commands premium positioning.
Water-based technology anchors the volume base while reactive platforms expand most quickly on performance premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan region anchors Germany's adhesive demand through its dense concentration of packaging lines and automotive component plants served by the Dortmund-Ems Canal logistics corridor.
Bavaria
Furniture manufacturers in Nuremberg and Munich are displacing mechanical fasteners with reactive hot-melt polyurethane systems that eliminate clamping infrastructure. The Federal Environment Agency enforces stringent VOC thresholds under EU REACH Annex XVII, accelerating solvent displacement in woodworking applications. High-speed corrugated board operations along the Main-Danube waterway sustain hot melt consumption volumes.
Baden-Württemberg
Stuttgart OEM plants are compressing bonding cycle times for aluminum-steel joints in electric vehicle architectures. KBA enforcement of isocyanate exposure limits is forcing reformulation toward low-monomer polyurethane variants. Cell-to-pack battery assembly lines in Sindelfingen require thermally conductive structural adhesives with dielectric isolation properties.
North Rhine-Westphalia
The Rhine-Ruhr corridor concentrates Germany's packaging adhesive demand through consumer goods manufacturing clusters. EU Green Deal taxonomy criteria are reshaping capital access for facilities demonstrating carbon-intensity reductions in curing energy consumption. Düsseldorf headquarters operations anchor premium automotive supply relationships through direct technical service partnerships.
Lower Saxony
Wind turbine blade manufacturing in the northern coastal region drives high-performance epoxy consumption for structural bonding applications. ECHA's 2023 restriction proposal on aromatic amine curing agents is redirecting formulation toward aliphatic alternatives with modified pot-life characteristics. Hanover-area industrial accounts demand on-site rheology optimization and substrate pretreatment validation.
Hesse
Frankfurt's aerospace maintenance operations specify certified structural adhesive films for composite repair protocols. The F-Gas Regulation restricts fluorinated compounds in specialty adhesive chemistries used in electronics potting applications. Precision electronics packaging demand in the Rhine-Main metropolitan region climbs on semiconductor miniaturization requirements.
Germany Adhesives Market Competitive Landscape
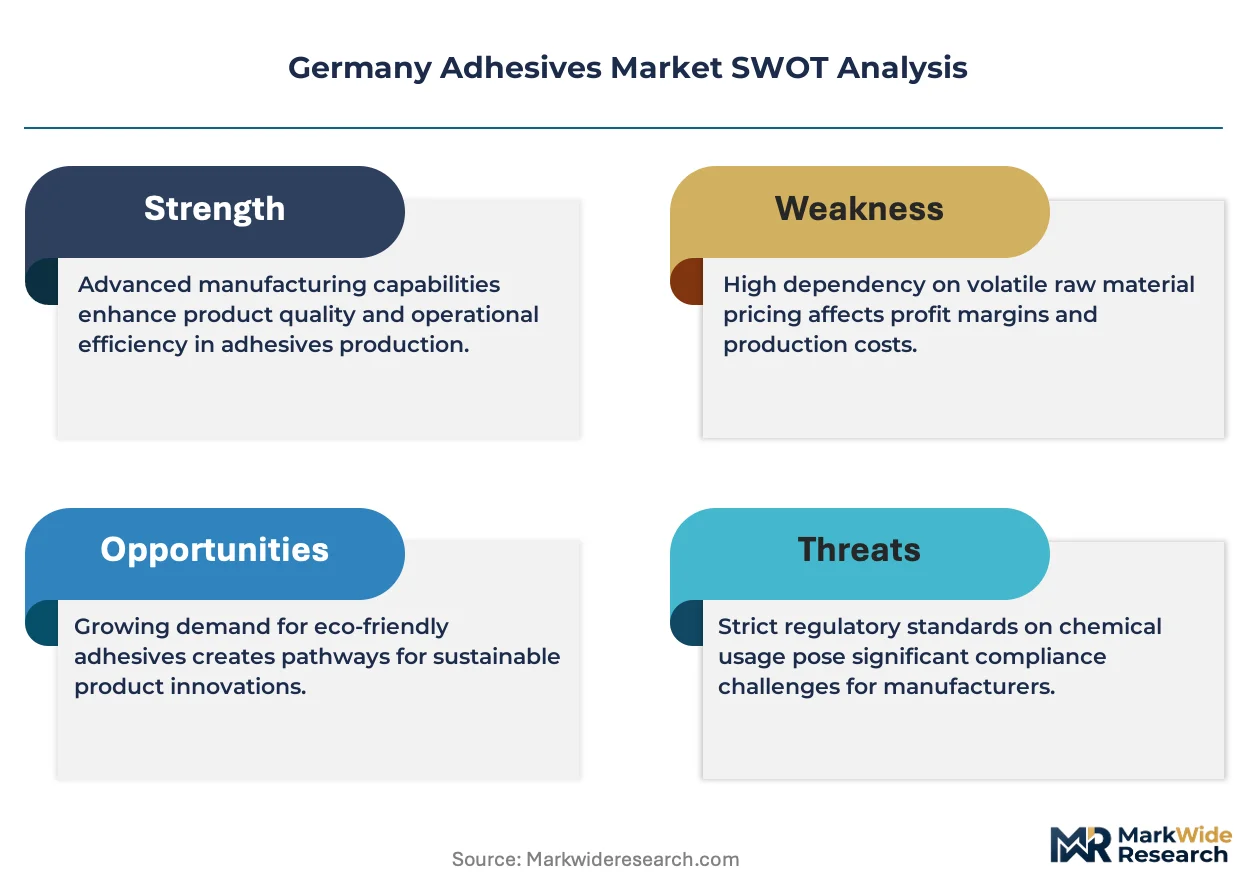
On the supply side, the industry is consolidating around formulation houses maintaining regional application laboratories and direct technical service capabilities. Düsseldorf and Stuttgart anchor distinct competitive clusters serving automotive OEMs versus construction contractors. Three strategic archetypes dominate: diversified chemical conglomerates with adhesive divisions, construction-focused specialty chemical producers, and precision electronics adhesive specialists. Capacity expansion in moisture-curing polyurethane platforms and strategic partnerships for UV-LED curing technology represent the dominant competitive vectors reshaping market positioning.
Within the diversified conglomerate tier, Henkel AG & Co. KGaA and Dow exemplify scale-driven players leveraging integrated resin production and global formulation networks. Sika AG occupies a position exemplifying construction-focused specialty chemical producers with infrastructure rehabilitation project dominance. DELO Industrie Klebstoffe GmbH & Co. KGaA represents the precision electronics specialist archetype, anchoring defensible positioning through semiconductor packaging applications. These three entities collectively illustrate how geographic proximity to Stuttgart and Düsseldorf industrial clusters, combined with regulatory compliance capabilities under EU REACH and KBA frameworks, determines procurement authority concentration in German adhesive markets.
| Leading Market Players |
|---|
| H.B. Fuller Company |
| Dow |
| Henkel AG & Co. KGaA |
| Avery Dennison Corporation |
| DELO Industrie Klebstoffe GmbH & Co. KGaA |
| Sika AG |
| Arkema Group |
| Jowat SE |
| 3M |
| Others |
Supply & Pricing Matrix
Isocyanate supply concentration across three European producers determines both margin compression patterns in polyurethane tiers and the just-in-time logistics architecture that German formulators must maintain. This feedstock dependency creates pricing power asymmetries where raw material volatility transmits directly to contract renegotiation cycles in the Rhine-Ruhr industrial corridor.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment scale. Premium structural adhesives for automotive OEMs in Stuttgart command positioning through KBA load-bearing certification and embedded technical service. Cost compression in standard-grade packaging adhesives intensifies because water-based acrylic platforms face EU REACH VOC threshold acceleration. DIY retail channels exhibit highest price sensitivity, while cell-to-pack battery manufacturers in Sindelfingen prioritize thermal conductivity specifications over unit cost.
Supply Chain Analysis
Tariff exposure between Germany and China for epoxy resin precursors dominates supply chain risk assessment for electronics packaging formulators. Feedstock sourcing draws from Belgium, the Netherlands, and domestic petrochemical complexes along the Rhine. MDI and propylene oxide dependencies create single-source vulnerability during force majeure events at major European producers. Distribution runs through specialty chemical distributors with bonded substrate testing capabilities, marginalizing transactional intermediaries lacking technical service infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical fastening substitution in automotive lightweighting programs threatens incumbent adhesive suppliers if cure-time and thermal resistance specifications fail to advance. Incumbents must navigate this displacement risk while defending margin pools in qualified structural bonding applications.
For Market Incumbents: Insulate qualified supplier status with Stuttgart and Wolfsburg OEMs through backward integration into low-monomer polyurethane resin production. Deepen application laboratory presence in Bavaria to capture reactive hot-melt conversion in furniture manufacturing. Defend against emerging UV-LED curing specialists by retrofitting existing thermal oven infrastructure at customer sites.
For New Entrants and Emerging Players: Build out precision electronics adhesive capabilities targeting Thuringia's underpenetrated manufacturing clusters where DELO Industrie Klebstoffe lacks localized coverage. Establish technical service partnerships with midsize industrial accounts in Saxony facing adhesive process engineer scarcity. Pursue go-to-market positioning through AI-driven formulation optimization that compresses new product development timelines.
For Investors and Strategic Acquirers: EU Green Deal taxonomy alignment reshapes the acquisition landscape by privileging facilities with demonstrated carbon-intensity reductions in curing energy consumption. Long-term viability centers on formulators with UV-LED adoption trajectories and construction adhesive certification capabilities under extended CE marking timelines. Watch for KBA enforcement patterns on isocyanate exposure limits as inflection indicators for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Monomer Polyurethane Resins | Captures margin pools threatened by MDI price volatility and KBA exposure limit enforcement. |
| UV-LED Curing Technology Partnership | Enables BMW and Mercedes-Benz assembly line retrofits while eliminating thermal damage risks. |
| Regional Application Laboratory Expansion | Concentrates procurement authority with formulation houses serving midsize Rhine-Ruhr accounts. |
| AI-Driven Formulation Optimization | Compresses development timelines from months to weeks for electronics miniaturization adhesives. |
| EU Green Deal Taxonomy Certification | Determines capital access for facility upgrades through carbon-intensity reduction documentation. |
Research Methodology
Initial hypotheses were tested against primary input from adhesive plant managers, procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors, then refined through secondary validation. Primary fieldwork combined structured interviews with downstream manufacturing accounts and upstream resin suppliers. Secondary sources included customs and trade data, Cefic sector reports, SEC 10-K filings from diversified chemical conglomerates, and KBA regulatory enforcement documentation. Bottom-up volume estimates from end-use application segments were triangulated against top-down market sizing from production capacity analysis.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation modeled across chemistry type, application vertical, technology platform, and regional production cluster. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trends. Forecast inputs incorporated EU REACH Annex XVII compliance timelines, ECHA restriction proposals on aromatic amine curing agents, and F-Gas Regulation implementation patterns.
Practitioners should monitor petrochemical feedstock volatility, isocyanate producer force majeure events, and CE marking timeline extensions for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Tobacco and Cigarette Adhesives Market
Adhesives & Sealants
Co-Polymer Sealants Market
Adhesives & Sealants
Global Ceramic Adhesives Market
Adhesives & Sealants
Europe Hot-Melt Adhesives Market
Adhesives & Sealants
United Kingdom Hot-Melt Adhesives Market
Adhesives & Sealants
South America Adhesives and Sealants Market
Adhesives & Sealants
Global Dimer Acid Market
Adhesives & Sealants
Global EVA Adhesives Market
Adhesives & Sealants
Anaerobic Adhesives Market
Adhesives & Sealants
South America Sealants Market
Adhesives & Sealants
Bio-Based Adhesive and Sealant Market
Adhesives & Sealants
Aviation Adhesives and Sealants Market
Adhesives & Sealants
Global Elastic Adhesive Market
Adhesives & Sealants
Hybrid Silane-Terminated Polymer Adhesives for EV Battery Pack Assembly Market
Adhesives & Sealants
South America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Dimethylaminoethyl Acrylate Market