
 Global Polymer Stabilizer Market | 2026-2036
Global Polymer Stabilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polymer Stabilizer Market Foresight
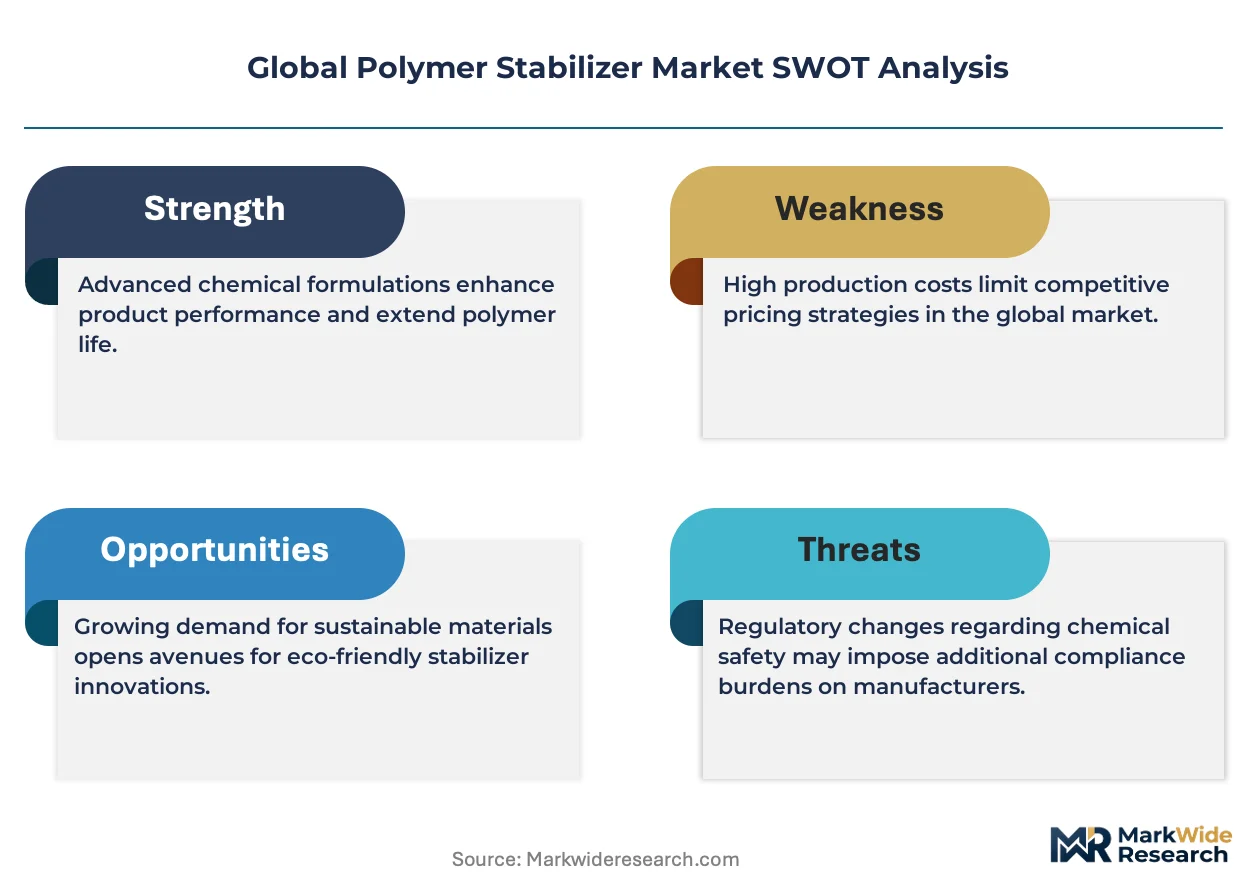
EU REACH restrictions on cadmium and lead-based heat stabilizers is hardening demand for calcium-organic and mixed-metal alternatives across European compounding operations. BASF SE leverages its integrated antioxidants portfolio to supply automotive OEMs transitioning to phthalate-free interior specifications. Clariant AG anchors its position through specialty masterbatch formulations that simplify downstream processing for packaging converters. SONGWON competes aggressively in Asia through backward integration into key phenolic and phosphite intermediate chemistries.
Polymer stabilizers are chemical additives, typically phenolic antioxidants, hindered amine light stabilizers, or organometallic heat stabilizers, dosed at 0.1-2.0 wt% to inhibit thermal oxidation and photodegradation during processing and end-use. These compounds preserve mechanical properties, color stability, and service life in polyolefins, PVC, and engineering plastics exposed to shear heat, UV radiation, or flame sources. Antioxidants command the deepest margin pools due to irreplaceable performance in high-temperature extrusion and long-duration automotive underhood applications. UV stabilizers represent the fastest-expanding category, driven by agricultural film durability mandates and exterior construction panel warranties. Masterbatch formulations are displacing liquid additives in high-volume packaging lines where dust control and dosing precision determine compounder economics.
The US EPA evaluates stabilizer chemistries under TSCA Section 5 for new substance notifications, while China's MEE enforces GB standards limiting volatile organic compound emissions from plastic processing facilities. Japan's METI classifies certain organotin heat stabilizers as Class I Specified Chemical Substances, accelerating substitution timelines for Japanese PVC compounders. Stakeholders must monitor regulatory divergence between jurisdictions, as divergent substance restrictions will fragment formulation portfolios and complicate cross-border supply qualifications.
Market Dynamics
REACH restrictions on cadmium and lead-based heat stabilizers are forcing European compounders to reformulate entire additive portfolios around calcium-zinc and organic alternatives, compressing formulation cycles and redirecting R&D budgets toward regulatory compliance rather than performance enhancement.
Growth Catalysts
- Automotive Lightweighting Mandates:Germany and Japan OEMs are accelerating consumption of high-performance heat stabilizers in underhood plastics and interior trim to meet fuel efficiency targets.
- REACH Phase-Out Deadlines:ECHA restrictions on heavy-metal additives are redirecting formulation investments toward calcium-organic heat stabilizers across European PVC compounding operations.
- China Capacity Expansion:Domestic polymer production growth is outpacing global averages, concentrating demand for antioxidants and UV stabilizers in Shanghai and Guangdong clusters.
Market Restraints
- Phenolic Intermediate Volatility:Feedstock cost swings for phosphite and hindered amine precursors squeeze compounder margins during contract renegotiations.
- Organotin Supply Concentration:Japanese METI classification of certain tin stabilizers as Class I Specified Chemical Substances has fragmented supplier qualification timelines.
- Technical Substitution Limits:Calcium-zinc alternatives fail to match lead-based thermal stability in high-shear PVC pipe extrusion above 200°C.
Strategic Opportunities
- India Packaging Conversion:FSSAI durability mandates for agricultural films create pull for hindered amine light stabilizers in Maharashtra and Gujarat processing corridors.
- Masterbatch Channel Innovation:Dust-free solid dosing formats are displacing liquid additive systems in high-volume Chinese flexible packaging lines.
- EU Green Deal Alignment:CSRD reporting requirements favor stabilizer suppliers offering verified carbon footprint data for Scope 3 emissions reduction.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in metal-organic coordination chemistry for heat stabilizer synthesis is concentrating among retiring specialists in Ludwigshafen and Tokyo.
- Cross-Border Qualification Friction:Divergent GB standards, REACH annexes, and TSCA Section 5 notification timelines force parallel testing programs for multi-territory compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polymer Stabilizer Market |
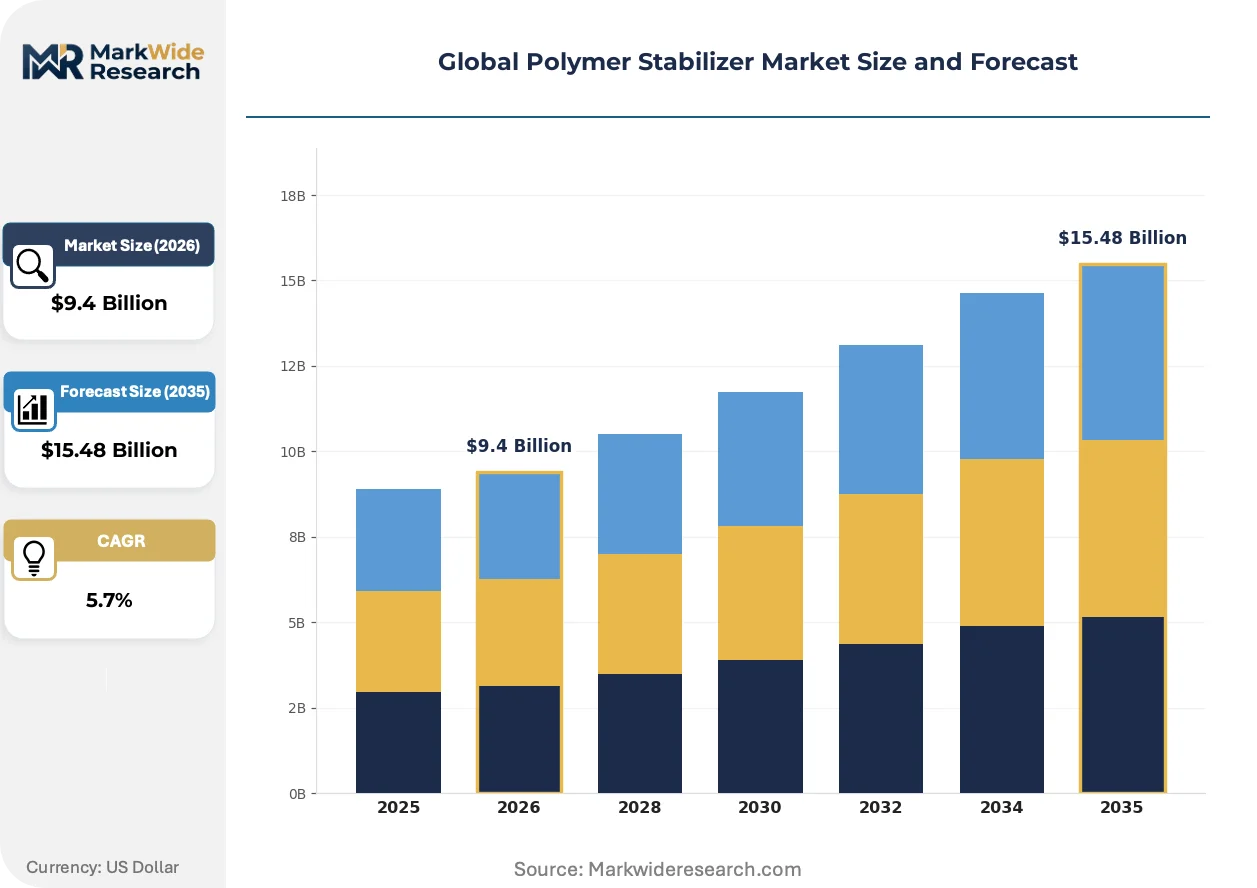
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $15.48 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Stabilizers, UV Stabilizers, Antioxidants, Fire Retardants Application: Automotive, Construction, Packaging, Electronics End User: Manufacturers, OEMs, Distributors, Retailers Formulation: Masterbatches, Liquid Additives, Compounds, Concentrates |
| Companies Covered | BASF SE, Clariant AG, SONGWON, Evonik Industries AG, Solvay, Arkema SA, SK Capital Partners, Adeka Corporation, Baerlocher GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polymer Stabilizer Market Shifts & Advancements
Reactive antioxidant technologies and bio-based hindered amine architectures are compressing traditional additive replacement cycles while regulatory pressure on heavy-metal chemistries accelerates portfolio turnover across formulation houses.
Polymeric hindered amine light stabilizers with graftable reactive groups are rewriting durability standards in agricultural film applications. European mulch film producers are adopting these architectures to meet EN 13655 biodegradability timelines without sacrificing UV resistance. The technology is compressing warranty periods for conventional low-molecular-weight stabilizer suppliers.
Japan's METI designation of specific organotin heat stabilizers as Class I Specified Chemical Substances is accelerating substitution timelines for domestic PVC compounders. Japanese pipe and profile extruders must complete formulation transitions by mandatory phase-out windows. The regulation is elevating calcium-zinc and rare-earth alternatives in building and construction applications.
Automotive OEMs in Germany and Japan are unbundling stabilizer procurement from resin supply agreements, establishing direct qualification relationships with additive houses. Tier-1 interior component suppliers now negotiate separate antioxidant and UV stabilizer contracts. This pattern is most visible in seating and dashboard programs where phthalate-free specifications demand dedicated formulation oversight.
Global Polymer Stabilizer Market Segmentation
Polymer stabilizer procurement splits across technical specifications, regulatory compliance tiers, and downstream processing formats. Formulation houses configure additive portfolios around REACH annex restrictions, automotive OEM material declarations, and packaging converter dosing infrastructure.
Product Type:
REACH annex XVII cadmium and lead restrictions have recategorized approval burdens across European heat stabilizer qualifications, while automotive OEM material declarations impose parallel substance disclosure requirements on antioxidant and UV stabilizer supply chains.
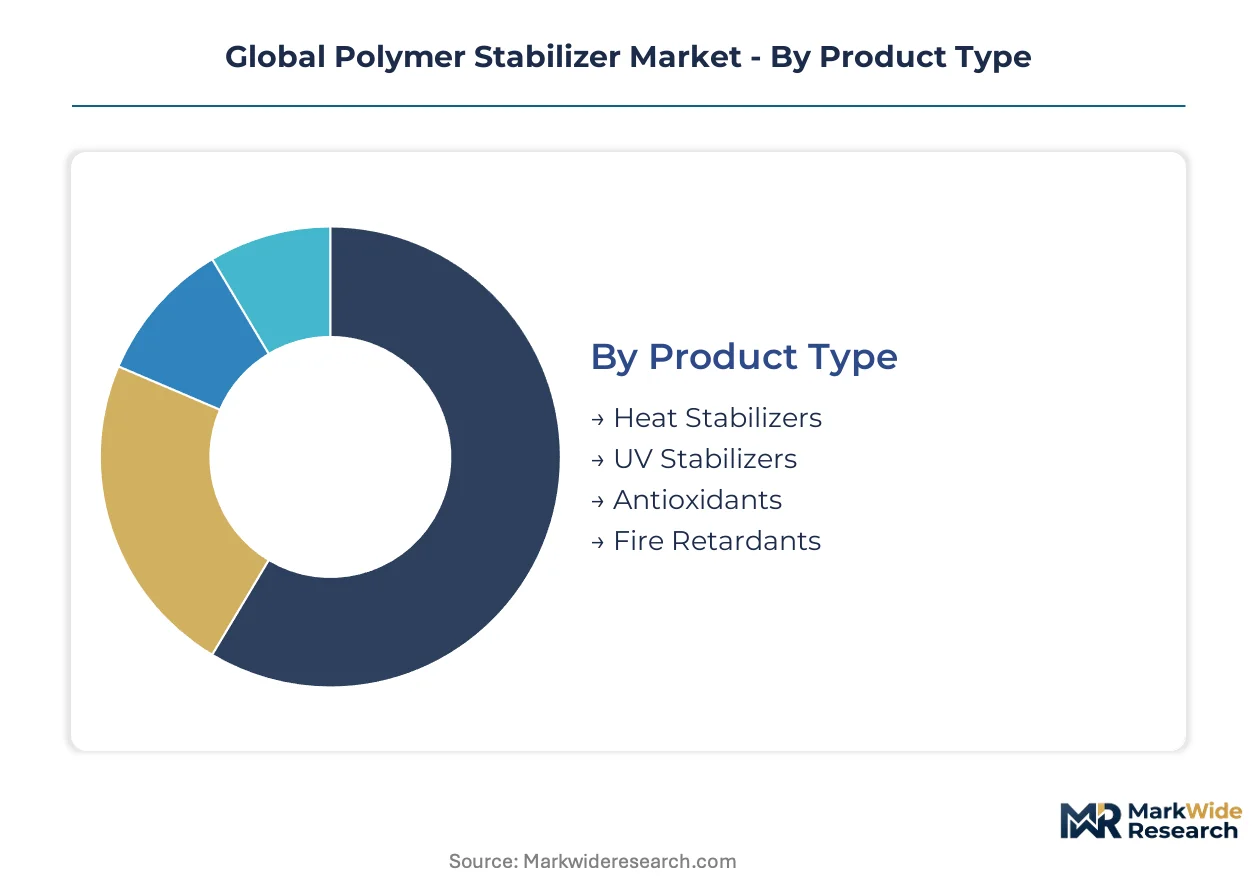
- Heat Stabilizers:Organometallic compounds—calcium-zinc, organotin, and rare-earth variants—preserve thermal integrity in PVC and engineering plastics during high-shear extrusion above 180°C. German automotive underhood specifications and Japanese METI Class I substance designations are compressing qualification timelines for tin-based chemistries. Leading the category by volume: Heat Stabilizers. Growing fastest: UV Stabilizers.
- UV Stabilizers:Hindered amine light stabilizers and UV absorbers inhibit photodegradation in agricultural films, exterior construction panels, and automotive clearcoats. Demand concentrates in China’s Shandong agricultural film corridor and Gujarat’s polymer processing clusters under FSSAI durability mandates.
- Antioxidants:Phenolic and phosphite architectures interrupt thermal oxidation chains in polyolefin extrusion and long-duration automotive applications.
- Fire Retardants:Halogenated and intumescent systems address flammability specifications in electronics housings and building materials.
Antioxidants command the deepest margin pools due to irreplaceable performance in high-temperature processing. UV stabilizers are climbing the fastest on agricultural film warranty extensions and construction panel durability mandates.
Application:
End-use concentration determines formulation complexity tiers, with automotive and construction applications demanding the most intensive substance tracking and performance certification documentation.
- Automotive:Underhood plastics, interior trim, and seating foams require heat and UV stabilization meeting OEM phthalate-free specifications and fuel efficiency lightweighting targets. German and Japanese OEMs now unbundle stabilizer procurement from resin supply agreements, establishing direct additive house relationships for seating and dashboard programs.
- Construction:PVC pipe, profile extrusion, and exterior cladding rely on calcium-zinc and rare-earth heat stabilizers as lead alternatives, though thermal performance gaps persist above 200°C shear conditions.
- Packaging:Flexible film and rigid container converters prioritize dust-free masterbatch formats for dosing precision and workplace exposure control.
- Electronics:Flame retardant and thermal stabilization requirements for connectors and housings track IEC and UL certification pathways.
Construction generates the highest stabilizer consumption by tonnage. Automotive applications are expanding most quickly on lightweighting program acceleration.
End User:
Procurement authority fragmentation creates divergent technical engagement models, with OEM direct qualification programs displacing traditional resin-supplier-mediated additive selection.
- Manufacturers:Polymer producers and compounders specify stabilizer packages during resin synthesis or compounding operations, with China’s domestic capacity expansion concentrating procurement authority in Shanghai and Guangdong chemical clusters.
- OEMs:Automotive and electronics original equipment manufacturers increasingly mandate approved substance lists and direct additive supplier qualifications, bypassing resin supplier formulation control.
- Distributors:Regional chemical distributors manage inventory and technical service for mid-volume compounders lacking direct additive house relationships.
- Retailers:Limited direct engagement; primarily indirect through private-label packaging specifications.
Manufacturers dominate procurement volume. OEM direct engagement is gaining share fastest on material declaration and sustainability traceability requirements.
Formulation:
Physical format selection hinges on dosing precision, dust exposure limits, and processing line integration costs across high-volume packaging and specialized compounding operations.
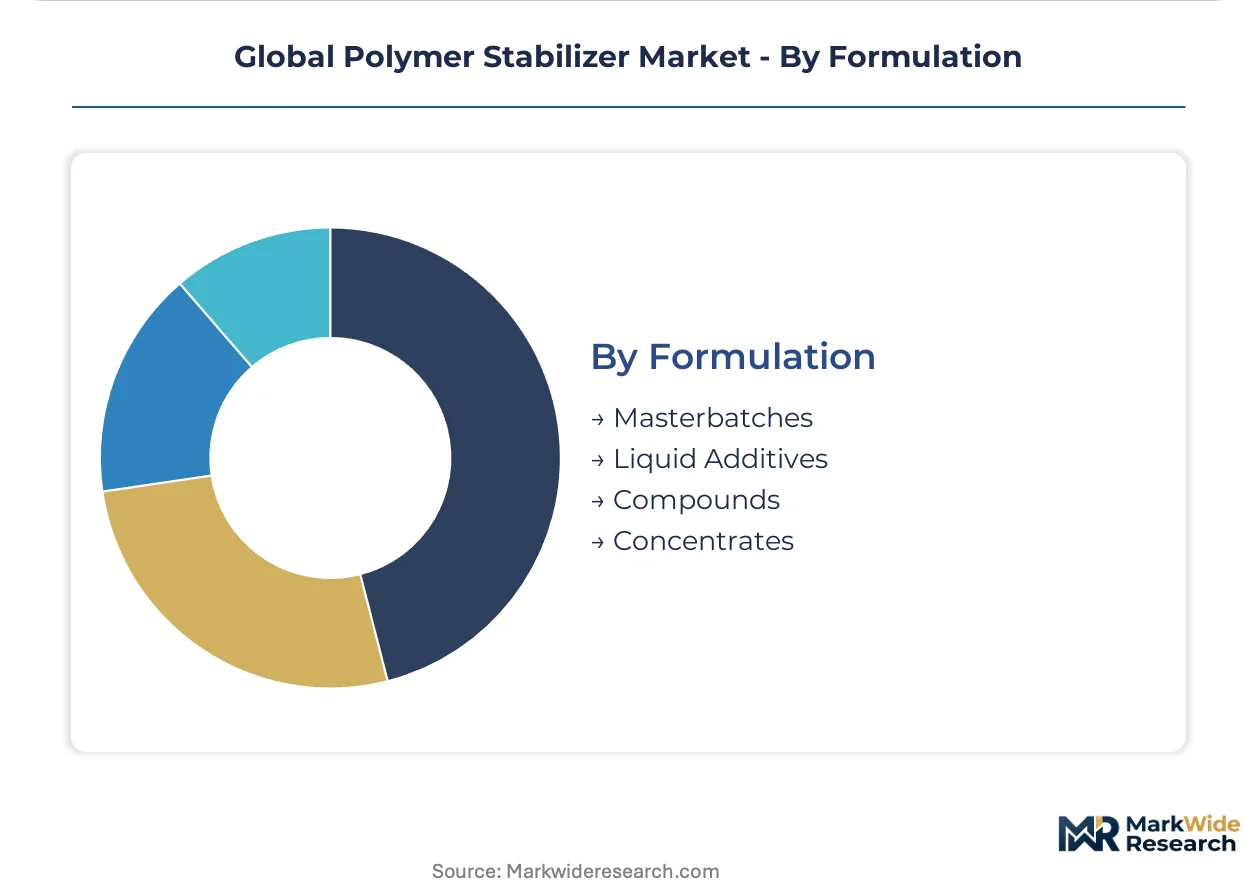
- Masterbatches:Solid, dust-free additive concentrates disperse uniformly in polyolefin carriers, simplifying dosing precision and workplace exposure control in high-speed Chinese flexible packaging lines.
- Liquid Additives:Pumpable systems suit continuous extrusion operations with liquid dosing infrastructure, though masterbatch displacement is accelerating in dust-sensitive environments.
- Compounds:Pre-stabilized resin systems reduce downstream formulation burden for processors lacking technical compounding capabilities.
- Concentrates:High-loading additive packages for dilution at point of use, common in custom compounding and specialized performance applications.
Masterbatches lead formulation volume on packaging line conversion. Concentrates are expanding most quickly in custom compounding and specialized durability applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of base polymers yet consumes stabilizers at rates exceeding domestic supply, while Germany and Japan drive specification intensity through automotive OEM direct qualification programs. This production-consumption asymmetry creates divergent procurement dynamics across major chemical clusters.
China
Shanghai and Guangdong chemical corridors concentrate domestic polymer capacity expansion, outpacing global averages for polyethylene and polypropylene output. MEE enforcement of GB standards limiting volatile organic compound emissions from plastic processing facilities forces compounders to upgrade stabilizer dosing infrastructure. Shandong's agricultural film belt generates concentrated pull for hindered amine light stabilizers under provincial durability mandates.
Germany
Automotive lightweighting programs in Bavaria and Baden-Württemberg accelerate consumption of high-performance heat stabilizers for underhood plastics and interior trim. ECHA REACH restrictions on cadmium and lead-based additives redirect formulation investments toward calcium-organic alternatives across Ludwigshafen compounding operations. The KBA maintains strict material declaration protocols for seating and dashboard components.
Japan
METI classification of specific organotin heat stabilizers as Class I Specified Chemical Substances compresses substitution timelines for Kanto and Kansai PVC pipe extruders. Automotive OEMs in Nagoya and Tokyo metro areas unbundle stabilizer procurement from resin supply agreements. Osaka-based compounders face mandatory phase-out windows for legacy heat stabilizer chemistries in building applications.
United States
EPA TSCA Section 5 evaluation timelines for new substance notifications extend qualification cycles for innovative antioxidant architectures. Gulf Coast petrochemical expansion concentrates polymer production capacity, driving stabilizer demand through Houston and Baton Rouge processing nodes. Midwest automotive clusters in Michigan and Ohio specify phthalate-free interior stabilizer packages under NHTSA-influenced material standards.
India
FSSAI durability mandates for agricultural films create demand pull for hindered amine light stabilizers across Maharashtra and Gujarat processing corridors. Domestic polymer production growth lags consumption, forcing reliance on imported stabilizer masterbatches. BIS certification requirements for construction-grade PVC compounds elevate technical barriers for calcium-zinc heat stabilizer formulations in pipe extrusion.
Global Polymer Stabilizer Market Competitive Landscape
The competitive structure tilts toward diversified chemical conglomerates with integrated antioxidant portfolios and specialty additive houses focused on masterbatch formulations. Tier-1 automotive direct qualification programs favor suppliers with REACH-compliant substance tracking and verified carbon footprint data. Three archetypes dominate: integrated petrochemical majors leveraging backward control into phenolic intermediates, regional specialists capturing packaging converter relationships, and technology licensors monetizing reactive stabilizer architectures. Capacity expansion and portfolio diversification toward bio-based alternatives represent the dominant competitive vectors.
Among European-based diversified suppliers, BASF SE and Clariant AG exemplify the integrated archetype through combined material science and formulation capabilities. SONGWON occupies a position within the Asia-Pacific specialist tier, representing regional competitive pressure through captive intermediate supply. These three anchors illustrate how geographic origin and corporate structure shape strategic positioning without guaranteeing segment-specific dominance.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| SONGWON |
| Evonik Industries AG |
| Solvay |
| Arkema SA |
| SK Capital Partners |
| Adeka Corporation |
| Baerlocher GmbH |
| Others |
Supply & Pricing Matrix
Formulation chemist expertise concentration in Ludwigshafen and Tokyo creates labor-cost differentials that widen pricing-tier spreads between premium REACH-compliant stabilizers and economy-grade alternatives.
Pricing Analysis
Margin tightening in standard-grade heat stabilizers reflects phenolic intermediate feedstock volatility squeezing compounder economics during contract renegotiations. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified automotive grades from construction PVC compounds and basic packaging formulations. Price differentiation hinges on certification grade and volume scale, with Tier-1 automotive OEMs least price-sensitive due to phthalate-free specification mandates.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for automotive antioxidant qualifications, bypassing traditional resin-supplier mediation. Supply concentrates in Germany, China, and Japan, with phenolic and phosphite intermediate production anchored in the Rhine-Ruhr corridor and Guangdong chemical clusters. Raw material dependencies draw from cumene derivatives, hindered amine precursors, and rare-earth metal oxides. Single-source vulnerability in organotin alternatives elevates risk as Japanese METI phase-out deadlines compress supplier transition timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reactive antioxidant architectures and bio-based hindered amine chemistries are displacing legacy additive systems as regulatory pressure accelerates portfolio turnover across formulation houses.
For Market Incumbents: Deepen backward integration into phenolic and phosphite intermediates to defend margin position against SONGWON's captive supply advantages in Asia. Prioritize REACH-compliant certification investments for automotive direct qualification programs as German and Japanese OEMs unbundle stabilizer procurement from resin agreements.
For New Entrants and Emerging Players: Reactive stabilizer technology with graftable functional groups offers entry wedge into agricultural film durability segments where EN 13655 biodegradability timelines create specification gaps. Target Maharashtra and Gujarat processing corridors under FSSAI mandates with masterbatch format innovations that displace liquid dosing systems.
For Investors and Strategic Acquirers: The window for entry favors specialty additive houses with verified carbon footprint data aligned to EU CSRD Scope 3 reporting requirements. Monitor ECHA REACH annex expansion timelines as inflection indicators for heavy-metal substitution acceleration across European compounding operations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenolic Intermediates | Captive supply of hindered amine precursors insulates BASF and SONGWON from feedstock volatility. |
| Masterbatch Format Innovation | Dust-free solid dosing displaces liquid systems in Shandong agricultural film packaging lines. |
| REACH-Compliant Certification Investment | ECHA cadmium and lead restrictions redirect R&D budgets toward calcium-organic heat stabilizer development. |
| Automotive Direct Qualification Programs | German OEMs in Bavaria now negotiate separate antioxidant contracts for seating and dashboard applications. |
| Bio-Based Hindered Amine Development | Polymeric architectures with graftable groups meet EN 13655 biodegradability without sacrificing UV resistance. |
Research Methodology
Independent corroboration across plant managers at compounding facilities, procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors underwrites the qualitative findings. Primary interviews with downstream processors in Shanghai, Guangdong, and Ludwigshafen chemical clusters combined with secondary validation from customs/trade data, Cefic additive consumption reports, and SEC 10-K filings of listed chemical conglomerates. Bottom-up volume estimates triangulated against top-down market sizing across product type, application, and formulation format dimensions.
Comparable-period anchoring to historical antioxidant and UV stabilizer consumption patterns established baseline growth trajectories across the analysis window. Segmentation modeling incorporated grade tier, end-use industry, packaging format, and regional production hub variables. CAGRs derived from regression analysis of polymer production capacity expansion rates and stabilizer dosing intensity coefficients. Forecast inputs included MEE GB standard enforcement timelines and METI Class I substance phase-out schedules.
Several conditions sit outside the modeled scope, including unannounced ECHA REACH annex amendments and disruptive substitution by non-stabilizer polymer modification technologies. Forecasts reflect documented assumptions about regulatory phase-out adherence and automotive lightweighting program continuity. Practitioners should monitor phenolic intermediate spot price movements and OEM material declaration protocol expansions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Medical Fluoropolymers Market
Polymers & Resins
Polystyrene Market
Polymers & Resins
Global Blow Molding Resins Market
Polymers & Resins
Polylactic Acid Market
Polymers & Resins
Polyvinyl Alcohol (PVA) Market
Polymers & Resins
Vinyl Acetate Homopolymer Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
Thermoplastic Polyurethane (TPU) Market
Polymers & Resins
Expanded Polypropylene (EPP) Foam Market
Polymers & Resins
Flame Retardant Polyester Resins Market
Polymers & Resins
Expanded Thermoplastic Polyurethane Market
Polymers & Resins
Polycaprolactone Polyols Market
Polymers & Resins
Bio-Based Construction Polymers Market
Polymers & Resins
Bio-Based and Synthetic Polyamide Market
Polymers & Resins
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market
Polymers & Resins
Silane-Modified Polymers Market