
 Flexible Foam Market | 2026-2036
Flexible Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Foam Market Intelligence
Asian petrochemical producers is shifting flexible polyol capacity toward specialty grades for automotive and bedding applications. Dow Inc. leverages integrated propylene oxide supply chains across the US Gulf Coast to sustain cost-advantaged TDI feedstock positions. Covestro AG anchors European flexible foam innovation through its Leverkusen technical center, where low-emission formulation platforms compete with Asian imports on certification metrics.
Flexible foam denotes cellular polymer structures with open-cell or semi-open-cell architectures, typically exhibiting densities from 10 to 80 kg per cubic meter and compressive resilience exceeding 60 percent recovery after deformation, manufactured through slabstock continuous pouring or molded reaction injection processes for cushioning, insulation, and energy absorption. Polyurethane foam dominates value generation across furniture and automotive interiors, where margin pools concentrate in customized formulations for OEM seating programs. Memory foam segments within the mattress application are expanding fastest through direct-to-consumer channels, while polyethylene foam in packaging maintains stable demand from electronics logistics networks.
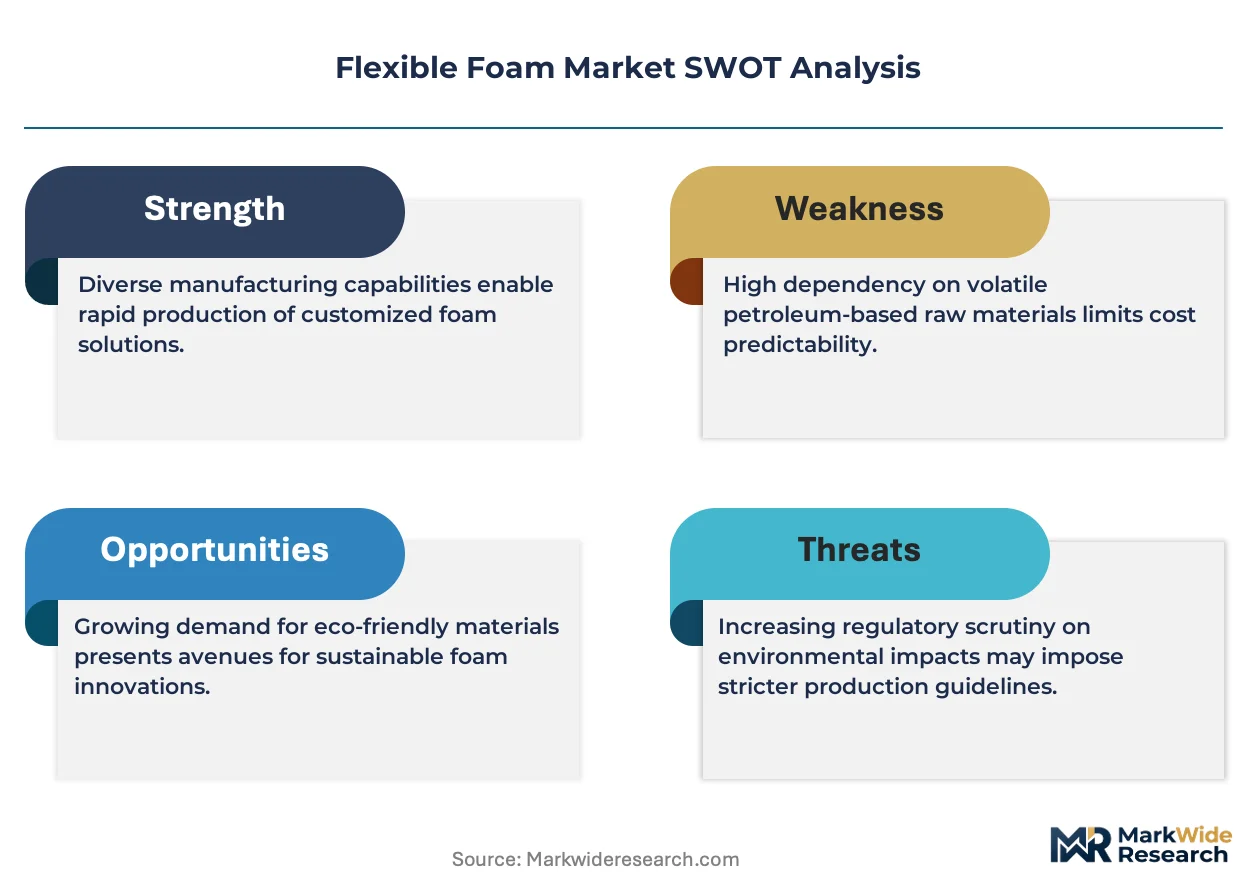
EPA regulations under TSCA Section 6 restrict methylene chloride content in consumer products, while REACH in Europe mandates Substance of Very High Concern disclosures for isocyanate precursors, compelling reformulation investments across formulation houses. OSHA workplace exposure limits for diisocyanates in the United States and analogous frameworks under China's MEE enforce respiratory protection protocols that elevate capital costs for new entrants. Stakeholders must monitor bio-based polyol certification trajectories and regional carbon border adjustments to align capacity planning with evolving compliance thresholds.
Market Dynamics
Automotive seating manufacturers are accelerating polyurethane foam reformulation investments ahead of stricter VOC emissions thresholds under EU REACH and EPA standards, compressing supplier certification timelines and consolidating procurement toward pre-qualified formulation houses.
Growth Catalysts
- REACH Substance of Very High Concern disclosures:European automotive OEMs are mandating low-emission foam certifications for interior programs, pulling demand toward compliant formulation specialists.
- China's bonded foam mattress segment:Domestic e-commerce mattress brands are scaling automated cutting and compression-packaging operations to serve next-day delivery networks.
- Reaction injection molding:Tier-1 seating suppliers are adopting this process for complex contour geometries in electric vehicle cabin designs, reducing scrap rates versus slabstock methods.
Market Restraints
- TDI feedstock concentration:Asian propylene oxide supply chains dominate flexible polyol precursor availability, exposing European formulators to freight cost volatility and carbon border adjustment exposure.
- Methylene chloride restrictions:EPA TSCA Section 6 limits on this blowing agent in consumer products force capital-intensive retooling toward water-blown or CO2-based alternatives.
- Polyethylene foam substitution:Expanded polystyrene and molded pulp formats are capturing share in electronics protective packaging due to lower unit costs and recycling infrastructure.
Strategic Opportunities
- India's mattress modernization:Organized retail and sleep-tech startups in Mumbai and Bangalore are importing foam-rolling equipment to replace traditional coir and cotton bedding.
- Bio-based polyol certification:USDA BioPreferred and analogous European sustainability labels are creating price premiums for foam products with verified renewable content thresholds.
- Direct-to-consumer channel:Mattress-in-a-box brands are bypassing wholesale furniture networks, capturing margin through compressed polyurethane and memory foam logistics.
Industry Challenges
- Diisocyanate respiratory protection compliance:OSHA workplace exposure limits and China's MEE enforcement protocols require automated dosing systems and enclosed mixing vessels, elevating greenfield facility costs.
- Cross-border formulation standardization:Divergent VOC testing methods between EPA, CARB, and EU harmonized standards force parallel certification tracks for global foam suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Foam Market |
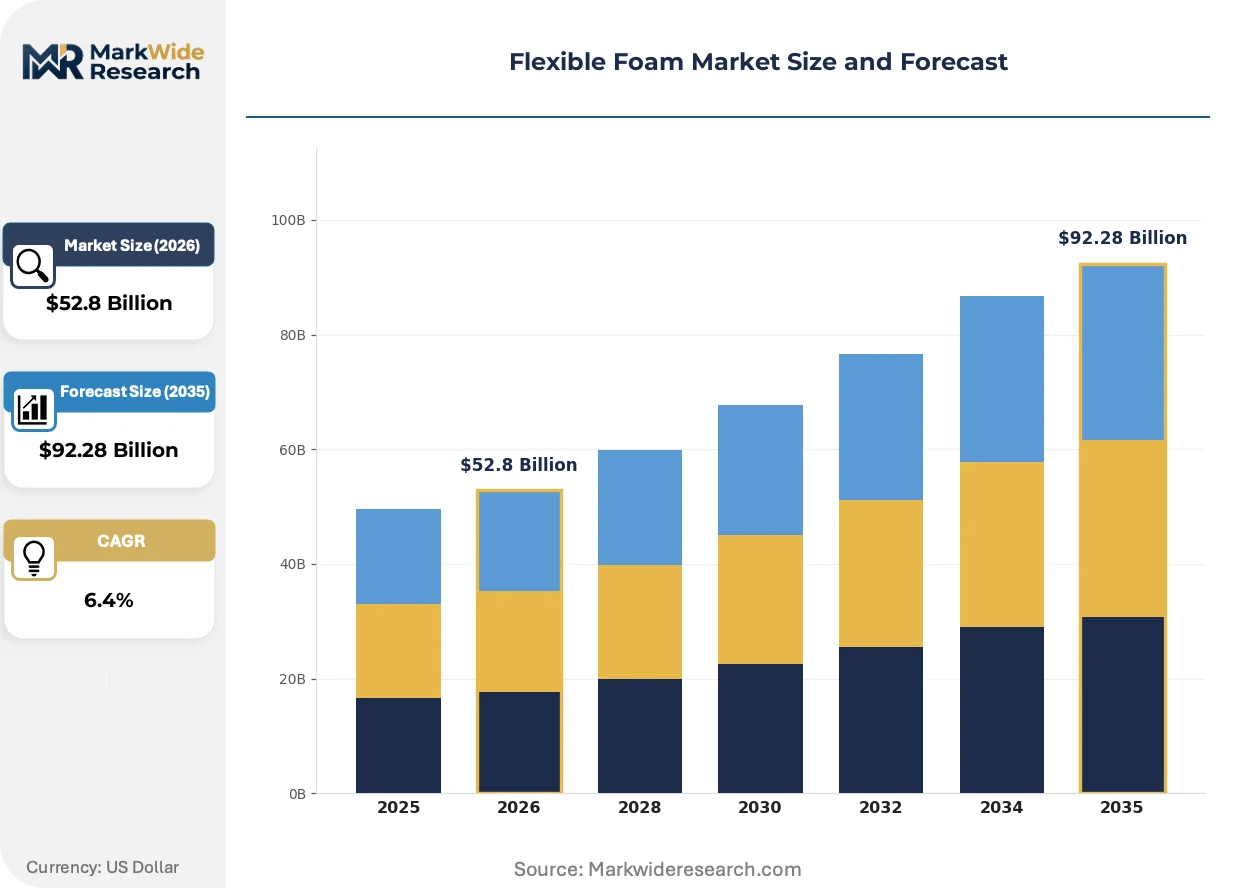
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Foam, Latex Foam, Memory Foam, Polyethylene Foam Application: Furniture, Automotive Interiors, Packaging, Mattresses End User: Residential, Commercial, Industrial, Healthcare Density: Low Density, Medium Density, High Density, Ultra High Density |
| Companies Covered | BASF SE, Covestro AG, Dow Inc., Huntsman International LLC, Recticel, Woodbridge, INOAC Corporation, Armacell, FXI, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Foam Market Strategic Shifts & Innovations
Formulation chemistry and manufacturing processes are converging around emissions reduction, automation, and circular feedstock integration, with competitive advantage shifting toward certified sustainable supply chains rather than commodity scale.
Water-blown polyurethane systems are modularizing factory configurations for small-batch custom seating programs. Tier-1 automotive suppliers in Germany and the United States are retrofitting existing slabstock lines with variable-pressure mixing heads to serve mixed-model electric vehicle production. This modularization is compressing minimum efficient scale thresholds and enabling regional foam houses to compete for OEM qualification.
REACH authorization requirements for isocyanate precursors are tightening disclosure obligations across the European value chain. Formulators must now document Substance of Very High Concern content through finished goods, compelling investments in analytical testing infrastructure. Automotive seating programs face the steepest compliance burden, with some OEMs shifting specification authority to in-house materials engineering teams.
Compressed mattress logistics are displacing traditional wholesale furniture distribution in North America and Western Europe. Direct-to-consumer brands are investing in roll-packing automation and last-mile partnerships, capturing end-user data that informs density and firmness customization. China and India represent the next wave, where urban warehousing density favors vacuum-compressed foam delivery over showroom-based selection.
Flexible Foam Market Segmentation
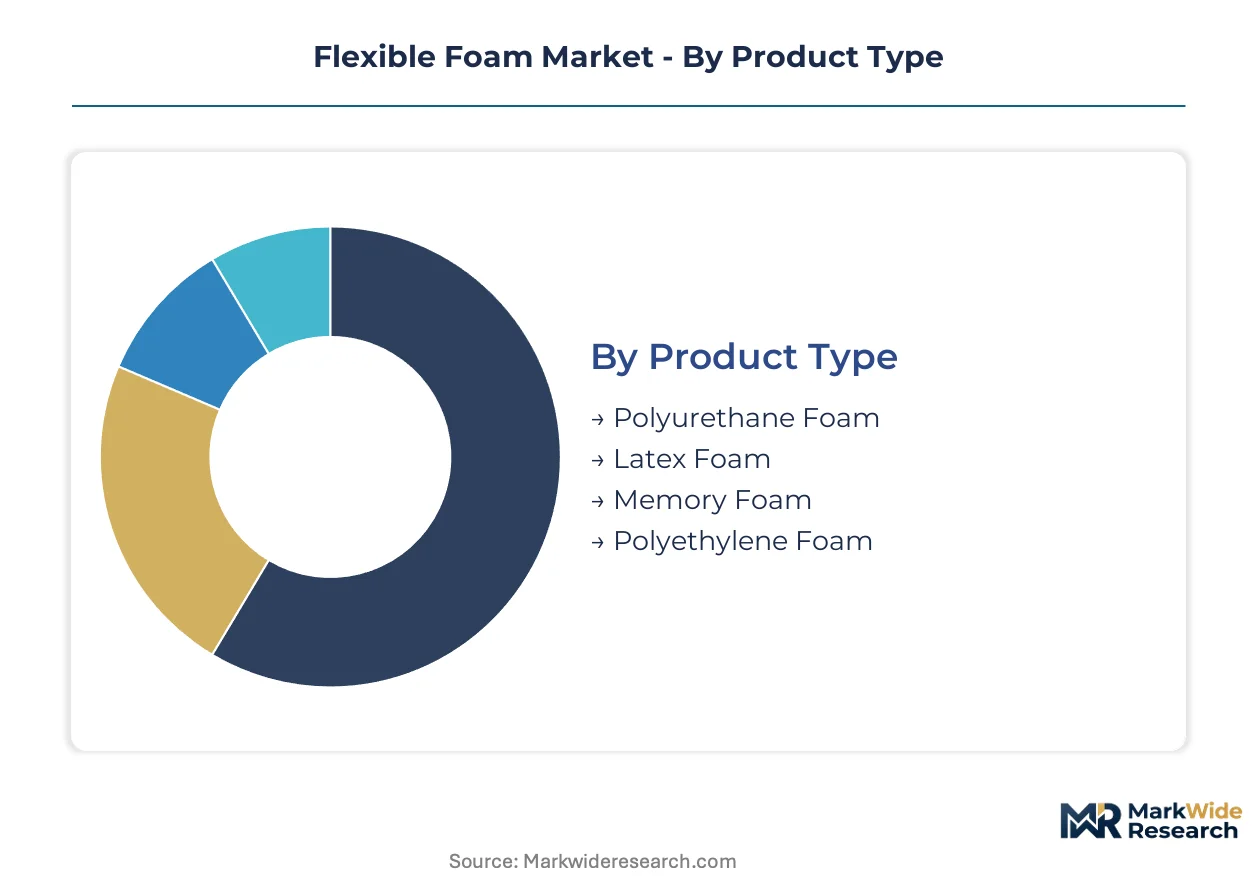
Segmentation in flexible foam markets reveals how formulation chemistry, density specifications, and end-use performance requirements fragment procurement patterns across automotive OEMs, furniture retailers, and industrial packaging networks. Buyers prioritize distinct combinations of compressive resilience, emission certifications, and compression-set recovery depending on whether the application serves seating, bedding, or protective logistics.
Product Type:
Buyers in this category differentiate primarily by reformulation complexity and emission compliance burden, with automotive and healthcare procurement teams demanding low-VOC certifications that commodity grades cannot satisfy.
- Polyurethane Foam:Open-cell structures manufactured through slabstock continuous pouring or molded reaction injection, typically spanning 10-80 kg per cubic meter densities. Automotive seating programs in Germany and the United States concentrate purchasing here, driven by EU REACH Substance of Very High Concern disclosure mandates that compress supplier qualification timelines toward pre-certified formulation houses.
- Memory Foam:Viscoelastic polyurethane variants with slow recovery characteristics and temperature-sensitive compression profiles. Direct-to-consumer mattress brands in North America and Western Europe scale automated roll-packing operations for this segment, capturing margin through compressed logistics that bypass traditional wholesale furniture networks.
- Latex Foam:Natural rubber-derived cellular structures with inherent antimicrobial properties and breathable open-cell architectures. Healthcare seating and premium residential bedding applications specify this grade where bio-based content thresholds create price premiums.
- Polyethylene Foam:Closed-cell structures manufactured through extrusion or cross-linking processes, exhibiting moisture resistance and dimensional stability. Electronics logistics networks in China and South Korea maintain stable demand for protective packaging formats, though expanded polystyrene and molded pulp substitutes capture share on unit cost.
Volume sits with polyurethane foam across slabstock and molded configurations; growth tilts toward memory foam through direct-to-consumer channel expansion.
Application:
Margin concentration varies sharply across this category, with automotive interiors commanding customized formulation premiums while packaging applications compete on unit throughput and freight efficiency.
- Automotive Interiors:Molded seat cushions, headrests, and acoustic insulation panels requiring flame-retardant and low-emission certifications. Tier-1 suppliers in Germany retrofit slabstock lines with variable-pressure mixing heads to serve mixed-model electric vehicle production, reducing scrap rates versus conventional methods.
- Mattresses:Core and comfort layer assemblies spanning bonded foam blocks to viscoelastic toppers. Domestic e-commerce brands in China scale automated cutting and compression-packaging operations to serve next-day delivery networks, displacing showroom-based selection.
- Furniture:Upholstery cushioning for residential and commercial seating applications. Indian organized retailers and sleep-tech startups in Mumbai and Bangalore import foam-rolling equipment to replace traditional coir and cotton bedding, modernizing supply chains.
- Packaging:Protective inserts, corner blocks, and cushioning for electronics and appliance logistics. Water-blown and CO2-based alternatives displace methylene chloride systems following EPA TSCA Section 6 restrictions, elevating capital costs for retooling.
Revenue concentrates in automotive interiors where OEM qualification creates switching costs; expansion accelerates fastest in mattress applications through compressed logistics and channel disintermediation.
End User:
Procurement sophistication diverges across this category, with industrial buyers optimizing for total cost of ownership while residential demand responds to sustainability labeling and channel convenience.
- Residential:Individual consumers purchasing mattresses, upholstered furniture, and DIY cushioning materials. USDA BioPreferred and analogous European sustainability labels create price premiums for foam products with verified renewable content thresholds.
- Commercial:Hotels, offices, and hospitality venues specifying durability and fire-safety certifications. OSHA workplace exposure limits for diisocyanates enforce respiratory protection protocols that elevate capital costs for new facility entrants.
- Industrial:Manufacturers integrating foam components into finished goods or protective packaging workflows. Reaction injection molding adoption climbs for complex contour geometries in electric vehicle cabin designs.
- Healthcare:Hospitals and long-term care facilities requiring pressure-relief surfaces and infection-control properties. REACH authorization requirements for isocyanate precursors tighten disclosure obligations across European value chains, compelling analytical testing infrastructure investments.
Volume concentrates in residential channels through mattress-in-a-box distribution; healthcare represents the steepest compliance burden with in-house materials engineering teams assuming specification authority.
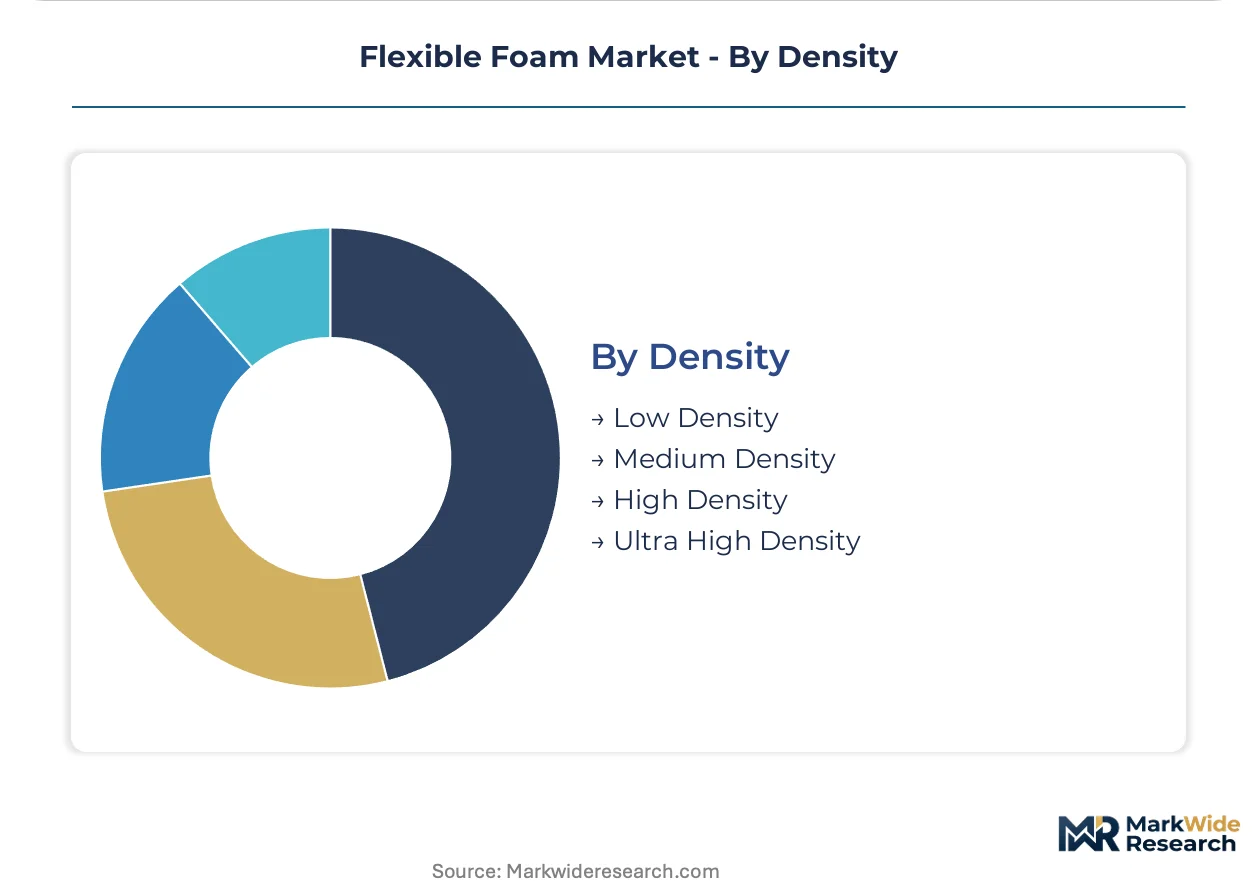
Density:
Performance requirements and cost positioning separate buyers here, with high-specification applications demanding precise compressive resilience while commodity segments prioritize unit economics.
- High Density:Cellular structures exceeding 50 kg per cubic meter with superior compressive strength and dimensional stability. Automotive seating programs specify these grades for durability under cyclic loading, with Dow Inc. leveraging integrated propylene oxide supply chains across the US Gulf Coast to sustain cost-advantaged TDI feedstock positions.
- Medium Density:Balanced performance profiles between 25-50 kg per cubic meter serving mainstream furniture and bedding applications. Covestro AG anchors European innovation through its Leverkusen technical center, where low-emission formulation platforms compete with Asian imports on certification metrics.
- Low Density:Lightweight structures below 25 kg per cubic meter for packaging, disposable cushioning, and cost-sensitive applications. Asian propylene oxide supply chains dominate flexible polyol precursor availability, exposing European formulators to freight cost volatility.
- Ultra High Density:Specialized grades exceeding 80 kg per cubic meter for industrial gasketing, heavy-load bearing, and precision-machined components. China's MEE enforcement protocols require automated dosing systems and enclosed mixing vessels, elevating greenfield facility costs for domestic producers.
Production volume clusters in medium density for furniture and mainstream bedding; specification intensity rises fastest in high density grades for automotive and healthcare compliance programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propylene oxide supply chains along the US Gulf Coast anchor North American flexible foam production, while Asian petrochemical corridors in eastern China and South Korea concentrate polyol precursor manufacturing for export-oriented formulation houses.
United States
Automotive seating manufacturers in Michigan and Tennessee are expanding polyurethane foam purchasing programs ahead of stricter EPA standards under TSCA Section 6. OSHA workplace exposure limits for diisocyanates enforce respiratory protection protocols that elevate capital costs for new facility entrants. Dow Inc. leverages integrated propylene oxide supply chains across the US Gulf Coast to sustain cost-advantaged TDI feedstock positions.
Germany
Tier-1 automotive suppliers in Bavaria and Baden-Württemberg retrofit slabstock lines with variable-pressure mixing heads to serve mixed-model electric vehicle production. REACH Substance of Very High Concern disclosures mandate low-emission foam certifications for interior programs. Covestro AG anchors European flexible foam innovation through its Leverkusen technical center, where low-emission formulation platforms compete with Asian imports on certification metrics.
China
Domestic e-commerce mattress brands in the Yangtze River Delta and Pearl River Delta are scaling bonded foam operations for next-day delivery networks. MEE enforcement protocols require automated dosing systems and enclosed mixing vessels, elevating greenfield facility costs for domestic producers. Asian petrochemical producers are shifting flexible polyol capacity toward specialty grades for automotive and bedding applications.
India
Organized retailers and sleep-tech startups in Mumbai and Bangalore import foam-rolling equipment to replace traditional coir and cotton bedding. The country's national chemical regulator enforces disclosure standards for isocyanate content in consumer products. Maharashtra and Karnataka industrial corridors concentrate mattress modernization investments as urban warehousing density favors vacuum-compressed foam delivery.
South Korea
Electronics logistics networks in Seoul and Busan maintain stable demand for polyethylene foam protective packaging formats. The national environmental ministry restricts methylene chloride content in consumer-grade blowing agents, compelling reformulation toward water-blown alternatives. Gyeonggi-do province hosts automated cutting and compression-packaging operations serving regional e-commerce distribution.
Flexible Foam Market Key Industry Players
Global majors compete with regional champions across formulation certification and feedstock integration, producing a tiered structure where integrated petrochemical players hold cost advantages in standard grades while specialized houses capture premiums in low-emission automotive specifications. Three archetypes dominate: integrated chemical conglomerates with captive polyol supply, regional formulation specialists with OEM qualification depth, and mattress-focused fabricators with direct-to-consumer logistics capabilities. Competitive moves concentrate on backward integration into propylene oxide and strategic partnerships for bio-based polyol certification.
Among integrated chemical conglomerates, BASF SE and Covestro AG exemplify the feedstock-integrated archetype with European technical center networks. Dow Inc. occupies a position within the North American integrated tier. Regional specialists including Huntsman International LLC and Recticel represent the formulation-focused segment with automotive OEM qualification depth. FXI, Inc. and Woodbridge sit within the North American automotive supply tier, while INOAC Corporation anchors Japanese flexible foam production. Armacell exemplifies the insulation-specialist segment with cross-material portfolio breadth.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| Dow Inc. |
| Huntsman International LLC |
| Recticel |
| Woodbridge |
| INOAC Corporation |
| Armacell |
| FXI, Inc. |
| Others |
Cost & Logistics Intelligence
Captive polyol production through integrated propylene oxide supply chains anchors both cost positioning and pricing power across flexible foam markets, with Dow Inc.'s US Gulf Coast infrastructure demonstrating how upstream control over TDI feedstock translates into margin defense against Asian import competition.
Pricing Analysis
Warranty and formulation certification bundling separates premium automotive foam contracts from commodity slabstock transactions, with REACH-compliant low-emission grades commanding sustained premiums over standard furniture grades. Three-tier pricing structure across premium, standard, and economy levels reflects divergence in VOC certification burden, customization depth, and volume commitment scale. Cost compression in standard-density furniture grades is intensifying because polyethylene foam substitutes and expanded polystyrene alternatives capture share on unit economics. Packaging buyers exhibit highest price sensitivity, while automotive OEMs prioritize emission compliance and durability guarantees over per-kilogram cost.
Supply Chain Analysis
Freight cost volatility from Asian propylene oxide corridors to European formulation houses is reshaping regional sourcing strategies, with carbon border adjustment exposure accelerating localization investments. China, South Korea, and the United States concentrate flexible polyol precursor manufacturing, drawing from propylene oxide, toluene diisocyanate, and specialty additive inputs. Single-source vulnerability in Asian petrochemical feedstock channels elevates risk for European formulators dependent on import-reliant supply chains. Distribution runs through direct-to-consumer compressed mattress logistics, Tier-1 automotive supplier qualification programs, and industrial packaging procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flexible foam market operates as a cost-of-compliance arena where REACH Substance of Very High Concern disclosures and EPA TSCA Section 6 restrictions erect capital-intensive barriers that favor incumbents with pre-certified analytical infrastructure and established OEM qualification relationships.
For Market Incumbents: Deepen backward integration into propylene oxide supply chains to defend margin position against Asian feedstock cost volatility, while accelerating low-emission formulation platform investments to capture automotive OEM specification authority before REACH authorization timelines compress further. Consolidate procurement relationships with mattress-in-a-box brands through dedicated compression-packaging capacity to lock in direct-to-consumer volume. For New Entrants and Emerging Players: Launch via India's mattress modernization wave, where organized retail penetration and sleep-tech startup demand outpaces domestic foam-rolling equipment supply, enabling imported machinery partnerships to establish production footholds. Target medium-density furniture grades with water-blown polyurethane systems that bypass methylene chloride regulatory restrictions while serving cost-sensitive residential channels. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of regional formulation specialists with deep automotive OEM qualification depth and captive testing infrastructure, as regulatory disclosure burdens render greenfield entry prohibitively capital-intensive. Monitor bio-based polyol certification trajectory as inflection indicator for sustainability premium capture and carbon border adjustment positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Dow Inc.'s US Gulf Coast supply chain demonstrates cost-advantaged TDI feedstock security against Asian import volatility. |
| Low-Emission Formulation Platform Investment | Covestro AG's Leverkusen technical center anchors European REACH compliance competitiveness versus certification-deficient imports. |
| Compressed Mattress Logistics Partnership | Direct-to-consumer brands bypass wholesale furniture networks through automated roll-packing and last-mile delivery alliances. |
| Bio-Based Polyol Certification Program | USDA BioPreferred and European sustainability labels create verified renewable content premiums for compliant producers. |
| Automated Dosing System Deployment | OSHA diisocyanate exposure limits and China's MEE protocols enforce enclosed mixing vessel investments for compliant production. |
Research Approach
Independent corroboration across plant managers at polyol production facilities, procurement leads at automotive Tier-1 suppliers, distribution channel partners in mattress logistics networks, and technical R&D directors at formulation houses underwrites the qualitative findings. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated chemical conglomerates, and EPA regulatory dockets. Bottom-up segmentation modeling triangulates against top-down macroeconomic demand indicators.
Comparable-period anchoring to historical automotive production cycles, furniture retail inventory patterns, and e-commerce mattress penetration rates establishes the forecast window baseline. The analysis models demand across product type, application, density grade, and regional production hub dimensions throughout the forecast period. CAGRs derive from elasticity-adjusted consumption trajectories, with propylene oxide supply capacity expansion schedules and REACH authorization phase-in timelines serving as industry-specific forecast inputs.
Feedstock price volatility, regulatory enforcement intensity variations, and substitute material penetration rates are the dominant revision risks that could alter trajectory assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
North America Polyphenylene Sulfide Compounds Market
Specialty Compounds
Global Antifreeze Proteins Market
Specialty Compounds
Global Specialty Polymer Market
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Silk Protein Market
Specialty Compounds
Thionyl Chloride Market
Specialty Compounds
Polyimide Coatings Market
Specialty Compounds
Plasma Powder Market
Specialty Compounds
Global Acetyls Market
Specialty Compounds
Potassium Gluconate Market
Specialty Compounds
Propylene Trimer Market
Specialty Compounds
Microcapsules Market
Specialty Compounds
United Kingdom Collagen Peptides Market
Specialty Compounds
North America Lithium Compound Market
Specialty Compounds
Middle East and Africa Color Masterbatch Market
Specialty Compounds
Global Masterbatch Market